
 Detergent Grade Zeolite Market | 2026-2036
Detergent Grade Zeolite Market Size, Share, and Industry Trends Forecast 2026-2036
Detergent Grade Zeolite Market Outlook
Direct supply contracts between zeolite producers and multinational detergent manufacturers is narrowing as procurement teams seek tighter specification control and volume guarantees. BASF SE leverages its integrated petrochemical feedstock position to sustain cost-advantaged synthetic zeolite output across European and Asian plants. Clariant AG anchors its competitive stance through specialized granular zeolite grades engineered for high-efficiency laundry formulations. Tosoh Corporation competes on manufacturing scale, operating dedicated zeolite production lines that serve Japanese and Southeast Asian household detergent brands.
Detergent grade zeolite refers to crystalline aluminosilicate materials, primarily Zeolite A (LTA structure) with typical SiO₂/Al₂O₃ ratios near 2.0, manufactured via hydrothermal crystallization of sodium aluminate and sodium silicate solutions to function as ion-exchange builders that sequester calcium and magnesium ions in washing formulations. Synthetic zeolite dominates volume flows due to consistent particle size distribution and controlled pore architecture demanded by automated detergent powder plants. Laundry detergents represent the largest application segment, though dishwashing liquids are gaining formulation share as liquid concentrate formats expand in North American and European retail. The household end user category retains the deepest margin pool, while institutional buyers increasingly specify concentrated zeolite grades that reduce packaging and transport intensity.
The EPA regulates zeolite manufacturing emissions under Clean Air Act provisions, while REACH mandates registration and hazard communication for synthetic zeolite imports into EU member states. China's MEE enforces wastewater discharge standards that constrain natural zeolite processing operations in Shandong and Henan provinces. India's BIS certification requirements for detergent raw materials create compliance thresholds that filter substandard zeolite suppliers from institutional procurement channels. Stakeholders must monitor evolving phosphate substitution mandates across Southeast Asian national standards bodies, as these regulatory timelines will determine capacity allocation between synthetic zeolite A and emerging zeolite MAP variants.
Market Dynamics
Phosphate substitution mandates across Southeast Asia are forcing detergent formulators to reconstitute supply agreements around zeolite ion-exchange builders, compressing qualification timelines and concentrating procurement authority among integrated petrochemical producers.
Growth Catalysts
- REACH Ecodesign requirements:European manufacturers redirect formulation spend toward synthetic zeolite alternatives as phosphate builders face downstream restrictions in Germany and the Netherlands.
- Liquid concentrate formats:North American dishwashing liquid producers expand zeolite loading in compact formulations to maintain hardness control without phosphate chelators.
- Indonesia's phosphate bans:Powder detergent plants in Java and Sumatra accelerate zeolite A procurement to meet national standard deadlines for builder substitution.
Market Restraints
- Sodium silicate supply concentration:Hydrothermal crystallization feedstock availability tightens around integrated chemical producers in China and Germany, constraining independent zeolite manufacturers.
- Zeolite MAP substitution threat:Magnesium aluminum phosphate variants capture share in premium laundry segments where higher ion-exchange capacity justifies unit cost premiums.
- MEE wastewater discharge standards:Natural zeolite processing operations in Shandong and Henan provinces face capacity constraints under stricter effluent monitoring.
Strategic Opportunities
- Vietnam's tightening phosphate regulations:Detergent manufacturers in Ho Chi Minh City and Hanoi seek qualified zeolite suppliers ahead of anticipated national builder bans.
- Concentrated zeolite grades:Institutional buyers specify high-density granular formats that reduce packaging mass and transport intensity for hotel and hospital laundries.
- High-efficiency laundry convergence:Cold-water wash formulations combine zeolite A with enzyme stabilizers to deliver calcium sequestration at reduced temperatures.
Industry Challenges
- Crystallization process control:Maintaining consistent SiO₂/Al₂O₃ ratios near 2.0 across batch hydrothermal runs requires specialized technical talent scarce outside major chemical clusters.
- BIS certification timelines:Indian detergent raw material standards create extended qualification periods that filter substandard suppliers from institutional procurement channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Detergent Grade Zeolite Market |
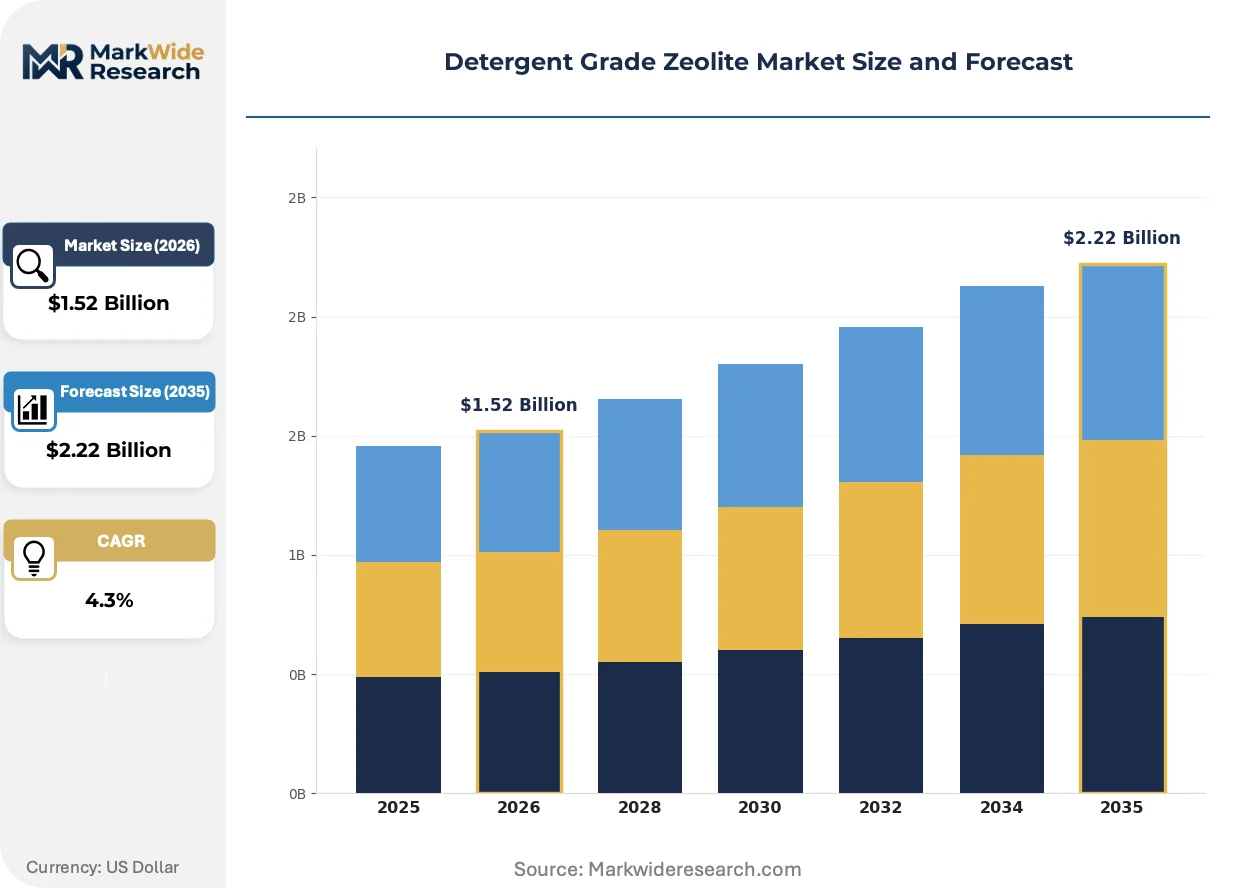
| Market Size in 2026 | $1.52 Billion |
| Market Size in 2035 | $2.22 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Zeolite, Synthetic Zeolite, Zeolite Powder, Granular Zeolite Application: Laundry Detergents, Dishwashing Liquids, Surface Cleaners, Fabric Softeners End User: Household, Commercial, Industrial, Institutional Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | BASF SE, Clariant AG, Honeywell International Inc., Zeochem AG, PQ Corporation, Tosoh Corporation, Arkema Group, W.R. Grace & Co., Zeolyst International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Detergent Grade Zeolite Market Strategic Shifts
Automation of detergent powder plants is digitizing specification requirements for particle size distribution and controlled pore architecture, forcing zeolite producers to retool quality assurance systems around real-time analytical feedback loops.
Zeolite A manufacturing is digitizing through inline X-ray diffraction and automated crystallization control systems that adjust sodium aluminate feed rates based on real-time phase purity detection. European and Japanese detergent plants now require certificate-of-analysis data packets with every bulk delivery. This digitization compresses rejection rates and narrows the qualified supplier base to producers with capital-intensive process analytical technology.
REACH registration mandates for synthetic zeolite imports force non-EU producers to maintain exhaustive substance data dossiers and hazard communication protocols. Downstream formulators in Germany and the Netherlands now audit supplier registration status before contract renewal. The regulation redirects procurement decisions toward established chemical conglomerates with dedicated regulatory affairs functions.
Direct supply contracting between zeolite producers and multinational detergent manufacturers is displacing distributor-mediated procurement in Southeast Asia and Western Europe. Procurement teams seek tighter specification control and volume guarantees through multi-year offtake agreements. This pattern concentrates most visible in Indonesia and Vietnam, where phosphate ban timelines create urgency around supplier qualification.
Detergent Grade Zeolite Market Segmentation
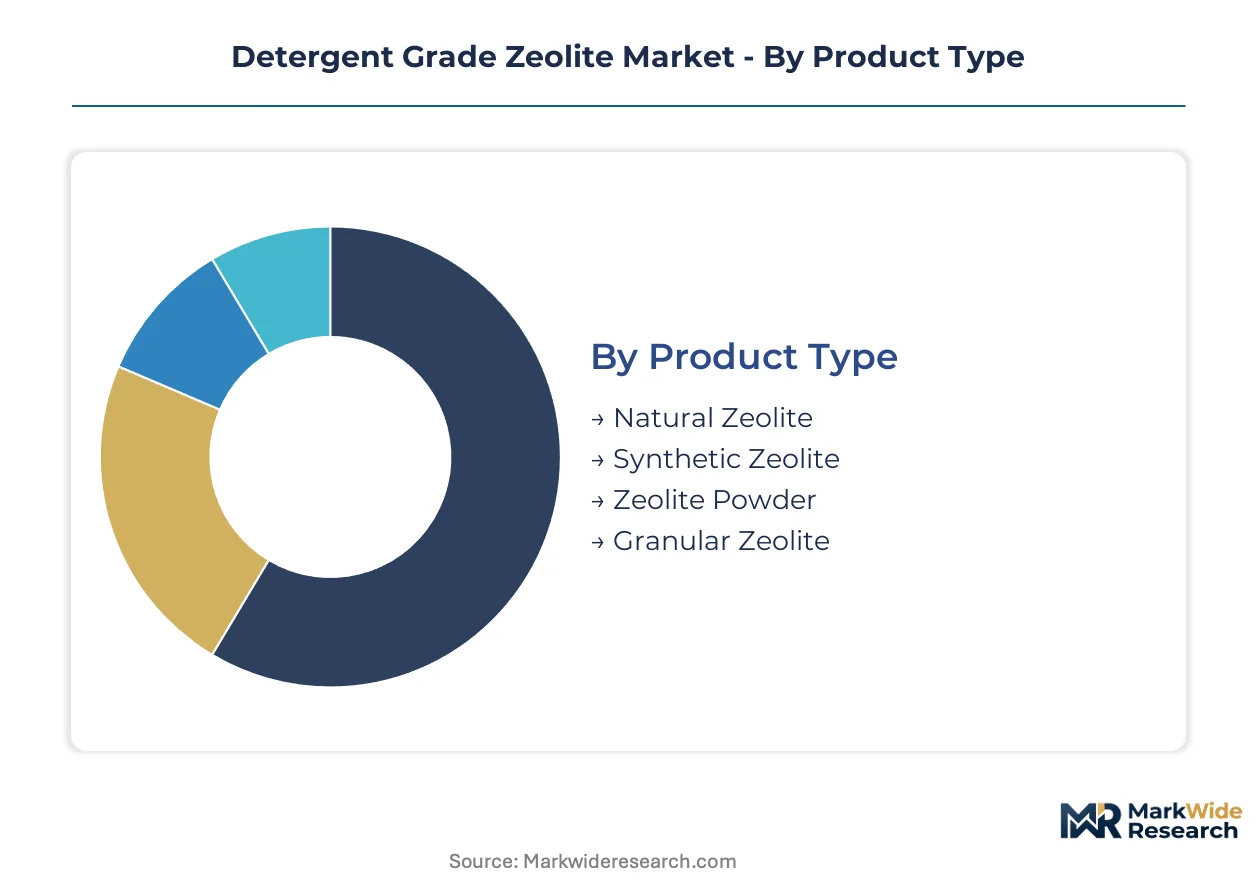
Formulators source zeolite grades through divergent technical and commercial pathways. Specification control, volume guarantees, and regulatory compliance requirements reshape how segments interact across procurement channels.
Product Type:
After-sales technical support intensity varies sharply across zeolite product categories, with synthetic grades demanding continuous process optimization assistance while natural variants require minimal post-sale intervention.
- Synthetic Zeolite:Manufactured via hydrothermal crystallization of sodium aluminate and sodium silicate solutions to achieve consistent SiO₂/Al₂O₃ ratios near 2.0. Demand concentrates among powder detergent plants in Indonesia, Vietnam, and Thailand as phosphate bans tighten and formulators require precise ion-exchange capacity for automated production lines.
- Granular Zeolite:Engineered through controlled agglomeration and calcination to deliver high-density formats with defined particle size distribution. Institutional laundries in Germany and the Netherlands specify these grades to reduce packaging mass and transport intensity under REACH Ecodesign procurement guidelines.
- Natural Zeolite:Mined and processed aluminosilicate materials with variable cation exchange capacity depending on deposit geology.
- Zeolite Powder:Finely milled crystalline material serving legacy detergent powder formulations with established specification tolerances.
Synthetic zeolite holds the largest share; momentum sits with granular formats.
Application:
Cost tier differentiation separates commodity laundry formulations from premium dishwashing concentrates requiring specialized builder performance.
- Laundry Detergents:The dominant application consuming Zeolite A for calcium and magnesium sequestration in washing formulations. Powder plants across Java and Sumatra accelerate procurement ahead of Indonesia's national phosphate substitution deadlines.
- Dishwashing Liquids:Liquid concentrate formats in North America expand zeolite loading to maintain hardness control without phosphate chelators, requiring modified dispersion stabilizers for clear product aesthetics.
- Surface Cleaners:Hard surface formulations incorporating zeolite for mild abrasive action and water softening in multi-purpose cleaning products.
- Fabric Softeners:Niche application where zeolite functions as a carrier for fragrance encapsulation and rinse-cycle water conditioning.
Laundry detergents hold the largest share; dishwashing liquids are expanding most quickly.
End User:
Volume concentration patterns diverge between mass-market household consumption and specialized institutional procurement with stringent certification requirements.
- Household:Retail packaged detergents for residential washing machines generate the deepest margin pool through brand premiums and formulation differentiation.
- Institutional:Hotel and hospital laundries specify concentrated zeolite grades with certificate-of-analysis data packets for every bulk delivery under digitized quality assurance protocols.
- Commercial:Laundromats and cleaning services purchasing intermediate bulk quantities with moderate specification stringency.
- Industrial:Large-scale textile processing and uniform rental operations with captive laundry facilities.
Household holds the largest share; institutional procurement is gaining share fastest.
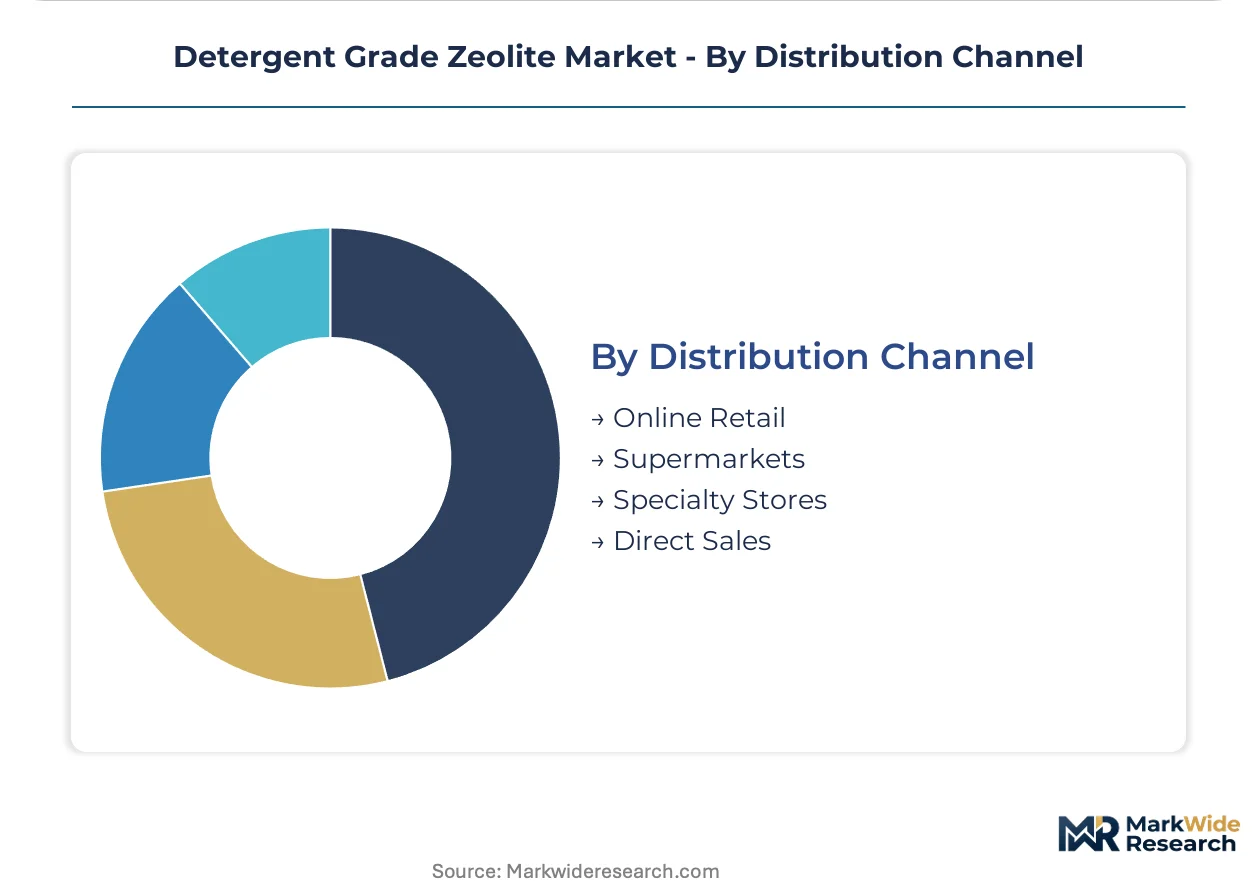
Distribution Channel:
Customer type stratification separates multinational formulators seeking direct supply contracts from smaller buyers reliant on distributor networks.
- Direct Sales:Multi-year offtake agreements between zeolite producers and multinational detergent manufacturers concentrate procurement authority and specification control. These arrangements displace distributor-mediated channels in Southeast Asia and Western Europe as phosphate ban timelines create qualification urgency.
- Online Retail:Specialty chemical marketplaces serving independent formulators and regional detergent brands with smaller batch requirements and extended delivery timelines.
- Supermarkets:Consumer-facing retail channels for finished detergent products rather than raw zeolite materials.
- Specialty Stores:Regional chemical distributors maintaining inventory for mid-tier formulators without volume scale for direct producer contracts.
Direct sales holds the largest share; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Northwest Europe's role as the primary consolidation point for sodium silicate feedstock flows into synthetic zeolite manufacturing.
Germany
Powder detergent plants in North Rhine-Westphalia and Bavaria accelerate Zeolite A procurement as REACH Ecodesign requirements tighten phosphate builder restrictions. The Federal Environment Agency enforces wastewater discharge standards that favor synthetic alternatives with controlled ion-exchange capacity. BASF SE's Ludwigshafen complex anchors regional supply through integrated petrochemical feedstock access.
Indonesia
Java and Sumatra-based formulators expand synthetic zeolite purchases ahead of national phosphate substitution deadlines for household laundry powders. The National Standardization Agency mandates builder reformulation timelines that compress supplier qualification windows. Surabaya's detergent manufacturing corridor concentrates procurement decisions among integrated chemical distributors.
Vietnam
Ho Chi Minh City and Hanoi detergent producers seek qualified zeolite suppliers in anticipation of tightening national phosphate regulations for powder formulations. The Ministry of Industry and Trade monitors builder content in imported consumer cleaning products. The southern manufacturing belt around Bien Hoa hosts expanding powder plant capacity targeting domestic and export markets.
China
Shandong and Henan province natural zeolite processors face capacity constraints under MEE wastewater discharge enforcement while synthetic producers expand. The Ministry of Ecology and Environment tightens effluent monitoring for aluminosilicate mining and processing operations. Qingdao's chemical port infrastructure supports sodium silicate import flows for hydrothermal crystallization plants serving Southeast Asian detergent manufacturers.
United States
North American dishwashing liquid producers in the Gulf Coast and Midwest regions expand zeolite loading in compact concentrate formulations. The EPA regulates manufacturing emissions under Clean Air Act provisions affecting crystallization plant siting decisions. Texas and Louisiana petrochemical corridors supply sodium aluminate feedstock for domestic synthetic zeolite output.
Detergent Grade Zeolite Market Competitive Environment
On the supply side, the industry is consolidating around integrated petrochemical conglomerates with captive feedstock positions and specialized chemical producers with formulation-technical capabilities. The vendor base separates into three strategic archetypes: integrated chemical majors with backward control over sodium silicate supply, specialized zeolite manufacturers with process analytical technology investments, and regional processors serving natural zeolite demand. Dominant competitive moves include direct supply contracting with multinational detergent manufacturers and multi-year offtake agreements that displace distributor channels.
Among European chemical conglomerates, BASF SE and Clariant AG exemplify the integrated-specialist split in competitive positioning. BASF SE anchors the feedstock-integrated archetype through petrochemical network access. Clariant AG occupies the formulation-technical tier with specialized granular grades. Tosoh Corporation represents the Asia-Pacific manufacturing scale archetype with dedicated production lines serving regional household brands.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Honeywell International Inc. |
| Zeochem AG |
| PQ Corporation |
| Tosoh Corporation |
| Arkema Group |
| W.R. Grace & Co. |
| Zeolyst International |
| Others |
Value Chain & Pricing Dynamics
Underutilized crystallization capacity in Shandong province is forcing Chinese synthetic zeolite producers to accept compressed contract terms, simultaneously eroding regional pricing power and accelerating supplier consolidation around integrated petrochemical majors with captive sodium silicate positions.
Pricing Analysis
Volume-discount tiering separates multinational detergent manufacturers purchasing via multi-year offtake agreements from mid-tier formulators sourcing through specialty distributors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and REACH registration status. Pricing pressure stems from Zeolite MAP substitution in premium laundry segments where higher ion-exchange capacity commands unit cost premiums. Institutional buyers demonstrate lowest price sensitivity due to digitized quality assurance protocols requiring certificate-of-analysis data packets.
Supply Chain Analysis
Extended payment terms from integrated chemical conglomerates are squeezing independent zeolite manufacturers without supply-chain finance facilities, concentrating procurement authority among feedstock-integrated players. Supply concentrates in Germany, China, and Japan, drawing from sodium aluminate, sodium silicate, and specialized process analytical technology inputs. Single-source vulnerability runs through sodium silicate supply concentration around integrated chemical producers in China and Germany. Distribution runs through direct sales channels displacing distributor-mediated procurement in Southeast Asia and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The detergent grade zeolite market functions as a defensive-moat story where REACH registration entrenchment creates switching costs that lock multinational formulators into qualified supplier relationships.
For Market Incumbents: Build regulatory moats through accelerated REACH dossier expansion and Ecodesign compliance certification ahead of Southeast Asian phosphate ban timelines. Deepen backward integration into sodium aluminate production to neutralize feedstock cost volatility from Chinese MEE wastewater enforcement. Secure multi-year offtake agreements with Indonesian and Vietnamese detergent plants before national standard deadlines compress qualification windows.
For New Entrants and Emerging Players: Pursue granular zeolite specialization for institutional laundries in Germany and the Netherlands where REACH Ecodesign procurement guidelines favor high-density formats with reduced transport intensity. Target Vietnam's anticipated phosphate regulations as the most penetrable geography, leveraging Surabaya's detergent manufacturing corridor knowledge for market entry. Deploy formulation-technical partnerships with regional powder plants seeking cold-water wash zeolite-enzyme stabilization expertise.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across synthetic zeolite manufacturing as inline X-ray diffraction and automated crystallization control systems become mandatory for qualified supplier status. Long-term viability centers on producers with dedicated regulatory affairs functions capable of navigating evolving phosphate substitution mandates across Southeast Asian national standards bodies. Acquisition target archetypes include specialized granular zeolite manufacturers with process analytical technology investments and established BIS certification for Indian institutional channels. Monitor Indonesia's National Standardization Agency builder reformulation timelines as the critical inflection signal for capacity allocation between synthetic zeolite A and emerging zeolite MAP variants.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate | Neutralizes feedstock cost volatility from Chinese MEE wastewater discharge enforcement. |
| Granular Zeolite Capacity Expansion | Captures institutional laundry demand under REACH Ecodesign procurement guidelines in Germany. |
| Direct Supply Contracting | Displaces distributor channels in Indonesia and Vietnam as phosphate ban timelines compress qualification. |
| Process Analytical Technology Investment | Enables real-time crystallization control required by automated detergent powder plants. |
| REACH Registration Dossier Expansion | Locks multinational formulators into qualified supplier relationships with embedded switching costs. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC chemical sector filings, and European Chemicals Agency registration databases. Primary interviews engaged zeolite plant managers, procurement leads at multinational detergent manufacturers, distribution channel partners, and technical R&D directors specializing in hydrothermal crystallization. Bottom-up volume modeling triangulates against top-down value estimates derived from trade flow analysis and petrochemical feedstock consumption patterns.
Forecast inputs span grade tier differentiation, end-use application intensity, packaging format density, and regional production hub capacity utilization. Segmentation dimensions modeled include synthetic versus natural origin, granular versus powder morphology, laundry versus dishwashing application, and household versus institutional end-user category. CAGRs derive from regression analysis of historical phosphate substitution trajectories and projected regulatory enforcement timelines. Industry-specific inputs incorporate sodium silicate feedstock availability indices and detergent powder plant automation penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed chemical conglomerates or accelerated Zeolite MAP commercialization would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
TEA Esterquats Market
Surfactants
North America Surfactants Market
Surfactants
Bitumen Emulsifier Market
Surfactants
Naphthalene Sulfonate Market
Surfactants
Global Sodium Cocoyl Glutamate Market
Surfactants
Wax Emulsion Market
Surfactants
Sulfate Free Body Wash Market
Surfactants
Global Barium Petroleum Sulfonate Market
Surfactants
Polymer Surfactants Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
Natural Wax Emulsion Market
Surfactants
Polyoxyethylene Sorbitan Tristearate Market
Surfactants
Global Low Foam Surfactants Market
Surfactants
Global Methyl Soyate Market
Surfactants
Alkylamines Market
Surfactants
Global Detergents Market