
 Powder Defoamers Market | 2026-2036
Powder Defoamers Market Size, Share, and Industry Trends Forecast 2026-2036
Powder Defoamers Market Analytics
Surfactant-free formulation technology is rewriting how manufacturers engineer powder defoamers for high-temperature industrial processes. BASF SE leverages its polymer research infrastructure to develop ethylene vinyl acetate carriers that enhance dispersion stability in cementitious systems. Dow Inc. anchors North American supply through backward integration into polypropylene glycol intermediates, sustaining cost advantages across construction end users. Evonik Industries AG differentiates via organo-modified siloxane architectures that compete on defoaming persistence in agrochemical tank mixes.
Powder defoamers comprise finely milled active agents—typically hydrophobic silica dispersed in silicone oil or polyether matrices—spray-dried onto inorganic carriers to achieve particle sizes between 50 and 200 microns for homogeneous incorporation into dry blends. Their primary purpose is the rapid collapse of foam lamellae in aqueous systems without introducing liquid-phase diluents that alter formulation viscosity or water demand. Silicone-based products occupy the dominant margin pool due to thermal stability above 150°C and broad pH tolerance, while non-silicone alternatives lead growth in food processing where FDA CFR 173.340 restricts organosilicon residues. Powdered and granular forms command premium positioning against pellets in instant-dissolution applications such as textile dyeing and pharmaceutical fermentation.
EPA effluent guidelines under the Clean Water Act and REACH Annex XVII restrictions on persistent surfactants compel reformulation toward biodegradable defoamer actives in US and European manufacturing. China's GB standards for construction chemical additives and India's BIS certification for textile auxiliaries further segment market access by regional compliance burden. Stakeholders must monitor regulatory divergence between OECD-aligned hazard assessment frameworks and emerging economy self-certification regimes to optimize product registration sequencing and manufacturing footprint decisions.
Market Dynamics
Silicone-free formulation chemistry is forcing incumbent powder defoamer producers to rebuild active-agent portfolios around bio-based carriers, as EPA and REACH restrictions on organosilicon persistence in wastewater tighten compliance windows for industrial end users.
Growth Catalysts
- REACH Annex XVII surfactant restrictions:European wastewater treatment plants are accelerating silicone-based powder defoamer adoption to meet effluent discharge limits on persistent organic compounds, creating pull from municipal utilities in Germany and the Netherlands.
- Cementitious system expansion:Dry-mix mortar producers in the United States are eliminating liquid defoamer carriers to reduce water demand in bagged construction chemicals, favoring powdered formats for transport efficiency.
- Agrochemical tank-mix persistence:Organo-modified siloxane architectures are extending defoaming duration in high-shear spray applications, penetrating crop protection formulations across Brazil and Argentina.
Market Restraints
- Hydrophobic silica supply concentration:Precipitated silica feedstock for carrier matrices concentrates among German and Chinese specialty chemical suppliers, exposing formulators to input cost volatility and allocation risk.
- Food-grade certification friction:FDA CFR 173.340 restrictions on organosilicon residues block silicone-based products from direct food contact applications, limiting addressable market in dairy and beverage processing.
- Liquid defoamer substitution:Concentrated emulsion technologies with extended shelf stability compete on total applied cost in high-volume textile dyeing operations where powder dissolution kinetics underperform.
Strategic Opportunities
- India BIS textile auxiliary certification:Formal compliance with Bureau of Indian Standards specifications opens institutional procurement channels for powder defoamers in Surat and Tiruppur dyeing clusters.
- EVA carrier convergence:Ethylene vinyl acetate matrix technology from polymer research infrastructure is enabling high-temperature dispersion stability in asphalt modification and roofing membrane compounds.
- China GB construction chemical standards:Mandatory additive certification for dry-mix mortars under national GB protocols creates regulated demand pull from provincial infrastructure spending in Sichuan and Guangdong.
Industry Challenges
- Spray-drying energy intensity:Particle engineering to 50-200 micron specifications requires thermal processing infrastructure that demands sustained natural gas or electricity access at stable tariff structures.
- Multi-jurisdiction registration sequencing:Divergent hazard assessment frameworks between OECD-aligned regimes and emerging economy self-certification regimes compress product launch timelines and inflate compliance staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powder Defoamers Market |
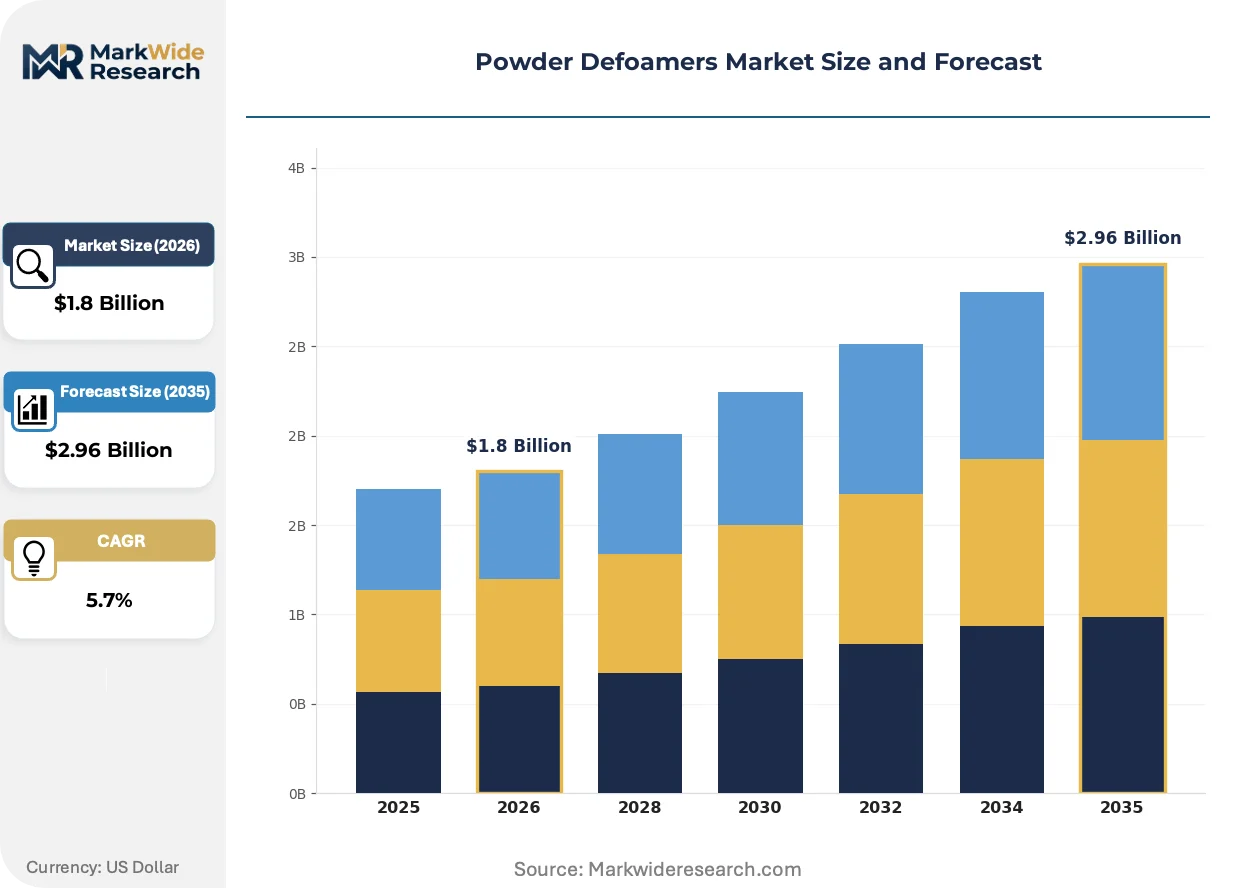
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone-based, Non-silicone-based, Ethylene Vinyl Acetate, Polypropylene Glycol Application: Personal Care, Food Processing, Agrochemicals, Coatings End User: Chemicals, Pharmaceuticals, Construction, Textiles Form: Powdered, Granular, Flake, Pellets |
| Companies Covered | Wacker Chemie AG, Air Products and Chemicals Inc., BASF SE, Elementis PLC, Clariant AG, Dow Inc., Shin-Etsu Chemical Co. Ltd., Momentive Performance Materials Inc., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powder Defoamers Market Evolving Landscape
Formulation science is pivoting toward surfactant-free active agents and bio-derived carrier matrices, compressing the performance gap between silicone and non-silicone chemistries while regulatory pressure accelerates portfolio turnover.
Spray-dried hydrophobic silica dispersed in polyether matrices is rendering obsolete traditional silicone-oil-based powder defoamers in high-pH construction chemical applications. Dry-mix mortar producers in Germany and the United States are adopting these alternatives at accelerating pace to preempt REACH and EPA compliance deadlines. The shift is compressing margin pools for incumbent silicone specialists while opening formulation partnerships between agrochemical and construction chemical divisions.
EPA effluent guidelines under the Clean Water Act are compelling municipal wastewater treatment facilities to document defoamer active biodegradability in discharge permits. Industrial laundries and food processing plants in the Great Lakes basin face the steepest compliance burden, driving substitution toward fatty-acid-ester-based powder formats that sacrifice some thermal stability for regulatory certainty. Equipment OEMs are responding with modified dosing systems optimized for lower-concentration bio-based actives.
Direct procurement relationships between powder defoamer formulators and dry-blend compounders are displacing traditional distribution through regional chemical distributors. Construction chemical manufacturers in Texas and Bavaria are consolidating supplier panels to capture volume pricing and technical service integration. This channel compression is most visible in instant-dissolution applications where formulation compatibility testing requires embedded technical support rather than arms-length trading.
Powder Defoamers Market Segmentation
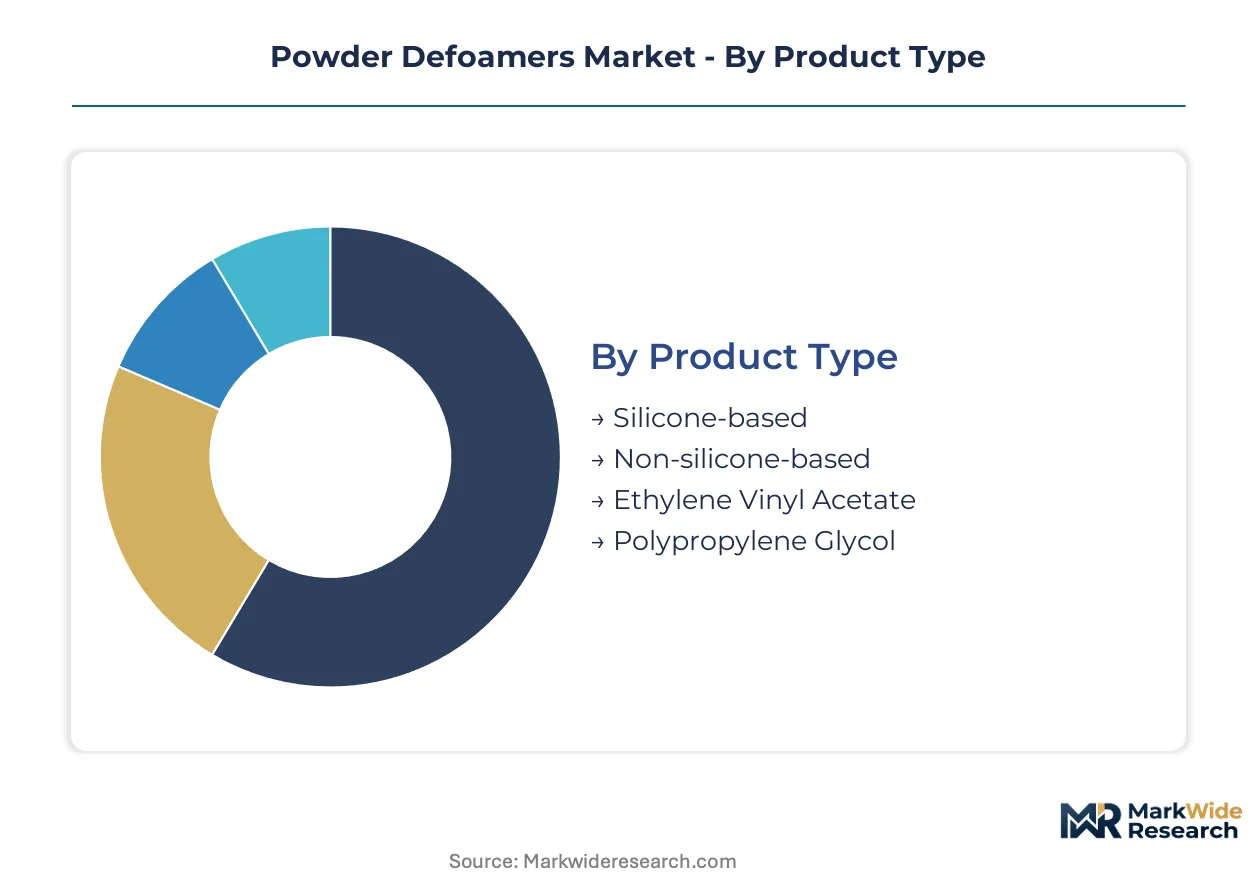
Powder defoamer segmentation reveals divergent margin structures across chemistry types and application intensities. Procurement cycles stretch from quarterly restocking in construction chemicals to multi-year contracts in pharmaceutical fermentation, reshaping how suppliers allocate technical service resources.
Product Type:
Silicone-based formulations turn inventory fastest in municipal wastewater treatment, while EVA carriers linger in specification trials for asphalt modification. Reformulation timelines stretch longest where REACH Annex XVII compliance forces active-agent substitution.
- Silicone-based:Hydrophobic silica dispersed in polydimethylsiloxane matrices delivers thermal stability above 150°C and broad pH tolerance. Demand concentrates in German and US wastewater treatment facilities under tightening EPA effluent guidelines and REACH surfactant restrictions.
- Non-silicone-based:Fatty-acid-ester and polyether actives serve food processing and beverage applications where FDA CFR 173.340 prohibits organosilicon residues. Dairy plants in Wisconsin and California drive specification adoption for direct-contact foam control.
- Ethylene Vinyl Acetate:Polymer carrier matrices enhance dispersion stability in high-temperature cementitious systems and roofing membrane compounds.
- Polypropylene Glycol:Polyether intermediate backbones support construction chemical formulations with controlled hydrophilic-lipophilic balance.
Silicone-based products dominate installed base. Non-silicone alternatives are where expansion concentrates.
Application:
Coatings applications run on monthly production schedules tied to automotive OEM coating lines, while agrochemical tank-mix demand spikes seasonally with Brazil and Argentina planting windows. Food processing maintains the most rigid certification barriers, stretching supplier qualification timelines.
- Coatings:Industrial powder coatings and architectural finishes require rapid lamellae collapse without viscosity alteration. Automotive OEM lines in Michigan and Bavaria specify instant-dissolution formats to eliminate liquid carrier waste and reduce transport costs.
- Agrochemicals:Organo-modified siloxane architectures extend defoaming persistence through high-shear spray applications. Crop protection formulators in Brazil and Argentina prioritize tank-mix stability across variable water chemistries.
- Personal Care:Cosmetic and toiletry applications demand surfactant-free actives with skin-safe certification profiles.
- Food Processing:Beverage and dairy operations require biodegradable defoamer actives documented in discharge permits under Clean Water Act guidelines.
Coatings command the deepest specification entrenchment. Agrochemicals present the steepest volume expansion trajectory.
End User:
Construction chemical buyers consolidate supplier panels annually to capture volume pricing, while pharmaceutical fermentation runs on locked multi-year agreements with embedded technical service. Textile dyeing houses in Surat and Tiruppur rotate suppliers most frequently on cost.
- Construction:Dry-mix mortar producers eliminate liquid defoamer carriers to reduce water demand in bagged products. Procurement in Texas and Bavaria favors powdered formats for transport efficiency and homogeneous dry-blend incorporation.
- Chemicals:Specialty and commodity chemical manufacturers specify particle sizes between 50 and 200 microns for consistent dispersion in aqueous process streams.
- Pharmaceuticals:Fermentation and downstream processing operations demand validated defoamer actives with full regulatory documentation packages.
- Textiles:Dyeing and finishing operations in India prioritize instant-dissolution kinetics for rapid foam control in high-temperature baths.
Construction anchors volume demand. Pharmaceuticals extract the highest service premiums.
Form:
Powdered and granular formats move through instant-dissolution applications with weekly replenishment cycles, while pellets serve slow-feed systems in continuous wastewater treatment with quarterly procurement. Flake formats occupy niche positioning in specialty chemical compounding.
- Powdered:Finely milled particles between 50 and 200 microns achieve homogeneous incorporation into dry blends without liquid-phase diluents. Textile dyeing and pharmaceutical fermentation operations in Germany and the United States command premium positioning for rapid dissolution kinetics.
- Granular:Controlled particle size distribution reduces dust generation during handling while maintaining dispersion performance. Municipal wastewater facilities in the Netherlands specify granular formats for automated dosing system compatibility.
- Flake:Compressed active-agent layers suit slow-release applications in specialty chemical manufacturing.
- Pellets:Dense spherical forms feed continuous processing equipment with minimal bridging or segregation.
Powdered formats dominate installed base. Granular products are gaining share fastest in automated dosing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction chemical buyers concentrate procurement in Germany and the United States, while textile dyeing houses drive volume in India. Wastewater treatment utilities in the Netherlands and agrochemical formulators in Brazil anchor regional demand clusters.
United States
Dry-mix mortar producers in Texas and California eliminate liquid defoamer carriers to reduce water demand in bagged construction chemicals. EPA effluent guidelines under the Clean Water Act compel municipal utilities in the Great Lakes basin to document defoamer biodegradability. Industrial laundries and food processing plants in Wisconsin prioritize fatty-acid-ester formats for regulatory certainty.
Germany
Wastewater treatment facilities across North Rhine-Westphalia and Bavaria accelerate silicone-based powder defoamer adoption under REACH Annex XVII surfactant restrictions. BASF SE leverages polymer research infrastructure in Ludwigshafen to develop ethylene vinyl acetate carriers for cementitious systems. Municipal utilities in the Netherlands mirror this compliance-driven procurement pattern.
China
Construction chemical additive demand concentrates in Sichuan and Guangdong provinces under mandatory GB standards for dry-mix mortars. Provincial infrastructure spending drives regulated demand pull from cementitious system producers. Hydrophobic silica supply concentrates among domestic specialty chemical suppliers, exposing formulators to input cost volatility.
India
Textile dyeing operations in Surat and Tiruppur prioritize instant-dissolution kinetics for rapid foam control in high-temperature baths. Bureau of Indian Standards certification for textile auxiliaries opens institutional procurement channels. Dyeing houses rotate suppliers frequently on cost, compressing margin structures for powder defoamer formulators.
Brazil
Agrochemical tank-mix formulators in São Paulo and Mato Grosso extend defoaming persistence through high-shear spray applications. Crop protection operations prioritize tank-mix stability across variable water chemistries during seasonal planting windows. Organo-modified siloxane architectures penetrate formulations as planting demand spikes.
Powder Defoamers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base distributes across multinational chemical conglomerates with backward integration into polyether intermediates, regional formulators serving single-industry verticals, and carrier-technology specialists licensing dispersion patents. Two dominant competitive moves define current positioning: direct procurement relationships displacing regional chemical distributors, and spray-drying capacity expansion to capture construction chemical volume in Texas and Bavaria.
Within the multinational conglomerate tier, BASF SE, Dow Inc., and Evonik Industries AG represent divergent strategic anchoring. BASF SE exemplifies polymer research infrastructure deployment for high-temperature carrier development. Dow Inc. occupies a position sustained by captive supply of polypropylene glycol intermediates. Evonik Industries AG sits within the organo-modified siloxane specialization vector, competing on defoaming persistence in agrochemical applications. These three entities collectively illustrate how raw material access, research depth, and application-specific formulation expertise separate market positions.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Air Products and Chemicals Inc. |
| BASF SE |
| Elementis PLC |
| Clariant AG |
| Dow Inc. |
| Shin-Etsu Chemical Co. Ltd. |
| Momentive Performance Materials Inc. |
| Evonik Industries AG |
| Others |
Value Network & Pricing Analysis
Undercapacity in spray-drying infrastructure across Texas and Bavaria is compressing supplier margins while elevating pricing power for capacity holders serving construction chemical formulators. This utilization squeeze feeds directly into procurement behavior, as dry-mix mortar producers consolidate supplier panels to lock in volume commitments before allocation constraints tighten further.
Pricing Analysis
Cost-plus contracts with silicone oil indexation dominate procurement between powder defoamer formulators and construction chemical manufacturers. Three-tier pricing structure across food-grade certified, industrial-grade, and economy bulk tiers separates pharmaceutical fermentation buyers from textile dyeing houses. Cost compression in the economy tier is intensifying because Indian dyeing clusters rotate suppliers quarterly on spot pricing. Construction chemical buyers in Germany exhibit the lowest price sensitivity due to embedded technical service requirements, while Surat textile houses drive the steepest discount negotiations.
Supply Chain Analysis
Tariff exposure between Germany and China dominates risk planning for hydrophobic silica feedstock procurement. Precipitated silica manufacturing concentrates in Germany, China, and the United States, while polypropylene glycol intermediates source primarily from US Gulf Coast and Rotterdam hub production. Spray-drying energy intensity rests on sustained natural gas access at stable tariff structures. Distribution runs through direct procurement relationships displacing regional chemical distributors, with construction chemical manufacturers in Texas and Bavaria consolidating supplier panels for volume pricing capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics is reshaping competitive positioning as direct procurement portals disintermediate traditional distribution, creating interoperability standards between powder defoamer formulators and dry-blend compounders that reward early standard-setters.
For Market Incumbents: Build captive spray-drying capacity moats in Texas and Bavaria to preempt allocation risk from undercapacity. Secure backward integration into polypropylene glycol intermediates to sustain cost advantages against concentrated emulsion substitutes. Defend specification entrenchment in pharmaceutical fermentation through embedded technical service teams that lock multi-year agreements. For New Entrants and Emerging Players: Build out BIS-certified production capacity targeting Surat and Tiruppur textile dyeing clusters where supplier rotation creates white-space entry. Penetrate fatty-acid-ester formulation segments serving Wisconsin dairy plants facing EPA discharge permit constraints. Lead with instant-dissolution kinetics demonstrations to bypass entrenched silicone-based incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward carrier-technology specialists licensing ethylene vinyl acetate dispersion patents for high-temperature cementitious applications. Long-term viability hinges on positioning for REACH Annex XVII compliance-driven portfolio turnover rather than commodity silicone volumes. Watch for EPA effluent guideline expansion beyond Great Lakes basin as signal for bio-based active demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Glycol | Dow Inc.'s captive intermediate supply sustains cost advantages across construction end users. |
| EVA Carrier Technology Licensing | BASF SE's polymer research infrastructure enables high-temperature dispersion stability in asphalt modification. |
| BIS Certification for Textile Auxiliaries | Formal compliance opens institutional procurement channels in Surat and Tiruppur dyeing clusters. |
| Spray-Drying Capacity Expansion | Thermal processing infrastructure additions in Texas and Bavaria capture construction chemical volume consolidation. |
| Organo-Modified Siloxane R&D Partnership | Evonik Industries AG's defoaming persistence competes in Brazil and Argentina agrochemical tank mixes. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at dry-mix mortar facilities, procurement leads at wastewater treatment utilities, and technical R&D directors at agrochemical formulators; and secondary validation through customs/trade data, SEC 10-K filings of multinational chemical conglomerates, EPA effluent discharge permit databases, and REACH registration dossiers. Bottom-up volume modeling triangulated against top-down market sizing across chemistry type, application intensity, and regional regulatory cluster dimensions.
Forecast inputs considered chemistry-grade tier penetration rates, end-use industry capacity utilization, packaging format adoption curves, and regional production hub expansion plans across the analysis window. Segmentation dimensions modeled include silicone versus non-silicone active agent substitution trajectories, construction versus pharmaceutical end-use service premium extraction, and powdered versus granular format share shifts in automated dosing applications. CAGRs were derived from regression analysis of historical volume trends against regulatory compliance deadline schedules and infrastructure spending patterns.
Stress conditions across natural gas tariff volatility, hydrophobic silica supply allocation, and REACH Annex XVII enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and construction chemical demand persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
MDEA Esterquats Market
Surfactants
Sodium Lauryl Sulphate Market
Surfactants
Global Detergent Polymers Market
Surfactants
Bio-Based Surfactants Market
Surfactants
Polymer Surfactants Market
Surfactants
Tetrabutylammonium Bromide Market
Surfactants
Non-Ionic Surfactants Market
Surfactants
Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market
Surfactants
Polyoxyethylene Sorbitan Tristearate Market
Surfactants
North America Surfactants Market
Surfactants
Sulfosuccinate Market
Surfactants
Global Barium Petroleum Sulfonate Market
Surfactants
Sugar-Based Surfactants Market
Surfactants
Dodecanol Market
Surfactants
Coconut Derived Surfactants Market
Surfactants
Sodium Cocoyl Isethionate Market