
 Video Intercom Devices Market | 2026-2036
Video Intercom Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Video Intercom Devices Market Intelligence
Multifamily property managers is reorganizing procurement priorities around cloud-connected access systems, displacing traditional single-tenant residential buyers as the dominant demand archetype. Legrand leverages its European channel depth to sustain premium positioning in flush-mounted smart intercom lines. Hikvision competes aggressively on manufacturing scale, anchoring cost leadership in outdoor installation segments across Asian markets. Dahua Technology specializes in AI-enhanced motion detection features, differentiating its portfolio from commoditized two-way communication hardware.
Video intercom devices encompass electronic communication systems integrating audio capture, video transmission, and door-release mechanisms operating over twisted-pair copper, IP networks, or radio frequency protocols, typically supporting resolutions from 720p to 4K with Power-over-Ethernet or low-voltage DC power architectures. These systems serve primary commercial and residential functions of visitor verification, remote entry authorization, and perimeter security management. Wired intercoms still occupy the largest installed base in legacy commercial buildings where infrastructure replacement cycles remain extended, while smart intercoms represent the fastest-expanding category as remote access and mobile app integration redefine buyer expectations. Wireless intercoms dominate retrofit residential applications where surface-mounted installation avoids structural modification costs.
FCC certification governs radio-frequency emissions for wireless intercom devices sold in the United States, while CE marking under the EU Radio Equipment Directive mandates interoperability and safety testing for European market access. China's MIIT enforces GB standards on network-connected security devices, creating compliance complexity for foreign suppliers seeking distribution through domestic channels. India's BIS certification requirements for electronic safety equipment add another regulatory layer for manufacturers targeting its residential construction boom. Stakeholders must monitor evolving cybersecurity mandates for IoT-connected access systems as regulators in multiple jurisdictions draft firmware update and data encryption requirements.
Market Dynamics
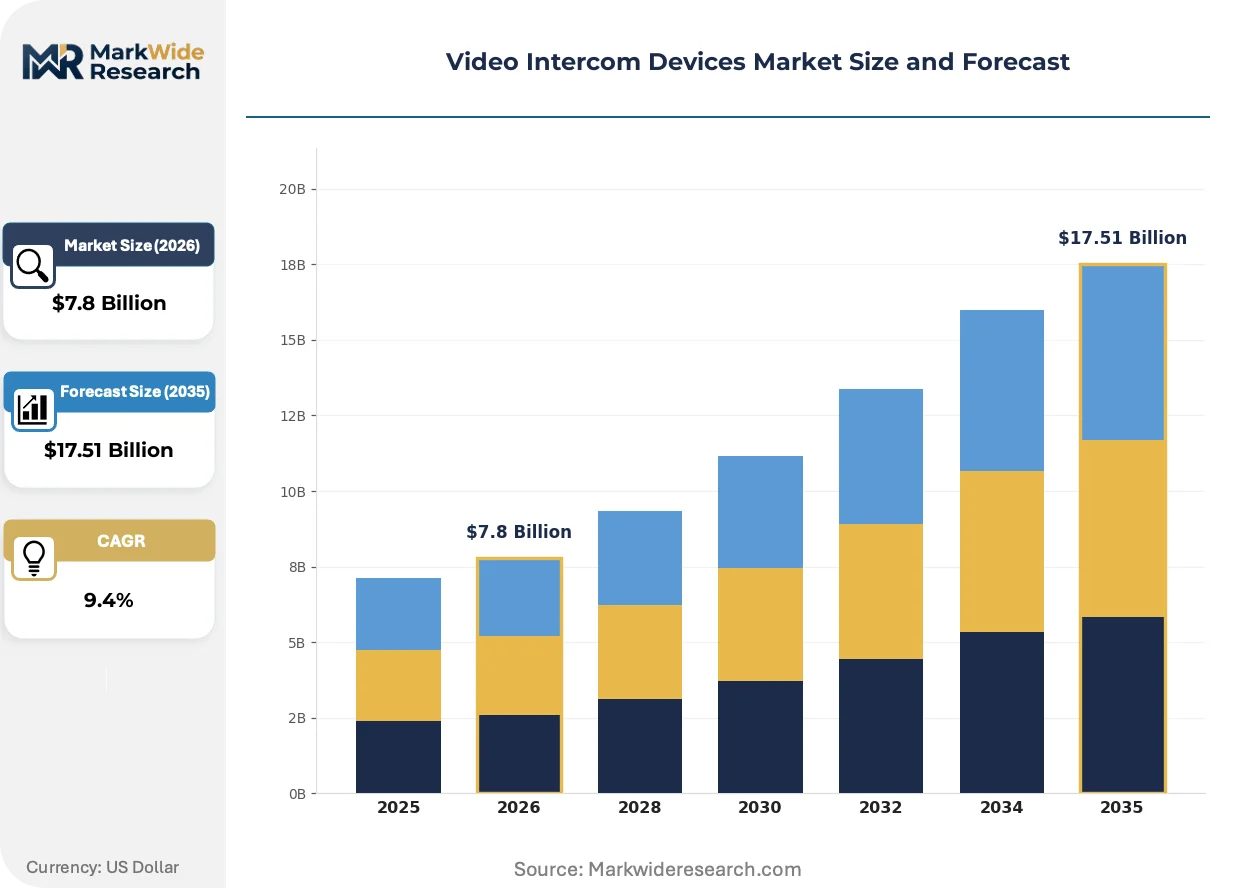
Cloud-connected access systems are reorganizing procurement priorities across residential and commercial verticals, displacing traditional single-tenant buyers as the dominant demand archetype and compressing replacement cycles for legacy wired infrastructure.
Growth Catalysts
- Smart Intercom Adoption in Gated Communities:Property managers prioritize integrated access control platforms that consolidate visitor management, package delivery, and perimeter monitoring into unified dashboards.
- EU AI Act Compliance Pathways:Facial recognition-enabled units require updated certification workflows, creating first-mover advantages for manufacturers with established European regulatory expertise.
- Residential Construction Concentration:China, India, and Brazil now generate the bulk of new infrastructure demand as urbanization accelerates and middle-income housing stock expands.
Market Restraints
- Semiconductor Supply Volatility:Image sensor and SoC lead times remain extended, constraining production schedules for 4K-resolution outdoor units.
- Legacy Infrastructure Lock-In:Twisted-popper copper installations in commercial buildings create high switching costs that delay IP-network migration.
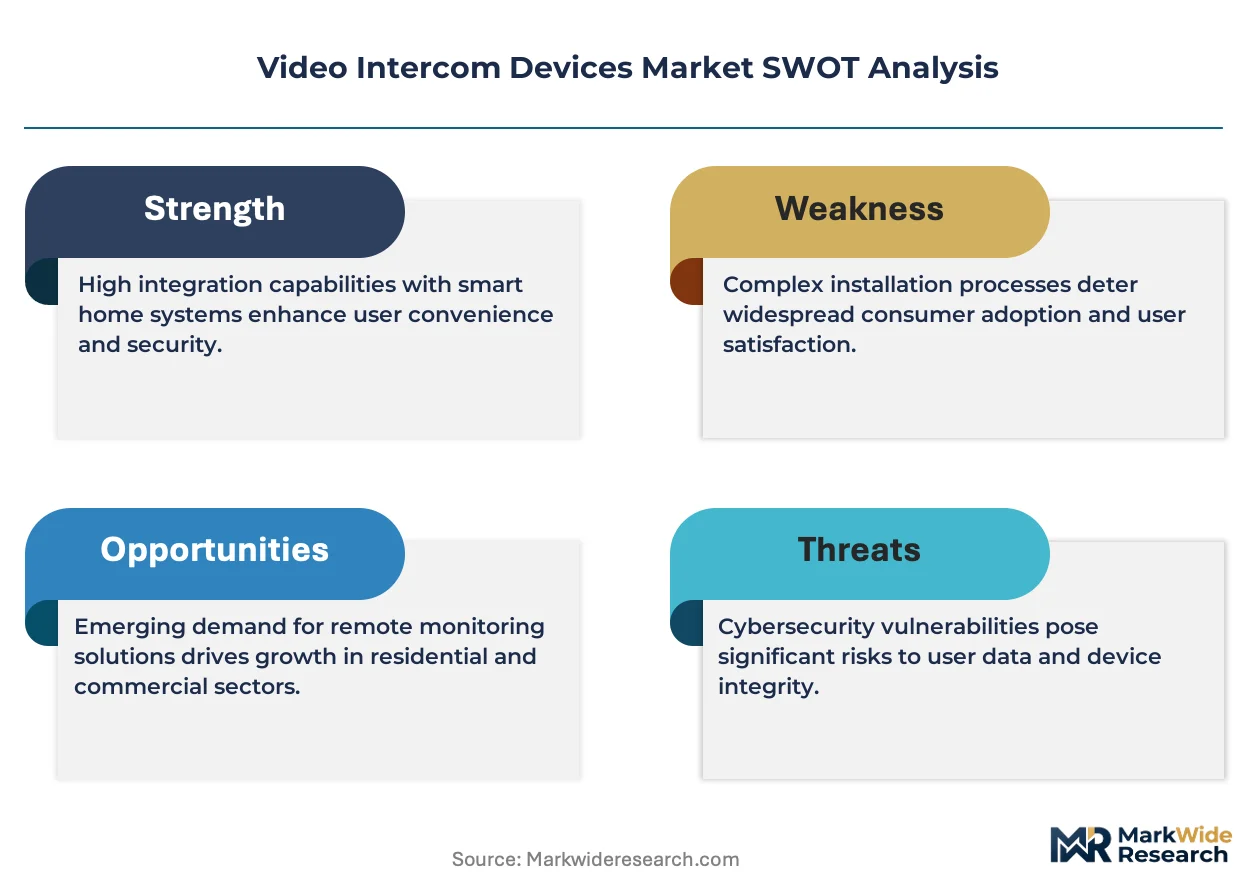
- Cybersecurity Compliance Burden:Emerging firmware update mandates and data encryption requirements across multiple jurisdictions inflate R&D overhead for IoT-connected systems.
Strategic Opportunities
- Retrofit Wireless Expansion:Surface-mounted wireless intercoms bypass structural modification costs in aging residential stock across Germany and France.
- AI-Enhanced Motion Detection:Convergence of edge computing and computer vision enables predictive analytics that differentiate premium portfolios from commoditized two-way hardware.
- Mobile-First Integration:Remote access applications redefine buyer expectations, opening subscription revenue streams for cloud service layers.
Industry Challenges
- Multi-Jurisdiction Certification Complexity:FCC, CE marking, MIIT GB standards, and BIS requirements create fragmented approval timelines that delay product launches.
- Legacy System Integration Friction:Hybrid deployments combining IP and analog architectures demand specialized engineering resources that strain mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Intercom Devices Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Intercoms, Wireless Intercoms, Smart Intercoms, Intercom Systems Installation Type: Indoor Installation, Outdoor Installation, Surface-Mounted, Flush-Mounted End User: Residential, Commercial Buildings, Gated Communities, Public Facilities Feature: Video Display, Two-Way Communication, Remote Access, Motion Detection |
| Companies Covered | Legrand, Aiphone, Hikvision, Comelit Group, Samsung Electronics, Panasonic Corporation, Dahua Technology, Siedle, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Intercom Devices Market Strategic Shifts & Innovations
Power-over-Ethernet architectures and edge AI processing are compressing hardware form factors while expanding functional capabilities. These shifts are redefining competitive differentiation beyond basic audio-video transmission.
PoE++ power delivery is displacing traditional low-voltage DC architectures in new commercial construction, enabling single-cable installation that reduces labor costs and simplifies cable management. Facility managers in Class A office buildings are specifying PoE-native intercoms as standard. This migration is compressing demand for separate power infrastructure and rewiring contractor relationships.
The EU AI Act's risk classification framework for biometric identification systems is forcing redesign cycles for facial recognition modules. Manufacturers must demonstrate algorithmic transparency and human oversight protocols to maintain CE marking eligibility. European channel partners are prioritizing suppliers with documented compliance roadmaps, reshaping vendor selection criteria.
Property management platforms are unbundling after-sales service from hardware procurement, favoring vendors with API-first architectures that integrate with centralized building operating systems. Multifamily operators in the United States now specify interoperability with access control software as a primary selection filter. This behavioral shift is marginalizing closed-ecosystem suppliers that lack third-party integration capabilities.
Video Intercom Devices Market Segmentation
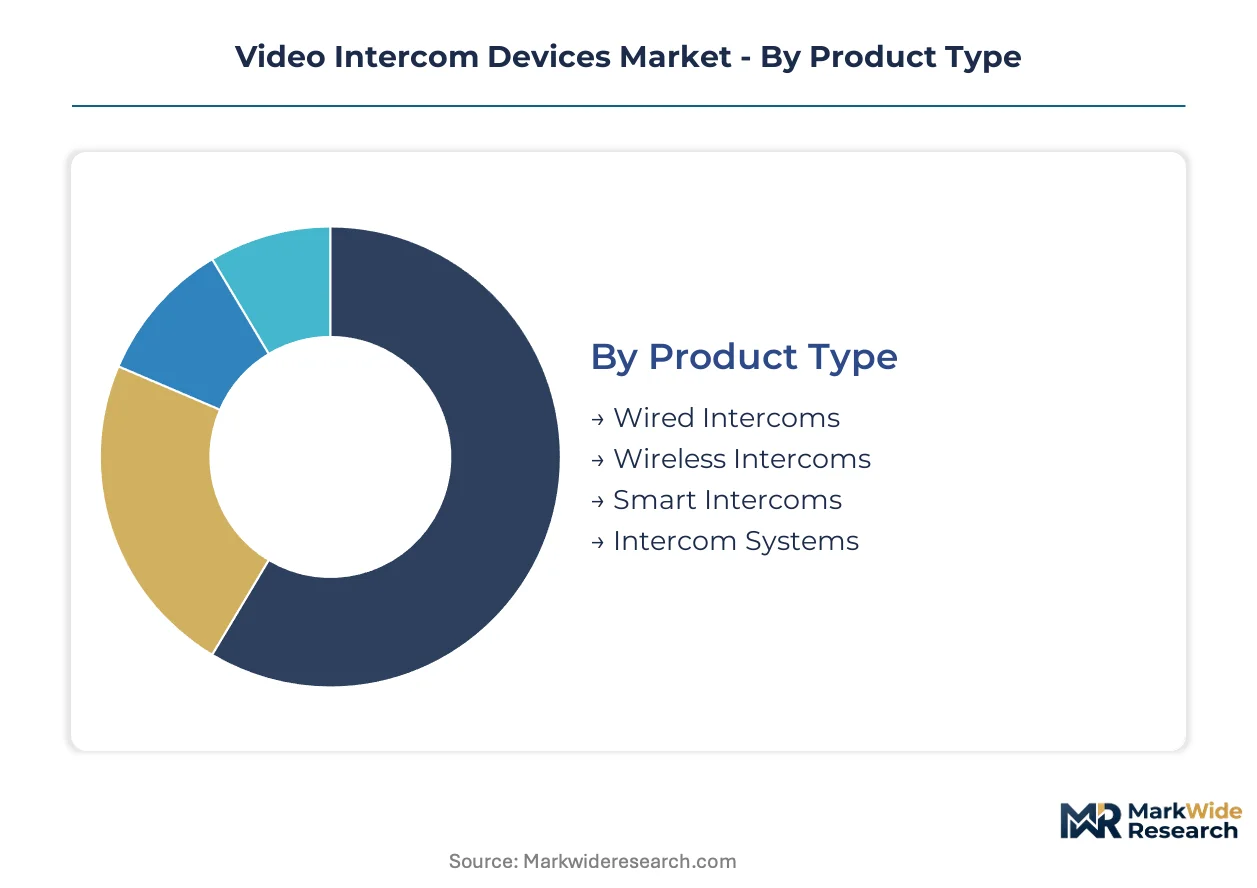
Video intercom procurement varies sharply across building vintages, power infrastructure, and regulatory environments. Segmentation reveals how FCC, CE marking, MIIT GB standards, and BIS certification each favor distinct hardware configurations and installation methodologies.
Product Type:
CE marking under the EU Radio Equipment Directive and FCC Part 15 certification create divergent compliance burdens that reshape competitive positioning across hardware categories.
- Wired Intercoms:These systems transmit audio and video over twisted-pair copper cabling, supporting 720p to 1080p resolutions with dedicated low-voltage DC power supplies. Demand concentrates in legacy commercial buildings across Germany and Japan where infrastructure replacement cycles extend beyond fifteen years and facilities managers prioritize reliability over connectivity.
- Smart Intercoms:Cloud-native architectures with mobile app integration and API-first designs enable remote access management and subscription service layers. Property management platforms in United States multifamily housing specify these units as procurement priorities displace traditional single-tenant residential buyers.
- Wireless Intercoms:Radio-frequency protocols eliminate structural modification requirements, dominating retrofit residential applications in aging European housing stock.
- Intercom Systems:Modular configurations integrate multiple entry points across large commercial footprints, serving Class A office buildings in Singapore and Dubai.
Established volume favors wired infrastructure; emerging adoption favors smart intercoms with cloud connectivity.
Installation Type:
Cost tier differentiation separates premium flush-mounted designs from economy surface-mounted alternatives, with labor intensity driving specification decisions.
- Indoor Installation:Lobby and corridor units prioritize vandal resistance and clean aesthetic integration, commanding premium pricing in luxury residential towers across Manhattan and London.
- Outdoor Installation:Weather-sealed housings with IP65+ ratings and heating elements protect image sensors in extreme climates, concentrating demand in Nordic countries and Gulf Cooperation Council states where temperature cycling accelerates hardware degradation.
- Surface-Mounted:Retrofit-friendly brackets avoid wall cavity modifications, expanding fastest in Paris and Berlin where heritage building restrictions limit structural alterations.
- Flush-Mounted:Recessed installation delivers seamless architectural integration, specified by premium developers in Mumbai and São Paulo luxury condominiums.
Surface-mounted hardware captures retrofit volume; flush-mounted specifications dominate new construction premiums.
End User:
Customer type fragmentation separates individual homeowner preferences from institutional procurement workflows with divergent integration requirements.
- Residential:Single-family and small multifamily deployments emphasize ease of use and smartphone compatibility, with Indian middle-income housing stock in Bangalore and Hyderabad generating concentrated demand for cost-optimized wireless units.
- Commercial Buildings:Enterprise security departments require centralized visitor logging and access audit trails, driving PoE++ adoption in United States Class A office markets.
- Gated Communities:Master-planned developments in Brazil and China integrate perimeter intercoms with vehicle barrier systems and package delivery management platforms.
- Public Facilities:Government and educational institutions mandate compliance with specific cybersecurity frameworks and encrypted firmware update protocols.
Commercial buildings anchor professional-grade volume; gated communities represent the steepest expansion trajectory for integrated access platforms.
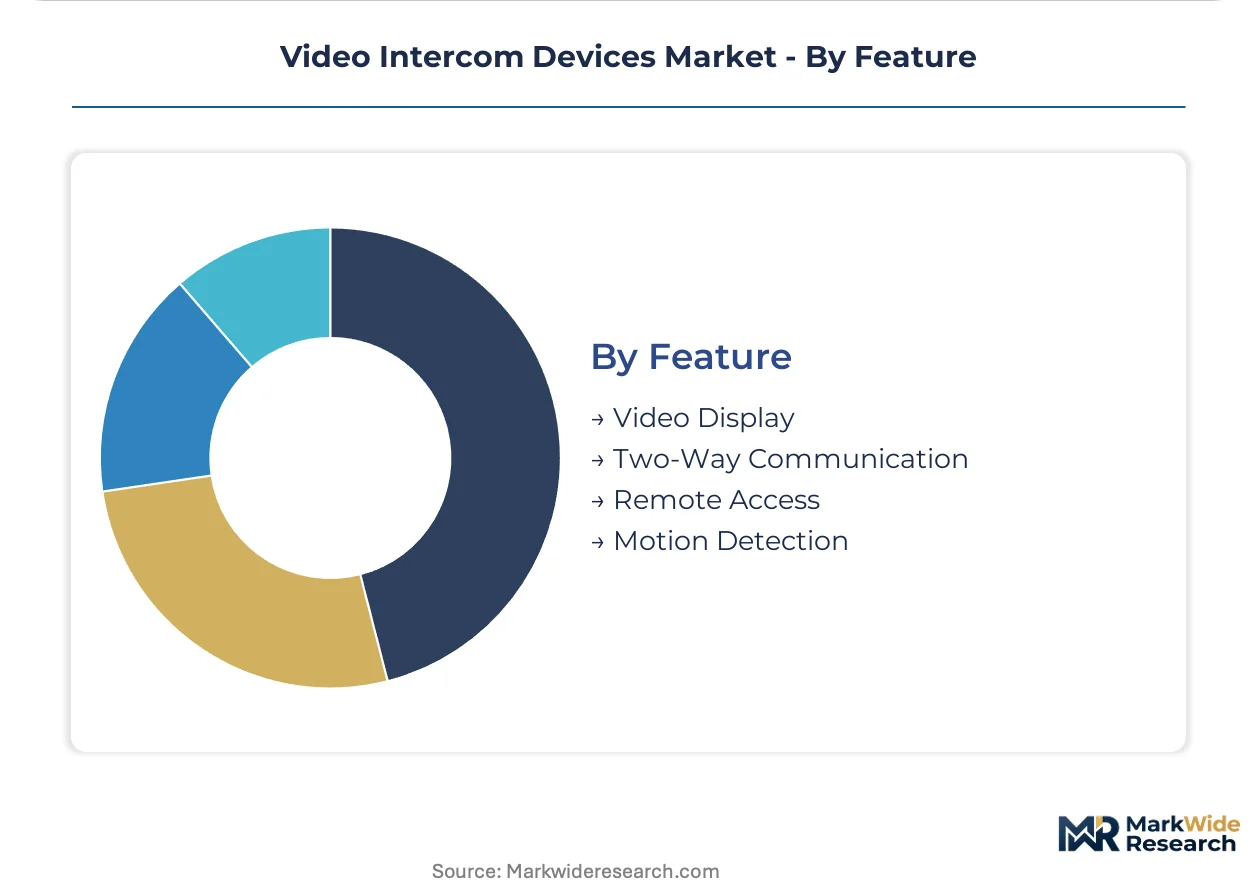
Feature:
Technology maturity separates commoditized two-way audio from AI-enhanced capabilities that command pricing premiums and recurring revenue attachment.
- Video Display:Screen-based visitor verification ranges from basic LCD panels to 4K touch interfaces, with resolution specifications climbing fastest in South Korean and Japanese premium residential markets.
- Two-Way Communication:Full-duplex audio with noise cancellation remains baseline functionality across all price tiers, offering limited differentiation.
- Remote Access:Mobile application integration enables entry authorization from off-site locations, now standard in United States multifamily procurement specifications.
- Motion Detection:Edge AI processing with predictive analytics differentiates premium portfolios, with EU AI Act compliance requirements favoring vendors with documented algorithmic transparency in European markets.
Video display and two-way communication anchor baseline specifications; motion detection with edge AI delivers the fastest-growing feature premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing scale clusters in China, while certification expertise concentrates in European markets. Demand expansion concentrates in India, Brazil, and Gulf states where residential construction accelerates.
China
MIIT enforces GB standards on network-connected security devices, creating compliance complexity for foreign suppliers. Zhejiang and Guangdong provinces host the dominant manufacturing clusters for outdoor installation hardware. Shenzhen-based fabricators compete aggressively on cost leadership for 4K-resolution units destined for Asian markets.
United States
FCC Part 15 certification governs radio-frequency emissions for wireless intercom devices. Multifamily operators in Manhattan and Los Angeles specify cloud-native architectures with mobile app integration. Class A office buildings in Chicago and Houston drive PoE++ adoption for single-cable installation.
Germany
CE marking under the EU Radio Equipment Directive mandates interoperability testing for European market access. Berlin and Munich concentrate demand for flush-mounted smart intercoms in luxury residential towers. Legrand leverages channel depth to sustain premium positioning in heritage building retrofit projects.
India
BIS certification requirements for electronic safety equipment add regulatory layers for foreign manufacturers. Bangalore and Hyderabad generate concentrated demand for cost-optimized wireless units in middle-income housing stock. Gated community developments in Mumbai integrate perimeter intercoms with vehicle barrier systems.
Brazil
ANVISA and national telecommunications regulators enforce certification on imported security electronics. São Paulo and Rio de Janeiro anchor demand for surface-mounted retrofit hardware in aging urban housing. Master-planned communities in Brasília prioritize integrated access control platforms with package delivery management.
Video Intercom Devices Market Key Industry Players
Concentration sits with diversified electrical equipment conglomerates and specialized security technology vendors. The vendor base spans three tiers: European incumbents with regulatory expertise, Asian scale manufacturers, and regional system integrators. Strategic moves center on API-first architecture development and European compliance roadmapping for facial recognition modules.
Among diversified electrical equipment conglomerates, Legrand S.A. and Honeywell International Inc. exemplify the regulatory-expertise archetype. Hikvision occupies a position within the scale-driven tier. These anchors demonstrate how certification depth and manufacturing scale define competitive differentiation in a market where cloud connectivity and AI-enhanced features compress replacement cycles.
| Leading Market Players |
|---|
| Legrand |
| Aiphone |
| Hikvision |
| Comelit Group |
| Samsung Electronics |
| Panasonic Corporation |
| Dahua Technology |
| Siedle |
| Honeywell International Inc. |
| Others |
Cost & Logistics Intelligence
PoE++ power delivery substitution for legacy low-voltage DC architectures is redrawing supply geography toward Shenzhen and Guangdong fabricators while compressing pricing premiums previously commanded by European electrical conglomerates. This single-cable migration simultaneously concentrates component sourcing in Chinese manufacturing clusters and erodes margin buffers for suppliers lacking captive power-over-Ethernet controller production.
Pricing Analysis
Three-tier pricing structure across premium flush-mounted, standard surface-mounted, and economy wireless levels separates Legrand's heritage-building positioning from Hikvision's cost-optimized outdoor volume. Price differentiation hinges on CE marking grade for EU AI Act facial recognition compliance and installation labor intensity. Pricing pressure stems from semiconductor supply volatility extending image sensor lead times. Gated community property managers show lowest price sensitivity due to bundled access-control platform budgets; Indian middle-income residential buyers exhibit highest sensitivity, prioritizing cost-optimized wireless units.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for European distributors dependent on Zhejiang and Guangdong manufacturing clusters. Video intercom hardware draws from China, South Korea, and Taiwan for image sensors, SoCs, and PoE controllers. Single-source vulnerability concentrates in MIIT GB-standard certification requirements that foreign suppliers must navigate for domestic Chinese channel access. Distribution runs through electrical equipment wholesalers in Germany, security technology integrators in the United States, and construction-material distributors in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Video intercom procurement is crossing into platform-economics territory as API-first architectures displace closed-ecosystem hardware, with property management software integration becoming the primary vendor selection filter.
For Market Incumbents: Secure CE marking roadmaps for EU AI Act biometric compliance before competitors establish regulatory expertise moats. Deepen backward integration into PoE controller and edge AI chip supply to offset semiconductor volatility. Channel control through certified installer networks in Germany and France defends premium positioning against Asian scale manufacturers. For New Entrants and Emerging Players: Anchor in wireless retrofit applications across Paris and Berlin heritage buildings where surface-mounted installation bypasses structural modification restrictions. Target Indian gated community developments in Bangalore and Hyderabad with cost-optimized units certified to BIS standards. API-first go-to-market alignment with property management platforms unlocks subscription revenue attachment absent from hardware-only competitors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vendors with documented European regulatory expertise and cloud-native architecture capabilities. Long-term viability across the analysis window depends on recurring service revenue attachment rather than transactional hardware margins. Acquisition targets should demonstrate algorithmic transparency documentation for EU AI Act compliance. The signal to watch is multifamily operator procurement specifications mandating third-party software interoperability as a primary selection filter.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Roadmapping | CE marking eligibility for facial recognition modules depends on documented algorithmic transparency protocols. |
| API-First Architecture Development | Property management platforms in United States multifamily housing specify interoperability as primary selection filter. |
| PoE++ Native Product Migration | Class A office buildings in Chicago and Houston demand single-cable installation reducing labor costs. |
| Wireless Retrofit Line Expansion | Heritage building restrictions in Paris and Berlin limit structural alterations favoring surface-mounted hardware. |
| Edge AI Motion Detection Integration | Predictive analytics capabilities differentiate premium portfolios from commoditized two-way communication hardware. |
Research Approach
The analysis maps wired, smart, wireless, and modular intercom systems, each validated through property technology officers, security systems integrators, electrical contractor purchasing managers, and multifamily asset managers. Primary interview data triangulates against secondary sources including FCC equipment authorization databases, CE marking notification files, MIIT GB standard publications, and BIS certification registries. Bottom-up unit economics and top-down construction spending patterns converge to establish market sizing boundaries.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, installation methodology, end-user vertical, and feature tier dimensions. CAGRs derive from replacement cycle compression rates and cloud connectivity adoption curves. Forecast inputs include residential construction permit data from China, India, and Brazil, plus multifamily housing transaction velocity in the United States.
Material uncertainties — semiconductor supply disruptions, EU AI Act enforcement variance, and cybersecurity mandate timing across FCC, MIIT, and BIS jurisdictions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and construction cycle continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Security Software for Consumers Market
Security Software
Anomaly Detection Market
Security Software
Cybersecurity Software Market
Security Software
US Hardware Encryption Market
Security Software
Home Webcam Market
Security Software
Asia Pacific Anti Money Laundering Solutions Market
Security Software
Global Digital Identity Solutions Market
Security Software
Mobile Threat Management Security Software Market
Security Software
US Evidence Management Market
Security Software
Global Optical Encryption Market
Security Software
Identity Governance and Administration Market
Security Software
Endpoint Detection and Response [EDR] Market
Security Software
Saudi Arabia Managed Security Services Market
Security Software
Endpoint Detection and Response Market
Security Software
Global Visitor Management System Market
Security Software
Hardware OTP Token Authentication Market