
 Single Sign-On Market | 2026-2036
Single Sign-On Market Size, Share, and Industry Trends Forecast 2026-2036
Single Sign-On Market Outlook
Identity architect scarcity is redrawing competitive dynamics across the Single Sign-On landscape. Okta leverages its cloud-native platform to dominate mid-market and enterprise deployments. CyberArk anchors high-security environments with privileged access integration that extends SSO into critical infrastructure zones. Ping Identity specializes in standards-based federation protocols that compete directly with legacy directory services.
Single Sign-On denotes an authentication mechanism enabling users to access multiple independent software applications through one set of credentials, typically employing Security Assertion Markup Language or OpenID Connect protocols to broker trust between identity providers and service providers. Its primary commercial purpose eliminates credential proliferation while centralizing audit trails for compliance officers and security teams. Cloud-based deployment leads solution uptake as organizations retire on-premises directory infrastructure, while authentication-as-a-service offerings capture expanding margin pools by offloading cryptographic operations to specialized providers. The BFSI end-user segment sustains premium pricing for solutions integrating behavioral biometrics with traditional SSO workflows.
FCC guidelines on communications infrastructure security, SEC cybersecurity disclosure rules, and HIPAA identity safeguards collectively shape product requirements and procurement criteria across North American buyer segments. The EU AI Act and GDPR mandate explainable access decisions, forcing vendors to embed audit-grade logging into authentication flows rather than treating compliance as peripheral functionality. Stakeholders must monitor how zero-trust architecture mandates recast SSO from convenience feature to mandatory control plane across regulated industries.
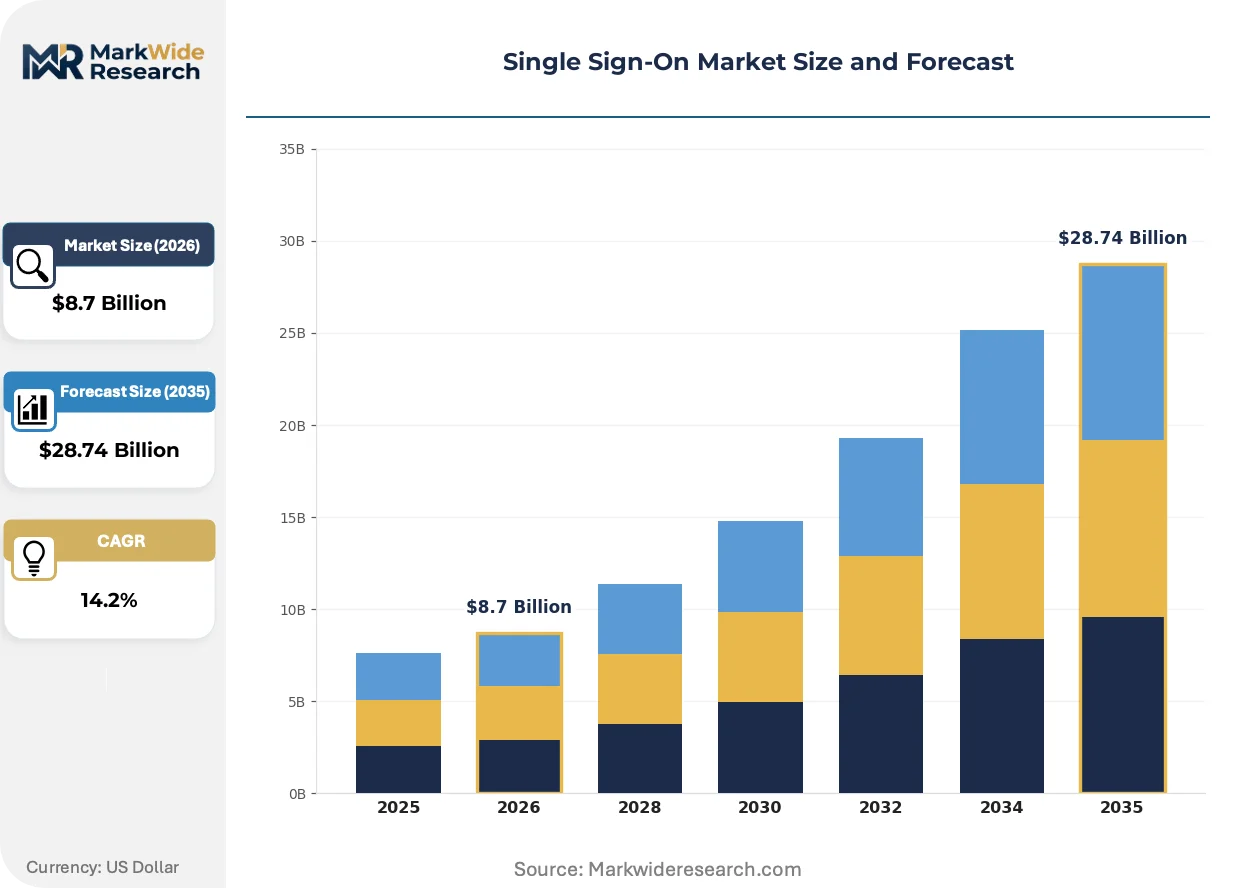
Market Dynamics
Zero-trust architecture mandates are recasting Single Sign-On from convenience feature to mandatory control plane, forcing vendors to embed continuous authentication and micro-segmentation capabilities into core product stacks.
Growth Catalysts
- Federal zero-trust mandates:US government procurement now requires identity-centric security architectures, redirecting public-sector IT budgets toward modern SSO platforms.
- Healthcare EHR fragmentation:Clinicians access an average of fifteen distinct clinical systems per shift, creating acute demand for unified credential management.
- GDPR explainability requirements:European enterprises must produce audit-grade access decision logs, accelerating replacement of legacy directory services.
Market Restraints
- Identity architect scarcity:Deployment complexity outpaces available talent pools, extending implementation timelines and inflating professional services costs.
- Certificate authority concentration:Browser root store policies concentrate trust in a handful of vendors, creating systemic vulnerability to supply chain disruption.
- SAML protocol legacy drag:Thousands of on-premises applications still rely on outdated federation standards, complicating cloud migration roadmaps.
Strategic Opportunities
- Machine identity explosion:Service-to-service authentication volumes now exceed human logins by orders of magnitude, opening adjacent product categories for workload identity.
- EU AI Act compliance services:Automated access decision documentation represents a premium attach opportunity for vendors with embedded logging architectures.
- Behavioral biometrics integration:Continuous authentication combining keystroke dynamics with SSO sessions commands pricing premiums in BFSI deployments.
Industry Challenges
- Legacy mainframe integration:Financial institutions struggle to bridge modern OIDC flows with decades-old RACF and ACF2 security subsystems.
- Cross-border data residency:Multi-national enterprises face conflicting sovereignty requirements when routing authentication traffic across regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Sign-On Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services End User: Healthcare, Education, Retail, BFSI Solution: Identity Management, Authentication as a Service, Access Management, User Provisioning Integration Level: Enterprise Applications, Web Applications, Mobile Applications, Third-Party Services |
| Companies Covered | CyberArk, JumpCloud, Okta, ForgeRock, miniOrange, OneLogin, Microsoft Azure Active Directory, Saviynt, Ping Identity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Sign-On Market Strategic Shifts
Authentication infrastructure is bifurcating between commodity convenience and high-assurance enforcement, with vendors racing to occupy the emerging middle ground of adaptive risk-based access.
Passwordless authentication is fragmenting the credential lifecycle across device-bound keys, biometric sensors, and hardware security modules. Financial services deploy FIDO2/WebAuthn at scale for customer-facing channels. The technology is fragmenting traditional password manager markets while compressing help-desk password reset volumes.
GDPR Article 32 and the EU AI Act jointly mandate explainable access decisions with retention periods extending to seven years. Vendors now embed immutable audit trails directly into authentication flows rather than bolting on compliance modules. European healthcare and public-sector buyers treat this capability as a hard procurement filter.
Consolidated identity marketplaces are displacing point-solution procurement. Enterprise buyers increasingly source SSO, privileged access, and identity governance through unified vendor relationships rather than best-of-breed stitching. This pattern concentrates most visibly in US Fortune 500 accounts where CISOs prioritize vendor reduction over feature depth.
Single Sign-On Market Segmentation
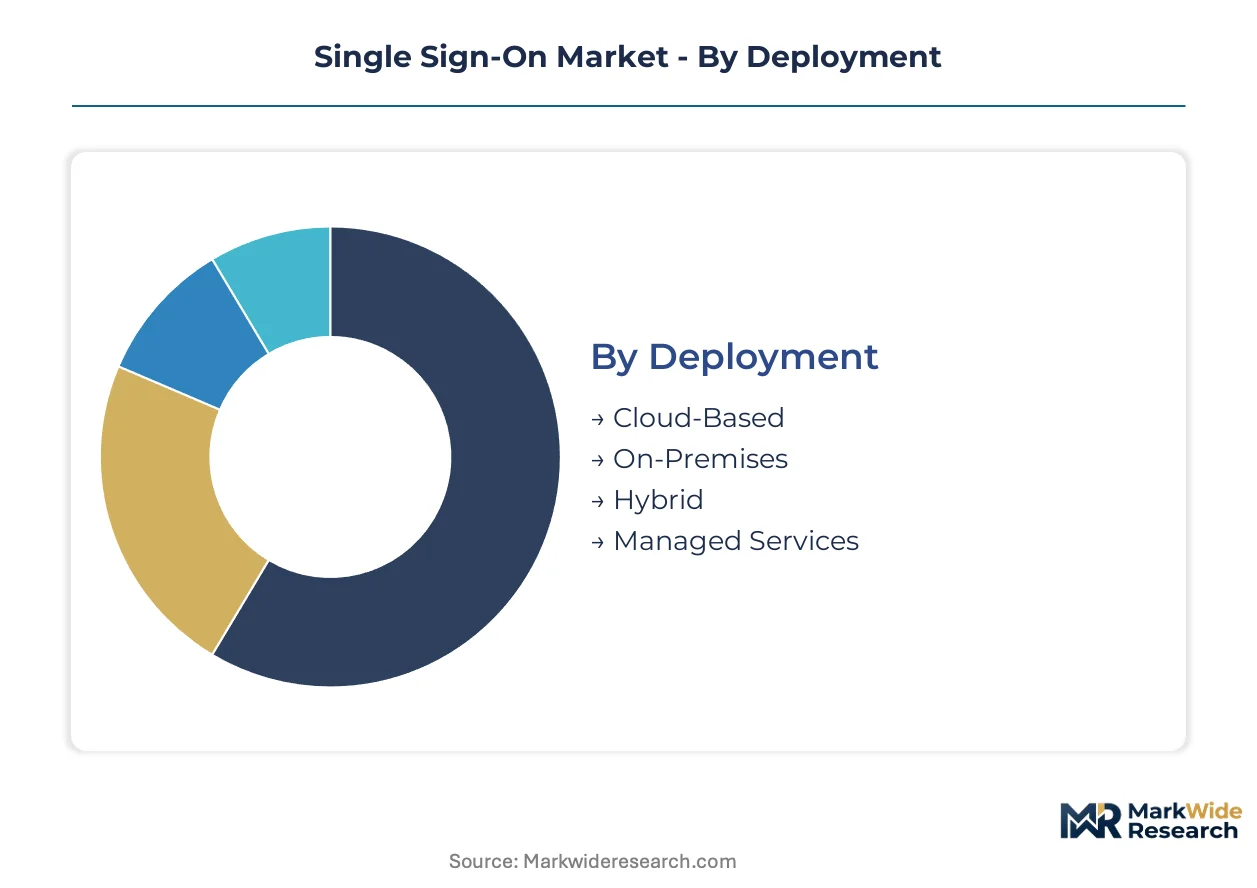
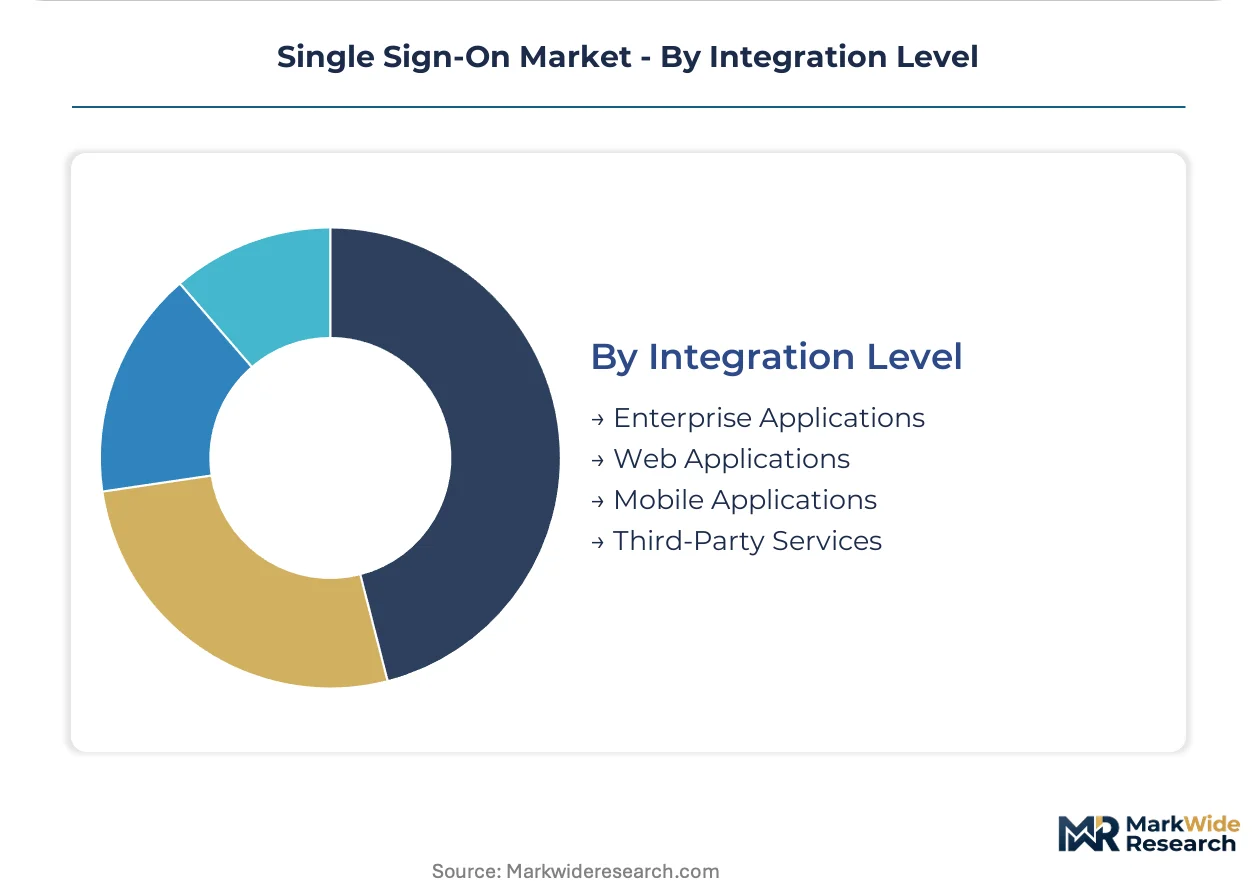
Single Sign-On procurement splits across deployment philosophy, end-user risk profile, solution architecture, and integration depth. Buyers trade off control against operational burden differently across these axes. Vendors must align product packaging to how specific segments weight security assurance versus implementation velocity.
Deployment:
Substitution pressure runs strongest against on-premises installations as cloud-native alternatives close security gaps and simplify compliance documentation.
- Cloud-Based:Multi-tenant architectures offload cryptographic operations to specialized providers. US federal agencies and mid-market enterprises concentrate demand here as zero-trust mandates accelerate retirement of legacy directory infrastructure.
- On-Premises:Dedicated hardware and software stacks maintained within customer data centers. Financial institutions in Frankfurt and defense contractors in Virginia retain this model where data residency requirements override cloud economics.
- Hybrid:Split architectures preserving sensitive authentication flows on-premises while extending session brokering to cloud edge nodes. German automotive manufacturers deploy this pattern to satisfy GDPR Article 32 logging mandates without sacrificing scalability.
- Managed Services:Outsourced operation of SSO infrastructure by third-party security providers. UK National Health Service trusts and Australian state governments source authentication through these arrangements to compensate for identity architect scarcity.
Cloud-Based retains volume leadership; Managed Services holds the steepest expansion curve.
End User:
Cost tier stratification separates premium-security deployments from commodity convenience plays across vertical markets.
- BFSI:Banking, financial services, and insurance operations demand continuous authentication layering behavioral biometrics atop traditional SSO sessions. Singaporean wealth managers and Swiss private banks concentrate procurement here, paying premiums for immutable audit trails required under SEC cybersecurity disclosure rules.
- Healthcare:Clinical environments where clinicians access fragmented electronic health record systems across multiple facilities. US hospital networks and NHS England trusts drive volume, with HIPAA identity safeguards shaping product requirements.
- Education:Universities and K-12 districts managing transient student populations and seasonal access patterns. State university systems in California and Texas optimize for self-service provisioning at scale.
- Retail:Seasonal workforce authentication and customer-facing identity federation. European omnichannel retailers and US grocery chains prioritize friction reduction over assurance depth.
BFSI commands pricing premiums; Healthcare generates the steepest volume climb as EHR fragmentation worsens.
Solution:
Application maturity varies sharply, with adjacent categories threatening to absorb standalone functionality.
- Identity Management:Comprehensive platforms spanning directory services, lifecycle automation, and access certification workflows. Fortune 500 CISOs in the United States consolidate procurement here, treating vendor reduction as priority over feature depth.
- Authentication as a Service:API-delivered verification primitives offloading credential validation to specialized clouds. Developer-centric buyers at fintech startups and SaaS vendors embed these services directly into application code.
- Access Management:Policy enforcement engines governing session duration, step-up triggers, and resource-level permissions. French healthcare networks and German automotive suppliers deploy these for EU AI Act explainability compliance.
- User Provisioning:Automated account creation, modification, and deactivation across target systems. HR-IT integration projects at multinational professional services firms concentrate demand for joiner-mover-leaver automation.
Identity Management holds installed base dominance; Authentication as a Service gains share fastest among cloud-native enterprises.
Integration Level:
Customer type segmentation separates complex enterprise transformation from lightweight departmental deployment.
- Enterprise Applications:Integration with ERP, CRM, and HCM suites spanning SAP, Oracle, and Workday ecosystems. Industrial conglomerates in Japan and Germany sustain demand for mainframe-compatible federation protocols bridging decades-old RACF subsystems with modern OIDC flows.
- Web Applications:Browser-based service provider integration via SAML or OpenID Connect. Mid-market software vendors and professional services firms standardize here, accepting commodity functionality for rapid deployment.
- Mobile Applications:Native iOS and Android SDK implementations with device-bound key storage. US consumer banks and Nordic mobile-first enterprises drive requirements for FIDO2/WebAuthn passwordless flows.
- Third-Party Services:Federation with external SaaS platforms, supply chain portals, and customer identity networks. Dutch logistics operators and Singaporean trade finance platforms prioritize this capability for cross-organizational collaboration.
Enterprise Applications anchor revenue concentration; Mobile Applications climbs fastest as workforce device mix shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC guidelines on communications infrastructure security, SEC cybersecurity disclosure rules, and HIPAA identity safeguards collectively anchor procurement criteria across North American buyer segments. Federal zero-trust mandates redirect public-sector IT budgets toward modern SSO platforms.
United States
US hospital networks and federal agencies drive volume as clinicians access fragmented EHR systems and zero-trust mandates reshape procurement. SEC cybersecurity disclosure rules and HIPAA identity safeguards shape product requirements. Silicon Valley vendors and Washington DC-area integrators concentrate deployment expertise for cloud-native authentication stacks.
Germany
Frankfurt financial institutions and Stuttgart automotive manufacturers retain on-premises models where GDPR Article 32 logging mandates override cloud economics. The EU AI Act and GDPR mandate explainable access decisions with seven-year retention. Bavarian industrial conglomerates deploy hybrid architectures to satisfy sovereignty requirements without sacrificing scalability.
United Kingdom
NHS England trusts source authentication through managed services arrangements to compensate for identity architect scarcity. UK regulators enforce audit-grade access logs for public-sector procurement. London financial services and Manchester healthcare clusters concentrate demand for behavioral biometrics integration.
Singapore
Wealth managers and trade finance platforms in Singapore concentrate procurement for premium-tier SSO with immutable audit trails. The Monetary Authority of Singapore's technology risk management guidelines shape financial sector requirements. Southeast Asian headquarters operations drive cross-border federation demand for regional banking networks.
Japan
Tokyo-based industrial conglomerates sustain demand for mainframe-compatible federation protocols bridging RACF subsystems with modern OIDC flows. METI cybersecurity frameworks influence enterprise procurement standards. Osaka manufacturing clusters and Nagoya automotive suppliers anchor hybrid deployment patterns for legacy system integration.
Single Sign-On Market Competitive Environment
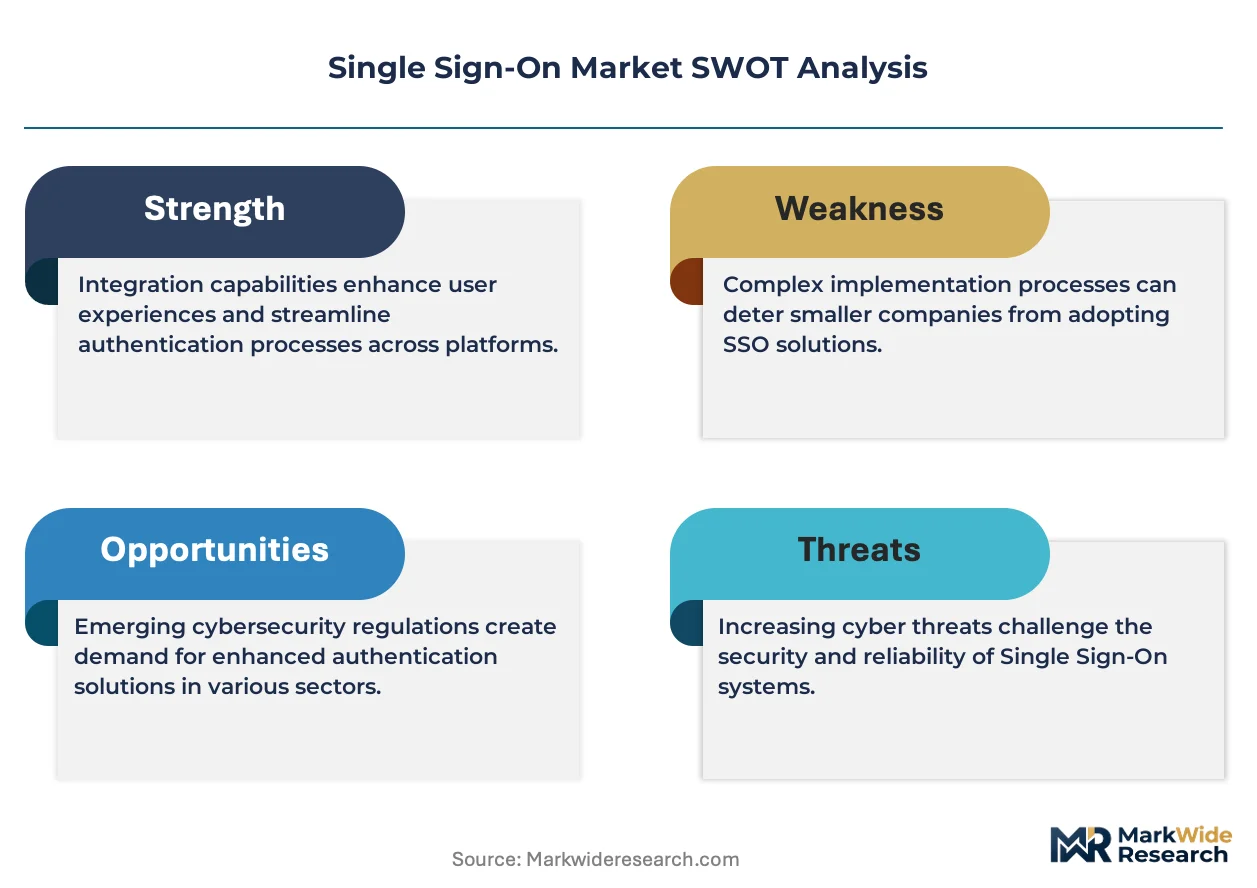
A small set of integrated leaders sits above a broader specialist tier, with cloud-native platforms competing against privileged access anchors and standards-based federation specialists. Identity architect scarcity extends implementation timelines and inflates professional services costs. Three archetypes dominate: cloud-native convenience platforms, high-security privileged access integrators, and standards-based federation protocol specialists. Competitive moves concentrate on portfolio diversification into machine identity and workload authentication, plus strategic partnerships to bridge legacy mainframe environments.
Within the cloud-native tier, Okta and JumpCloud exemplify the velocity-focused archetype targeting mid-market and developer-centric buyers. CyberArk occupies a position among security-anchored providers extending SSO into critical infrastructure zones. Ping Identity represents the standards-specialist vector competing directly with legacy directory services through federation protocol depth.
| Leading Market Players |
|---|
| CyberArk |
| JumpCloud |
| Okta |
| ForgeRock |
| miniOrange |
| OneLogin |
| Microsoft Azure Active Directory |
| Saviynt |
| Ping Identity |
| Others |
Value Chain & Pricing Dynamics
Ninety-day implementation cycles for enterprise SSO deployments concentrate pricing power with vendors possessing pre-built connector libraries, while supply constraints on identity architect talent inflate professional services premiums across North American and European procurement.
Pricing Analysis
Geographic price spreads of 40-60% separate US federal agency contracts from mid-market European SaaS subscriptions. Three-tier pricing structure across premium, standard, and economy levels dominates, with behavioral biometrics integration and immutable audit trails commanding tier premiums. Cost compression in standard-tier cloud subscriptions is intensifying because hyperscaler bundling erodes standalone authentication margins. Healthcare networks exhibit highest price sensitivity due to constrained IT budgets, while Singaporean wealth managers demonstrate lowest sensitivity given regulatory compliance mandates.
Supply Chain Analysis
Inventory of pre-certified federation connectors runs leanest for legacy mainframe protocols, extending deployment timelines for financial institutions bridging RACF subsystems. Cryptographic hardware security modules concentrate supply in Germany, Taiwan, and the United States. Software development draws from open-source identity libraries, commercial SDKs, and proprietary directory services. Single-source vulnerability in browser root store policies creates systemic concentration risk. Distribution runs through direct enterprise sales, hyperscaler marketplaces, and managed security service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Fortune 500 CISOs reduce vendor counts through unified identity platform procurement, compressing margins for point-solution specialists.
For Market Incumbents: Fortify market position by deepening machine identity product lines ahead of workload authentication volume surges, and anchor high-security deployments with privileged access integration that extends SSO into critical infrastructure zones. Certificate authority concentration poses substitution threat from decentralized identity architectures. Vertical integration into behavioral biometrics engines preserves pricing premiums in BFSI segments. For New Entrants and Emerging Players: Managed services gaps in NHS England trusts and Australian state governments offer immediate white-space entry where identity architect scarcity extends implementation timelines. European GDPR Article 32 compliance services represent the most penetrable segment. Developer-centric API-first positioning captures fintech startup procurement bypassing traditional enterprise sales cycles. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because vendor reduction priorities among CISOs will concentrate share among integrated platforms. Acquisition target archetype: standards-based federation specialists with OIDC/SAML protocol depth. Signal to watch: hyperscaler bundling intensity in authentication-as-a-service segments.| Strategic Initiative | Industry Significance |
|---|---|
| Machine Identity Platform Extension | Service-to-service authentication volumes now exceed human logins, opening adjacent revenue pools for workload identity vendors. |
| EU AI Act Compliance Service Layer | Automated access decision documentation with seven-year retention creates premium attach opportunities for vendors with embedded logging. |
| Legacy Mainframe Bridge Partnership | Financial institutions in Tokyo and Frankfurt require RACF-compatible federation protocols to modernize decades-old security subsystems. |
| Behavioral Biometrics Integration | Continuous authentication combining keystroke dynamics commands pricing premiums in Singaporean wealth management and Swiss private banking. |
| Hyperscaler Marketplace Distribution | AWS, Azure, and GCP procurement channels capture mid-market volume as IT departments consolidate cloud vendor relationships. |
Study Parameters
A spread of perspectives from identity architects, CISOs at Fortune 500 enterprises, healthcare IT directors, federal procurement officers, and authentication-as-a-service product managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC cybersecurity disclosure filings, EU AI Act regulatory texts, NHS procurement databases, and hyperscaler identity service documentation. Bottom-up deployment counts triangulated against top-down IT security spending estimates.
Segmentation dimensions modeled span deployment philosophy, end-user risk profile, solution architecture, and integration depth across the projection horizon. CAGRs derive from logistic adoption curves fitted to zero-trust mandate implementation schedules and EHR system consolidation timelines. Cloud migration velocity and machine identity proliferation serve as primary demand-side forecast inputs.
Underlying assumptions cover federal procurement continuity, GDPR enforcement intensity, and identity architect supply elasticity, with deviation risk concentrated in regulatory timeline shifts and hyperscaler bundling acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Business Email Compromise (BEC) Market
Security Software
Cloud Encryption Software Market
Security Software
Cloud File Security Software Market
Security Software
Global Data Loss Prevention Software Market
Security Software
Global Security Assertion Markup Language (SAML) Authentication Market
Security Software
Mass Notification System Market
Security Software
Secaas Market
Security Software
Global Security Software in Telecom Market
Security Software
Global SMS Firewall Market
Security Software
Unified Threat Management (UTM) Market
Security Software
Global Reputation Protection Software Market
Security Software
Global Consumer IAM Market
Security Software
Automotive Endpoint Authentication Market
Security Software
Cyber Attack Simulation Software Market
Security Software
Personal Data Recovery Software Market
Security Software
Global User Activity Monitoring Market