
 Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market | 2026-2036
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market Size, Share, and Industry Trends Forecast 2026-2036
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market Analytics
Atomic layer deposition process windows is narrowing as device geometries shrink below seven nanometers, forcing precursor suppliers to demonstrate sub-part-per-billion metallic impurity thresholds. American Elements leverages its vertically integrated rare earth and transition metal supply chain to control feedstock quality from mine to finished organometallic. Sigma-Aldrich anchors its position through ISO-certified packaging protocols that extend shelf stability for moisture-sensitive copper complexes. TCI Chemicals differentiates via specialized synthesis routes that reduce halogen contamination in cyclooctadiene ligand structures.
Copper (I) hexafluoroacetylacetonate 1,5-cyclooctadiene denotes a coordination compound wherein a copper(I) center binds both a fluorinated beta-diketonate and a cyclic diene ligand, yielding a volatile solid with thermal decomposition temperatures suited to chemical vapor deposition. The material serves primarily as a single-source precursor for depositing ultrathin copper seed layers in interconnect metallization. Chemical synthesis and catalysis applications together dominate current volume offtake, though material science segments are expanding fastest as organic electronics researchers adopt copper-based emitters and charge transport layers. Pharmaceutical end users sustain premium pricing for high-enantiomeric-purity batches used in asymmetric hydrogenation catalysts, while electronics buyers drive standard-grade volume procurement through direct sales channels.
EPA oversight of per- and polyfluoroalkyl substance reporting now captures hexafluoroacetylacetonate derivatives, compelling suppliers to document environmental fate and transport characteristics. REACH registration requirements in Europe mandate full toxicological dossiers for organometallic substances above one-tonne annual thresholds, elevating compliance costs for smaller distributors. Academia and coatings end users must monitor evolving semiconductor fab chemical qualification protocols, as foundry customers tighten incoming material specifications faster than regulatory minima evolve.
Market Dynamics
Atomic layer deposition precursor qualification timelines at sub-7nm semiconductor nodes are compressing supplier development cycles while metallic impurity specifications tighten below part-per-billion thresholds, forcing copper organometallic producers to restructure quality assurance protocols around fab-specific certification requirements.
Growth Catalysts
- Semiconductor interconnect scaling:Copper seed layer deposition demand accelerates as foundries transition to advanced packaging architectures requiring ultrathin metallization. Samsung and TSMC qualification programs for next-generation precursors expand addressable volume.
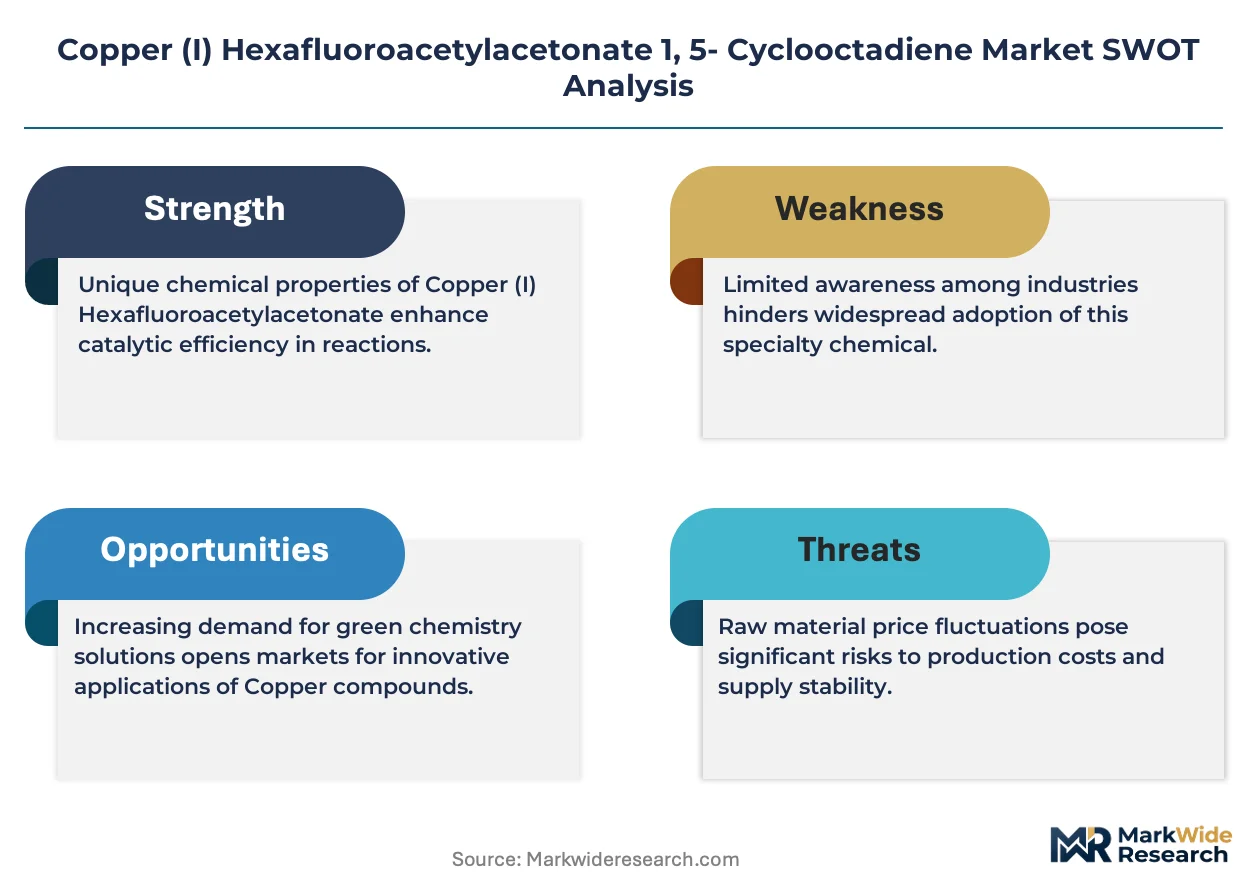
- EPA perfluoroalkyl substance reporting:Environmental compliance documentation requirements now capture hexafluoroacetylacetonate derivatives, creating first-mover advantages for suppliers with pre-filed fate-and-transport studies.
- Organic electronics material science:Research adoption of copper-based emitters and charge transport layers in flexible display prototypes opens adjacent demand channels beyond traditional semiconductor fabrication.
Market Restraints
- Feedstock fluorinated diketone concentration:Russian and Chinese suppliers dominate hexafluoroacetylacetone raw material output, exposing downstream formulators to geopolitical supply disruption and input cost volatility.
- Moisture sensitivity handling infrastructure:Copper(I) complex degradation under atmospheric exposure necessitates glovebox synthesis and argon-sealed packaging, elevating capital intensity for new market entrants.
- Plasma-enhanced atomic layer deposition substitution:Ruthenium and cobalt precursors gain traction at 3nm nodes as alternative barrier-seed metallization schemes, threatening copper's interconnect dominance at leading-edge geometries.
Strategic Opportunities
- Indian pharmaceutical catalyst market:Asymmetric hydrogenation demand for high-enantiomeric-purity copper complexes remains underpenetrated by established electronics-focused suppliers, creating white space for dedicated pharmaceutical-grade production.
- EU Green Deal sustainable chemistry incentives:REACH-registered organometallic substances with documented environmental fate profiles qualify for green public procurement preferences in European research funding allocations.
- Direct-to-fab distribution channels:Bypassing traditional chemical distributor markups through qualified supplier status at Samsung, SK Hynix, and Tokyo Electron facilities captures margin expansion opportunities.
Industry Challenges
- Organometallic synthesis expertise scarcity:Schlenk line operation and air-free chemistry specialization required for copper(I) complex production concentrates in aging academic and national laboratory talent pools.
- Fab qualification timeline compression:Incoming material specification updates at Samsung and TSMC now outpace standard ISO certification renewal cycles, forcing suppliers to maintain parallel documentation streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market |
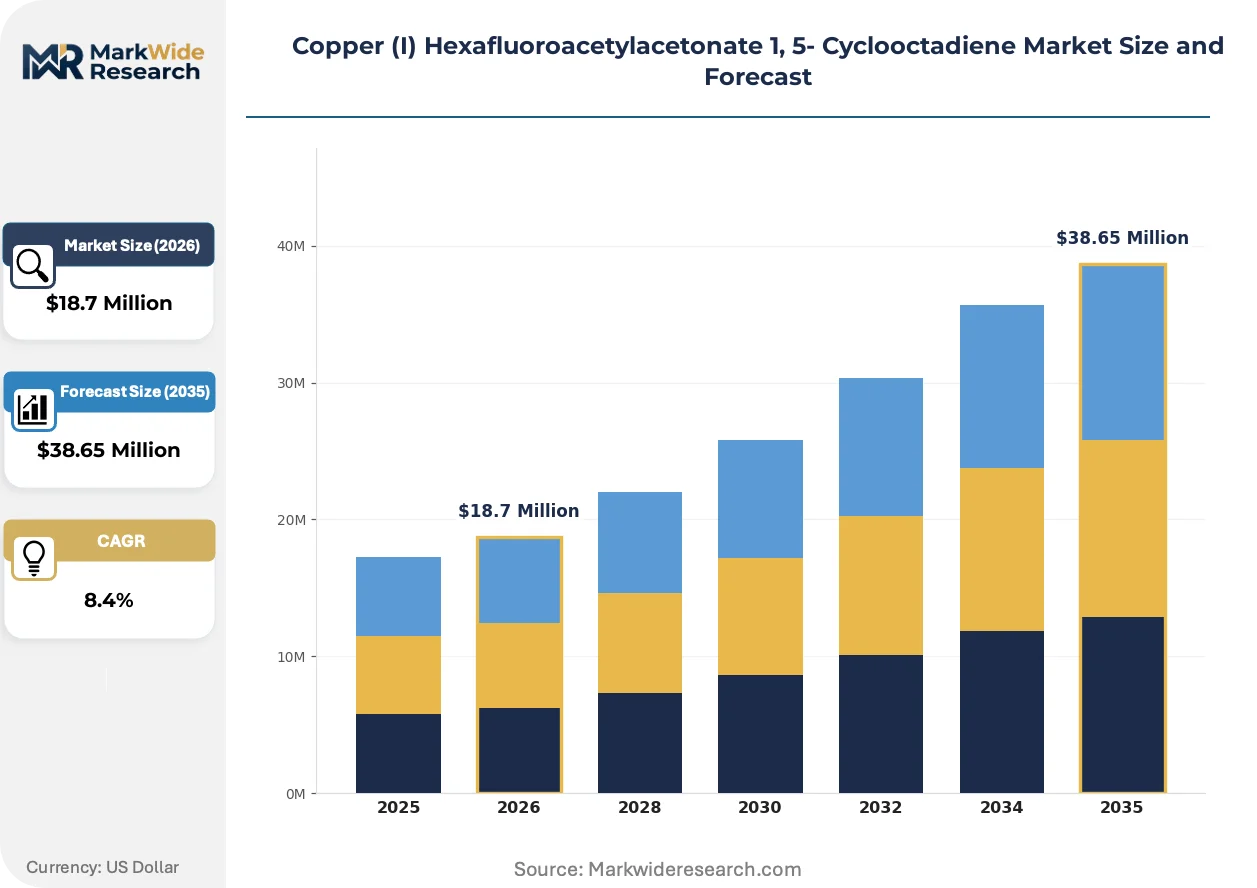
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $38.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Complex, Hexafluoroacetylacetonate, Cyclooctadiene, Salts Application: Chemical Synthesis, Catalysis, Material Science, Research End User: Pharmaceuticals, Electronics, Coatings, Academia Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | American Elements, Alfa Chemistry, BOC Sciences, EpiValence, GasChem, Sigma-Aldrich, TCI Chemicals, ABCR GmbH, Biosynth Carbosynth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market Evolving Landscape
Copper organometallic precursor development is bifurcating between legacy chemical vapor deposition process optimization and emerging atomic layer deposition precision requirements, with synthesis innovation increasingly directed at ligand engineering for enhanced thermal stability and reduced decomposition temperature windows.
Vapor-phase deposition equipment is hybridizing copper(I) precursor delivery systems with in-situ spectroscopic monitoring capabilities. Lam Research and Applied Materials integrate residual gas analyzers directly into ALD reactor chambers for real-time decomposition pathway verification. This convergence is compressing process development timelines from months to weeks for new precursor qualification.
REACH authorization procedures for fluorinated organometallics are tightening substance volume thresholds and toxicological data requirements. ECHA's 2024 updated guidance on persistent, bioaccumulative, and toxic substance classification now captures hexafluoroacetylacetonate complexes above one-tonne annual manufacture. European electronics chemical distributors are consolidating registration dossiers to spread compliance cost burdens across supplier networks.
Foundry procurement departments are consolidating precursor supplier panels from twelve-plus vendors to four-to-six strategic partners per material category. Samsung's 2023 supplier rationalization program eliminated mid-tier chemical distributors lacking direct synthesis capabilities. This concentration is visible most acutely in South Korea's Pyeongtaek and Hwaseong manufacturing clusters, where qualified supplier status now requires dedicated technical service personnel co-located at fab sites.
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market Segmentation
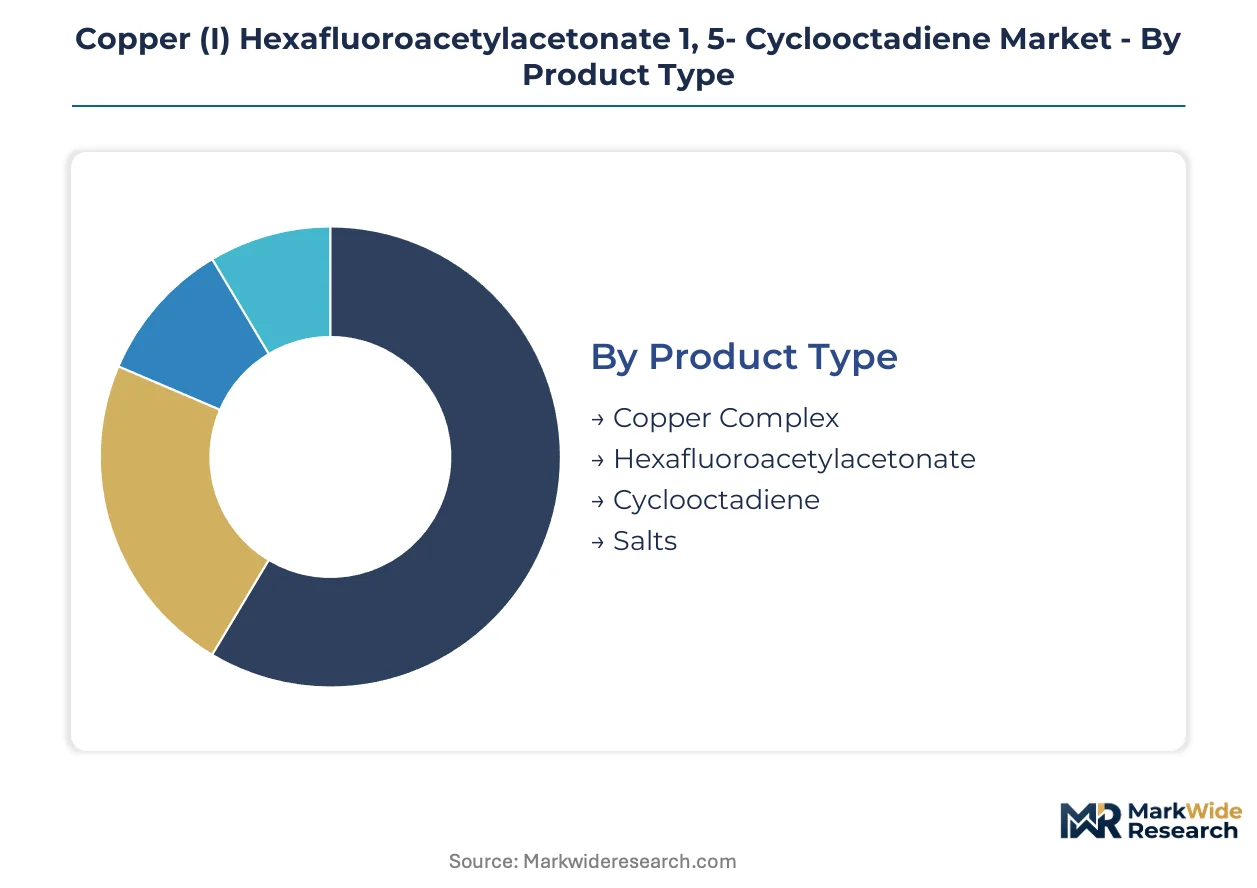
Precursor qualification requirements differ sharply across end-use applications, forcing suppliers to maintain parallel product specifications. Segment-specific handling protocols—moisture sensitivity for electronics, enantiomeric purity for pharmaceuticals—determine margin structures and customer retention economics.
Product Type:
After-sales service intensity varies dramatically by product chemistry, with copper complexes demanding glovebox technical support while salts require minimal field intervention.
- Copper Complex:Volatile organometallic compounds with hexafluoroacetylacetonate and cyclooctadiene ligands bound to copper(I) centers. Samsung and TSMC qualification programs concentrate demand for electronic-grade material with sub-ppb metallic impurity thresholds.
- Hexafluoroacetylacetonate:Fluorinated beta-diketonate ligand precursors requiring specialized synthesis under inert atmosphere. South Korean foundry supply chains drive volume offtake for atomic layer deposition process development.
- Cyclooctadiene:Cyclic diene ligand structures where TCI Chemicals has reduced halogen contamination through specialized synthesis routes.
- Salts:Ionic copper derivatives with simpler handling requirements and broader chemical synthesis applications.
By volume, copper complexes lead. By growth pace, hexafluoroacetylacetonate ligand precursors are climbing the fastest.
Application:
Cost tier stratification separates commodity chemical synthesis from premium semiconductor-grade atomic layer deposition precursors.
- Chemical Synthesis:Standard-grade material for organic transformation reactions with modest purity requirements. Pharmaceutical manufacturers in India sustain premium pricing for high-enantiomeric-purity batches.
- Catalysis:Asymmetric hydrogenation applications demanding precise ligand geometry control. European research funding under EU Green Deal incentives favors REACH-registered substances with documented environmental fate profiles.
- Material Science:Copper-based emitters and charge transport layers for flexible display prototypes. Organic electronics researchers in Japan are expanding adoption fastest.
- Research:Small-batch procurement with stringent documentation requirements for academic laboratories.
Chemical synthesis dominates current volume. Material science applications are gaining share fastest as organic electronics mature.
End User:
Customer type determines pricing architecture, with electronics buyers driving standard-grade volume procurement and pharmaceuticals sustaining premium tiers.
- Pharmaceuticals:Asymmetric hydrogenation catalyst demand requiring high-enantiomeric-purity batches. Indian pharmaceutical catalyst market remains underpenetrated by electronics-focused suppliers.
- Electronics:Semiconductor fabrication and atomic layer deposition precursor consumption. Samsung, SK Hynix, and Tokyo Electron facilities consolidate supplier panels to four-to-six strategic partners.
- Coatings:Thin-film deposition for functional surface applications with moderate purity specifications.
- Academia:Research procurement subject to evolving fab chemical qualification protocols as foundry specifications tighten.
Electronics generates the highest volume. Pharmaceuticals command the steepest price premiums per kilogram.
Distribution Channel:
Supply concentration shapes channel economics, with direct-to-fab relationships capturing margin expansion opportunities.
- Direct Sales:Qualified supplier status at major foundry facilities bypassing traditional distributor markups. Samsung's 2023 supplier rationalization eliminated mid-tier distributors lacking direct synthesis capabilities.
- Distributors:Regional chemical distributors consolidating REACH registration dossiers to spread compliance cost burdens across European networks.
- Online Retail:Small-batch procurement for research and academic end users with standardized packaging protocols.
- Wholesalers:Bulk material handling for commodity-grade chemical synthesis applications.
Direct sales channels lead by revenue contribution. Online retail is expanding most quickly for research-scale procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese raw material suppliers dominate hexafluoroacetylacetone feedstock exports to South Korean and Japanese foundry networks, creating a concentrated trade corridor that shapes regional procurement strategies for copper organometallic precursors.
South Korea
Samsung Electronics and SK Hynix drive atomic layer deposition precursor demand through aggressive sub-7nm node qualification programs. The country's Ministry of Trade, Industry and Energy (METI) coordinates domestic chemical supplier development under national semiconductor self-sufficiency initiatives. Pyeongtaek and Hwaseong manufacturing clusters now require dedicated technical service personnel co-located at fab sites for qualified supplier status.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor precision equipment and materials demand for copper seed layer deposition. The Ministry of Economy, Trade and Industry (METI) enforces chemical substance reporting under the Act on the Evaluation of Chemical Substances and Regulation of Their Manufacture. The Tsukuba and Osaka industrial corridors concentrate organic electronics research adopting copper-based emitters for flexible display prototypes.
United States
Intel and Applied Materials sustain demand for advanced packaging metallization precursors amid domestic fab construction expansion. EPA oversight of per- and polyfluoroalkyl substance reporting now captures hexafluoroacetylacetonate derivatives, compelling suppliers to document environmental fate characteristics. The Phoenix semiconductor corridor and Hudson Valley research clusters represent primary consumption centers for electronic-grade organometallics.
Germany
BASF and Merck KGaA leverage existing organometallic synthesis infrastructure to serve European semiconductor equipment manufacturers. ECHA's REACH authorization procedures for fluorinated organometallics mandate full toxicological dossiers above one-tonne annual thresholds. The Rhine-Main and Upper Bavaria chemical clusters consolidate registration dossiers to spread compliance cost burdens across distributor networks.
India
Dr. Reddy's and Sun Pharmaceutical sustain asymmetric hydrogenation catalyst demand for high-enantiomeric-purity copper complexes. The Central Drugs Standard Control Organization (CDSCO) regulates pharmaceutical-grade organometallic imports through active pharmaceutical ingredient registration requirements. Hyderabad and Ahmedabad manufacturing hubs remain underpenetrated by electronics-focused suppliers, creating white space for dedicated pharmaceutical-grade production.
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market Competitive Landscape
On the supply side, the industry is bifurcating between vertically integrated rare earth specialists and distributor-dependent formulators lacking direct synthesis capabilities. Three strategic archetypes dominate: mine-to-finished-product integrators controlling feedstock quality; ISO-certified packaging specialists extending shelf stability for moisture-sensitive complexes; and regional distributors consolidating regulatory compliance dossiers. Capacity expansion and strategic partnerships represent the dominant competitive moves, as foundry supplier panel consolidation from twelve-plus vendors to four-to-six strategic partners per material category accelerates.
Among vertically integrated specialists, American Elements exemplifies the mine-to-finished-product archetype through captive control over transition metal feedstocks. Sigma-Aldrich occupies a position within the certification-intensive tier, anchoring quality assurance through standardized packaging protocols. TCI Chemicals represents the synthesis-specialist vector, with technical positioning centered on contamination reduction in ligand structures. These three companies illustrate the capability segmentation—upstream integration, certification infrastructure, and synthesis specialization—that defines competitive positioning in electronic-grade organometallic supply.
| Leading Market Players |
|---|
| American Elements |
| Alfa Chemistry |
| BOC Sciences |
| EpiValence |
| GasChem |
| Sigma-Aldrich |
| TCI Chemicals |
| ABCR GmbH |
| Biosynth Carbosynth |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese hexafluoroacetylacetone feedstock production is compressing input costs for downstream copper complex formulators while simultaneously eroding pricing power at the ligand precursor tier, forcing suppliers to recalibrate margin extraction toward electronic-grade certification premiums and direct-to-fab service bundling.
Pricing Analysis
Sub-7nm node qualification premiums for atomic layer deposition precursors command substantial markups over legacy chemical vapor deposition grades, while prior-generation material faces commoditization pressure from plasma-enhanced ALD substitution threats. Three-tier pricing structure across electronic-grade, pharmaceutical-grade, and standard research-grade levels separates buyers by metallic impurity thresholds and enantiomeric purity specifications. Cost compression in standard-grade chemical synthesis is intensifying because Indian pharmaceutical manufacturers are consolidating procurement volumes and demanding volume discounts. Electronics buyers at Samsung and TSMC facilities exhibit the lowest price sensitivity due to fab qualification switching costs, whereas academic research laboratories remain highly price-elastic and comparison-shop across online retail channels.
Supply Chain Analysis
Export-control restrictions on fluorinated organometallic synthesis equipment under US Commerce Department regulations are limiting technology transfer to emerging producers and concentrating advanced production capacity among established suppliers with grandfathered equipment licenses. Geographic supply concentration centers on China for hexafluoroacetylacetone feedstock, South Korea for copper complex formulation, and Japan for cyclooctadiene ligand purification. Raw material dependencies draw from Russian-mined copper concentrates, Chinese-manufactured fluorinated diketones, and petroleum-derived diene feedstocks. Single-source vulnerability in hexafluoroacetylacetone supply exposes formulators to geopolitical disruption and input cost volatility. Distribution runs through direct sales channels to qualified fab suppliers, bypassing traditional chemical distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase driven by semiconductor fab capacity expansion cycles, as foundry capital expenditure commitments for sub-7nm node ramp-ups translate into precursor procurement acceleration after a prolonged qualification-heavy trough period.
For Market Incumbents: Harden fab qualification moats by embedding dedicated technical service personnel at Samsung Pyeongtaek and TSMC Arizona facilities, converting supplier panel consolidation from threat to structural advantage. Deepen backward integration into hexafluoroacetylacetone synthesis to offset Chinese feedstock price volatility and capture margin upstream. Pre-file EPA environmental fate documentation for hexafluoroacetylacetonate derivatives to secure first-mover compliance positioning ahead of regulatory threshold tightening.
For New Entrants and Emerging Players: Build out pharmaceutical-grade production capabilities targeting Indian asymmetric hydrogenation catalyst demand, where electronics-focused incumbents remain underpenetrated and CDSCO registration requirements create defensible entry barriers. Establish Schlenk line synthesis expertise through academic laboratory partnerships to overcome organometallic chemistry talent scarcity. Pursue EU Green Deal sustainable chemistry incentives by documenting REACH-compliant environmental fate profiles for green public procurement qualification.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-qualified suppliers at major foundry facilities, where multi-year precursor offtake agreements and technical service retainers generate predictable cash flows insulated from spot market volatility. Target acquisition candidates with captive hexafluoroacetylacetone synthesis capabilities and existing Samsung or SK Hynix qualified supplier status. Monitor EPA perfluoroalkyl substance reporting threshold adjustments as the inflection signal for compliance cost restructuring and supplier consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Synthesis | Captive hexafluoroacetylacetone production insulates margins from Chinese supply volatility and geopolitical disruption. |
| Direct-to-Fab Technical Service Deployment | Co-located personnel at Samsung and TSMC facilities secures qualified supplier status amid panel consolidation. |
| REACH Registration Dossier Consolidation | European distributors spreading ECHA compliance costs across networks preserve market access above one-tonne thresholds. |
| Pharmaceutical-Grade Capacity Addition | Dedicated high-enantiomeric-purity production targets underpenetrated Indian catalyst demand with premium pricing. |
| EPA Environmental Fate Pre-Filing | First-mover documentation of perfluoroalkyl substance characteristics creates compliance advantage for hexafluoroacetylacetonate derivatives. |
Research Methodology
Initial hypotheses were tested against primary input from semiconductor fab procurement managers, organometallic synthesis chemists, pharmaceutical catalyst procurement leads, and chemical distributor regulatory affairs directors and refined through secondary validation against customs trade data, SEC 10-K filings, ECHA registration dossiers, and foundry supplier qualification documentation. Bottom-up volume estimates from individual precursor consumption rates at named fab facilities were triangulated against top-down market sizing from trade flow analysis and industry association reports.
Demand-supply balance modeling across the projection horizon incorporated semiconductor capital expenditure cycles, foundry node transition timelines, and pharmaceutical catalyst procurement patterns. Segmentation dimensions included product chemistry tier, end-use application, customer type, and regional manufacturing cluster. CAGRs were derived from fitted growth curves calibrated to historical qualification-to-volume conversion rates and projected fab capacity ramps. Industry-specific forecast inputs captured atomic layer deposition equipment installation data and EPA regulatory threshold evolution scenarios.
Stress conditions across hexafluoroacetylacetone feedstock supply disruption, plasma-enhanced ALD substitution acceleration, and REACH authorization timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about continued copper interconnect dominance at nodes above 3nm and stable pharmaceutical catalyst demand growth. Material shifts in foundry metallization material selection or perfluoroalkyl substance regulatory reclassification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Flame Retardants Market
Specialty Chemicals
Anti-Static Control Products Market
Specialty Chemicals
13X Molecular Sieve Activated Powder Market
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Tubatoxin Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Photo Emulsion Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Antioxidant 412S Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
Asia-Pacific UV Stabilizers Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
GLDA Market