
 Metal Biocide Market | 2026-2036
Metal Biocide Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Biocide Market Foresight
The EU Green Deal's chemical sustainability benchmarks is realigning procurement criteria across European coatings manufacturers. BASF SE leverages its integrated silver salt production network to serve pharmaceutical-grade applications. Lonza anchors its position through captive supply of quaternary ammonium precursors. Dow competes on geographic dominance in North American municipal water contracts.
Metal biocides are antimicrobial agents incorporating metallic ions—principally silver, copper, or zinc—typically formulated at 0.1-10% active concentration to disrupt microbial cell membranes through oxidative stress mechanisms. These compounds serve industrial and commercial markets requiring durable, non-volatile protection against bacterial and fungal colonization. Silver-based formulations command premium positioning in healthcare device coatings due to sustained ion-release kinetics and regulatory acceptance for patient-contact applications. Copper variants dominate agricultural fungicide blends where broad-spectrum efficacy and lower phytotoxicity thresholds align with integrated pest management protocols. Zinc formulations occupy cost-sensitive construction segments, particularly in antimicrobial drywall and sealant applications where margin pools favor commodity-scale supply.
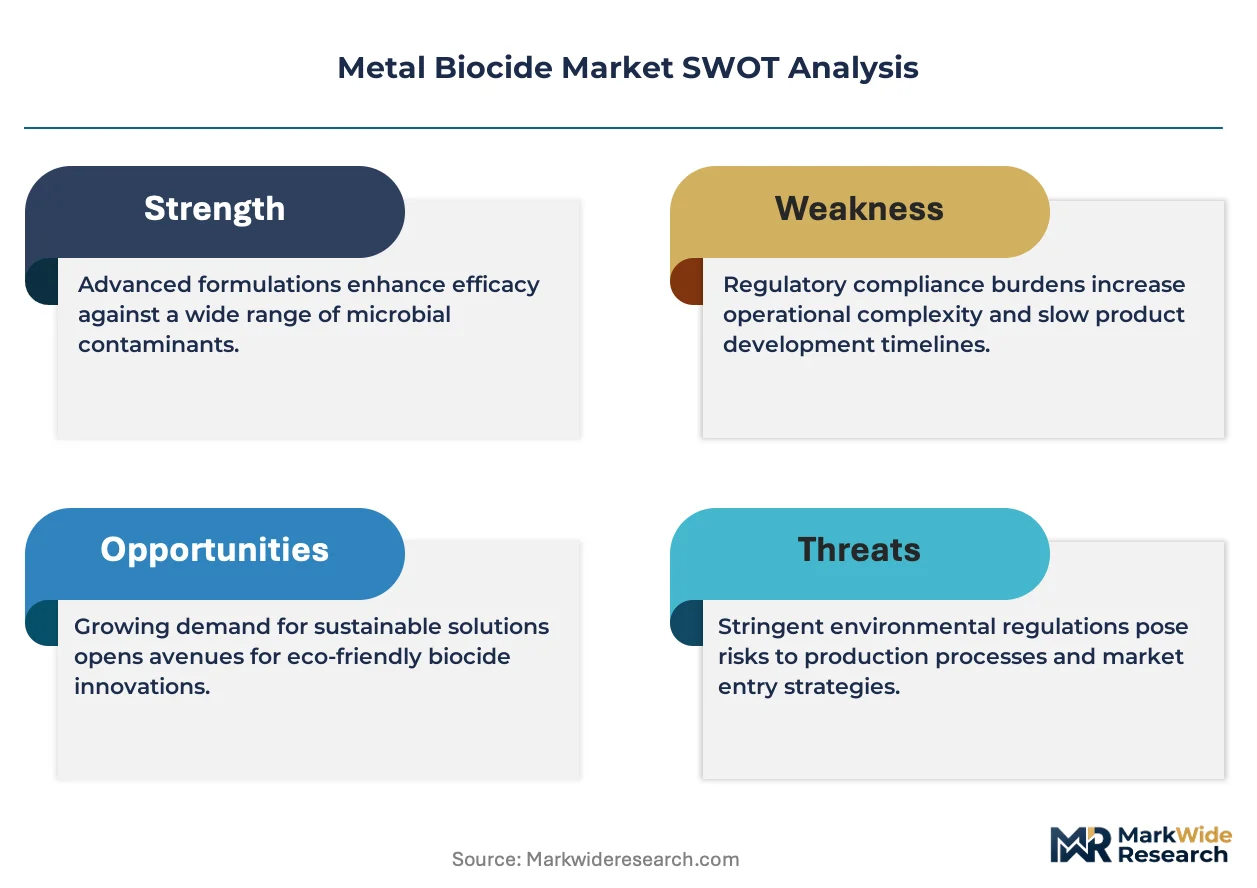
EPA registration requirements under FIFRA govern biocidal claims in US consumer and industrial products, compelling multi-year efficacy validation that filters out smaller formulation entrants. ECHA's Biocidal Products Regulation in Europe mandates active substance approval and product authorization, creating a dual-compliance burden that advantages established registrants with dedicated regulatory affairs capacity. China's MEE enforces discharge limits on metal-containing effluents, pushing domestic manufacturers toward controlled-release delivery systems. Stakeholders must weigh the capital requirements of parallel regulatory dossiers against the defensive moat these barriers construct around incumbent suppliers.
Market Dynamics
EPA discharge rule tightening across US industrial corridors is forcing cooling tower operators toward higher-frequency copper-based biocide procurement cycles, compressing supplier lead time tolerances and favoring regional blending capacity over import-dependent sourcing.
Growth Catalysts
- Silver-ion textile complexes:China's MIIT antimicrobial textile standards redirect formulation demand toward silver-ion delivery systems in apparel and medical textiles.
- Copper agricultural blends:Integrated pest management protocols in specialty crop regions favor copper variants for broad-spectrum fungal control with lower phytotoxicity thresholds.
- Healthcare device coatings:Sustained ion-release kinetics in silver-based formulations command premium positioning for patient-contact applications requiring durable antimicrobial protection.
Market Restraints
- Copper price volatility:Mining supply disruptions and speculative commodity positioning create input cost instability for copper-based formulation producers.
- Dual-compliance burden:ECHA's Biocidal Products Regulation active substance approval and product authorization requirements filter out smaller formulation entrants lacking dedicated regulatory affairs capacity.
- Zinc substitution ceiling:Performance limitations in high-humidity environments restrict zinc formulations to cost-sensitive construction segments where efficacy trade-offs are acceptable.
Strategic Opportunities
- Controlled-release delivery systems:China's MEE discharge limits on metal-containing effluents push domestic manufacturers toward advanced encapsulation technologies with extended release profiles.
- Pharmaceutical-grade silver salts:Integrated production networks serving medical device and wound care applications capture margin pools unavailable to commodity-grade suppliers.
- Municipal water contract consolidation:Geographic dominance in North American municipal procurement creates defensive positioning through multi-year service agreements and technical support integration.
Industry Challenges
- FIFRA registration timelines:Multi-year efficacy validation requirements under EPA rules compress cash conversion cycles and demand sustained R&D commitment without near-term revenue.
- Formulation chemist scarcity:Specialized expertise in metal ion stabilization and controlled-release kinetics concentrates among legacy suppliers, constraining new entrant technical capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Biocide Market |
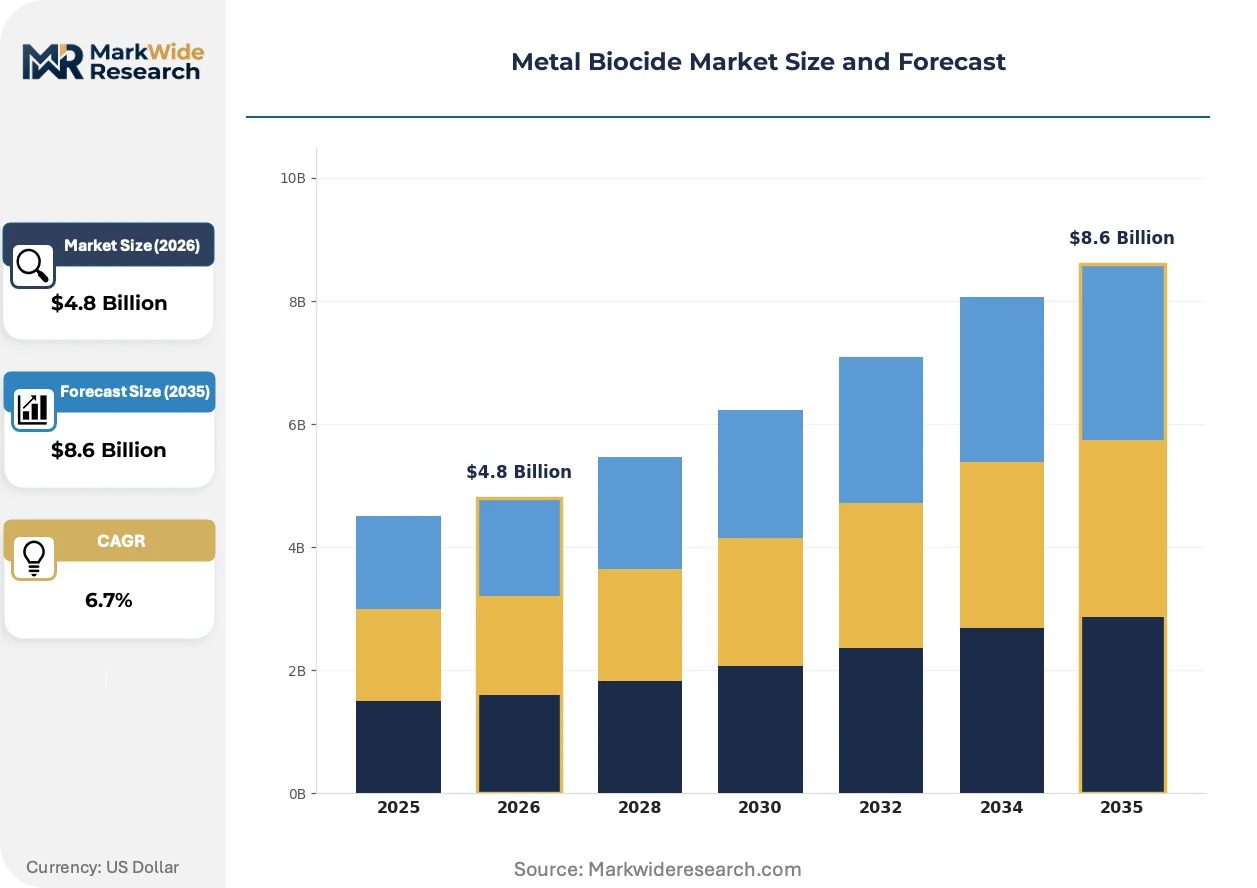
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver, Copper, Zinc, Others Application: Water Treatment, Agriculture, Coatings, Healthcare Form: Powder, Liquid, Granular, Tablets End User: Food Industry, Textile, Construction, Municipal |
| Companies Covered | BASF SE, Clariant, Dow, Lonza, Milliken Chemical Company, Troy Corporation, SANITIZED AG, Lanxess, Noble Biomaterials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Biocide Market Shifts & Advancements
Active reformulation around controlled-release mechanisms and ion-stabilization chemistry is reshaping competitive positioning, as discharge regulations and efficacy durability requirements converge to favor technical sophistication over commodity scale.
Encapsulated silver nanoparticles with pH-responsive release kinetics are expanding into chronic wound dressings and implantable device coatings. Medical device manufacturers in Germany and Switzerland adopt these systems to satisfy MDR biocompatibility requirements while extending protection intervals. The technology is expanding into premium healthcare segments previously served by conventional antibiotic coatings, compressing addressable market share for organic biocide alternatives.
REACH authorization timelines for existing metal biocide actives are compressing registration windows and forcing parallel dossier preparation across multiple regulatory jurisdictions. European coatings manufacturers requalify supply chains to exclude substances facing sunset date uncertainty. Agricultural fungicide blenders in France and Spain accelerate copper complex formulations to replace actives entering regulatory review.
Water treatment utilities along the US Gulf Coast petrochemical belt consolidate procurement through multi-year technical service agreements bundling chemical supply with monitoring equipment and dosage optimization. Municipal buyers in Texas and Louisiana favor suppliers with captive regional blending capacity over distant competitors. This consolidation rewards integrated service models and marginalizes transaction-only chemical distributors.
Metal Biocide Market Segmentation
Metal biocide procurement cycles vary sharply across end-use contexts, with cooling tower operators replacing copper formulations quarterly while medical device coatings demand silver-ion systems validated for multi-year durability. Segmentation clarity enables suppliers to align controlled-release investments with specific regulatory and performance thresholds.
Product Type:
Upgrade cycles in industrial water treatment are compressing procurement intervals for copper-based formulations as EPA discharge monitoring intensifies.
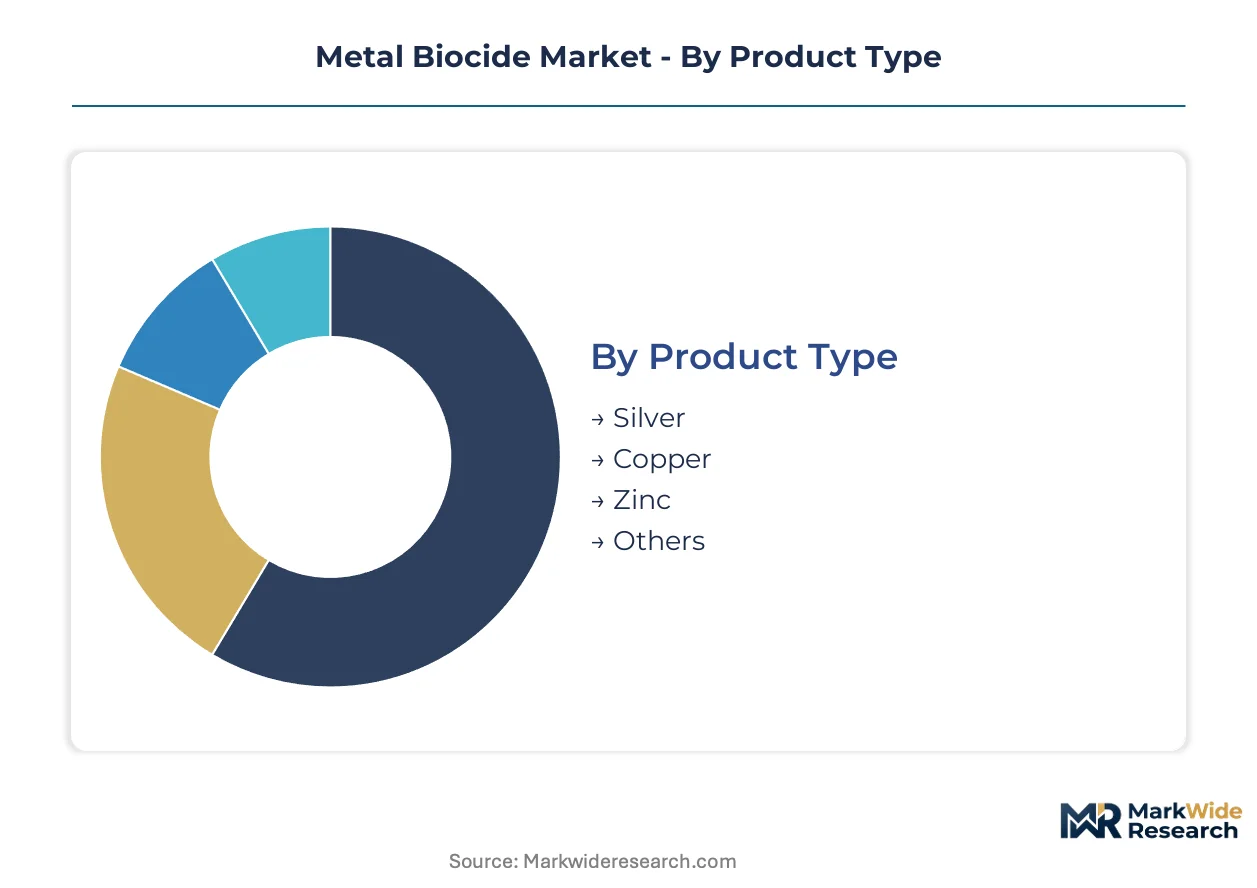
- Silver:Ion-release kinetics in silver salt complexes enable sustained antimicrobial action in implantable devices and chronic wound dressings. German and Swiss medical device manufacturers specify these systems to satisfy MDR biocompatibility requirements while reducing replacement frequency.
- Copper:Broad-spectrum oxidative mechanisms in copper sulfate and oxide formulations dominate agricultural fungicide blends and cooling tower applications. Gulf Coast petrochemical operators in Texas and Louisiana favor these variants for integrated pest management protocols where phytotoxicity limits constrain organic alternatives.
- Zinc:Cost-positioned zinc pyrithione and oxide variants serve antimicrobial drywall and construction sealant segments where humidity tolerance trade-offs are acceptable.
- Others:Emerging metal complexes including titanium and gold nanoparticles occupy niche research-phase applications in specialized coating formulations.
Volume placements concentrate in copper formulations for industrial water treatment; the faster expansion belongs to silver-ion complexes for healthcare device applications.
Application:
Cost tier differentiation separates commodity-scale agricultural users from premium healthcare segments where regulatory validation investments create margin pools unavailable to standard-grade suppliers.
- Water Treatment:Municipal and industrial cooling tower operators deploy copper-based biocides at 0.5-2 ppm active concentration to control Legionella and biofilm formation. Texas and Louisiana utilities bundle chemical supply with automated monitoring systems under multi-year technical service agreements.
- Agriculture:Copper hydroxide and oxychloride formulations dominate vineyard and orchard fungicide programs in France and Spain. REACH authorization uncertainty for legacy actives accelerates requalification toward metal-based alternatives with established regulatory dossiers.
- Coatings:Silver-ion additives in architectural and marine coatings provide durable surface protection against bacterial colonization in high-touch environments.
- Healthcare:Patient-contact devices and wound care products specify pharmaceutical-grade silver salts with validated ion-release profiles. FDA and EMA dual compliance requirements filter out commodity-grade suppliers lacking dedicated regulatory affairs capacity.
Revenue concentration sits with water treatment procurement cycles; healthcare coatings are climbing the fastest as MDR biocompatibility standards displace conventional antibiotic alternatives.
Form:
Supply concentration among legacy formulators with captive blending capacity favors liquid and powder delivery systems over specialized tablet configurations.
- Powder:Dry silver and copper salts enable precise dosing in agricultural spray tank mixing and industrial bulk handling systems. Chinese manufacturers favor powder forms for domestic textile finishing operations under MIIT antimicrobial standards.
- Liquid:Pre-dispersed aqueous suspensions simplify automated injection in cooling tower and municipal water treatment infrastructure. Regional blending facilities along the US Gulf Coast maintain captive liquid formulation capacity to compress lead times.
- Granular:Controlled-dissolution granules serve slow-release applications in soil treatment and construction material integration where extended protection intervals reduce reapplication frequency.
- Tablets:Compressed solid forms target small-scale potable water and recreational water applications requiring portable dosing convenience.
Procurement volume clusters in liquid formulations for industrial water treatment; granular systems are gaining share fastest in construction material integration.
End User:
Customer type maturity separates regulated healthcare and food safety applications from price-sensitive construction segments where zinc formulations compete on input cost.
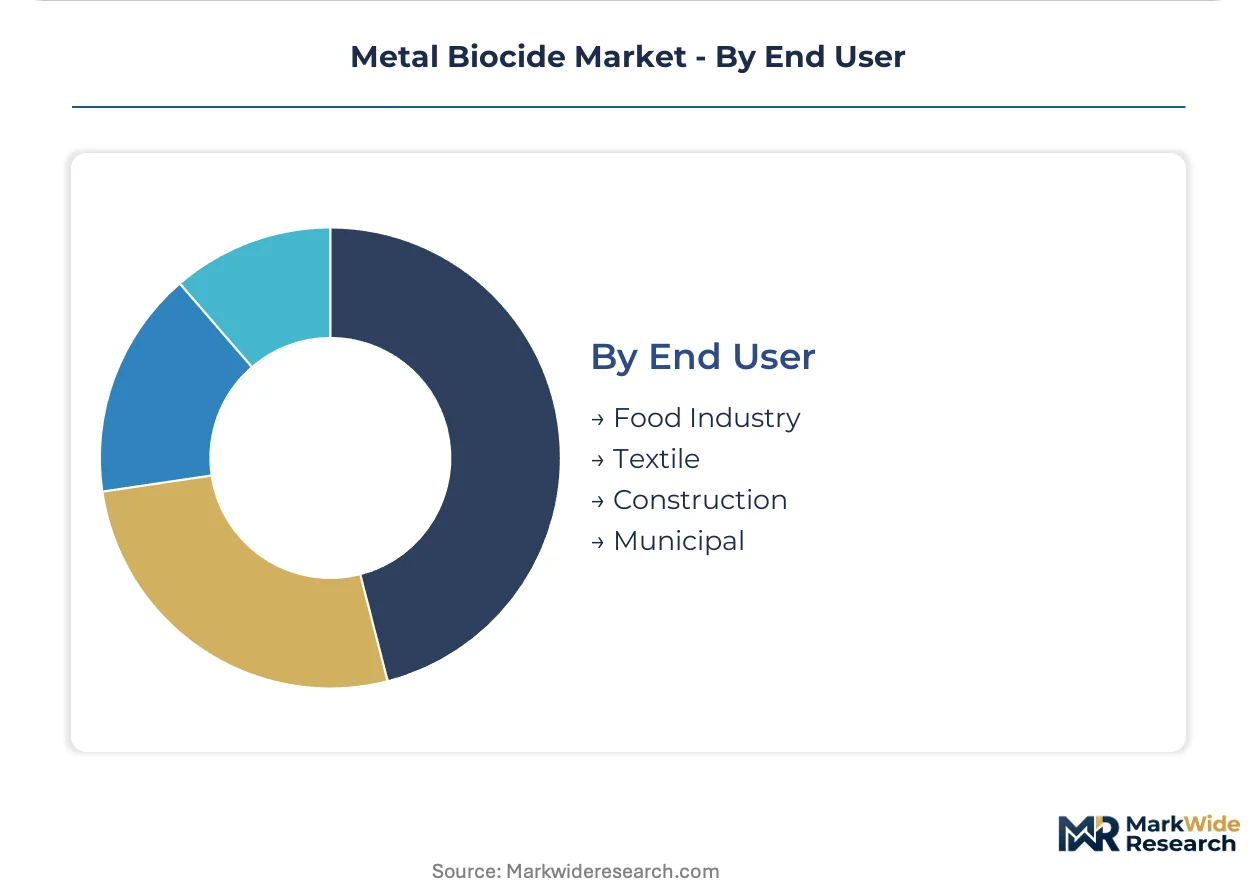
- Food Industry:FDA-regulated processing equipment and packaging specifications demand silver-based antimicrobial additives with validated migration limits. Dairy and beverage manufacturers in Wisconsin and California specify these systems for extended shelf-life protection.
- Textile:China's MIIT GB/T 20944 standards mandate silver-ion complexes in medical apparel and consumer antimicrobial fabrics. Domestic mills redirect formulation demand toward controlled-release delivery systems to satisfy discharge limits under MEE enforcement.
- Construction:Antimicrobial drywall, sealants, and HVAC components incorporate zinc and copper additives where humidity exposure remains moderate. Cost-sensitive builders in Florida and Arizona accept efficacy trade-offs for commodity-grade supply.
- Municipal:Drinking water and wastewater treatment utilities procure copper-based biocides under FIFRA-registered labels with multi-year efficacy validation. Consolidated procurement in Texas and Louisiana favors suppliers with integrated technical service capabilities.
Contract value concentrates in municipal water treatment agreements; textile applications are expanding most quickly as Chinese regulatory standards redirect domestic manufacturing specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast petrochemical corridor spanning Texas and Louisiana concentrates industrial cooling tower demand, where copper-based biocide procurement cycles compress under intensifying EPA discharge monitoring.
United States
Water treatment utilities across Texas and Louisiana execute multi-year technical service agreements bundling copper biocide supply with automated monitoring equipment. EPA FIFRA registration requirements filter formulation entrants through multi-year efficacy validation protocols. Gulf Coast petrochemical operators favor regional blending capacity to compress lead times against import-dependent sourcing.
Germany
Medical device manufacturers in Baden-Württemberg and Bavaria specify silver-ion coatings for implantable devices requiring MDR biocompatibility compliance. ECHA's Biocidal Products Regulation mandates dual active substance approval and product authorization dossiers. Stuttgart and Munich anchor pharmaceutical-grade silver salt demand for chronic wound dressing applications.
China
Domestic textile mills under MIIT GB/T 20944 standards redirect formulation demand toward silver-ion complexes for medical apparel and consumer antimicrobial fabrics. MEE discharge limits on metal-containing effluents push manufacturers toward controlled-release delivery systems. Yangtze River Delta finishing operations concentrate domestic antimicrobial textile production.
France
Vineyard and orchard operators in Provence-Alpes-Côte d'Azur and Nouvelle-Aquitaine accelerate copper hydroxide fungicide programs as REACH authorization uncertainty affects legacy actives. EU Green Deal chemical sustainability benchmarks requalify supply chains toward established regulatory dossiers. Bordeaux and Marseille anchor agricultural copper blend procurement.
Switzerland
Medical technology clusters around Basel and Zurich adopt encapsulated silver nanoparticles with pH-responsive release kinetics for implantable device coatings. Swissmedic and MDR dual requirements favor suppliers with validated ion-release profiles and dedicated regulatory affairs capacity. Basel's pharmaceutical corridor concentrates wound care and device coating innovation.
Metal Biocide Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory validation depth and ion-stabilization chemistry sophistication. The vendor base concentrates among legacy registrants with captive regulatory affairs capacity and parallel dossier preparation across EPA, ECHA, and NMPA jurisdictions. Three archetypes dominate: integrated chemical conglomerates with silver salt production networks, specialty biocide formulators with regional blending assets, and pharmaceutical-grade specialists serving medical device coatings. Competitive moves center on multi-year municipal water contract consolidation and controlled-release encapsulation technology licensing.
Within the integrated chemical tier, BASF SE and Dow exemplify archetypes spanning commodity-scale supply through pharmaceutical-grade positioning. Lonza occupies a specialist position anchored through captive supply chain structures. These three represent the defensive moat construction around incumbent suppliers with parallel regulatory dossier capacity across US, European, and Chinese jurisdictions.
| Leading Market Players |
|---|
| BASF SE |
| Clariant |
| Dow |
| Lonza |
| Milliken Chemical Company |
| Troy Corporation |
| SANITIZED AG |
| Lanxess |
| Noble Biomaterials |
| Others |
Supply & Pricing Matrix
Silver salt feedstock costs cascade through three distinct pricing tiers, with pharmaceutical-grade ion-complex formulations commanding multiples over commodity copper sulfate blends sold to Gulf Coast cooling tower operators. EPA FIFRA registration investments and ECHA dual-compliance dossiers embed regulatory capital into premium tier pricing, while zinc variants compete on input cost in humidity-tolerant construction segments.
Pricing Analysis
Value-based pricing anchors on antimicrobial efficacy duration and regulatory validation depth, with medical device coatings tied to patient-contact safety outcomes rather than unit volume. Pricing stratifies across pharmaceutical-grade, industrial-certified, and commodity-grade tiers, with certification level and ion-release kinetics as primary differentiation drivers. Cost compression in copper formulations is intensifying because mining supply disruptions create input instability. Municipal water utilities exhibit lowest price sensitivity due to bundled technical service agreements, while construction contractors remain most responsive to unit cost.
Supply Chain Analysis
Regional distribution centers in Texas, Louisiana, and the Yangtze River Delta maintain hub-and-spoke patterns to compress lead times for liquid biocide formulations. Manufacturing concentrates in China, Germany, and the United States, with silver salt production anchored in German pharmaceutical corridors and copper blending capacity clustered along the US Gulf Coast. Raw material dependencies span Chilean copper cathode, Mexican silver concentrates, and Chinese zinc oxide. Single-source vulnerability in silver salt purification creates supply chain risk. Distribution runs through captive regional blending facilities rather than third-party chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Parallel regulatory dossier capacity acts as the binding supply constraint, with ECHA active substance approval timelines and EPA FIFRA validation protocols limiting formulation entrant expansion and sustaining incumbent pricing power.
For Market Incumbents: Deepen captive silver salt production networks to defend margin pools against commodity-grade zinc substitution in construction segments. Expand regional blending capacity in Texas and Louisiana to capture municipal water contract consolidation. Prioritize controlled-release encapsulation R&D to satisfy China's MEE discharge limits. For New Entrants and Emerging Players: Regional chemical distributors offer the most accessible channel partnership route for penetrating cost-sensitive construction segments underserved by integrated service models. Target antimicrobial drywall and sealant applications in Florida and Arizona where efficacy trade-offs are acceptable. Pursue private-label formulation supply to bypass direct registration burdens. For Investors and Strategic Acquirers: REACH authorization sunset dates for legacy organic actives is the leading indicator that copper complex formulation demand will accelerate in European agricultural segments. Frame long-term viability around regulatory validation depth rather than commodity scale. Acquire specialist encapsulation technology providers with validated ion-release profiles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Salt Production | Captive supply secures margin pools in pharmaceutical-grade applications against commodity competitors. |
| Controlled-Release Encapsulation Licensing | Technology transfer addresses China's MEE discharge limits while extending protection intervals. |
| Regional Blending Capacity Expansion | Gulf Coast facilities compress lead times for municipal water contracts in Texas and Louisiana. |
| Parallel Regulatory Dossier Preparation | Simultaneous EPA, ECHA, and NMPA filings accelerate market access across jurisdictions. |
| Multi-Year Technical Service Agreements | Bundled chemical supply with monitoring equipment locks in municipal procurement consolidation. |
Research Methodology
Independent corroboration across cooling tower operators, agricultural fungicide blenders, and medical device coating specialists underwrites the qualitative findings. Primary interviews engaged formulation chemists, regulatory affairs directors at biocide registrants, municipal procurement officers in Texas and Louisiana, and textile finishing plant managers in the Yangtze River Delta. Secondary validation drew from EPA FIFRA registration databases, ECHA Biocidal Products Regulation dossiers, Chinese MIIT GB/T 20944 standards, customs trade data, and SEC filings of integrated chemical conglomerates. Bottom-up volume estimates triangulated against top-down market sizing across silver, copper, and zinc product categories.
Historical reference periods anchored the forecast window to observed procurement cycle compression in industrial water treatment and regulatory-driven specification shifts in Chinese textiles. The analytical framework modeled segmentation across metal type, application, form, and end user throughout the forecast period. CAGRs were derived from volume trajectory analysis incorporating EPA discharge rule implementation timelines, REACH authorization sunset schedules, and MIIT standard adoption curves. Industry-specific inputs included copper price volatility assumptions and pharmaceutical-grade silver salt capacity expansion plans.
Caveats apply where copper mining supply disruptions, ECHA active substance approval delays, or Chinese MEE enforcement intensity could materially shift the outlook. Forecasts reflect documented assumptions around regulatory timeline adherence and ion-release technology adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
Taurine Market
Specialty Chemicals
Global Tattoo Inks Market
Specialty Chemicals
Organo-Modified Siloxanes Market
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Global Flash Chromatography Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Fluorotelomers Market
Specialty Chemicals
Global 28-Homobrassinolide Market
Specialty Chemicals
Ferrous Gluconate Market
Specialty Chemicals
Eco-Friendly Plasticizers Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Isoeicosane Market
Specialty Chemicals
Dimethyl Succinyl Succinate Market
Specialty Chemicals
Global Vinyl Sulfone Market