
 Beer Dispenser Market | 2026-2036
Beer Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Dispenser Market Analytics
China's manufacturing base is fragmenting as domestic producers expand stainless steel fabrication capacity for draft systems. Micro Matic A/S anchors European dispensing technology through its tower and tap portfolio. Perlick Corporation differentiates via premium underbar equipment and custom installations for hospitality venues. True Manufacturing Co., Inc. sustains North American production of commercial refrigeration-backed dispensers.
A beer dispenser is a pressurized dispensing appliance that regulates carbon dioxide or nitrogen flow to maintain optimal serving temperature and carbonation levels, typically constructed with stainless steel contact surfaces and insulated cooling chambers for commercial or residential use. Kegerator units lead residential adoption due to their self-contained refrigeration and multi-keg storage capacity, while countertop systems dominate commercial bars where space constraints favor compact footprint designs. Electric and hybrid technology segments are gaining traction as venues replace manual pumps with precision flow control systems that reduce waste and standardize pour volumes.
The EPA Energy Star program and EU Ecodesign Directive regulate commercial refrigeration efficiency, compelling manufacturers to redesign cooling compressors and insulation systems in dispenser units. NSF International sanitation standards govern materials and cleanability for foodservice equipment, directly affecting product development cycles and market access timelines. Stakeholders must monitor evolving efficiency benchmarks and certification requirements that will determine competitive viability in regulated procurement channels.
Market Dynamics
Draft beer quality standardization is forcing venue operators to replace manual pouring with precision flow control systems, compressing equipment replacement cycles and elevating technical specifications in procurement tenders.
Growth Catalysts
- EPA Energy Star efficiency mandates:US commercial refrigeration standards are accelerating equipment refresh cycles as bars and restaurants seek certified dispensers to qualify for utility rebates and avoid regulatory penalties.
- On-premise consumption recovery:Germany's beer hall and gastropub culture sustains concentrated demand for tower and tap installations that prioritize pour consistency and reduced waste.
- Stainless steel fabrication advances:Domestic Chinese producers are expanding precision machining capacity for draft system components, shortening lead times and lowering landed costs for regional distributors.
Market Restraints
- Compressor input cost volatility:Copper and refrigerant price swings squeeze margin structures for manufacturers of electrically cooled kegerator units, forcing inventory hedging or pass-through pricing.
- European supply concentration:Tower and tap assembly remains concentrated among specialized Danish and German fabricators, creating vulnerability to regional logistics disruptions or energy cost spikes.
- NSF sanitation certification timelines:Extended approval cycles for food-contact surface materials delay product launches and tie up working capital in pre-certified inventory.
Strategic Opportunities
- India premium hospitality expansion:Five-star hotel chains and microbrewery startups in Mumbai and Bangalore represent underpenetrated demand for imported dispensing technology and training services.
- Hybrid nitrogen-CO2 systems:Convergence of gas blending technology with IoT flow monitoring enables stout and nitro-coffee service from shared infrastructure, opening adjacent beverage categories.
- EU Ecodesign Directive retrofit incentives:Member state subsidy programs for energy-efficient commercial equipment create pull-through demand for replacement of aging draft systems in legacy pubs.
Industry Challenges
- Refrigeration technician scarcity:Specialized service networks for pressurized cooling systems remain thin outside major metropolitan clusters, constraining aftermarket revenue capture and customer retention.
- Legacy POS integration friction:Smart dispenser connectivity protocols often conflict with established restaurant management software stacks, requiring costly middleware development or manual reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Dispenser Market |
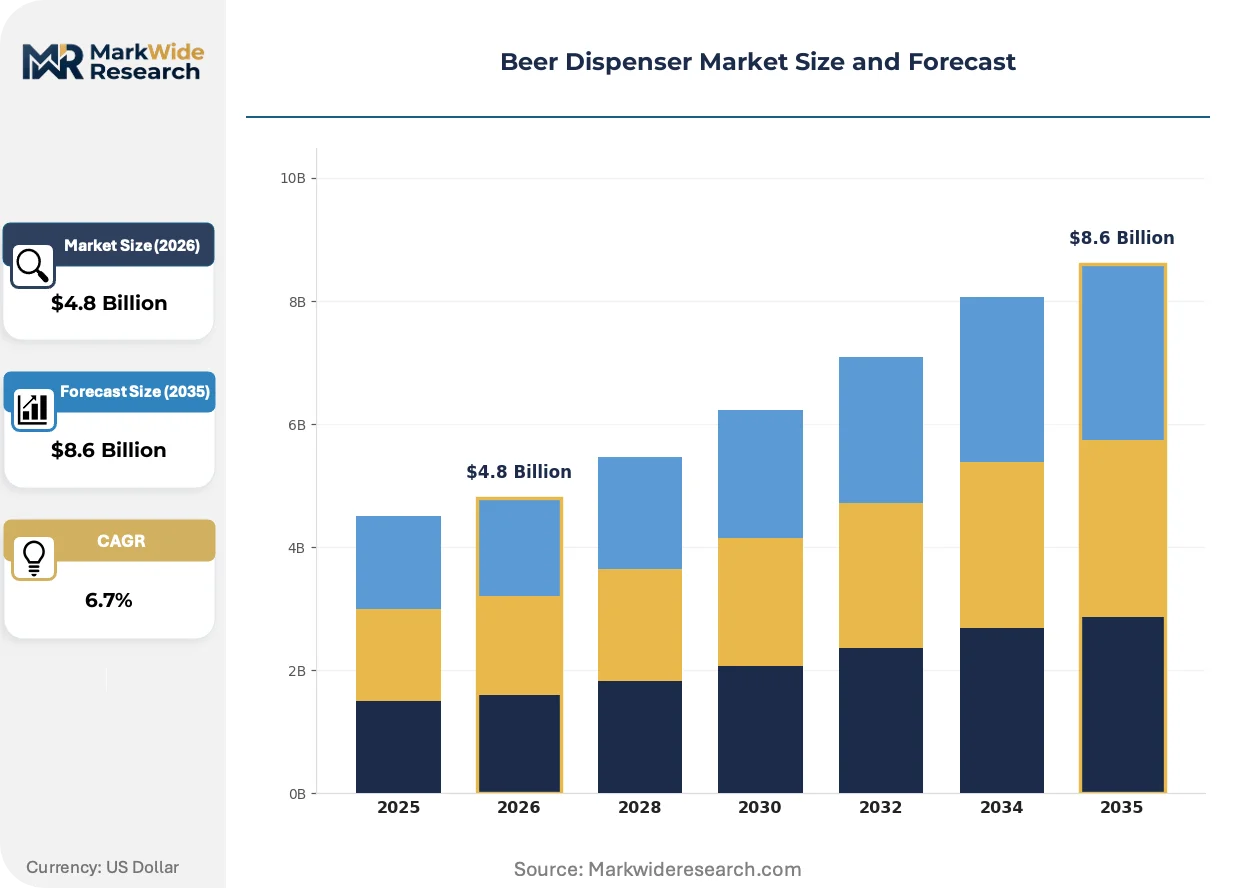
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Wall-Mounted, Kegerator, Portable End User: Bars, Restaurants, Homes, Events Technology: CO2 Pressure, Manual, Electric, Hybrid Capacity: Single Tap, Dual Tap, Multi-Tap, Mini |
| Companies Covered | Beverage-Air Corporation, True Manufacturing Co., Inc., Micro Matic A/S, Beerjet GmbH, Celli Spa, Turbo Air Inc., Perlick Corporation, Kegco, Philips Domestic Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Dispenser Market Evolving Landscape
Connected dispensing infrastructure is rewriting operational protocols across hospitality venues, embedding sensors and automation into equipment that once operated purely mechanically.
Precision electronic flow meters with integrated temperature compensation are collapsing the variance between manual pour quality and machine consistency. High-volume sports bars and airport concessions are adopting these systems fastest, driven by waste reduction targets and labor cost containment. The technology is collapsing the traditional distinction between draft service skill and equipment capability, enabling operator-agnostic quality.
REACH chemical restrictions and F-Gas refrigerant phase-down rules are compelling redesigns of cooling system architectures. Manufacturers must substitute lower-GWP refrigerants and validate new thermal performance profiles under stricter test protocols. European commercial equipment buyers are prioritizing pre-certified platforms to avoid installation delays from customs holds or retrofit requirements.
Compressed equipment financing cycles are altering ownership economics for independent bars and restaurant groups. Leasing and subscription models with bundled maintenance are displacing outright purchase in North American mid-market accounts. This shift is most visible in Texas and California, where multi-location operators favor operational expenditure treatment and vendor-managed uptime guarantees over capital deployment.
Beer Dispenser Market Segmentation
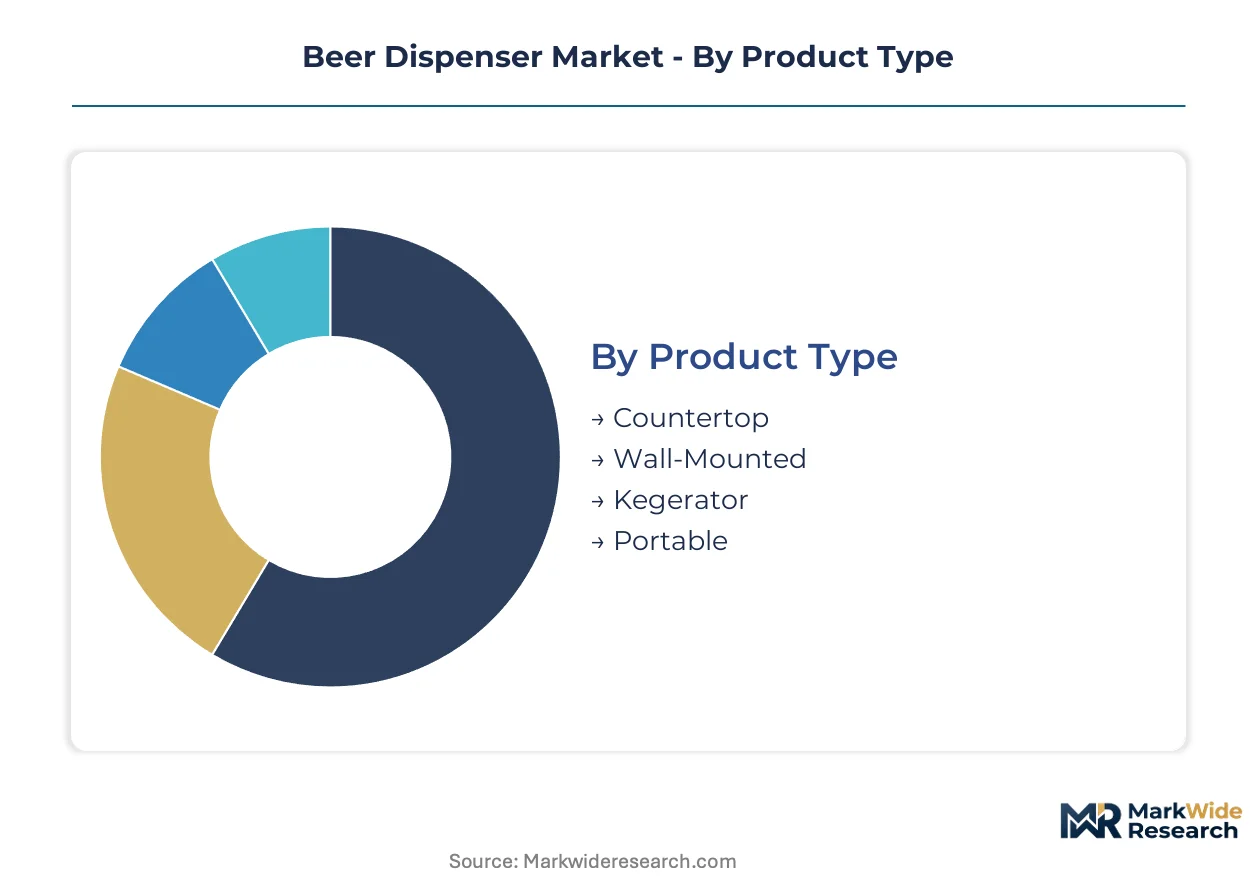
Beer dispenser segmentation reveals how venue constraints, beverage formats, and operational intensity reshape procurement priorities. Equipment specifications diverge sharply between high-volume commercial installations and precision-focused residential systems.
Product Type:
Countertop units serve space-constrained venues requiring rapid throughput without floor footprint allocation.
- Countertop:Compact pressurized systems integrate cooling compressors and CO2 regulation into underbar footprints. Sports bars in Texas and airport concessions deploy these for high-frequency service where floor space commands premium lease rates.
- Wall-Mounted:Tower assemblies anchor permanent installations with direct-draw lines from remote walk-in coolers. German beer halls and Dublin pubs favor this configuration for traditional aesthetic alignment and reduced counter clutter.
- Kegerator:Self-contained refrigeration units with multi-keg storage serve residential basements and corporate hospitality suites.
- Portable:Battery-cooled mobile dispensers support outdoor events and temporary festival installations.
Established volume favors wall-mounted towers in legacy European pubs; emerging adoption favors countertop systems in North American airport concessions.
End User:
Procurement authority concentrates with operators managing pour consistency and waste metrics.
- Bars:High-volume establishments prioritize NSF-certified contact surfaces and Energy Star refrigeration to qualify for utility rebates and avoid EPA penalties.
- Restaurants:Gastropubs and casual dining chains specify hybrid nitrogen-CO2 systems for stout and craft beer diversification. Mumbai and Bangalore five-star properties represent underpenetrated demand for imported dispensing technology.
- Homes:Residential buyers favor kegerator units with single-tap simplicity and minimal installation requirements.
- Events:Rental fleets and festival operators demand portable systems with rapid setup protocols and redundant cooling.
Commercial accounts dominate current procurement volume; residential kegerator sales climb fastest as craft beer culture penetrates suburban markets.
Technology:
Gas delivery mechanisms determine carbonation stability and beverage format flexibility.
- CO2 Pressure:Standard carbon dioxide regulation maintains lager and ale carbonation across temperature fluctuations.
- Manual:Hand-pump systems persist in budget-tier portable applications and emergency backup configurations.
- Electric:Precision flow meters with temperature compensation enable waste reduction targets in high-volume sports bars.
- Hybrid:Converged nitrogen-CO2 blending supports stout service and nitro-coffee expansion from shared infrastructure.
Electric precision systems gain share in new-build venues; hybrid configurations represent the steepest expansion trajectory as beverage menus diversify.
Capacity:
Tap density aligns with throughput requirements and SKU breadth in beverage programs.
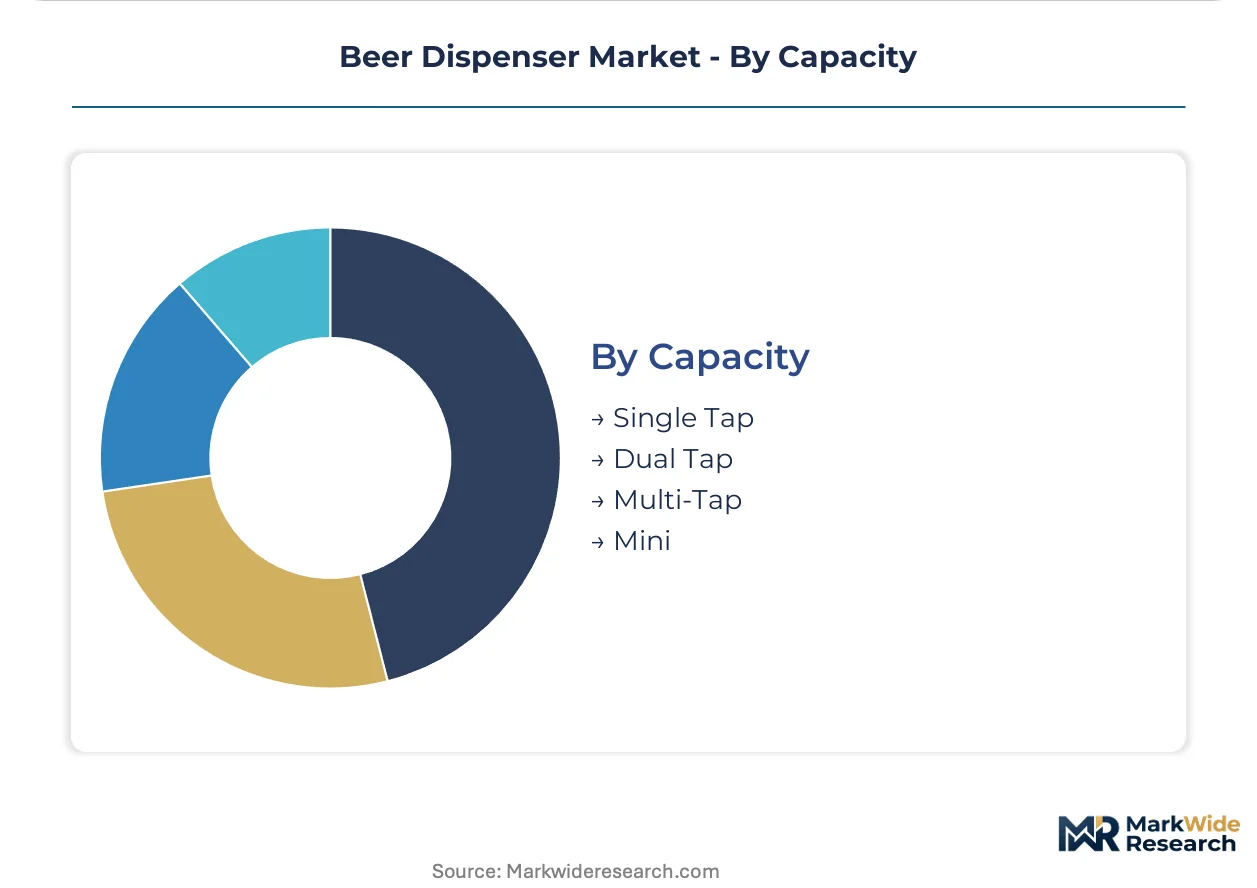
- Single Tap:Simplified configurations serve residential users and specialty single-beer installations.
- Dual Tap:Split-line systems accommodate two standard keg formats in compact footprints.
- Multi-Tap:Tower assemblies with four or more handles support craft beer rotation programs in German gastropubs and California multi-location operators.
- Mini:Reduced-capacity units target countertop residential use and limited-SKU event deployment.
Multi-tap towers anchor revenue in commercial hospitality; mini units expand fastest in apartment-dwelling residential segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys wall-mounted tower systems for beer hall culture, while the United States favors countertop units for space-constrained airport concessions and sports bars. This consumption-mix differential shapes procurement priorities across geographies.
United States
High-volume sports bars and airport concessions drive electric precision flow systems. EPA Energy Star mandates accelerate equipment refresh cycles as operators seek utility rebates. Texas and California multi-location operators favor leasing models with vendor-managed uptime guarantees over capital deployment.
Germany
Beer hall and gastropub culture sustains concentrated demand for tower and tap installations prioritizing pour consistency. EU Ecodesign Directive efficiency standards reshape procurement criteria for commercial refrigeration. Bavaria's brewing heritage clusters fabrication expertise for draft system components.
China
Domestic producers expand stainless steel fabrication capacity for draft systems, shortening lead times for regional distributors. The country's national environmental regulator enforces dual carbon goals that pressure cooling compressor redesigns. Yangtze River Delta manufacturing hubs scale precision machining for kegerator components.
India
Five-star hotel chains and microbrewery startups in Mumbai and Bangalore represent underpenetrated demand for imported dispensing technology. The Bureau of Indian Standards governs commercial equipment certification timelines affecting market access. Maharashtra's hospitality expansion concentrates procurement authority with premium venue operators.
United Kingdom
Dublin-style pubs and London gastropubs favor hybrid nitrogen-CO2 systems for stout and craft diversification. REACH chemical restrictions and F-Gas refrigerant phase-down rules compel cooling system architecture redesigns. Scotland's craft beer movement drives multi-tap tower adoption in Edinburgh and Glasgow venues.
Beer Dispenser Market Competitive Landscape
Capability concentration sits with specialized European fabricators; scale advantage sits with North American refrigeration manufacturers. The market structure tiers around three strategic archetypes: tower and tap specialists, integrated refrigeration-backed dispenser producers, and precision flow control technology developers. Competitive moves center on portfolio diversification into adjacent beverage categories and geographic expansion through distributor network deepening.
Among European dispensing technology specialists, Micro Matic A/S and Beerjet GmbH represent the precision-engineering tier, while Perlick Corporation exemplifies North American premium-tier positioning for hospitality venues. True Manufacturing Co., Inc. anchors the integrated refrigeration-backed segment with domestic production scale.
| Leading Market Players |
|---|
| Beverage-Air Corporation |
| True Manufacturing Co., Inc. |
| Micro Matic A/S |
| Beerjet GmbH |
| Celli Spa |
| Turbo Air Inc. |
| Perlick Corporation |
| Kegco |
| Philips Domestic Appliances |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta manufacturing cluster anchors stainless steel fabrication capacity for draft system components, concentrating upstream supply power among domestic Chinese producers and compressing margin structures for importers competing on landed cost.
Pricing Analysis
Long-term offtake contracts dominate procurement between multi-location operators and integrated refrigeration manufacturers, insulating buyers from copper and refrigerant price volatility while locking in service bundling. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified Energy Star units from basic commercial configurations and residential kegerator imports. Cost compression in economy-tier countertop systems is intensifying because Yangtze River Delta fabricators are expanding precision machining capacity. Independent bars exhibit highest price sensitivity due to compressed financing cycles, while five-star hotel chains in premium hospitality markets prioritize certification tier over unit economics.
Supply Chain Analysis
Stainless steel feedstock draws from Chinese domestic mills, German specialty metal fabricators in Bavaria, and Danish tower assembly specialists in Copenhagen. Copper tubing, refrigeration compressors, and precision gas regulators constitute critical component dependencies. Single-source vulnerability concentrates in European tower and tap assembly, where specialized Danish and German fabricators lack geographic redundancy. Distribution runs through authorized equipment dealers and direct OEM relationships with multi-location hospitality groups, with leasing intermediaries gaining share in North American accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized refrigeration technician networks remain thin outside major metropolitan clusters, creating a persistent asset gap that constrains aftermarket service capture and customer retention across the installed base.
For Market Incumbents: Insulate margin structures by deepening backward integration into compressor assembly and captive stainless steel fabrication capacity in Yangtze River Delta hubs. Certification investment in pre-approved EU Ecodesign Directive platforms prevents customs delays and retrofit penalties that threaten competitive position against domestic Chinese producers with shorter lead times. For New Entrants and Emerging Players: Mid-market commercial bars in India represent the most penetrable entry point, where five-star hotel chains and microbrewery startups in Mumbai and Bangalore currently rely on fragmented import channels with limited training support. Hybrid nitrogen-CO2 system technology offers a differentiated go-to-market angle, enabling stout and nitro-coffee service from shared infrastructure that incumbent pure-play draft specialists have not addressed. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision flow control developers with IoT-enabled waste reduction capabilities over legacy mechanical tap manufacturers. Long-term viability hinges on connectivity protocol standardization that resolves POS integration friction constraining smart dispenser adoption. Acquisition targets should demonstrate installed base density in Texas or California multi-location accounts. Monitor EPA Energy Star efficiency mandate expansion timelines as inflection indicators for equipment refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive production of cooling systems insulates margins from copper price volatility and refrigerant phase-down disruptions. |
| EU Ecodesign Pre-Certification Investment | Pre-approved thermal performance profiles prevent installation delays from customs holds in European member states. |
| Hybrid Gas Blending Technology Launch | Converged nitrogen-CO2 infrastructure opens adjacent nitro-coffee revenue streams in airport concessions and specialty cafes. |
| Leasing Model Expansion with Uptime Guarantees | Operational expenditure treatment attracts Texas and California multi-location operators avoiding capital deployment. |
| Technician Training Network Development | Certified service density outside metropolitan clusters captures aftermarket revenue and improves customer retention. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with bar operations managers, restaurant procurement directors, refrigeration equipment dealers, aftermarket service technicians, and hospitality group facility directors. Secondary validation drew from EPA Energy Star certification databases, EU Ecodesign Directive technical documentation, NSF International sanitation standards filings, and customs trade records for stainless steel fabrication imports. Bottom-up triangulation against installed base estimates and top-down reconciliation with hospitality construction expenditure data anchored volume projections.
Calibration against historical equipment replacement cycles and regulatory mandate implementation timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type configuration, end-user procurement authority, gas delivery technology, and tap density capacity tier. CAGRs were derived from slope analysis of replacement cycle compression and efficiency standard adoption curves. Refrigeration compressor redesign timelines and F-Gas refrigerant phase-down schedules constituted industry-specific forecast inputs.
Practitioners should monitor copper price volatility, REACH chemical restriction expansions, and EPA efficiency benchmark revisions for early signals of margin compression or product architecture disruption. Cross-checking against hospitality construction permit databases and beer volume consumption trends by metropolitan statistical area is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
China Tequila Market
Alcoholic Beverages
Cognac Brandy Market
Alcoholic Beverages
Gluten Free Alcoholic Drinks Market
Alcoholic Beverages
North America Soju Market
Alcoholic Beverages
Roasted Malt Market
Alcoholic Beverages
Wine Chocolate Market
Alcoholic Beverages
Automated Brewing System Market
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
Champagne Market
Alcoholic Beverages
Honey Wine Market
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
High-End Chinese Spirits Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Beer Processing Market
Alcoholic Beverages
Mead Beverage Market