
 Hopped Malt Extract Market | 2026-2036
Hopped Malt Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Hopped Malt Extract Market Outlook
ISO 22000 certification is reorganizing supplier eligibility across the hopped malt extract value chain, forcing smaller maltsters into costly facility upgrades. Muntons plc sustains extensive barley sourcing networks across East Anglia and dominates liquid extract throughput for European craft brewers. Döhler leverages integrated flavor systems and competes on customized bittering profiles for non-alcoholic beverage applications. Associated British Foods plc anchors retail distribution through its grocery and specialty store channels, extending brand recognition into homebrewing segments.
Hopped malt extract comprises concentrated wort infused with hop-derived bittering compounds and aromatic oils, typically standardized to specific alpha-acid units and soluble nitrogen parameters for reproducible brewing outcomes. The ingredient serves commercial brewers seeking batch consistency and food manufacturers requiring controlled bitterness without raw hop handling complexity. Liquid extract leads volume throughput due to its direct pumpability into brewhouse operations, while powder extract commands premium positioning in nutraceutical and dietary supplement formulations where shelf stability and precise dosing matter. Ready-to-use formats are gaining traction among entry-level homebrewers and small-scale food processors lacking extraction equipment.
FDA oversight of GRAS status for hop bittering compounds and EU REACH registration requirements for solvent residues in concentrated extracts are elevating analytical documentation burdens on suppliers. Germany's BfR and the U.S. TTB maintain divergent thresholds for hop oil carryover in malt-derived products, complicating cross-border formulation standardization. Brewers and ingredient buyers must monitor evolving alcohol-alternative labeling rules and carbon-accounting disclosures that will reshape supplier scoring criteria.
Market Dynamics
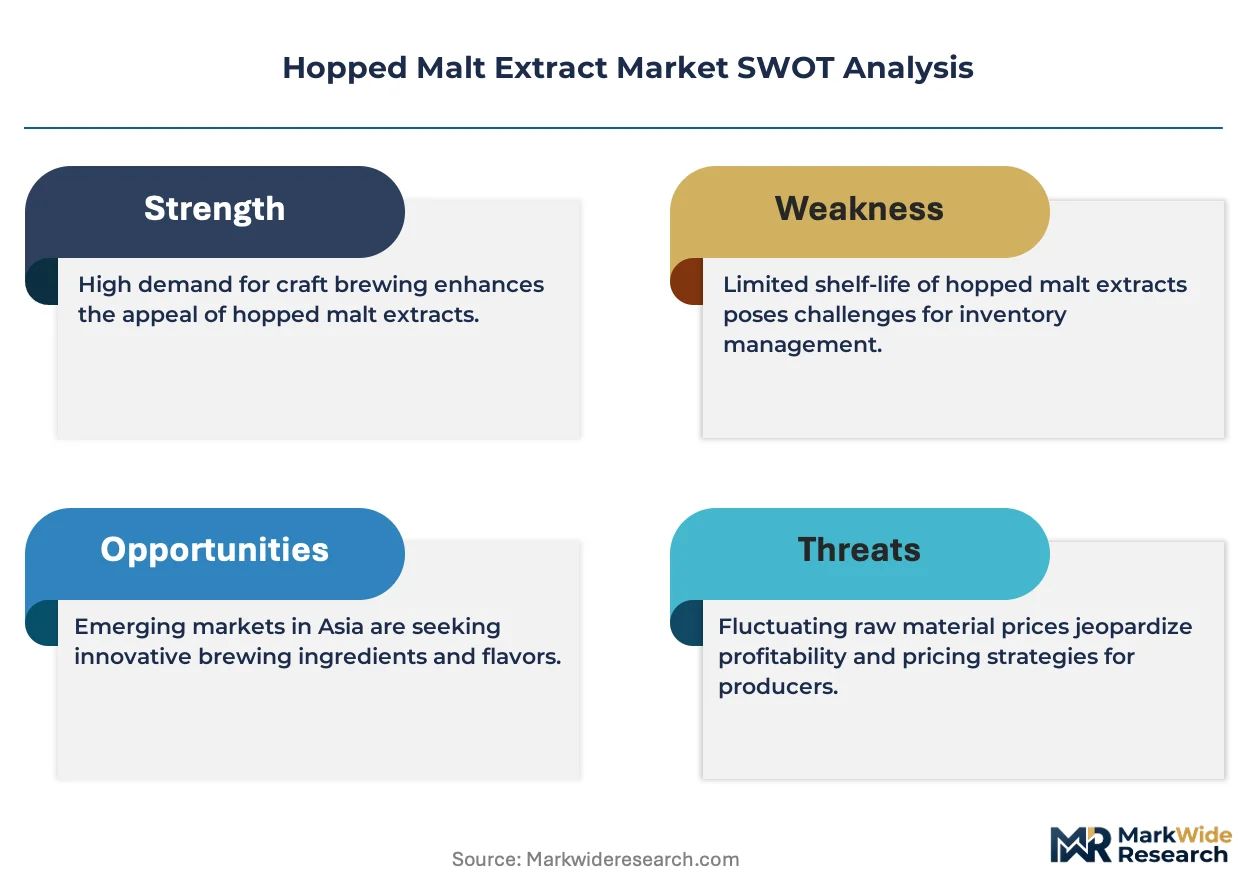
ISO 22000 certification requirements are forcing facility upgrades across the hopped malt extract supply chain, elevating capital barriers for smaller maltsters while consolidating procurement decisions around verified suppliers with integrated quality systems.
Growth Catalysts
- Craft brewery expansion:Breweries across Germany and the United States are adopting liquid hopped extracts to standardize bittering profiles and reduce raw hop handling complexity.
- EU REACH compliance:Registration requirements for food contact substances are filtering supplier pools toward integrated extract producers with analytical documentation capabilities.
- Non-alcoholic beverage innovation:Food manufacturers are incorporating controlled bitterness systems into functional drinks and hop-flavored alternatives.
Market Restraints
- Barley input volatility:Maltsters face margin pressure from weather-driven barley supply fluctuations in East Anglia and North American growing regions.
- Solvent residue thresholds:Divergent BfR and TTB limits on hop oil carryover complicate cross-border formulation standardization for concentrated extracts.
- Raw hop substitution:Advanced cryogenic hop products and CO2 extracts compete for premium bittering applications requiring aromatic precision.
Strategic Opportunities
- Homebrewing channel expansion:Ready-to-use extract formats address entry-level brewers lacking extraction equipment in the Pacific Northwest and Belgium.
- Carbon accounting integration:EU Green Deal disclosure requirements will reshape supplier scoring criteria toward low-carbon malt sourcing.
- Nutraceutical powder positioning:Shelf-stable extract formats serve dietary supplement manufacturers requiring precise alpha-acid dosing.
Industry Challenges
- ISO 22000 implementation timelines:Smaller maltsters struggle with facility certification costs and audit preparation.
- Legacy brewhouse integration:Liquid extract pumpability requirements conflict with traditional lautering equipment configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hopped Malt Extract Market |
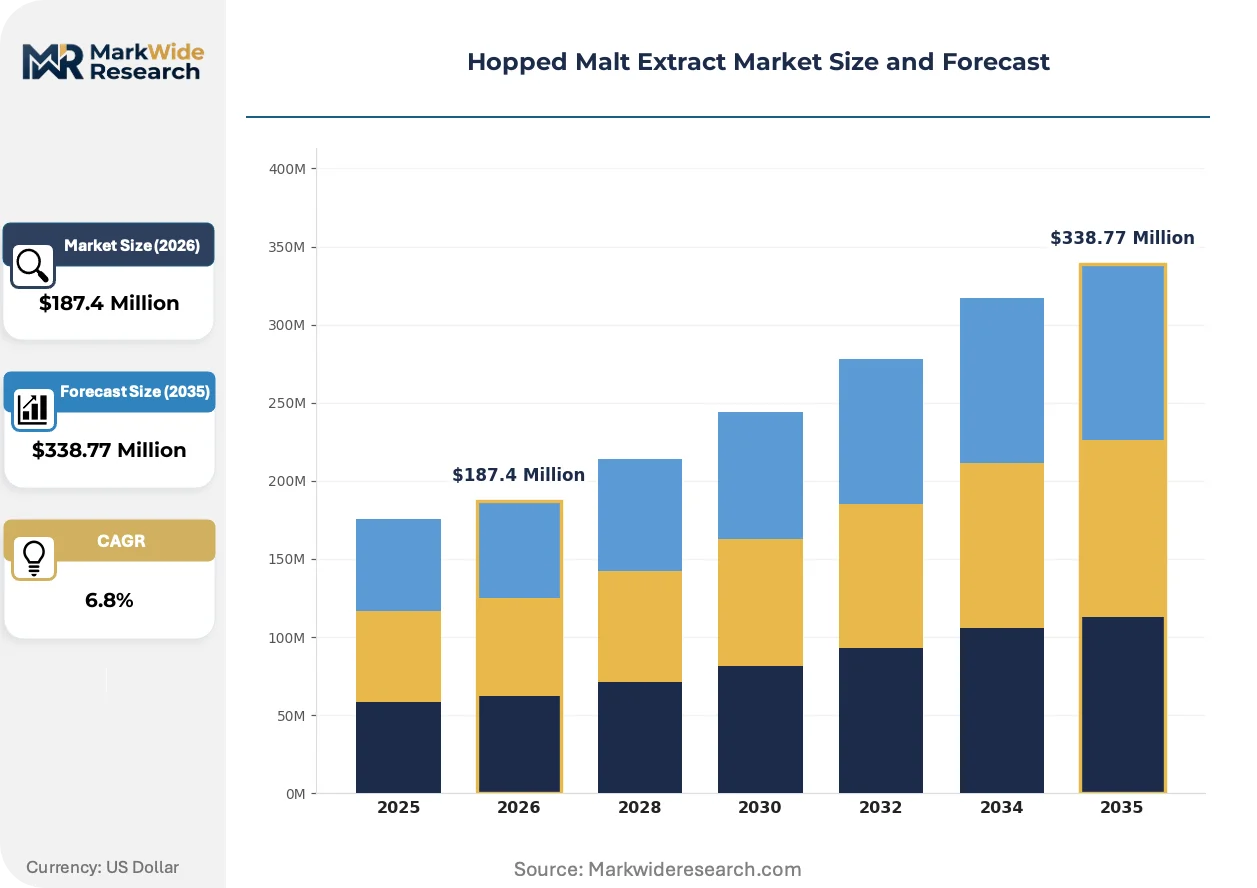
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder Extract, Concentrated Extract, Ready-to-Use Application: Brewing, Food & Beverage, Nutraceuticals, Snacks End Use Industry: Alcoholic Beverages, Non-Alcoholic Beverages, Food Processing, Dietary Supplements Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Koninklijke DSM N.V., Muntons plc, Associated British Foods plc, Döhler, P.A.B. srl - Mr. Malt, CereX B.V., Hambleton Bard Ltd, IREKS GmbH, Coopers International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hopped Malt Extract Market Strategic Shifts
Automation in extract standardization and tightening contaminant thresholds are compressing supplier margins while rewarding integrated producers with captive laboratories and regulatory affairs capabilities.
Continuous flow extraction systems using supercritical CO2 are displacing traditional solvent-based methods in premium extract production. Mid-sized craft breweries in the Czech Republic and Oregon are adopting these inputs for reproducible alpha-acid units. The technology is displacing batch-to-batch variability that previously required brewmaster intervention.
EU REACH registration deadlines for solvent residues in concentrated extracts are elevating analytical documentation burdens on non-integrated suppliers. German BfR maintains stricter hop oil carryover thresholds than U.S. TTB standards, forcing dual-formulation strategies. Liquid extract exporters are responding by segmenting production lines between regulatory jurisdictions.
Direct procurement relationships between craft breweries and certified maltsters are shortening traditional three-tier distribution chains. Specialty brewing hubs in Belgium and the Pacific Northwest now source through verified supplier portals rather than commodity brokers. This pattern concentrates purchasing power among ISO 22000-certified extract producers with transparent batch documentation.
Hopped Malt Extract Market Segmentation
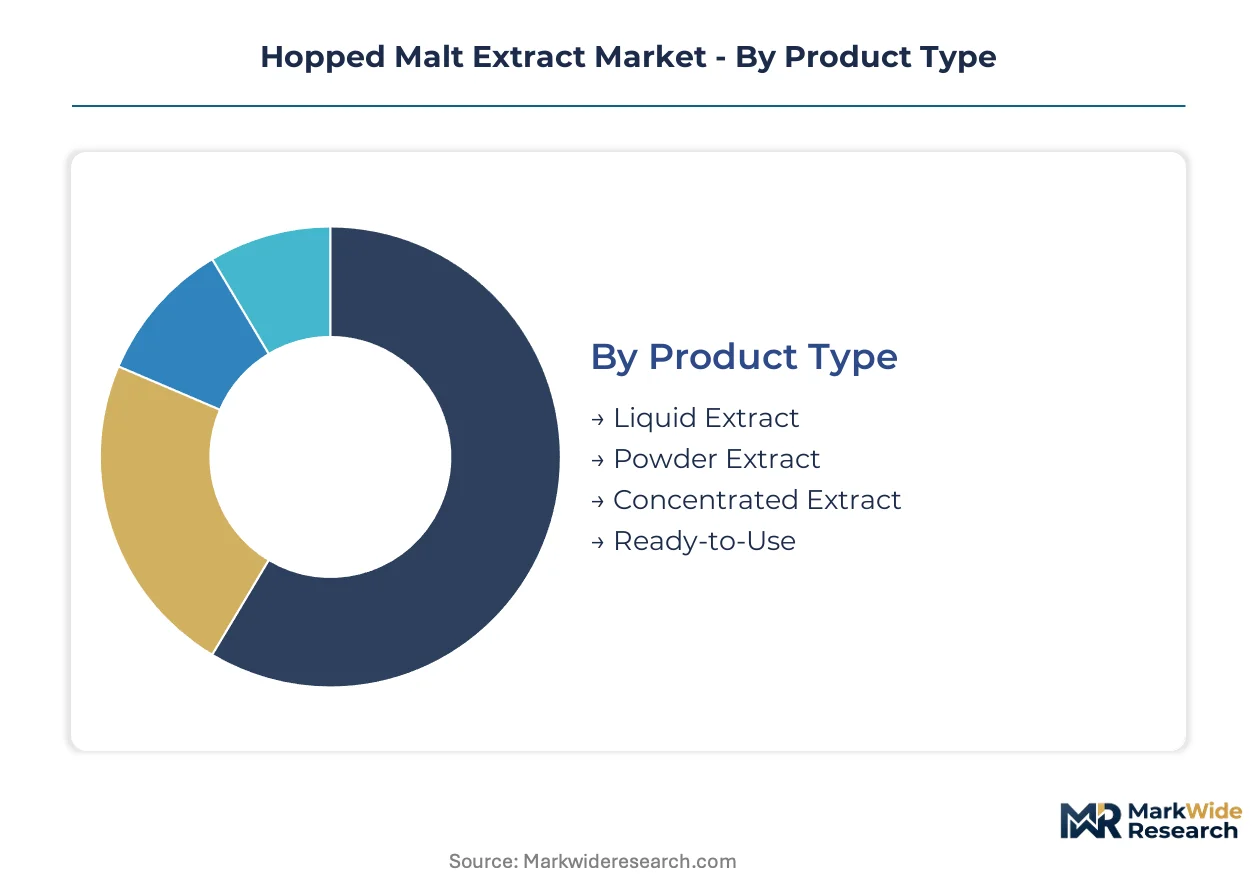
Hopped malt extract serves divergent buyer requirements across brewing, food manufacturing, and nutraceutical formulation. Segment boundaries reflect technical specifications, regulatory exposure, and channel access rather than interchangeable commodity positioning.
Product Type:
Liquid extract dominates domestic procurement in Germany and the United States where craft breweries prioritize pumpable brewhouse integration. Powder extract and concentrated formats travel longer export distances to Asia-Pacific nutraceutical manufacturers.
- Liquid Extract:Pumpable concentrated wort with standardized alpha-acid units and soluble nitrogen parameters. Craft breweries in Oregon and the Czech Republic source this format for direct brewhouse integration without lautering equipment modification. ISO 22000 certification filters supplier eligibility for this segment.
- Powder Extract:Spray-dried or vacuum-dried format with extended shelf stability and precise dosing characteristics. Dietary supplement manufacturers in Switzerland and homebrewing distributors in Belgium concentrate procurement here due to transport economics and storage flexibility.
- Concentrated Extract:High-solids formulation requiring dilution prior to use.
- Ready-to-Use:Pre-diluted format targeting entry-level homebrewers without extraction equipment.
Liquid extract commands the established base. The steepest expansion runs through powder extract.
Application:
Cost tier stratification separates premium brewing applications from commodity food processing. Brewing commands formulation precision and batch documentation. Snack applications absorb lower-specification material at compressed margins.
- Brewing:Commercial and craft beer production requiring reproducible bittering profiles and aromatic consistency. German BfR and U.S. TTB divergent thresholds on hop oil carryover force dual-formulation strategies for cross-border suppliers.
- Food & Beverage:Controlled bitterness systems for functional drinks and hop-flavored alternatives. Non-alcoholic beverage innovators in the Pacific Northwest and Belgium incorporate these inputs for flavor differentiation without ethanol.
- Nutraceuticals:Alpha-acid dosing for dietary supplement formulations.
- Snacks:Flavoring applications with reduced specification requirements.
Brewing absorbs the volume concentration. Food and beverage applications are climbing the fastest.
End Use Industry:
Customer type determines regulatory pathway and documentation burden. Alcoholic beverage producers navigate TTB and BfR jurisdiction-specific requirements. Dietary supplement manufacturers face additional analytical scrutiny for GRAS-equivalent positioning.
- Alcoholic Beverages:Beer production with established three-tier distribution in the United States and direct procurement relationships emerging in Belgium. EU REACH compliance on solvent residues elevates supplier qualification requirements.
- Non-Alcoholic Beverages:Functional drinks and hop-flavored alternatives requiring controlled bitterness without ethanol. This segment expands with EU Green Deal carbon accounting disclosures reshaping supplier scoring.
- Food Processing:General manufacturing applications.
- Dietary Supplements:Precision alpha-acid dosing for health positioning.
Alcoholic beverages retain the revenue foundation. Non-alcoholic beverages show the steepest trajectory.
Distribution Channel:
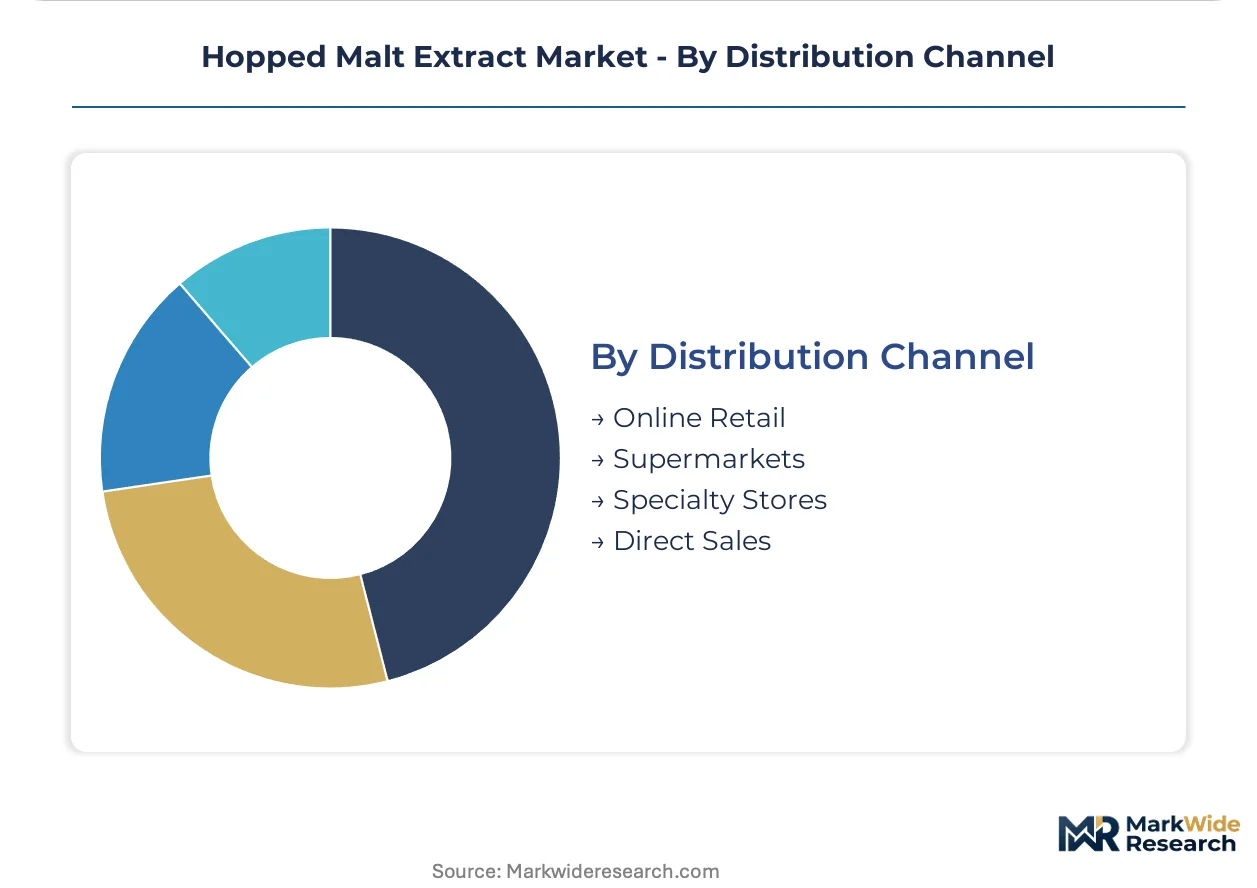
Supply concentration favors direct sales and specialty stores in verified supplier networks. Online retail expands reach to dispersed homebrewing populations lacking geographic proximity to maltster facilities.
- Direct Sales:Verified supplier portals connecting certified maltsters with craft breweries in the Czech Republic and Pacific Northwest. This channel shortens traditional three-tier distribution and concentrates purchasing power among ISO 22000-certified producers.
- Specialty Stores:Homebrewing and professional brewing supply retailers with technical consultation capabilities. Associated British Foods plc anchors this channel through grocery and specialty store networks.
- Online Retail:E-commerce platforms serving dispersed entry-level brewers.
- Supermarkets:Mass retail for ready-to-use consumer formats.
Direct sales command the premium tier. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk terminals anchor European extract distribution, while Union Pacific's refrigerated rail corridors connect Pacific Northwest maltsters to interior brewing clusters across the United States.
United States
Craft breweries in Oregon and Washington source liquid hopped extracts through direct procurement portals, bypassing traditional distribution tiers. The TTB maintains divergent hop oil carryover thresholds from EU standards, forcing formulation segmentation for cross-border suppliers. Seattle and Portland brewing clusters concentrate demand for ISO 22000-certified extracts with transparent batch documentation.
Germany
Barley growing networks across East Anglia supply maltsters serving German craft breweries adopting liquid extract workflows. The BfR enforces stricter solvent residue limits than U.S. counterparts, elevating analytical documentation burdens on concentrated extract imports. Bavarian brewing hubs near Munich and Franconia drive premium procurement of standardized bittering systems.
Belgium
Specialty brewing traditions in Flanders and Wallonia absorb ready-to-use extract formats for entry-level homebrewers lacking extraction equipment. EU REACH registration requirements for food contact substances filter supplier pools toward integrated producers with captive laboratories. Antwerp's specialty store networks anchor retail distribution for consumer-facing malt products.
Czech Republic
Mid-sized craft breweries in Bohemia adopt supercritical CO2 extraction inputs for reproducible alpha-acid units in premium lager production. The country's national food safety authority aligns with EU REACH compliance timelines for solvent residue documentation. Prague and Plzeň brewing clusters concentrate procurement decisions among verified maltster portals.
United Kingdom
Homebrewing distributors across England and Scotland concentrate demand for powder extract formats with extended shelf stability. The Food Standards Agency enforces labeling standards for malt-derived ingredients that tighten supplier qualification requirements. London specialty retailers extend brand recognition into consumer brewing segments through grocery channel integration.
Hopped Malt Extract Market Competitive Environment
Listed leaders compete with private specialists across certification and distribution dimensions, producing a tiered structure where scale advantages concentrate in publicly traded maltsters while agility resides in family-owned extract producers. Three archetypes dominate: integrated barley-to-extract operators with captive sourcing networks, flavor system specialists competing on customized bittering profiles, and retail-anchored conglomerates leveraging grocery distribution for homebrewing penetration. Competitive moves center on ISO 22000 certification investments and direct procurement portal development that shortens traditional three-tier chains.
Within the integrated maltster tier, Muntons plc and Associated British Foods plc exemplify divergent scale strategies, with the former representing supply-side consolidation around East Anglia barley networks and the latter anchoring demand-side reach through grocery and specialty store channels. Döhler occupies a position among flavor system specialists, competing on customized bittering profiles for non-alcoholic beverage applications where controlled hop-derived inputs replace raw handling complexity. IREKS GmbH sits within the mid-tier private specialist category, serving regional brewing clusters with technical consultation capabilities that larger listed competitors struggle to replicate at equivalent service intensity.
| Leading Market Players |
|---|
| Koninklijke DSM N.V. |
| Muntons plc |
| Associated British Foods plc |
| Döhler |
| P.A.B. srl - Mr. Malt |
| CereX B.V. |
| Hambleton Bard Ltd |
| IREKS GmbH |
| Coopers International Ltd. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for liquid hopped extract concentrate procurement power in the hands of ISO 22000-certified maltsters with captive barley sourcing networks across East Anglia and North American growing regions. Buyers lacking direct supplier relationships absorb premium markups from commodity brokers while facing formulation inconsistency risks.
Pricing Analysis
Volume-discount tiering structures separate craft brewery direct procurement from homebrewing retail channels, with premium positioning commanded by powder extract formats serving Swiss nutraceutical manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 22000 certification status, soluble nitrogen parameter precision, and batch documentation transparency. Cost compression in standard-grade liquid extract is intensifying because barley input volatility in East Anglia and North American regions squeezes maltster margins. Homebrewing distributors through specialty stores exhibit highest price sensitivity, while non-alcoholic beverage innovators in Belgium and the Pacific Northwest prioritize bittering profile consistency over unit cost.
Supply Chain Analysis
Germany and the United States anchor liquid hopped extract production for craft brewery workflows, with Belgium and the Czech Republic serving specialty brewing hub distribution. The supply chain draws from barley cultivation networks in East Anglia, hop processing facilities in Bavaria and Oregon, and supercritical CO2 extraction technology providers. Single-source vulnerability concentrates in certified maltster capacity for REACH-compliant concentrated formats. Distribution runs through direct procurement portals shortening traditional three-tier chains, with Union Pacific refrigerated rail corridors and Port of Rotterdam liquid bulk terminals anchoring North American and European logistics respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hopped malt extract demand acceleration reflects supercritical CO2 extraction technology displacement of solvent-based batch variability, compressing supplier margins while rewarding integrated producers with captive laboratories.
For Market Incumbents: Secure ISO 22000 certification investments across all production lines to defend against emerging cryogenic hop product substitutes threatening premium bittering applications. Anchor backward integration into East Anglia barley sourcing networks to buffer margin pressure from weather-driven supply fluctuations. Control direct procurement portal development to lock out commodity brokers from Czech Republic and Pacific Northwest brewing clusters.
For New Entrants and Emerging Players: Technical consultation capabilities for mid-sized craft breweries represent a service-layer gap where incumbents under-serve with equivalent intensity. Target ready-to-use extract formats for entry-level homebrewers in Belgium and the United Kingdom lacking geographic proximity to maltster facilities. Pursue carbon accounting integration partnerships to exploit EU Green Deal disclosure requirements reshaping supplier scoring criteria.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because ISO 22000 certification barriers and REACH analytical documentation burdens filter supplier pools toward integrated extract producers with regulatory affairs capabilities. Acquire family-owned extract producers with regional brewing cluster relationships and technical service intensity that listed competitors struggle to replicate. Monitor divergent BfR and TTB hop oil carryover threshold harmonization efforts as signal for cross-border formulation standardization inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22000 Certification Investment | Filters supplier eligibility for liquid extract procurement by Oregon and Czech Republic craft breweries. |
| Backward Integration into Barley Sourcing | Captures East Anglia growing network control to buffer weather-driven input volatility. |
| Direct Procurement Portal Development | Shortens three-tier distribution chains connecting certified maltsters with verified brewery buyers. |
| Supercritical CO2 Extraction Scale-Up | Displaces solvent-based batch variability for reproducible alpha-acid units in premium lager production. |
| Carbon Accounting Integration | Aligns supplier scoring with EU Green Deal disclosure requirements for low-carbon malt sourcing. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA GRAS determinations, EU REACH registration databases, TTB labeling guidance documents, and malt industry trade association publications. Interviews with craft brewery procurement directors, maltster plant managers, regulatory affairs specialists at extract producers, and specialty store category buyers informed supply chain and pricing dynamics assessment. Bottom-up volume modeling across product type and application segments triangulates against top-down macroeconomic drivers.
Segmentation dimensions modeled span liquid, powder, concentrated, and ready-to-use product formats; brewing, food and beverage, nutraceutical, and snack applications; alcoholic beverages, non-alcoholic beverages, food processing, and dietary supplement end-use industries; and direct sales, specialty stores, online retail, and supermarket distribution channels. CAGRs derive from regression analysis against barley supply indices, craft brewery formation rates, and regulatory compliance cost trajectories across the projection horizon. Industry-specific inputs include soluble nitrogen parameter standardization trends and hop oil carryover threshold divergence between German BfR and U.S. TTB jurisdictions.
Underlying assumptions cover REACH registration timeline adherence, craft brewery expansion continuity in Germany and the United States, and barley yield stability in East Anglia and North American growing regions, with deviation risk concentrated in regulatory threshold harmonization failures and climate-driven crop volatility. Recalibration cycles align with material shifts in EU Green Deal carbon accounting implementation, supercritical CO2 extraction technology adoption rates, and FDA GRAS status determinations for hop-derived ingredients.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Uganda Spirits Market
Alcoholic Beverages
Middle East and Africa Alcoholic Beverage Market
Alcoholic Beverages
Dark Spirits Market
Alcoholic Beverages
Liquor Flavored Ice Cream Market
Alcoholic Beverages
Balsam Bottle Market
Alcoholic Beverages
Ready to Serve Cocktails Market
Alcoholic Beverages
Germany Alcohol E-Commerce Market
Alcoholic Beverages
Beer Line Cleaning Kit Market
Alcoholic Beverages
Global Distillation System Market
Alcoholic Beverages
Electrolyte Beer Market
Alcoholic Beverages
RTD Canned Cocktail Market
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
Fruit Beer Market
Alcoholic Beverages
Global Food-Grade Alcohol Market