
 Brewing Supplies Market | 2026-2036
Brewing Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Brewing Supplies Market Outlook
Germany is fragmenting as new equipment vendors and specialty malt houses enter alongside established brewing technology centers. Alfa Laval leverages its heat-transfer systems to dominate brewhouse efficiency upgrades across Central Europe. GEA Group competes through integrated process lines that span milling to packaging. Ss Brewtech specializes in compact stainless fermenters that anchor the mid-scale craft segment in North America and Australia.
Brewing supplies encompass raw inputs, processing equipment, and auxiliary systems used to convert malted grains, hops, yeast, and water into beer through mashing, lautering, boiling, fermentation, conditioning, and packaging stages. Stainless steel construction with 304 or 316 grade certification defines equipment durability standards, while temperature control within 0.5°C precision governs fermentation consistency for commercial output. Malt and hops remain the largest product type categories by volume, though additives including enzymes and flavor stabilizers command higher margin pools as brewers pursue product differentiation. Fermenters and cooling units represent the fastest-growing equipment segment as microbreweries and brewpubs expand capacity without full greenfield builds.
EPA effluent guidelines in the United States enforce wastewater treatment standards that shape brewery equipment specifications, while EU REACH and F-Gas Regulation constrain refrigerant choices in cooling systems across European installations. FDA oversight of food-contact surfaces and FSMA preventive controls further condition material selection and cleaning protocol design for brewing supplies sold into American facilities. Stakeholders must monitor evolving energy efficiency mandates and carbon accounting rules that will increasingly determine equipment procurement criteria and supplier qualification thresholds.
Market Dynamics
Automated brewhouse systems are compressing labor requirements while EU Green Deal water mandates force capital-intensive wastewater retrofits across German, Czech, and Belgian production facilities. Equipment procurement now hinges on energy recovery metrics and refrigerant compliance rather than throughput alone.
Growth Catalysts
- EU Green Deal water reuse mandates:Commercial breweries in Germany face binding effluent standards that accelerate filtration and heat-recovery equipment upgrades. Retrofit demand concentrates among mid-scale facilities seeking compliance without greenfield construction.
- Hop acreage expansion:United States Pacific Northwest growers are adding processing capacity for cryogenic hop products. Specialty maltsters in Oregon and Washington are co-locating to secure supply proximity.
- 304/316 stainless certification:FDA food-contact surface rules under FSMA preventive controls are disqualifying lower-grade alloys from American brewery builds. Certification is becoming a non-negotiable procurement filter.
Market Restraints
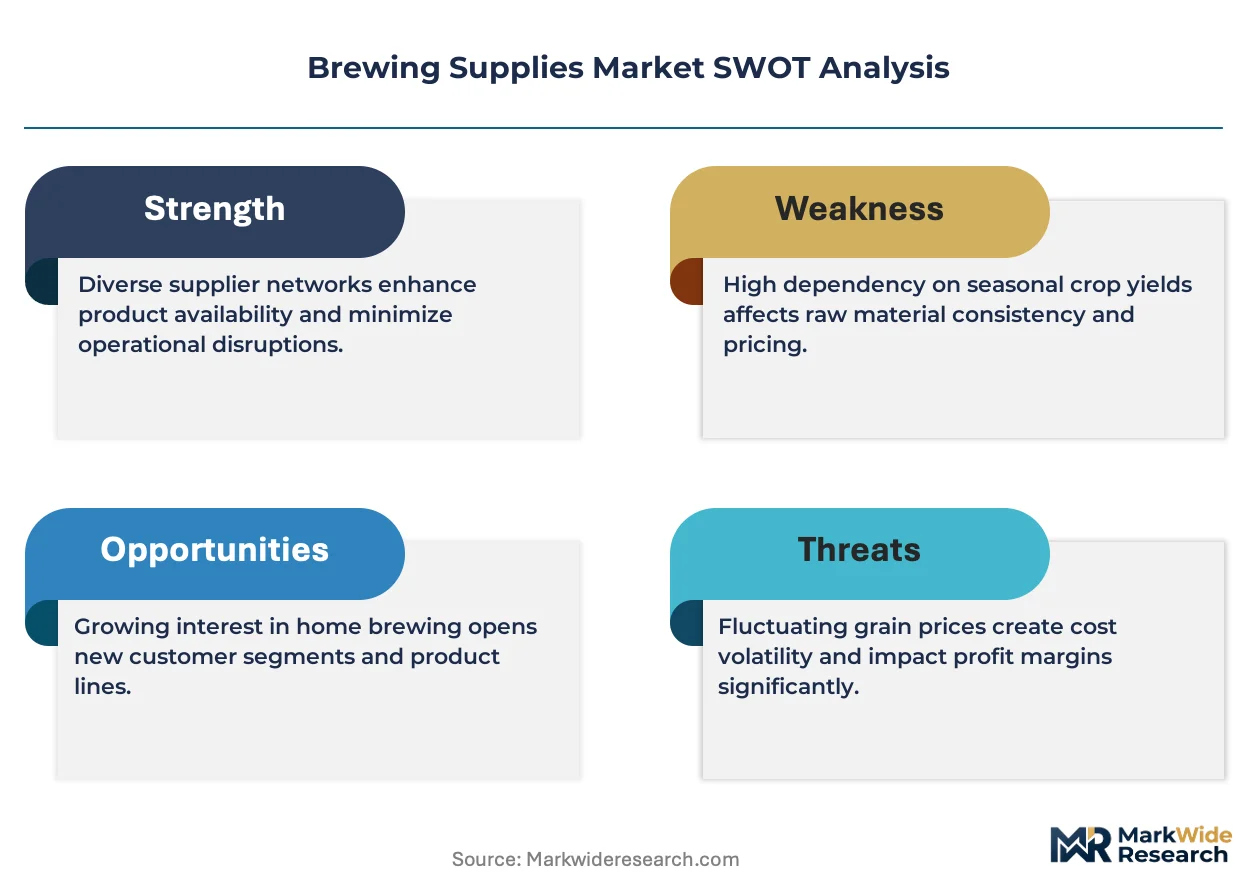
- Copper and nickel price volatility:Heat-exchanger fabrication depends on these inputs, exposing brewhouse equipment margins to London Metal Exchange swings. European vendors absorb most contract risk.
- German equipment vendor concentration:Automated bottling and kegging lines rely on a narrow supplier base around Munich and Nuremberg engineering clusters. Disruption risk elevates lead times for North American buyers.
- F-Gas refrigerant phase-down:EU Regulation 517/2014 constrains cooling system choices, forcing breweries to abandon conventional chillers before alternative technologies achieve cost parity.
Strategic Opportunities
- India craft segment underpenetration:BIS standards alignment for food-grade stainless creates a compliance pathway for equipment exporters. Bangalore and Pune microbrewery licensing is liberalizing.
- Carbon accounting integration:CSRD disclosure requirements in Europe are creating demand for energy-monitoring modules that retrofit onto existing fermentation vessels. Software-hardware bundles command premium positioning.
- Direct-to-brewery malt distribution:Specialty maltsters are bypassing traditional grain merchants to sell roasted and caramel malts through e-commerce portals. Australian and Canadian craft brewers are early adopters.
Industry Challenges
- Automation technician scarcity:PLC programming and pneumatic system maintenance skills are concentrated among aging workforces in Bavaria and Wisconsin. Training pipelines have not expanded to match equipment deployment rates.
- Legacy cooling infrastructure incompatibility:Natural refrigerant retrofits require complete compressor replacement rather than component swaps. Breweries with 15-20 year old glycol systems face full system write-offs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brewing Supplies Market |
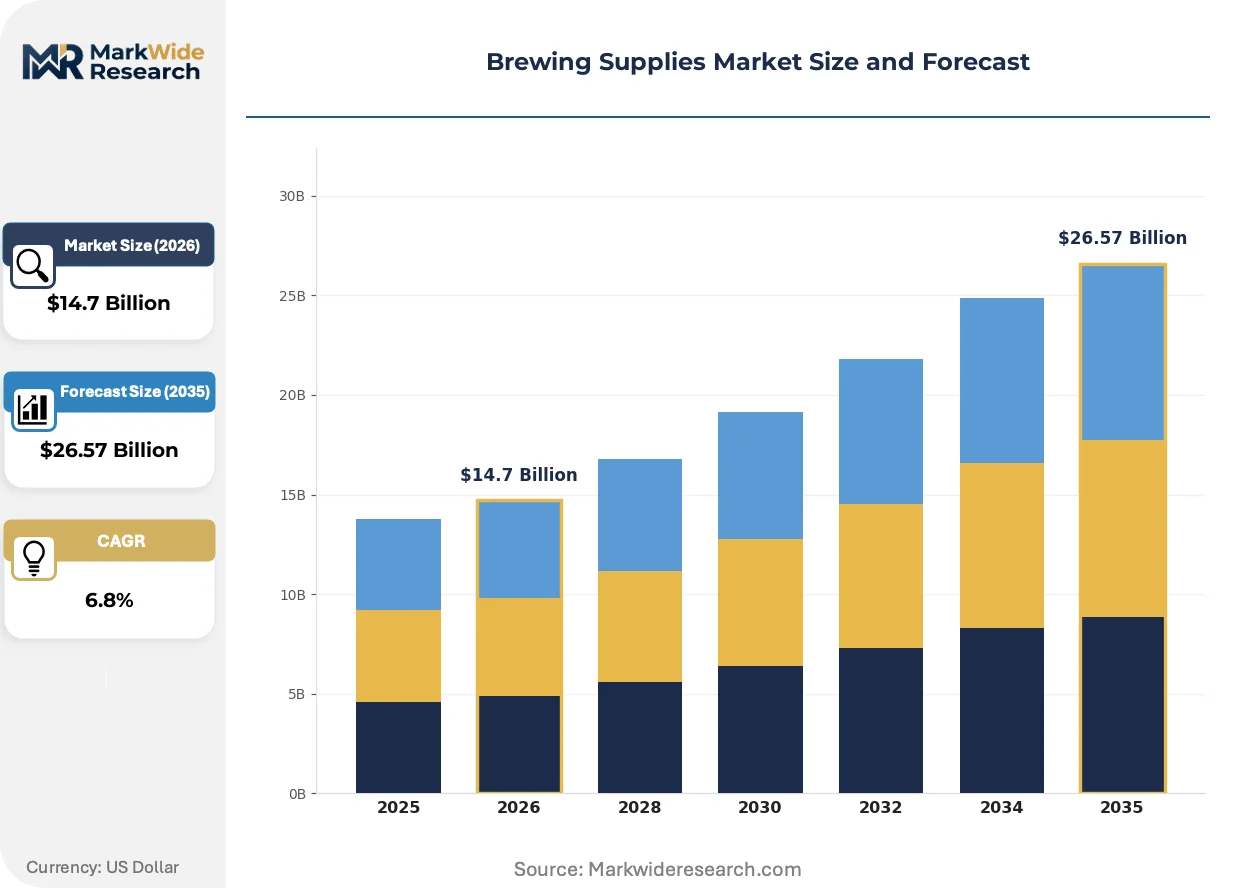
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Malt, Hops, Yeast, Additives Equipment: Brew Kettles, Fermenters, Bottling Systems, Cooling Units End User: Microbreweries, Home Brewers, Commercial Breweries, Brewpubs Distribution Channel: Online Retail, Specialty Stores, Distributor, Wholesale |
| Companies Covered | Alfa Laval, DME Brewing Solutions, HGMC, Paul Mueller Company, Ss Brewtech, GEA Group, JV Northwest, Brauhaus Technik Austria, Krones AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brewing Supplies Market Strategic Shifts
Modular brewhouse architectures are fragmenting equipment procurement patterns, enabling capacity expansion without full production line replacement. Three technology and behavioral shifts are restructuring competitive positioning.
Single-vessel brewhouse systems that combine mashing, lautering, and boiling in one tank are collapsing the floor-space and capital requirements for microbrewery entry. Nano-scale entrants in Australia and New Zealand are adopting these units at triple the rate of traditional three-vessel configurations. Equipment vendors are compressing delivery lead times from sixteen weeks to six for standardized modular skids.
REACH chemical authorization is restricting cleaning compound formulations used in European brewing facilities, forcing reformulation of caustic and acid-based CIP systems. ECHA substance evaluation is extending compliance timelines for novel surfactants. German brewhouse operators are accelerating validation of enzyme-based cleaning alternatives to preempt authorization delays.
Consolidated procurement consortia among American regional craft brewery associations are displacing individual equipment negotiations. Group purchasing organizations in the Mountain West and Southeast are aggregating fermenter and cooling unit orders to extract volume pricing from stainless fabricators. This behavior is most visible among 5,000-15,000 barrel annual production facilities seeking to defend margin against input cost pressure.
Brewing Supplies Market Segmentation
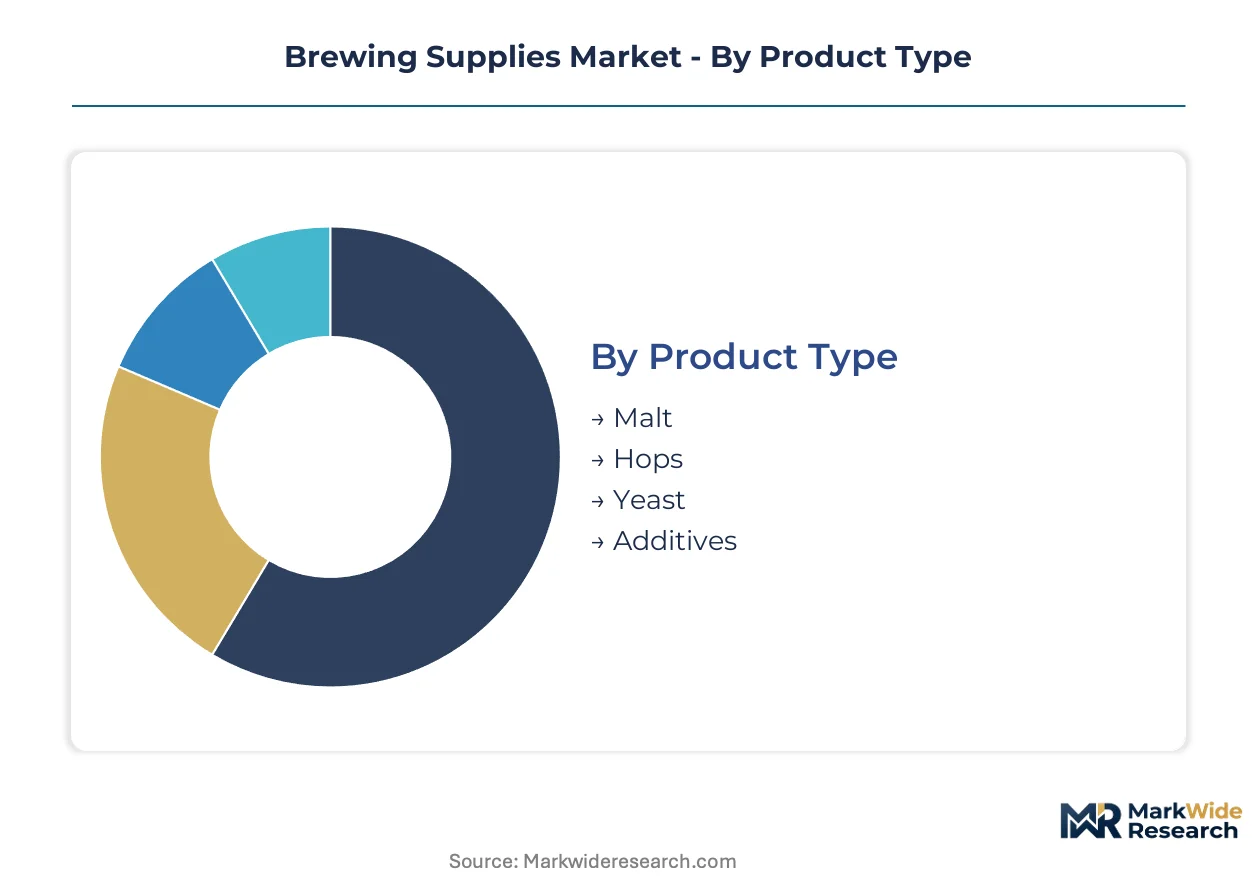
Brewing supplies segmentation reveals divergent service intensity across product categories. Malt and hops demand continuous quality certification support, while equipment segments require installation supervision and calibration maintenance that shapes vendor profitability.
Product Type:
After-sales service intensity varies sharply across raw input categories, with yeast and additives requiring technical advisory support that malt and hops suppliers rarely provide.
- Malt:Base malts from two-row barley constitute the volume foundation, with specialty roasted and caramel variants commanding formulation consulting fees. German Weyermann and Belgian Castle Malting anchor premium positioning through sensory laboratory services. Demand concentrates among Pacific Northwest craft brewers seeking terroir differentiation through local barley programs.
- Hops:Pellet and cryogenic extract formats dominate commercial procurement, with oil content and alpha acid specifications governing bittering calculations. Yakima Valley processors are expanding nitrogen-flushed packaging capacity to preserve aromatic compounds. IPA-focused breweries in Oregon and Washington drive varietal substitution toward Citra and Mosaic.
- Yeast:Liquid culture propagation requires cold-chain logistics that strain distributor capabilities.
- Additives:Enzyme formulations and flavor stabilizers carry regulatory documentation burdens under FDA and EFSA frameworks.
By volume, malt leads. By growth pace, additives are ahead.
Equipment:
Cost tier stratification separates artisanal fabricators from industrial systems houses, with mid-scale craft breweries creating a contested middle ground.
- Brew Kettles:Steam-jacketed vessels with internal calandria dominate brewhouse thermal efficiency. Ss Brewtech and Blichmann Engineering compete through electric and direct-fire configurations that reduce installation complexity. Australian nano-breweries favor compact single-vessel systems that collapse footprint requirements.
- Fermenters:Cylindroconical tanks with glycol dimple jackets enable temperature precision within 0.5°C for consistent fermentation curves. Demand concentrates among Mountain West craft breweries expanding capacity without greenfield construction. CSRD disclosure requirements in Europe are accelerating demand for energy-monitoring retrofits.
- Bottling Systems:Counter-pressure fillers with CO2 pre-purge minimize dissolved oxygen pickup.
- Cooling Units:F-Gas Regulation constraints are forcing compressor technology transitions before cost parity.
By capital deployed, fermenters absorb the largest share. By expansion urgency, cooling units face the steepest replacement cycle.
End User:
Application maturity separates established commercial operations from experimental formats that tolerate higher failure rates.
- Microbreweries:Production facilities below 15,000 barrels annually prioritize equipment modularity over throughput optimization. These operators aggregate purchasing through Mountain West and Southeast consortiums to extract volume pricing. Bangalore and Pune licensing liberalization is opening import pathways for stainless fabricators.
- Commercial Breweries:Automated brewhouse integration with ERP systems governs procurement criteria among German mid-scale facilities facing EU Green Deal water mandates. Alfa Laval and GEA Group dominate retrofit specifications through energy recovery guarantees.
- Home Brewers:All-grain advancement kits with temperature-controlled fermentation chambers anchor the hobbyist segment.
- Brewpubs:Front-of-house visibility requirements favor copper-clad vessels over pure stainless construction.
By absolute spend, commercial breweries dominate. By vendor count, microbreweries fragment supplier relationships most severely.
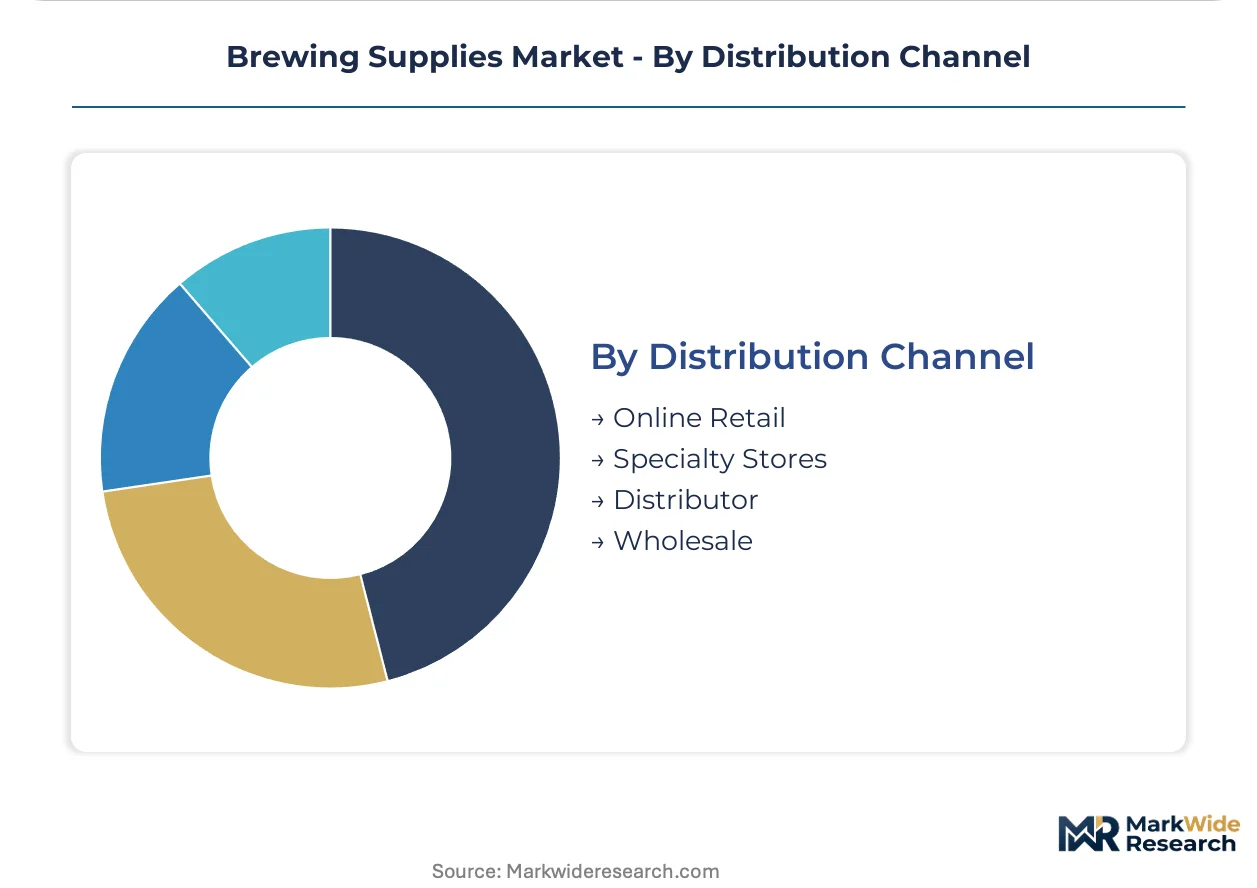
Distribution Channel:
Customer type concentration shapes channel viability, with institutional procurement bypassing retail formats entirely.
- Distributor:Full-line beer supply houses carry malt, hops, and adjunct chemicals alongside equipment financing. These intermediaries concentrate in Wisconsin and Bavaria where brewery density supports route efficiency. Technical field service capabilities differentiate surviving distributors from pure logistics players.
- Wholesale:Grain merchants and hop cooperatives aggregate commodity volumes that individual breweries cannot contract directly. Yakima Valley hop grower cooperatives and Canadian prairie barley pools anchor supply security for risk-averse buyers.
- Online Retail:Direct-to-brewery specialty malt portals are displacing traditional grain merchants in Australia and Canada.
- Specialty Stores:Home brew-focused retailers carry ingredient kits and small-batch equipment.
By transaction volume, wholesale channels move the most tonnage. By margin capture, distributor relationships with embedded service yield superior returns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput anchors Northern European brewing equipment import flows, while the Rhine-Main-Danube canal network distributes malt and hops to Central European processing clusters.
United States
Pacific Northwest hop acreage expansion and craft maltster co-location drive equipment procurement in Oregon and Washington. EPA effluent guidelines under the Clean Water Act shape brewery wastewater system specifications. Yakima Valley processors are expanding nitrogen-flushed packaging capacity for cryogenic hop products.
Germany
Automated bottling investments accelerate among commercial breweries facing binding EU Green Deal water reuse mandates. F-Gas Regulation constraints force cooling system technology transitions before alternative refrigerants achieve cost parity. Munich and Nuremberg engineering clusters concentrate automated kegging line fabrication capacity.
Belgium
Heritage brewing traditions sustain demand for specialty malt formulations and artisanal equipment configurations. EU REACH chemical authorization restricts cleaning compound formulations used in brewhouse CIP systems. Brussels and Leuven anchor R&D partnerships between equipment vendors and traditional lambic producers.
Australia
Nano-brewery entrants adopt single-vessel brewhouse systems at triple the rate of traditional three-vessel configurations. TGA-equivalent state-level food safety standards govern stainless steel certification requirements. Melbourne and Sydney microbreweries aggregate purchasing through distributor consortia to extract volume pricing.
India
Bangalore and Pune microbrewery licensing liberalization opens import pathways for stainless fabricators seeking market entry. BIS standards alignment for food-grade stainless creates compliance pathways for equipment exporters. Maharashtra and Karnataka state regulations are converging toward unified food-contact surface requirements.
Brewing Supplies Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The vendor base separates into consolidated industrial systems houses and fragmented artisanal fabricators. Three strategic archetypes dominate: heat-transfer engineering platforms, stainless fabrication specialists, and integrated process line providers. Competitive moves concentrate on energy recovery technology licensing and geographic expansion through distributor partnerships.
Among Swedish-origin platform integrators, Alfa Laval exemplifies the heat-transfer engineering archetype. German GmbH-structured houses including GEA Group and Krones AG occupy positions within the integrated process line tier. Ss Brewtech represents the compact stainless fabrication specialist archetype serving mid-scale craft segments.
| Leading Market Players |
|---|
| Alfa Laval |
| DME Brewing Solutions |
| HGMC |
| Paul Mueller Company |
| Ss Brewtech |
| GEA Group |
| JV Northwest |
| Brauhaus Technik Austria |
| Krones AG |
| Others |
Value Chain & Pricing Dynamics
The Munich-Nuremberg engineering cluster concentrates automated bottling and kegging line fabrication, granting German vendors substantial pricing leverage over North American buyers facing extended lead times. This geographic concentration of specialized capacity creates asymmetric power dynamics where equipment procurement costs reflect supply scarcity rather than pure manufacturing economics.
Pricing Analysis
Volume-discount tiering structures dominate equipment procurement, with three-tier pricing separating premium-grade 316 stainless systems from standard 304 configurations and economy-grade alternatives. Price differentiation hinges on certification grade under FDA FSMA preventive controls and after-sales service bundling. Cost compression in mid-scale craft segments is intensifying because consolidated procurement consortia are aggregating fermenter orders to extract volume pricing. Home brewers exhibit the highest price sensitivity, while commercial breweries facing EU Green Deal water mandates show relative inelasticity for compliance-critical retrofits.
Supply Chain Analysis
Export-control regimes around heat-exchanger technologies and precision temperature control systems constrain equipment flows to certain jurisdictions. Supply concentrates in Germany, the United States, and Belgium, with raw material dependencies on copper and nickel for thermal systems, stainless steel feedstock from Chinese mills, and specialized hop extracts from Yakima Valley processors. Single-source vulnerability around Munich-Nuremberg automated line fabrication elevates disruption risk. Distribution runs through full-line beer supply houses in Wisconsin and Bavaria that embed technical field service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brewing supplies sit in early-cycle expansion as craft maltster capacity and microbrewery licensing liberalization outpace traditional commercial brewery saturation. Nano-scale entrants and brewpub formats are driving penetration depth in underdeveloped markets.
For Market Incumbents: Pre-empt modular brewhouse fragmentation by acquiring compact stainless fabrication specialists before they scale beyond regional reach. Consolidate distributor relationships in the Mountain West and Southeast where procurement consortia are displacing individual negotiations. Energy recovery technology licensing represents the priority defensive lever against Alfa Laval's heat-transfer dominance.
For New Entrants and Emerging Players: Bangalore and Pune microbrewery licensing liberalization offers the most penetrable white-space entry point for stainless fabricators seeking market establishment. Target cryogenic hop processing equipment gaps in the Pacific Northwest where Yakima Valley capacity expansion strains existing supplier relationships. Direct-to-brewery e-commerce portals for specialty malts provide a proven go-to-market angle already validated in Australia and Canada.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors carbon-accounting-integrated equipment vendors with energy-monitoring retrofit capabilities. Long-term viability over the next decade rests on CSRD disclosure compliance and F-Gas refrigerant transition readiness. Acquisition targets should demonstrate installed base penetration in German mid-scale facilities facing binding water reuse mandates. The signal to watch is automation technician training pipeline expansion rates in Bavaria and Wisconsin relative to equipment deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Malt Production | Castle Malting and Weyermann demonstrate premium positioning through sensory laboratory services that command formulation consulting fees. |
| Energy-Monitoring Retrofit Bundles | CSRD disclosure requirements in Europe are creating demand for software-hardware modules that retrofit onto existing fermentation vessels. |
| Single-Vessel Brewhouse System Launch | Australian nano-breweries adopt compact configurations at triple the rate of traditional three-vessel setups, collapsing floor-space requirements. |
| Geographic Expansion via Distributor Partnerships | Melbourne and Sydney microbreweries aggregate purchasing through consortia to extract volume pricing from stainless fabricators. |
| Enzyme-Based Cleaning Alternative Validation | ECHA substance evaluation timelines are forcing German brewhouse operators to accelerate novel surfactant reformulation ahead of REACH authorization delays. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with brewery operations directors, equipment procurement managers, specialty maltster technical leads, and cooling system maintenance technicians; alongside secondary validation through SEC 10-K filings of listed brewing technology vendors, EU ECHA substance authorization databases, FDA FSMA guidance documents, and customs trade data on stainless steel equipment imports. Bottom-up facility-level capacity assessments and top-down market sizing triangulated volume estimates.
Forecast inputs considered malt and hop demand trajectories, equipment replacement cycles driven by F-Gas Regulation phase-downs, and microbrewery licensing velocity across state-level jurisdictions. Segmentation dimensions modeled include product type hierarchy, equipment cost tier stratification, end-user production scale brackets, and distribution channel concentration patterns. CAGRs were derived from weighted capacity expansion schedules and regulatory compliance-driven retrofit timelines. Industry-specific inputs encompassed hop acreage expansion rates in the Pacific Northwest and EU Green Deal water mandate implementation schedules.
Practitioners should monitor copper and nickel price volatility on the London Metal Exchange and automation technician training pipeline expansion for early signals of margin pressure and service capacity constraints. Forecasts reflect assumptions around regulatory compliance timelines and craft segment licensing liberalization velocity. Material shifts in EU REACH chemical authorization schedules or F-Gas refrigerant cost parity achievement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
North America Beer Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
Fermented Beverages Market
Alcoholic Beverages
Single Serve Wine Market
Alcoholic Beverages
Brandy Flavor Market
Alcoholic Beverages
Russia Tequila Market
Alcoholic Beverages
Rose Wine Market
Alcoholic Beverages
Hard Kombucha Market
Alcoholic Beverages
Spirits Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Beer Stabilizers Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Hookah Charcoal Market
Alcoholic Beverages
Alcoholic Drinks Market
Alcoholic Beverages
Premium Wine Cooler Market