
 Cabernet Sauvignon Market | 2026-2036
Cabernet Sauvignon Market Size, Share, and Industry Trends Forecast 2026-2036
Cabernet Sauvignon Market Analysis
The widening gap between ultra-premium single-vineyard bottlings and mass-market commodity Cabernet is realigning procurement patterns across the wine trade. Harlan Estate leverages its Oakville terroir exclusivity to command allocation-based distribution. Beringer Vineyards sustains volume scale across multiple California AVAs while competing on price-accessible tiers. Silver Oak anchors its portfolio with American-oak-aged expressions that dominate restaurant wine lists.
Cabernet Sauvignon denotes a red Vitis vinifera varietal distinguished by thick skins, high tannin content, and typical alcohol levels ranging from 13.5% to 15%, fermented on skins and aged in oak barrels to develop structure and aromatic complexity. The varietal serves as the backbone of premium red wine production across temperate climate zones worldwide. Ultra-Premium price tier expressions capture disproportionate margin pools as collectors and allocators concentrate purchases on provenance-verified bottlings. Direct Sales channels expand fastest as wineries bypass traditional three-tier systems to build consumer relationships and retain full margin.
US Alcohol and Tobacco Tax and Trade Bureau labeling standards govern appellation claims and alcohol content disclosures, shaping how producers market origin and style. EU REACH chemicals regulation and EFSA pesticide residue limits constrain vineyard input choices, pushing growers toward integrated pest management and organic conversion. California's State Water Resources Control Board groundwater sustainability requirements restrict irrigation access in drought-prone counties. Stakeholders must monitor how climate adaptation regulations intersect with consumer willingness to absorb compliance-driven cost pass-throughs.
Market Dynamics
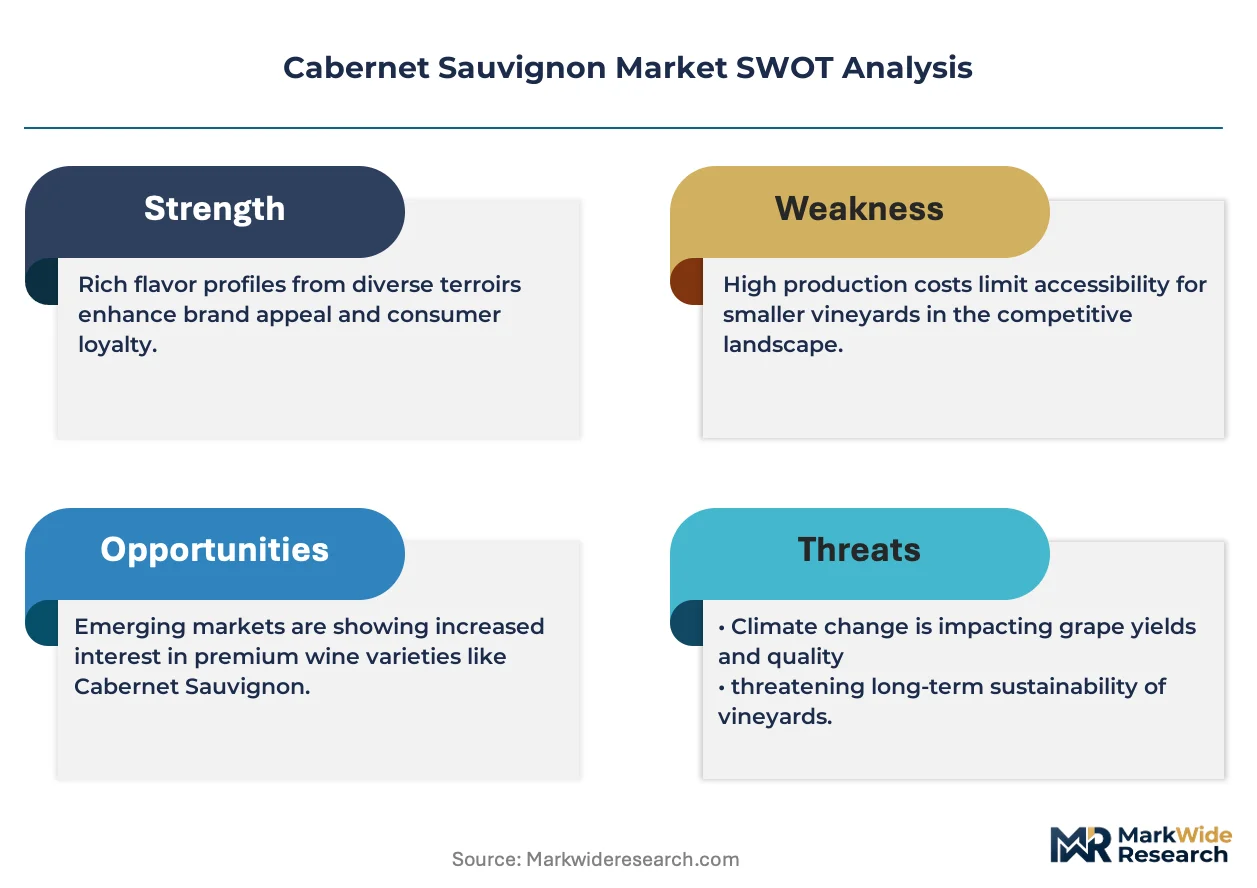
Climate adaptation mandates from California's State Water Resources Control Board are compressing vineyard irrigation access while EU Green Deal certification requirements fragment supply eligibility across export channels.
Growth Catalysts
- Direct-to-Consumer Channel Expansion:Wineries bypass three-tier distribution to capture full margin through subscription clubs and estate visitation. Napa Valley producers lead this channel pivot.
- EU Green Deal Sustainability Mandates:Organic and biodynamic certification requirements reshape vineyard management practices. Compliance unlocks premium pricing in European export markets.
- On-Premise Dining Recovery:Ultra-premium restaurant wine lists drive allocation-based distribution for single-vineyard expressions. Sommelier curation concentrates demand on provenance-verified bottlings.
Market Restraints
- Groundwater Access Restrictions:California's Sustainable Groundwater Management Act limits irrigation in drought-prone AVAs. Vineyard development costs escalate in water-constrained counties.
- American Oak Barrel Concentration:Cooperage supply concentrates among Missouri and Minnesota forest suppliers. Tariff exposure and freight costs amplify input price volatility.
- Climate-Induced Vintage Variability:Heat spikes and smoke exposure from wildfires degrade fruit quality in temperate zones. Crop insurance gaps expose growers to catastrophic loss.
Strategic Opportunities
- Biodynamic Certification Penetration:Demeter and Regenerative Organic Certified standards command price premiums in coastal urban markets. Early conversion captures allocation scarcity value.
- Alternative Oak Species Adoption:French and Eastern European oak integration diversifies flavor profiles beyond American oak dominance. Blending programs expand stylistic range.
- Non-Traditional AVA Development:High-elevation sites in Lake County and Paso Robles offer terroir differentiation at lower land costs. Cool-climate expressions attract sommelier attention.
Industry Challenges
- Viticulture Labor Shortage:H-2A visa program constraints limit seasonal harvest crews. Mechanization lags for selective hand-picking of premium fruit.
- Extended Compliance Timelines:Organic certification requires three-year conversion periods with yield penalties. Cash flow stress accumulates during transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cabernet Sauvignon Market |
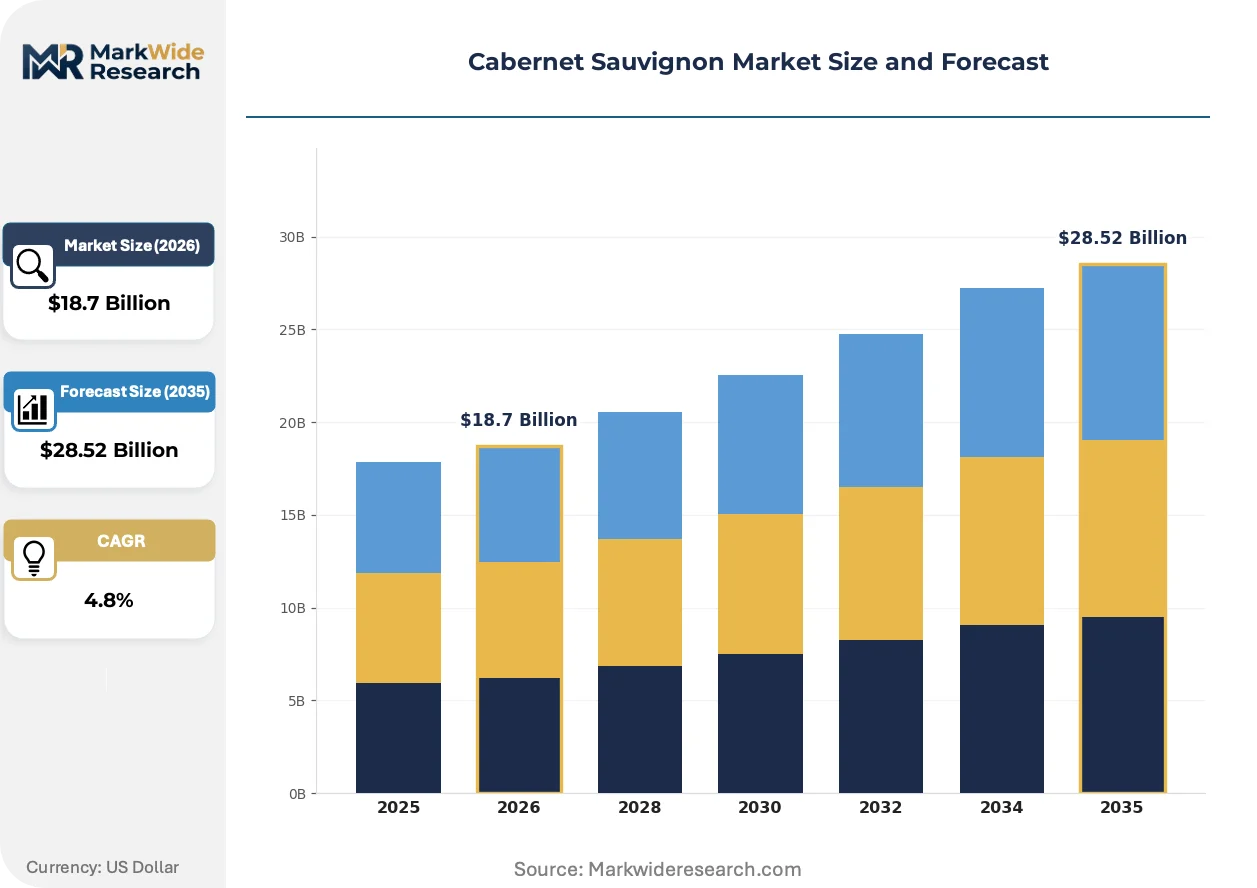
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red, White, Sparkling, Dessert Price Tier: Premium, Mid-Range, Budget, Ultra-Premium Distribution Channel: Online, Retail, HoReCa, Direct Sales Packaging Type: Bottle, Box, Can, Tetra Pak |
| Companies Covered | Harlan Estate, Stag's Leap Wine Cellars, Beringer Vineyards, Spottswoode Estate, Silver Oak, Duckhorn Vineyards, Caymus Vineyards, Far Niente, Screaming Eagle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cabernet Sauvignon Market Emerging Trajectories
Precision viticulture technologies and regenerative agriculture protocols are compressing traditional vineyard management cycles while reshaping how producers validate quality claims to trade buyers.
Sensor-based canopy management systems integrating drone-mounted multispectral imaging with soil moisture telemetry are overtaking visual scouting and manual intervention schedules. Large estate holdings in Napa and Sonoma deploy these platforms to optimize irrigation timing and disease pressure response. The technology is overtaking experiential vineyard management by enabling block-level precision that reduces input waste and compresses operational decision cycles from weeks to hours.
EU REACH chemicals regulation and EFSA pesticide residue limits are constraining synthetic input portfolios across export-oriented vineyards. Producers face reformulation costs for vineyard sprays and extended residue testing protocols. The regulation most affects bulk wine exporters to European markets, pushing accelerated adoption of integrated pest management and sulfur-only spray programs.
Allocation-based purchasing through mailing lists and futures programs is displacing traditional wholesale distribution for ultra-premium tiers. Collectors and restaurant buyers secure barrel commitments before bottling, locking in scarcity value. This behavioral shift concentrates most visibly in Napa Valley, where Harlan Estate and similar producers maintain waitlists exceeding a decade for new customers.
Cabernet Sauvignon Market Segmentation
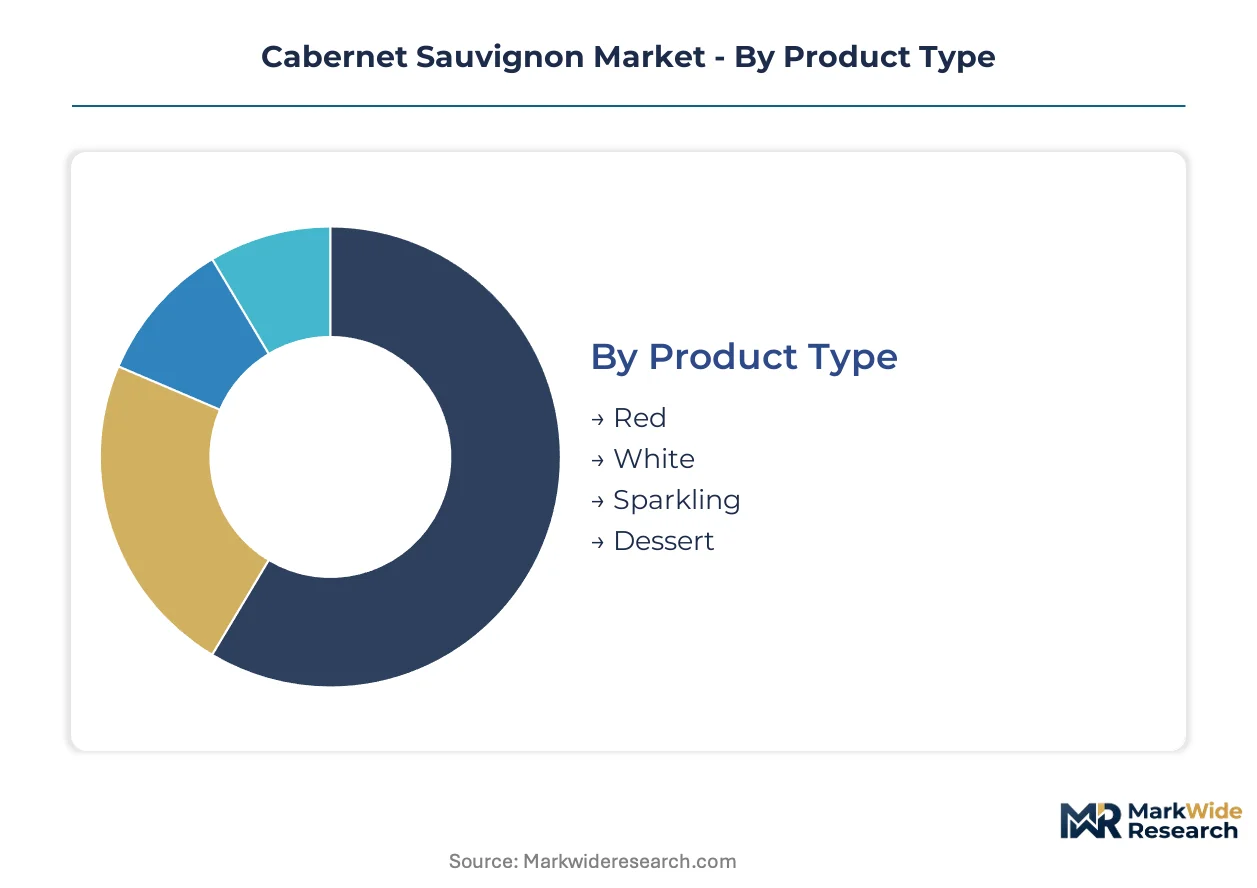
Cabernet Sauvignon's market architecture fragments across four critical dimensions. Each category captures distinct margin pools and operational constraints that reshape how producers allocate capital and build route-to-market strategies.
Product Type:
Red wine production concentrates in Napa Valley and Bordeaux, where thick-skinned Vitis vinifera fruit commands premium extraction protocols.
- Red:Fermented on skins with extended maceration periods, this expression dominates restaurant wine lists and collector cellars. Napa Valley's Oakville bench anchors global demand for single-vineyard bottlings as sommeliers prioritize provenance verification.
- White:Produced via immediate pressing and cool fermentation, this style serves as a stylistic outlier for warm-climate producers seeking differentiation. Paso Robles experimentation attracts coastal urban markets seeking novelty.
- Sparkling:Traditional method secondary fermentation creates texture variation for celebratory occasions. Limited production scales constrain mainstream penetration.
- Dessert:Late-harvest or fortified expressions occupy niche gift and after-dinner channels. Port-style regulations limit geographic claim authenticity.
Today's leader: Red. Tomorrow's challenger: White.
Price Tier:
Margin concentration follows allocation scarcity and provenance authentication intensity across the value pyramid.
- Ultra-Premium:Single-vineyard designates with barrel-select programs command allocation-based distribution through mailing lists. Harlan Estate waitlists exceed a decade as collectors absorb scarcity premiums.
- Premium:AVA-specific bottlings with estate fruit concentration dominate independent retail and on-premise by-the-glass programs. Sommelier curation drives repeat placement velocity.
- Mid-Range:Multi-AVA blending achieves volume scale while retaining varietal typicity. Grocery channel placement requires price-point discipline against private label competition.
- Budget:Bulk wine sourcing and synthetic cork closure minimize unit economics for mass-market distribution. Margin compression limits brand investment capacity.
Ultra-Premium captures margin concentration. Mid-Range faces the steepest channel pressure.
Distribution Channel:
Route-to-market selection determines margin retention and consumer relationship depth.
- Direct Sales:Subscription clubs and estate visitation bypass three-tier markups entirely. Napa producers retain full margin while capturing behavioral data for personalization.
- HoReCa:On-premise placement requires distributor relationships and sommelier education investment. List placement velocity correlates with critic scores.
- Retail:Independent merchants and grocery chains demand promotional support and shelf placement fees. Consolidated buyer power compresses terms.
- Online:Third-party platforms and proprietary e-commerce expand geographic reach. Shipping compliance complexity fragments state-by-state execution.
Direct Sales expands most quickly. Retail confronts margin erosion.
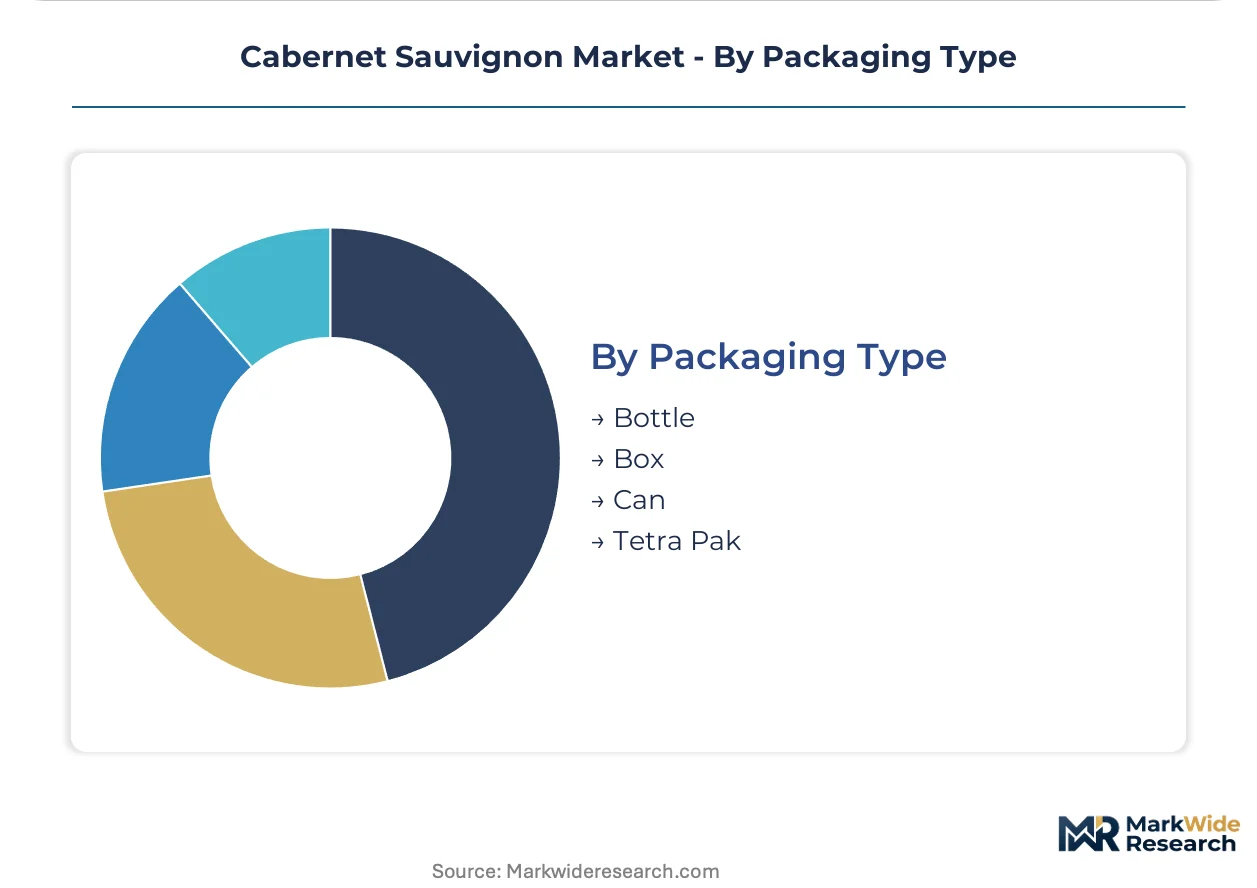
Packaging Type:
Format selection signals quality positioning while constraining logistics and occasion targeting.
- Bottle:Traditional 750ml glass with natural cork closure dominates provenance-verified tiers. American oak barrel aging protocols align with closure oxygen transmission rates.
- Box:Bag-in-box formats reduce per-liter shipping costs for casual consumption occasions. European export markets accept quality claims more readily than domestic channels.
- Can:Single-serve aluminum enables outdoor and event-based consumption. Limited premium adoption constrains price realization.
- Tetra Pak:Aseptic cartons minimize carbon footprint for volume shipping. EU Green Deal packaging mandates accelerate format experimentation.
Bottle maintains quality authority. Box gains sustainability-driven traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Winemaking talent clusters in California's Napa and Sonoma counties anchor global Cabernet Sauvignon production, with master viticulturists and enologists commanding premium compensation packages that reinforce quality differentiation.
United States
Napa Valley's Oakville bench and Rutherford bench concentrate ultra-premium single-vineyard demand as collectors prioritize provenance verification. California's State Water Resources Control Board groundwater sustainability requirements restrict irrigation access in drought-prone counties, elevating vineyard development costs. St. Helena and Calistoga sub-regions attract biodynamic conversion investments as producers seek allocation scarcity value.
France
Bordeaux's Pauillac and Margaux appellations sustain allocation-based distribution through négociant networks and en primeur futures programs. EU REACH chemicals regulation and EFSA pesticide residue limits constrain synthetic vineyard inputs, pushing growers toward integrated pest management. The Médoc peninsula's gravel terroir commands sustained sommelier curation in Paris and London on-premise channels.
Australia
Coonawarra's terra rossa soil corridor and Margaret River's cool-climate sites attract sommelier attention for stylistic differentiation from California expressions. The country's national wine regulator enforces strict geographical indication standards that shape export market access. Barossa Valley producers experiment with alternative oak species to diversify beyond American cooperage dominance.
Chile
Maipo Valley's alluvial terraces and Colchagua Valley's hillside plantings offer terroir differentiation at lower land costs than Napa equivalents. The national agricultural service enforces sustainability certification protocols that unlock European export market premiums. Santiago-based producers expand direct-to-consumer e-commerce platforms to bypass traditional three-tier markups.
Italy
Super Tuscan producers in Bolgheri and Maremma leverage Cabernet Sauvignon blending flexibility to command price premiums above traditional Sangiovese expressions. The national ministry of agriculture enforces organic conversion incentives that accelerate biodynamic certification timelines. Florence and Milan urban markets concentrate collector demand for provenance-verified bottlings.
Cabernet Sauvignon Market Vendor Landscape
Capital-heavy estate producers compete with asset-light negociant blenders across tiered market positions. The vendor base concentrates in California's Napa Valley and Bordeaux's Médoc, with family-held estates dominating ultra-premium allocation channels while corporate holdings sustain volume scale. Three archetypes anchor competitive positioning: terroir-exclusive single-vineyard specialists, multi-AVA blending houses, and American-oak-aging-focused portfolio builders. Dominant competitive moves include biodynamic certification conversion to capture scarcity premiums and direct-to-consumer channel expansion to retain full margin.
Within the terroir-exclusive tier, Harlan Estate and Screaming Eagle occupy positions defined by Oakville bench exclusivity and decade-long waitlist dynamics. Among multi-AVA blending houses, Beringer Vineyards and Caymus Vineyards represent scale-driven archetypes that sustain volume across price-accessible tiers while retaining brand authority. Silver Oak anchors the American-oak-aging specialist archetype, with portfolio concentration on restaurant wine list dominance.
| Leading Market Players |
|---|
| Harlan Estate |
| Stag's Leap Wine Cellars |
| Beringer Vineyards |
| Spottswoode Estate |
| Silver Oak |
| Duckhorn Vineyards |
| Caymus Vineyards |
| Far Niente |
| Screaming Eagle |
| Others |
Supply Flow & Price Mechanics
Family-held estate producers across Napa Valley and Bordeaux anchor supply-side discipline through generational capital allocation that resists short-term pricing pressure. Their ownership structure enables decade-long aging programs and allocation-based distribution that corporate roll-ups cannot replicate, insulating ultra-premium tiers from commodity volatility while compressing margins in volume-driven segments.
Pricing Analysis
Allocation-based futures programs versus spot-market wholesale purchasing splits pricing behavior across tiers. Ultra-premium expressions command scarcity premiums through mailing-list distribution, while mid-range tiers face grocery-channel price compression against private-label competition. Cost escalation in American oak cooperage and drought-driven vineyard development expenses intensify margin pressure at the premium-mid-economy boundary. Restaurant buyers and collectors absorb price premiums for provenance-verified bottlings; mass-market consumers demonstrate acute sensitivity to shelf-price differentials.
Supply Chain Analysis
California's groundwater sustainability mandates and EU Green Deal organic certification requirements are reshaping input sourcing across export-oriented vineyards. Missouri and Minnesota forest suppliers concentrate American oak cooperage supply, while French and Eastern European alternatives diversify barrel programs. Tariff exposure on imported oak and single-source vulnerability in premium cork supply amplify input price volatility. Distribution runs through three-tier wholesale networks for retail and HoReCa channels, with direct-to-consumer estate sales bypassing traditional markups entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cabernet Sauvignon operates as a late-cycle quality story as collector demand shifts decisively toward single-vineyard designates with verified provenance. This specification premium rewards patient capital and terroir-exclusive positioning over volume-scale strategies.
For Market Incumbents: Cement allocation scarcity value through biodynamic certification conversion in Napa Valley and St. Helena sub-regions. Deepen vertical integration into estate vineyard holdings to secure fruit supply against drought-driven development cost escalation. Prioritize direct-to-consumer channel infrastructure to capture full margin and build behavioral data assets for personalization.
For New Entrants and Emerging Players: The price-point gap between ultra-premium Oakville bench designates and mid-range multi-AVA blends offers white-space entry. Target high-elevation Lake County and Paso Robles sites for terroir differentiation at lower land costs. Pursue sommelier-led placement in coastal urban on-premise channels as the primary go-to-market vector.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap multi-AVA blending houses with underdeveloped direct-to-consumer infrastructure. Long-term viability hinges on water-rights security and organic certification timelines. Watch biodynamic conversion completion rates as the inflection signal for allocation scarcity value capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodynamic Certification Conversion | Demeter and Regenerative Organic Certified standards unlock scarcity premiums in coastal urban markets. |
| Direct-to-Consumer Channel Expansion | Subscription clubs and estate visitation bypass three-tier markups while capturing consumer behavioral data. |
| Alternative Oak Species Integration | French and Eastern European oak diversification reduces tariff exposure and expands stylistic range. |
| High-Elevation AVA Development | Lake County and Paso Robles sites offer terroir differentiation at lower land costs than Napa equivalents. |
| Precision Viticulture Technology Deployment | Drone-mounted multispectral imaging compresses operational decision cycles from weeks to hours. |
Methodological Framework
Multiple input streams — primary interviews with estate winemakers, enologists, and sommelier buyers; secondary validation through customs records and AVA production databases; and regulatory filing analysis — were reconciled to construct segment-level estimates. Conversations with Napa Valley vineyard managers, Bordeaux négociant network heads, and restaurant wine program directors supplied operational context. Trade publications, EU REACH compliance documentation, and California State Water Resources Control Board filings provided secondary grounding. Bottom-up vineyard acreage and case production estimates triangulated against top-down value chain assessments.
Historical vintage volume patterns cross-referenced against expert panel input on climate adaptation and certification timelines shaped the projection framework. Segmentation modeling spanned product type, price tier, distribution channel, and packaging format dimensions across the analysis window. CAGRs derived from trend extrapolation moderated by regulatory compliance cost pass-through assumptions and consumer willingness-to-pay elasticity estimates. Forecast inputs incorporated groundwater restriction severity scenarios and organic conversion yield penalty curves.
Caveats apply where wildfire smoke exposure frequency, tariff regime shifts on cooperage imports, or H-2A visa program constraints could materially shift the outlook. Forecasts embed assumptions regarding sustained collector demand for provenance-verified bottlings and restaurant wine list recovery velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Home Beer Brewing Machine Market
Alcoholic Beverages
Puncheon Barrel Market
Alcoholic Beverages
Organic Wine Market
Alcoholic Beverages
Premixed Margarita Market
Alcoholic Beverages
RTD Canned Cocktail Market
Alcoholic Beverages
Cognac Brandy Market
Alcoholic Beverages
North America Soju Market
Alcoholic Beverages
United States Tequila Market
Alcoholic Beverages
North America Craft Beer Market
Alcoholic Beverages
Rhum Agricole Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Canada Alcohol E-Commerce Market
Alcoholic Beverages
Wine Chocolate Market
Alcoholic Beverages
Brandy Market