
 Organic Alcoholic Beverages Market | 2026-2036
Organic Alcoholic Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Alcoholic Beverages Market Analytics
Premium certified organic tiering is bifurcating the competitive landscape as health-conscious consumers trade up from conventional alternatives. Constellation Brands leverages its wine portfolio depth to secure North American shelf space for organic varietals. Diageo anchors its strategy through dedicated organic spirit lines in European duty-free channels. Pernod Ricard differentiates via biodynamic vineyard partnerships that extend beyond baseline organic compliance.
Organic alcoholic beverages denote ethanolic drinks manufactured from ingredients cultivated without synthetic pesticides, genetically modified organisms, or petroleum-based fertilizers, typically bearing third-party organic certification such as USDA Organic or EU Organic logo compliance. The category serves commercial and retail buyers seeking verified clean-label alternatives with traceable agricultural inputs. Wine dominates current revenue contribution due to established vineyard conversion programs and mature certification infrastructure across Old World producers. Beer registers the fastest structural expansion as craft breweries retrofit operations to capture health-conscious millennials. Spirits concentrate margin pools in super-premium price bands where organic agave and grain provenance command substantial bottle-price premiums.
USDA Organic standards govern American ingredient sourcing and labeling claims, while EU organic wine regulations restrict oenological additives and sulfite thresholds for certified European production. REACH chemical frameworks indirectly shape supply chains by limiting permitted vineyard treatments in export-bound European grapes. Forward-looking stakeholders must monitor certification harmonization between national organic programs as divergence creates compliance friction for multinational brand portfolios.
Market Dynamics
Certification divergence between USDA Organic and EU organic wine standards is fragmenting supply chains as producers face dual compliance burdens for transatlantic distribution. This regulatory friction forces portfolio segmentation and raises input traceability costs across the value chain.
Growth Catalysts
- Millennial urban consumption clusters:Premium bar scenes in Berlin, Brooklyn, and Melbourne drive organic beer trial and brand switching among health-conscious drinkers aged 25-40.
- EU organic wine regulation tightening:Stricter sulfite thresholds and oenological additive restrictions create competitive moats for early-certifying Old World vineyards.
- Craft brewery retrofitting wave:Small-batch facilities in Germany's Bavaria and North Rhine-Westphalia regions convert malt sourcing to certified organic supply.
Market Restraints
- Organic grain and grape input cost volatility:Weather-sensitive organic barley and wine grape harvests in France and Italy create margin compression for price-locked contract brewers.
- Certification infrastructure concentration:USDA-accredited certifiers cluster in California and Washington, creating geographic bottlenecks for heartland distillers seeking organic spirit designation.
- Technical yield gaps:Organic vineyard conversion programs in Spain and Portugal require 3-year transition periods without corresponding price premiums during interim harvests.
Strategic Opportunities
- Underpenetrated Indian metropolitan markets:Mumbai and Bangalore hospitality sectors show nascent demand for imported organic wine, with FSSAI import clearance pathways now clarifying.
- Biodynamic premium tier extension:Demeter-certified vineyard partnerships in Austria and Germany command 40-60% bottle price premiums above baseline organic compliance.
- Duty-free channel specialization:European airport retail chains expand dedicated organic spirits shelving, capturing transit passenger trial with limited-edition regional expressions.
Industry Challenges
- Enologist and viticulturist talent scarcity:Specialized expertise in organic fermentation management and biodynamic vineyard practices concentrates in legacy European wine regions, limiting New World expansion.
- Multi-certification audit complexity:Producers seeking simultaneous USDA Organic, EU organic, and biodynamic credentials face overlapping inspection schedules and conflicting documentation standards.
- Legacy equipment reconfiguration costs:Conventional breweries and distilleries must replace petroleum-based cleaning agents and sanitizers to meet organic processing facility requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Alcoholic Beverages Market |
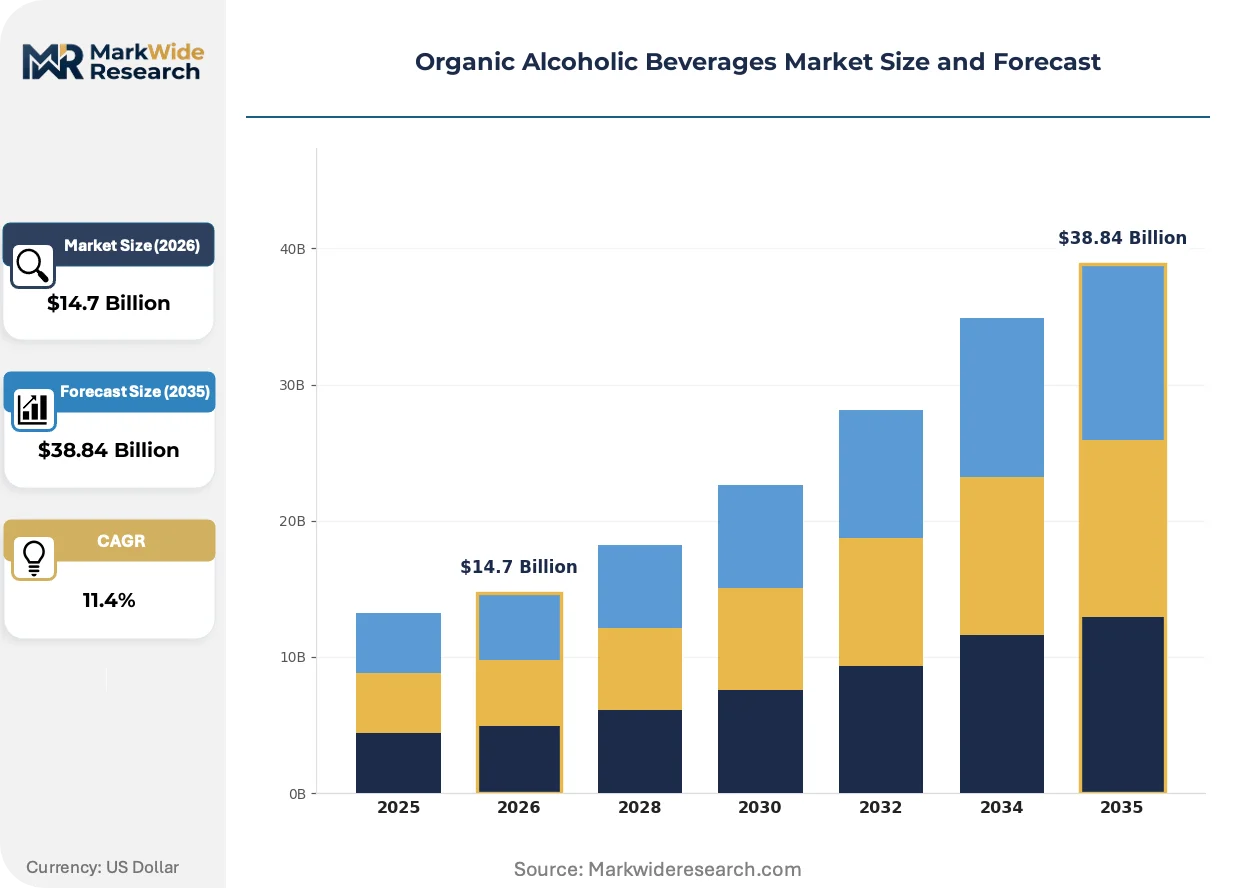
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Cider Packaging Type: Bottles, Cans, Kegs, Pouches Distribution Channel: Retail, Online, Wholesale, Direct-to-Consumer Consumer Type: Millennials, Health-Conscious Drinkers, Eco-Friendly Consumers, Trendsetters |
| Companies Covered | Constellation Brands, Pernod Ricard, Diageo, Carlsberg Group, Bacardi Limited, Brown-Forman, Heineken, Asahi Group Holdings, Anheuser-Busch InBev, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Alcoholic Beverages Market Evolving Landscape
Blockchain-enabled provenance tracking is reshaping how organic alcoholic beverages compete on transparency, with distributed ledger verification replacing paper-based chain-of-custody documentation. This shift compresses the information asymmetry between certified producers and skeptical premium buyers.
Near-infrared spectroscopy is fragmenting quality control workflows across organic wine and spirits production. Handheld NIR devices enable rapid pesticide residue screening at receiving docks, accelerating batch release decisions. Mid-sized craft producers in Oregon and Alsace deploy these units to reduce third-party laboratory testing dependencies. The technology compresses certification compliance timelines from weeks to hours.
EU F-Gas Regulation phase-down mandates are forcing refrigeration system retrofits in organic wine cellars across France, Italy, and Spain. Natural refrigerant alternatives and passive cooling architecture now dominate new facility construction. Premium biodynamic estates in Burgundy and Piedmont absorb these capex burdens to maintain carbon-neutral brand positioning and avoid operational disruption from synthetic coolant supply constraints.
Direct-to-consumer subscription models are displacing traditional three-tier distribution for niche organic spirits and small-batch wines. Urban millennials in London, San Francisco, and Sydney curate monthly deliveries based on terroir transparency and regenerative agriculture storytelling. This channel shift concentrates customer data ownership with producers and compresses wholesale margin capture for legacy distributors.
Organic Alcoholic Beverages Market Segmentation
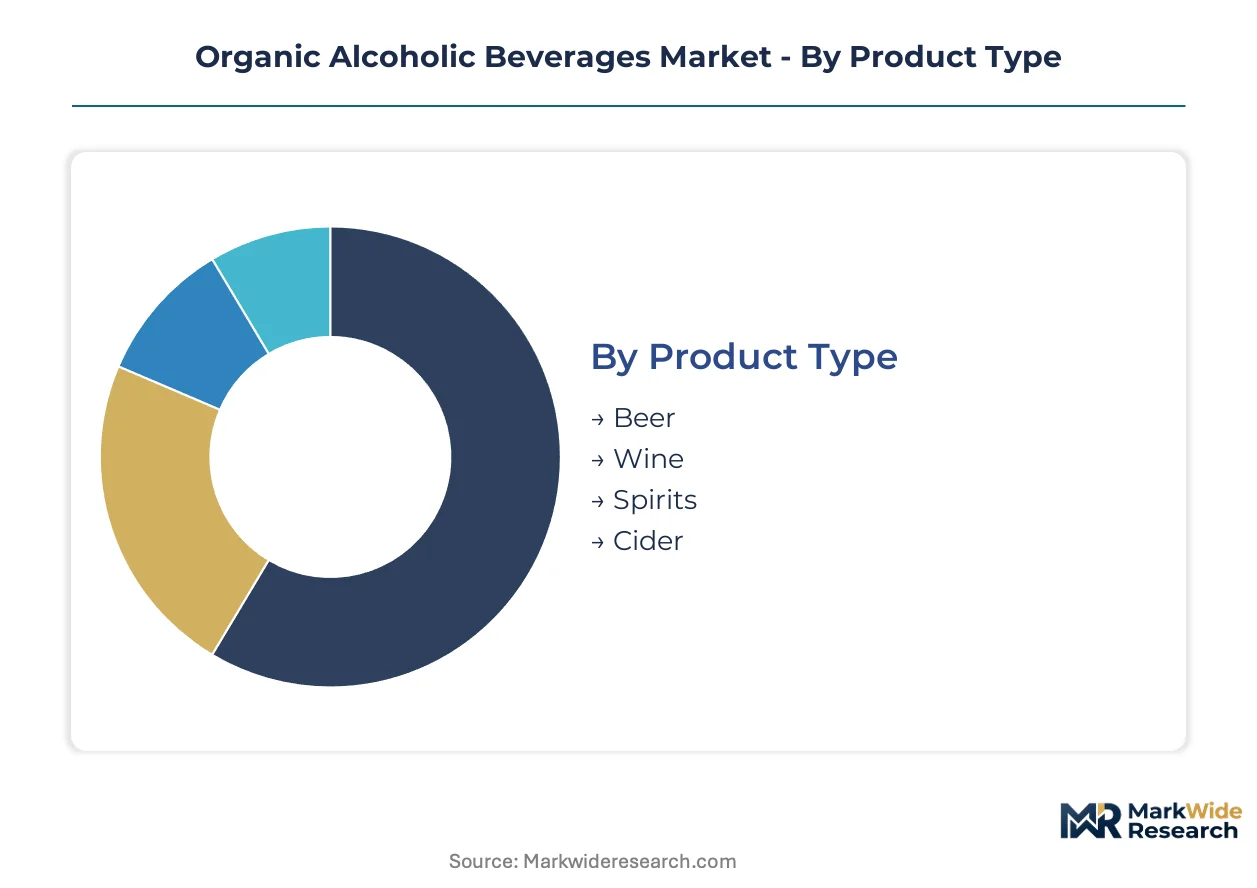
Organic alcoholic beverages fragment across four distinct category axes that determine pricing power, channel access, and certification burden. Product type governs agricultural input requirements and conversion timelines. Packaging and distribution shape margin capture and consumer data ownership. Consumer segmentation reveals which demographics absorb premium price tiers.
Product Type:
Wine and spirits face intensifying substitution pressure from non-alcoholic botanical alternatives in wellness-focused hospitality venues, forcing organic producers to differentiate through terroir storytelling rather than intoxication effects alone.
- Wine:Fermented grape juice from certified organic vineyards, subject to EU sulfite thresholds and USDA processing standards. Demand clusters in Germany's urban restaurant scenes where sommelier certification programs elevate organic list placement. Old World vineyard conversion programs in France and Italy supply established import channels.
- Beer:Malted barley and hop-based fermentation requiring organic grain supply chains and petroleum-free facility sanitization. Brooklyn, Melbourne, and Berlin craft brewery clusters drive fastest structural expansion as millennials trade conventional lagers for traceable organic alternatives. Bavarian maltsters anchor European supply.
- Spirits:Distilled ethanol from organic agave, grain, or sugarcane with super-premium positioning in duty-free and specialty retail. Demeter-certified biodynamic expressions from Austria command bottle price premiums above baseline organic compliance.
- Cider:Apple or pear fermentation with lighter regulatory burden than wine but concentrated seasonal supply risk. English and Normandy orchards supply heritage varietal expressions.
Wine retains volume leadership across certification tiers; beer holds the steepest expansion curve among product categories.
Packaging Type:
Cost tier stratification separates premium glass presentation from economy aluminum and bulk keg formats, with packaging choice directly constraining distribution channel eligibility and per-unit margin realization.
- Bottles:Standard wine and spirits presentation format with established recycling infrastructure and premium shelf positioning. Burgundy and Alsace producers favor lightweight glass to reduce transport emissions.
- Cans:Aluminum format dominating craft beer and RTD spirits, enabling outdoor and event consumption occasions. Oregon and Colorado breweries lead organic canning line adoption.
- Kegs:Stainless steel and PET formats for on-premise draft service, concentrating in Berlin and Melbourne bar economies with deposit-return schemes.
- Pouches:Flexible film packaging for festival and camping occasions, limited to cider and wine spritzers with shorter shelf stability requirements.
Bottles command margin leadership in spirits; cans are expanding most quickly in beer applications.
Distribution Channel:
Direct-to-consumer models are displacing wholesale intermediaries, concentrating customer data ownership with producers while compressing legacy distributor margin capture in premium urban markets.
- Retail:Supermarket and specialty store placement requiring organic certification documentation and slotting fee negotiations. Whole Foods and Edeka chains expand dedicated organic alcohol shelving.
- Online:E-commerce platforms and subscription services enabling terroir storytelling and regenerative agriculture narratives. London, San Francisco, and Sydney millennials curate monthly deliveries bypassing three-tier systems.
- Wholesale:Traditional distributor networks controlling restaurant and bar access, with organic portfolios concentrated in California, Washington, and Bavaria wholesaler portfolios.
- Direct-to-Consumer:Winery and brewery tasting room sales plus shipping compliance, strongest in states with relaxed direct shipping laws.
Retail maintains volume concentration; direct-to-consumer channels gain share fastest among premium producers.
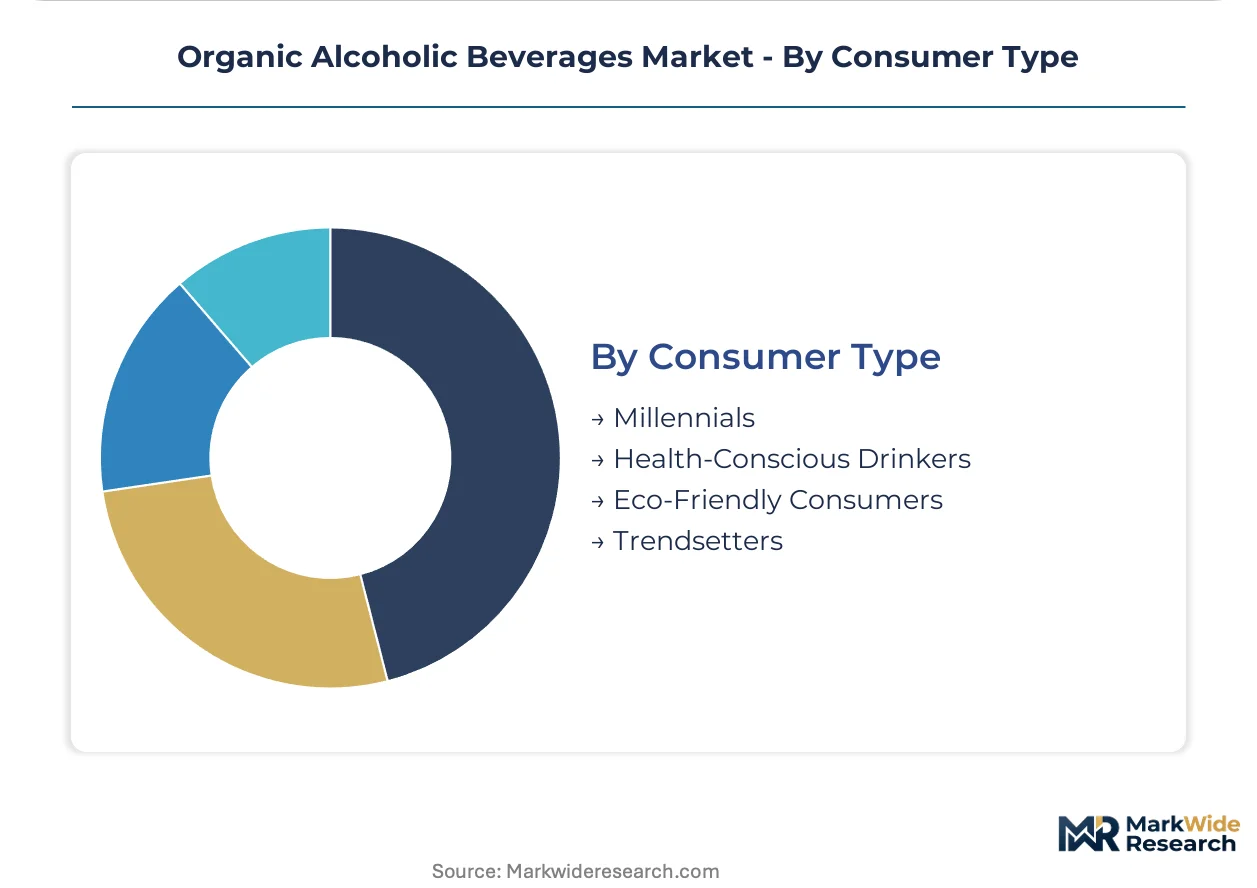
Consumer Type:
Application-based segmentation separates habitual drinkers seeking clean-label assurance from occasion-driven purchasers responding to sustainability signaling and social visibility.
- Millennials:Urban consumers aged 25-40 driving trial in premium bar scenes and subscription curation, with price elasticity varying by metropolitan density.
- Health-Conscious Drinkers:Buyers prioritizing pesticide-free inputs and sulfite reduction, concentrated in fitness-integrated lifestyle segments across Australia and California.
- Eco-Friendly Consumers:Sustainability-motivated purchasers responding to carbon-neutral and regenerative agriculture claims, with willingness-to-pay premiums for blockchain-verified provenance.
- Trendsetters:Early adopters seeking limited releases and biodynamic expressions for social signaling, dominating Instagram-native brand discovery.
Millennials anchor current volume; health-conscious drinkers are climbing the fastest as wellness integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified organic vineyard acreage concentrates in France, Germany, and Italy, where conversion programs and EU regulatory harmonization anchor supply. Millennial consumption clusters in Brooklyn, Berlin, and Melbourne pull volume through premium urban hospitality channels. National organic programs in the United States and emerging import pathways in India reshape distribution geography.
United States
Millennial clusters in Brooklyn and San Francisco drive organic beer trial through craft brewery taprooms. USDA Organic standards govern ingredient sourcing and labeling claims for domestic producers. California's Central Valley and Washington's Yakima Valley host the densest concentrations of certified organic vineyard acreage.
Germany
Berlin's premium bar scene anchors European organic beer consumption among health-conscious urban drinkers aged 25-40. EU organic wine regulations enforce stricter sulfite thresholds than competing jurisdictions. Bavaria and North Rhine-Westphalia host craft brewery clusters retrofitting malt supply chains to certified organic specifications.
France
Old World vineyard conversion programs in Burgundy and Bordeaux supply established export channels with certified organic varietals. REACH chemical frameworks limit permitted vineyard treatments in export-bound grapes. Alsace producers deploy near-infrared spectroscopy for rapid pesticide residue screening at receiving docks.
Italy
Piedmont and Tuscany estates absorb three-year organic conversion periods without corresponding price premiums during interim harvests. EU F-Gas Regulation phase-down mandates force refrigeration retrofits in organic wine cellars across northern regions. Biodynamic Demeter-certified partnerships in Emilia-Romagna command substantial bottle price premiums.
India
Mumbai and Bangalore hospitality sectors show nascent demand for imported organic wine among affluent urban consumers. FSSAI import clearance pathways are clarifying for certified organic beverage categories. Metropolitan duty-free channels at Delhi and Mumbai airports expand dedicated organic spirits shelving.
Organic Alcoholic Beverages Market Competitive Landscape
Concentration sits with diversified beverage conglomerates that leverage existing distribution infrastructure to secure retail shelf space for organic portfolios. The competitive landscape tiers between multinational volume players, regional craft specialists, and premium biodynamic estates. Strategic moves center on portfolio diversification through dedicated organic product lines and backward integration into certified ingredient supply chains.
Within the multinational tier, Constellation Brands, Pernod Ricard, and Diageo represent distinct strategic archetypes. Constellation Brands exemplifies wine portfolio depth applied to North American organic varietal placement. Pernod Ricard occupies a position defined by biodynamic vineyard partnerships extending beyond baseline organic compliance. Diageo anchors its approach through dedicated organic spirit lines in European duty-free channels. These three players collectively illustrate how scale advantages translate into certification infrastructure and channel access.
| Leading Market Players |
|---|
| Constellation Brands |
| Pernod Ricard |
| Diageo |
| Carlsberg Group |
| Bacardi Limited |
| Brown-Forman |
| Heineken |
| Asahi Group Holdings |
| Anheuser-Busch InBev |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Bavarian maltsters and craft breweries lock in organic barley supply visibility while insulating brewers from harvest price spikes. These agreements concentrate procurement leverage among early-certifying producers and compress margin volatility for retrofitted facilities in Germany's North Rhine-Westphalia cluster.
Pricing Analysis
EU organic wine regulations dictate the pricing tier structure by enforcing stricter sulfite thresholds that create compliance moats for certified Old World vineyards. Three-tier pricing structure across premium biodynamic, standard organic, and economy conventional levels separates Demeter-certified Austrian estates from baseline USDA Organic competitors. Pricing pressure stems from weather-sensitive organic grape harvests in France and Italy that compress margins for price-locked contract producers. Health-conscious millennials in Brooklyn and Berlin show lowest price sensitivity, while conventional beer drinkers trading up exhibit highest elasticity.
Supply Chain Analysis
Container availability constraints on Atlantic trade lanes complicate inbound logistics for European organic wine exports to North American retail chains. Geographic supply concentration centers on France, Italy, and Germany for certified vineyard acreage, with Bavaria anchoring European organic malt production. Raw material dependencies rest on organic barley from German cooperatives, wine grapes from Burgundy and Piedmont estates, and biodynamic agave from select Mexican highland parcels. Single-source vulnerability concentrates in USDA-accredited certifiers clustered in California and Washington, creating geographic bottlenecks for heartland distillers. Distribution runs through three-tier wholesale networks controlling restaurant and bar access, with direct-to-consumer subscription models displacing legacy intermediaries in premium urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic alcoholic beverages market is recovering from cyclical input cost compression as vineyard conversion programs mature and certified acreage expands. Weather-driven harvest volatility remains the primary cyclical swing factor dictating margin restoration timelines.
For Market Incumbents: Fortify certification infrastructure by securing captive organic grain supply through backward integration into Bavarian maltster partnerships. Expand dedicated organic spirits shelving in European duty-free channels before competitor portfolio saturation. Channel control through direct-to-consumer subscription platforms defends against wholesale margin compression from legacy distributors.
For New Entrants and Emerging Players: Differentiate on blockchain-enabled provenance tracking to capture eco-friendly consumers willing to pay premiums for transparent agricultural inputs. Target Mumbai and Bangalore hospitality sectors where FSSAI import pathways are clarifying and competition remains sparse. Deploy near-infrared spectroscopy for rapid pesticide screening to accelerate batch release and reduce third-party laboratory dependencies.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap craft breweries with retrofitting momentum in Germany's urban consumption clusters, where millennial trial rates support volume expansion. Long-term viability hinges on certification harmonization between national organic programs reducing compliance friction for multinational portfolios. Monitor EU F-Gas Regulation enforcement as inflection indicator for cellar refrigeration capex burdens affecting biodynamic estate valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Grain Supply | Bavarian maltster partnerships secure input traceability for certified beer production. |
| Biodynamic Certification Investment | Demeter credentials from Austrian estates command 40-60% bottle price premiums. |
| Direct-to-Consumer Platform Launch | Subscription models bypass three-tier systems and concentrate customer data ownership. |
| Blockchain Provenance Implementation | Distributed ledger verification compresses information asymmetry for skeptical premium buyers. |
| Duty-Free Channel Specialization | European airport retail chains expand dedicated organic spirits shelving for transit passenger trial. |
Research Methodology
A spread of perspectives from craft brewery operations directors, organic certification auditors, wine import procurement managers, and duty-free retail category buyers converged on the working assumptions underlying volume and value estimates. Primary fieldwork combined structured interviews with secondary validation from USDA organic certification databases, EU organic wine regulation filings, customs trade records, and SEC beverage conglomerate disclosures. Bottom-up facility capacity assessments triangulated against top-down category spending patterns.
Segmentation dimensions modeled include product type, packaging format, distribution channel, and consumer archetype across the projection horizon. CAGRs were derived from historical certified acreage expansion rates and millennial consumption cluster penetration curves. Industry-specific forecast inputs incorporated vineyard conversion program timelines and craft brewery retrofitting capex cycles.
Decision-makers should treat outputs as directional under assumptions of regulatory harmonization progress and stable organic input cost trajectories; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
North America Tequila Market
Alcoholic Beverages
Beer Dispensing Machine Market
Alcoholic Beverages
North America Beer Market
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
Bahrain Alcoholic Beverages Market
Alcoholic Beverages
Wine Cork Market
Alcoholic Beverages
Global Bourbon Market
Alcoholic Beverages
India Tequila Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Global Red Wine Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Global Hard Seltzers Market
Alcoholic Beverages
Nitro Cocktails Market
Alcoholic Beverages
Canned Wine Market
Alcoholic Beverages
Wine Filling Machine Market
Alcoholic Beverages
South America Wine Market