
 Cigar Market | 2026-2036
Cigar Market Size, Share, and Industry Trends Forecast 2026-2036
Cigar Market Analysis
Subscription-based cigar club services is hardening into a core revenue layer as enthusiasts seek curated monthly deliveries with tasting notes and pairing guidance. Habanos S.A. leverages its state-controlled monopoly over Cuban tobacco to sustain scarcity-driven pricing power across export markets. Scandinavian Tobacco Group A/S dominates machine-made and value-tier segments through mass-market retail channel control. Altria Group Inc. navigates regulatory complexity by diversifying into reduced-risk alternatives while maintaining premium cigar portfolio positions.
A cigar is a tightly rolled bundle of dried and fermented tobacco leaves, typically measuring four to eight inches in length with ring gauges between 32 and 60, designed for slow combustion and manual smoking without inhalation. The fermentation process, lasting months to years, develops complex aromatic compounds through microbial and enzymatic transformation of leaf sugars and proteins. Premium cigars command disproportionate margin pools relative to volume, with hand-rolled puro formats exhibiting the highest per-unit profitability across the product type dimension. Nicaraguan and Dominican tobacco origins are expanding fastest as Cuban supply faces persistent trade restriction pressures, while machine-made cigars occupy the volume-dominant tier through convenience-store and gas-station distribution.
The FDA's Center for Tobacco Products enforces premarket authorization requirements that directly shape which cigar formats achieve legal US market access, while the EU Tobacco Products Directive mandates health warning coverage and restricts cross-border distance sales. Cuba's state monopoly structure, enforced through Habanos S.A. and national customs controls, limits legitimate supply channels and sustains parallel market dynamics. Stakeholders must monitor evolving exemption thresholds for premium hand-rolled classifications, as regulatory reclassification would fundamentally alter compliance burdens and competitive positioning across the value chain.
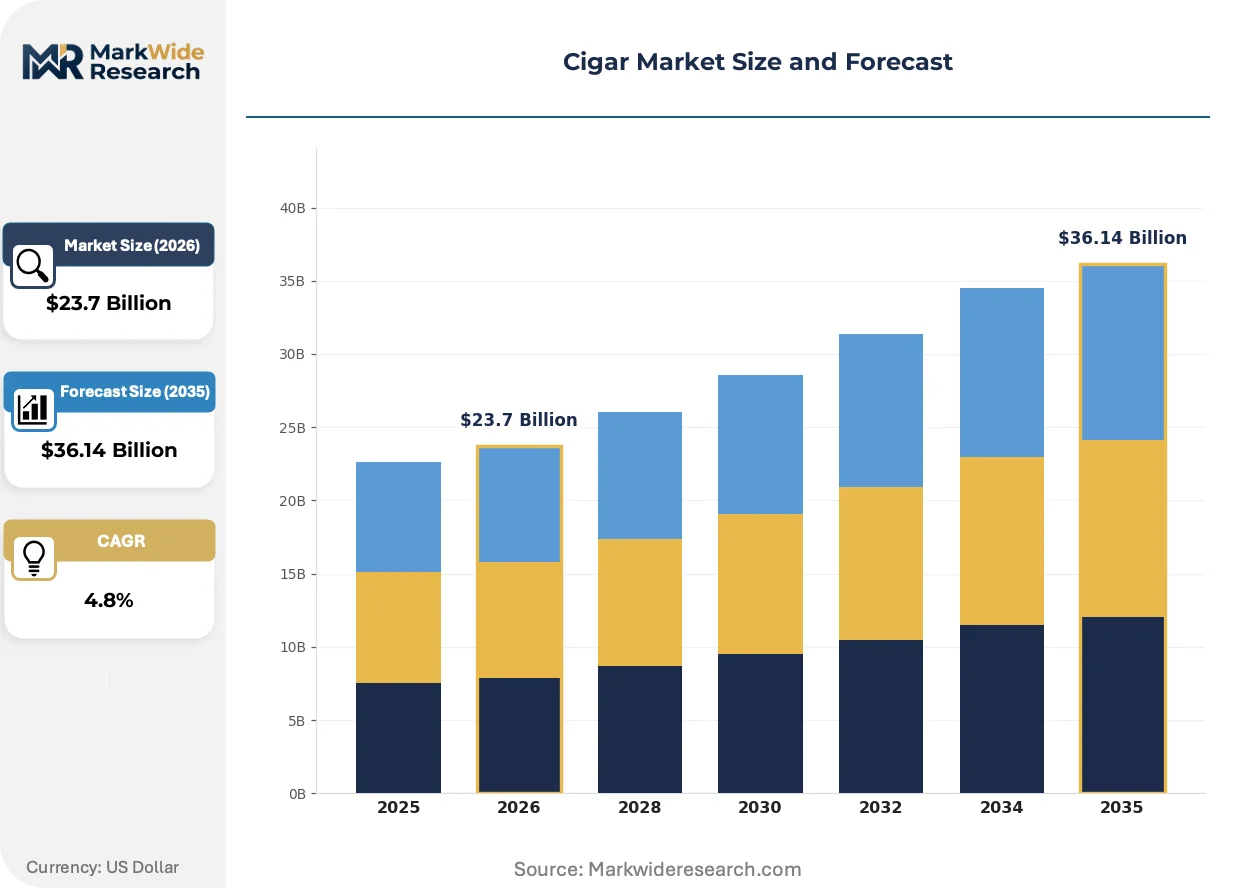
Market Dynamics
Scarcity-driven pricing power concentrated in Cuban state-controlled supply channels is forcing buyer migration toward Nicaraguan and Dominican origins, restructuring competitive positioning across the premium tier.
Growth Catalysts
- Subscription-based cigar club services:Curated monthly deliveries with tasting notes and pairing guidance harden into a core revenue layer as enthusiasts seek discovery-driven consumption models.
- FDA deeming rule debates:Ongoing premium cigar exemption discussions in the US directly shape market access conditions and compliance burden distribution across hand-rolled formats.
- Nicaraguan puro production:Connoisseur buyers actively seek alternatives to Cuban supply constraints, elevating attention toward Central American tobacco origins with established fermentation expertise.
Market Restraints
- Input cost volatility:Tobacco leaf prices fluctuate with climate-driven yield variations across growing regions, compressing margin predictability for small-batch producers.
- Supply concentration risk:Habanos S.A.'s state monopoly over Cuban tobacco limits legitimate export channels and sustains parallel market dynamics that distort price signaling.
- Regulatory friction:The EU Tobacco Products Directive mandates health warning coverage and restricts cross-border distance sales, constraining direct-to-consumer growth vectors in European markets.
Strategic Opportunities
- Underpenetrated hospitality integration:Luxury venues in Dubai and Miami are expanding dedicated cigar lounge programming, creating experiential retail footprints beyond traditional tobacconist channels.
- Reduced-risk alternative diversification:Altria Group Inc. and comparable portfolio managers navigate complexity by building adjacent revenue streams while maintaining premium cigar positions.
- Machine-made volume tier:Scandinavian Tobacco Group A/S demonstrates mass-market retail channel control through convenience-store and gas-station distribution networks that capture frequency-driven consumption.
Industry Challenges
- Master roller talent scarcity:Hand-rolled production depends on skilled torcedores with multi-year training curves, creating bottlenecks as demand shifts toward premium formats.
- Premarket authorization timelines:FDA Center for Tobacco Products enforcement creates extended compliance windows that freeze product innovation cycles and capital deployment.
- Legacy distribution reconfiguration:Traditional brick-and-mortar tobacconist networks face compression from digital discovery platforms, forcing channel conflict management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cigar Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Puro, Cigarillos, Premium Cigars, Machine-Made Cigars Tobacco Origin: Cuban, Dominican, Nicaraguan, Honduran Package Type: Boxes, Bundles, Single Cigars, Tins Flavor Profile: Natural, Flavored, Maduro, Sungrown |
| Companies Covered | Altria Group Inc., Habanos S.A., Scandinavian Tobacco Group A/S, Philip Morris International Inc., British American Tobacco PLC, Imperial Brands PLC, Swisher International Inc., Japan Tobacco Inc., China National Tobacco Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cigar Market Emerging Trajectories
Digital curation platforms and precision fermentation monitoring are restructuring how enthusiasts discover, authenticate, and experience premium tobacco products across physical and virtual touchpoints.
Precision humidity and temperature monitoring systems embedded in smart humidors are overtaking passive storage solutions among serious collectors. High-net-worth buyers in Miami, Dubai, and São Paulo now demand real-time environmental telemetry with mobile alerts. This technology is compressing secondary market risk by guaranteeing provenance condition and reducing insurance disputes over storage-related degradation.
The FDA's deeming rule for premium cigar exemption continues generating industrial uncertainty across US distribution channels. Pending classification thresholds would fundamentally alter compliance burdens for hand-rolled versus machine-made formats. Premium manufacturers are responding by intensifying lobbying investment and diversifying production toward exempt size and weight specifications.
Discovery-driven buying patterns now dominate enthusiast procurement, with curated subscription services displacing traditional brand loyalty among younger demographic segments. Scandinavian and German consumers demonstrate highest adoption of monthly tasting programs with educational content. This behavioral shift is most visible in urban centers where experiential consumption merges with home-based ritual development.
Cigar Market Segmentation
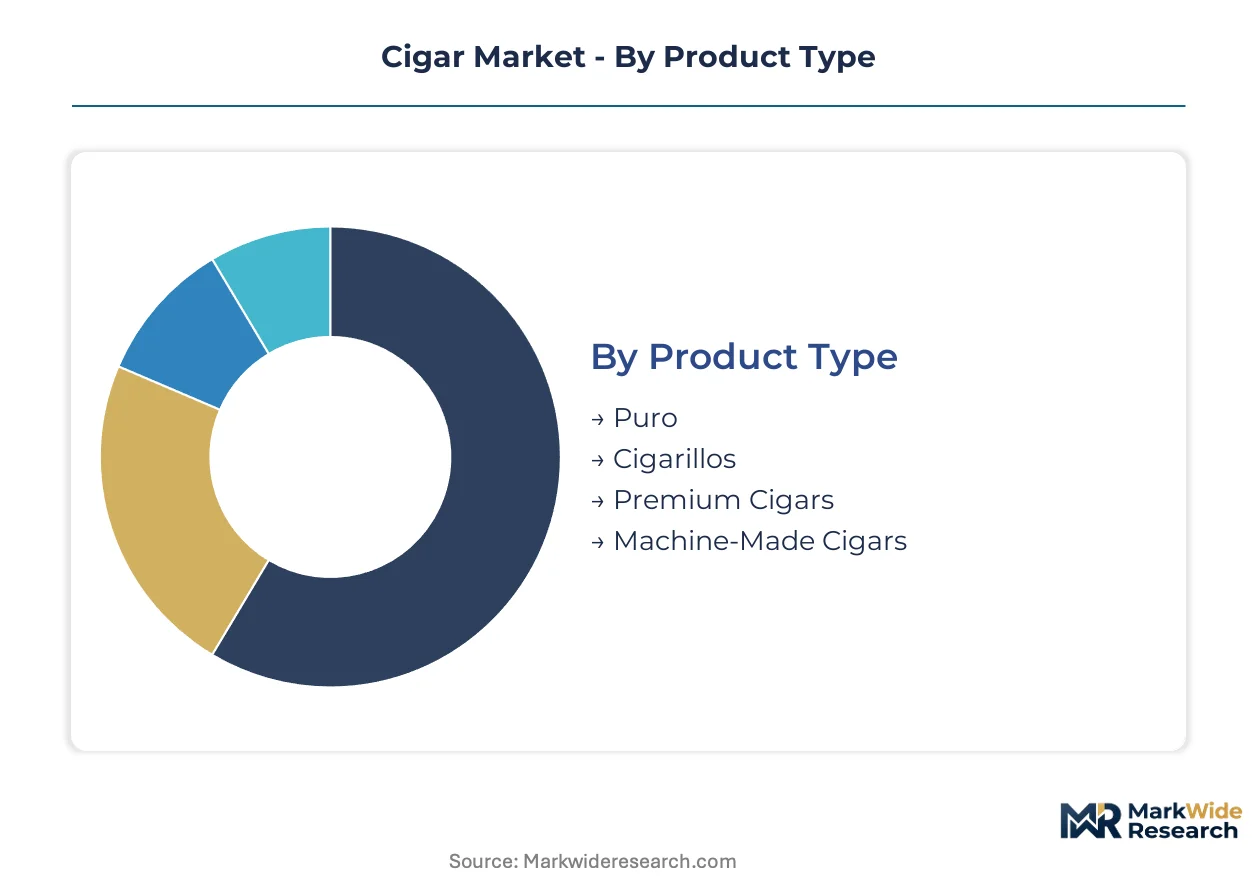
Cigar market segmentation separates volume-driven convenience consumption from artisanal premium rituals, with each category commanding distinct margin structures and channel strategies. Manufacturers align production capabilities against these divides, optimizing fermentation scale and hand-rolling capacity for their target tier.
Product Type:
Volume concentration clusters in machine-made formats, while premium profitability concentrates in hand-rolled puro and traditional cigar constructions.
- Puro:Single-origin tobacco construction from wrapper through filler creates unified terroir expression. Nicaraguan puros command particular attention from connoisseurs seeking alternatives to Cuban supply constraints amid persistent trade restrictions.
- Premium Cigars:Hand-rolled formats with extended fermentation cycles deliver the highest per-unit margins across the product spectrum. Demand concentrates in dedicated tobacconist channels and luxury hospitality venues in Miami, Dubai, and São Paulo where experiential retail commands price premiums.
- Cigarillos:Shorter formats with faster combustion profiles serve frequency-driven consumption occasions. Scandinavian and German markets demonstrate strongest adoption through convenience retail.
- Machine-Made Cigars:Automated production delivers volume scale through gas-station and convenience-store distribution. Scandinavian Tobacco Group dominates this tier through mass-market channel control.
Mature deployment sits with machine-made cigars. Newer deployment is concentrated in premium hand-rolled formats.
Tobacco Origin:
Supply geography determines scarcity positioning and regulatory exposure, with state-controlled Cuban channels diverging from open-market Central American alternatives.
- Nicaraguan:Volcanic soil conditions and established fermentation expertise produce full-bodied leaf profiles. Connoisseur buyers actively seek Nicaraguan supply as Cuban availability faces persistent constraint.
- Cuban:Habanos S.A.'s state monopoly enforces scarcity-driven pricing power across export markets. Parallel market dynamics distort legitimate price signaling due to limited authorized distribution channels.
- Dominican:Connecticut-seed shade wrapper cultivation dominates premium mild-format production. Dominican origins expand fastest among buyers seeking consistent quality without Cuban supply volatility.
- Honduran:Corojo and Criollo varietal cultivation supports medium-to-full bodied blend construction. Honduran leaf serves as filler component in multi-origin premium assemblies.
Traditional prestige attaches to Cuban origin. Fastest expansion is occurring in Nicaraguan and Dominican supply channels.
Package Type:
Packaging format signals consumption occasion and collector intent, from single-unit trial to humidor-scale box acquisitions.
- Boxes:20-25 count cedar constructions with integrated humidification elements serve serious collector storage. High-net-worth buyers in Miami and Dubai demand real-time environmental telemetry integration.
- Single Cigars:Individual unit sales enable trial and occasion-based purchase without commitment. Luxury hotel lounges and airport duty-free channels drive single-unit velocity.
- Bundles:Value-tier bulk packaging without decorative elements reduces per-unit cost for frequent consumers. Bundles concentrate in direct-to-consumer and subscription club distribution.
- Tins:Small-format metal packaging protects cigarillos and short formats from environmental degradation. Tins dominate travel retail and convenience channel placement.
Collector-grade deployment centers on box formats. Trial-driven expansion concentrates in single cigars and subscription-compatible bundles.
Flavor Profile:
Fermentation method and wrapper leaf selection create taste differentiation across natural, processed, and infused constructions.
- Maduro:Extended fermentation of wrapper leaf produces dark coloration and sweet, earthy flavor concentration. Maduro wrappers command premium positioning in connoisseur channels.
- Natural:Unprocessed Connecticut or Ecuadorian shade wrapper maintains mild, creamy flavor profile. Natural formats dominate entry-level premium adoption and gift purchase occasions.
- Sungrown:Sun-cured wrapper cultivation yields fuller body and more pronounced spice notes than shade-grown alternatives. Sungrown expansion correlates with connoisseur preference for intensity.
- Flavored:Infused constructions with added aromatic agents serve occasional smokers and crossover consumers. Flavored formats face regulatory scrutiny under FDA premarket authorization requirements.
Traditional connoisseur preference anchors in natural and maduro profiles. Sungrown formats are gaining share fastest among intensity-seeking segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Central American volcanic soil corridors, while consumption clusters in high-net-worth urban centers across North America, Europe, and the Middle East. Trade restrictions on Cuban supply channels redirect procurement flows toward Nicaraguan and Dominican origins. Regulatory fragmentation across FDA, EU Tobacco Products Directive, and national customs regimes shapes competitive access conditions.
United States
Subscription-based cigar clubs and luxury hospitality programming in Miami drive enthusiast demand growth. FDA Center for Tobacco Products premarket authorization requirements create compliance bottlenecks for new product introductions. Miami's Design District and Brickell corridors anchor experiential retail expansion with dedicated lounge footprints.
Germany
Curated monthly tasting programs with educational content attract Scandinavian and German consumers seeking discovery-driven buying patterns. EU Tobacco Products Directive health warning mandates and cross-border distance sales restrictions constrain direct-to-consumer channels. Hamburg and Berlin concentrate specialist tobacconist networks serving connoisseur segments.
United Arab Emirates
Luxury hotel and resort venues in Dubai expand dedicated cigar lounge programming for high-net-worth visitors. MOHAP tobacco product registration requirements govern import and distribution authorization. Dubai's DIFC and Palm Jumeirah clusters host the most intensive hospitality integration in the Middle East.
Nicaragua
Volcanic soil conditions and established fermentation expertise attract buyer migration from constrained Cuban supply. National customs and export licensing frameworks regulate leaf and finished product outbound flows. Estelí and Jalapa Valley anchor the densest premium hand-rolled production corridors outside Cuba.
Dominican Republic
Connecticut-seed shade wrapper cultivation supports consistent quality for mild-format premium production. Dominican tobacco board oversight maintains origin certification and export documentation standards. Santiago de los Caballeros and La Romana host the largest concentration of fermentation facilities and master roller workshops.
Cigar Market Vendor Landscape
Top-tier vendors anchor state-monopoly and multinational conglomerate positions, while mid-tier specialists and regional fabricators occupy differentiated niches. The competitive structure splits between scarcity-driven Cuban supply control, mass-market volume scale, and premium hand-rolled craftsmanship. Three archetypes dominate: state-controlled origin monopolies, diversified tobacco conglomerates with reduced-risk portfolios, and Central American pure-play fermentation specialists. Consolidation pressure manifests through lobbying investment for regulatory exemption and production diversification toward exempt size specifications.
Among diversified multinational portfolios, Altria Group Inc. and Philip Morris International Inc. occupy positions spanning premium cigar maintenance and adjacent reduced-risk development. Habanos S.A. exemplifies state-controlled scarcity architecture. Scandinavian Tobacco Group A/S represents mass-market channel dominance through convenience retail penetration. These three anchors illustrate the tripartite competitive structure: monopoly-origin pricing power, conglomerate diversification resilience, and volume-tier distribution scale.
| Leading Market Players |
|---|
| Altria Group Inc. |
| Habanos S.A. |
| Scandinavian Tobacco Group A/S |
| Philip Morris International Inc. |
| British American Tobacco PLC |
| Imperial Brands PLC |
| Swisher International Inc. |
| Japan Tobacco Inc. |
| China National Tobacco Corp. |
| Others |
Supply Flow & Price Mechanics
High-net-worth collector concentration in Miami and Dubai anchors scarcity-driven pricing models that reward provenance authentication and controlled-release distribution architectures. Cuban state-monopoly supply constraints amplify parallel market premiums while Nicaraguan and Dominican alternatives reset reference pricing across premium tiers.
Pricing Analysis
Price erosion across machine-made tiers traces to Scandinavian Tobacco Group's mass-market channel dominance and gas-station distribution scale. Three-tier pricing structure across premium hand-rolled, mid-tier bundle, and economy machine-made levels separates connoisseur collectors from frequency-driven convenience buyers. Cost-down pressure on small-batch producers accelerates because climate-driven tobacco leaf yield variations compress margin predictability. Subscription club members demonstrate lowest price sensitivity while convenience-channel machine-made buyers exhibit highest elasticity.
Supply Chain Analysis
Domestic-content mandates in Cuba's state-controlled Habanos S.A. monopoly reshape legitimate export sourcing toward Nicaraguan and Dominican alternatives. Fermentation expertise concentrates in Nicaragua, Dominican Republic, and Honduras, with volcanic soil corridors anchoring premium wrapper cultivation. Finished production draws from Connecticut-seed shade wrapper dependencies and Corojo varietal inputs. Single-source vulnerability runs through Cuban state-channel concentration. Distribution runs through luxury hospitality venues, dedicated tobacconist networks, and convenience retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation monitoring and smart humidor telemetry are displacing passive storage and manual quality verification across collector segments.
For Market Incumbents: Anticipate FDA deeming rule reclassification by diversifying production toward exempt size and weight specifications while intensifying lobbying investment. Secure master roller talent pipelines through apprenticeship programs in Estelí and Santiago de los Caballeros to defend hand-rolled capacity. Backward integration into Nicaraguan volcanic soil wrapper cultivation reduces Cuban supply volatility exposure. For New Entrants and Emerging Players: Curated subscription digital channels offer lowest customer acquisition friction among Scandinavian and German discovery-driven buyers. Target underpenetrated luxury hospitality integration in São Paulo and Dubai where experiential retail commands price premiums. Lead with educational content and pairing guidance to differentiate from legacy brand loyalty. For Investors and Strategic Acquirers: The window for entry favors Central American pure-play fermentation specialists with established torcedore workshops and export licensing frameworks. Long-term viability hinges on regulatory exemption maintenance and scarcity-driven pricing architecture durability. Watch FDA premium cigar classification thresholds as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Humidor Technology Integration | Real-time environmental telemetry from Boveda and SensorPush reduces secondary market condition disputes. |
| Subscription Club Platform Launch | Monthly curated deliveries with pairing notes capture discovery-driven younger demographic segments in Hamburg. |
| Master Roller Apprenticeship Program | Multi-year torcedore training pipelines in Jalapa Valley address talent scarcity constraining premium output. |
| Nicaraguan Puro Production Expansion | Single-origin volcanic soil construction captures buyer migration from constrained Cuban supply channels. |
| Luxury Hospitality Partnership | Dedicated lounge programming in Dubai's DIFC cluster creates experiential retail footprints beyond traditional tobacconists. |
Methodological Framework
Independent corroboration across master roller workshops, luxury hotel procurement directors, and FDA regulatory affairs specialists underwrites the qualitative findings in this study. Primary interviews with fermentation facility managers, subscription club operators, and Scandinavian convenience channel buyers combined with secondary validation from customs export records, MOHAP registration databases, and EU Tobacco Products Directive implementation reports. Bottom-up production capacity estimates and top-down consumption pattern analysis triangulate volume and value outputs.
Comparable-period anchoring to historical fermentation cycle durations and premium cigar inventory aging patterns structured the projection horizon. Segmentation modeling spanned product type, tobacco origin, package format, and flavor profile dimensions across the analysis window. CAGRs derived from trend extrapolation adjusted for regulatory friction coefficients and scarcity-premium decay functions. Forecast inputs incorporated master roller labor availability curves and climate-driven leaf yield variance projections.
The model holds under stable FDA exemption thresholds and continued Cuban supply constraints; deviation in deeming rule reclassification or trade restriction relaxation would shift volume and value trajectories. Forecasts reflect documented assumptions about collector behavior persistence and hospitality integration adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Whey Based Vodka Market
Alcoholic Beverages
Still Wine Market
Alcoholic Beverages
Mexico Tequila Market
Alcoholic Beverages
Gluten Free Alcoholic Drinks Market
Alcoholic Beverages
France Alcohol E-Commerce Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Microbrewery Supplies Market
Alcoholic Beverages
F-Style Jugs Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Cognac Market
Alcoholic Beverages
Port Wine Market
Alcoholic Beverages
Winetainer Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Sake Market