
 Tanzania Spirits Market | 2026-2036
Tanzania Spirits Market Size, Share, and Industry Trends Forecast 2026-2036
Tanzania Spirits Market Intelligence
Dar es Salaam's distillery cluster is pivoting toward higher-proof production lines to serve premium export and domestic accounts. Tanzania Breweries Limited leverages its integrated malt supply chain to sustain cost advantages across East Africa. Diageo competes through brand equity built in Nairobi and Kampala that extends into Tanzanian bars and hotels. East Africa Spirits (T) Limited anchors its position in local sugarcane-based rum and gin, occupying a distinct price tier below multinational labels.
Spirits encompass distilled alcoholic beverages typically exceeding 20% alcohol by volume, produced through fermentation followed by distillation in copper or stainless-steel stills, then aged, filtered, or blended to achieve desired flavor profiles and proof levels. Whiskey and vodka lead product type demand in Tanzania, with whiskey commanding stronger margins among premium buyers while vodka penetrates casual drinking occasions through lower entry prices. Retail stores and supermarkets dominate distribution channel flow, though bars capture higher per-occasion spending from tourists and urban professionals seeking on-premise experiences.
Tanzania Revenue Authority administers excise duties that directly inflate shelf prices and incentivize local production over imports, while the Tanzania Bureau of Standards enforces labeling and alcohol content rules that filter non-compliant products from formal channels. The country's food and drug regulator monitors production hygiene and additive limits, adding compliance costs that favor scaled distillers over informal operators. Stakeholders must track excise rate adjustments and local content enforcement as these policy levers determine competitive viability for imported versus domestically bottled spirits.
Market Dynamics
Tanzania Revenue Authority's excise duty regime is compressing import volumes while channeling investment toward domestic distillation capacity. This fiscal pressure is redrawing competitive boundaries between local bottlers and multinational suppliers.
Growth Catalysts
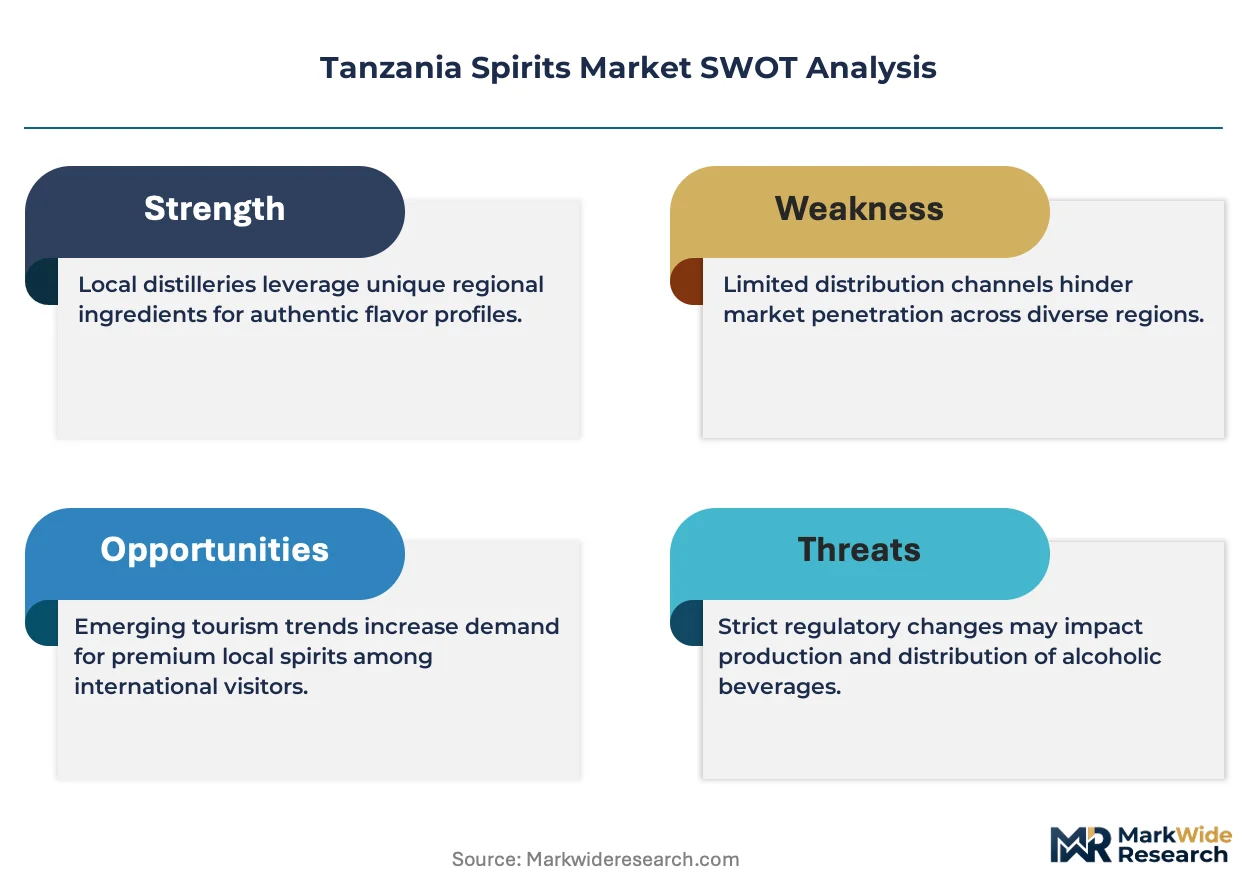
- Excise Tax Differential:Tanzania Revenue Authority's graduated duty structure favors locally bottled spirits over finished imports, accelerating capital deployment into Dar es Salaam production facilities.
- Urban Income Expansion:Metropolitan professionals in Dar es Salaam and Arusha are migrating toward premium whiskey and vodka segments, expanding addressable spend per capita.
- Sugarcane Feedstock Abundance:Northern Tanzania's cane belt provides molasses and juice inputs for rum and gin distillation at cost structures below grain-based alternatives.
Market Restraints
- Import Duty Volatility:Tanzania Revenue Authority's periodic rate adjustments on ethanol and aged spirits create margin unpredictability for distributors holding inventory.
- Glass Bottle Supply Concentration:East Africa's limited container manufacturing forces reliance on Kenyan and South African glassworks, exposing producers to currency and freight shocks.
- Informal Sector Competition:Unregulated chang'aa and gongo distillers in rural zones undercut formal pricing by evading Tanzania Bureau of Standards compliance costs.
Strategic Opportunities
- Arusha Tourism Corridor:Safari lodges and international hotels in northern Tanzania represent underpenetrated on-premise accounts for premium single-malt and craft gin placements.
- Modern Trade Expansion:Supermarket chains in Mwanza and Dodoma are adding dedicated spirits aisles, creating shelf space previously monopolized by traditional liquor stores.
- Regional Export Positioning:East African Community tariff harmonization enables Tanzanian distillers to access Burundi and Rwandan markets with preferential duty treatment.
Industry Challenges
- Skilled Distiller Scarcity:Copper still operation and cask management expertise concentrates among a handful of technicians trained in South Africa or Kenya, constraining quality scaling.
- Compliance Timeline Compression:Tanzania Bureau of Standards certification cycles for new product labels and alcohol content declarations routinely extend six to nine months, delaying launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tanzania Spirits Market |
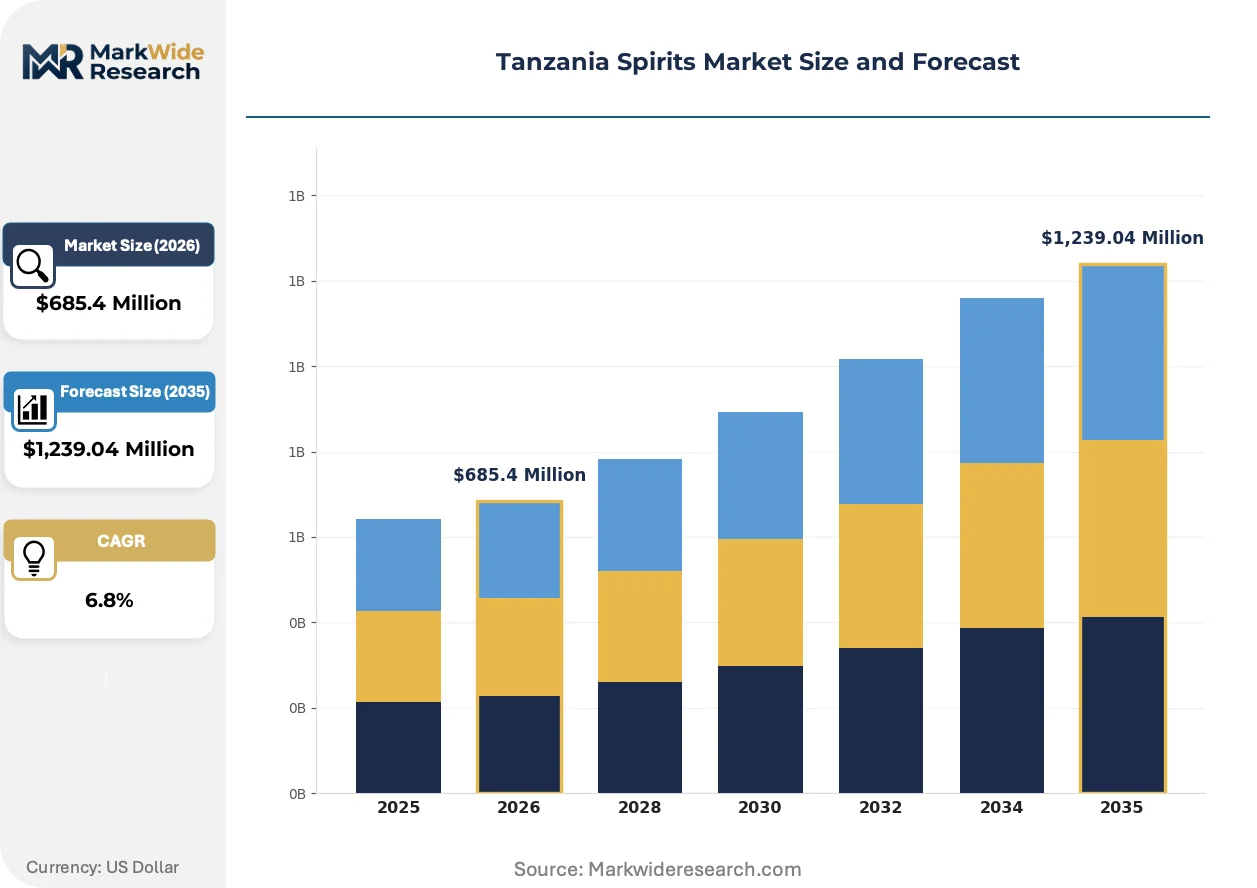
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whiskey, Vodka, Rum, Gin Packaging Type: Bottle, Can, Tetra Pack, Keg Distribution Channel: Retail Stores, Bars, Online, Supermarkets Customer Type: Adult Consumers, Premium Buyers, Casual Drinkers, Tourists |
| Companies Covered | Tanzania Breweries Limited, East Africa Spirits (T) Limited, Tanzania Distilleries Limited, Pernod Ricard, Diageo, Distell, Edward Snell & Company, La Martiniquaise, William Grant & Sons, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tanzania Spirits Market Strategic Shifts & Innovations
Dar es Salaam's distillery cluster is adopting precision fermentation controls and automated blending systems that compress batch-to-batch variation. These capital investments are narrowing the quality gap between local output and imported premium labels.
Continuous column still technology is consolidating production economics across Tanzania's mid-scale distillers. Kioo Distillers and smaller competitors in the Tanga corridor are retrofitting pot stills with continuous systems to raise throughput without proportional labor expansion. The shift is compressing unit costs for neutral spirits used in vodka and gin blending, enabling price competition with Kenyan and Ugandan imports.
Tanzania Revenue Authority's digital tax stamp mandate is reshaping packaging line investments. The requirement for excise-tracked labels on every bottle is forcing informal operators toward formal registration or exit. Legitimate producers are responding by integrating track-and-trace hardware directly into filling lines, converting compliance burden into supply chain visibility.
Urban buyers in Dar es Salaam and Mwanza are fragmenting purchase occasions between on-premise experiences and curated home consumption. Bars are responding with single-serve premium pours and tasting flights, while retailers are expanding chilled ready-to-drink sections. The split is most visible among professionals aged twenty-five to forty who maintain distinct budgets for weekend hospitality and weekday home inventory.
Tanzania Spirits Market Segmentation
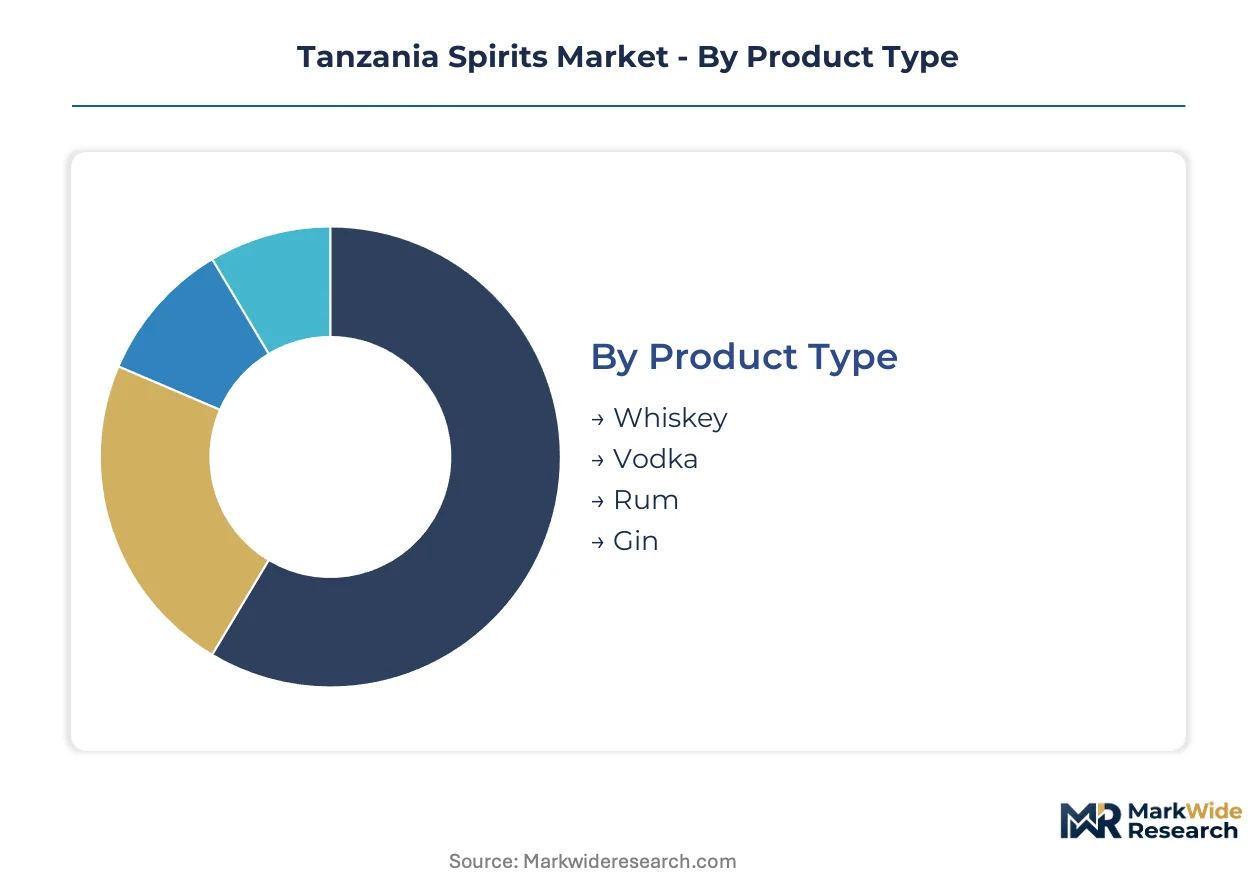
Spirits segmentation in Tanzania reflects divergent purchasing power between urban professionals and rural consumers, with product mix and channel strategy varying sharply across income tiers. Distillers calibrate proof levels, packaging formats, and pricing bands to capture specific consumption occasions from safari tourism to household celebrations.
Product Type:
Standardization dominates grain-based categories while sugarcane-derived spirits allow greater localization of flavor profiles and raw material sourcing.
- Whiskey:Aged grain spirits typically matured in oak casks, with Tanzanian distillers importing aged stock for blending or local finishing. Dar es Salaam's premium buyers drive demand for imported single-malts and locally blended equivalents, though excise duties inflate landed costs.
- Vodka:Neutral spirits filtered through activated carbon or charcoal to achieve clarity and minimal congeners. Metropolitan retail channels in Mwanza and Dodoma absorb the highest volumes, with price-sensitive consumers favoring domestic column-still production over imported labels.
- Rum:Molasses or fresh cane juice fermentation distilled into light or dark variants. Northern Tanzania's cane belt supplies feedstock to distillers in Tanga and Arusha corridors.
- Gin:Juniper-forward neutral spirit with botanical infusions including coriander, angelica, and local citrus. Small-batch producers experiment with indigenous botanicals for tourism-channel differentiation.
Most installed capacity flows through vodka and rum. Expansion is steepest in whiskey as urban incomes climb.
Packaging Type:
Cost per unit and breakage risk determine format selection, with glass dependency exposing all categories to Kenyan and South African supply volatility.
- Bottle:Glass containers ranging from 50ml miniature to 750ml standard and 1-liter value formats. Supermarkets and dedicated liquor stores in Dar es Salaam command the majority of bottle flow, though glass import costs compress margins.
- Can:Aluminum vessels for ready-to-drink spirits and mixers targeting outdoor consumption. Arusha's safari lodges and beach venues in Zanzibar absorb can volumes for poolside and excursion service.
- Tetra Pack:Aseptic cartons for low-proof traditional beverages and informal sector products. Rural distribution favors this format for transport durability.
- Keg:Stainless steel or disposable plastic vessels for on-premise dispensing. Bars in Oyster Bay and Masaki neighborhoods deploy kegs for high-volume vodka and rum service.
Glass bottles retain the dominant share of spirits value. Cans are gaining share fastest in tourism-corridor on-premise accounts.
Distribution Channel:
Channel selection directly determines margin structure, with modern trade extracting listing fees while traditional retail offers faster inventory turns.
- Retail Stores:Dedicated liquor shops and kiosks serving neighborhood catchments with personalized credit relationships. These outlets dominate volume in secondary cities and peri-urban zones.
- Bars:On-premise establishments from roadside chang'aa houses to hotel cocktail lounges. Dar es Salaam's Slipway and Kariakoo bar clusters capture premium per-occasion spending.
- Online:E-commerce platforms and delivery apps serving urban professionals with curated selections. Regulatory ambiguity around alcohol e-commerce constrains scaling.
- Supermarkets:Chain retailers including dedicated spirits aisles with chilled sections and promotional displays. Modern trade expansion in Mwanza and Dodoma is displacing traditional liquor store dominance.
Traditional retail stores still handle the greatest volume. Supermarket spirits aisles are expanding most quickly as modern trade penetrates secondary cities.
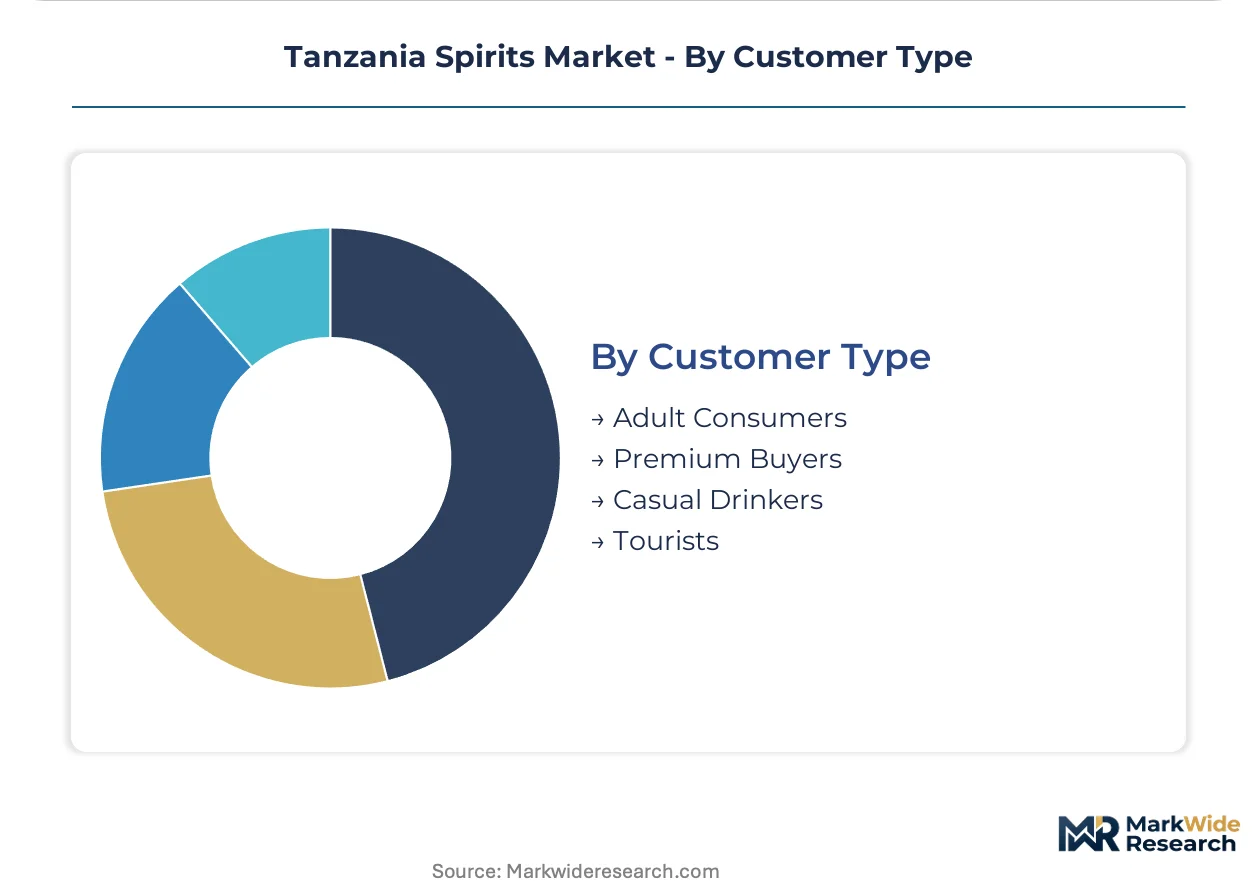
Customer Type:
Purchasing behavior fragments sharply between daily consumption budgets and occasion-based premium outlays.
- Adult Consumers:Core legal-age drinkers spanning all income levels and consumption frequencies. This broad category concentrates in household purchasing for at-home consumption across rural and urban Tanzania.
- Premium Buyers:High-income professionals and business owners prioritizing brand prestige and aged statements. Dar es Salaam's banking and telecom sectors generate concentrated demand for single-malts and super-premium vodka.
- Casual Drinkers:Occasional consumers purchasing for social gatherings without strong brand loyalty. Price promotions and local rum or gin offerings capture this segment.
- Tourists:International visitors seeking familiar global brands or local craft experiences. Safari circuits through Arusha and beach resorts in Zanzibar drive on-premise premium consumption.
Adult consumers represent the largest addressable base. Premium buyers are climbing fastest as Dar es Salaam's professional class expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting distillation investment toward jurisdictions where excise compliance costs and feedstock access create production advantages over finished-goods importation.
Dar es Salaam
Metropolitan professionals drive premium whiskey and vodka consumption as banking and telecom sectors expand. Tanzania Revenue Authority's graduated excise structure favors local bottling over finished imports, compressing landed-cost premiums. The Kurasini industrial zone hosts retrofitting of continuous column stills that raise neutral-spirit throughput for price-competitive vodka output.
Arusha Corridor
Safari tourism generates concentrated on-premise demand for single-malt and craft gin placements at international lodges. Tanzania Bureau of Standards labeling requirements filter non-compliant products from formal hospitality channels. Distillers in the Tanga corridor leverage northern cane-belt molasses access for rum production at grain-substitute cost structures.
Mwanza
Lake Zone commercial activity supports retail-spirits expansion as supermarket chains displace traditional liquor-store dominance. Modern trade listing fees reshape margin structures for domestic bottlers seeking shelf presence. Regional distribution hubs serve Burundian and Rwandan markets under East African Community preferential tariff treatment.
Zanzibar
Beach-resort tourism drives ready-to-drink and canned-spirits consumption for poolside and excursion service occasions. Import-duty volatility on aged ethanol stocks creates inventory-margin unpredictability for hospitality distributors. Stone Town's hospitality cluster sources premium placements through Nairobi and Kampala supply relationships.
Tanzania Spirits Market Key Industry Players
Dar es Salaam producers anchor the domestic-bottling tier; Nairobi and Johannesburg specialists hold premium-import positioning through brand equity extension. Market structure exhibits moderate consolidation around integrated malt-supply operators and sugarcane-feedstock distillers, with multinational labels occupying prestige price bands. Two strategic archetypes dominate: excise-optimized local bottlers leveraging feedstock proximity, and brand-equity importers routing through regional hubs. Competitive moves concentrate on capacity retrofitting for continuous still technology and modern-trade shelf-space capture.
Among Tanzania-based operators, Tanzania Breweries Limited exemplifies integrated supply-chain positioning through captive malt sourcing, while East Africa Spirits (T) Limited occupies the sugarcane-derived rum and gin tier below multinational price bands. Diageo represents the brand-equity archetype extending Nairobi-built recognition into Tanzanian bars and hotels.
| Leading Market Players |
|---|
| Tanzania Breweries Limited |
| East Africa Spirits (T) Limited |
| Tanzania Distilleries Limited |
| Pernod Ricard |
| Diageo |
| Distell |
| Edward Snell & Company |
| La Martiniquaise |
| William Grant & Sons |
| Others |
Cost & Logistics Intelligence
Captive molasses sourcing from northern Tanzania's cane belt anchors both supply security and margin control for domestic distillers competing against landed imports. This backward integration into feedstock production insulates local bottlers from currency-driven ethanol cost spikes while compressing unit economics below grain-based alternatives.
Pricing Analysis
Distributor margin layers absorb the steepest compression as Tanzania Revenue Authority's excise stamp mandates add compliance hardware costs. Three-tier pricing structure across premium, standard, and economy levels separates multinational single-malts from local blended equivalents and informal chang'aa substitutes. Price differentiation hinges on excise-paid legitimacy and aged-stock provenance. Pricing pressure stems from modern trade listing fees in expanding supermarket channels. Casual drinkers in peri-urban zones exhibit highest price sensitivity; premium buyers in Dar es Salaam's banking sector show lowest elasticity.
Supply Chain Analysis
Glass bottle supply rests on Kenyan and South African manufacturing concentration, exposing Tanzanian distillers to freight cost volatility and currency fluctuation. Raw material dependencies center on molasses from Kilimanjaro corridor cane estates, imported aged whiskey stock for blending, and activated carbon for vodka filtration. Supply chain risk concentrates in single-source container vulnerability from East African Glassworks. Distribution runs through traditional retail stores in secondary cities, with modern trade expansion in Mwanza and Dodoma reshaping downstream flow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tanzania Spirits Market functions as a geographic-arbitrage play where excise duty differentials between local bottling and finished imports create sustainable margin wedges for domestic producers. Tanzania Revenue Authority's graduated duty structure rewards capital deployment into Dar es Salaam production facilities while penalizing landed premium stock.
For Market Incumbents: Extend continuous still retrofitting across Tanga corridor facilities to raise neutral spirit throughput without proportional labor expansion. Defend against Kenyan and Ugandan import competition by deepening captive molasses supply contracts with northern cane cooperatives. Prioritize Tanzania Bureau of Standards certification pipeline acceleration to compress six-to-nine month label approval timelines that delay product launches.
For New Entrants and Emerging Players: Begin with craft gin positioning in Arusha's safari tourism corridor, where international lodges seek differentiated local botanical offerings absent from multinational portfolios. Target underpenetrated on-premise accounts at beach resorts in Zanzibar for ready-to-drink and canned spirits formats. Build initial presence through direct hospitality relationships before pursuing modern trade shelf space.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale sugarcane-feedstock distillers because excise compliance costs and digital tax stamp mandates are forcing informal operators toward formal registration or exit. Five-to-ten year viability hinges on feedstock proximity and regulatory adaptation capacity. Watch Tanzania Revenue Authority excise rate adjustments as the primary inflection signal for import versus domestic bottling competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Still Retrofitting | Kioo Distillers and Tanga corridor competitors compress unit costs for vodka and gin blending. |
| Digital Tax Stamp Integration | Legitimate producers convert Tanzania Revenue Authority compliance burden into supply chain visibility. |
| Modern Trade Shelf Expansion | Supermarket chains in Mwanza and Dodoma displace traditional liquor store dominance. |
| Arusha Tourism Corridor Placement | Safari lodges and international hotels absorb premium single-malt and craft gin volumes. |
| Regional Export Positioning | East African Community tariff harmonization enables Burundi and Rwanda market access. |
Research Approach
Direct dialogue with distillery operations managers, Tanzania Revenue Authority excise compliance officers, modern trade category buyers, and hospitality procurement directors grounded qualitative findings in operational reality. Secondary validation drew from Tanzania Bureau of Standards certification records, East African Community customs documentation, and excise duty rate gazettes. Bottom-up and top-down triangulation cross-checked production capacity estimates against channel inventory flows and consumer spending patterns.
Bottom-up modeling built from individual distillery throughput assumptions, feedstock cost structures, and channel margin stacks. Top-down validation anchored against national excise revenue collections and regional trade flows. Segmentation dimensions spanned product type, packaging format, distribution channel, and customer archetype across the projection horizon. CAGRs derived from weighted capacity expansion schedules and income elasticity assumptions for premium versus standard tiers. Forecast inputs incorporated urbanization trajectories for Dar es Salaam and Arusha corridors alongside tourism arrival patterns.
Caveats apply where Tanzania Revenue Authority excise rate adjustments, Kenya-South Africa glass supply disruptions, or informal sector enforcement intensity could materially shift the outlook. Forecasts reflect documented assumptions about regulatory stability and feedstock availability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
Beer Filter System Market
Alcoholic Beverages
Port Wine Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Kegs Market
Alcoholic Beverages
Wine Filling Machine Market
Alcoholic Beverages
Crystal Malt Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
South Korea Tequila Market
Alcoholic Beverages
GCC Beer Market
Alcoholic Beverages
China Tequila Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
East Africa Alcoholic Beverages Market
Alcoholic Beverages
Tequila Market