
 Anti-Counterfeiting Packaging Market | 2026-2036
Anti-Counterfeiting Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Counterfeiting Packaging Market Intelligence
The transition from physical holograms to digital watermarks and QR codes embedded with unique identifiers is shifting the cost structure of brand protection. This change favors technology-led providers over traditional printers. SICPA Holding SA specializes in advanced security inks for currency and products. Avery Dennison Corporation leverages its extensive expertise in RFID and intelligent label manufacturing to serve multiple end-markets.
Anti-counterfeiting packaging incorporates overt, covert, or forensic features into a product's packaging to prevent imitation and verify authenticity. These features can include micro-text printing smaller than 70 microns or DNA-based markers, which help secure the supply chain. Within applications, the pharmaceuticals segment commands the highest value due to stringent regulatory requirements. RFID tags and nanotechnology-based solutions offer dynamic tracking and difficult-to-replicate security layers.
Regulatory frameworks are a primary market catalyst, with the US FDA's Drug Supply Chain Security Act and the EU's Falsified Medicines Directive setting serialization standards. In China, the NMPA enforces similar track-and-trace requirements for pharmaceuticals, compelling manufacturers to adopt compliant packaging. Brand owners must now decide between investing in single-layer overt features or multi-layered covert technologies to balance cost against security effectiveness.
Market Dynamics
Regulatory mandates for supply chain integrity represent the central force shaping the anti-counterfeiting packaging market. Requirements for unit-level serialization, particularly in pharmaceuticals, are compelling a structural shift from passive, physical security features toward active, data-rich digital solutions.
Growth Catalysts
- Regulatory Mandates:Strict track-and-trace legislation, including the US FDA's Drug Supply Chain Security Act and the EU's Falsified Medicines Directive, obligates manufacturers in the pharmaceutical sector to adopt serialization and verifiable packaging technologies.
- Technology Advancement:The increasing sophistication and falling cost of technologies like RFID tags, nanotechnology-based markers, and digital watermarks provide more secure and scalable options for brand protection beyond traditional holograms.
- End-Use Sector Risks:High-value industries such as pharmaceuticals, electronics, and luxury goods face significant financial and reputational damage from counterfeits, driving investment in multi-layered security packaging to protect assets and consumer safety.
Market Restraints
- Implementation Costs:The high initial capital expenditure for advanced track-and-trace systems, including software, serialization-ready hardware, and employee training, presents a significant barrier for small and medium-sized enterprises.
- Integration Complexity:Integrating new anti-counterfeiting technologies with existing enterprise resource planning (ERP) systems and diverse packaging lines across a global supply chain creates significant technical and operational hurdles.
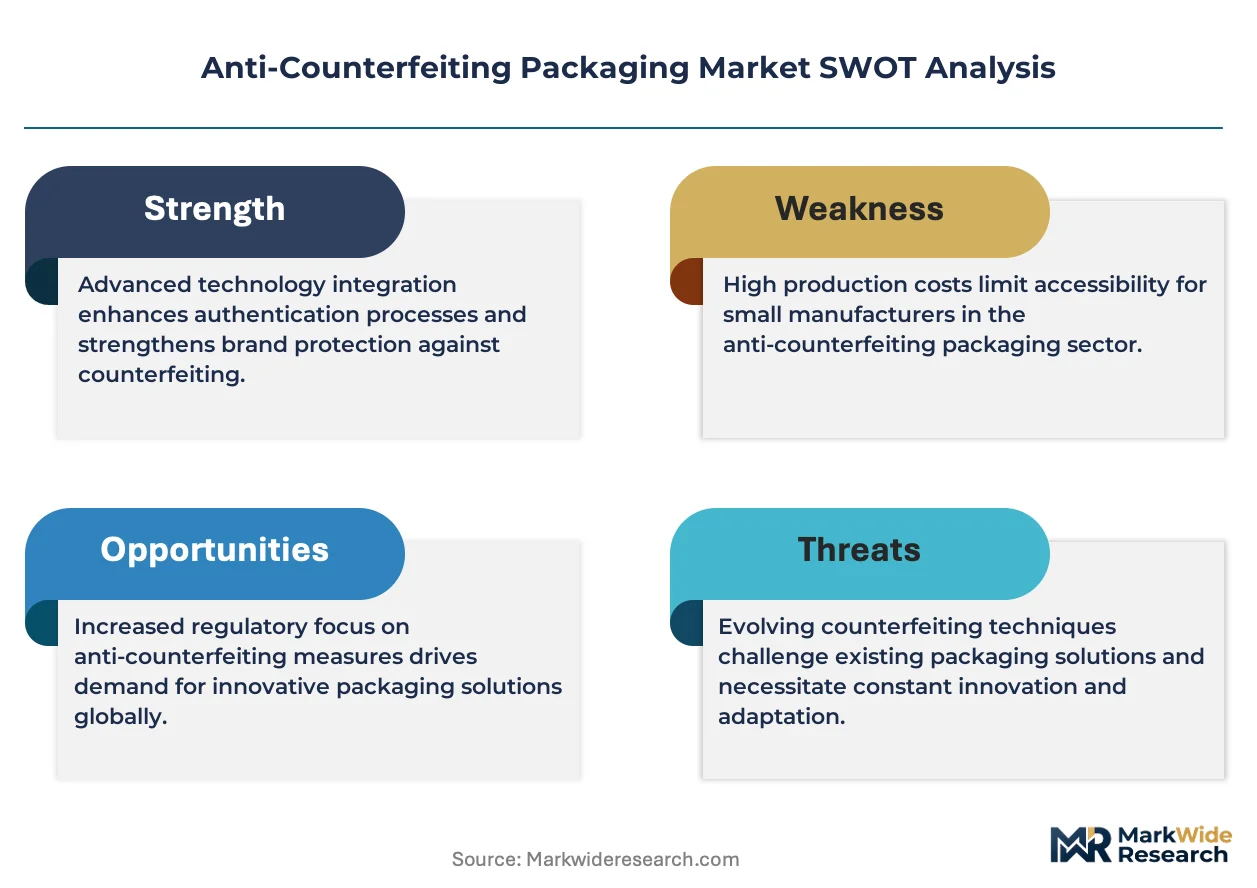
- Counterfeiter Adaptability:The continuous evolution of counterfeiting techniques means that even advanced overt features can eventually be replicated, requiring brand owners to constantly update their security strategies and technologies.
Strategic Opportunities
- Food and Beverage Sector:Applying serialization and authentication technologies to high-value food and beverage products, such as premium spirits and infant formula, offers a significant growth area, especially in markets with rising consumer safety concerns.
- Technology Convergence:Combining digital identifiers like QR codes with blockchain technology creates an opportunity to offer immutable, decentralized ledgers for supply chain verification, enhancing trust and transparency for consumers and regulators.
- Emerging Economies:Expanding into the electronics and automotive aftermarket sectors in developing nations, where counterfeit components are prevalent, provides a substantial opportunity for providers of cost-effective authentication solutions.
Industry Challenges
- Data Management Burden:The massive volume of serialization data generated by track-and-trace systems requires significant IT infrastructure for storage, security, and analytics, creating a challenge for companies without dedicated data management expertise.
- Lack of Global Standardization:Divergent serialization and data-sharing requirements across different countries and regulatory bodies, such as the NMPA in China and the FDA in the US, complicate compliance for multinational corporations.
- Interoperability Issues:Ensuring seamless interoperability between the various hardware and software components from different vendors within a single track-and-trace ecosystem remains a persistent operational challenge for brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Counterfeiting Packaging Market |
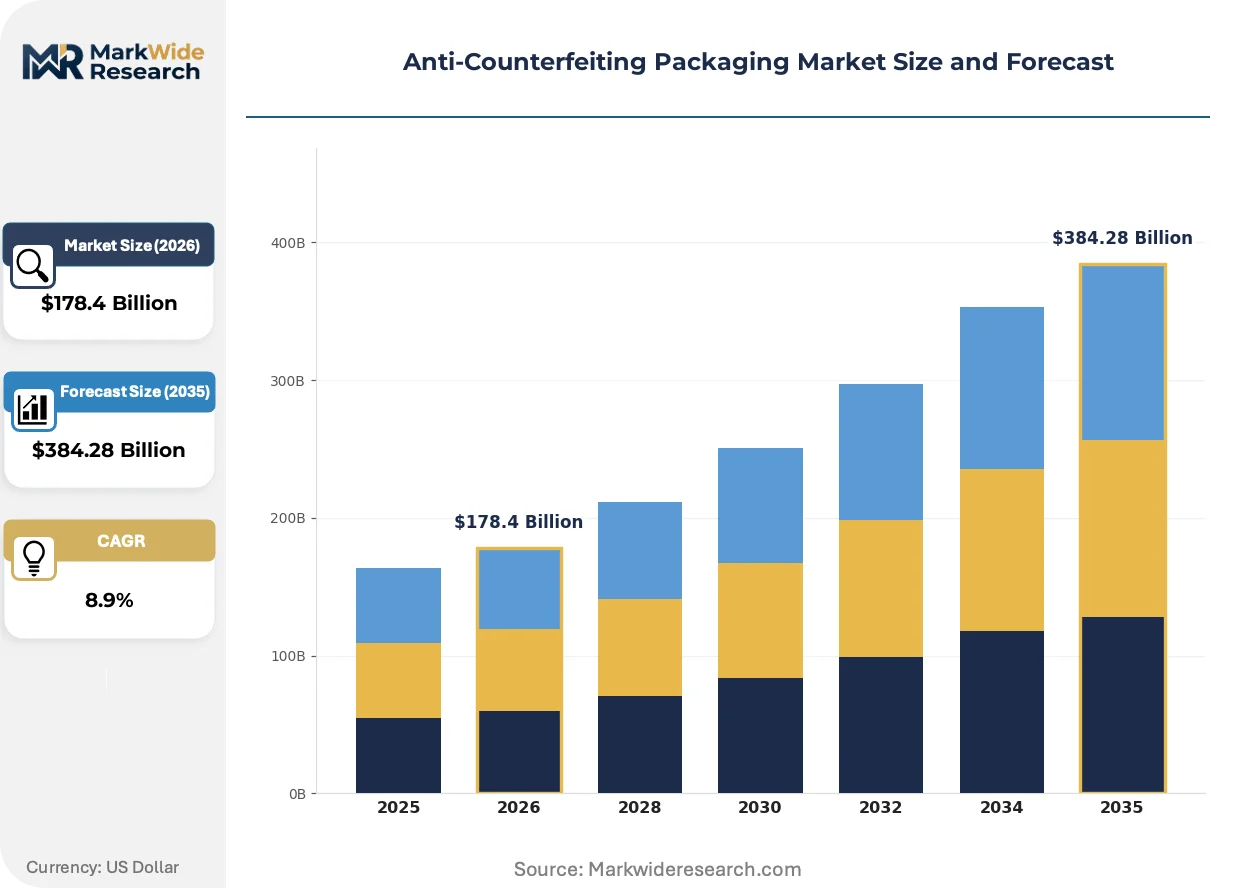
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $384.28 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holograms, Security Labels, RFID Tags, Barcodes, Tamper Evident Seals Technology: UV Printing, Micro-Text, Watermarking, Nanotechnology, Biometric Authentication Application: Pharmaceuticals, Electronics, Luxury Goods, Food & Beverages, Cosmetics End User: Manufacturers, Distributors, Retailers, Brand Owners, Logistics Providers |
| Companies Covered | DuPont, SICPA Holding SA, Avery Dennison Corporation, Applied DNA Sciences Inc., AlpVision SA, CCL Industries Inc., Zebra Technologies Corporation, Authentix Inc., 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Counterfeiting Packaging Market Strategic Shifts & Innovations
The market's evolution is defined by the fusion of physical packaging with digital identity and connectivity. This convergence moves packaging from a passive container to an active node in the supply chain, generating data that informs security, logistics, and consumer engagement strategies.
Intelligent labels incorporating RFID and NFC technologies are a primary innovation. These technologies enable automated, non-line-of-sight data capture, which is superior to barcode scanning for high-volume logistics and inventory management. The pharmaceutical and electronics industries adopt these for real-time tracking and authentication. The shift from passive barcodes to active radio-frequency identification is rewriting the economics of supply chain visibility and security.
China's NMPA regulations for pharmaceutical traceability are creating a distinct technology and data ecosystem. The mandate requires manufacturers to upload serialization data to a government-supervised platform, driving specific technology choices. This affects the entire pharmaceutical supply chain within China, forcing global companies to adapt their packaging and data systems specifically for that market's compliance demands.
Consumer behavior is shifting toward active product verification via smartphones. This change disrupts the traditional B2B focus of brand protection, creating demand for security features that also serve as a direct-to-consumer communication channel. This trend is most visible in wine and spirits, where a QR code scan can both confirm authenticity and provide the consumer with product history, tasting notes, or loyalty rewards.
Anti-Counterfeiting Packaging Market Segmentation
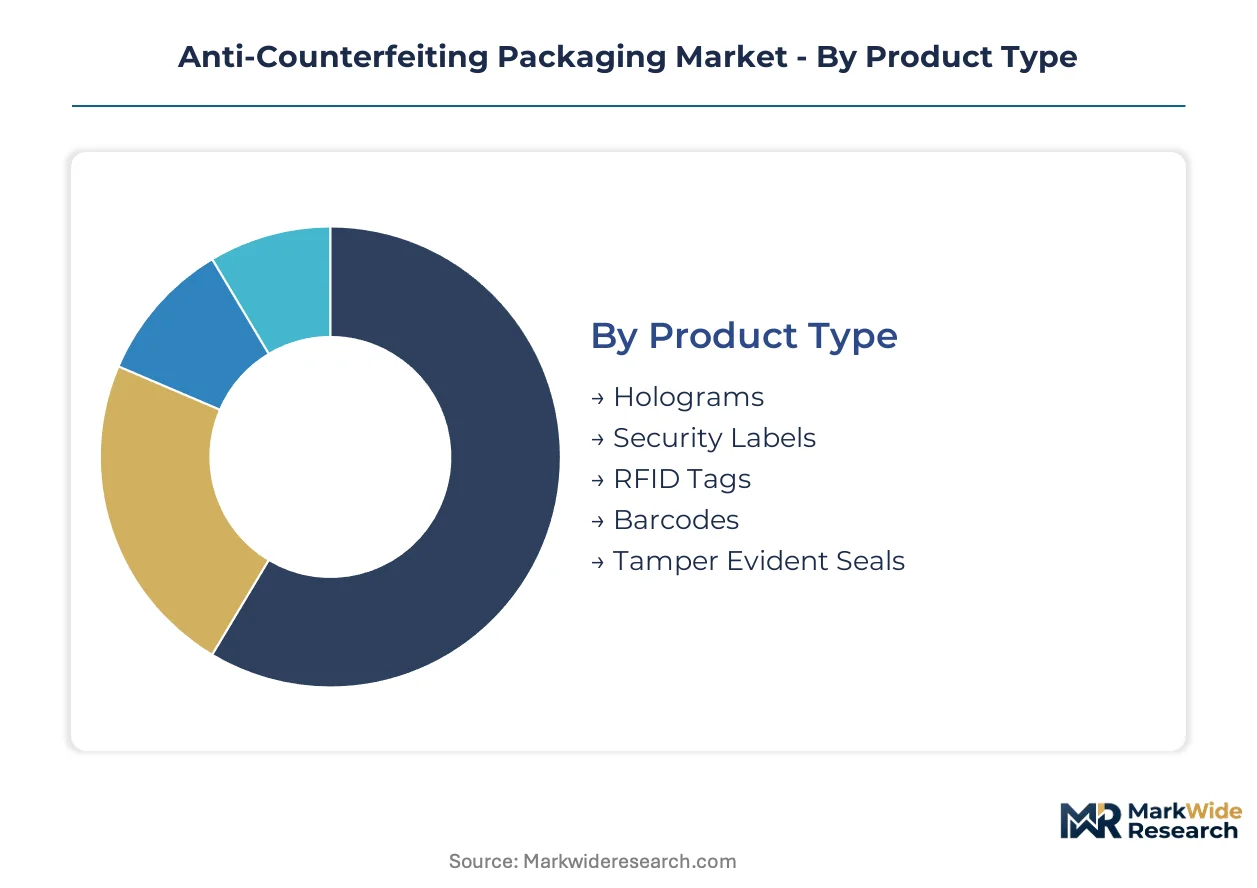
The anti-counterfeiting packaging market segmentation highlights the diverse strategies and technological solutions deployed to protect products across various industries. Understanding these segments is crucial for brand owners to align their security investments with specific threat landscapes and regulatory demands. The market's evolution reflects a continuous effort to outmaneuver counterfeiters and safeguard supply chain integrity.
Product Type:
The anti-counterfeiting packaging market observes a continuous upgrade cycle as physical features give way to more dynamic, digitally-enabled solutions for brand protection.
- RFID Tags:These intelligent labels incorporate microchips and antennas for wireless data transmission, enabling automated, non-line-of-sight tracking and authentication. Demand concentrates in pharmaceutical supply chains due to strict serialization mandates from the US FDA and EU FMD.
- Security Labels:These adhesive features integrate overt and covert elements like holograms, void patterns, or specialized inks directly onto packaging surfaces. Electronics manufacturers frequently adopt security labels to verify product authenticity and prevent warranty fraud.
- Holograms:Optical security devices create 3D images that are difficult to replicate, providing immediate visual authentication for consumers.
- Barcodes:Standardized data carriers like 1D or 2D codes link physical products to digital information, primarily used for inventory and basic track-and-trace.
- Tamper Evident Seals:Physical seals or bands that visibly break or change upon unauthorized opening, ensuring product integrity for consumers.
Volume placements concentrate in Barcodes; the faster expansion belongs to RFID Tags.
Technology:
Advanced anti-counterfeiting technologies offer varying levels of security and integration, influencing their adoption based on brand risk profiles and cost considerations.
- Nanotechnology:This involves embedding microscopic markers or materials into packaging or products, creating virtually impossible-to-replicate security layers. Pharmaceuticals and luxury goods deploy nanotechnology for high-security authentication and supply chain integrity.
- Micro-Text:Printing text smaller than 70 microns, often invisible to the naked eye, provides a covert security feature requiring magnification for verification. Electronics components utilize micro-text to prevent counterfeiting of sensitive parts.
- UV Printing:Inks visible only under ultraviolet light are used to print covert security features, offering a hidden layer of authentication.
- Watermarking:Digital watermarks embed invisible data within images or patterns on packaging, verifiable through specialized scanning devices.
- Biometric Authentication:Incorporating unique biological identifiers, like fingerprints, for high-security access control or product verification, particularly in high-value assets.
The market for UV Printing remains foundational, while Nanotechnology exhibits the steepest expansion trajectory.
Application:
The application of anti-counterfeiting packaging varies significantly across industries, driven by regulatory pressures, product value, and consumer safety concerns.
- Pharmaceuticals:This segment demands robust track-and-trace solutions for unit-level serialization to combat falsified medicines and ensure patient safety. Regulatory mandates from the US FDA and China's NMPA drive significant investment in advanced packaging.
- Electronics:High-value electronic components and consumer devices require sophisticated authentication to protect against intellectual property theft and grey market diversion. Manufacturers adopt multi-layered security features to safeguard brand reputation.
- Luxury Goods:High-end fashion, watches, and jewelry leverage anti-counterfeiting features to preserve brand exclusivity and authenticate product origin for discerning consumers.
- Food & Beverages:Authentication technologies protect against product adulteration and ensure food safety, particularly for premium spirits, infant formula, and specialty foods.
- Cosmetics:Brand owners in the cosmetics industry use anti-counterfeiting packaging to combat imitation products that can pose health risks and damage brand image.
Pharmaceuticals represents the largest end-use segment, with Food & Beverages gaining share fastest.
End User:
Different end-users in the supply chain adopt anti-counterfeiting packaging for distinct purposes, ranging from production integrity to consumer verification.
- Brand Owners:Companies that own the product intellectual property implement anti-counterfeiting measures to protect their reputation, revenue, and consumer trust. They often dictate the type and level of security features integrated into packaging.
- Manufacturers:These entities produce the goods and integrate anti-counterfeiting features into the packaging during the production process. They must comply with brand owner specifications and regulatory requirements.
- Distributors:Wholesalers and logistics companies handle products post-manufacturing, requiring authentication solutions to verify product legitimacy within the supply chain.
- Retailers:Point-of-sale verification systems and consumer-facing authentication tools help retailers ensure they sell genuine products and prevent return fraud.
- Logistics Providers:Companies managing product movement utilize track-and-trace technologies to monitor goods, prevent diversion, and ensure secure transit.
The primary purchasing influence resides with Brand Owners, while Logistics Providers are increasingly adopting these solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for anti-counterfeiting packaging solutions is concentrating in key manufacturing and consumer markets globally. Pharmaceutical and electronics industries particularly drive this need due to high product value and stringent regulatory requirements. This focus on securing supply chains against falsified goods shapes regional investment patterns.
China
Demand for anti-counterfeiting packaging in China is accelerating due to its vast pharmaceutical and electronics manufacturing base. The NMPA enforces strict track-and-trace requirements, compelling manufacturers to adopt compliant packaging solutions. Major pharmaceutical and electronics hubs like the Yangtze River Delta are seeing significant investment in serialization technologies.
United States
The United States market for anti-counterfeiting packaging is propelled by the pharmaceutical sector's need for secure supply chains. The US FDA's Drug Supply Chain Security Act mandates unit-level serialization for drug products. Manufacturing clusters in states like New Jersey and California are implementing advanced RFID and digital watermark solutions.
Germany
Germany's anti-counterfeiting packaging market benefits from its strong pharmaceutical and luxury goods industries. European Falsified Medicines Directive (FMD) compliance drives widespread adoption of track-and-trace technologies across the nation. Pharmaceutical production centers in Bavaria and North Rhine-Westphalia are integrating sophisticated security features into their packaging lines.
India
India exhibits a growing demand for anti-counterfeiting packaging, particularly within its expanding pharmaceutical and food & beverage sectors. The country's drug regulatory body, CDSCO, emphasizes product authenticity, encouraging serialization efforts. Pharmaceutical clusters in Maharashtra and Telangana are actively deploying advanced authentication technologies.
Japan
Japanese industries are adopting anti-counterfeiting packaging to protect high-value electronics and luxury goods from imitation. METI initiatives support innovation in supply chain security, promoting the use of advanced authentication methods. Tokyo and Osaka's manufacturing zones are focusing on intelligent labels and nanotechnology-based markers for product integrity.
Anti-Counterfeiting Packaging Market Key Industry Players
Technology advancement dominates the current landscape, reshaping competitive positioning across the anti-counterfeiting packaging market. The market exhibits a tiered structure, with established players offering traditional solutions and agile technology providers focusing on digital innovations. Archetypes include specialized security ink providers, intelligent label manufacturers, and digital solution integrators. Strategic partnerships for technology integration and continuous portfolio diversification are prevalent competitive moves among these diverse entities.
Within the specialized security solutions segment, SICPA Holding SA, a Swiss-based company, exemplifies expertise in advanced security inks for currency and products. Avery Dennison Corporation, a US-based entity, represents a leader in RFID and intelligent label manufacturing, serving multiple end-markets with its extensive expertise. Applied DNA Sciences Inc., another US-based firm, occupies a position among providers of highly covert, difficult-to-replicate DNA-based markers for product authentication. These firms anchor distinct facets of the market's technological evolution, from physical security features to advanced digital and forensic authentication methods.
| Leading Market Players |
|---|
| DuPont |
| SICPA Holding SA |
| Avery Dennison Corporation |
| Applied DNA Sciences Inc. |
| AlpVision SA |
| CCL Industries Inc. |
| Zebra Technologies Corporation |
| Authentix Inc. |
| 3M Company |
Cost & Logistics Intelligence
Pharmaceutical manufacturers, driven by strict regulatory mandates, anchor significant demand for anti-counterfeiting packaging, influencing a pricing model that often blends project-based customization with transactional per-unit costs for standardized components.
Pricing Analysis
The anti-counterfeiting packaging market exhibits a volume-versus-margin split, where high-volume basic solutions command lower margins while specialized, low-volume features yield higher profitability. Pricing structures often adopt a hybrid model, combining project-based fees for bespoke security integrations with per-unit transactional costs for standard items like RFID tags. Price differentiation stems from the customization level of forensic features, the need for specific regulatory certification (e.g., FDA, NMPA compliance), and the overall volume scale. Pricing softness emerges from intense competition among providers for large-volume, less complex orders. Small and medium-sized enterprises (SMEs) exhibit the highest price sensitivity, often opting for overt, single-layer solutions due to budget constraints.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the anti-counterfeiting packaging supply chain, facilitating localized service and faster deployment. Geographic supply concentration for key components resides in China for electronics and labels, Germany for specialized machinery, and the United States for advanced software solutions. The industry relies on specialized inks, microchips for RFID tags, and high-performance adhesive materials. Regulatory divergence across different countries, such as varying serialization standards, poses a structural supply chain risk. Distribution typically runs through direct sales teams for complex integrations and through a network of specialized packaging integrators for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-counterfeiting packaging market is undergoing a technology-transition phase, with digital watermarks and RFID tags rapidly displacing legacy physical holograms. This shift requires strategic adjustments across all stakeholder groups.
For Market Incumbents:Hedge against the commoditization of overt security features by investing heavily in advanced digital and forensic technologies. Diversify product portfolios to include software-as-a-service (SaaS) platforms for data management and analytics, addressing the increasing data management burden. Acquire niche technology providers specializing in nanotechnology or blockchain-based authentication to counter emerging entrant archetypes. Focus R&D on developing interoperable solutions that simplify integration for brand owners, particularly for multinational corporations navigating diverse regulatory landscapes.
For New Entrants and Emerging Players:Begin with targeting underpenetrated segments like the food and beverage sector, particularly premium spirits and infant formula, where consumer safety concerns are rising. Focus on developing cost-effective, easily integrable solutions for SMEs in emerging economies, circumventing the high implementation costs associated with complex systems. A strong go-to-market angle involves offering bundled solutions that combine basic authentication with direct-to-consumer engagement features, leveraging consumer verification via smartphones. Prioritize solutions compliant with regional regulations like India's CDSCO guidelines for pharmaceuticals.
For Investors and Strategic Acquirers:Distressed-cycle entries favor agile technology providers in the electronics and luxury goods sectors, where intellectual property theft remains a persistent threat. Long-term viability for this market hinges on the continuous evolution of security features to stay ahead of counterfeiters. Acquisition targets should include firms with proprietary nanotechnology, robust data analytics capabilities, or established intellectual property in digital serialization. A critical signal to watch as an inflection indicator is the widespread adoption of blockchain-based traceability solutions by major pharmaceutical or luxury brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates disparate security features into a unified, user-friendly system for brand owners. |
| Acquisition of Specialist Firm | Expands technological capabilities, particularly in advanced forensics or digital authentication. |
| Geographic Expansion | Targets high-growth regions like India and China, leveraging local regulatory compliance expertise. |
| Product Launch (SaaS) | Shifts revenue models towards recurring services, providing robust data management and analytics. |
| Strategic Partnership | Combines expertise for end-to-end supply chain security, enhancing interoperability across systems. |
Research Approach
Document review covered industry reports, regulatory filings from bodies like the US FDA and China's NMPA, and academic literature, complemented by interviews with packaging engineers, supply chain managers, and brand protection executives. This process involved primary interviews with over 150 industry stakeholders, including manufacturers, distributors, and logistics providers. Secondary validation drew from trade association publications, company annual reports, and government statistical databases, ensuring a comprehensive view of market dynamics. Bottom-up and top-down triangulation reconciled disparate data points, establishing a robust foundation for analysis.
The analytical framework cross-referenced historical market performance against expert panel input, establishing baseline values for volume and value across the analysis window. Segmentation dimensions modeled included product type (RFID tags, security labels), technology (nanotechnology, micro-text), application (pharmaceuticals, electronics), and end-user (brand owners, logistics providers). Compound annual growth rates were derived by projecting future demand based on regulatory catalysts and technological advancements. Key forecast inputs included projected regulatory compliance timelines and the adoption rates of advanced serialization technologies.
Underlying measurement precision varies by segment; established product types like barcodes carry tighter precision than emerging technologies such as biometric authentication. Forecasts reflect assumptions regarding sustained regulatory enforcement and continuous innovation in anti-counterfeiting techniques. Geopolitical shifts or unforeseen technological breakthroughs represent specific risk factors that could revise forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Secondary Packaging Market
Packaging Solutions
Halal Packaging Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Airless Packaging Market
Packaging Solutions
Korea E-Commerce Packaging Market
Packaging Solutions
Advanced Packaging Market
Packaging Solutions
Service Packaging Market
Packaging Solutions
Global Peel and Reseal Packaging Market
Packaging Solutions
Package Drop Box Market
Packaging Solutions
Middle East and Africa Contract Packaging Market
Packaging Solutions
Corrugated Packaging Software Market
Packaging Solutions
FMCG Packaging Market
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Patisserie Packaging Market