
 Anticholinergic Drugs Market | 2026-2036
Anticholinergic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Anticholinergic Drugs Market Analysis
The anticholinergic drugs market is recalibrating around a widening split between premium once-daily LAMA inhalers and commoditized short-acting agents facing reimbursement compression. Novartis AG anchors its position through proprietary dry-powder device technology and sustained R&D investment in fixed-dose combinations. Boehringer Ingelheim International GmbH differentiates via vertical control over tiotropium supply chains and direct-to-specialist channel strategies. Teva Pharmaceutical Industries Ltd. competes aggressively on cost-positioned generics while navigating complex FDA bioequivalence requirements for complex inhalation products.
Anticholinergic drugs constitute a pharmacological class of muscarinic receptor antagonists that block acetylcholine binding at M1-M5 subtypes, with quaternary ammonium compounds such as ipratropium bromide exhibiting limited central nervous system penetration due to poor blood-brain barrier crossing. These agents serve primarily as bronchodilators in obstructive airway diseases and as detrusor muscle relaxants in urological disorders. Tiotropium and umeclidinium inhalation products command the largest revenue pools within the product type dimension, reflecting patient preference for once-daily dosing and payer willingness to subsidize adherence-improving regimens. The chronic obstructive pulmonary disease indication dominates prescription volumes, though overactive bladder therapies are expanding fastest in absolute terms as oral solifenacin and mirabegron combinations penetrate primary care.
FDA review standards for inhaled drug-device combinations, EMA MDR requirements for connected inhaler technologies, and WHO essential medicines list inclusion criteria collectively shape market access and pricing flexibility across developed markets. The EPA's phase-down of hydrofluorocarbon propellants under the AIM Act is forcing reformulation of metered-dose anticholinergic inhalers toward lower-global-warming-potential alternatives. Stakeholders must monitor how propellant transition timelines intersect with patent cliffs for major LAMA products, as this convergence will determine whether generic entrants capture volume or branded manufacturers extend franchise life through green chemistry claims.
Market Dynamics
The anticholinergic drugs market is restructuring around propellant-phase-down imperatives and inhaled drug-device integration requirements, with manufacturers racing to reformulate metered-dose inhalers ahead of regulatory deadlines while defending patent positions on long-acting muscarinic antagonists.
Growth Catalysts
- Aging Demographics in Developed Markets:Population pyramids across Japan, Italy, and the United States are driving prescription volumes for COPD maintenance therapies. Pulmonology practices in these markets prioritize once-daily LAMA regimens that improve adherence metrics.
- EMA MDR for Connected Inhalers:The European Medical Device Regulation's data-integrity requirements are accelerating investment in digital adherence-monitoring platforms. Manufacturers embedding Bluetooth-enabled dose counters gain preferential formulary positioning in Germany and France.
- Overactive Bladder Therapeutics:Primary care physicians in North American markets are expanding prescriptions for oral solifenacin combinations. Urology clinics report rising patient willingness to pursue pharmacological management before procedural interventions.
Market Restraints
- Hydrofluorocarbon Propellant Costs:The EPA's AIM Act phase-down is compressing margins on existing metered-dose inhaler portfolios. Reformulation toward hydrofluoroalkane alternatives requires capital deployment without corresponding price recovery mechanisms.
- API Supply Concentration:Tiotropium bromide active pharmaceutical ingredient production concentrates in Chinese and Indian chemical manufacturing clusters. Geopolitical friction or environmental enforcement actions at these sites threaten continuity of supply for Western formulators.
- Generic Bioequivalence Barriers:FDA requirements for in vitro-in vivo correlation studies in complex inhalation products extend development timelines for generic LAMA entrants. This technical limitation preserves branded pricing power while limiting patient access to lower-cost alternatives.
Strategic Opportunities
- Fixed-Dose Combination Expansion:LAMA-LABA-ICS triple therapies are capturing pulmonologist preference in severe COPD segments. Novartis and AstraZeneca are prioritizing clinical trial investment in these regimens to extend franchise lifecycles.
- Homecare Distribution Channels:Direct-to-patient subscription models for maintenance inhalers are penetrating Medicare Advantage populations. Pharmacy benefit managers in the United States are piloting adherence-linked reimbursement structures.
- India's CDSCO Streamlining:The Central Drugs Standard Control Organization's accelerated approval pathway for respiratory products is attracting contract manufacturing investment. Multinational sponsors are establishing local stability-testing facilities to serve South Asian markets.
Industry Challenges
- Inhaler Device Engineering Talent:The convergence of pharmaceutical formulation and precision mechanical engineering is creating skill scarcity. Manufacturers compete for aerosol physicists and human-factors specialists capable of optimizing pulmonary deposition profiles.
- Legacy System Integration:Connected inhaler platforms must interface with hospital electronic health record architectures and payer prior-authorization systems. Data interoperability standards remain fragmented across United States health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anticholinergic Drugs Market |
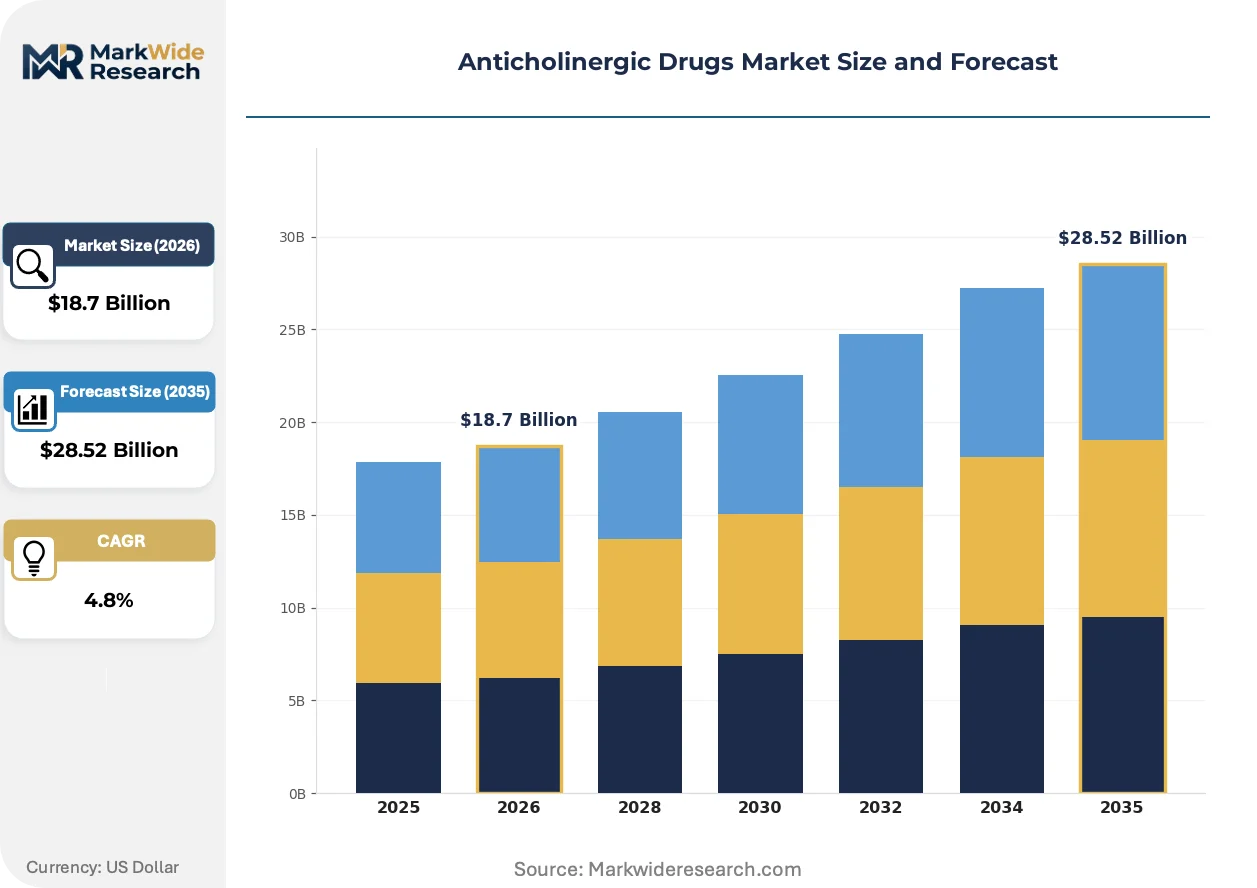
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ipratropium Bromide, Tiotropium, Glycopyrrolate, Umeclidinium Indication: Chronic Obstructive Pulmonary Disease, Asthma, Overactive Bladder, Motion Sickness Delivery Mode: Inhalation, Oral, Injectable, Transdermal End User: Healthcare Professionals, Pharmacies, Hospitals, Homecare Settings |
| Companies Covered | Novartis AG, Pfizer Inc., Boehringer Ingelheim International GmbH, Teva Pharmaceutical Industries Ltd., Johnson & Johnson, GlaxoSmithKline plc, Astellas Pharma Inc., Viatris Inc., AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anticholinergic Drugs Market Emerging Trajectories
Dry-powder inhaler technology is displacing pressurized metered-dose systems as the dominant delivery platform for anticholinergic maintenance therapies, driven by propellant environmental concerns and patient preference for breath-actuated dosing.
Soft-mist inhaler technology is absorbing development resources previously allocated to nebulized formulations. Boehringer Ingelheim's Respimat platform has demonstrated superior lung deposition efficiency in head-to-head trials against traditional pMDIs. Pulmonology practices in Germany and the United Kingdom are converting stable COPD patients to this delivery system, compressing demand for compressor-driven nebulization in routine maintenance settings.
The EPA's hydrofluorocarbon phase-down under the AIM Act is forcing portfolio-wide reformulation investments across North American operations. Manufacturers must redesign valve-actuator systems to accommodate lower-global-warming-potential propellants while maintaining dose reproducibility. Generic sponsors face particular pressure, as bioequivalence demonstration for reformulated pMDIs requires costly clinical endpoint studies that branded competitors amortized over decades.
Hospital procurement committees are consolidating inhaler purchasing around standardized formularies with adherence-monitoring requirements. Pharmacy directors in United States integrated delivery networks now mandate electronic compliance tracking for high-cost LAMA therapies. This behavioral shift favors manufacturers with mature digital infrastructure and disadvantages pure-generic suppliers lacking connected-device capabilities.
Anticholinergic Drugs Market Segmentation
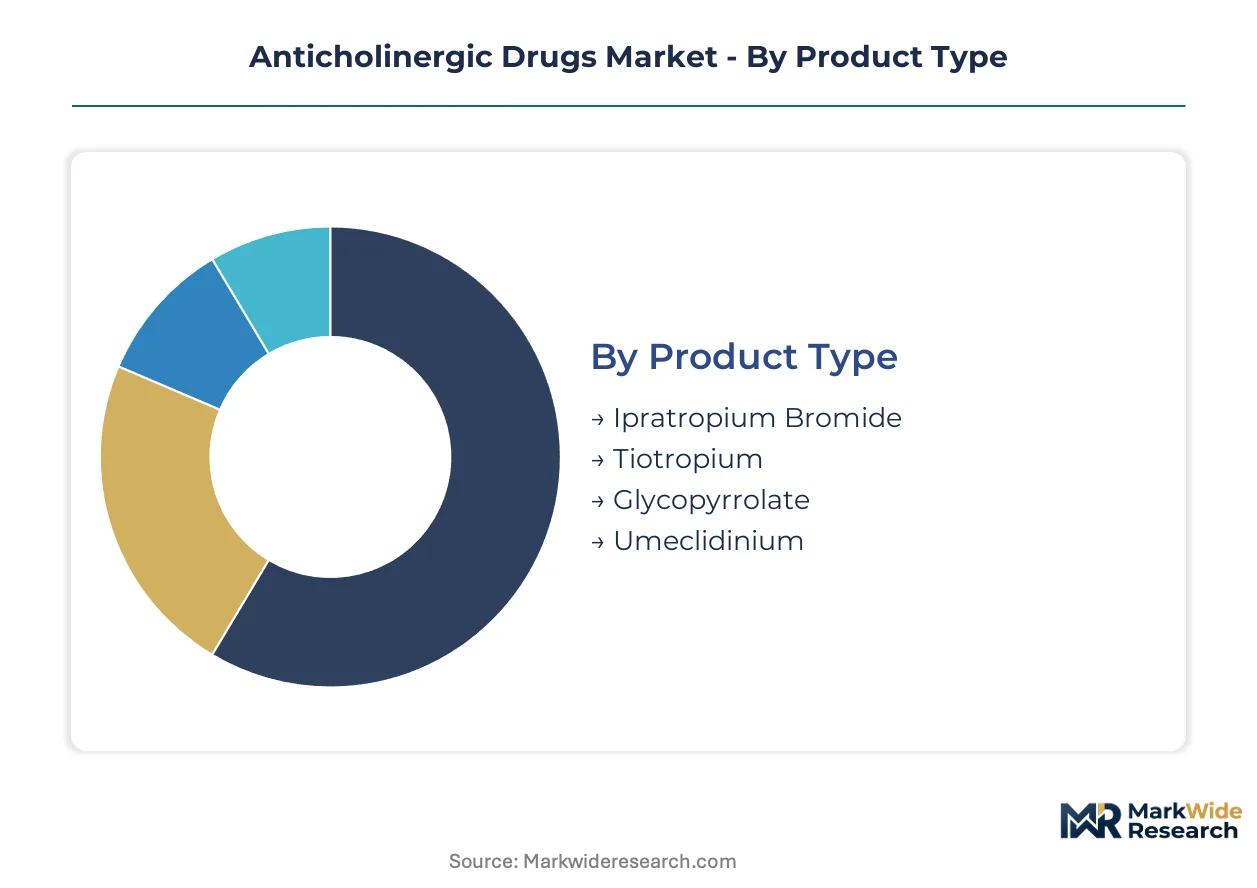
Anticholinergic drug manufacturers align portfolio investments with distinct technical requirements across delivery platforms and clinical indications. Segmentation reveals where formulation complexity creates margin differentiation versus where commoditization pressures dominate purchasing decisions.
Product Type:
Payer reimbursement tiers and dosing frequency preferences determine prescribing patterns across the muscarinic antagonist class.
- Tiotropium:Long-acting muscarinic antagonist with 24-hour receptor occupancy enables once-daily COPD maintenance regimens. United States Medicare formularies prioritize this agent for reducing hospitalization rates in severe airflow obstruction cases.
- Umeclidinium:LAMA component in fixed-dose combinations with vilanterol demonstrates superior FEV1 improvement in head-to-head trials against tiotropium. Pulmonology practices in Germany and the United Kingdom favor this agent for triple-therapy escalation pathways.
- Ipratropium Bromide:Short-acting quaternary ammonium compound serves acute bronchospasm rescue indications and nebulized hospital protocols.
- Glycopyrrolate:Quaternary ammonium structure limits CNS penetration, supporting perioperative and sialorrhea applications alongside respiratory uses.
Volume sits with tiotropium; growth tilts toward umeclidinium.
Indication:
Clinical endpoint stringency and trial duration requirements fragment development resource allocation across therapeutic areas.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation drives the largest prescription base for maintenance bronchodilation. FDA approval standards for exacerbation reduction endpoints demand multi-year outcome trials, concentrating investment among sponsors with respiratory specialty infrastructure.
- Overactive Bladder:Oral solifenacin and mirabegron combinations expand primary care prescribing as patients defer procedural interventions. United States urology clinics report rising willingness to pursue pharmacological management before botulinum toxin or neuromodulation.
- Asthma:Add-on LAMA therapy in stepwise guidelines captures severe eosinophilic phenotypes inadequately controlled by ICS-LABA alone.
- Motion Sickness:Transdermal scopolamine patches serve naval, aviation, and cruise line procurement channels with distinct stability requirements.
Prescription concentration favors COPD; expansion rates are steepest in overactive bladder.
Delivery Mode:
Device engineering capabilities and environmental compliance timelines reshape competitive positioning across administration routes.
- Inhalation:Dry-powder and soft-mist systems displace pressurized metered-dose formats as EPA hydrofluorocarbon phase-downs advance. Boehringer Ingelheim's Respimat platform demonstrates superior lung deposition efficiency against traditional pMDIs in German head-to-head studies.
- Oral:Immediate-release and extended-release tablet formulations serve overactive bladder and motion sickness indications with lower technical barriers to generic entry.
- Injectable:Intramuscular glycopyrrolate supports anesthesia reversal protocols and emergency anticholinergic toxicity management.
- Transdermal:Scopolamine patches require specialized adhesive matrix engineering for consistent absorption across skin types.
Revenue pools concentrate in inhalation; oral formats expand most quickly in absolute terms.
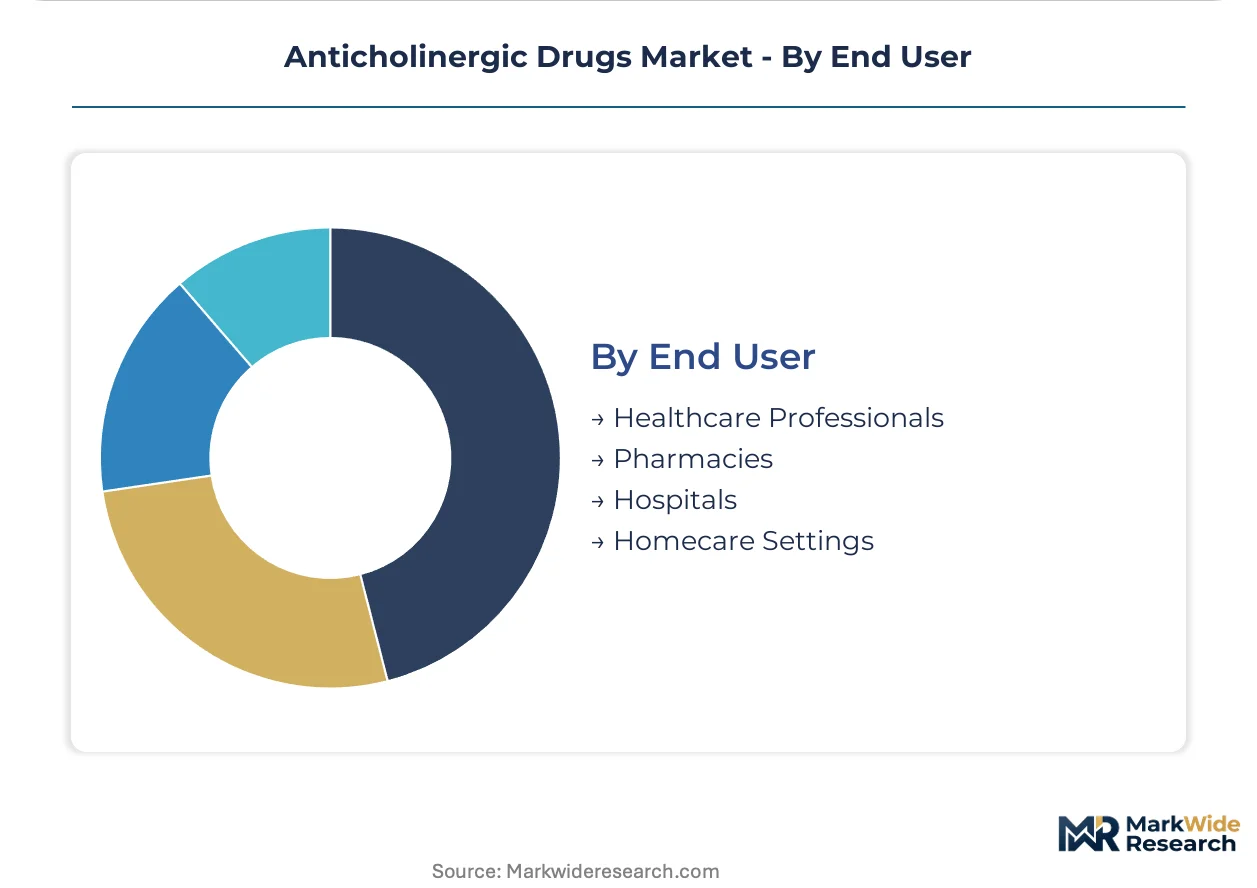
End User:
Procurement centralization and adherence-monitoring infrastructure differentiate channel economics for maintenance versus acute therapies.
- Hospitals:Integrated delivery networks consolidate inhaler purchasing around standardized formularies with electronic compliance tracking. United States pharmacy directors mandate connected-device capabilities for high-cost LAMA reimbursement authorization.
- Homecare Settings:Direct-to-patient subscription models penetrate Medicare Advantage populations with adherence-linked benefit structures. Pharmacy benefit managers pilot outcomes-based contracts linking device data to continuation criteria.
- Healthcare Professionals:Pulmonology and urology specialists drive initial therapy selection through detailed patient counseling on muscarinic receptor subtype selectivity.
- Pharmacies:Retail dispensing faces margin compression on generic ipratropium while capturing dispensing fees on specialty LAMA products.
Procurement scale favors hospitals; service intensity is highest in homecare channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basel anchors pharmaceutical formulation activity for muscarinic antagonist therapies, with Novartis AG maintaining specialized respiratory R&D infrastructure that shapes regional supply patterns for dry-powder inhaler platforms.
United States
Medicare Advantage enrollment expansion and COPD hospitalization reduction programs drive LAMA prescription volumes. FDA review standards for inhaled drug-device combinations tighten bioequivalence requirements. Research Triangle Park in North Carolina concentrates clinical trial operations for respiratory endpoints.
Germany
Pulmonology practices prioritize soft-mist inhaler conversion for stable COPD maintenance. EMA MDR data-integrity requirements accelerate Bluetooth-enabled adherence platform adoption. The Rhine-Main cluster around Frankfurt hosts Boehringer Ingelheim's Respimat manufacturing and specialist channel distribution headquarters.
Japan
Aging demographics and GOLD guideline implementation expand tiotropium maintenance therapy penetration. PMDA streamlined review pathways for fixed-dose combinations reduce time-to-market for LAMA-LABA products. Osaka-Kobe pharmaceutical corridor concentrates device engineering talent for pulmonary deposition optimization.
India
Domestic COPD prevalence and primary care diagnostic expansion drive ipratropium bromide generic volumes. CDSCO accelerated approval pathways for respiratory products attract contract manufacturing investment. Hyderabad's bulk drug manufacturing cluster supplies tiotropium API to Western formulators under tightened environmental enforcement.
United Kingdom
NHS England inhaler switching programs favor dry-powder platforms over pressurized metered-dose systems. NICE technology appraisals condition reimbursement on exacerbation reduction evidence. Cambridge life sciences corridor hosts AstraZeneca's respiratory combination therapy development operations.
Anticholinergic Drugs Market Vendor Landscape
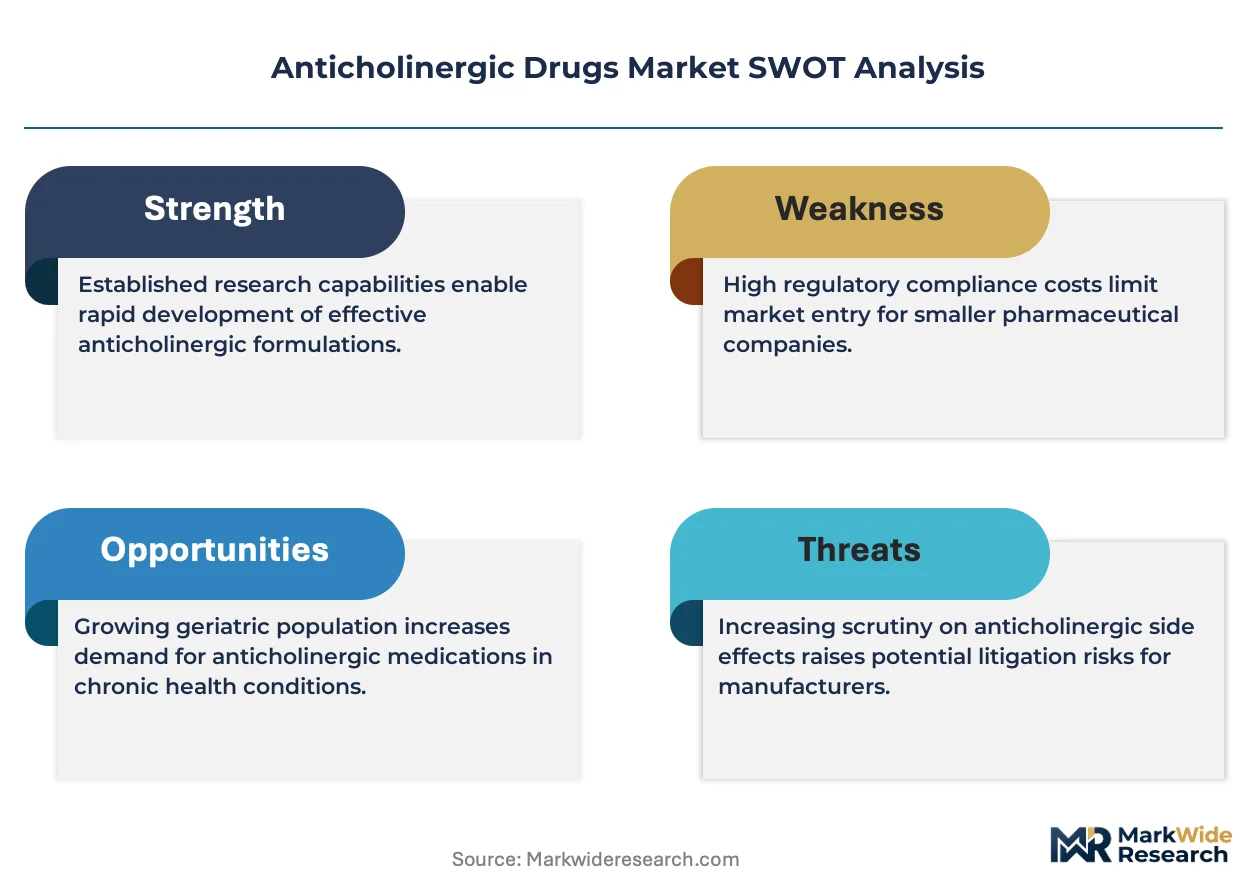
Premium-margin players sit above commodity-margin players across device-technology and formulation-complexity dimensions. The market structures around three tiers: multinational innovators controlling proprietary inhaler platforms, mid-scale specialists with regional manufacturing footprints, and pure-generic suppliers facing bioequivalence barriers. Consolidation pressure concentrates among platform-technology holders seeking fixed-dose combination pipelines, while API supply concentration in Asian chemical clusters creates vulnerability for Western formulators.
Within the multinational innovator tier, Novartis AG, Boehringer Ingelheim International GmbH, and AstraZeneca plc exemplify divergent competitive positions. Novartis occupies the dry-powder device-technology anchor through proprietary platform development. Boehringer Ingelheim sits within the soft-mist delivery system specialization with vertical control over tiotropium supply chains. AstraZeneca represents the triple-therapy combination strategy targeting severe COPD segments through clinical trial investment in LAMA-LABA-ICS regimens.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Boehringer Ingelheim International GmbH |
| Teva Pharmaceutical Industries Ltd. |
| Johnson & Johnson |
| GlaxoSmithKline plc |
| Astellas Pharma Inc. |
| Viatris Inc. |
| AstraZeneca plc |
| Others |
Supply Flow & Price Mechanics
Propellant transition timelines under the EPA's AIM Act are compressing cost structures while redrawing competitive boundaries between reformulation-capable multinationals and capital-constrained generic sponsors. This dual pressure on manufacturing economics and environmental compliance is concentrating pricing power among device-technology holders with captive chemistry capabilities.
Pricing Analysis
Outcome-linked reimbursement for exacerbation reduction anchors value-based pricing for long-acting muscarinic antagonists in United States Medicare Advantage formularies. Pricing stratifies across premium once-daily LAMA inhalers with connected-device capabilities, standard dry-powder formulations, and economy-positioned short-acting ipratropium facing generic substitution. Cost compression in the short-acting segment is intensifying because Indian and Chinese API oversupply erodes manufacturer margins. Hospital procurement committees exhibit lowest price sensitivity due to adherence-monitoring mandates, while retail pharmacy dispensing faces margin pressure on commoditized rescue therapies.
Supply Chain Analysis
Tiotropium bromide API production rests on chemical manufacturing clusters in Hyderabad, India and Zhejiang Province, China. Western formulators draw from these concentrated sources for quaternary ammonium compounds while sourcing specialized valve-actuator components from German precision engineering suppliers. Single-source vulnerability in hydrofluorocarbon propellant alternatives creates exposure as EPA phase-down deadlines approach. Distribution runs through hospital integrated delivery networks in developed markets and fragmented wholesale channels in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around device-technology differentiation as propellant reformulation costs and FDA bioequivalence barriers force weaker generic sponsors toward exit or contract manufacturing roles.
For Market Incumbents: Deploy connected-inhaler platform investments to capture formulary adherence-monitoring mandates in United States integrated delivery networks. Defensive consolidation should prioritize backward integration into lower-global-warming-potential propellant chemistry to preempt supply disruption as EPA enforcement tightens. Novartis and Boehringer Ingelheim have established templates for this vertical control. For New Entrants and Emerging Players: Specialty pharmacy distributors represent the most accessible channel for penetrating Medicare Advantage homecare subscription models with adherence-linked benefit structures. White-space targets include oral overactive bladder combinations in North American primary care and soft-mist inhaler generics in European markets where EMA MDR data-integrity requirements have slowed incumbent refresh cycles. A go-to-market angle emphasizing green chemistry claims can differentiate against legacy propellant portfolios. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale device-technology specialists possessing dry-powder or soft-mist platforms given fixed-dose combination pipeline demands from AstraZeneca and GlaxoSmithKline. Long-term viability favors sponsors with demonstrated FDA in vitro-in vivo correlation capabilities and established stability-testing infrastructure in India. The signal to watch is CDSCO enforcement actions in Hyderabad that could accelerate API supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Inhaler Platform Development | Bluetooth-enabled dose counters satisfy EMA MDR data-integrity requirements for German and French formulary access. |
| Lower-GWP Propellant Reformulation | Hydrofluoroalkane transition preserves pMDI market presence under EPA AIM Act compliance deadlines. |
| Fixed-Dose Combination Pipeline Investment | LAMA-LABA-ICS triple therapies capture pulmonologist preference in severe COPD segments per GOLD guidelines. |
| API Supply Backward Integration | Captive tiotropium production mitigates exposure to CDSCO enforcement in Indian chemical manufacturing clusters. |
| Homecare Subscription Model Pilot | Direct-to-patient adherence-linked structures align with Medicare Advantage pharmacy benefit manager reimbursement experiments. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving respiratory drug development executives, hospital formulary directors, FDA regulatory affairs leads, and Indian contract manufacturing officers. FDA 510(k) filings, EMA MDR submissions, ClinicalTrials.gov protocol registrations, and United States import records provided validation points. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were reconciled through iterative triangulation.
Data-stream reconciliation across manufacturer shipment reports, wholesaler distribution audits, and national health service dispensing records informed the analytical framework over the projection horizon. Segmentation dimensions included product type, indication, delivery mode, and end-user channel with regional regulatory cluster differentiation. CAGRs were derived from logarithmic trend fitting to normalized prescription volumes. Forecast inputs incorporated COPD prevalence epidemiology and EPA propellant phase-down compliance timelines.
Caveats apply where CDSCO enforcement intensity, FDA bioequivalence guidance revisions, or Medicare Advantage reimbursement restructuring could materially shift the outlook. Forecasts reflect assumptions regarding generic entry timelines for complex inhalation products and connected-device adoption curves in European hospital systems. A small set of named triggers warrants ongoing watch: propellant supply disruption, EMA MDR implementation delays, and tiotropium API manufacturing consolidation in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Paclitaxel Injection Market
Pharmaceuticals
Topical Corticosteroids Market
Pharmaceuticals
Japan Diabetes Drugs Market
Pharmaceuticals
Antiandrogens Market
Pharmaceuticals
United States Pharmaceutical 3PL Market
Pharmaceuticals
Granulocyte Macrophage Colony Stimulating Factor Market
Pharmaceuticals
Unit Dose Manufacturing Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
United Kingdom (UK) Diabetes Drugs Market
Pharmaceuticals
Global Pharmerging Market
Pharmaceuticals
Carbapenem Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
North America Analgesics Market
Pharmaceuticals
Lidocaine Ointment Market
Pharmaceuticals
Acne Drugs Market
Pharmaceuticals
Global Two Piece Empty Hard Capsule Market