
 Global Visitor Management System Market | 2026-2036
Global Visitor Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Visitor Management System Market Foresight
Aftermarket service revenue from visitor management platforms is fragmenting across cloud maintenance contracts, on-site integration support, and compliance audit services. Envoy Inc. leverages its SaaS-native architecture to anchor recurring revenue streams in enterprise deployments. HID Global Corporation dominates physical access control integration, while Proxyclick SA specializes in mid-market corporate rollouts across European commercial hubs.
A visitor management system constitutes an integrated software-hardware platform that automates guest registration, identity verification, access credentialing, and facility egress tracking through biometric scanners, QR code readers, and real-time database synchronization with building security infrastructure. Cloud-based deployment leads solution architecture as facility operators prioritize remote administration and API connectivity with existing access control ecosystems, while compliance tracking solutions capture expanding margin pools as GDPR and sector-specific data retention mandates intensify audit requirements across healthcare and government applications.
The EU AI Act, GDPR, and ISO 27001 collectively reshape product standards for biometric visitor identification and cross-border data residency in European deployments, while the US FDA and HIPAA constrain health facility visitor tracking protocols to protect patient privacy. Facility operators and security services must monitor evolving AI governance frameworks to determine biometric feature investments versus credential-based alternatives.
Market Dynamics
Facility operators are consolidating fragmented security infrastructure into unified cloud-native platforms, compressing procurement cycles from multi-year capital projects to annual SaaS renewals anchored by API-driven interoperability mandates.
Growth Catalysts
- EU AI Act compliance mandates:Biometric data governance frameworks are compelling European facility operators to replace legacy visitor logs with audit-ready digital systems that embed consent management and retention controls.
- Healthcare facility modernization:HIPAA-covered entities in the United States are deploying patient-privacy-compliant visitor tracking to satisfy Joint Commission accreditation standards and reduce unauthorized access incidents.
- QR code and mobile credential integration:Touchless check-in protocols adopted during public health contingencies have permanently altered enterprise reception workflows, creating durable pull for smartphone-based authentication.
Market Restraints
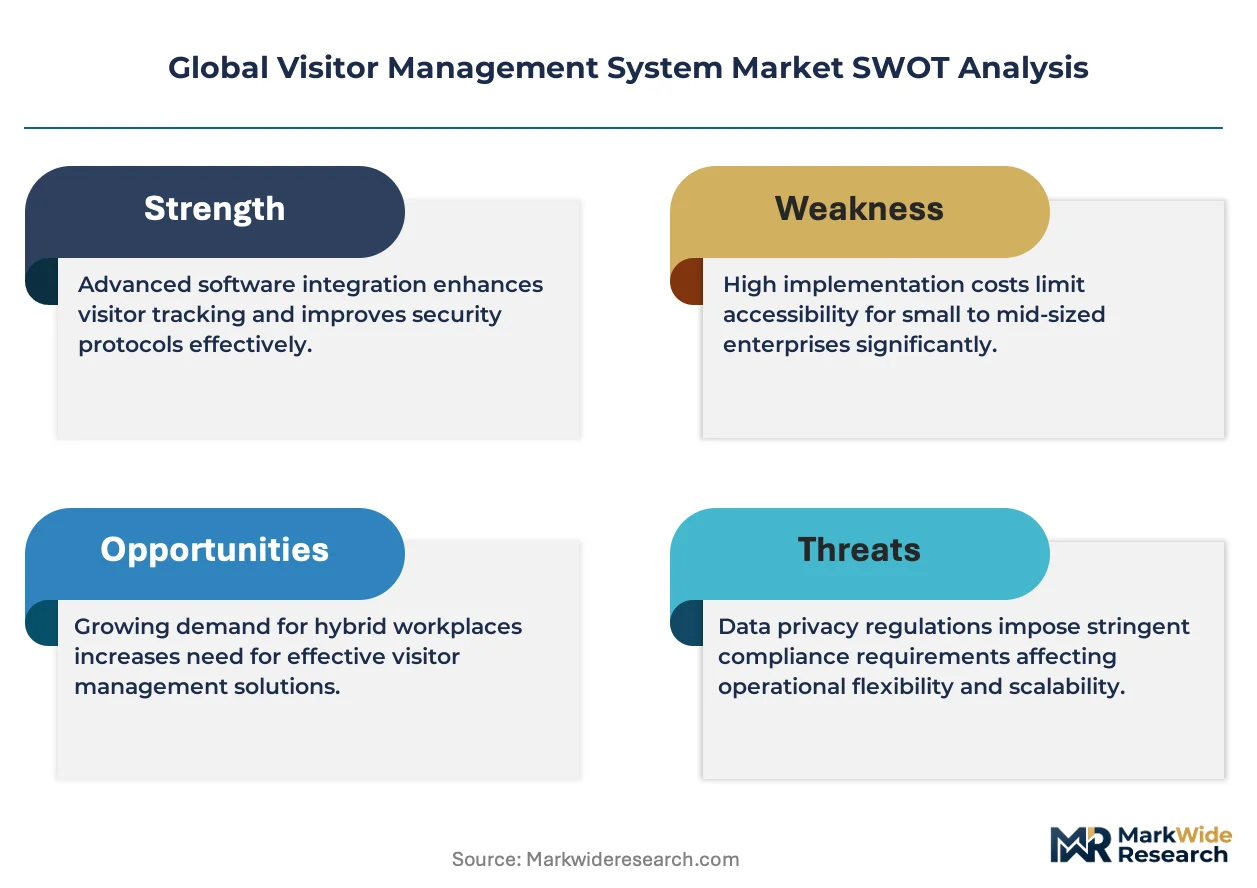
- Semiconductor supply concentration:Biometric scanner production depends on specialized image sensor foundries concentrated in Taiwan and South Korea, exposing hardware vendors to geopolitical disruption risks.
- GDPR cross-border data friction:European data residency requirements block seamless cloud replication to US-based servers, forcing vendors to maintain redundant regional infrastructure and raising operational overhead.
- Facial recognition substitution threat:Privacy advocates and municipal regulators in Germany and France are restricting biometric identification, pushing buyers toward NFC badge and PIN-based alternatives that reduce system differentiation.
Strategic Opportunities
- India commercial real estate expansion:Smart city initiatives in Bengaluru and Hyderabad are embedding visitor management into integrated building automation tenders, creating entry points for platform vendors before local competitors consolidate.
- API marketplace monetization:Vendors are opening credentialing modules to third-party workplace experience apps, capturing recurring revenue from parking, catering, and meeting room integrations without direct sales overhead.
- CSRD sustainability reporting alignment:Corporate sustainability directives are requiring facility operators to document building occupancy efficiency, positioning visitor flow analytics as inputs to Scope 3 emissions calculations.
Industry Challenges
- Cybersecurity certification timelines:ISO 27001 and SOC 2 Type II audits for cloud platforms require 12-18 month implementation cycles, delaying enterprise sales closes and consuming engineering resources.
- Legacy access control integration:Decades-old physical security infrastructure in US federal buildings and European heritage facilities lacks standard communication protocols, forcing costly middleware development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Visitor Management System Market |
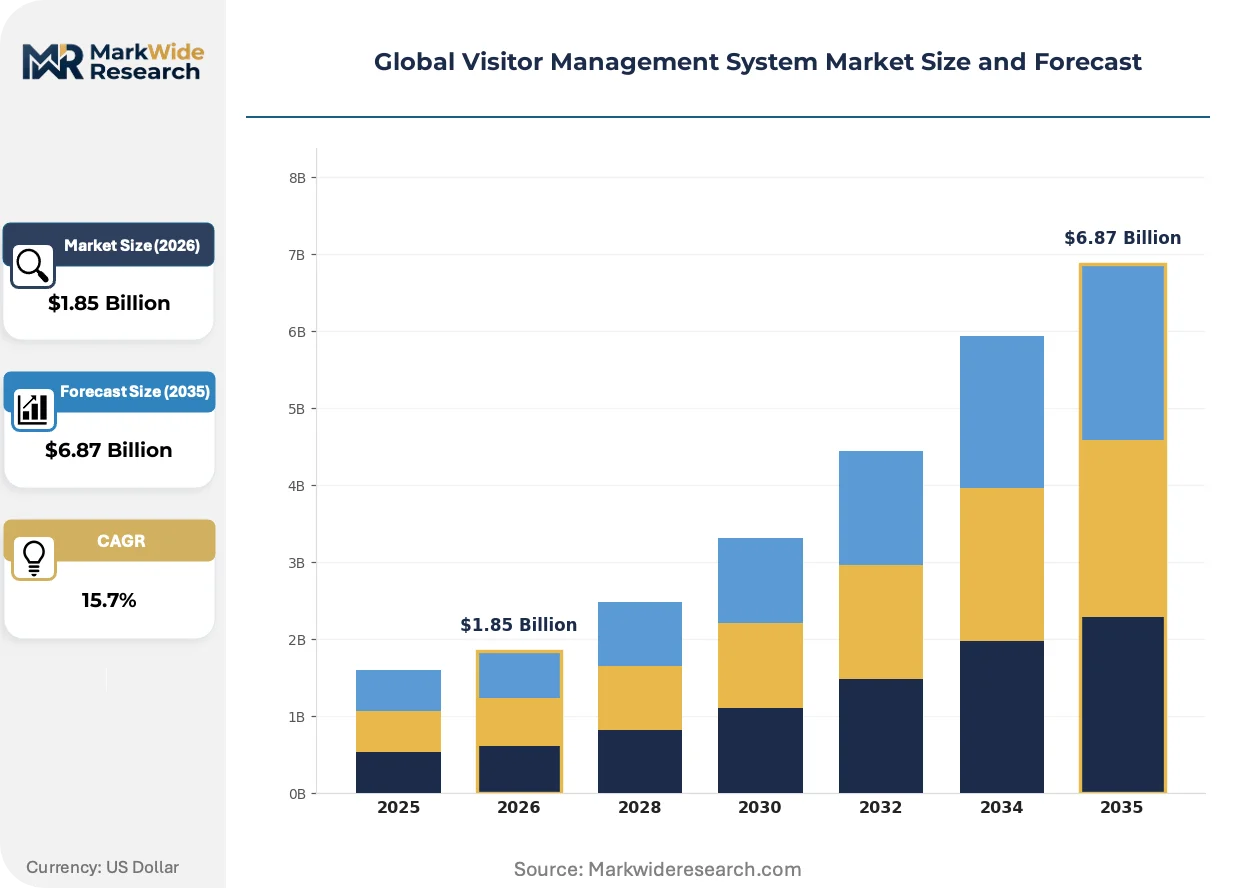
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution Type: Visitor Identification, Access Control, Compliance Tracking, Notification Management, Reporting & Analytics Application: Corporate Offices, Educational Institutions, Government Facilities, Healthcare Centers, Event Management End User: Facility Management Firms, Security Services, Educational Administrators, Healthcare Providers, Event Organizers |
| Companies Covered | Envoy Inc., Proxyclick SA, Traction Guest Corporation, HID Global Corporation, iLobby Systems Inc., Honeywell Forge, Acre Security, Greetly Inc., SwipedOn Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Visitor Management System Market Shifts & Advancements
Visitor management architecture is pivoting from perimeter security tools to workplace experience platforms, embedding identity verification within broader employee and contractor journey orchestration.
Edge computing nodes are virtualizing biometric processing functions that previously required centralized server infrastructure. Large corporate campuses in Texas and Singapore are deploying on-premise inference engines to reduce latency for high-throughput reception areas. This distributed architecture is virtualizing the traditional SaaS delivery model, enabling sub-second identity verification while maintaining data sovereignty compliance.
The EU AI Act's risk-based classification system is reclassifying most biometric visitor identification as high-risk AI, triggering conformity assessment obligations and human oversight mandates. Hardware vendors must now document training data provenance and algorithmic accuracy rates to place products on the European market. Healthcare and government verticals are responding by piloting credential-based alternatives that sidestep biometric classification entirely.
Enterprise procurement teams are unbundling visitor management from bundled security contracts, creating direct vendor relationships with SaaS specialists rather than channeling through incumbent access control distributors. Facility management firms in London and New York are negotiating platform-agnostic API agreements that preserve switching flexibility. This purchasing autonomy is most visible in technology and professional services sectors where workplace experience budgets sit with HR rather than security operations.
Global Visitor Management System Market Segmentation
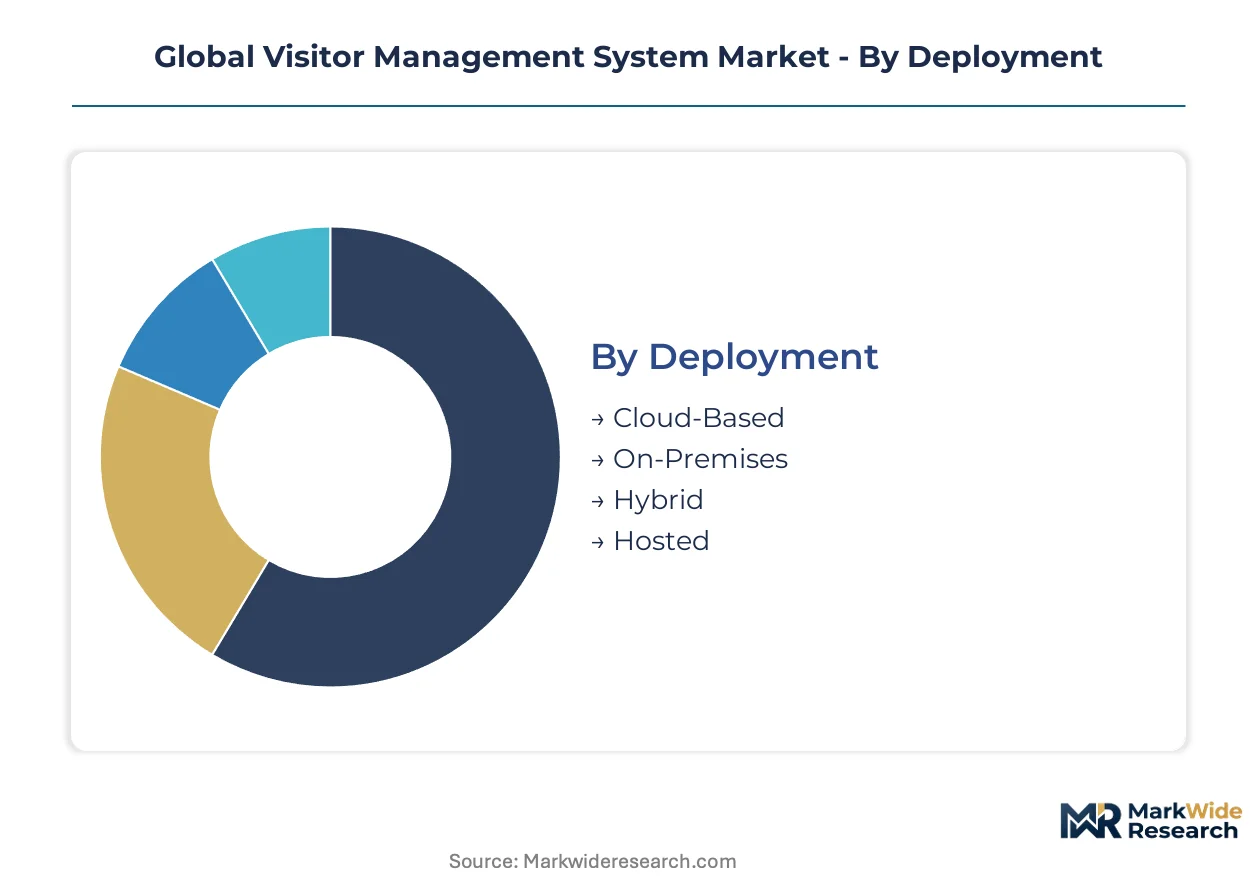
Segmentation in visitor management systems reveals divergent margin profiles across deployment architectures and end-user procurement sophistication. Cloud-native platforms command recurring revenue premiums while on-premises installations carry heavier integration service burdens. Understanding these structural differences enables vendors to align R&D investment with the highest-yield customer configurations.
Deployment:
After-sales-service intensity varies sharply across deployment modes, with cloud-based solutions generating continuous maintenance contracts while hybrid architectures demand perpetual on-site technical support.
- Cloud-Based:Multi-tenant SaaS architecture enables remote administration through browser-based dashboards and API connectivity with existing access control ecosystems. Demand concentrates in United States commercial real estate portfolios where facility management firms prioritize centralized oversight across distributed office towers. The EU AI Act's biometric governance mandates are accelerating European procurement of audit-ready cloud platforms with embedded consent management.
- On-Premises:Single-tenant installations run on customer-owned servers behind corporate firewalls, requiring dedicated IT infrastructure and localized database management. German and French government facilities favor this mode to satisfy strict data residency requirements under GDPR cross-border transfer restrictions. Higher upfront capital expenditure is offset by reduced ongoing subscription costs for large institutional buyers with captive IT capabilities.
- Hybrid:Combines edge processing for biometric verification with cloud synchronization for analytics and reporting, balancing latency performance with remote accessibility. Singapore and Texas corporate campuses deploy this architecture to maintain data sovereignty while enabling headquarters-level dashboard visibility.
- Hosted:Dedicated private cloud instances managed by vendor or third-party provider, offering single-tenant isolation without customer infrastructure ownership. Mid-market European firms select this option to satisfy sector-specific compliance without internal DevOps investment.
By volume, Cloud-Based leads. By growth pace, Hybrid is gaining share fastest as sovereignty-conscious enterprises seek architectural compromise.
Solution Type:
Margin concentration follows regulatory complexity, with compliance-tracking modules capturing premium pricing as GDPR and HIPAA audit requirements intensify across healthcare and government verticals.
- Visitor Identification:Biometric scanners, QR code readers, and credential verification systems authenticate guest identity at facility entry points. United States corporate offices are standardizing touchless smartphone-based authentication following public health protocol adoptions. The EU AI Act's high-risk classification for biometric identification is redirecting some European demand toward credential-based alternatives in Germany and France.
- Access Control:Integration with physical security infrastructure including turnstiles, elevator banks, and zone-restricted door hardware. Demand clusters in London and New York facility management contracts where unification of fragmented legacy systems drives procurement decisions. API-driven interoperability mandates are compressing sales cycles from multi-year capital projects to annual renewals.
- Compliance Tracking:Automated audit trails, consent management workflows, and data retention policy enforcement for regulatory documentation. HIPAA-covered entities in United States healthcare systems deploy these modules to satisfy Joint Commission accreditation standards.
- Notification Management:Real-time alerts to hosts, security personnel, and emergency responders via SMS, email, or mobile push notifications. Corporate campuses in Bengaluru and Hyderabad embed these capabilities within smart building automation tenders.
- Reporting & Analytics:Occupancy analytics, visitor flow visualization, and sustainability metrics integration for CSRD-aligned emissions calculations. European facility operators increasingly require these outputs for Scope 3 documentation.
By installed base, Access Control dominates. By expansion trajectory, Compliance Tracking is climbing the fastest as regulatory mandates proliferate.
Application:
Procurement autonomy varies by application, with corporate offices unbundling visitor management from bundled security contracts while government facilities retain centralized purchasing through incumbent distributors.
- Corporate Offices:Technology and professional services firms in London and New York are negotiating platform-agnostic API agreements that preserve switching flexibility. Workplace experience budgets controlled by HR rather than security operations are driving direct vendor relationships with SaaS specialists.
- Healthcare Centers:HIPAA-covered entities deploy patient-privacy-compliant visitor tracking to reduce unauthorized access incidents and satisfy accreditation standards. United States hospital systems represent concentrated demand for biometric alternatives that bypass facial recognition restrictions.
- Government Facilities:Decades-old physical security infrastructure in United States federal buildings and European heritage facilities lacks standard communication protocols, forcing costly middleware development for each deployment.
- Educational Institutions:Campus-wide visitor tracking for K-12 and university environments balances open accessibility with child safety protocols. Indian smart city initiatives are embedding these systems into integrated building automation tenders.
- Event Management:Temporary credentialing and crowd flow management for conferences, exhibitions, and sporting venues. Post-pandemic touchless protocols have permanently altered enterprise reception workflows in this segment.
By revenue concentration, Corporate Offices lead. By procurement velocity, Healthcare Centers are expanding most quickly as privacy compliance deadlines approach.
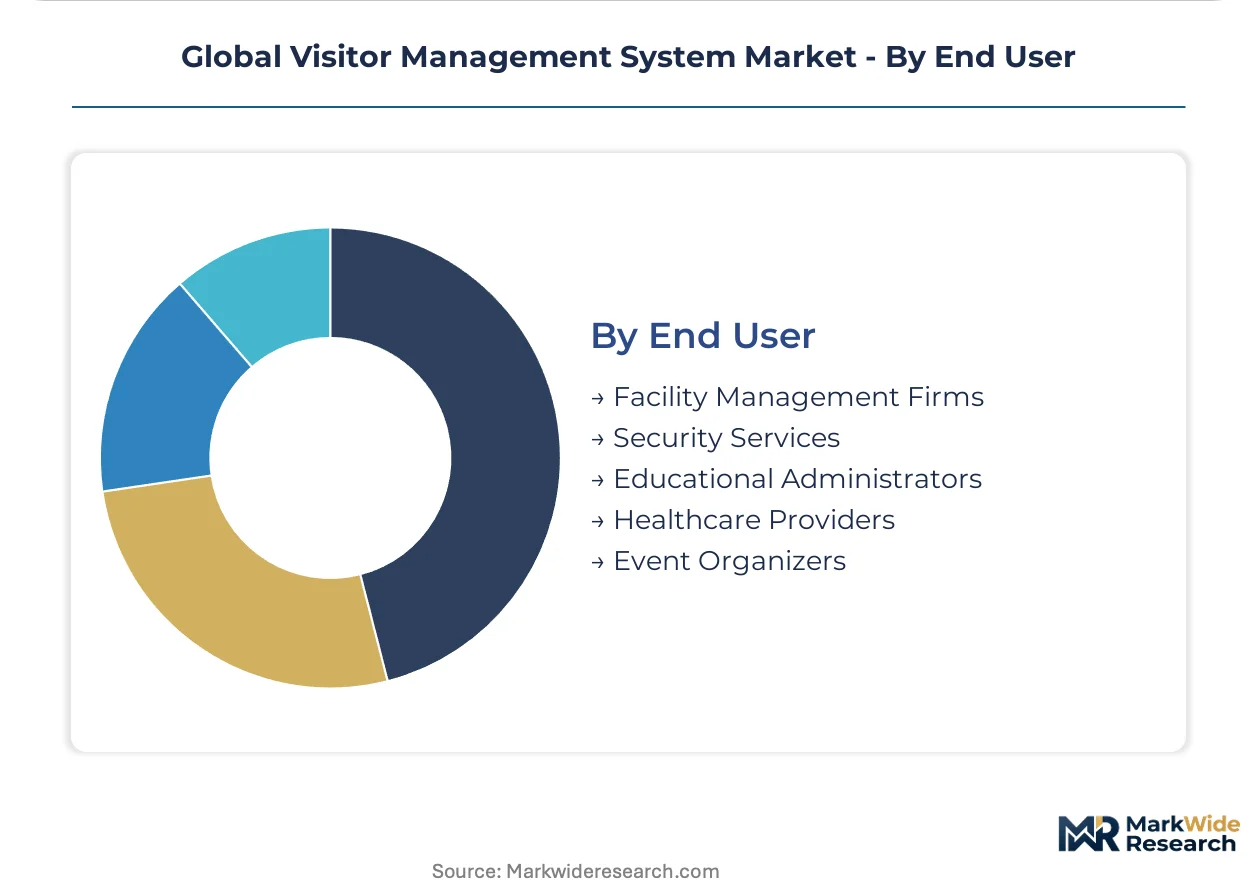
End User:
Technical sophistication and integration requirements diverge across end-user categories, with Facility Management Firms demanding API marketplace connectivity while Security Services prioritize physical access control unification.
- Facility Management Firms:Multi-tenant commercial real estate operators in United States markets modernize security infrastructure across portfolios through centralized cloud platforms. These buyers capture recurring revenue from parking, catering, and meeting room integrations through credentialing module APIs.
- Security Services:Incumbent access control distributors face disintermediation as enterprise procurement teams unbundle visitor management from bundled contracts. HID Global Corporation dominates physical access control integration for this customer type.
- Healthcare Providers:HIPAA-covered entities require patient-privacy-compliant systems with Joint Commission-aligned audit capabilities. United States hospital procurement cycles extend 12-18 months for ISO 27001 and SOC 2 Type II certified platforms.
- Educational Administrators:Campus safety officers balance open accessibility with emergency response coordination. European data residency requirements complicate cloud adoption for international school networks.
- Event Organizers:Temporary deployment specialists prioritize rapid configuration and mobile credential distribution over deep integration with fixed infrastructure. QR code and smartphone-based authentication dominate this use case.
By contract value, Facility Management Firms lead. By platform sophistication requirements, Healthcare Providers are advancing fastest toward biometric alternatives that sidestep AI Act classification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility operators in the United States deploy visitor management systems primarily for portfolio-wide security unification, while European buyers prioritize biometric governance compliance and German manufacturers favor on-premises data sovereignty. Indian smart city initiatives embed these platforms into integrated building automation tenders with fundamentally different procurement logic.
United States
Commercial real estate portfolios in New York and Chicago drive cloud-native platform adoption as facility management firms modernize distributed office towers. HIPAA-covered entities deploy patient-privacy-compliant visitor tracking to satisfy Joint Commission accreditation standards. Texas corporate campuses pilot edge computing nodes for sub-second biometric verification.
Germany
Federal and heritage facilities mandate on-premises installations to satisfy strict GDPR cross-border data residency requirements. Municipal regulators in Berlin and Munich restrict facial recognition deployment, redirecting demand toward NFC badge and PIN-based credentialing alternatives. The EU AI Act's high-risk classification triggers conformity assessment obligations for biometric vendors.
United Kingdom
London facility management firms negotiate platform-agnostic API agreements that preserve switching flexibility between SaaS specialists. Technology and professional services sectors assign workplace experience budgets to HR rather than security operations. CSRD sustainability reporting directives position visitor flow analytics as inputs to Scope 3 emissions calculations.
India
Smart city initiatives in Bengaluru and Hyderabad embed visitor management into integrated building automation tenders before local competitors consolidate. Educational institutions balance campus accessibility with child safety protocols across K-12 and university environments. Commercial real estate expansion creates entry points for platform vendors ahead of indigenous solution maturation.
Singapore
Corporate campuses deploy hybrid architectures combining edge processing for biometric verification with cloud synchronization for headquarters-level dashboard visibility. Data sovereignty requirements intersect with high-throughput reception demands in financial services and technology sectors. Government facilities prioritize API connectivity with existing access control ecosystems.
Global Visitor Management System Market Competitive Landscape
Capability concentration sits with SaaS-native specialists; scale advantage sits with physical access control incumbents. The vendor base stratifies across three tiers: cloud-first platform providers, hardware-integrated security conglomerates, and mid-market regional specialists. Dominant competitive moves include API marketplace expansion and cybersecurity certification acceleration to compress enterprise sales cycles.
Within the SaaS-native tier, Envoy Inc. and Proxyclick SA exemplify recurring revenue architectures anchored in enterprise deployments. HID Global Corporation occupies a position bridging physical access control integration with visitor management software. Traction Guest Corporation sits within the mid-market corporate rollout segment across North American commercial hubs. These three anchors represent divergent strategic postures: pure-software subscription scaling, hardware-software convergence, and vertical specialization.
| Leading Market Players |
|---|
| Envoy Inc. |
| Proxyclick SA |
| Traction Guest Corporation |
| HID Global Corporation |
| iLobby Systems Inc. |
| Honeywell Forge |
| Acre Security |
| Greetly Inc. |
| SwipedOn Limited |
| Others |
Supply & Pricing Matrix
Taiwanese image sensor foundries in Hsinchu Science Park anchor biometric scanner production capacity, concentrating upstream supply leverage among hardware vendors and compressing margin negotiation room for downstream platform integrators facing annual SaaS renewal pressures.
Pricing Analysis
Long-term subscription offtakes dominate enterprise procurement, though project-based installations persist in government and heritage facility segments. Pricing stratifies across premium, standard, and economy tiers based on ISO 27001 certification status and API integration complexity. Cost compression in the mid-market tier is intensifying because European data residency requirements force redundant regional infrastructure investments. Facility management firms in United States commercial real estate portfolios exhibit lowest price sensitivity due to portfolio-scale efficiency gains, while Indian educational institutions and event organizers remain most sensitive to upfront capital expenditure.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculations for biometric hardware components. Taiwan, South Korea, and Japan anchor specialized image sensor and edge computing processor production. Raw material dependencies include silicon wafers, rare earth magnets for motor assemblies, and optical-grade glass for camera modules. Single-source vulnerability concentrates in Taiwan Semiconductor Manufacturing capacity for inference engine chips. Distribution runs through physical security distributors in North America and direct vendor relationships in European commercial hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits as a defensive-moat story anchored in regulatory entrenchment: compliance certification timelines and data residency mandates create switching costs that cement incumbent positions once enterprise contracts close.
For Market Incumbents: Build switching-cost moats through deep API integration with incumbent access control ecosystems and accelerated SOC 2 Type II certification investments. Defend against emerging cloud-native entrants by capturing parking, catering, and meeting room integrations through credentialing module marketplaces. Prioritize capacity addition in Frankfurt and Singapore data centers to satisfy GDPR and local sovereignty requirements without latency penalties.
For New Entrants and Emerging Players: Establish a beachhead in Indian smart city building automation tenders before indigenous competitors consolidate. Target European mid-market corporate offices seeking platform-agnostic API agreements that preserve switching flexibility. Deploy credential-based authentication alternatives to sidestep EU AI Act high-risk classification and accelerate sales cycles in Germany and France.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue compounding play because SaaS-native architectures generate durable maintenance streams with negative churn characteristics in enterprise deployments. Target acquisition profiles emphasize vendors with ISO 27001 certification completion and existing API marketplace traction. Watch HIPAA audit deadline acceleration in United States healthcare systems as inflection indicator for compliance-tracking module demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| API Marketplace Expansion | Captures recurring revenue from parking and catering integrations without direct sales overhead. |
| Edge Computing Node Deployment | Enables sub-second biometric verification while maintaining GDPR data sovereignty compliance. |
| Cybersecurity Certification Acceleration | Compresses enterprise sales cycles from multi-year capital projects to annual SaaS renewals. |
| Compliance Tracking Module Development | Addresses HIPAA and EU AI Act audit requirements in healthcare and government verticals. |
| Hybrid Architecture Rollout | Balances latency performance with remote accessibility for sovereignty-conscious enterprises. |
Research Methodology
Operator-level perspectives from facility management directors, security operations leads, IT procurement officers, and compliance audit specialists anchored the qualitative base. Primary interview insights combined with secondary validation from SEC filings of publicly traded security technology vendors, hyperscaler data center capex disclosures, and European regulatory framework documentation. Bottom-up deployment volume estimates triangulated against top-down commercial real estate modernization spending patterns across the analysis window.
Scenario-bracketing framed the analytical approach, modeling demand trajectories under varying regulatory enforcement intensities for biometric data governance. Segmentation dimensions included deployment architecture, solution type, application vertical, and end-user procurement sophistication. CAGRs derived from installed base expansion rates and annual recurring revenue per account growth across the projection horizon. Industry-specific inputs incorporated EU AI Act implementation timelines and HIPAA audit deadline schedules.
Sensitivities concentrate around semiconductor supply disruption, cross-border data transfer restriction tightening, and municipal facial recognition ban proliferation. Forecasts reflect assumptions regarding regulatory enforcement consistency and enterprise cloud migration velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
POS Security Market
Security Software
Intrusion Detection System / Intrusion Prevention System (IDS / IPS) Market
Security Software
Global Automatic Number Plate Recognition (ANPR) System Market
Security Software
E Passport Market
Security Software
Cybersecurity Software Market
Security Software
Data Leakage Prevention Product Market
Security Software
Endpoint Detection and Response [EDR] Market
Security Software
Global Data Classification Market
Security Software
Extended Detection and Response Market
Security Software
Website Monitoring Software Market
Security Software
North America Secure Access Service Edge Market
Security Software
Endpoint Security Solutions Market
Security Software
Communication Encryption Software Market
Security Software
Spain Endpoint Detection and Response Market
Security Software
Global Security Operation Center As a Service Market
Security Software
Application Control Software Market