
 Global Cloud IAM Market | 2026-2036
Global Cloud IAM Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud IAM Market Foresight
Managed security service provider channels are reshaping how cloud IAM reaches mid-market buyers. Microsoft Corporation leverages its Azure Active Directory ecosystem to anchor enterprise deployments across hybrid cloud environments. Okta Inc. competes through deep API integrations with thousands of SaaS applications. IBM Corporation specializes in regulated industries where identity governance meets compliance auditing requirements.
Cloud IAM encompasses identity verification, access control, and privilege management delivered through cloud-native architectures with multi-tenant scalability and SAML 2.0 / OIDC protocol support. Its primary purpose is to authenticate users and authorize resource access across distributed IT environments without on-premises infrastructure dependency. Single Sign-On solutions dominate current spending as organizations consolidate application portals, while Privileged Access Management represents the fastest-expanding segment due to escalating insider threat concerns. Identity Governance offerings command premium pricing where audit trails and role-based certifications satisfy regulatory mandates.
The EU AI Act, NIS2 Directive, and GDPR collectively mandate stronger identity assurance for automated decision-making systems and critical infrastructure operators. In the United States, SEC cybersecurity disclosure rules and NIST zero-trust guidelines are accelerating board-level IAM investment approvals. Stakeholders must monitor how fragmented national digital identity frameworks reshape cross-border service architecture requirements.
Market Dynamics
Zero-trust architecture mandates from NIST and the SEC are forcing enterprise identity infrastructure rebuilds, compressing deployment timelines from multi-year roadmaps into 18-month execution windows.
Growth Catalysts
- SEC Cybersecurity Disclosure Rules:US public companies must now report material IAM incidents within four business days, elevating board-level security budgets.
- Hybrid Workforce Expansion:Financial services firms deploy cloud IAM to secure distributed traders, analysts, and compliance officers accessing sensitive systems remotely.
- NIS2 Directive:EU critical infrastructure operators face mandatory multi-factor authentication and privileged access monitoring for operational technology environments.
Market Restraints
- Skills Concentration:Certified identity architects cluster in Seattle, London, and Bangalore, creating talent acquisition bottlenecks for secondary markets.
- Protocol Fragmentation:Legacy systems relying on Kerberos and LDAP resist SAML 2.0 and OIDC migration, extending integration timelines.
- Input Cost Volatility:Specialized hardware security module manufacturers face semiconductor supply constraints, delaying high-assurance deployments.
Strategic Opportunities
- API-First Architectures:Machine-to-machine authentication for IoT device fleets represents an underpenetrated expansion vector beyond human-centric IAM.
- India's Digital Public Infrastructure:The country's Aadhaar-linked identity stack creates demand for cloud-native verification services among fintech and e-commerce platforms.
- Behavioral Biometrics Convergence:Keystroke dynamics and mouse-movement analysis layered atop traditional credentials enable continuous authentication without user friction.
Industry Challenges
- Certificate Lifecycle Management:Expiring machine identities at scale overwhelm security operations centers, requiring automated rotation tooling that most enterprises lack.
- Cross-Border Data Residency:GDPR, China's PIPL, and Russia's data localization laws fragment identity data architectures, multiplying compliance engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud IAM Market |
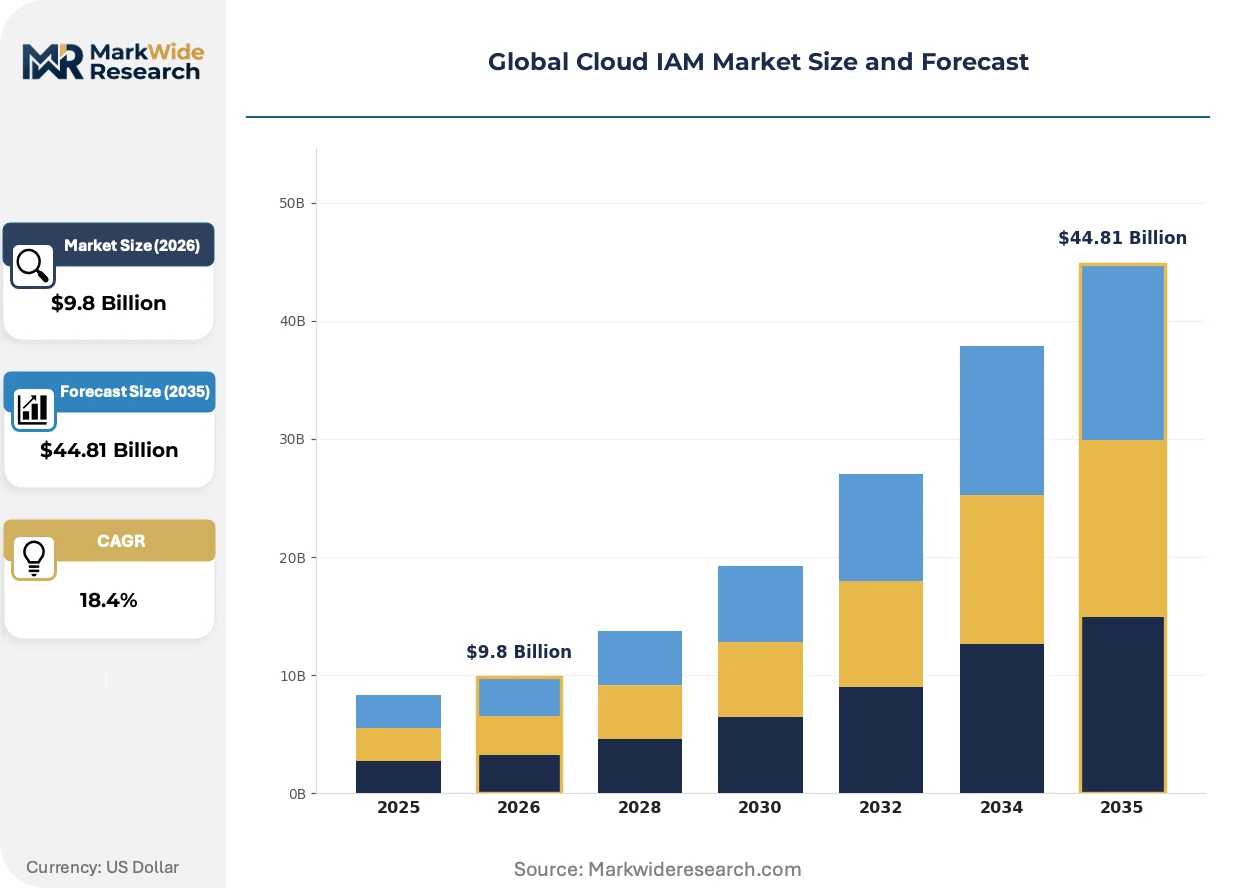
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $44.81 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution/Offering: Single Sign-On, Multi-Factor Authentication, Identity Governance, Access Management, Privileged Access Management Application: BFSI, Government Agencies, Telecommunications, Education, Manufacturing End User: Enterprises, Small & Medium Businesses, Educational Institutions, Government Organizations |
| Companies Covered | Microsoft Corporation, IBM Corporation, Okta Inc., Oracle Corporation, Ping Identity Corporation, SailPoint Technologies Holdings Inc., Intel Corporation, OneLogin Inc., Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud IAM Market Shifts & Advancements
Passwordless authentication architectures are displacing credential-based systems across regulated industries, while continuous authorization engines replace static access decisions.
Decentralized identity wallets built on W3C standards are digitizing how individuals present verifiable credentials to employers, banks, and government agencies. European banks and healthcare providers pilot these systems for customer onboarding. The technology is digitizing trust establishment between parties without centralized identity providers.
The EU AI Act's risk classification framework mandates human oversight for automated identity verification systems processing biometric data. High-risk AI deployments require conformity assessments and CE marking. Financial institutions in Germany and France are restructuring their facial recognition pipelines to satisfy these requirements.
Security-conscious buyers now demand consumption-based IAM licensing rather than per-seat contracts. Mid-market enterprises in the United States negotiate usage tiers aligned with seasonal workforce fluctuations. This model is compressing vendor lock-in and accelerating competitive switching between cloud identity platforms.
Global Cloud IAM Market Segmentation
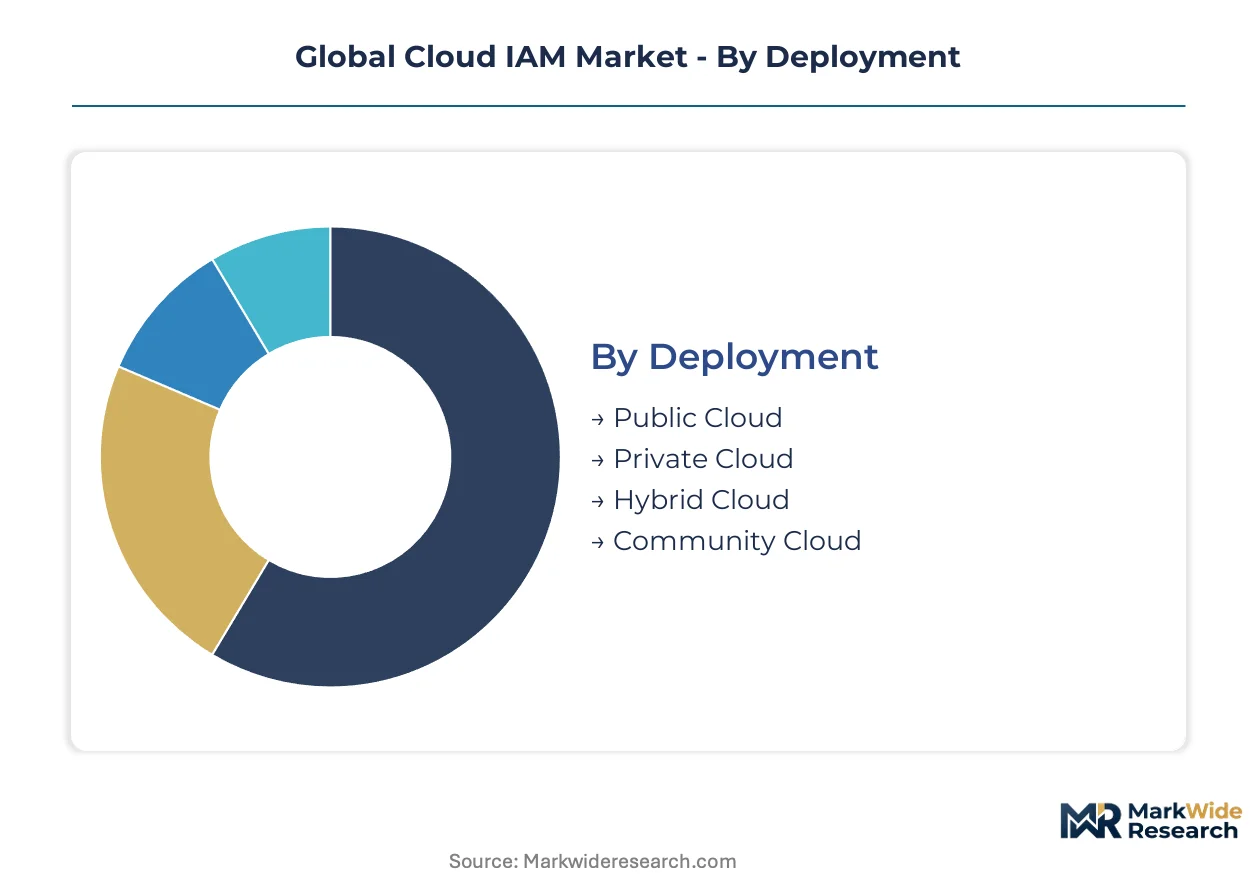
Cloud IAM segmentation reveals how deployment architectures, solution types, and buyer profiles create distinct commercial battlegrounds. Each dimension carries unique margin structures and competitive dynamics that shape vendor strategy.
Deployment:
Mature public cloud offerings coexist with emerging sovereign and edge-distributed alternatives across the maturity spectrum.
- Public Cloud:Multi-tenant SaaS delivery enables rapid provisioning without infrastructure capital. Financial services firms in the United States favor this model for trader and analyst access to market data systems, though latency constraints limit high-frequency trading use cases.
- Hybrid Cloud:Identity fabric spans on-premises Active Directory and cloud-native directories through synchronized policy enforcement. German automotive manufacturers deploy this architecture to protect intellectual property while enabling supplier collaboration portals.
- Private Cloud:Dedicated tenant isolation satisfies defense and intelligence community requirements. The model carries 40-60% cost premiums over public equivalents but eliminates co-tenancy risk assessments.
- Community Cloud:Shared infrastructure among regulated peers—healthcare networks, credit unions, municipal governments—achieves compliance economies without full private deployment overhead.
Public cloud handles the majority of throughput; hybrid cloud is the fastest mover on share.
Solution/Offering:
Cost tier stratification separates commodity authentication from premium governance suites with audit automation.
- Single Sign-On:Session management across application portfolios through SAML 2.0 and OIDC protocol mediation. Mid-market enterprises in the United States consolidate an average of 47 applications per employee through these portals.
- Privileged Access Management:Vaulting, session recording, and just-in-time elevation for administrative credentials. The segment attracts the highest pricing multiples due to insider threat insurance requirements and SEC disclosure rule implications.
- Multi-Factor Authentication:Push notifications, hardware tokens, and biometric verification layers. French banks under EU AI Act pressure are restructuring facial recognition pipelines to satisfy high-risk AI conformity assessments.
- Identity Governance:Role mining, access certification campaigns, and segregation-of-duties enforcement. Annual recertification workflows command premium subscriptions in healthcare and financial services.
- Access Management:Policy decision points and enforcement engines for coarse-grained authorization. Standardized pricing and rapid commoditization pressure margins below governance and PAM tiers.
Single Sign-On handles the majority of throughput; Privileged Access Management is climbing the fastest on revenue contribution.
Application:
Volume concentration in regulated sectors contrasts with emerging adoption across industrial and educational verticals.
- BFSI:Trading floor access, customer onboarding, and payment system authorization. NIST zero-trust mandates and SEC four-day incident disclosure rules are compressing deployment timelines from multi-year roadmaps into 18-month execution windows.
- Telecommunications:Subscriber identity management and network operations center access. 5G network slicing introduces machine-to-machine authentication at unprecedented scale.
- Government Agencies:Citizen digital identity and classified system access. India's Aadhaar-linked stack creates demand for cloud-native verification among state and federal implementers.
- Manufacturing:Operational technology environment protection and supply chain partner onboarding. NIS2 Directive multi-factor authentication mandates are accelerating deployment across EU critical infrastructure operators.
- Education:Student lifecycle identity and research data access. Budget constraints favor consumption-based licensing aligned with semester enrollment fluctuations.
BFSI handles the majority of throughput; manufacturing is expanding most quickly as industrial IoT authentication requirements multiply.
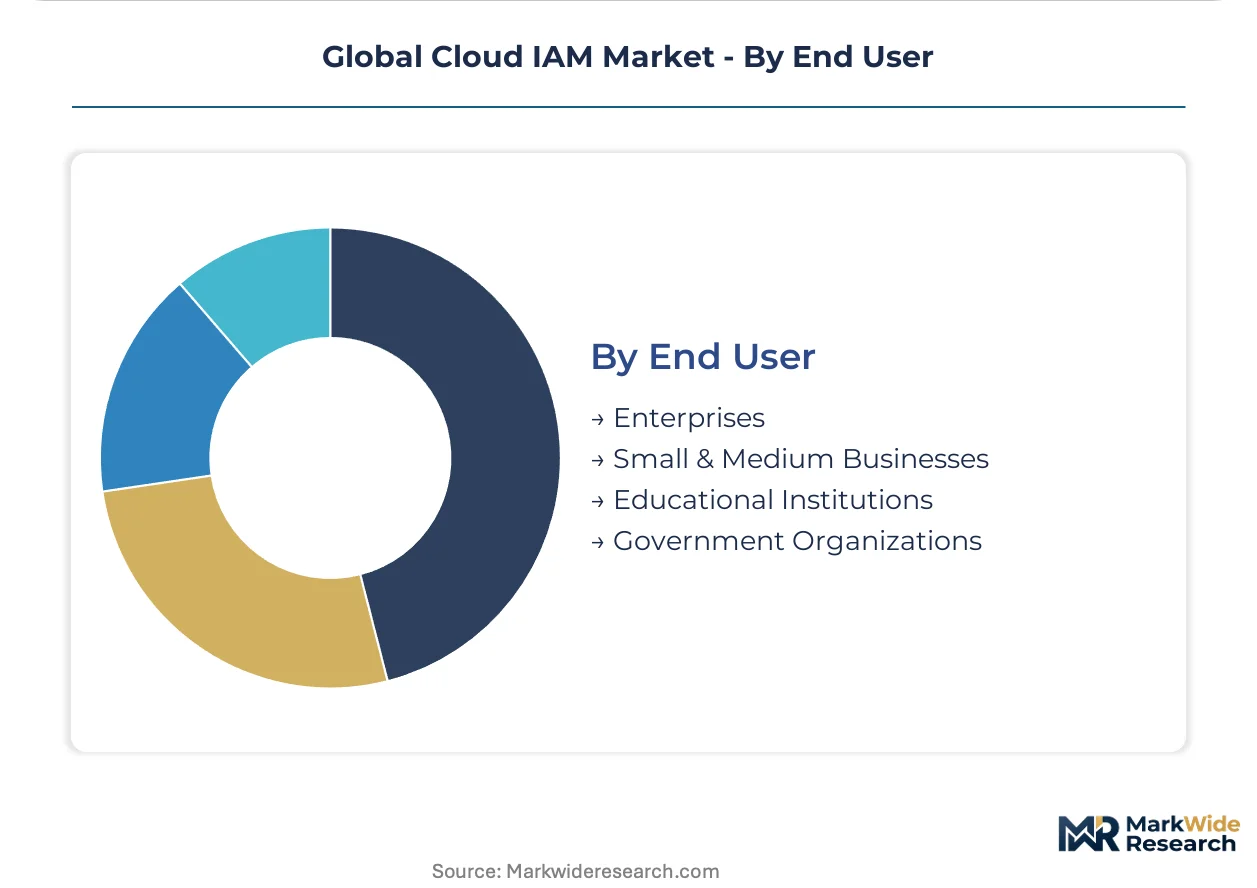
End User:
Customer type segmentation separates complex multi-directory enterprises from standardized mid-market deployments.
- Enterprises:Global identity fabrics spanning acquired subsidiaries and heterogeneous technology stacks. Certificate lifecycle management automation becomes critical at scale as expiring machine identities overwhelm security operations centers.
- Small & Medium Businesses:Managed security service provider channel delivery with pre-configured policy templates. Consumption-based licensing negotiations are compressing vendor lock-in and accelerating competitive switching.
- Government Organizations:Sovereign cloud requirements and classified network segmentation. Cross-border data residency mandates from GDPR, China's PIPL, and Russia's localization laws fragment architecture decisions.
- Educational Institutions:Seasonal workforce patterns and research collaboration federation. Identity governance investments lag enterprise peers due to decentralized IT governance structures.
Enterprises handle the majority of throughput; small and medium businesses are gaining share fastest through managed service provider channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ashburn-Loudoun data center corridor underwrites the United States' dominance in cloud IAM infrastructure deployment, while submarine cable landings at Mumbai and Singapore anchor Asia-Pacific service delivery.
United States
SEC cybersecurity disclosure rules and NIST zero-trust mandates compress enterprise deployment timelines into 18-month windows. Financial services firms in New York and Chicago deploy cloud IAM to secure hybrid trading floors. Seattle hosts the densest concentration of certified identity architects, creating talent acquisition bottlenecks for secondary markets.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg deploy hybrid cloud identity fabrics to protect intellectual property while enabling supplier collaboration. The EU AI Act and NIS2 Directive mandate multi-factor authentication for critical infrastructure operators. Frankfurt's financial district drives demand for identity governance with audit automation.
India
The Aadhaar-linked digital public infrastructure creates demand for cloud-native verification services among fintech and e-commerce platforms. RBI guidelines and SEBI cybersecurity frameworks tighten authentication requirements for financial institutions. Bengaluru and Hyderabad concentrate identity engineering talent for both domestic deployment and offshore service delivery.
United Kingdom
London's financial services sector accelerates zero-trust architecture rollouts in response to Bank of England operational resilience requirements. The Financial Conduct Authority's cybersecurity expectations elevate board-level IAM investment approvals. The Thames Valley corridor hosts managed security service providers serving mid-market European enterprises.
France
French banks under EU AI Act pressure restructure facial recognition pipelines to satisfy high-risk AI conformity assessments. CNIL enforcement of GDPR identity verification standards drives premium governance suite adoption. Paris-based healthcare providers pilot decentralized identity wallets for patient onboarding.
Global Cloud IAM Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in protocol mediation and hardware security modules. The vendor base stratifies across three tiers: hyperscale cloud platforms with directory services, best-of-breed identity specialists, and managed security service providers with pre-configured policy templates. Dominant competitive moves include API ecosystem expansion and consumption-based licensing model introductions.
Within the platform integrator tier, Microsoft Corporation exemplifies the hyperscale archetype leveraging directory infrastructure, while Okta Inc. occupies a position among API-first specialists. IBM Corporation represents the regulated industry focus where identity governance intersects with compliance auditing. These three anchors illustrate how competitive positioning separates cloud-native delivery from hybrid infrastructure plays.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Okta Inc. |
| Oracle Corporation |
| Ping Identity Corporation |
| SailPoint Technologies Holdings Inc. |
| Intel Corporation |
| OneLogin Inc. |
| Hewlett Packard Enterprise |
| Others |
Supply & Pricing Matrix
Single-source dependency on hardware security module manufacturers in Taiwan and South Korea determines both tiered pricing spreads and supply chain resilience, as semiconductor supply constraints compress deployment timelines for high-assurance identity infrastructure and force buyers toward consumption-based licensing models that reduce upfront capital exposure.
Pricing Analysis
Volume-discount tiering structures separate enterprise identity fabrics from mid-market managed service offerings, with consumption-based SaaS licensing displacing per-seat contracts as buyers negotiate usage tiers aligned with seasonal workforce fluctuations. Price differentiation rests on certification grade—FIPS 140-2 Level 3 versus Level 4 hardware—and vertical integration depth in protocol mediation stacks. Cost compression in the standard tier intensifies as hyperscalers bundle directory services into broader cloud contracts. Small and medium businesses exhibit highest price sensitivity, while defense and intelligence buyers accept 40-60% premiums for private cloud tenant isolation.
Supply Chain Analysis
Extended payment terms from cloud hyperscalers to hardware security module suppliers concentrate working capital demands on component manufacturers in Taiwan, South Korea, and Israel. The supply chain draws from specialized semiconductor foundries, cryptographic processor designers, and SAML/OIDC protocol stack developers. Single-source vulnerability in FIPS-certified chip fabrication creates chokepoint exposure. Distribution runs through managed security service provider channels for mid-market penetration and direct enterprise sales for complex multi-directory deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of certified identity architects in Seattle, London, and Bangalore constrains deployment velocity and inflates implementation costs, creating a capability-scarcity environment where talent acquisition determines competitive position more than feature parity.
For Market Incumbents: Pre-empt API-first specialists from capturing machine-to-machine authentication workloads by embedding continuous authorization engines into existing directory infrastructure. Acquire behavioral biometrics capabilities before EU AI Act high-risk classification mandates reshape facial recognition pipelines. Channel control through managed security service provider certification programs defends against consumption-based licensing erosion. For New Entrants and Emerging Players: Build out sovereign cloud identity offerings for German automotive manufacturers and French healthcare providers facing GDPR and EU AI Act data residency fragmentation. India's Aadhaar-linked fintech ecosystem presents the most penetrable geography. Position through pre-configured compliance templates that accelerate NIS2 Directive and SEC disclosure rule alignment without custom engineering. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors identity governance specialists with audit automation IP over commodity SSO providers facing hyperscaler bundling pressure. Long-term viability hinges on regulatory workflow integration rather than protocol mediation alone. Watch for EU AI Act conformity assessment bottlenecks as inflection indicator for premium governance suite demand.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Machine-to-machine authentication for IoT device fleets opens underpenetrated revenue beyond human-centric IAM. |
| Behavioral Biometrics Acquisition | Keystroke dynamics and mouse-movement analysis satisfy EU AI Act continuous authentication without user friction. |
| Sovereign Cloud Partnership | Data residency compliance for German automotive and French healthcare buyers fragments architecture requirements. |
| Consumption-Based Licensing Transition | Usage-tier contracts align with seasonal workforce patterns and compress vendor lock-in across mid-market buyers. |
| Managed Security Service Provider Certification | Pre-configured policy templates accelerate channel penetration among price-sensitive small and medium businesses. |
Research Methodology
Initial hypotheses were tested against primary input from chief information security officers, identity architects, cloud procurement officers, and managed security service provider channel managers and refined through secondary validation against SEC cybersecurity disclosure filings, NIST zero-trust architecture guidelines, EU AI Act regulatory texts, and hyperscaler capex disclosures. Bottom-up deployment estimates triangulated with top-down market sizing across public cloud, hybrid cloud, private cloud, and community cloud deployment models.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling solution type segmentation—Single Sign-On, Privileged Access Management, Multi-Factor Authentication, Identity Governance, and Access Management—against end user categories and application verticals. CAGRs were derived from policy mandate timelines and workforce distribution shifts. Forecast inputs included NIS2 Directive implementation schedules and SEC four-day incident disclosure compliance deadlines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscalers bundling identity into platform contracts or decentralized identity wallet specialists capturing European banking pilots would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Software Assurance Market
Security Software
Information Rights Management Market
Security Software
Global Electronic Passports Market
Security Software
Online Background Check Market
Security Software
Global Enterprise Data Loss Prevention Software Market
Security Software
Global Consumer IAM Market
Security Software
Global Network Encryption Market
Security Software
Global Advanced Authentication Market
Security Software
Consumer Endpoint Security Market
Security Software
Smartphone Security Market
Security Software
Employee Fraud Detection Market
Security Software
Biometric POS Terminals Market
Security Software
Global Electronic Offender Monitoring Solutions Market
Security Software
Antivirus Software Package Market
Security Software
North America Video Management System Market
Security Software
Mobile Security Market