
 United States Consumer Identity and Access Management Market | 2026-2036
United States Consumer Identity and Access Management Market Size, Share, and Industry Trends Forecast 2026-2036
United States Consumer Identity and Access Management Market Analytics
Platform licensing revenue is narrowing as vendors shift toward consumption-based identity verification models. Microsoft Corporation leverages its Azure Active Directory ecosystem to anchor enterprise-consumer hybrid deployments. Okta competes through extensive third-party application integrations that sustain developer loyalty. Ping Identity specializes in risk-based authentication protocols that differentiate its financial services positioning.
Consumer Identity and Access Management comprises software systems that authenticate, authorize, and manage digital identities for non-workforce users across web and mobile channels, typically incorporating biometric verification, behavioral analytics, and tokenized session management to prevent fraudulent account access. The architecture serves e-commerce platforms, healthcare portals, and banking applications requiring seamless yet secure customer onboarding. Cloud-based deployment leads structural growth as organizations abandon on-premises directory infrastructure for API-based integration models. Multi-factor Authentication solutions capture expanding security budgets while Single Sign-On retains the largest installed base across E-commerce and Banking end users. Identity Governance remains the most mature solution category with slower expansion but durable renewal rates.
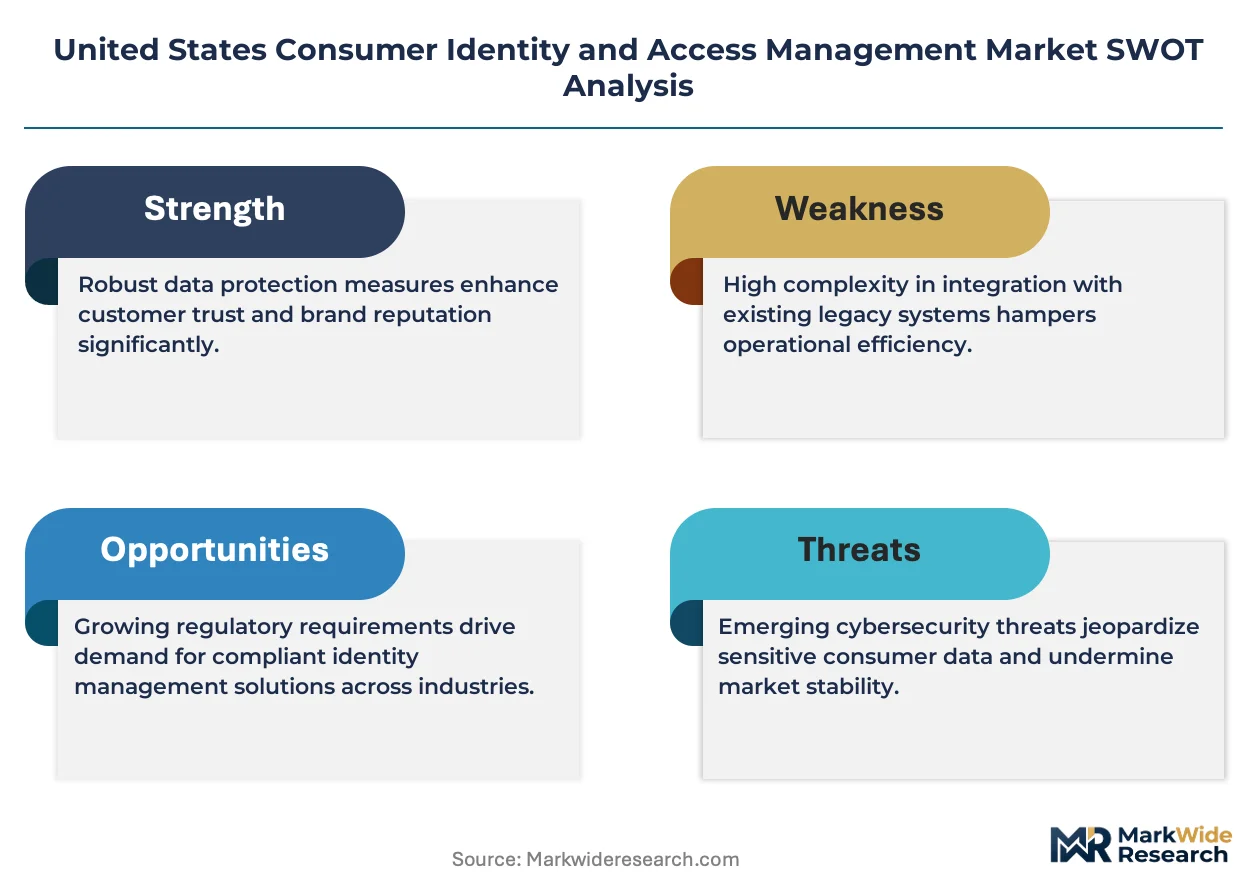
The Federal Trade Commission enforces data breach notification standards that compel consumer-facing enterprises to strengthen identity infrastructure, while NIST guidelines mandate phishing-resistant authentication for federal contractors. State-level regulations, including California's Consumer Privacy Act enforcement by the Attorney General, extend compliance obligations to identity data retention and deletion protocols. Healthcare sector adoption further ties to HIPAA security rule requirements for patient portal access controls. Stakeholders must monitor emerging Federal Reserve guidance on digital identity verification for open banking participation.
Market Dynamics
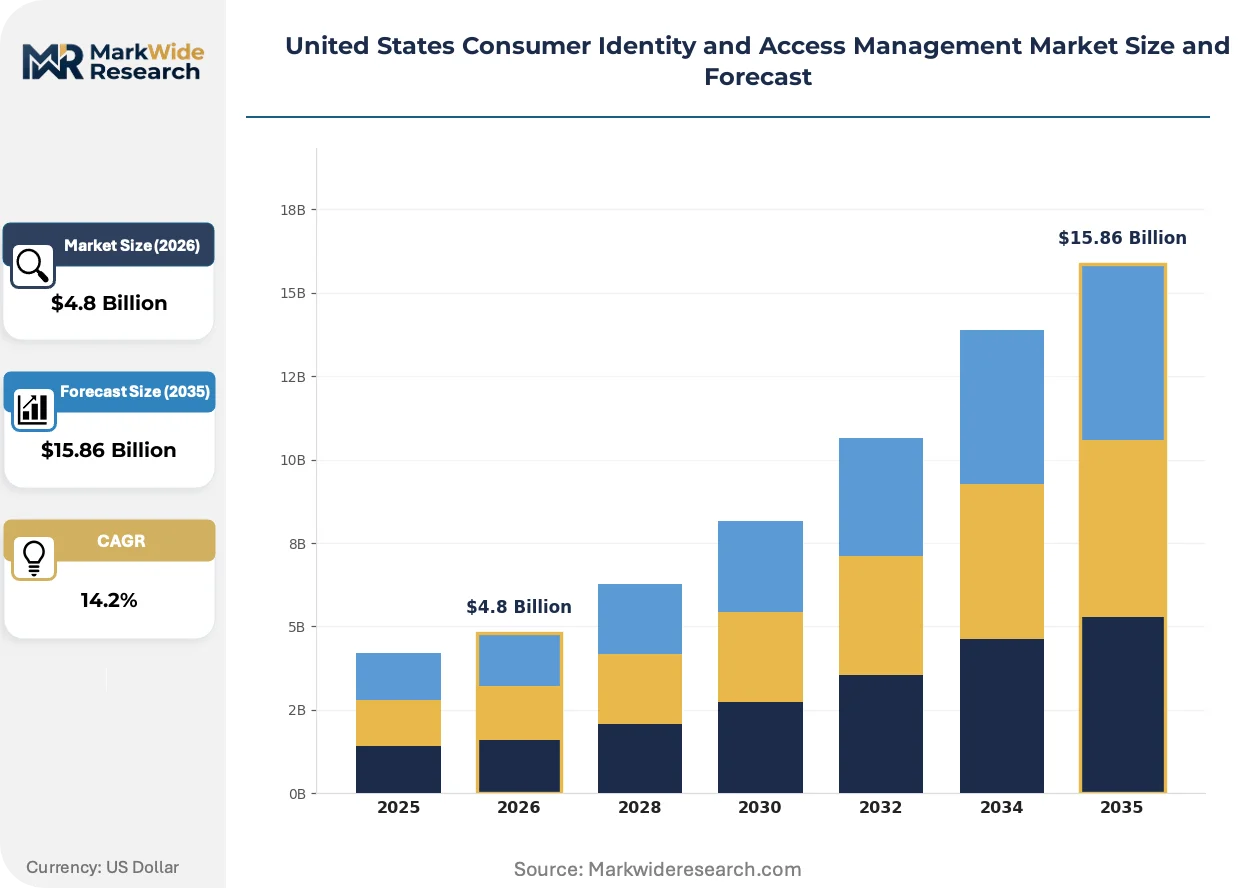
The United States Consumer Identity and Access Management Market is compressing around cloud-native deployment models as financial institutions dismantle legacy directory infrastructure in favor of API-based authentication services.
Growth Catalysts
- NIST Cybersecurity Framework Revisions:Federal contractors now face mandatory phishing-resistant authentication requirements that accelerate procurement of FIDO2-compliant identity platforms.
- California Consumer Privacy Act Enforcement:The Attorney General's data retention mandates compel enterprises to implement automated identity lifecycle management with deletion protocols.
- Biometric Verification Adoption:Banking applications are integrating behavioral analytics and facial recognition to reduce synthetic identity fraud in digital onboarding workflows.
Market Restraints
- Cloud Concentration Risk:Identity platform dependence on hyperscale infrastructure in Northern Virginia and Oregon data centers creates single-point-of-failure exposure.
- Legacy System Integration Friction:Mainframe-based core banking systems require costly middleware development to connect with modern OAuth protocols.
- Skill Scarcity in Zero-Trust Architecture:Enterprises face 14-month average hiring timelines for identity engineers certified in continuous authentication frameworks.
Strategic Opportunities
- Texas and Florida Healthcare Expansion:Patient portal mandates under HIPAA Security Rule create greenfield demand for identity governance in Sun Belt hospital networks.
- Open Banking Identity Verification:Federal Reserve guidance on digital identity standards for financial data sharing opens API monetization pathways.
- Passwordless Convergence:FIDO2 and WebAuthn standards are hybridizing with mobile device biometrics to eliminate credential-based attack surfaces.
Industry Challenges
- Multi-Vendor Orchestration Complexity:Enterprises struggle to synchronize identity flows across separate workforce and consumer IAM instances without creating security gaps.
- Consent Management Engineering:CCPA and emerging state privacy laws require real-time preference centers that most legacy identity stacks cannot support without rebuild.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Consumer Identity and Access Management Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, Managed Services End User: E-commerce, Banking, Telecom, Healthcare Solution: Multi-factor Authentication, Single Sign-On, Identity Governance, Access Management Integration Level: API-based, LDAP, SAML, OAuth |
| Companies Covered | Microsoft Corporation, IBM Corporation, Salesforce Inc., SAP SE, Okta, Ping Identity, ForgeRock, Akamai Technologies, LoginRadius Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Consumer Identity and Access Management Market Evolving Landscape
Authentication architectures are fragmenting across device-bound and cloud-resident credentials as vendors race to eliminate passwords entirely from consumer-facing workflows.
Decentralized identity wallets are hybridizing verifiable credentials with mobile operating system security enclaves. Regional banks in the Midwest are piloting these architectures for account recovery scenarios. This convergence is compressing traditional identity provider margins by shifting trust verification to device manufacturers.
The FTC's updated Safeguards Rule now mandates multi-factor authentication for all financial institutions handling customer information. Compliance deadlines are forcing mid-market credit unions to abandon SMS-based one-time passwords. California-based fintechs are responding fastest, deploying hardware security key programs for high-net-worth account tiers.
Subscription-based identity verification is displacing perpetual licensing in enterprise procurement cycles. E-commerce platforms in the Northeast are unbundling fraud detection from core identity services, purchasing verification events on consumption metrics. This shift is most visible among direct-to-consumer brands scaling internationally without building captive identity engineering teams.
United States Consumer Identity and Access Management Market Segmentation
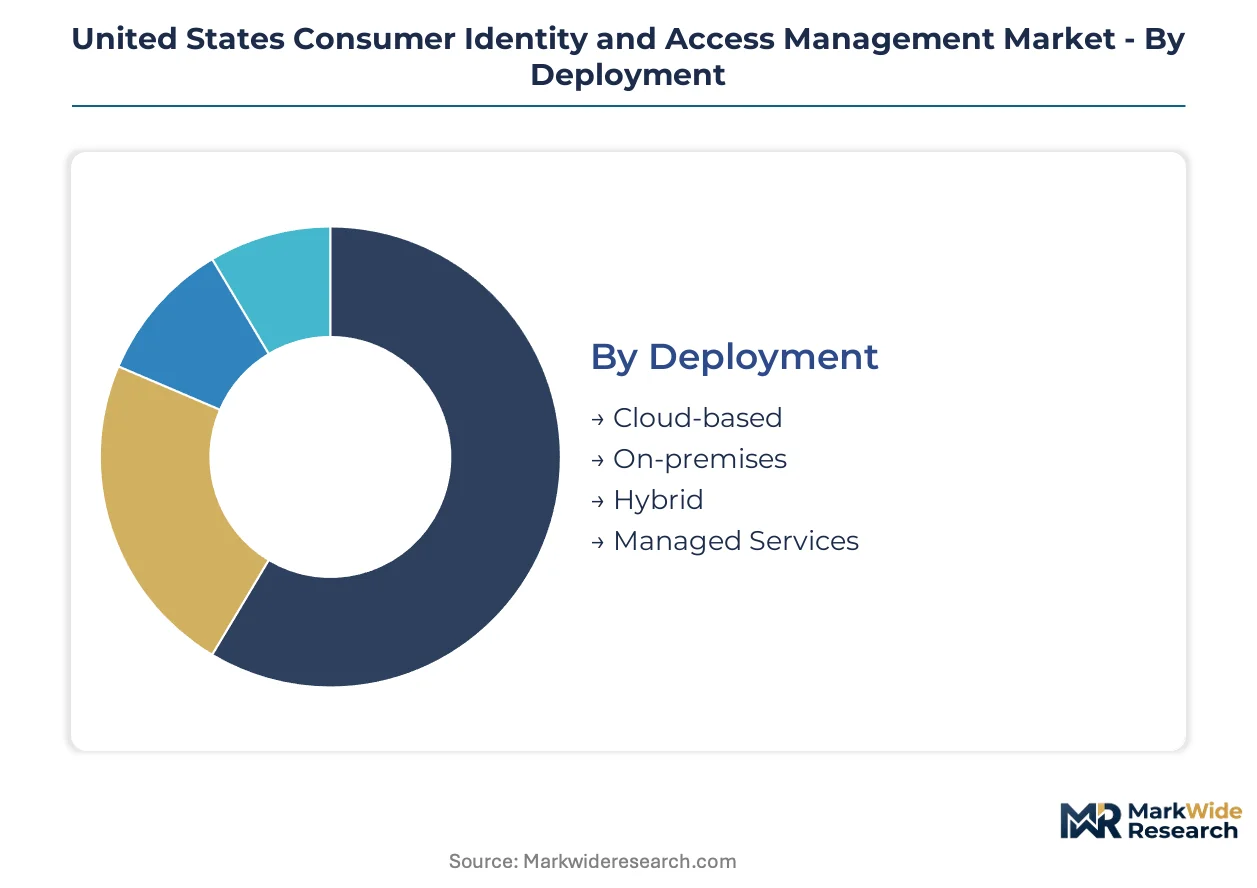
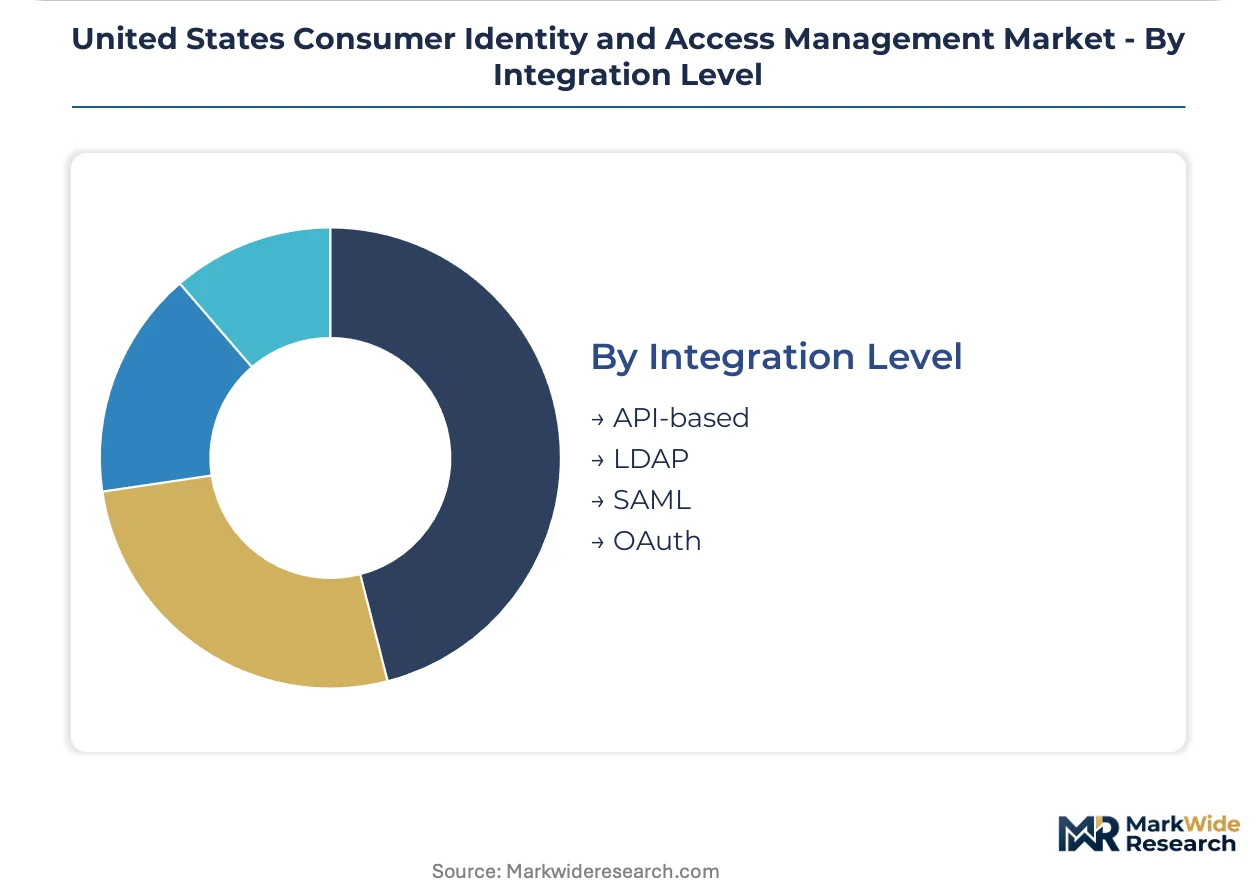
Segmentation in the United States Consumer Identity and Access Management Market reveals divergent technology requirements across deployment architectures, regulatory-sensitive end users, and integration protocols. Each dimension carries distinct procurement patterns and compliance obligations that shape vendor positioning.
Deployment:
Cost tier determines infrastructure ownership models and operational overhead trajectories for identity platform consumption.
- Cloud-based:Fully managed identity services delivered through hyperscale infrastructure eliminate capital expenditure for directory hardware. Financial institutions in California's technology corridor favor these deployments for elastic capacity during enrollment spikes. The NIST cybersecurity framework revisions accelerate migration away from self-managed alternatives.
- On-premises:Dedicated identity infrastructure residing within enterprise data centers retains appeal for classified federal contractor environments. Defense sector procurement mandates in Northern Virginia sustain this segment despite higher total cost of ownership. Air-gapped deployments satisfy the most stringent data residency requirements.
- Hybrid:Split architectures combining cloud directory services with on-premises authentication gateways serve regulated healthcare networks. Texas hospital systems deploy these configurations to segment patient portal access from internal clinical systems.
- Managed Services:Outsourced identity operations where third-party providers assume full platform administration burden. Mid-market credit unions in the Midwest contract these arrangements to address skill scarcity in zero-trust engineering.
Cloud-based deployments command the established base. The steepest expansion runs through hybrid configurations bridging legacy and modern architectures.
End User:
Application context drives authentication complexity, with fraud exposure and regulatory density varying sharply across sectors.
- Banking:Digital channels for deposit accounts, lending platforms, and wealth management require phishing-resistant credential protocols. The FTC Safeguards Rule mandates multi-factor authentication for all customer information handling. California fintechs deploy hardware security keys fastest among this cohort.
- E-commerce:Transactional identity verification prioritizes friction reduction alongside fraud prevention. Direct-to-consumer brands in the Northeast unbundle verification services, purchasing on consumption metrics rather than perpetual licenses.
- Healthcare:Patient portal access controls governed by HIPAA Security Rule requirements for audit trails and session termination. Florida hospital networks represent greenfield demand as patient engagement mandates expand.
- Telecom:Subscriber identity management for mobile and broadband services with high-volume provisioning workflows. Account takeover protection integrates with device recognition across carrier ecosystems.
Banking retains the largest installed base. E-commerce represents the fastest-climbing trajectory as subscription verification models displace traditional licensing.
Solution:
Functional maturity separates established identity governance from emerging authentication modalities competing for security budget allocation.
- Single Sign-On:Centralized session management enabling consumers to access multiple applications through one authenticated credential. E-commerce and banking platforms maintain the deepest deployments of this longest-tenured solution category.
- Multi-factor Authentication:Layered verification combining passwords with device possession or biometric confirmation. The FTC's updated mandates are forcing abandonment of SMS-based one-time passwords across financial institutions.
- Identity Governance:Lifecycle management encompassing provisioning, access certification, and automated deactivation. This most mature category exhibits durable renewal rates despite slower expansion velocity.
- Access Management:Policy enforcement and session monitoring for real-time authorization decisions. Behavioral analytics integration distinguishes next-generation offerings from legacy web access control.
Single Sign-On holds the deepest entrenchment. Multi-factor Authentication is expanding most quickly as regulatory deadlines compel infrastructure refresh.
Integration Level:
Technical protocol selection determines interoperability scope and developer resource requirements for identity system connectivity.
- API-based:RESTful and GraphQL interfaces enabling programmatic identity operations without proprietary middleware. Cloud-native platforms standardize on these patterns for mobile and web application integration.
- OAuth:Token-based authorization framework delegating access rights without credential exposure. Open banking initiatives under Federal Reserve guidance are accelerating OAuth adoption for financial data sharing scenarios.
- SAML:XML-based federation protocol for enterprise application single sign-on. Legacy SaaS integrations and government systems sustain SAML relevance despite newer alternatives.
- LDAP:Directory access protocol connecting authentication requests to hierarchical user repositories. Mainframe-based core banking systems in the Northeast retain LDAP dependencies requiring costly middleware bridges.
API-based integration commands dominant positioning for new deployments. OAuth is gaining share fastest as open banking standards mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across domestic markets. Mid-market credit unions in the Midwest resist premium identity platforms while California fintechs absorb higher costs for hardware security key programs. Texas hospital systems occupy the middle ground, balancing compliance mandates against constrained IT budgets.
California
Silicon Valley technology corridors generate concentrated demand for cloud-native identity platforms serving enterprise clients. The state's Attorney General enforces Consumer Privacy Act data retention mandates that compel automated identity lifecycle management. San Francisco-based fintechs deploy hardware security keys fastest among domestic banking cohorts.
Texas
Patient portal mandates under HIPAA Security Rule create greenfield demand across Sun Belt hospital networks. State medical privacy regulations extend federal requirements for audit trails and session termination protocols. Dallas-Fort Worth health systems deploy hybrid architectures segmenting patient access from internal clinical infrastructure.
New York Metro
Legacy financial institutions dismantle on-premises directory infrastructure for API-based authentication services. New York State Department of Financial Services cybersecurity regulations impose multi-factor authentication requirements for banking licensees. Manhattan-based wealth managers pioneer risk-based authentication protocols for high-net-worth account tiers.
Florida
Healthcare sector adoption accelerates as patient engagement mandates expand across hospital networks. State-level medical privacy statutes align with federal HIPAA requirements for portal access controls. Miami-Dade hospital systems represent emerging demand for identity governance solutions in the Southeast corridor.
Northern Virginia
Defense sector procurement mandates sustain on-premises deployments for classified federal contractor environments. NIST cybersecurity framework revisions require phishing-resistant authentication for government suppliers. Fairfax County data centers concentrate hyperscale identity infrastructure creating single-point-of-failure exposure concerns.
United States Consumer Identity and Access Management Market Competitive Landscape
Capability concentration sits with specialized identity vendors; scale advantage sits with cloud platform incumbents. The vendor base organizes around three strategic archetypes: hyperscale platform providers leveraging existing enterprise relationships, pure-play identity specialists competing on protocol depth, and managed service operators addressing mid-market skill gaps. Dominant competitive moves include API ecosystem expansion and consumption-based pricing model transitions.
Within the hyperscale tier, Microsoft Corporation anchors enterprise-consumer hybrid deployments through its Azure directory ecosystem. Okta occupies a position exemplifying extensive third-party application integration strategies. Ping Identity represents risk-based authentication specialization for financial services positioning. These three vendors illustrate divergent paths for sustaining developer loyalty and procurement preference in regulated environments.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Salesforce Inc. |
| SAP SE |
| Okta |
| Ping Identity |
| ForgeRock |
| Akamai Technologies |
| LoginRadius Inc. |
| Others |
Value Network & Pricing Analysis
Hyperscale cloud concentration in Northern Virginia and Oregon data centers creates single-point-of-failure exposure that compresses pricing spreads between premium managed services and economy self-hosted tiers while forcing buyers toward redundant multi-cloud supply configurations. This infrastructure chokepoint simultaneously elevates subscription pricing for high-availability deployments and accelerates migration away from capital-intensive on-premises alternatives.
Pricing Analysis
Consumption-based verification event pricing drives lifetime value as e-commerce platforms unbundle fraud detection from core identity services. Three-tier pricing structure across premium managed identity, standard SaaS, and economy API-only levels differentiates by service-level guarantees and compliance certification depth. Pricing pressure stems from hyperscaler bundling of basic identity functions with cloud infrastructure contracts. Mid-market credit unions in the Midwest exhibit highest price sensitivity; California fintechs absorbing hardware security key programs show lowest.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn, Jabil, and Flex holding capacity for FIDO2 hardware security key production. Component sourcing draws from Taiwan for secure element chips, South Korea for biometric sensors, and China for printed circuit board assemblies. Single-source vulnerability in FIDO Alliance certification testing creates regulatory chokepoint risk for new vendor market entry. Distribution runs through direct hyperscaler marketplaces and value-added resellers serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around FIDO2 and WebAuthn standardization, where interoperability shifts trust verification toward device manufacturers and compresses traditional identity provider margins.
For Market Incumbents: Insulate enterprise-consumer hybrid deployments through deeper Azure Active Directory ecosystem integration and API marketplace expansion. Defensive consolidation requires acquiring specialized biometric verification startups before device manufacturers capture authentication trust layers. Vertical integration into behavioral analytics engines addresses emerging entrant pressure from AI-native fraud detection vendors.
For New Entrants and Emerging Players: Mid-market healthcare networks in Texas and Florida represent the most penetrable entry point given HIPAA Security Rule mandates and incumbent platform switching costs below banking verticals. Regional credit unions lacking zero-trust engineering talent offer greenfield consumption-based contracting opportunities. Go-to-market execution should anchor on managed service wrappers eliminating customer technical staffing requirements.
For Investors and Strategic Acquirers: The market sits at a standards-convergence phase that favors identity orchestration specialists bridging multi-vendor environments. Long-term viability over the coming decade rests on API ecosystem breadth and developer workflow integration depth. Acquisition targets should demonstrate FIDO2 certification completion and open banking OAuth deployment traction. Federal Reserve guidance publication on digital identity verification standards serves as the critical inflection signal to monitor.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure Active Directory ecosystem expansion anchors enterprise-consumer hybrid deployments for financial institutions. |
| Strategic Partnership | FIDO Alliance certification partnerships accelerate phishing-resistant authentication deployment across federal contractors. |
| Acquisition of Specialist Firm | Behavioral analytics engine purchases address AI-native fraud detection competition in digital onboarding workflows. |
| Geographic Expansion | Texas and Florida healthcare network penetration captures HIPAA-mandated patient portal identity governance demand. |
| Product Launch | Passwordless WebAuthn-native platforms eliminate credential-based attack surfaces for California fintech deployments. |
Research Methodology
A spread of perspectives from chief information security officers, identity platform engineers, healthcare IT directors, financial services compliance leads, and federal procurement officers converged on the working assumptions underlying this analysis. Primary interview intelligence combined with secondary validation against NIST cybersecurity framework documentation, FTC Safeguards Rule enforcement records, Federal Reserve guidance publications, and HIPAA Security Rule audit findings. Bottom-up deployment volume estimates triangulated against top-down security budget allocation surveys across banking, healthcare, and e-commerce verticals.
Demand-supply balance framing anchored the analytical approach across the projection horizon, modeling deployment architecture preferences, end-user regulatory exposure tiers, solution functional maturity levels, and integration protocol adoption patterns. CAGRs derived from segment-level growth rate synthesis weighted by installed base renewal velocity and greenfield procurement pipeline indicators. Identity verification event volume metrics and cloud infrastructure capex disclosures from hyperscale providers served as industry-specific forecast calibration inputs.
Macroeconomic conditions sit as an overlay; deviation in federal cybersecurity spending authorization levels and state-level privacy law enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding NIST framework revision implementation timelines and open banking regulatory finalization. Quarterly review of federal contractor authentication compliance deadlines and state Attorney General CCPA enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Devsecops Market
Security Software
Global Anti-Spam Software Market
Security Software
Security Testing Market
Security Software
Keystroke Dynamics Market
Security Software
Global Enterprise Data Loss Prevention Software Market
Security Software
Single Sign-On Market
Security Software
Door Phone Market
Security Software
Information Rights Management Market
Security Software
Online Background Check Market
Security Software
Network Security Appliance Market
Security Software
Global IMSI Catcher Market
Security Software
Identity-As-A-Service (Idaas) Market
Security Software
Mobile Data Protection Solutions and Services Market
Security Software
US and Latin America Identity and Access Management (IAM) Market
Security Software
ATM Security Market
Security Software
Social Media Security Market