
 Consumer Endpoint Security Market | 2026-2036
Consumer Endpoint Security Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Endpoint Security Market Analysis
Subscription renewal revenue is tilting toward AI-powered threat detection modules, displacing traditional signature-based antivirus renewals. McAfee Corp. leverages its retail channel presence to sustain recurring revenue from home office users. Kaspersky Lab anchors its competitive position through specialized behavioral analysis engines for consumer endpoints. Bitdefender LLC differentiates via machine learning-driven malware detection that operates across hybrid deployment environments.
Consumer endpoint security encompasses software and services deployed on individual devices—PCs, smartphones, tablets—to detect, prevent, and respond to cyber threats through real-time scanning, heuristic analysis, and automated remediation protocols. The primary purpose is to protect personal data, financial credentials, and identity assets from malware, ransomware, phishing, and unauthorized access across distributed computing environments. Antivirus software remains the largest revenue pool though margin compression pushes vendors toward endpoint detection and response bundles. Cloud-based deployment represents the fastest-expanding delivery mode as consumers prioritize automatic updates and cross-device synchronization without local infrastructure management.
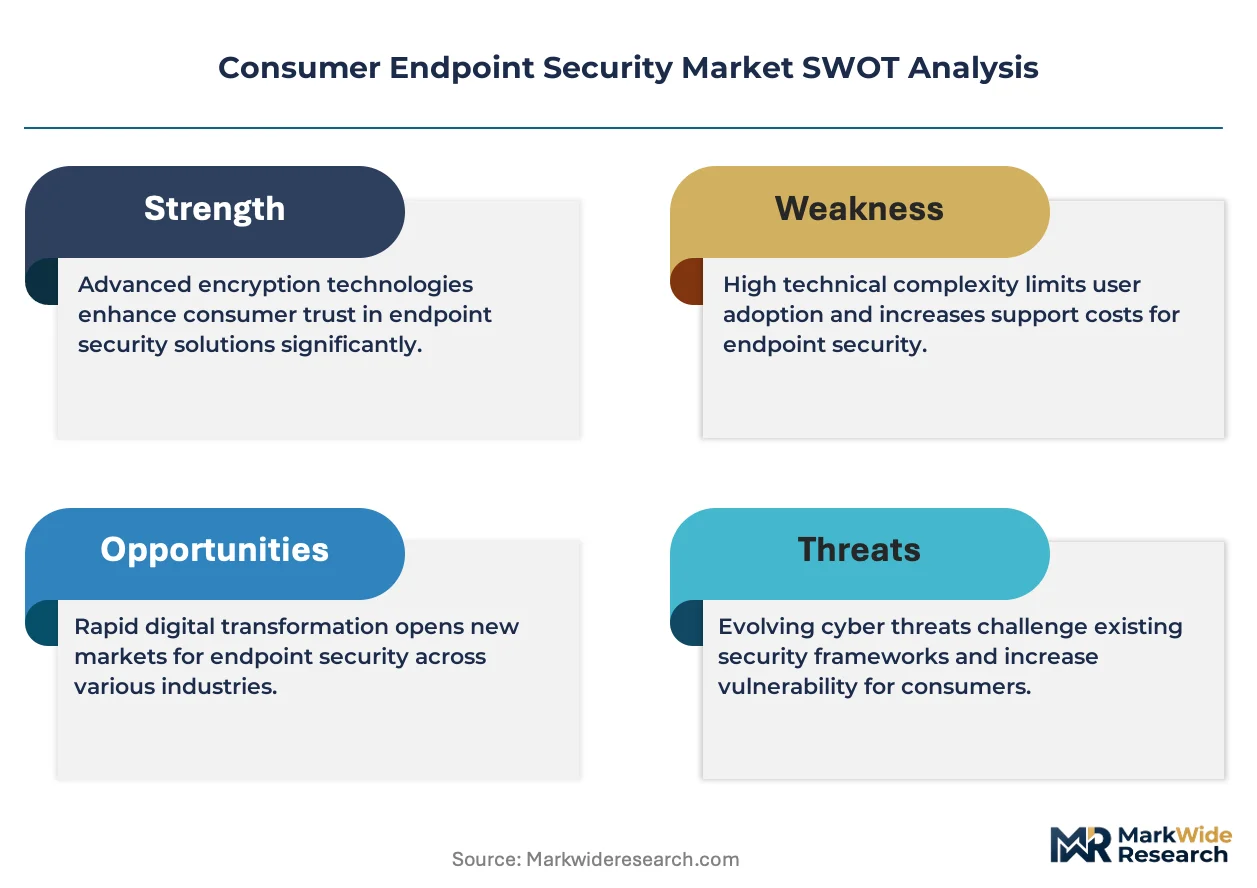
The Federal Trade Commission enforces data breach notification standards that shape product liability exposure for US consumer security vendors, while the EU AI Act imposes algorithmic transparency requirements on automated threat detection systems sold in European markets. ISO 27001 certification serves as a baseline trust signal for enterprise-adjacent consumer products targeting remote workers and home offices. Stakeholders must weigh the capital intensity of on-device AI inference against the latency and privacy advantages of edge-based protection architectures.
Market Dynamics
The migration of consumer endpoint protection toward edge-based AI inference architectures is compressing traditional signature-scanning revenue pools while elevating privacy-preserving deployment models. Vendors must now balance on-device computational intensity against latency-sensitive threat response requirements across distributed home office networks.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Automated threat detection systems sold in European markets face mandatory explainability requirements, accelerating demand for auditable machine learning pipelines and privacy-preserving endpoint architectures that satisfy GDPR cross-border data transfer rules.
- Remote worker household expansion:Distributed work normalization has created a durable buyer segment requiring enterprise-grade protection for personally-owned devices, with home office users seeking cross-device synchronization and automatic security updates without IT department oversight.
- Behavioral analysis engine maturation:Heuristic detection capabilities now identify zero-day exploits through device interaction patterns rather than known signatures, enabling proactive ransomware interception before payload execution.
Market Restraints
- On-device AI inference cost structure:Neural processing unit requirements for real-time threat analysis elevate hardware specifications for consumer-grade endpoints, compressing margins on entry-tier subscriptions.
- Cloud infrastructure supplier concentration:Cross-device synchronization and automatic update delivery depend on hyperscale hosting providers, creating single-point vulnerability for vendor service continuity.
- False positive rate technical limitation:Aggressive heuristic thresholds necessary for zero-day detection generate user friction through legitimate application blocking, elevating support costs and churn risk.
Strategic Opportunities
- Underpenetrated smart home device integration:IoT endpoints in residential environments lack standardized protection protocols, creating white space for unified security orchestration across routers, cameras, and voice assistants.
- ISO 27001 certification tailwind:Enterprise-adjacent consumer products targeting remote workers leverage baseline trust signals to differentiate from commodity antivirus offerings and justify premium positioning.
- Machine learning and confidential computing convergence:Privacy-preserving inference techniques enable threat analysis on encrypted device data without plaintext exposure, addressing GDPR data minimization requirements while maintaining detection efficacy.
Industry Challenges
- AI/ML security engineering talent scarcity:Adversarial robustness testing and model explainability implementation require specialized skill sets that command premium compensation, constraining vendor R&D scaling.
- FTC data breach notification compliance timeline:Product liability exposure under federal enforcement standards demands rapid incident response infrastructure investment, diverting capital from feature development.
- Legacy Windows antivirus integration complexity:Kernel-level hook architectures conflict with modern operating system security subsystems, forcing expensive codebase refactoring for platform compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Endpoint Security Market |
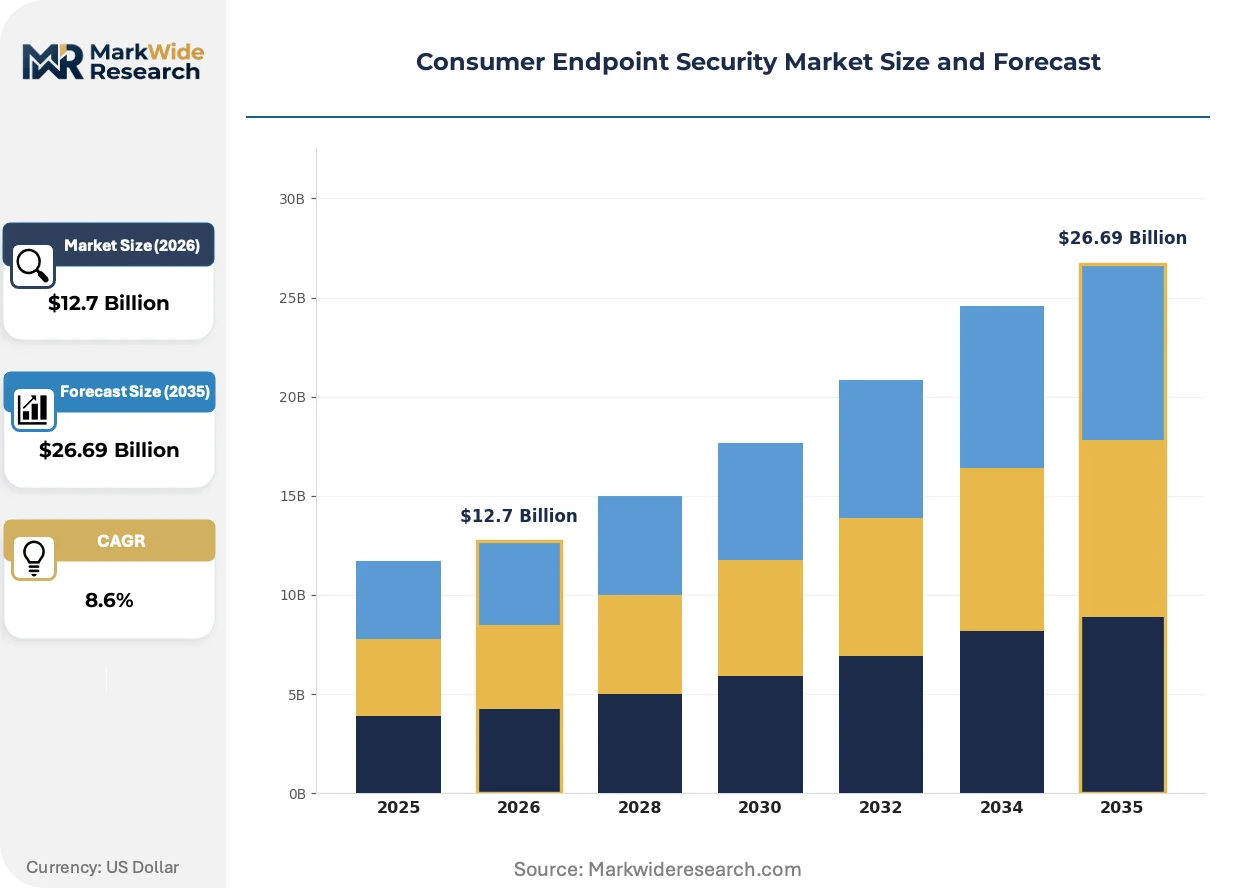
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $26.69 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirus Software, Firewall Solutions, Endpoint Detection & Response, Mobile Security Technology: Machine Learning, Behavioral Analysis, AI-Based Security, Threat Intelligence Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services Customer Type: Individual Consumers, Home Offices, Small Businesses, Remote Workers |
| Companies Covered | Gen Digital Inc., McAfee Corp., Kaspersky Lab, Trend Micro Incorporated, Bitdefender LLC, Avast Software s.r.o., ESET, spol. s r.o., Sophos Group plc, F-Secure Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Endpoint Security Market Emerging Trajectories
Endpoint security architectures are fragmenting across deployment models as consumer expectations diverge between transparency-demanding privacy advocates and convenience-seeking mainstream users. Technical differentiation now centers on where threat intelligence processing occurs rather than detection signature breadth.
On-device neural inference engines are hybridizing consumer protection architectures by distributing machine learning workloads between local silicon and cloud backends. Privacy-conscious remote workers in Germany and France prioritize edge-based analysis that prevents telemetry transmission to foreign jurisdictions. This bifurcation is compressing pure-cloud vendor margins while rewarding hybrid deployment flexibility.
The EU AI Act's risk classification framework for biometric and behavioral analysis systems is mandating conformity assessments for automated threat detection sold in European markets. Vendors must now document training data provenance and algorithmic decision logic to obtain CE marking for high-risk AI applications. Home office segments with cross-border data exposure face the steepest compliance cost escalation.
Subscription bundling patterns among remote worker households now favor consolidated protection across personal laptops, mobile devices, and home network infrastructure. Traditional single-device antivirus renewals face displacement by family-tier endpoint detection and response packages with centralized policy management. This consolidation is most visible in United States metropolitan markets where distributed employment density remains highest.
Consumer Endpoint Security Market Segmentation
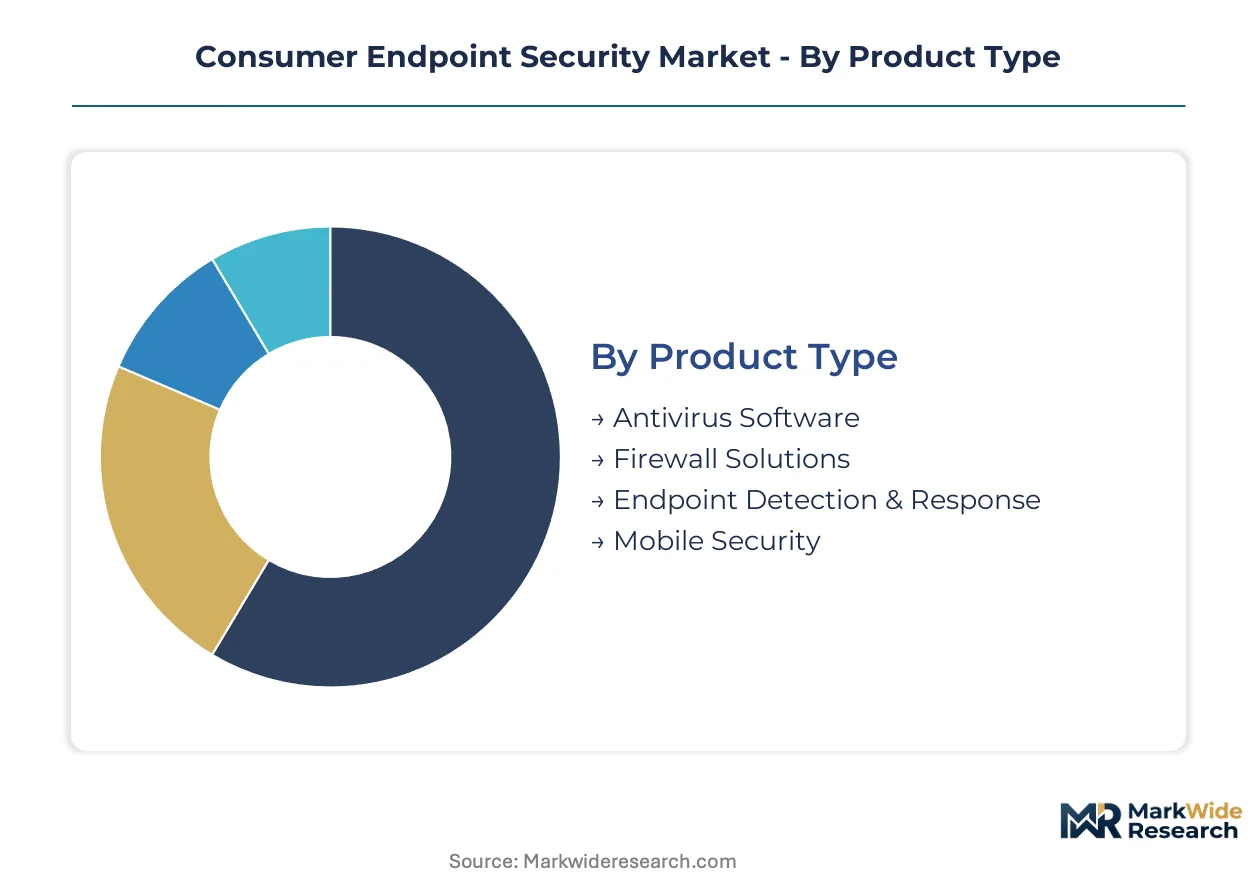
Consumer endpoint security vendors must align product architecture with distinct threat surfaces across device types, processing models, and user sophistication levels. Segmentation reveals where subscription economics favor premium AI-powered bundles over legacy signature-based renewals.
Product Type:
Application focus determines margin structure, with detection sophistication commanding tiered pricing premiums against commodity scanning utilities.
- Antivirus Software:Signature-based malware scanning remains the largest revenue pool despite margin compression from free alternatives. Home office users in the United States sustain renewal rates through bundled identity protection add-ons.
- Endpoint Detection & Response:Real-time behavioral monitoring and automated threat containment now displace traditional antivirus in remote worker households seeking enterprise-grade protection without IT department oversight. EDR bundles capture the steepest expansion trajectory as distributed work normalizes.
- Firewall Solutions:Network-level traffic filtering integrates with home router infrastructure to block unauthorized access attempts before endpoint penetration.
- Mobile Security:Application sandboxing and phishing link detection address smartphone-specific attack vectors including malicious sideloading and SMS-based social engineering.
Antivirus Software holds installed capacity. Endpoint Detection & Response is rotating up the share rankings.
Technology:
Processing methodology separates premium positioning from commodity offerings, with inference location and explainability emerging as regulatory compliance differentiators.
- AI-Based Security:Neural networks trained on global threat telemetry enable zero-day detection without signature updates. Vendors selling into European markets face EU AI Act algorithmic transparency mandates requiring documented decision logic for automated blocking actions.
- Behavioral Analysis:Device interaction pattern recognition identifies ransomware pre-execution through anomalous file system access sequences. Kaspersky Lab anchors competitive positioning through specialized behavioral engines for consumer endpoints.
- Machine Learning:Lightweight models optimized for edge inference reduce cloud dependency while satisfying GDPR data minimization requirements in France and Germany.
- Threat Intelligence:Real-time indicator feeds from global sensor networks accelerate threat identification but create cross-border data transfer compliance exposure under European privacy frameworks.
Behavioral Analysis holds installed capacity. AI-Based Security is rotating up the share rankings.
Deployment:
Infrastructure location shapes operational overhead, latency characteristics, and regulatory jurisdiction for data processing activities.
- Cloud-Based:Centralized threat intelligence processing enables cross-device synchronization and automatic model updates without user intervention. Remote worker households prioritize this delivery mode for seamless protection across distributed personal devices.
- Hybrid:Distributed inference architectures balance on-device analysis for sensitive data against cloud aggregation for complex threat correlation. Privacy-conscious users in Germany and France favor this model to prevent telemetry transmission to foreign jurisdictions.
- On-Premises:Local-only processing satisfies air-gapped security requirements for high-sensitivity home office environments with strict data residency constraints.
- Managed Services:Outsourced monitoring and response offloads technical complexity to vendor security operations centers, appealing to small businesses lacking dedicated IT personnel.
Cloud-Based holds installed capacity. Hybrid is rotating up the share rankings.
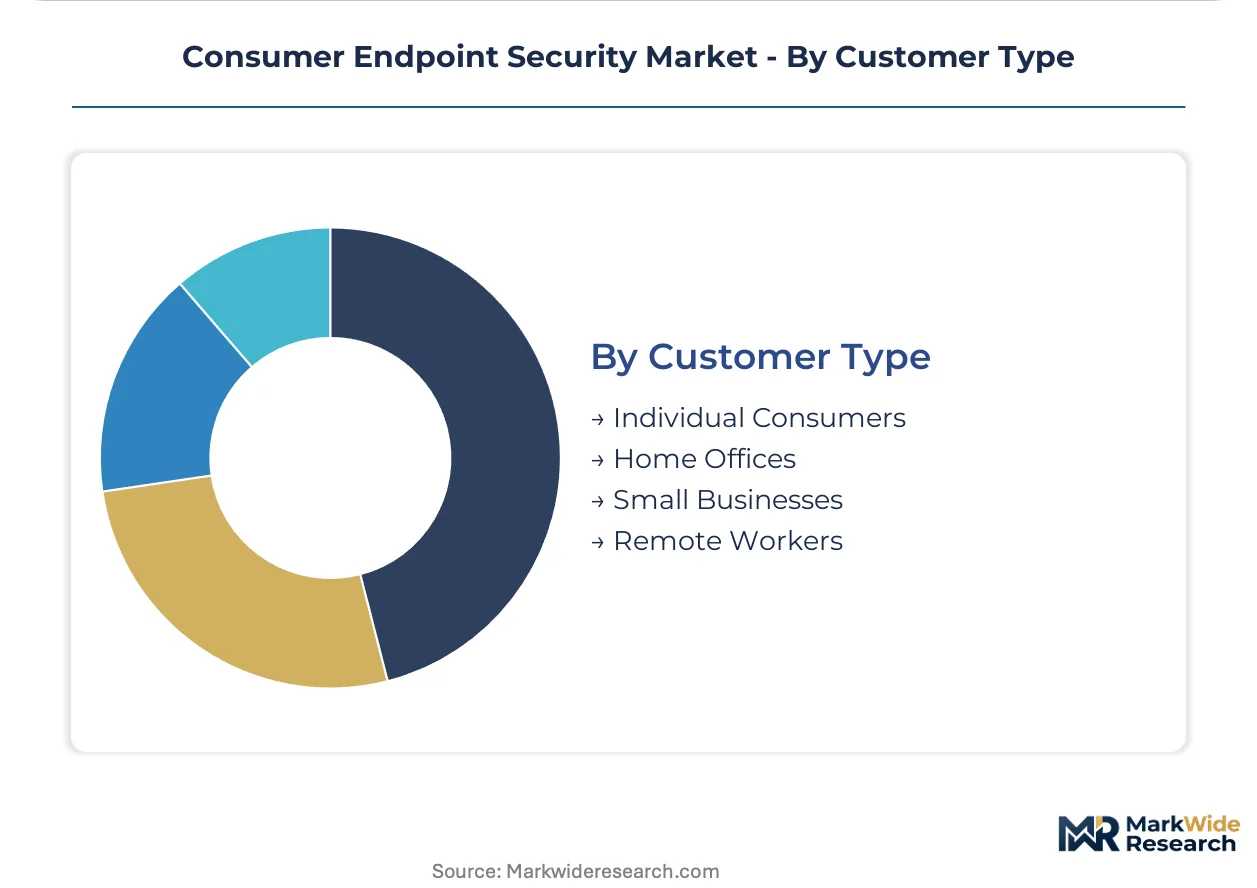
Customer Type:
User sophistication and device count drive packaging economics, from single-device consumers to multi-endpoint household orchestration.
- Remote Workers:Enterprise-adjacent consumers require cross-platform protection for personally-owned laptops, tablets, and smartphones used for professional activities. ISO 27001 certification serves as a baseline trust signal justifying premium positioning in this segment.
- Home Offices:Dedicated workspace setups with network infrastructure integration demand router-level protection alongside endpoint agents. FTC data breach notification standards shape product liability exposure for vendors targeting United States home office users.
- Individual Consumers:Single-device protection with minimal configuration overhead dominates this price-sensitive tier, though churn rates exceed multi-device household subscriptions.
- Small Businesses:Five-to-fifty employee organizations without dedicated security staff seek centralized policy management across heterogeneous device fleets.
Individual Consumers holds installed capacity. Remote Workers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States households prioritize cross-device subscription bundles with automatic updates, while European users demand edge-based processing that satisfies data residency requirements. Asian markets show mixed preferences, with developed economies favoring premium EDR tiers and emerging markets remaining price-sensitive on single-device antivirus.
United States
Remote worker density and enterprise-adjacent home office setups drive demand for family-tier endpoint detection and response packages. FTC data breach notification standards shape vendor product liability exposure and incident response infrastructure investment. Metropolitan clusters in California, Texas, and the Northeast Corridor concentrate cybersecurity spending as distributed employment normalizes across technology and financial services sectors.
Germany
Privacy-conscious consumers in Bavaria and North Rhine-Westphalia prioritize hybrid deployment models that prevent telemetry transmission to foreign jurisdictions. GDPR cross-border data transfer rules and the EU AI Act's algorithmic transparency mandates elevate compliance costs for automated threat detection systems. Berlin-Brandenburg hosts emerging vendors specializing in confidential computing architectures for privacy-preserving inference.
United Kingdom
ISO 27001 certification serves as a baseline trust signal for remote worker segments seeking enterprise-grade protection without IT department oversight. The Information Commissioner's Office enforces data minimization principles that favor on-device processing over cloud aggregation. London and the Southeast concentrate demand for multi-device household orchestration with centralized policy management capabilities.
France
CNIL guidance on automated decision-making creates regulatory headwinds for AI-powered blocking systems without documented explainability. Île-de-France and Auvergne-Rhône-Alpes anchor demand for behavioral analysis engines that identify ransomware pre-execution through anomalous file system patterns. French consumers show above-average willingness to pay for premium tiers that guarantee data remains within EU jurisdictions.
Japan
Kanto and Kansai regions exhibit strong preference for managed services that offload technical complexity to vendor security operations centers. METI cybersecurity frameworks encourage adoption of advanced endpoint protection among small businesses lacking dedicated security personnel. Japanese consumers demonstrate lower churn tolerance for false positives, elevating vendor investment in heuristic threshold calibration.
Consumer Endpoint Security Market Vendor Landscape
Capability concentration sits with specialized behavioral analysis vendors; scale advantage sits with diversified cybersecurity platforms with retail channel presence. The market exhibits tiered structure with premium AI-powered bundles displacing commodity signature-based offerings. Three archetypes dominate: cloud-native platforms with automatic update infrastructure, hybrid deployment specialists with edge inference expertise, and retail-anchored vendors with recurring revenue from home office segments. Competitive moves center on portfolio diversification into IoT protection and strategic partnerships with router manufacturers for network-level integration.
Within the specialized behavioral analysis tier, Kaspersky Lab exemplifies engineering depth in heuristic detection for consumer endpoints. McAfee Corp. occupies a position among retail-anchored platforms sustaining recurring revenue through physical channel presence. Bitdefender LLC represents hybrid deployment flexibility with machine learning architectures operating across cloud and edge environments.
| Leading Market Players |
|---|
| Gen Digital Inc. |
| McAfee Corp. |
| Kaspersky Lab |
| Trend Micro Incorporated |
| Bitdefender LLC |
| Avast Software s.r.o. |
| ESET, spol. s r.o. |
| Sophos Group plc |
| F-Secure Corporation |
| Others |
Supply Flow & Price Mechanics
Tariff exposure between the United States and China on semiconductor components determines both pricing tier spreads and supply chain shape in consumer endpoint security, compressing margins on AI-enabled tiers while forcing vendors toward diversified silicon sourcing strategies. Neural processing unit dependencies in edge-inference architectures amplify cost differentials between premium behavioral analysis bundles and commodity signature-based subscriptions.
Pricing Analysis
Long-term subscription contracts dominate the consumer endpoint security market, with annual and multi-year SaaS tiers capturing recurring revenue from remote worker households while monthly plans serve price-sensitive individual consumers. Three-tier pricing structure across premium, standard, and economy levels reflects detection sophistication, with AI-powered EDR bundles commanding premiums over legacy antivirus. Cost compression in entry-tier subscriptions is intensifying because free alternatives from operating system vendors displace paid signature-based products. Individual consumers exhibit highest price sensitivity, while ISO 27001-certified enterprise-adjacent remote workers accept premium positioning for cross-device orchestration.
Supply Chain Analysis
Single-source vulnerability in cloud infrastructure supplier concentration dominates supply chain risk for consumer endpoint security vendors dependent on hyperscale hosting providers for cross-device synchronization and automatic model updates. Taiwan, South Korea, and the United States anchor neural processing unit and advanced semiconductor supply for on-device AI inference. Raw material dependencies span silicon wafers, specialized ASICs, and high-bandwidth memory modules. Distribution runs through retail channel partnerships, direct-to-consumer digital storefronts, and OEM pre-installation agreements with device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The consumer endpoint security market sits at a platform-economics inflection where router-integrated protection and IoT orchestration capabilities determine ecosystem lock-in, with interoperability standards across smart home devices reshaping competitive boundaries.
For Market Incumbents: Insulate recurring revenue streams by deepening backward integration into confidential computing architectures that satisfy GDPR data minimization requirements in Germany and France. Prioritize ISO 27001 certification investment to differentiate enterprise-adjacent offerings from commodity antivirus facing margin erosion. Control retail channel positioning against cloud-native entrants lacking physical presence in United States metropolitan markets. For New Entrants and Emerging Players: Pursue underpenetrated smart home device integration as the most accessible white space, targeting router manufacturers and voice assistant platforms lacking standardized protection protocols. Enter through hybrid deployment specialization addressing privacy-conscious remote workers in European jurisdictions with strict data residency constraints. Leverage machine learning explainability tooling as a go-to-market angle for EU AI Act compliance positioning. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors behavioral analysis engineering depth over scale-driven platform breadth. Long-term viability hinges on edge inference expertise and regulatory compliance infrastructure across multiple jurisdictions. Target acquisition profiles center on specialized vendors with proven adversarial robustness testing capabilities. The signal to watch is FTC enforcement intensity on data breach notification timelines, which will accelerate capital requirements for incident response infrastructure and favor scaled players.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Architecture Development | Privacy-preserving inference satisfies GDPR requirements in France and Germany while maintaining detection efficacy. |
| Router Manufacturer Partnership | Network-level integration captures smart home protection white space before standardized protocols emerge. |
| ISO 27001 Certification Investment | Baseline trust signal justifies premium positioning among enterprise-adjacent remote worker segments. |
| EU AI Act Compliance Tooling | Documented algorithmic explainability enables CE marking for automated threat detection in European markets. |
| Behavioral Analysis Engine Acquisition | Heuristic detection depth differentiates against commodity signature-based competitors facing renewal displacement. |
Methodological Framework
Desk research of regulatory filings from the FTC and European Commission, patent databases, and hyperscaler infrastructure disclosures preceded structured interviews with CISOs at distributed enterprises, consumer security product managers, channel partners at retail distributors, and compliance officers navigating EU AI Act implementation. Primary fieldwork with behavioral analysis engineering teams and cloud security architects validated technical assumptions about edge inference cost structures. Secondary sources included SEC 10-K filings from publicly traded cybersecurity vendors, customs records on semiconductor component trade flows, and ISO certification registry data. Bottom-up subscription revenue modeling triangulated against top-down market sizing from device shipment correlations.
Assumptions around remote worker household expansion rates, EU AI Act enforcement timelines, and neural processing unit cost curves were held fixed across baseline scenarios while cloud infrastructure concentration risk and false positive tolerance thresholds were stress-tested under alternative projections. Segmentation dimensions modeled spanned deployment architecture, detection technology methodology, customer sophistication tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to observable subscription renewal patterns and EDR bundle penetration trajectories. Forecast inputs incorporated adversarial robustness testing maturity curves and confidential computing hardware availability roadmaps from Taiwanese foundry partners.
Sensitivities concentrate around FTC data breach notification enforcement intensity, EU AI Act conformity assessment bottlenecks, and hyperscale hosting provider consolidation events that could disrupt cross-device synchronization services. Forecasts reflect documented assumptions about distributed work normalization durability and consumer willingness to pay for privacy-preserving architectures. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Dynamic Application Security Testing Market
Security Software
US Hardware Encryption Market
Security Software
Secure Digital Card Market
Security Software
Private Virtual Communications for Police Network Market
Security Software
Asia-Pacific Fraud Detection & Prevention Market
Security Software
Mobile Identity Management Market
Security Software
Security Software for Consumers Market
Security Software
Cloud Data Loss Prevention Solution Market
Security Software
Key Management Service Market
Security Software
Global Hardware Security Modules (HSM) Market
Security Software
Global Data Classification Market
Security Software
Endpoint Detection and Response [EDR] Market
Security Software
Embedded Security Market
Security Software
Global Anti-Spam Software Market
Security Software
Social Media Security Market
Security Software
Europe Smart Doorbell Market