
 Anomaly Detection Tools Market | 2026-2036
Anomaly Detection Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Anomaly Detection Tools Market Outlook
A shortage of data scientists fluent in unsupervised learning architectures is redrawing competitive boundaries across the anomaly detection tools landscape. IBM sustains deep research partnerships with academic institutions to secure pipeline access to PhD-level talent in statistical signal processing. Elastic leverages its open-source community to crowdsource anomaly detection algorithm improvements without comparable payroll expansion. Splunk dominates the security information and event management channel, giving it privileged distribution into enterprise security operations centers.
Anomaly detection tools are software systems that apply statistical, machine learning, or rule-based algorithms to identify patterns in data that deviate from established baselines, typically processing time-series metrics, log files, or event streams with sub-second latency requirements for operational alerting. These tools serve industrial and commercial users by flagging equipment failures, fraudulent transactions, or network intrusions before cascading damage occurs. Cloud-based deployment now captures the fastest expansion as organizations retire capital-intensive on-premises data centers, while machine learning technology commands the highest margin pools due to specialized GPU infrastructure requirements. Edge computing deployment remains nascent but is gaining traction in manufacturing predictive maintenance applications where millisecond response times matter.
The EU AI Act imposes conformity assessment obligations on high-risk automated monitoring systems, directly shaping product development roadmaps for vendors serving European financial services and healthcare providers. In the United States, NIST's AI Risk Management Framework and the SEC's cybersecurity disclosure rules are pushing publicly traded companies toward auditable anomaly detection capabilities. Stakeholders must weigh regulatory compliance costs against the competitive disadvantage of lagging detection sophistication as attack surfaces multiply across hybrid infrastructure.
Market Dynamics
The EU AI Act is forcing vendors to re-engineer algorithmic transparency into real-time monitoring systems, while cloud migration accelerates demand for sub-second latency architectures. This dual pressure is compressing product development cycles and redrawing competitive boundaries across deployment modes.
Growth Catalysts
- Algorithmic Accountability Mandates:The EU AI Act imposes conformity assessment obligations on high-risk automated monitoring systems, compelling financial services and healthcare providers to upgrade legacy detection infrastructure.
- Industrial Predictive Maintenance:Germany's automation corridor is driving edge-computing deployments where millisecond response times prevent cascading equipment failures in automotive and semiconductor fabrication.
- GPU Infrastructure Proliferation:Specialized machine learning hardware is lowering the barrier for unsupervised learning implementations in mid-market enterprises previously priced out of advanced anomaly detection.
Market Restraints
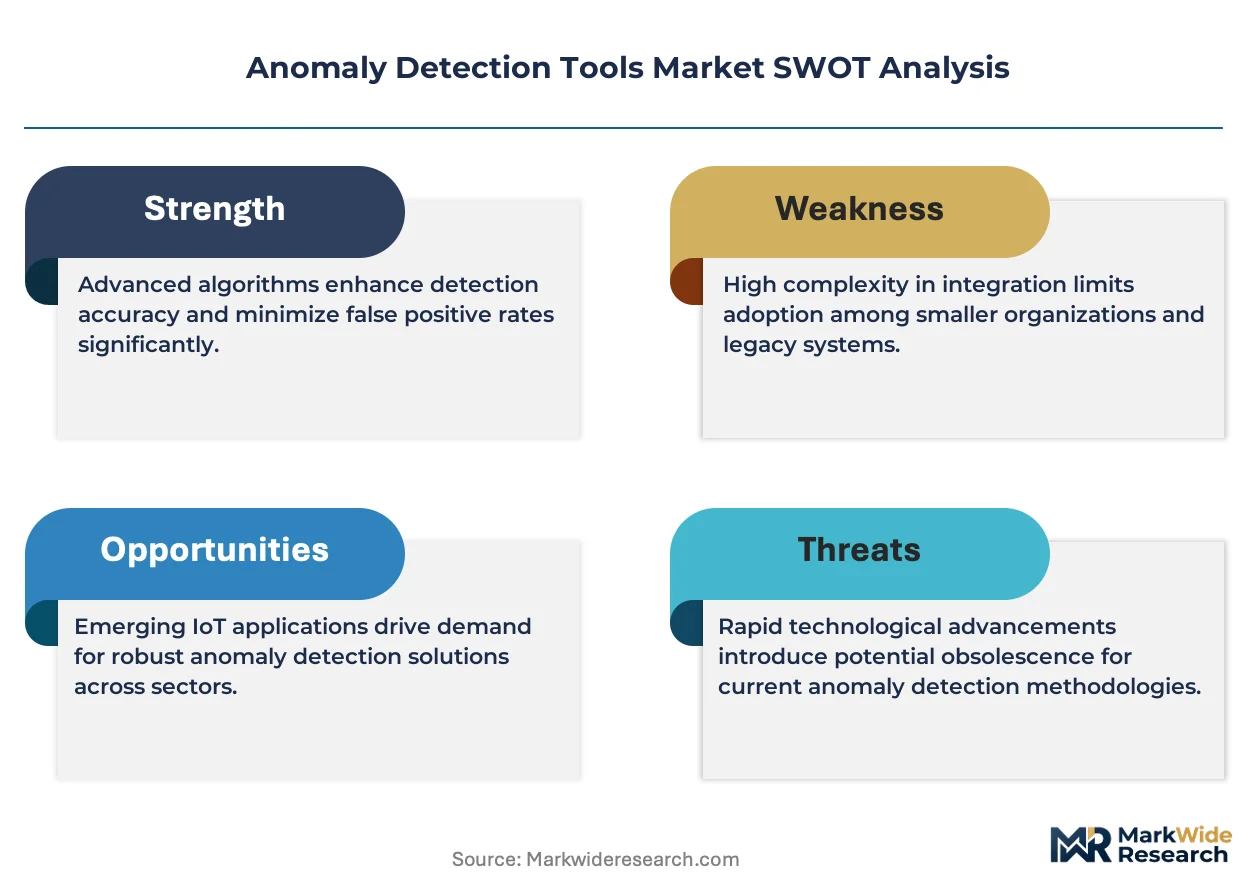
- PhD-Level Talent Scarcity:A shortage of data scientists fluent in statistical signal processing and unsupervised architectures is inflating compensation costs and constraining vendor expansion.
- Regulatory Fragmentation:Divergent compliance requirements between the EU AI Act, NIST AI Risk Management Framework, and sector-specific SEC cybersecurity disclosure rules are multiplying certification burdens.
- On-Premises Asset Stranding:Organizations with capital-intensive legacy data centers face sunk-cost inertia that slows cloud migration timelines and defers new procurement.
Strategic Opportunities
- Edge-Native Manufacturing:Predictive maintenance applications in Japan and South Korea offer white-space expansion for vendors with sub-50ms inference capabilities.
- Open-Source Community Leverage:Crowdsourced algorithm development through publicly available repositories enables capability building without proportional payroll expansion.
- Security Operations Center Integration:Privileged distribution channels into enterprise SOC workflows create defensive moats against point-solution competitors.
Industry Challenges
- Hybrid Infrastructure Complexity:Detection systems must integrate across on-premises, cloud, and edge environments simultaneously, multiplying deployment engineering requirements.
- Explainability Engineering:Regulatory demands for auditable decision trails conflict with black-box neural network architectures, forcing expensive model re-architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anomaly Detection Tools Market |
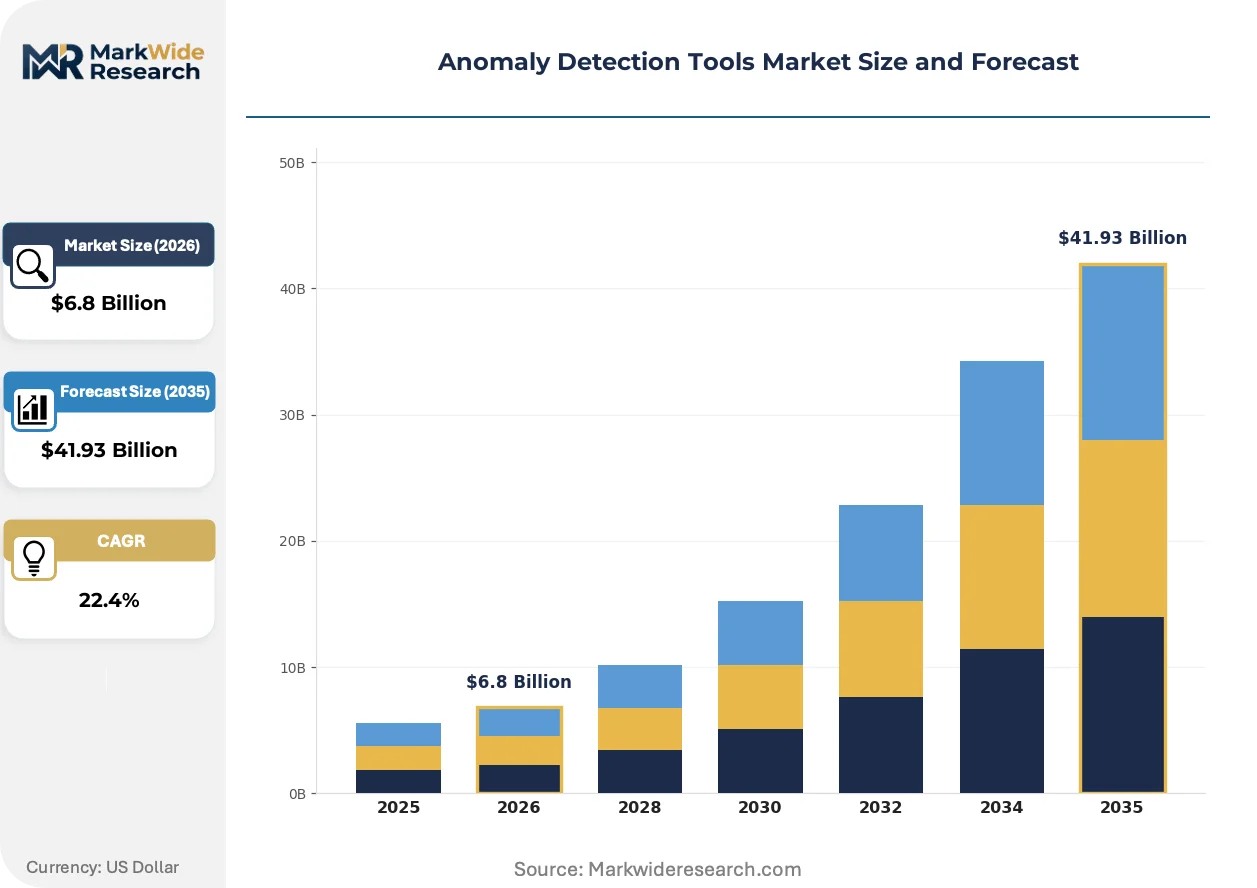
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $41.93 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Technology: Machine Learning, Statistical Analysis, Data Mining, Artificial Intelligence End User: Financial Services, Healthcare Providers, IT Services, Manufacturing Application: Fraud Detection, Network Security, Quality Assurance, Predictive Maintenance |
| Companies Covered | Datadog, Dynatrace, IBM, Anodot, New Relic, Microsoft, Splunk, Elastic, AWS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anomaly Detection Tools Market Strategic Shifts
Machine learning architectures are bifurcating into explainable versus high-performance camps, while regulatory pressure and procurement transformation reshape vendor priorities simultaneously.
Transformer-based anomaly detection is bifurcating the competitive landscape. These architectures process time-series and log data with superior pattern recognition. Financial institutions in London and Singapore are adopting them for fraud detection at scale. The technology is bifurcating vendor tiers into GPU-dependent premium providers and rule-based economy alternatives.
Algorithmic transparency requirements under the EU AI Act are reshaping product roadmaps. Vendors must now embed explainability modules that trace decision pathways. European financial services and healthcare providers face the steepest compliance curves. German insurers are piloting interpretable surrogate models to satisfy regulator demands without sacrificing detection accuracy.
Enterprise buyers are consolidating vendor relationships around integrated security platforms. Standalone anomaly detection tools face displacement by bundled SIEM and observability suites. Security operations centers in the United States and United Kingdom are driving this consolidation. Japanese manufacturers remain an exception, maintaining preference for specialized predictive maintenance solutions with dedicated support contracts.
Anomaly Detection Tools Market Segmentation
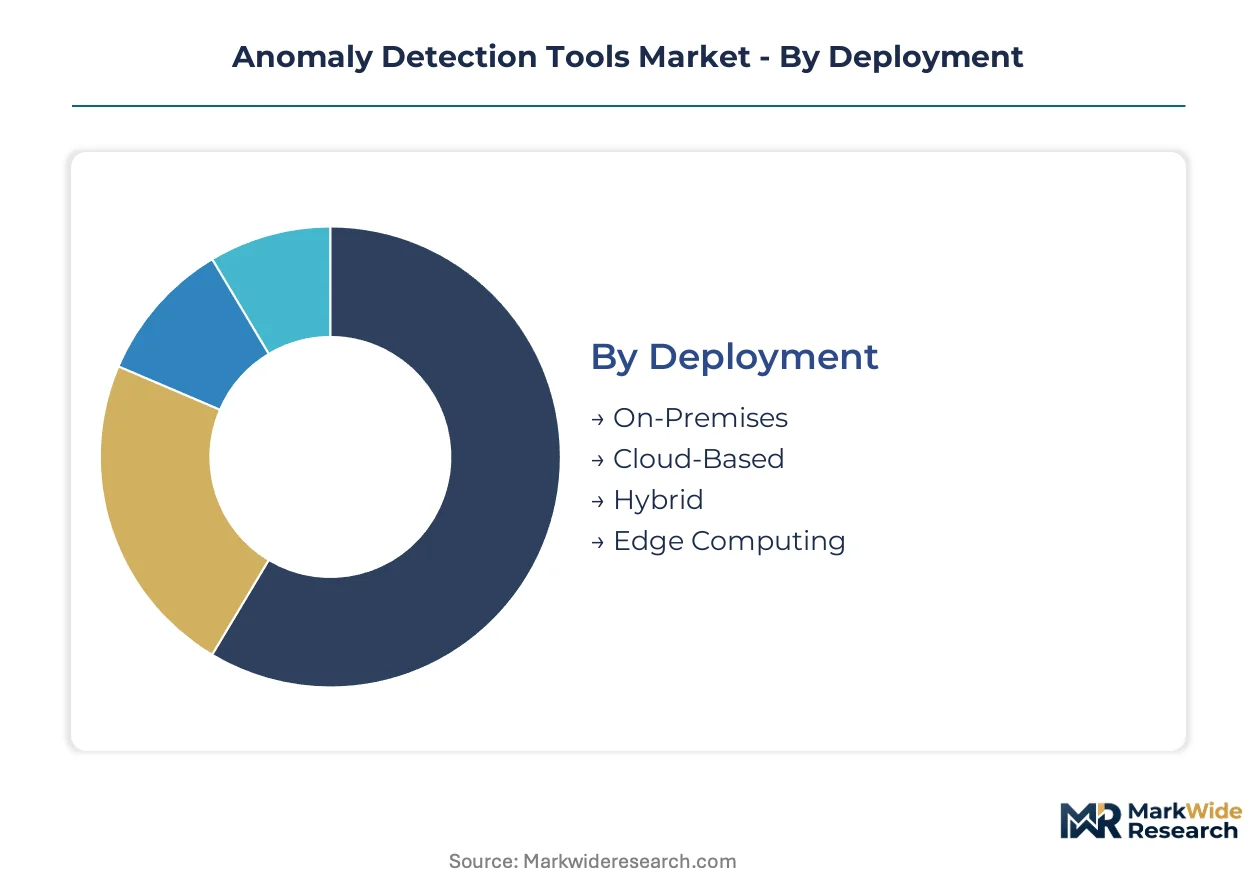
Anomaly detection tools fragment across four critical dimensions that determine procurement priorities, engineering requirements, and margin structures. Deployment mode dictates infrastructure investment cycles. Technology selection separates GPU-dependent premium offerings from rule-based economy alternatives. End-user verticals impose sector-specific compliance burdens. Application type governs latency thresholds and explainability mandates.
Deployment:
Geographic concentration varies sharply: cloud-based solutions serve export-oriented multinationals with distributed operations, while edge deployments cluster in Germany's industrial automation corridor and Japan's precision manufacturing zones.
- On-Premises:Organizations with sunk-cost data center infrastructure in regulated jurisdictions maintain these deployments to satisfy data sovereignty requirements. Financial institutions in Switzerland and German automotive suppliers favor capital-intensive control over operational expenditure models.
- Cloud-Based:Scalable compute resources eliminate upfront hardware procurement. Mid-market enterprises across Singapore, the United Kingdom, and the United States are retiring legacy server farms for subscription-based anomaly detection services.
- Hybrid:Split architectures process sensitive data locally while leveraging cloud elasticity for model training. Healthcare providers in Canada and Australia deploy this mode to balance HIPAA-equivalent privacy mandates with computational scale.
- Edge Computing:Sub-50 millisecond inference enables real-time equipment intervention. Semiconductor fabrication facilities in South Korea and automotive plants in Stuttgart deploy these for predictive maintenance where network latency risks cascading failure.
On-premises installations command the established base. The steepest expansion runs through cloud-based deployments.
Technology:
Cost tier stratification separates GPU-intensive premium implementations from lightweight statistical alternatives accessible to budget-constrained buyers.
- Machine Learning:Unsupervised architectures detect novel anomalies without labeled training data. Financial services firms in London and Singapore deploy these for fraud detection at transaction scale, though PhD-level talent scarcity constrains vendor expansion.
- Statistical Analysis:Established techniques including z-score thresholds and control charts require minimal computational overhead. Small and medium enterprises across Italy and Spain rely on these for baseline operational monitoring without specialized infrastructure.
- Data Mining:Pattern extraction across high-dimensional datasets identifies subtle deviation clusters. Retail and logistics operators in the Netherlands apply these to supply chain anomaly detection with interpretable rule outputs.
- Artificial Intelligence:Transformer-based architectures process sequential data with superior context awareness. Investment banks in New York and Tokyo are piloting these for complex fraud pattern recognition despite explainability engineering challenges.
Statistical analysis retains the broadest installed base. Artificial intelligence implementations are climbing the fastest as GPU infrastructure costs decline.
End User:
Application intensity varies by sector maturity: financial services and healthcare lead procurement sophistication, while manufacturing adoption concentrates in specific geographic clusters.
- Financial Services:Real-time transaction monitoring for anti-money laundering and fraud prevention dominates procurement. EU AI Act compliance mandates are forcing algorithmic transparency upgrades across German, French, and Dutch banking institutions.
- Healthcare Providers:Clinical anomaly detection for patient deterioration and diagnostic imaging interpretation requires regulatory validation. Hospitals in the United States and United Kingdom face SEC cybersecurity disclosure and NHS data governance requirements simultaneously.
- IT Services:Managed security providers bundle anomaly detection into broader observability offerings. Cloud-native firms in Ireland and India integrate these capabilities into multi-tenant platforms for mid-market client bases.
- Manufacturing:Equipment failure prediction drives adoption in automotive and electronics fabrication. Germany's automation corridor and Japan's precision engineering clusters represent concentrated demand for edge-deployed solutions.
Financial services commands premium pricing power. Manufacturing is gaining share fastest as predictive maintenance ROI documentation improves.
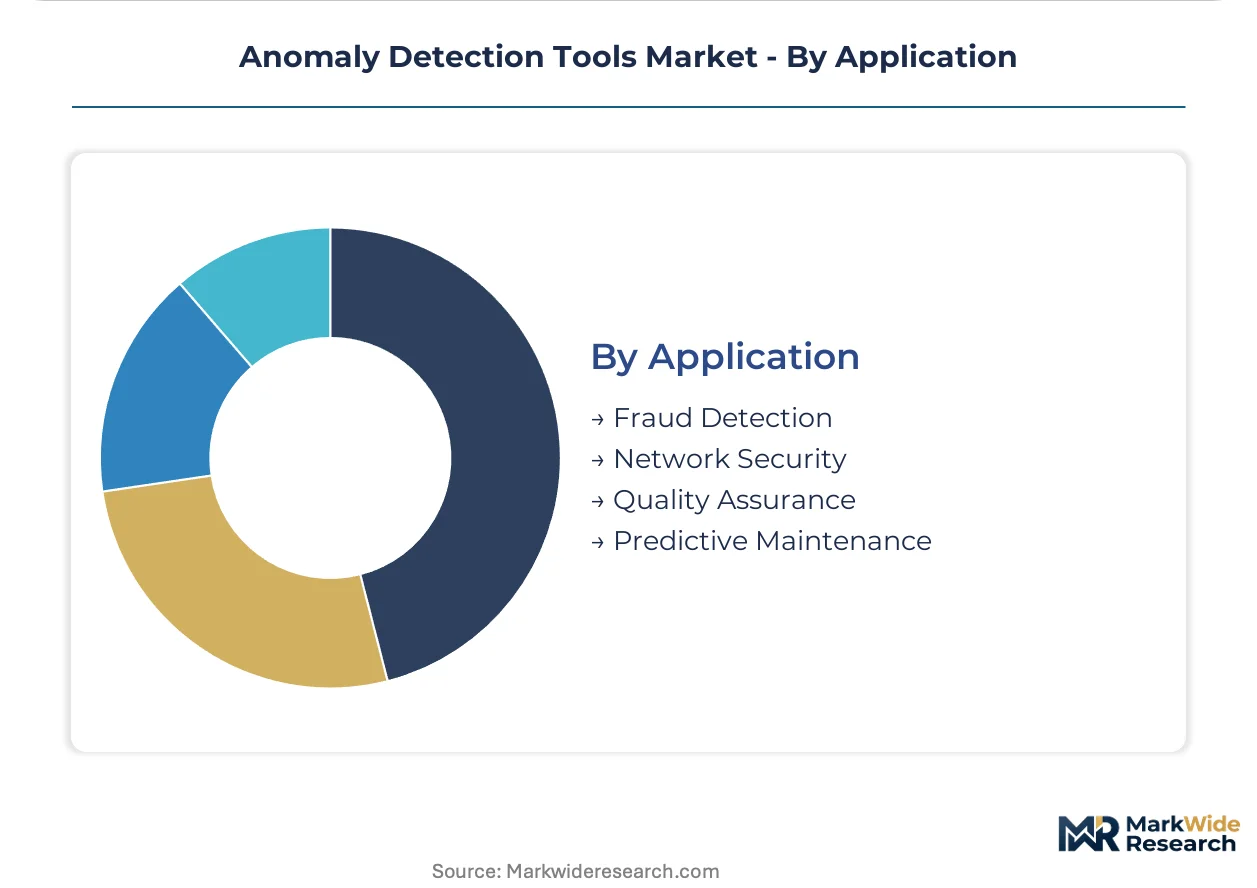
Application:
Customer type bifurcation separates security-focused enterprise buyers from operations-centric industrial users with distinct procurement timelines.
- Fraud Detection:Real-time scoring of transactions and behavioral biometrics prevents financial losses before settlement. Payment processors in Singapore and card networks in the United States deploy sub-second latency architectures for authorization decisions.
- Network Security:Intrusion detection and lateral movement identification protect hybrid infrastructure. Security operations centers in the United Kingdom and Germany consolidate these capabilities into integrated SIEM platforms.
- Quality Assurance:Manufacturing defect identification in visual inspection and process control reduces waste. Pharmaceutical packaging lines in Switzerland and electronics assembly in South Korea deploy computer-vision-based anomaly detection.
- Predictive Maintenance:Vibration analysis and thermal monitoring forecast equipment degradation. Wind turbine operators in Denmark and steel mills in Japan leverage these to minimize unplanned downtime.
Network security retains the largest deployment footprint. Predictive maintenance is expanding most quickly as industrial IoT sensor density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act anchors European demand, mandating algorithmic transparency for high-risk automated monitoring systems. Financial institutions and healthcare providers across the continent face steep compliance curves. Procurement concentrates in specific national clusters with distinct regulatory and industrial profiles.
United States
SEC cybersecurity disclosure rules and NIST's AI Risk Management Framework push publicly traded enterprises toward auditable detection capabilities. Financial services firms in New York deploy sub-second latency architectures for real-time fraud prevention. Silicon Valley cloud providers anchor the subscription-based deployment expansion.
Germany
Industrial automation corridors in Stuttgart and Munich drive edge-computing adoption for predictive maintenance with millisecond response requirements. The EU AI Act imposes conformity assessment obligations on automotive and semiconductor fabrication monitoring systems. Baden-Württemberg's precision engineering clusters represent concentrated demand for specialized solutions.
United Kingdom
NHS data governance requirements and Financial Conduct Authority oversight create dual compliance pressures for healthcare and banking sectors. London's security operations centers consolidate vendor relationships around integrated SIEM platforms. The capital's fintech ecosystem pilots transformer-based architectures for complex fraud pattern recognition.
Japan
METI industrial policy promotes smart manufacturing adoption, accelerating predictive maintenance deployments in automotive and electronics fabrication. Osaka-based pharmaceutical packaging lines apply computer-vision-based anomaly detection for quality assurance. Nagoya's precision engineering clusters maintain preference for specialized solutions with dedicated support contracts.
Singapore
The Monetary Authority of Singapore's technology risk management guidelines mandate robust fraud detection infrastructure for payment processors and banking institutions. Sub-second latency architectures dominate authorization decision systems. The city-state's position as a regional financial hub attracts vendor investment in localized cloud infrastructure.
Anomaly Detection Tools Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the anomaly detection tools landscape. GPU-dependent premium providers command specialized infrastructure margins, while open-source community models crowdsource algorithm improvements without proportional payroll expansion. Three archetypes dominate: cloud-native platform integrators, academic research partners securing PhD-level talent pipelines, and security channel incumbents with privileged SOC distribution. Competitive moves center on M&A for talent acquisition and strategic partnerships for edge-computing deployment capabilities.
Within the cloud-native tier, Datadog and Dynatrace exemplify platform consolidation strategies that bundle anomaly detection into broader observability offerings. IBM occupies a position bridging enterprise software heritage with deep academic research partnerships for statistical signal processing expertise. Splunk anchors the security channel incumbent archetype, leveraging SIEM integration for privileged access to enterprise security operations workflows.
| Leading Market Players |
|---|
| Datadog |
| Dynatrace |
| IBM |
| Anodot |
| New Relic |
| Microsoft |
| Splunk |
| Elastic |
| AWS |
| Others |
Value Chain & Pricing Dynamics
Subscription-based capacity reservation contracts lock in GPU infrastructure access for cloud-native vendors while anchoring price predictability for enterprise buyers navigating the EU AI Act compliance cycle. These arrangements concentrate pricing power with hyperscale infrastructure providers in the United States and Singapore, compressing margins for mid-tier software vendors without captive compute resources.
Pricing Analysis
Geographic price spreads widen significantly between Frankfurt and Singapore data center zones, reflecting differential energy costs and regulatory compliance overhead. SaaS-tiered subscription models dominate procurement, with pricing stratifying across premium GPU-dependent machine learning tiers, standard statistical analysis offerings, and economy rule-based alternatives. Cost compression in the standard tier intensifies as open-source frameworks commoditize baseline algorithmic capabilities. Mid-market enterprises across Italy and Spain exhibit highest price sensitivity, while financial institutions in London and New York accept premium positioning for sub-second latency guarantees.
Supply Chain Analysis
Just-in-time GPU procurement strategies predominate among cloud-native vendors, though strategic stockpiling of specialized inference accelerators is emerging among edge-computing specialists serving German automotive corridors. Hardware supply concentrates in Taiwan, South Korea, and the United States for advanced semiconductor fabrication. Software supply draws from distributed open-source repositories and concentrated PhD talent pipelines anchored in academic institutions. Single-source vulnerability around NVIDIA's data center GPU architecture presents structural risk. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels with embedded professional services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment modes and compliance regimes is creating defendable niches for specialists. Procurement bifurcation between cloud-native mid-market buyers and edge-heavy industrial users prevents winner-take-all consolidation.
For Market Incumbents: Secure exclusive distribution relationships with security operations centers in London and New York before SIEM consolidation displaces standalone offerings. Deepen backward integration into GPU infrastructure through long-term capacity reservations with Taiwan-based foundries, insulating margin structures from hyperscaler pricing power. For New Entrants and Emerging Players: Differentiate on explainable AI architectures purpose-built for EU AI Act conformity assessment workflows. Target white-space expansion in Japanese precision manufacturing clusters where specialized predictive maintenance solutions with dedicated support contracts command premium positioning. Pursue channel partnerships with German industrial automation integrators rather than direct enterprise sales. For Investors and Strategic Acquirers: Capital is best deployed toward academic research spinouts with captive PhD pipelines in statistical signal processing, given talent scarcity constraints vendor expansion across the analysis window. Watch for inflection when transformer-based architectures achieve regulatory-validated explainability without accuracy degradation, signaling tier-1 vendor displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Architecture Development | Sub-50ms inference capabilities unlock German automotive and South Korean semiconductor fabrication procurement. |
| Academic Research Partnership | PhD pipeline access in statistical signal processing addresses critical talent scarcity constraining vendor expansion. |
| Explainability Module Integration | EU AI Act compliance embedding captures financial services procurement across Frankfurt, Paris, and Amsterdam. |
| Security Operations Center Integration | Privileged SIEM distribution channels create defensive moats against point-solution competitors in London and New York. |
| Open-Source Community Cultivation | Crowdsourced algorithm development enables capability building without proportional payroll expansion. |
Study Parameters
The analysis maps machine learning, statistical analysis, data mining, and transformer-based AI sub-sectors, each validated through chief technology officers, IT procurement officers, platform engineers, and channel partners. Primary interviews with these stakeholders combined with secondary validation against SEC filings, hyperscaler capex disclosures, and EU regulatory transparency databases. Bottom-up deployment mode sizing and top-down technology spend allocation were triangulated to ensure consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled deployment mode, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions. CAGRs were derived from segment-level growth trajectory analysis incorporating GPU infrastructure cost curves, regulatory compliance timeline acceleration, and industrial IoT sensor density expansion as industry-specific inputs.
Forecasts assume regulatory continuity in EU AI Act implementation and NIST AI Risk Management Framework adoption; material policy shifts would require re-modeling. Specific risks include PhD talent pipeline disruption, hyperscaler marketplace policy changes, and semiconductor export control expansion. Revision becomes warranted when transformer-based explainability validation crosses commercial deployment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Antivirus Software Package Market
Security Software
Global Privileged Access Management (PAM) Solutions Market
Security Software
Global Electronic Offender Monitoring Solutions Market
Security Software
Digital Credential Management Software Market
Security Software
Private Virtual Communications for Police Network Market
Security Software
Global Data Masking Market
Security Software
Encryption As A Service Market
Security Software
Asia-Pacific Smart Doorbell Market
Security Software
Spain Endpoint Detection and Response Market
Security Software
Remote Access Management Market
Security Software
Asia-Pacific Encryption Software Market
Security Software
Vsaas Market
Security Software
Mobile Threat Management Security Software Market
Security Software
Anomaly Detection Market
Security Software
Employee Fraud Detection Market
Security Software
DC and PKI Market