
 Global Data Classification Market | 2026-2036
Global Data Classification Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Classification Market Foresight
ISO 27001 certification is bifurcating the competitive landscape into qualified and non-qualified vendors. IBM Corporation leverages its governance portfolio to anchor enterprise accounts across regulated industries. Microsoft Corporation competes through native integration with productivity suites and identity infrastructure. Amazon Web Services, Inc. differentiates via serverless classification pipelines embedded within cloud storage services.
Data classification encompasses the systematic categorization of structured and unstructured information assets based on sensitivity, regulatory exposure, and business criticality, employing machine learning models, regular expression engines, and natural language processing to assign persistent metadata tags at the file, field, or object level. The primary commercial purpose centers on enabling policy enforcement, access control, and breach response workflows across distributed data estates. Cloud-based deployment architectures represent the fastest-expanding configuration as organizations retire on-premises data centers and adopt SaaS delivery models. Regulatory compliance applications command the deepest margin pools given the complexity of cross-jurisdiction rule mapping and audit trail requirements. File-level classification remains the most mature solution category, while content discovery tools gain traction in unstructured data repositories.
The EU AI Act, GDPR, and SEC cybersecurity disclosure rules collectively reshape product roadmaps and procurement criteria across the vendor base. HIPAA and FERC standards in the United States add sector-specific layering for healthcare and energy clients. Stakeholders must evaluate vendor interoperability with zero-trust architectures and emerging quantum-resistant encryption standards.
Market Dynamics
Cloud-native deployment architectures are compressing procurement cycles as financial services firms in New York, London, and Singapore retire legacy on-premises classification stacks. This infrastructure migration is redistributing margin pools toward vendors with serverless pipeline capabilities and cross-jurisdiction compliance automation.
Growth Catalysts
- EU AI Act enforcement timelines:Automated classification platforms now qualify as high-risk AI system components under the EU AI Act, forcing enterprises to procure certified solutions before the 2026 compliance deadline.
- Financial services procurement waves:Banks and asset managers in Singapore are mandating real-time data lineage tagging for trading algorithms, driving demand for field-level classification engines.
- Natural language processing maturation:Transformer-based models now parse unstructured legal contracts and medical records with sufficient accuracy to replace manual review workflows.
Market Restraints
- ISO 27001 certification scarcity:The bifurcation between qualified and non-qualified vendors limits procurement options for regulated industries, concentrating supplier power among pre-certified incumbents.
- Quantum-resistant encryption uncertainty:NIST post-quantum cryptography standards remain incomplete, freezing long-term architecture decisions for classification metadata protection.
- Cross-border data localization mandates:China's data security law and Russia's sovereign internet requirements fragment cloud deployment strategies, raising operational complexity for multinational enterprises.
Strategic Opportunities
- Healthcare unstructured data repositories:HIPAA-covered entities in the United States are deploying content discovery tools to classify patient imaging archives and clinical notes previously invisible to governance programs.
- Zero-trust architecture convergence:Integration between classification metadata and identity infrastructure enables dynamic access policies that adjust in real time based on data sensitivity tags.
- Japan's METI data governance guidelines:The 2024 framework incentivizes automated classification for cross-enterprise data sharing consortia in manufacturing supply chains.
Industry Challenges
- Machine learning operations talent gap:Enterprises lack personnel capable of retraining classification models as data schemas evolve, creating dependency on vendor professional services.
- Legacy mainframe integration friction:Mainframe-resident structured data in banking and insurance resists standard API-based classification tagging, requiring costly custom connector development.
- Audit trail standardization delays:Competing frameworks from ISO, NIST, and sector-specific bodies prevent interoperable compliance reporting across multinational deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Classification Market |
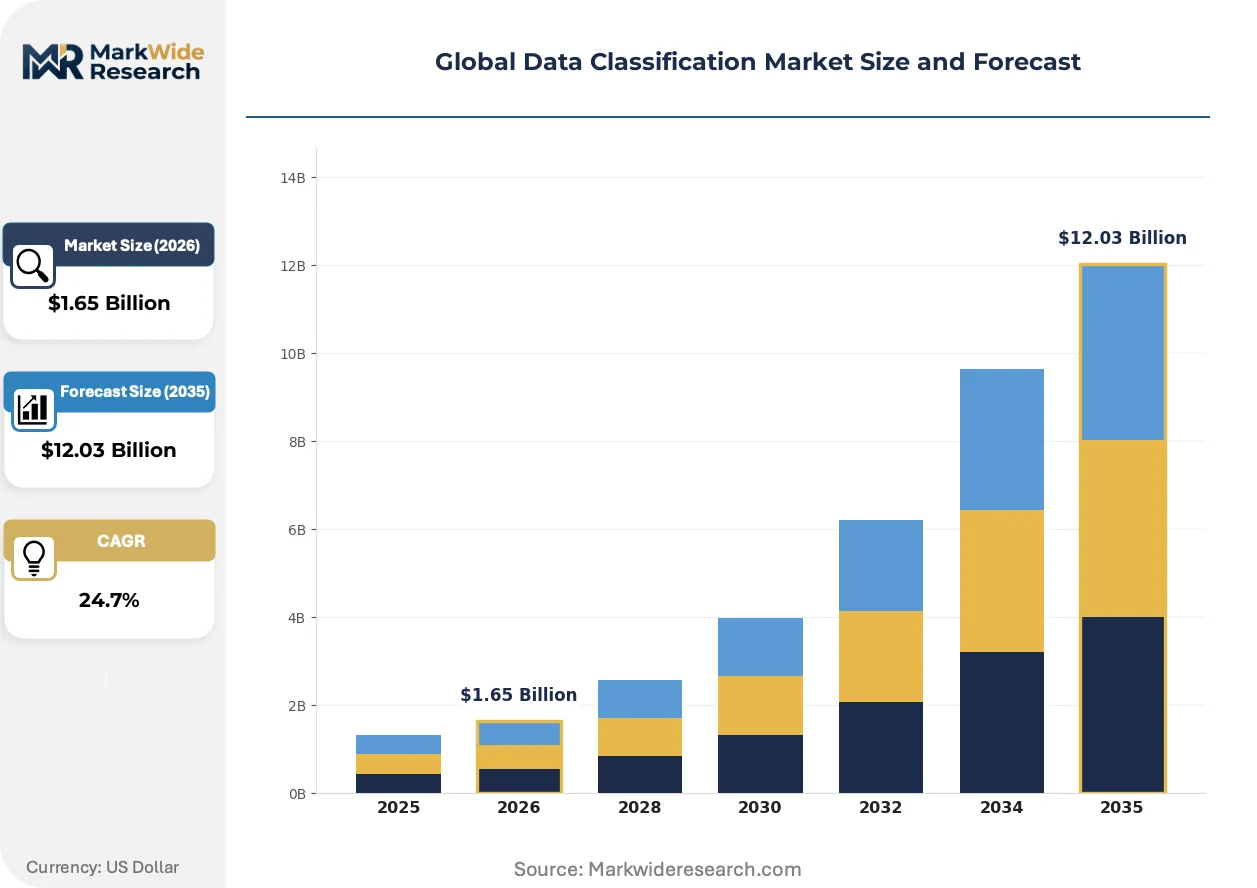
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $12.03 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: File-Level Classification, Content Discovery, Metadata Tagging, Data Loss Prevention, Policy Management Deployment: On-Premises, Cloud-Based, Hybrid, Virtual Appliance Application: Risk Management, Regulatory Compliance, Data Privacy, Insider Threat Detection, Intellectual Property Protection End User: Government Agencies, Financial Institutions, Telecommunications Providers, Legal Firms, Educational Institutions |
| Companies Covered | IBM Corporation, Microsoft Corporation, Amazon Web Services, Inc., Broadcom Inc., Informatica LLC, Varonis Systems, Inc., Forcepoint LLC, Alphabet Inc., Netwrix Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Classification Market Shifts & Advancements
Classification technology is converging with identity infrastructure and encryption systems, collapsing previously separate procurement categories into unified data governance platforms. Vendors are racing to embed classification engines directly within storage and productivity services rather than delivering standalone products.
Edge-deployed classification agents are miniaturizing to run on endpoint devices without cloud round-trips. Manufacturing firms with sensitive intellectual property in Germany and Japan are adopting these lightweight models to classify CAD files and sensor data at the source. This architecture is compressing latency for real-time access decisions while reducing exposure during network transit.
The EU AI Act's risk classification framework is mandating algorithmic transparency for automated decision systems. Financial services firms deploying credit scoring and fraud detection models must now maintain complete data lineage documentation. This requirement is accelerating procurement of classification tools that persist sensitivity metadata through machine learning training pipelines.
Subscription consumption models are displacing perpetual licenses for classification software. Enterprise buyers in the United States and United Kingdom are prioritizing usage-based pricing that scales with data volume growth rather than fixed seat counts. This shift is pressuring vendors to restructure revenue recognition and customer success functions around consumption metrics.
Global Data Classification Market Segmentation
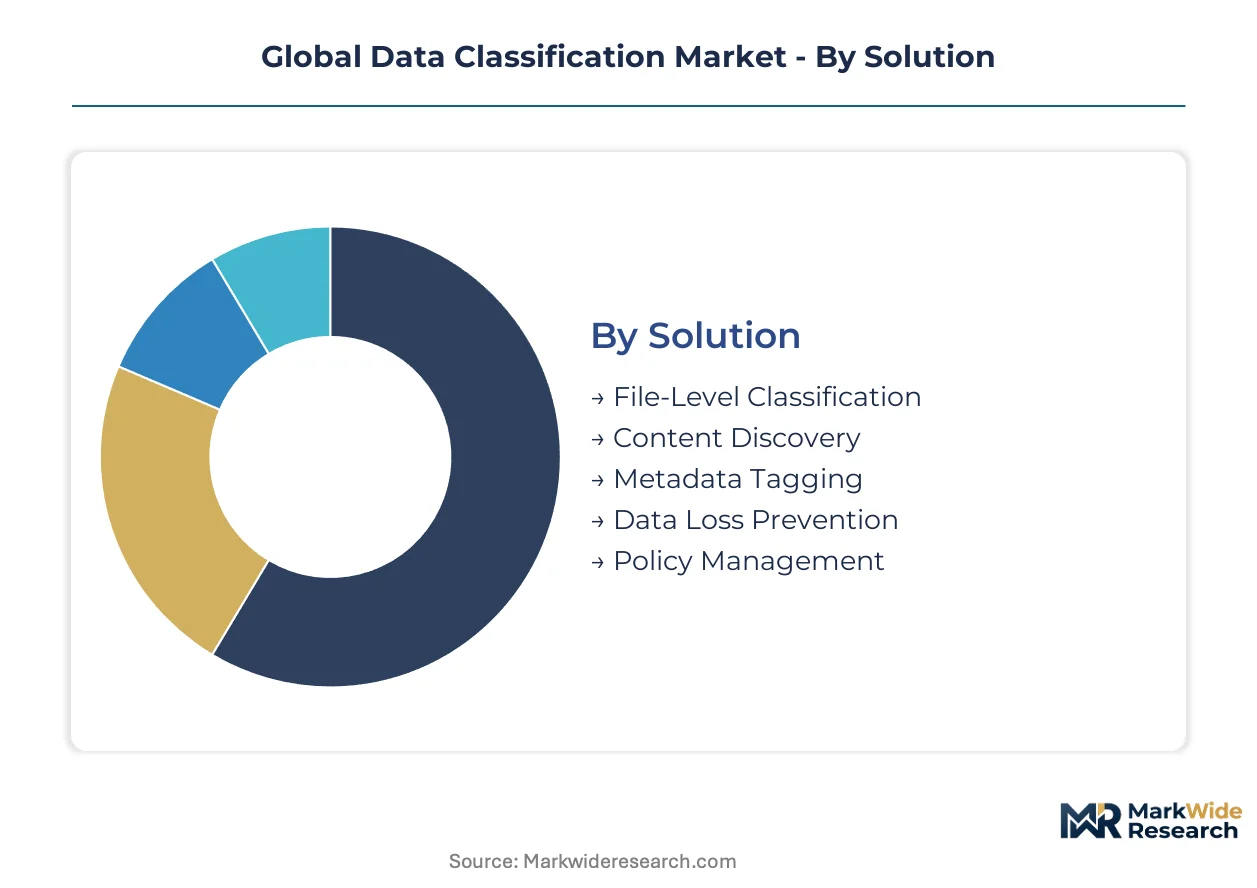
Data classification vendors structure product portfolios around four intersecting dimensions that determine procurement patterns and margin capture. Solution architecture, deployment model, application priority, and end-user vertical each create distinct competitive battlegrounds with diverging pricing power and technical requirements.
Solution:
Margin pools concentrate in tools that embed classification engines directly into storage and productivity services rather than standalone products.
- File-Level Classification:Mature technology segment employing persistent metadata tagging at the file object level across distributed storage estates. Financial institutions in Singapore and New York are mandating real-time lineage tagging for trading algorithms, compressing procurement cycles toward vendors with serverless pipeline capabilities.
- Content Discovery:Transformer-based natural language processing parses unstructured legal contracts and medical records with sufficient accuracy to replace manual review workflows. HIPAA-covered entities in the United States deploy these tools to classify patient imaging archives and clinical notes previously invisible to governance programs.
- Metadata Tagging:Systematic assignment of sensitivity and regulatory exposure labels at field or object level.
- Data Loss Prevention:Policy enforcement mechanisms triggered by classification tags during data movement.
- Policy Management:Centralized rule configuration for cross-jurisdiction compliance automation.
File-Level Classification holds installed capacity. Content Discovery is rotating up the share rankings.
Deployment:
Cost tier bifurcation separates enterprises retiring legacy data centers from those maintaining sovereign control requirements.
- Cloud-Based:Serverless classification pipelines embedded within cloud storage services represent the fastest-expanding configuration as organizations adopt SaaS delivery models. Financial services firms in London and Singapore are retiring on-premises stacks and redistributing margin pools toward vendors with cross-jurisdiction compliance automation.
- Hybrid:Split architectures preserving sensitive data on-premises while pushing non-critical workloads to cloud. Manufacturing firms with intellectual property in Germany and Japan adopt edge-deployed agents that classify CAD files and sensor data at the source without cloud round-trips.
- On-Premises:Legacy configurations persisting in banking and insurance due to mainframe-resident structured data resisting standard API-based tagging.
- Virtual Appliance:Pre-configured software images for rapid deployment in regulated environments with strict change control.
Cloud-Based deployment captures new logo growth. Hybrid is rotating up the share rankings.
Application:
Volume concentration follows regulatory enforcement timelines rather than organic technology adoption curves.
- Regulatory Compliance:Cross-jurisdiction rule mapping and audit trail requirements command the deepest margin pools given complexity. The EU AI Act and GDPR enforcement timelines are accelerating vendor qualification requirements, forcing enterprises to procure certified solutions before compliance deadlines.
- Data Privacy:Sensitivity tagging for consent management and subject access request fulfillment. Educational institutions in the United Kingdom deploy these tools to manage student records under GDPR and domestic data protection frameworks.
- Risk Management:Quantification of data exposure for cyber insurance and board reporting.
- Insider Threat Detection:Behavioral analytics combined with classification metadata for anomaly detection.
- Intellectual Property Protection:CAD file and source code classification for manufacturing and technology firms.
Regulatory Compliance holds installed capacity. Data Privacy is rotating up the share rankings.
End User:
Customer type determines sales cycle length and professional services attachment rates.
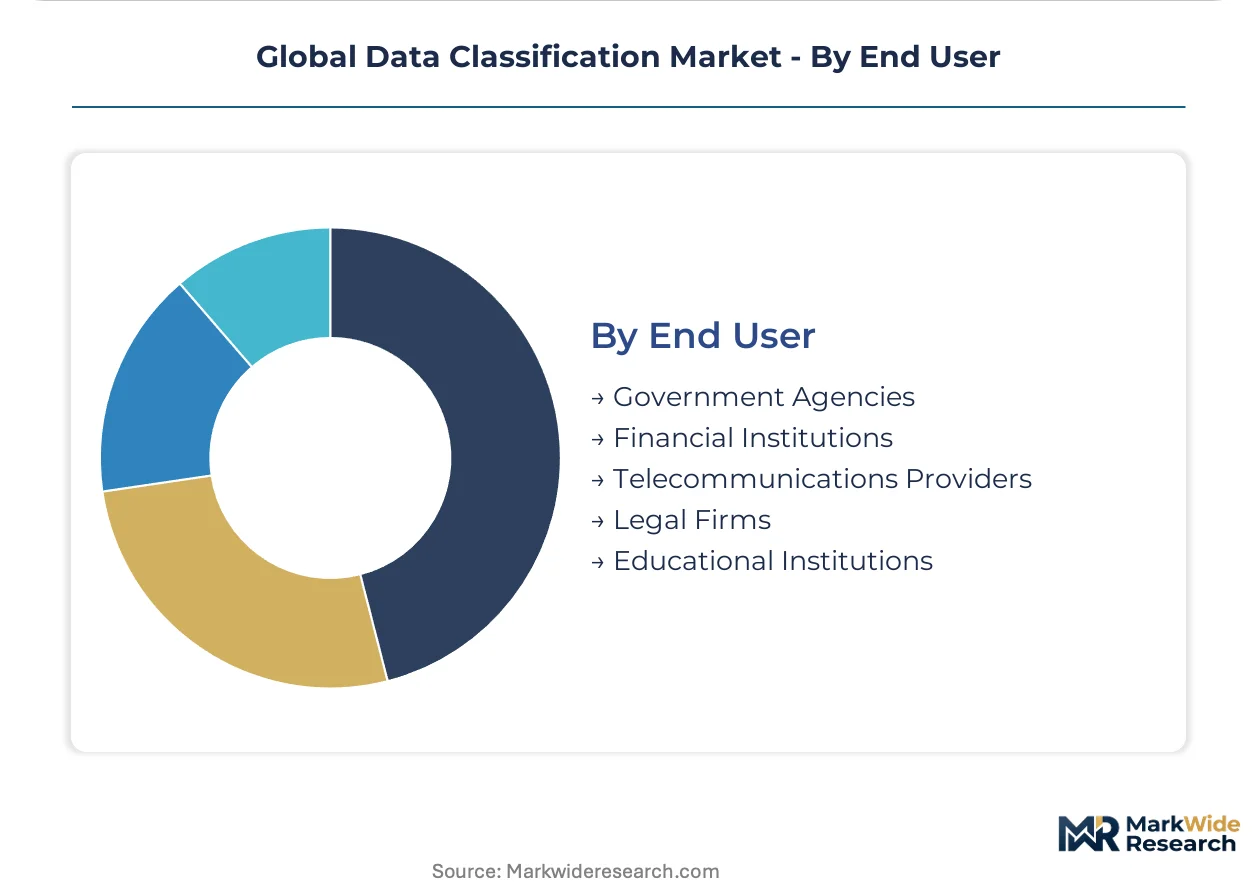
- Financial Institutions:Banks and asset managers mandate field-level classification engines with real-time data lineage documentation for algorithmic transparency. ISO 27001 certification scarcity limits procurement options and concentrates supplier power among pre-certified incumbents.
- Government Agencies:Sovereign requirements for data localization and quantum-resistant encryption standards freeze long-term architecture decisions. Classification metadata must interoperate with zero-trust identity infrastructure for dynamic access policies.
- Telecommunications Providers:Network-level traffic inspection for customer data protection obligations.
- Legal Firms:Contract and discovery document classification for privilege protection.
- Educational Institutions:Student and research data governance under sector-specific privacy frameworks.
Financial Institutions hold installed capacity. Government Agencies is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU AI Act enforcement timelines and GDPR audit requirements are accelerating procurement across financial centers. Cloud-native deployment architectures dominate new spending as enterprises retire legacy stacks.
United States
SEC cybersecurity disclosure rules and HIPAA enforcement are driving healthcare and financial services procurement. The Department of Health and Human Services mandates breach reporting within 72 hours. New York financial institutions deploy real-time lineage tagging for trading algorithms.
Germany
Industrial data governance under METI-aligned frameworks supports manufacturing supply chain consortia. The Federal Office for Information Security certifies vendors for critical infrastructure protection. Bavarian automotive suppliers classify CAD files and sensor data at the edge.
Singapore
Monetary Authority of Singapore guidelines mandate automated classification for algorithmic trading transparency. The Personal Data Protection Commission enforces cross-border transfer restrictions. Financial institutions in the Marina Bay district procure field-level engines for real-time compliance.
Japan
METI's 2024 data governance guidelines incentivize automated classification for cross-enterprise sharing. The Ministry of Economy, Trade and Industry promotes manufacturing consortium standardization. Nagoya industrial clusters deploy lightweight classification agents for intellectual property protection.
United Kingdom
Information Commissioner's Office enforcement of GDPR and domestic data protection frameworks pressures educational and legal sectors. The National Cyber Security Centre publishes zero-trust architecture guidance. London financial services firms consolidate vendor relationships around ISO 27001-certified platforms.
Global Data Classification Market Competitive Landscape
Player mix skews toward cloud infrastructure incumbents with governance portfolio extensions. Market structure concentrates among three strategic archetypes: hyperscale cloud providers embedding classification into storage services, enterprise software vendors integrating with productivity suites, and cybersecurity specialists offering standalone policy enforcement. Competitive dynamics center on M&A activity targeting NLP capabilities and strategic partnerships with zero-trust identity vendors.
Within the hyperscale tier, IBM Corporation and Microsoft Corporation exemplify divergent positioning strategies. IBM anchors enterprise accounts across regulated industries through governance portfolio breadth. Microsoft competes via native integration with productivity suites and identity infrastructure. Amazon Web Services, Inc. occupies a distinct position through serverless classification pipelines embedded within cloud storage services.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Amazon Web Services, Inc. |
| Broadcom Inc. |
| Informatica LLC |
| Varonis Systems, Inc. |
| Forcepoint LLC |
| Alphabet Inc. |
| Netwrix Corporation |
| Others |
Supply & Pricing Matrix
Subscription-based SaaS contracts with consumption-scaling provisions lock in multi-year revenue visibility for vendors while capping buyer exposure to data volume spikes. This structure concentrates procurement power among enterprises in the United States, Germany, and Japan that can commit to minimum spend thresholds against EU AI Act compliance deadlines.
Pricing Analysis
Certification level creates the primary spread between ISO 27001-qualified platforms and uncertified alternatives. Three-tier pricing separates enterprise-grade governance suites from mid-market SaaS offerings and developer API tiers. Cost compression in the mid-market tier intensifies as hyperscale cloud providers bundle classification into storage services at marginal incremental cost. Financial institutions in Singapore and New York exhibit lowest price sensitivity due to regulatory mandate urgency, while educational institutions in the United Kingdom face acute budget constraints.
Supply Chain Analysis
The United States anchors cloud infrastructure provisioning for classification pipelines, while Ireland and Singapore host regional data residency zones for GDPR and PDPC compliance. Transformer model training draws from NVIDIA GPU clusters concentrated in Taiwan and South Korea, creating single-source vulnerability for NLP-dependent content discovery tools. Distribution runs through hyperscale marketplace integrations and direct enterprise sales teams with professional services attachment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-classification framework for automated decision systems compresses procurement timelines and rewards vendors with pre-certified algorithmic transparency capabilities.
For Market Incumbents: Fortify ISO 27001 certification moats through accelerated audit cycles ahead of the EU AI Act enforcement window. Anchor enterprise accounts in financial services by embedding classification metadata directly into identity infrastructure for zero-trust convergence, neutralizing displacement risk from native cloud provider offerings. For New Entrants and Emerging Players: Fast-track certification through ISO 27001-aligned audit preparation services creates procurement eligibility for regulated industries locked out of non-qualified vendors. Penetrate healthcare unstructured data repositories in the United States where HIPAA-covered entities lack internal NLP capabilities. Lead with edge-deployed lightweight agents for manufacturing intellectual property protection in Germany and Japan. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native vendors with serverless pipeline architectures and cross-jurisdiction compliance automation. Five-to-ten-year viability hinges on quantum-resistant encryption roadmap execution as NIST standards finalize. Monitor EU AI Act delegated act publications as the definitive inflection signal for vendor qualification demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Acceleration | Qualifies vendors for EU AI Act high-risk system procurement before enforcement deadlines. |
| Serverless Pipeline Integration | Embeds classification engines within AWS S3 and Azure Blob storage services. |
| Zero-Trust Architecture Convergence | Links sensitivity metadata to identity infrastructure for dynamic access policies. |
| Edge Agent Miniaturization | Deploys lightweight classification models on manufacturing endpoints without cloud round-trips. |
| NLP Capability Acquisition | Targets transformer-based content discovery for unstructured legal and medical records. |
Research Methodology
The analysis maps file-level classification, content discovery, metadata tagging, and policy management segments, each validated through chief information security officers, data governance leads, cloud procurement officers, and compliance program directors. Primary fieldwork combined structured interviews with secondary validation against SEC cybersecurity disclosure filings, EU AI Act delegated act drafts, HIPAA breach notification databases, and hyperscaler service catalog disclosures. Bottom-up deployment volume estimates triangulated against top-down regulatory mandate sizing across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across cloud-native, hybrid, and on-premises deployment configurations. Segmentation dimensions modeled include solution architecture, deployment model, application priority, and end-user vertical with regional adoption pattern overlays. CAGRs derived from regression analysis of procurement cycle compression rates and vendor qualification timeline acceleration. Industry-specific forecast inputs incorporated EU AI Act enforcement phase transitions and NIST post-quantum cryptography standardization progress.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement intensity and cloud migration continuity; material deviation in quantum-resistant encryption timelines or cross-border data localization mandates would warrant model refresh. Recalibration cycles align with material shifts in EU AI Act delegated act publications and NIST standard finalization events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Europe Video Management System Market
Security Software
Global Email Verification Tools Market
Security Software
Secure Flash Drive Market
Security Software
Data Loss Prevention Market
Security Software
Employee Computer Monitoring Software Market
Security Software
Europe Anti-Money Laundering Software Market
Security Software
Video Intercom Devices and Equipment Market
Security Software
Robocall Mitigation Market
Security Software
Global Security Assertion Markup Language (SAML) Authentication Market
Security Software
Information Rights Management Market
Security Software
BYOD Security Market
Security Software
Global Wireless Intrusion Prevention System Market
Security Software
Employee Surveillance and Monitoring Software Market
Security Software
Europe User Provisioning Market
Security Software
Global Consumer IAM Market
Security Software
Mass Notification System Market