
 Secure Flash Drive Market | 2026-2036
Secure Flash Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Secure Flash Drive Market Analysis
Aftermarket firmware update services is tilting toward subscription-based enterprise licensing. Kingston Technology leverages its captive NAND flash supply chain to control cost structures across government contracts. Kanguru Solutions specializes in FIPS-certified device manufacturing, sustaining premium positioning in North American public-sector procurement. DataLocker competes through centralized management platforms that anchor fleet-wide policy enforcement for financial clients.
A secure flash drive is a portable NAND flash storage device integrating hardware or software cryptographic modules to enforce data confidentiality through AES-256 encryption, secure key storage, and tamper-evident enclosures; its primary purpose is to transport sensitive information across air-gapped or high-threat environments without exposing plaintext data to host system compromise. Hardware-encrypted units dominate unit economics due to their resistance to side-channel extraction, while biometric-encrypted variants capture expanding interest from legal firms and healthcare compliance officers seeking multi-factor physical authentication. The application landscape shows encrypted backup and compliance management as the fastest-growing revenue pools, reflecting regulatory pressure on retention and audit-readiness.
The National Institute of Standards and Technology administers FIPS 140-2 and FIPS 140-3 validation programs that gate U.S. federal procurement, while the European Union Agency for Cybersecurity promotes Common Criteria certification as a baseline for cross-border sensitive data handling. China's SAMR enforces GB/T cryptographic standards that fragment product architectures for domestic versus export-bound supply. Stakeholders must monitor divergence between national encryption export controls and mutual recognition agreements that could bifurcate R&D roadmaps.
Market Dynamics
FIPS 140-2 certification requirements and GDPR-mandated data localization rules are tightening compliance thresholds across government and enterprise procurement, compressing vendor qualification timelines and fragmenting product architectures by jurisdiction.
Growth Catalysts
- Federal procurement mandates:NIST-administered FIPS validation programs gate U.S. federal contracting, forcing hardware-encrypted device adoption across defense and civilian agencies.
- Healthcare compliance pressure:HIPAA security rule enforcement drives legal firms and medical practices toward biometric-authenticated storage for patient data portability.
- NAND flash supply concentration:Captive flash production in South Korea and Taiwan enables cost-controlled encryption module integration at scale.
Market Restraints
- Controller chip supply concentration:ASIC encryption processors rely on TSMC and Samsung foundry capacity, creating single-source vulnerability.
- GB/T standard fragmentation:China's SAMR enforces domestic cryptographic algorithms that bifurcate R&D roadmaps for export-bound versus China-market products.
- Cloud storage substitution:Zero-trust architecture adoption in financial services reduces physical media dependency for non-air-gapped workflows.
Strategic Opportunities
- India digital sovereignty push:BIS certification requirements and government data localization create procurement pull for indigenized encryption hardware.
- Subscription management platforms:Enterprise fleet policy enforcement tools enable recurring revenue attachment to hardware sales.
- Post-quantum cryptographic modules:NIST's PQC standardization timeline positions early module integration for defense sector pre-qualification.
Industry Challenges
- FIPS 140-3 migration complexity:Validation timeline compression from 18 to 24 months strains engineering resource allocation across product lines.
- Side-channel resistance engineering:Power analysis and electromagnetic leakage mitigation requires specialized hardware security expertise in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secure Flash Drive Market |
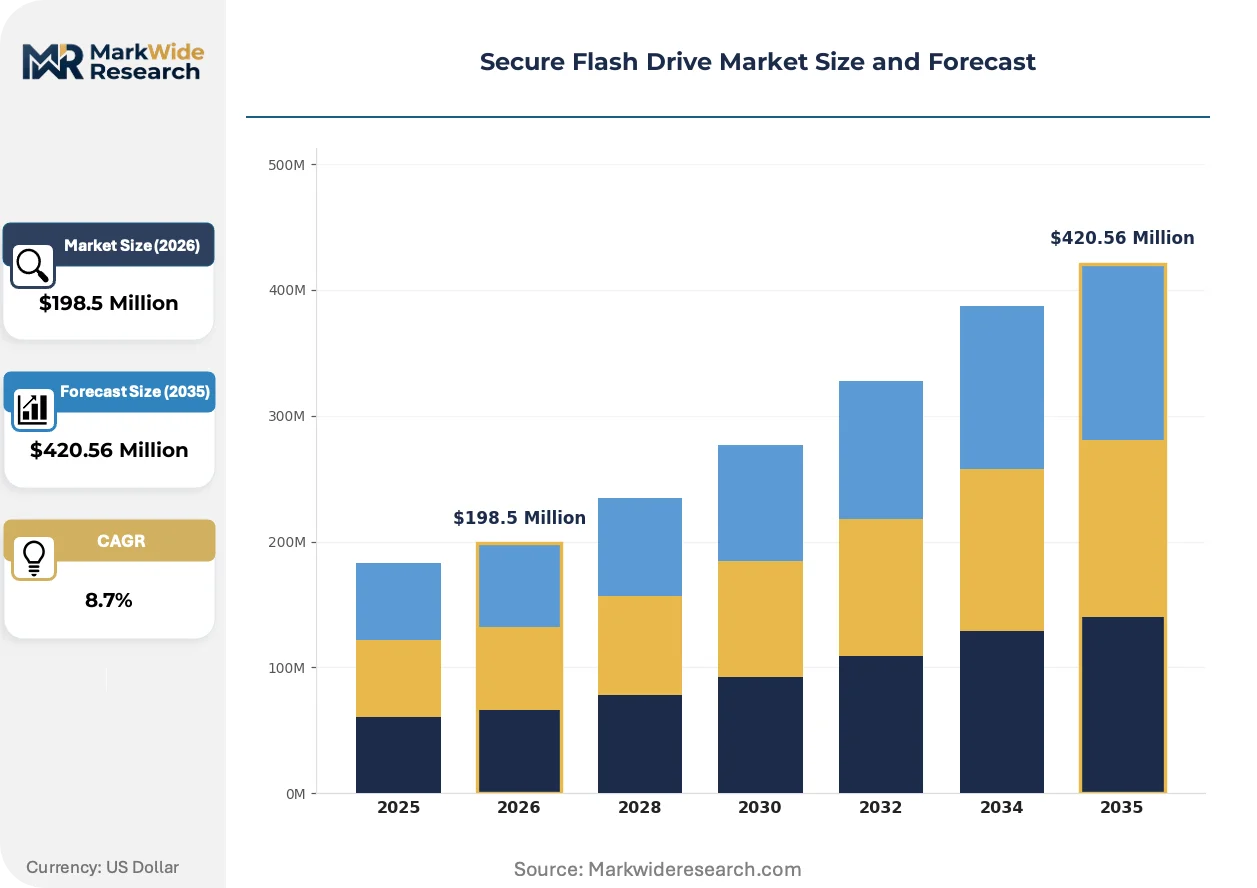
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $420.56 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware-Encrypted, Software-Encrypted, Biometric-Encrypted, Password-Protected, RFID-Based Application: Data Protection, Secure File Sharing, Encrypted Backup, Secure Corporate Communication, Compliance Management End User: Government Agencies, Financial Institutions, Legal Firms, Educational Organizations, Small & Medium Enterprises Distribution Channel: Online Retailers, OEMs, IT Resellers, Specialty Electronics Stores, Enterprise Vendors |
| Companies Covered | Kingston Technology, Kanguru Solutions, SanDisk, Transcend Information, DataLocker, Apricorn, iStorage, Verbatim, Integral Memory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secure Flash Drive Market Emerging Trajectories
Hardware-encrypted storage is hybridizing with identity management and centralized policy platforms, compressing the traditional boundary between physical media and enterprise security infrastructure.
Biometric-authenticated flash controllers are hybridizing fingerprint and PIN fallback architectures into single-chip solutions. Legal discovery firms and healthcare compliance officers in Germany and Japan are adopting these modules for multi-factor physical authentication. This convergence is hybridizing procurement criteria, collapsing standalone biometric and hardware-encrypted categories into unified specification checklists.
GDPR Article 44 cross-border transfer restrictions and EU AI Act data governance provisions are mandating localized encryption key custody. European defense contractors must now maintain EU-sovereign key management infrastructure, disqualifying U.S.-hosted cloud backup integration. French CNIL and German BSI guidance documents are accelerating Common Criteria certification adoption as a baseline procurement filter.
Enterprise buyers are consolidating vendor relationships around integrated fleet management platforms rather than discrete hardware procurement. Financial services CISOs in London and Singapore are unbundling device purchasing from policy enforcement software, favoring subscription-anchored contracts. This behavioral shift concentrates purchasing power with vendors offering unified hardware-software stacks, marginalizing pure-play device manufacturers.
Secure Flash Drive Market Segmentation
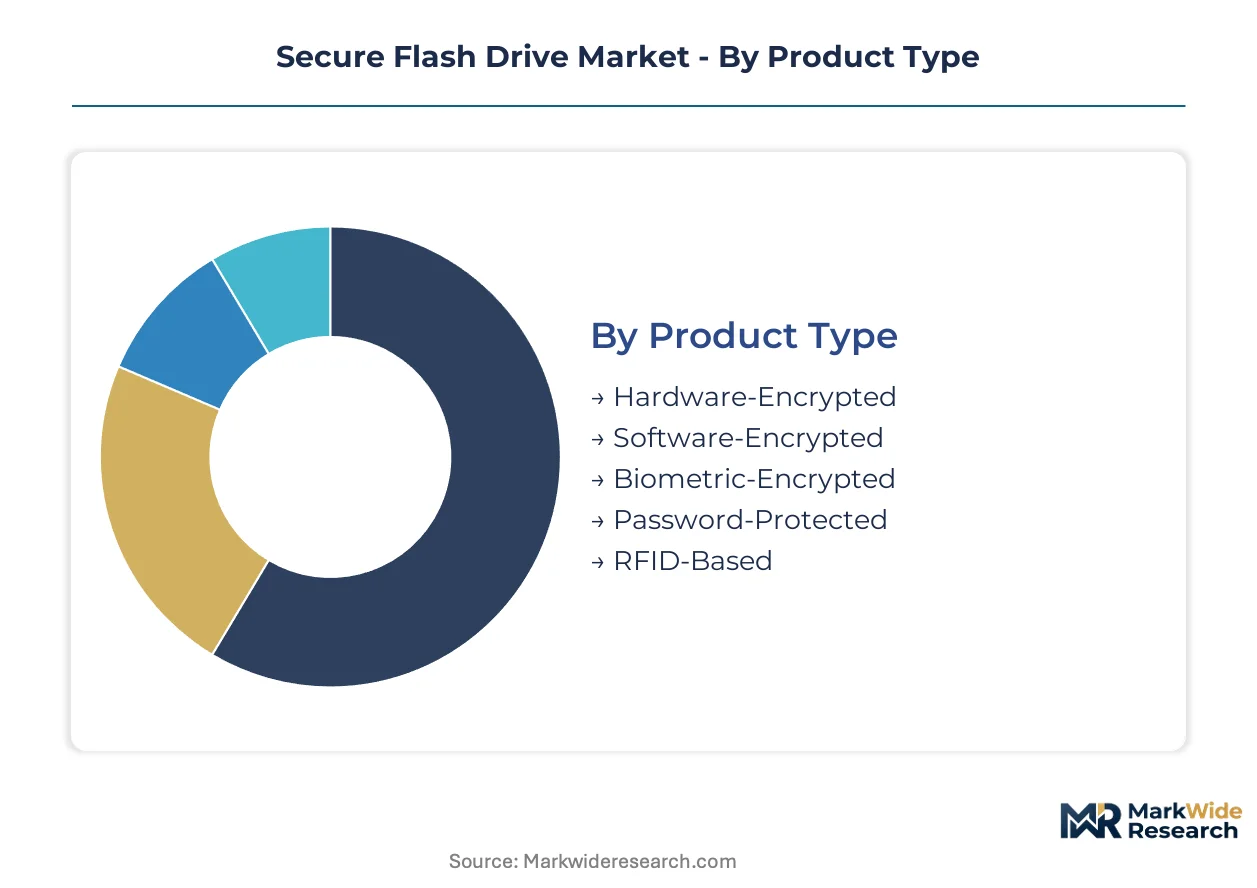
Segmentation in secure flash drives reflects divergent procurement cycles across federal, enterprise, and consumer channels. Hardware-encrypted units command extended validation timelines while biometric variants accelerate through healthcare compliance windows. Understanding these velocity differentials enables vendor resource allocation across certification-heavy and speed-to-market segments.
Product Type:
Replacement cycles stretch from 18-month consumer refresh patterns to 7-year federal deployment horizons, creating tiered inventory and support obligations across the supplier base.
- Hardware-Encrypted:ASIC-based cryptographic modules execute AES-256 operations in dedicated silicon isolated from host system buses. Federal agencies in the United States and defense contractors in Germany anchor procurement volumes under FIPS 140-2 and Common Criteria mandates, with validation timelines compressing vendor cash conversion cycles.
- Biometric-Encrypted:Fingerprint sensors fused with secure elements enable multi-factor physical authentication without host-dependent PIN entry. Legal discovery firms in Germany and hospital compliance officers in Japan drive adoption for HIPAA and GDPR-aligned patient data portability, with 24-36 month replacement cycles tied to sensor warranty periods.
- Software-Encrypted:Host-dependent encryption utilities leverage processor-based AES-NI instructions without dedicated hardware.
- Password-Protected:Basic PIN or password authentication without cryptographic module isolation serves cost-sensitive education and SME procurement.
- RFID-Based:Near-field authentication tokens pair with contactless readers for physical access-integrated data security in corporate campus deployments.
Hardware-Encrypted anchors the volume base while Biometric-Encrypted gains share at the steepest rate.
Application:
Margin structures compress from standardized backup utilities toward bespoke compliance platforms requiring ongoing audit documentation and policy attestation.
- Compliance Management:Integrated audit trails, key escrow, and retention policy enforcement address GDPR Article 44 localization and SEC record-keeping rules. Financial services CISOs in London and Singapore attach subscription-based policy platforms to hardware procurement, transforming one-time sales into recurring revenue relationships.
- Encrypted Backup:Air-gapped archival storage satisfies ransomware recovery mandates and regulatory retention requirements without cloud dependency. Healthcare networks in Japan and legal practices in Germany concentrate demand where patient and client data sovereignty prohibits third-party hosting.
- Data Protection:General-purpose confidentiality for portable intellectual property and personal information.
- Secure File Sharing:Cross-organizational transfer of sensitive documents between non-trusted network boundaries.
- Secure Corporate Communication:Classified briefing materials and executive correspondence in high-threat travel environments.
Encrypted Backup sustains the largest installed base while Compliance Management expands most quickly through subscription attachment.
End User:
Procurement sophistication escalates from volume-driven SME tenders toward specification-heavy federal contracts with multi-year validation prerequisites.
- Government Agencies:NIST FIPS 140-2/140-3 validation and NSA CSfC program compliance gate entry to U.S. federal, German BSI, and Japanese defense procurement. Contract vehicles span 3-5 year ordering periods with mandatory domestic sourcing provisions and supply chain attestation.
- Financial Institutions:FFIEC and PCI-DSS audit requirements drive fleet-wide encryption with centralized key management. Banks in Singapore and asset managers in London consolidate vendor relationships around integrated hardware-software stacks with API-accessible policy enforcement.
- Legal Firms:Attorney-client privilege protection and discovery process integrity in cross-border litigation.
- Educational Organizations:FERPA-aligned student data protection with constrained IT security staffing.
- Small & Medium Enterprises:Cost-optimized encryption without dedicated security infrastructure or compliance officers.
Government Agencies dominate contract value while Financial Institutions drive the steepest platform consolidation trajectory.
Distribution Channel:
Channel economics fragment between low-touch digital fulfillment and high-touch enterprise consultative selling with implementation services.
- Enterprise Vendors:Direct sales organizations with certified security engineers configure fleet deployments, integrate with SIEM infrastructure, and deliver compliance documentation. Multi-year enterprise license agreements in North American federal contracting and European defense sectors concentrate purchasing power with vendors offering unified policy platforms.
- IT Resellers:Value-added distributors provide pre-sales technical validation, staging services, and post-deployment support for mid-market accounts lacking dedicated security architecture teams.
- Online Retailers:Self-service procurement with standardized SKUs for consumer and SME segments.
- OEMs:Bundled integration with laptop, workstation, and server manufacturer security offerings.
- Specialty Electronics Stores:Physical retail presence for immediate procurement in regulated facility proximity requirements.
Enterprise Vendors capture the premium contract base while IT Resellers expand most quickly through mid-market security outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between federal procurement systems and enterprise fleet deployments. Government agencies in the United States and Germany anchor hardware-encrypted volumes through multi-year validation contracts, while financial institutions in Singapore and Japan prioritize subscription-anchored management platforms over discrete device purchasing.
United States
Defense contractors and civilian agencies drive FIPS 140-2 validated procurement through NIST-administered programs. The NSA's Commercial Solutions for Classified (CSfC) framework gates entry to sensitive compartmented information environments. Washington DC and Northern Virginia host concentrated vendor presences serving federal contracting vehicles with 3-5 year ordering periods.
Germany
BSI technical guidelines and Common Criteria certification requirements shape defense and automotive sector demand. GDPR Article 44 localization mandates disqualify U.S.-hosted key management for cross-border sensitive data handling. Munich and Stuttgart industrial clusters anchor procurement for automotive supply chain confidentiality requirements.
Japan
METI cybersecurity frameworks and healthcare network modernization drive biometric-authenticated adoption for patient data portability. Hospital compliance officers in Tokyo and Osaka concentrate demand where third-party cloud hosting faces regulatory friction. Domestic encryption module integration satisfies government data sovereignty preferences.
Singapore
Financial institution CISOs consolidate vendor relationships around API-accessible policy enforcement platforms. MAS technology risk management guidelines mandate encryption for cross-border data flows in asset management and private banking. The city-state's regional headquarters concentration amplifies procurement influence across Southeast Asian operations.
India
BIS certification requirements and government data localization create procurement pull for indigenized encryption hardware. Defense and public sector digitization initiatives under digital sovereignty programs compress vendor qualification timelines. Bengaluru and Hyderabad technology corridors host emerging domestic module integration capabilities.
Secure Flash Drive Market Vendor Landscape
Capability concentration sits with validation-heavy specialists; scale advantage sits with NAND-integrated manufacturers. The vendor base stratifies across three tiers: captive flash producers with cost-controlled encryption integration, FIPS-certified device specialists sustaining premium positioning, and centralized management platform providers anchoring subscription revenue. Dominant competitive moves include backward integration into NAND supply and enterprise software stack attachment to hardware procurement.
Within the captive supply tier, Kingston Technology exemplifies cost structure control through integrated NAND flash production. Kanguru Solutions and DataLocker occupy distinct positioning vectors in the North American federal contracting space, with the former representing FIPS-certified manufacturing specialization and the latter exemplifying policy platform consolidation for financial services fleet management.
| Leading Market Players |
|---|
| Kingston Technology |
| Kanguru Solutions |
| SanDisk |
| Transcend Information |
| DataLocker |
| Apricorn |
| iStorage |
| Verbatim |
| Integral Memory |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Los Angeles maritime corridor's container rate volatility directly compresses margins on NAND flash module imports from Taiwan and South Korea, forcing vendors to differentiate pricing across FIPS-certified premium tiers versus standard hardware-encrypted units while absorbing logistics cost spikes into long-term federal contract structures.
Pricing Analysis
Long-term offtake agreements dominate federal procurement, with multi-year ordering vehicles locking unit economics for validated hardware-encrypted devices while spot-market exposure concentrates in SME channels. Price differentiation rests on FIPS 140-2 certification tier and captive NAND integration depth, with Kingston Technology's backward integration enabling cost-controlled positioning against specialist competitors. Cost compression in the standard hardware-encrypted tier intensifies because TSMC foundry capacity constraints elevate ASIC controller costs. Government agencies exhibit the lowest price sensitivity due to mandate-driven procurement, while educational organizations and SMEs face acute budget constraints.
Supply Chain Analysis
Extended payment terms from Taiwanese and South Korean NAND suppliers to module integrators compress working capital cycles for encryption device manufacturers. Geographic supply concentration centers on Taiwan for ASIC controller fabrication, South Korea for captive NAND production, and China for PCB assembly and enclosure manufacturing. Raw material dependencies include AES-256 cryptographic processors, tamper-evident enclosure resins, and fingerprint sensor modules. Single-source vulnerability in TSMC encryption processor capacity creates supply chain risk. Distribution runs through enterprise vendor direct sales for federal contracts, IT resellers for mid-market penetration, and online retailers for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The secure flash drive market sits in early-cycle expansion as post-quantum cryptographic pre-qualification mandates create replacement demand across defense sector installed bases before NIST standardization finalizes.
For Market Incumbents: Pre-empt cloud storage substitution threats by anchoring hardware procurement to subscription-based fleet management platforms with centralized policy enforcement. Deepen backward integration into NAND supply through foundry partnerships or captive wafer agreements to defend margin position against cost-controlled competitors. Accelerate FIPS 140-3 validation pipelines to compress 18-24 month qualification timelines before federal procurement windows shift. For New Entrants and Emerging Players: Establish a beachhead in India's BIS-certified encryption hardware segment where digital sovereignty initiatives compress vendor qualification barriers for indigenized module integration. Target biometric-authenticated variants for German legal discovery firms and Japanese hospital compliance officers seeking GDPR-HIPAA aligned patient data portability. Pursue API-accessible policy platform partnerships with regional IT resellers to bypass direct federal contracting certification requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with dormant encryption hardware divisions lacking enterprise software stack integration. Long-term viability hinges on subscription revenue attachment rates rather than discrete device margins. Monitor NIST post-quantum cryptographic standardization announcements as the inflection signal for defense sector pre-qualification spending acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptographic Module Integration | NIST standardization timeline positions early movers for defense sector pre-qualification contracts. |
| Subscription Management Platform Launch | Financial services CISOs in London and Singapore unbundle hardware from policy enforcement software. |
| India BIS Certification Investment | Domestic encryption module integration satisfies government data sovereignty procurement preferences. |
| Biometric-PIN Hybrid Controller Development | German legal discovery firms and Japanese healthcare compliance officers demand multi-factor authentication. |
| Captive NAND Supply Agreement | Kingston Technology's cost structure control demonstrates competitive positioning through upstream integration. |
Methodological Framework
The analysis maps hardware-encrypted, biometric-encrypted, software-encrypted, password-protected, and RFID-based product categories, each validated through primary interviews with federal procurement officers, healthcare compliance directors, financial services CISOs, and encryption hardware engineering leads, combined with secondary triangulation across NIST FIPS validation databases, Common Criteria certification registries, SEC supplier disclosure filings, and customs trade data for NAND flash module flows.
Assumption sets held regulatory certification timelines and NAND flash supply concentration fixed while varying cloud storage substitution rates and post-quantum cryptographic adoption curves across the projection horizon. The analytical framework models product type, application, end user, and distribution channel segmentation dimensions, deriving CAGRs from bottom-up unit economics triangulated against top-down addressable market sizing with inputs from federal contract vehicle disclosures and healthcare network modernization budgets.
Stress conditions across TSMC foundry capacity allocation, FIPS 140-3 validation timeline compression, and GDPR Article 44 enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumption sets; macroeconomic contraction, encryption export control divergence, or breakthrough quantum computing timelines would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Insider Threat Management ITM Software Market
Security Software
Web Content Filtering Market
Security Software
Video Intercom Devices and Equipment Market
Security Software
Mobile Data Protection Solutions and Services Market
Security Software
Privileged Access Management (PAM) Market
Security Software
Content Protection and Watermarking Market
Security Software
Secure Web Gateway Market
Security Software
Smart Video Doorbell Market
Security Software
Global SMS Firewall Market
Security Software
Global Enterprise Data Loss Prevention Software Market
Security Software
Digital Risk Protection Platform Market
Security Software
Passport Reader Market
Security Software
Global Data Classification Market
Security Software
Public Key Infrastructure (PKI) Market
Security Software
Mobile Security Market
Security Software
Europe IP Video Intercom Device and Equipment Market