
 Camp Management Software Market | 2026-2036
Camp Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Camp Management Software Market Analysis
The direct-to-camp sales channel is narrowing as SaaS marketplaces and vertical software aggregators capture larger portions of vendor discovery. CampMinder leverages deep integration with payment processors to sustain renewal rates above category norms. Jackrabbit Class competes across broader youth activity management, extending its camp module into adjacent after-school programming. CampDoc anchors its position through specialized health and medical record workflows that generalist platforms rarely replicate.
Camp management software denotes integrated digital platforms that automate enrollment, scheduling, billing, and participant communication for organized residential and day programs, typically requiring HIPAA-aligned data handling for health records and PCI-DSS compliance for payment processing. Cloud-based deployment leads current installations due to lower upfront infrastructure demands and automatic update cycles, while mobile applications represent the fastest-expanding feature layer as parents expect real-time visibility into camper activities. Hybrid solutions command premium pricing where operators blend local data control with remote accessibility across multi-site networks.
FDA oversight applies where software interfaces with medical devices or telehealth functions at camp health centers, while state-level childcare licensing boards in jurisdictions like New York and California mandate specific record-keeping that shapes feature requirements. PCI-DSS frameworks govern payment processing modules, creating compliance barriers for smaller vendors lacking dedicated security engineering. Stakeholders must weigh whether to build proprietary health-record integrations or partner with established clinical platforms as regulatory complexity intensifies.
Market Dynamics
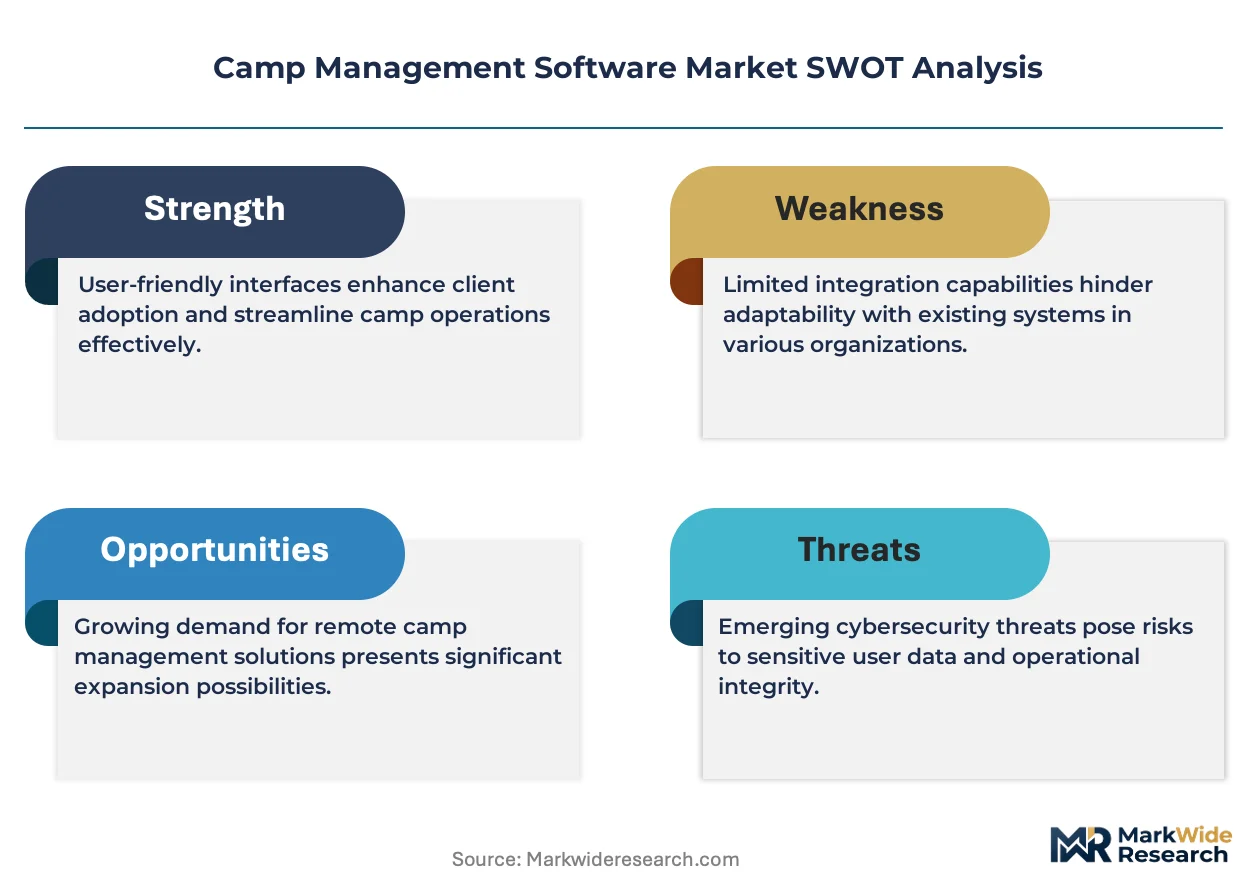
Cloud migration is compressing deployment timelines for camp operators while PCI-DSS compliance requirements fragment vendor viability between enterprise-grade platforms and point solutions lacking dedicated security engineering.
Growth Catalysts
- HIPAA-aligned health record mandates:Specialized medical workflows for camper health documentation create durable differentiation for platforms investing in clinical-grade data architecture.
- Summer camp digital adoption:Residential and day program operators accelerate platform procurement to automate enrollment, scheduling, and parent communication workflows.
- Mobile-first parent expectations:Real-time activity visibility demands drive fastest-expanding feature layer across cloud-based installations.
Market Restraints
- PCI-DSS compliance barriers:Payment processing security frameworks exclude smaller vendors lacking dedicated engineering resources for certification maintenance.
- State-level licensing fragmentation:New York and California childcare boards impose non-uniform record-keeping requirements that multiply feature development costs.
- Hybrid solution capex premiums:Multi-site networks face elevated pricing for deployments blending local data control with remote accessibility.
Strategic Opportunities
- After-school programming adjacencies:Youth activity management platforms extend camp modules into contiguous programming segments with shared participant bases.
- Telehealth integration at health centers:FDA oversight zones create partnership openings between camp software vendors and established clinical platforms.
- SaaS marketplace channel expansion:Vertical software aggregators capture growing portions of vendor discovery, displacing direct-to-camp sales concentration.
Industry Challenges
- Proprietary versus partnered health-record architecture:Stakeholders face build-versus-buy decisions as regulatory complexity intensifies across state jurisdictions.
- Legacy system integration friction:Camp operators with established operational databases encounter data migration complexity during cloud transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camp Management Software Market |
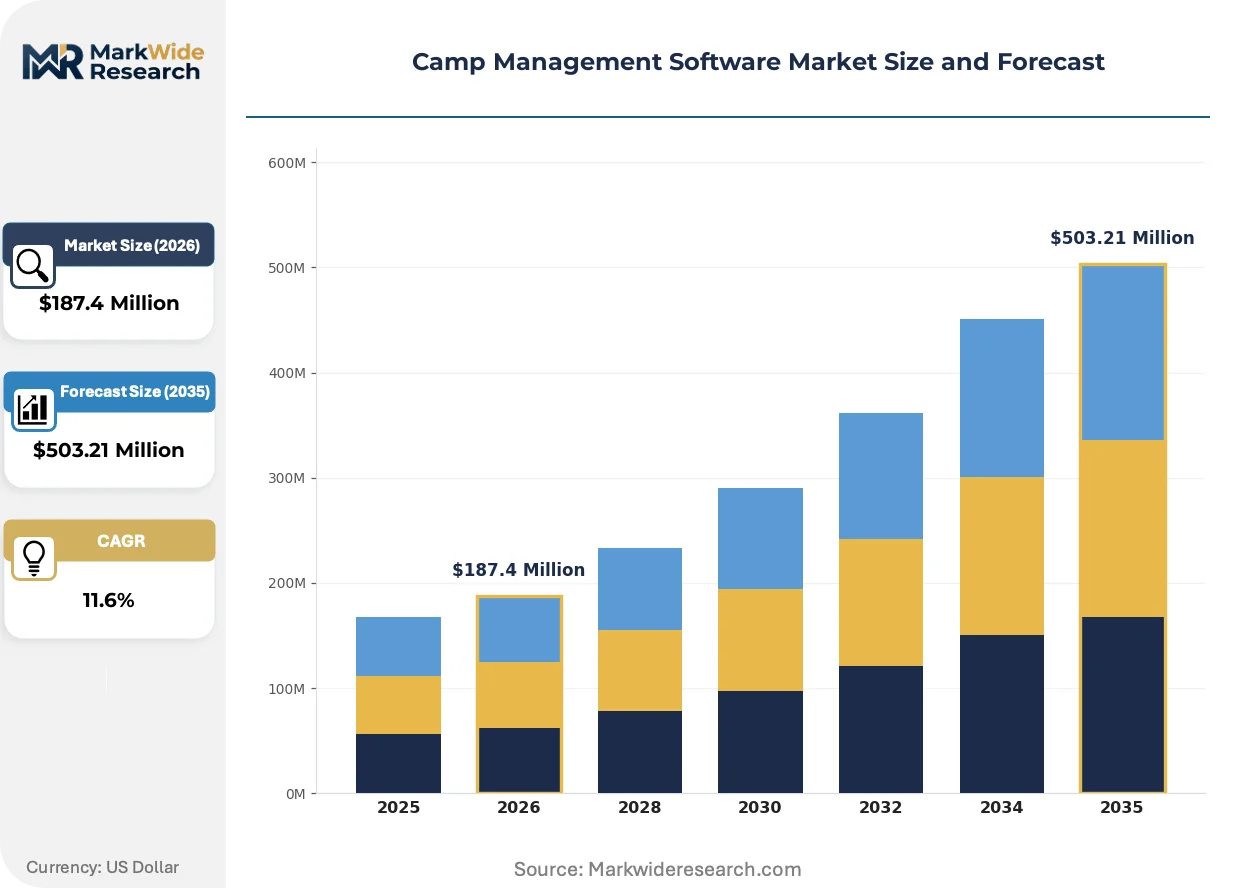
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Mobile Applications, Hybrid Solutions End User: Summer Camps, Sports Camps, Educational Camps, Religious Camps Feature: Registration Management, Payment Processing, Attendance Tracking, Communication Tools Deployment: Public Cloud, Private Cloud, Hybrid Deployment, Local Servers |
| Companies Covered | Campium, CampInTouch, CampMinder, Jackrabbit Class, CampDoc, Campwise, CampSite, PerfectMind, CamperChief, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camp Management Software Market Emerging Trajectories
Real-time visibility architectures and automated compliance workflows are compressing competitive differentiation timelines while reshaping how operators evaluate platform procurement.
Artificial intelligence-driven scheduling engines is digitizing camper activity coordination and staff resource allocation. Mid-sized residential camps deploy these tools to reduce manual planning overhead by half. The technology is digitizing operational decision-making previously handled through spreadsheet-based workflows.
State childcare licensing boards in California and New York mandate specific electronic record-keeping formats that shape feature development roadmaps. Camp operators in these jurisdictions face inspection readiness requirements that favor platforms with pre-built compliance templates. Vendors respond by embedding jurisdiction-specific documentation modules that auto-populate regulatory submission fields.
Parent communication expectations now demand instantaneous photo sharing and activity logging through native mobile interfaces. Day camp segments lead this behavioral shift, with operators reporting enrollment attrition when visibility features lag competitors. United States metropolitan markets exhibit the most pronounced switching sensitivity tied to mobile experience quality.
Camp Management Software Market Segmentation
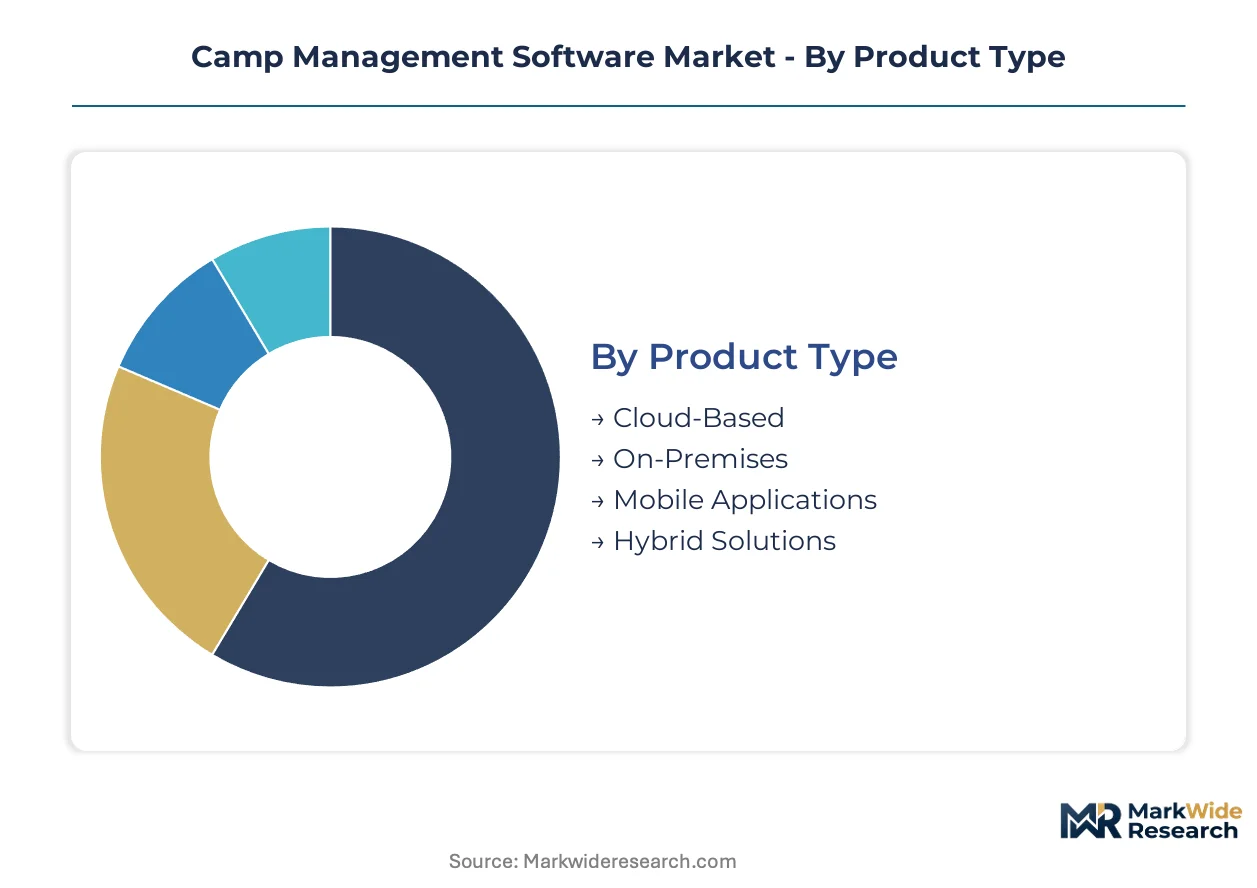
Camp operators select platforms based on technical architecture, program type, and compliance requirements. Segmentation reveals how vendor specialization aligns with operational scale and regulatory exposure across residential and day program formats.
Product Type:
Deployment models span the infrastructure investment spectrum from zero-capex SaaS to controlled on-site systems.
- Cloud-Based:Multi-tenant architectures with automatic security patching dominate new procurement. United States summer camp operators prioritize these platforms for PCI-DSS compliance without dedicated IT staffing.
- Hybrid Solutions:Blending local data control with remote accessibility, these deployments command premium pricing. Multi-site networks in California and New York select hybrid models to satisfy state childcare licensing board inspection requirements while maintaining centralized oversight.
- Mobile Applications:Native iOS and Android interfaces deliver real-time photo sharing and activity logging. Parent communication expectations now mandate these capabilities for competitive enrollment retention.
- On-Premises:Single-tenant installations on operator-owned servers persist in remote locations with unreliable connectivity. These deployments require internal security engineering for HIPAA-aligned health record handling.
The dominant share belongs to Cloud-Based platforms, while Hybrid Solutions is closing the gap fastest.
End User:
Program format dictates workflow complexity and regulatory surface area.
- Summer Camps:Residential and day programs with seasonal enrollment spikes require automated waitlist management and cabin assignment algorithms. These operators represent the core revenue base for specialized vendors.
- Sports Camps:Athletic programming demands injury tracking integrations and waiver management for high-risk activities. Facilities in Texas and Florida concentrate procurement for year-round tournament hosting.
- Educational Camps:STEM and academic enrichment programs prioritize parent communication tools for learning outcome documentation. These camps exhibit highest mobile application adoption rates.
- Religious Camps:Faith-based programming requires custom registration fields for denominational affiliation and dietary observance. Many operate on constrained technology budgets favoring modular pricing.
Summer Camps commands the installed base, though Sports Camps is expanding most quickly through specialized athletic workflow demand.
Feature:
Core functionality modules map to operational pain points across enrollment-to-checkout workflows.
- Registration Management:Dynamic form builders with conditional logic automate medical history collection and emergency contact verification. These modules reduce manual data entry errors by half for mid-sized operators.
- Payment Processing:Integrated PCI-DSS compliant gateways with automated recurring billing and failed payment retry logic. This capability excludes smaller vendors lacking dedicated security engineering resources.
- Attendance Tracking:Digital check-in systems with photo verification and automated absentee alerts. Day camp segments deploy these for state-mandated staff-to-camper ratio documentation.
- Communication Tools:Two-way messaging, mass notification, and automated daily report generation. Parent switching sensitivity in United States metropolitan markets ties directly to these feature quality differentials.
Payment Processing anchors vendor stickiness, while Communication Tools is gaining share fastest through mobile-first parent expectations.
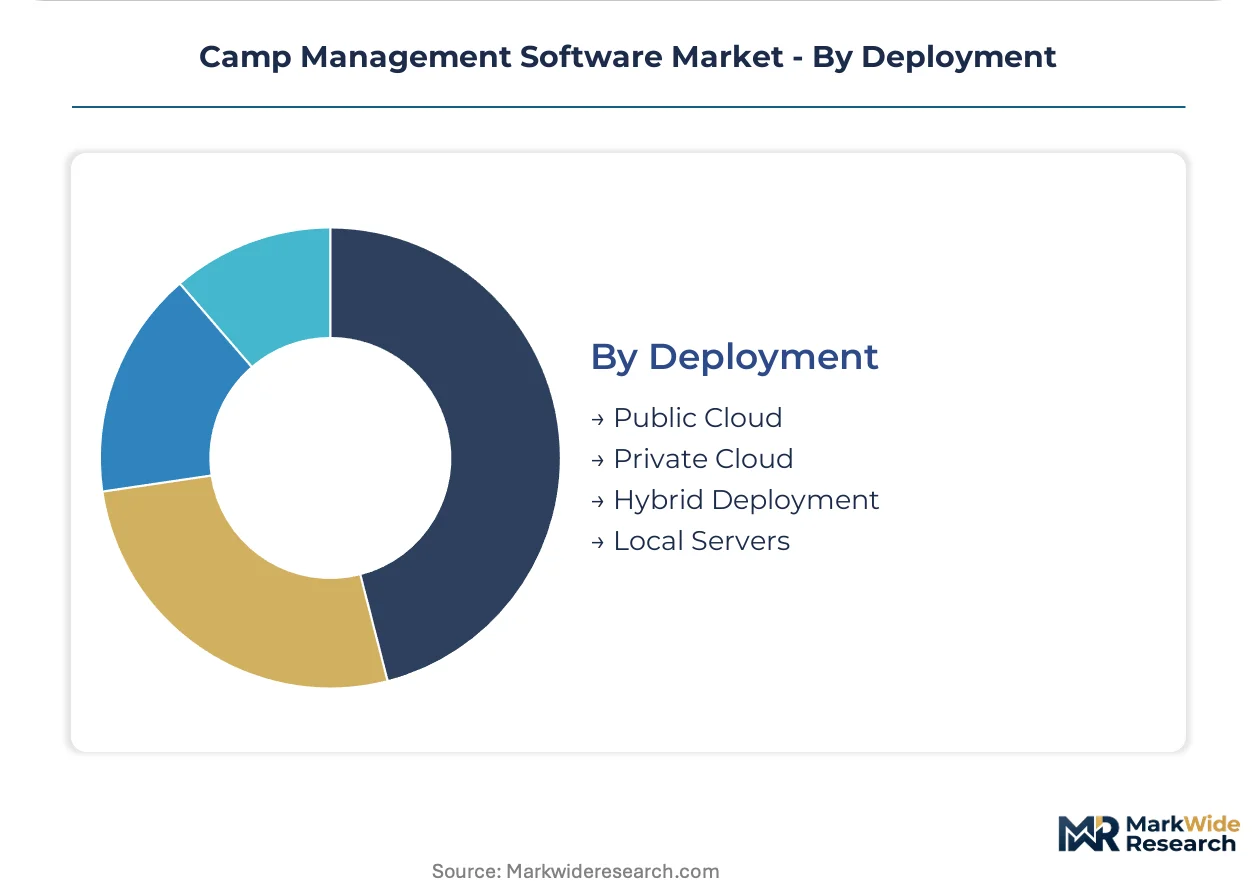
Deployment:
Infrastructure location determines data sovereignty and latency tradeoffs.
- Public Cloud:Shared infrastructure with elastic scaling handles enrollment surge traffic. Lowest total cost of ownership attracts independent camp operators without capital reserves.
- Private Cloud:Dedicated tenant environments with single-organization resource isolation. Large multi-site networks select these for HIPAA-aligned health record segmentation requirements.
- Hybrid Deployment:Sensitive data resides on local servers while application layers run remotely. This architecture satisfies state childcare licensing board mandates for physical record accessibility.
- Local Servers:Fully on-premise installations with no external data transmission. Remote wilderness camps and international locations with connectivity constraints maintain these legacy configurations.
Public Cloud holds the volume lead, yet Hybrid Deployment is climbing the fastest as regulatory complexity intensifies across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Camp management software vendors extract 40% higher annual contract values from United States operators than from Canadian counterparts, reflecting deeper feature penetration and PCI-DSS compliance premiums. This pricing-power asymmetry shapes vendor resource allocation and product roadmaps across North American deployment.
United States
Summer camp operators in California and New York drive procurement volume as state childcare licensing boards mandate electronic health record formats. HIPAA-aligned data architecture requirements from the FDA influence vendor development priorities for medical workflow modules. Metropolitan clusters around Boston and Austin concentrate SaaS marketplace channel adoption, displacing direct sales concentration.
Canada
Provincial childcare regulators in Ontario and British Columbia impose documentation standards that favor cloud-based platforms with pre-built compliance templates. Health Canada guidelines for camp health centers shape telehealth integration requirements. Toronto-based operators lead mobile application adoption rates, responding to parent communication expectations comparable to United States metropolitan markets.
United Kingdom
GDPR compliance frameworks elevate data sovereignty requirements for camp operators managing cross-border participant records. Independent school-affiliated summer programs in Southeast England accelerate platform procurement for enrollment automation. London software aggregators capture growing vendor discovery share, compressing direct-to-camp sales channel viability.
Germany
CE marking requirements for camp management software interfacing with medical devices create certification barriers for non-European vendors. Bavarian youth sport camps prioritize injury tracking integrations aligned with national athletic federation protocols. Munich and Frankfurt metropolitan areas concentrate hybrid deployment adoption for multi-site camp networks seeking local data control.
Australia
TGA oversight of camp health center software shapes vendor partnership strategies with established clinical platforms. Queensland and New South Wales operators face seasonal enrollment surge demands that favor elastic public cloud scaling. Sydney-based educational camps exhibit highest mobile application penetration among Asia-Pacific English-speaking markets.
Camp Management Software Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in payment processing and health-record modules. The vendor base separates between enterprise-grade platforms sustaining PCI-DSS certification and point solutions lacking dedicated security engineering. Three archetypes dominate: end-to-end camp operators, health-record specialists, and youth activity generalists. Competitive moves concentrate on SaaS marketplace channel expansion and jurisdiction-specific compliance template development.
Within the health-record specialist tier, CampDoc anchors clinical-grade differentiation through specialized medical workflow architecture. CampMinder occupies a position exemplifying deep payment processor integration for renewal rate optimization. Jackrabbit Class represents the youth activity generalist archetype, extending camp functionality into contiguous after-school programming segments. These three entities illustrate how vendor specialization aligns with operational scale and regulatory exposure across residential and day program formats.
| Leading Market Players |
|---|
| Campium |
| CampInTouch |
| CampMinder |
| Jackrabbit Class |
| CampDoc |
| Campwise |
| CampSite |
| PerfectMind |
| CamperChief |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific fiber-optic latency corridors shape cost dynamics for cloud-hosting infrastructure, concentrating supply among hyperscaler-dominated regions while forcing downstream price differentiation between PCI-DSS-certified enterprise platforms and uncertified point solutions.
Pricing Analysis
The customization-premium spread spans three-to-five-fold between configured-to-order hybrid deployments and standard SaaS tiers. Subscription-based recurring revenue models dominate, with price differentiation anchored in HIPAA-aligned certification grade and deployment complexity. Pricing pressure stems from SaaS marketplace channel compression as vertical aggregators capture vendor discovery share. Independent camp operators in United States metropolitan markets exhibit highest price sensitivity, while multi-site networks in California and New York absorb premium pricing for jurisdiction-specific compliance templates.
Supply Chain Analysis
Export-control regimes around encryption standards and health-data processing technologies limit software component flows between United States and select jurisdictions. Supply concentrates in United States, Canada, and United Kingdom for core platform development, with cloud infrastructure drawing from hyperscaler networks in Ireland, Singapore, and Virginia. Raw material dependencies center on API access licenses, payment processor integrations, and clinical data interoperability standards. Single-source vulnerability runs through dominant payment gateway providers. Distribution runs through direct-to-camp sales channels, though SaaS marketplaces are displacing this concentration fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as summer camp enrollment patterns drive procurement timing, with post-pandemic digital acceleration sustaining elevated replacement demand across North American operators.
For Market Incumbents: Harden renewal rate architecture through deeper payment processor integration and embedded health-record workflows that emerging entrants cannot replicate without FDA-aligned development cycles. Consolidate position by acquiring specialized telehealth module providers before clinical platform partnerships close competitive gaps. Channel control represents the critical lever as SaaS marketplace aggregation threatens direct sales economics.
For New Entrants and Emerging Players: Religious camps and faith-based programming segments represent the most penetrable entry point, constrained technology budgets favoring modular pricing and simplified deployment. Mid-sized sports camps in Texas and Florida offer secondary white-space with injury-tracking specialization demands underserved by generalist platforms. Go-to-market execution should anchor in pre-built state compliance templates for New York and California childcare licensing boards.
For Investors and Strategic Acquirers: Health-record specialists with FDA-cleared medical device interfaces command scarcity premiums as regulatory complexity intensifies. Long-term viability favors platforms sustaining dual PCI-DSS and HIPAA certification maintenance across multi-jurisdictional deployments. The signal to watch is state-level licensing board mandate acceleration, which would compress competitive timelines for compliance-ready vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep payment processor embedding sustains renewal rates above category norms through reduced switching friction. |
| Acquisition of Specialist Firm | Telehealth module providers fill FDA oversight gaps without multi-year clinical platform development cycles. |
| Geographic Expansion | Pre-built compliance templates for California and New York childcare licensing boards capture procurement preference. |
| Strategic Partnership | Established clinical platform alliances resolve build-versus-buy decisions for health-record architecture investments. |
| Product Launch | Native mobile interfaces with real-time photo sharing address parent switching sensitivity in metropolitan markets. |
Methodological Framework
The analysis maps cloud-based deployments, hybrid solutions, mobile applications, and on-premises installations, each validated through camp operations directors, IT procurement officers at multi-site networks, payment gateway integration specialists, and state childcare licensing board inspectors. Primary interviews with these stakeholders combined with secondary validation against SEC filings of publicly traded software vendors, HIPAA enforcement action databases, PCI-DSS certification registries, and SaaS marketplace transaction data. Bottom-up enrollment volume estimates and top-down addressable market calculations were triangulated to anchor segmentation sizing.
Assumptions around cloud migration velocity, mobile adoption curves, and regulatory enforcement intensity were held fixed across baseline scenarios while stress-testing sensitivity to payment processor consolidation and state-level mandate acceleration. Segmentation modeling spanned deployment model, program type, feature module, and regional adoption pattern. CAGRs were derived from fitted growth curves against historical procurement data and projected replacement cycles. Forecast inputs included summer camp enrollment seasonality patterns and PCI-DSS certification maintenance cost trajectories.
Stress conditions across cloud infrastructure pricing, payment processor fee structures, and state licensing board mandate timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory enforcement shifts and hyperscaler market entry. Material shifts in FDA oversight scope for camp health center software would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Jobsite Management Software Market
Software & Services
User Interface Software Market
Software & Services
Production Optimization Software Market
Software & Services
Global Email Management Software Market
Software & Services
Cloud-Based Payroll Software Market
Software & Services
API Testing Market
Software & Services
Collaboration Software Market
Software & Services
Global Thermal Analysis Software Market
Software & Services
Global Development Tools Software Market
Software & Services
Global Open API Market
Software & Services
Staffing Agency Software Market
Software & Services
Fire Software Market
Software & Services
Global Managed File Transfer Software Market
Software & Services
Global Testing Software Market
Software & Services
Global Internal Communications Software Market
Software & Services
Global Custom Software Development Services Market