
 Global Software Resellers Market | 2026-2036
Global Software Resellers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Software Resellers Market Foresight
Subscription-based financing and asset-light leasing models are narrowing the capital barrier for mid-tier resellers to compete against established distributors. CDW leverages its federal contracting infrastructure to sustain dominance in public-sector software procurement. Insight Enterprises anchors its competitive position through deep specialization in cloud migration services and hybrid deployment architectures. Bechtle competes across European enterprise accounts with a differentiated focus on managed service provider capabilities and long-term licensing partnerships.
Software resellers function as intermediary entities that aggregate, license, and distribute third-party software solutions to end-user organizations, typically layering technical implementation, compliance validation, and ongoing support atop core license transactions. Their primary commercial purpose centers on reducing procurement complexity for buyers while extending software vendors' market reach through established trust relationships and localized technical expertise. Cloud Solution Providers and Managed Service Providers represent the fastest-expanding partner-type segments, as recurring revenue models and embedded operational support command superior margin retention compared to transactional perpetual-license resale. Hybrid deployment models are gaining structural prominence among client organizations seeking to balance legacy on-premise investments against cloud scalability requirements without full infrastructure displacement.
FDA oversight of software-as-medical-device classifications, HIPAA security rule enforcement for business associates, and EU GDPR data processing agreements collectively reshape reseller liability frameworks and due diligence obligations across transatlantic software supply chains. The SEC's cybersecurity disclosure rules for publicly traded entities further elevate the compliance burden that resellers must absorb when advising financial services clients. Stakeholders must monitor how evolving AI procurement guidelines from NIST and analogous standards bodies redefine vendor qualification criteria and contract terms for software intermediaries.
Market Dynamics
Cloud Solution Providers and Managed Service Providers are capturing margin from traditional transactional resellers by embedding operational support into recurring revenue frameworks, fundamentally restructuring how software intermediaries monetize client relationships.
Growth Catalysts
- Federal Cloud Migration Mandates:United States government agencies are channeling procurement through authorized reseller networks to meet FedRAMP and NIST 800-53 compliance requirements, expanding addressable contract volume for certified intermediaries.
- HIPAA Security Rule Enforcement:Healthcare enterprises facing OCR audit expansion are prioritizing resellers with validated business associate agreements and security risk assessment capabilities over direct vendor relationships.
- AI Governance Frameworks:The EU AI Act's risk-based classification system is creating specialized demand for resellers capable of documenting conformity assessments and technical documentation for high-risk software deployments.
Market Restraints
- Vendor Consolidation Risk:Microsoft's Cloud Solution Provider program and analogous direct-to-customer licensing portals are compressing intermediary margins by reducing exclusive distribution territories.
- Certification Cost Burden:ISO 27001 and SOC 2 Type II compliance requirements for serving financial services clients impose six-figure annual audit costs that disadvantage smaller resellers.
- Hybrid Integration Complexity:Legacy on-premise ERP systems from SAP and Oracle resist seamless cloud connectivity, forcing resellers to absorb expensive professional services overhead without guaranteed recurring revenue.
Strategic Opportunities
- India Digital Infrastructure Expansion:The country's PLI scheme for IT hardware and data center localization requirements are creating demand for resellers bridging multinational software vendors with domestic compliance mandates.
- Embedded Operational Support:Converging endpoint detection and response platforms with managed security service delivery enables resellers to capture multi-year contracts previously held by pure-play cybersecurity vendors.
- SEC Cybersecurity Disclosure Rules:Publicly traded entities in the United States require reseller partners capable of documenting supply chain risk management and incident response capabilities for 8-K filing support.
Industry Challenges
- Multi-Cloud Architecture Expertise Scarcity:Resellers struggle to staff certified engineers across AWS, Azure, and Google Cloud Platform simultaneously, fragmenting service quality and extending implementation timelines.
- Software-as-Medical-Device Liability:FDA 510(k) clearance requirements for clinical decision support tools expose resellers to product liability claims previously borne solely by manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Software Resellers Market |
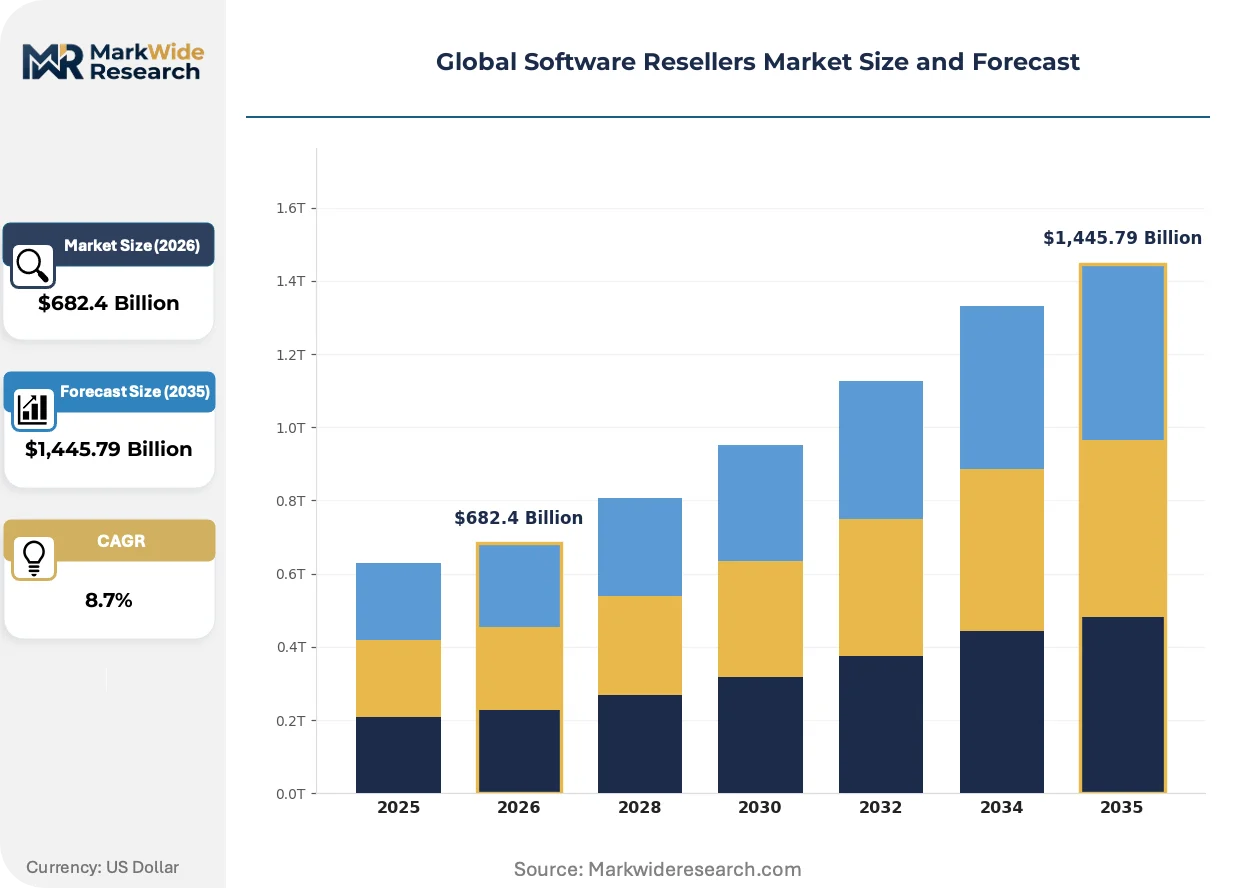
| Market Size in 2026 | $682.4 Billion |
| Market Size in 2035 | $1,445.79 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Partner Type: Value-Added Resellers, System Integrators, Managed Service Providers, Independent Software Vendors, Cloud Solution Providers Deployment Model: On-Premise, Cloud-Based, Hybrid, Hosted, Multi-Cloud Client Industry: BFSI, Telecommunications, Public Sector, Manufacturing, Education, Hospitality License Model: Subscription, Perpetual, Freemium, Open Source, Usage-Based |
| Companies Covered | Softchoice, Arrow Electronics, CDW, SoftwareONE, Tekelec, Insight Enterprises, Presidio, Bechtle, SHI International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Software Resellers Market Shifts & Advancements
Software distribution models are fragmenting across specialized intermediaries that combine technical implementation with compliance validation, displacing pure license-brokering functions. Three structural developments are redefining competitive positioning.
Container orchestration and Kubernetes-based deployment platforms are hybridizing infrastructure management responsibilities between vendors, resellers, and end-user IT departments. Financial services institutions in Germany and Singapore are adopting these architectures fastest, demanding resellers who assume operational accountability for cluster security and patch management rather than merely licensing the underlying software.
The EU CSRD sustainability reporting requirements and corresponding supply chain due diligence obligations are forcing software resellers to document environmental impact across their vendor portfolios. Industrial manufacturing clients in France and Italy now exclude resellers unable to provide granular carbon footprint data for cloud workloads, compressing procurement timelines and elevating compliance costs for intermediaries serving these accounts.
Enterprise buyers are consolidating vendor relationships around outcome-based consumption models that bundle software licensing with guaranteed uptime and performance metrics. Healthcare systems in the United States and pharmaceutical manufacturers in Switzerland are piloting these arrangements most aggressively, replacing traditional seat-based subscriptions with patient-outcome-linked pricing that transfers operational risk to reseller partners.
Global Software Resellers Market Segmentation
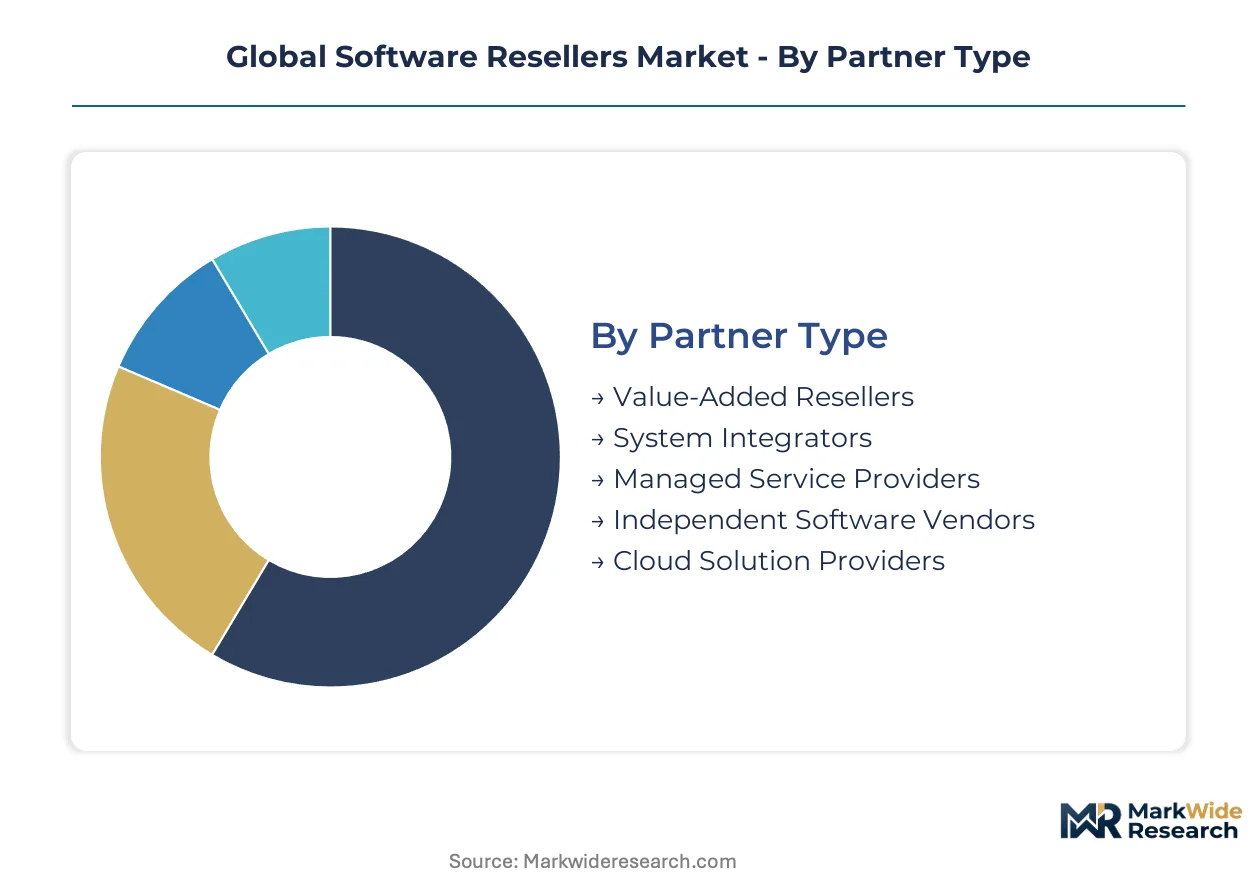
Software reseller segmentation reveals how intermediary value creation differs across partner archetypes, deployment architectures, and client procurement maturity. Each dimension carries distinct margin profiles, compliance obligations, and renewal dynamics that shape competitive positioning.
Partner Type:
After-sales-service intensity separates partner types most sharply, with operational embedding determining contract duration and margin retention.
- Managed Service Providers:These partners assume full operational accountability for software environments, layering 24/7 monitoring, patch management, and incident response atop core licensing. Healthcare systems in Germany and financial institutions in Singapore favor MSP relationships for clinical and trading platforms where downtime carries regulatory and reputational penalties. The business associate agreement requirements under HIPAA and GDPR data processor obligations make MSPs indispensable for compliance-heavy verticals.
- Cloud Solution Providers:Microsoft's CSP program and analogous frameworks from AWS and Google Cloud enable partners to own the entire customer lifecycle including billing, support, and technical enablement. Mid-market enterprises in the United States and United Kingdom gravitate toward CSP relationships to consolidate vendor management overhead while accessing consumption-based pricing. These partners capture recurring revenue streams that transactional resellers cannot match.
- Value-Added Resellers:Traditional VARs concentrate on pre-sales technical consultation, implementation services, and license aggregation without assuming ongoing operational responsibility.
- System Integrators:These partners specialize in complex multi-vendor deployments, particularly for hybrid ERP and CRM transformations requiring custom development.
- Independent Software Vendors:ISVs that resell complementary third-party solutions alongside proprietary offerings, common in vertical-specific applications.
By volume, Value-Added Resellers still lead transaction counts. By growth pace, Managed Service Providers are climbing the fastest as clients outsource operational risk.
Deployment Model:
Cost tier separation across deployment models reflects infrastructure ownership patterns and professional services intensity.
- Hybrid:Combines on-premise legacy systems with cloud-native workloads, demanding specialized integration expertise and ongoing orchestration support. Manufacturing enterprises in Japan and automotive suppliers in Germany prioritize hybrid architectures to preserve capital-intensive ERP investments while adding AI and analytics capabilities. Resellers serving these accounts must maintain dual competencies across VMware, Kubernetes, and hyperscaler platforms.
- Multi-Cloud:Distributes workloads across AWS, Azure, and Google Cloud Platform simultaneously to avoid vendor lock-in and optimize price-performance. Fintech startups in Singapore and digital health ventures in Switzerland adopt multi-cloud fastest, requiring resellers with cross-platform certification density and unified cost management tooling.
- Cloud-Based:Fully cloud-native deployments with no on-premise infrastructure footprint, dominant among born-digital enterprises.
- On-Premise:Traditional data center deployments persisting in defense, air-gapped industrial, and highly regulated financial environments.
- Hosted:Single-tenant cloud deployments managed by resellers or specialized hosting providers, bridging control and outsourcing preferences.
By volume, Cloud-Based deployments lead new procurement. By growth pace, Multi-Cloud is gaining share fastest as risk diversification becomes standard.
Client Industry:
Application criticality varies enormously across client industries, with regulated sectors demanding validated implementation methodologies.
- BFSI:Banks, insurers, and capital markets firms require resellers with ISO 27001, SOC 2 Type II, and PCI-DSS certifications plus demonstrated incident response capabilities. The SEC's cybersecurity disclosure rules and analogous EU DORA requirements elevate due diligence standards for software sourcing. Resellers serving BFSI capture premium pricing but absorb substantial compliance overhead.
- Public Sector:Government agencies channel procurement through authorized reseller networks with FedRAMP, NIST 800-53, or country-specific security clearances. CDW and comparable federal specialists dominate this segment through established contracting vehicles and cleared personnel rosters.
- Telecommunications:Carriers and network operators demand resellers with OSS/BSS integration expertise and 5G core deployment experience.
- Manufacturing:Industrial clients prioritize OT/IT convergence capabilities and supply chain traceability solutions.
- Education:Universities and K-12 districts favor volume licensing specialists with E-rate program expertise in the United States.
- Hospitality:Hotel chains and restaurant groups concentrate on property management system integration and guest experience platforms.
By volume, BFSI generates the largest contract value. By growth pace, Public Sector is expanding most quickly under federal cloud migration mandates.
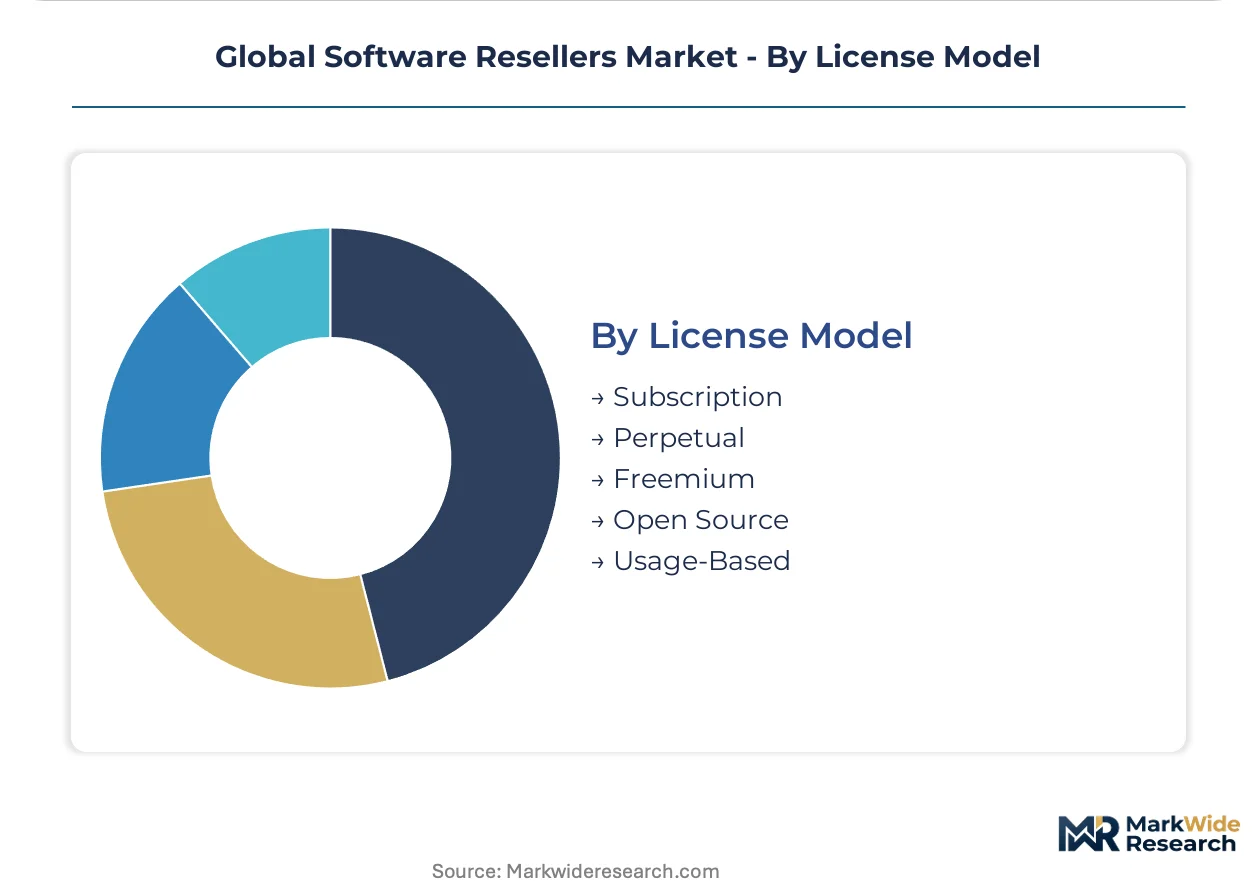
License Model:
Customer type and procurement maturity determine license model preferences, with recurring frameworks displacing perpetual transactions.
- Subscription:Recurring revenue models with predictable cash flows and embedded upgrade rights now dominate enterprise software procurement. SaaS vendors and their reseller partners prefer subscriptions for revenue visibility; buyers value operational flexibility and reduced capital commitment. The transition from perpetual to subscription licensing is restructuring reseller economics toward annuity relationships.
- Usage-Based:Consumption-metered pricing tied to actual compute, storage, or transaction volumes aligns costs with realized value. Cloud-native enterprises and variable-workload environments favor this model, requiring resellers with sophisticated cost optimization and forecasting capabilities.
- Perpetual:One-time license purchases with optional maintenance contracts, persisting in on-premise infrastructure and specialized vertical applications.
- Freemium:Tiered offerings with no-cost entry points and paid feature unlocks, common in collaboration and productivity software.
- Open Source:Community-licensed software with commercial support and enterprise feature subscriptions layered by resellers.
By volume, Subscription leads current transaction value. By growth pace, Usage-Based is climbing the fastest as FinOps discipline matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software reseller trade flows favor import-dependent markets where domestic vendor presence remains thin. The United States runs a substantial services surplus through federal contracting channels, while Germany and India generate net exporter positions through specialized compliance advisory and cloud migration capabilities respectively.
United States
Federal cloud migration mandates and defense IT modernization programs channel procurement through authorized reseller networks. FedRAMP and NIST 800-53 compliance requirements restrict contract eligibility to certified intermediaries. The Washington DC-Northern Virginia corridor concentrates cleared personnel rosters and established contracting vehicles that dominate public-sector software sourcing.
Germany
Industrial manufacturing enterprises prioritize OT/IT convergence capabilities and supply chain traceability solutions. The EU CSRD sustainability reporting requirements and supply chain due diligence obligations force resellers to document environmental impact across vendor portfolios. Bavaria and Baden-Württemberg host automotive suppliers and machinery builders that demand granular carbon footprint data for cloud workloads.
India
The PLI scheme for IT hardware and data center localization requirements create demand for resellers bridging multinational software vendors with domestic compliance mandates. BIS certification and RBI data localization rules reshape vendor qualification criteria. Bangalore and Hyderabad clusters concentrate cloud engineering talent that supports hybrid deployment architectures for financial services clients.
United Kingdom
Mid-market enterprises gravitate toward Cloud Solution Provider relationships to consolidate vendor management overhead while accessing consumption-based pricing. The UK GDPR data processing agreements and FCA operational resilience requirements elevate due diligence standards. London's financial services concentration drives demand for resellers with ISO 27001 and SOC 2 Type II certifications.
Japan
Manufacturing enterprises prioritize hybrid architectures to preserve capital-intensive ERP investments while adding AI and analytics capabilities. METI's data free flow with trust initiatives and cybersecurity framework updates reshape cross-border software sourcing. The Tokyo-Osaka corridor concentrates system integrators with dual competencies across VMware, Kubernetes, and hyperscaler platforms.
Global Software Resellers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower licensing scope. The vendor base concentrates around three strategic tiers: federal contracting specialists with cleared personnel infrastructure, cloud migration advisors with multi-platform certification density, and managed service providers assuming operational accountability. Consolidation pressure intensifies as hyperscaler direct-to-customer portals compress intermediary margins. Strategic moves center on embedded operational support capabilities and long-term licensing partnerships that transfer recurring revenue from transactional resale.
Within the federal contracting tier, CDW leverages established infrastructure to sustain dominance in public-sector software procurement. Insight Enterprises anchors competitive positioning through deep specialization in cloud migration services and hybrid deployment architectures. Bechtle occupies a position across European enterprise accounts with differentiated focus on managed service provider capabilities. These three represent distinct archetypes: public-sector platform integrator, cloud transformation advisor, and European operational outsourcer respectively.
| Leading Market Players |
|---|
| Softchoice |
| Arrow Electronics |
| CDW |
| SoftwareONE |
| Tekelec |
| Insight Enterprises |
| Presidio |
| Bechtle |
| SHI International |
| Others |
Supply & Pricing Matrix
The Washington DC-Northern Virginia corridor concentrates cleared personnel rosters and established federal contracting vehicles that dominate public-sector software sourcing, granting resellers with FedRAMP authorization substantial pricing power over uncertified competitors serving defense and civilian agencies.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture FedRAMP-authorized providers and ISO 27001-certified MSPs serving financial services; standard tiers cover CSP-program partners with multi-cloud competencies; economy tiers encompass transactional VARs competing on license aggregation alone. Pricing pressure stems from Microsoft's direct-to-customer licensing portals compressing intermediary margins. Healthcare systems exhibit highest price sensitivity due to OCR audit cost absorption, while defense agencies show lowest sensitivity given mandate-driven procurement.
Supply Chain Analysis
Upstream cloud infrastructure feeds from hyperscaler data center clusters in the United States, Ireland, and Singapore. Software licensing inventories draw from Microsoft, AWS, and Google Cloud distribution programs; professional services capacity rests on certified engineer pools; compliance documentation hinges on third-party audit firms. Single-source vulnerability concentrates around Microsoft's CSP program dominance. Distribution runs through authorized partner networks with direct vendor billing relationships rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise buyer consolidation around outcome-based consumption models shifts negotiation power toward procurement teams demanding guaranteed uptime and performance metrics, fragmenting reseller pricing autonomy.
For Market Incumbents: Pre-empt margin compression from hyperscaler direct portals by embedding operational accountability into multi-year managed service contracts. CDW's federal contracting infrastructure offers a template for channel control through cleared personnel rosters. Invest in ISO 27001 and SOC 2 Type II certifications to defend financial services relationships against emerging compliance-focused entrants.
For New Entrants and Emerging Players: India's PLI scheme for IT hardware and data center localization requirements represent underpenetrated white space where multinational vendor relationships remain thin. Target domestic compliance advisory bridging BIS certification and RBI data localization rules. Lead with hybrid deployment expertise for manufacturing enterprises preserving legacy ERP investments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors managed service providers with recurring revenue frameworks over transactional license resellers. Long-term viability centers on operational embedding rather than distribution scale. Monitor NIST AI procurement guideline evolution as an inflection indicator for vendor qualification criteria redefinition.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Investment | Unlocks federal contract eligibility under NIST 800-53 compliance mandates. |
| Multi-Cloud Certification Density | Captures fintech and digital health demand for AWS-Azure-GCP interoperability. |
| Managed Security Service Integration | Absorbs multi-year cybersecurity contracts from pure-play EDR vendors. |
| EU AI Act Conformity Capability | Documents technical assessments for high-risk software deployments in Europe. |
| Carbon Footprint Documentation | Satisfies CSRD supply chain due diligence for French and Italian manufacturing clients. |
Research Methodology
A spread of perspectives from CTOs, IT procurement officers, cloud solution provider channel managers, and compliance audit specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, hyperscaler capex disclosures, and FedRAMP authorization databases. Bottom-up partner-type segmentation triangulated against top-down regional demand modeling.
Demand-supply-balance framing anchored the forecast framework across the analysis window. Segmentation dimensions included deployment model, organization size, vertical industry, and integration complexity. CAGRs derived from license volume trajectories and services revenue mix shifts. Cloud migration mandate timelines and AI governance framework implementation pace served as industry-specific forecast inputs.
Practitioners should monitor vendor direct-to-customer portal expansion and AI procurement guideline evolution from NIST for early signals requiring forecast revision. Cross-checking against hyperscaler partner program disclosure trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Non-Profit Donation Software Market
Software & Services
Feedback Management Software Market
Software & Services
Global Audience Response Software Market
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
Global Online Assessment Software Market
Software & Services
Remote Sensing Software Market
Software & Services
Global Software Quality Assurance Market
Software & Services
Time and Attendance Software Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Global Note Taking App Market
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
Streaming Server Software Market
Software & Services
Global SAP S-4HANA Application Market
Software & Services
Global Managed File Transfer (MFT) Software and Service Market
Software & Services
Automotive Design Software Market
Software & Services
Global Fixed Asset Management Software Market