
 Small Business Manufacturing Software Market | 2026-2036
Small Business Manufacturing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Small Business Manufacturing Software Market Analysis
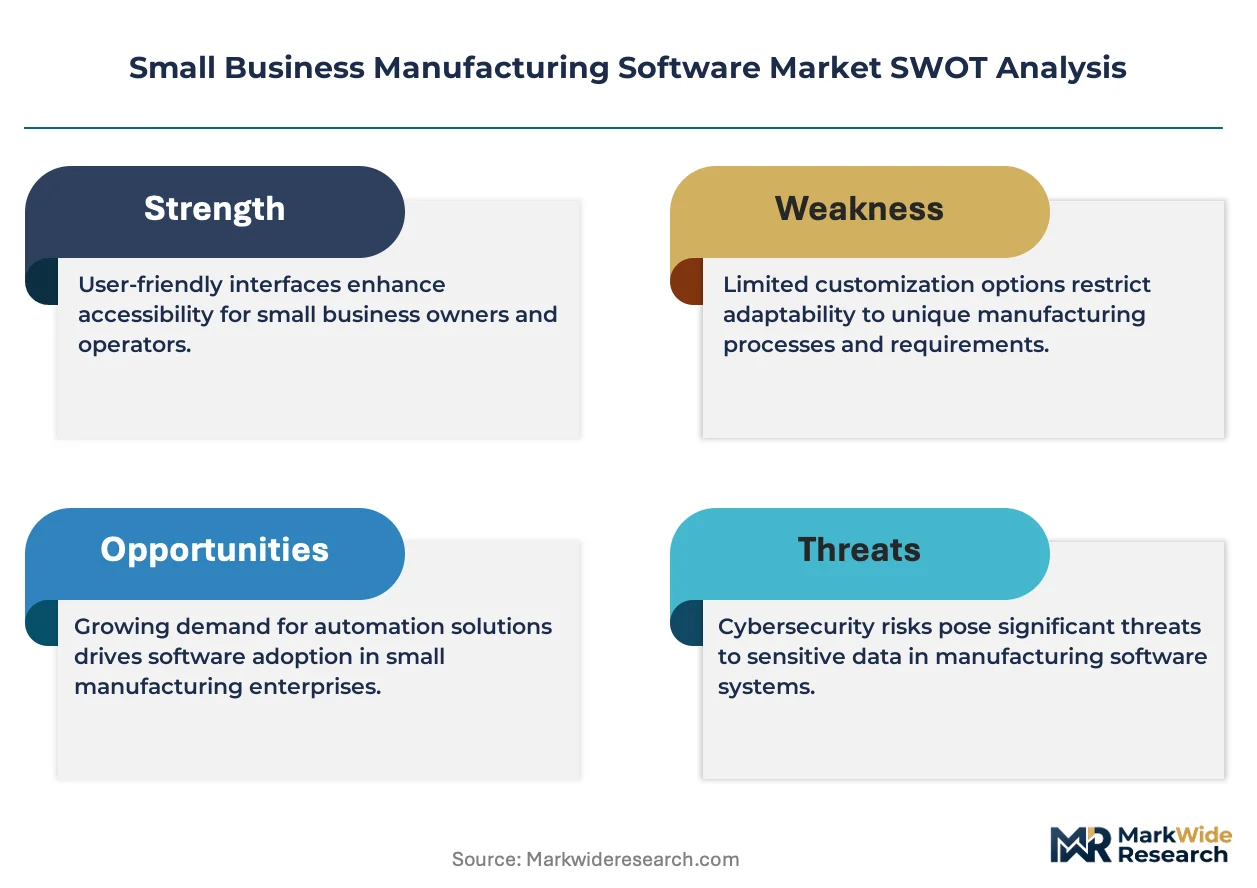
EU Green Deal supply-chain disclosure rules are shifting procurement requirements for small manufacturers across member states. Epicor Software Corp. leverages deep ERP specialization for discrete manufacturing to anchor its European mid-market position. SAP SE competes through extensive partner-network deployment models that reduce implementation friction for capital-constrained buyers. Odoo ERP differentiates with open-source architecture that lowers total cost of ownership for furniture and textile producers.
Small business manufacturing software encompasses integrated systems that coordinate production planning, inventory tracking, shop-floor execution, and supplier collaboration through modular architectures typically supporting under 500 concurrent users and sub-50-node machine connectivity. These platforms synchronize material requirements planning with real-time work-order dispatch to reduce work-in-process inventory and improve on-time delivery rates for batch-oriented producers. ERP deployments retain the largest installed base among product types, though SaaS delivery models are capturing the fastest growth as vendors eliminate upfront license barriers. Cloud-based MES modules are gaining traction in electronics end-user segments where frequent engineering changes demand agile routing capabilities. Quality control feature sets command premium pricing when bundled with lot-traceability compliance tools for food and beverage processors.
FDA 21 CFR Part 11 digital signature standards shape software validation requirements for small pharmaceutical and medical device contract manufacturers seeking market access. EPA hazardous materials tracking mandates and OSHA machine-safety documentation rules further condition feature development priorities for domestic vendors. ISO 9001 and ISO 13485 audit-readiness functionality increasingly determines competitive win rates in regulated sub-segments. Stakeholders must weigh the pace of AI-driven predictive maintenance integration against the implementation bandwidth constraints that persist across owner-operated manufacturing enterprises.
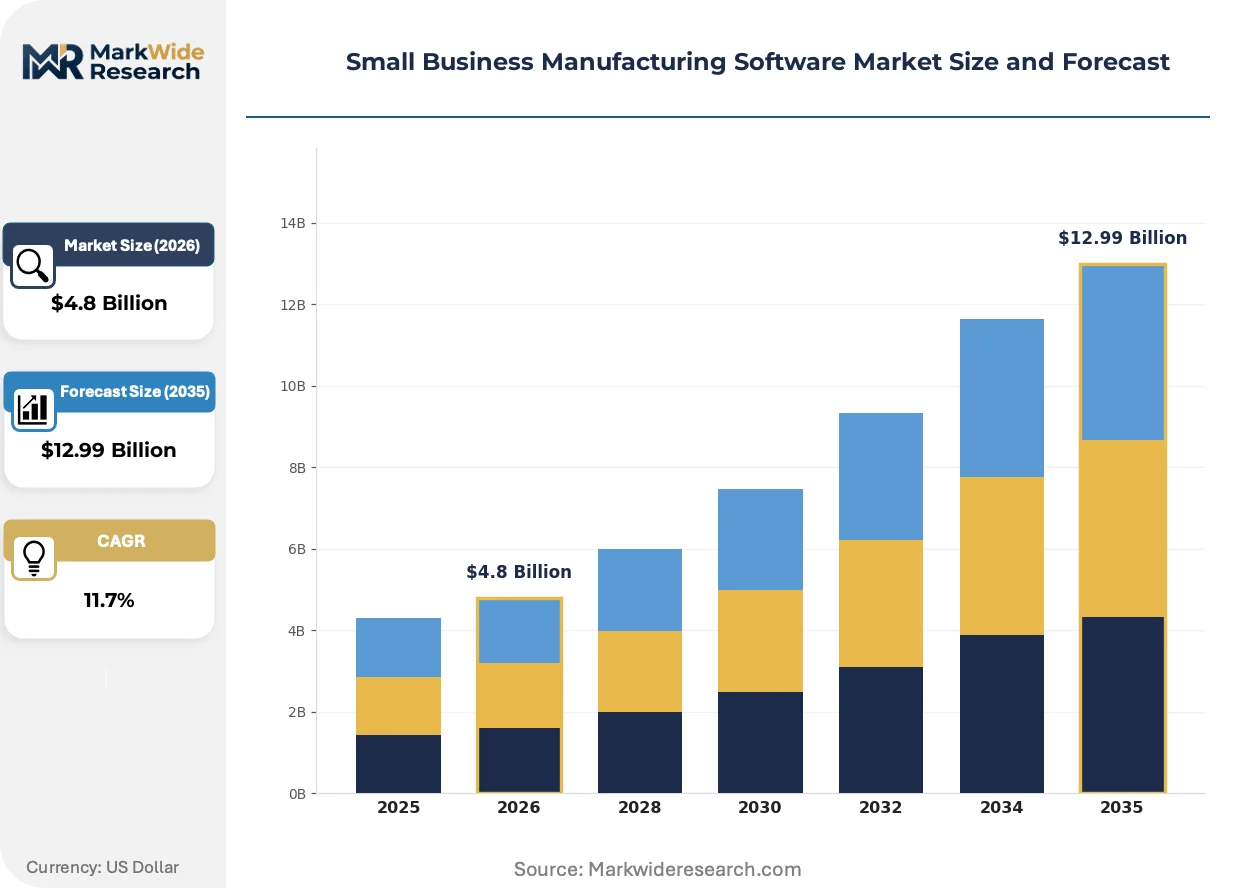
Market Dynamics
Cloud-native MES platforms are compressing deployment cycles for small-batch electronics producers facing EU Green Deal supply-chain disclosure mandates, forcing incumbent vendors to modularize architectures or lose mid-market share to agile SaaS entrants.
Growth Catalysts
- EU Green Deal disclosure rules:Tier-two German electronics suppliers accelerate MES adoption to document carbon intensity across multi-tier supply chains for OEM qualification.
- India PLI scheme traceability requirements:Precision component clusters digitize shop-floor operations to meet automotive and aerospace OEM audit standards for component genealogy.
- Edge-to-cloud data pipelines:Real-time machine connectivity enables predictive quality interventions that reduce scrap rates in high-mix, low-volume production environments.
Market Restraints
- Implementation bandwidth scarcity:Owner-operated manufacturing enterprises lack dedicated IT staff to manage multi-module ERP deployments alongside daily production demands.
- Data sovereignty fragmentation:Cross-border cloud hosting restrictions in Germany, France, and India force vendors to maintain region-specific infrastructure, elevating operational complexity.
- Legacy equipment protocol diversity:Proprietary machine interfaces in aging metalworking and plastics assets resist standardized data extraction without expensive gateway hardware.
Strategic Opportunities
- AI-driven predictive maintenance convergence:Machine learning modules layered atop MES data streams create subscription revenue models for vendors serving capital-constrained buyers.
- Food and beverage lot-traceability white space:Small processors lacking enterprise-scale budgets seek affordable compliance tools for FDA 21 CFR Part 11 and FSSAI audit readiness.
- Direct-to-manufacturer SaaS distribution:Vendor-hosted trials and self-service onboarding bypass traditional systems integrator channels, reducing customer acquisition costs.
Industry Challenges
- OT-IT integration complexity:Shop-floor technicians and back-office analysts operate with mismatched data vocabularies, delaying value realization from unified platforms.
- Multi-standard certification timelines:Simultaneous pursuit of ISO 9001, ISO 13485, and sector-specific quality marks extends sales cycles for regulated-subsegment vendors.
- Skills scarcity in industrial data architecture:Small manufacturers compete with larger enterprises for limited talent capable of configuring API connections between MES and ERP layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Business Manufacturing Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ERP, MES, MRP, SCM Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Electronics, Furniture, Textile, Food & Beverage Feature: Inventory Management, Production Scheduling, Quality Control, Reporting Tools |
| Companies Covered | Epicor Software Corp., Infor Corp., NetSuite, Oracle Corp., SAP SE, Microsoft Dynamics 365 Business Central, Acumatica, Odoo ERP, MRPeasy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Business Manufacturing Software Market Emerging Trajectories
Modular, API-first architectures are displacing monolithic ERP suites as small manufacturers demand surgical capability additions without wholesale system replacement. This shift rewards vendors with platform ecosystems over those with integrated but rigid product stacks.
Composable MES applications built on containerized microservices are unifying previously siloed quality, maintenance, and scheduling functions into single-pane visibility. Electronics contract manufacturers in Bavaria and Tamil Nadu deploy these configurations to accommodate weekly engineering changes without reconfiguring entire workflows. The unification is compressing vendor consolidation timelines as buyers favor best-of-breed integration over single-suite lock-in.
CSRD sustainability reporting mandates are compelling software vendors to embed emissions calculation engines directly into production planning modules. Small automotive suppliers in Germany must now generate Scope 3 disclosures for tier-one customers, creating pull-through demand for carbon-aware MRP functionality. Food processors across France and Italy similarly retrofit traceability stacks to satisfy EFSA-driven supply-chain transparency expectations.
Subscription pricing models are displacing perpetual licenses as the dominant commercial structure, compressing upfront barriers but extending vendor-customer relationship horizons. Indian precision component clusters and US Midwest job shops alike evaluate total cost of ownership across five-year horizons rather than initial capital outlay. This behavioral shift favors cloud-native vendors with consumption-based metering over traditional on-premise deployers.
Small Business Manufacturing Software Market Segmentation
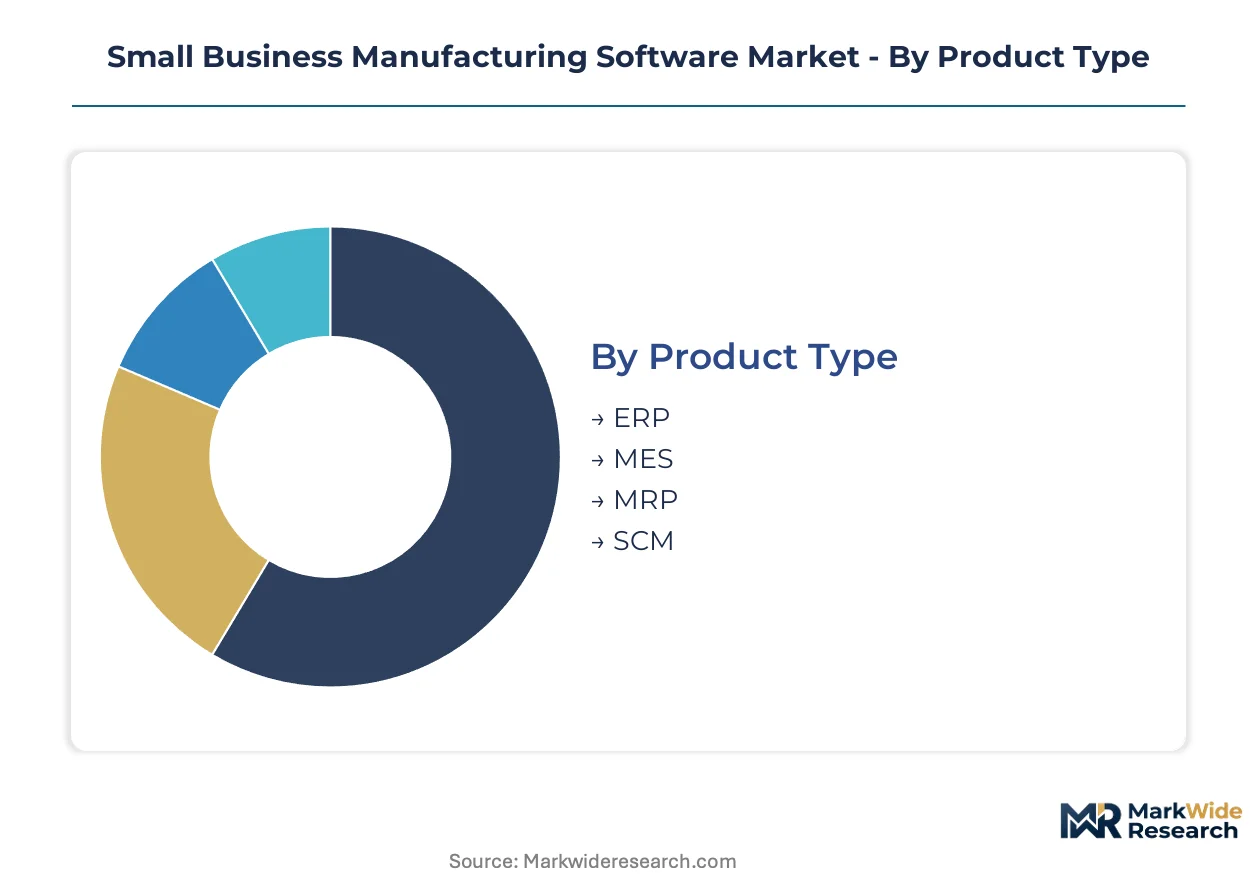
Small business manufacturing software segments reflect divergent upgrade pressures across owner-operated enterprises. Replacement cycles compress where EU Green Deal disclosure mandates force rapid platform modernization, while capital constraints prolong legacy system reliance in unregulated sub-segments.
Product Type:
Upgrade cycles vary sharply by functional module, with integrated suites facing slower replacement than point solutions addressing urgent compliance gaps.
- ERP:Enterprise resource planning platforms coordinate financial, procurement, and human capital workflows through unified databases. German furniture and textile producers prioritize ERP refresh cycles to embed CSRD-compliant carbon accounting modules for tier-one customer qualification. ERP sits at the top of the volume ranking, with MES climbing the fastest.
- MES:Manufacturing execution systems dispatch real-time work orders and capture machine-level production data. Bavarian electronics contract manufacturers deploy cloud-native MES to document component genealogy under EU Green Deal supply-chain transparency rules. MES modules command premium pricing when bundled with lot-traceability engines for medical device subcontractors.
- MRP:Material requirements planning software calculates net demand from bill-of-materials explosions and master production schedules. Indian precision component clusters under PLI scheme pressure adopt MRP to synchronize multi-tier supplier deliveries with automotive OEM audit timelines.
- SCM:Supply chain management platforms extend visibility beyond facility boundaries into tier-two and tier-three supplier operations. Food processors across France leverage SCM tools to map ingredient provenance for EFSA-driven transparency mandates.
MES platforms are gaining share fastest as compliance-driven procurement accelerates point-solution adoption ahead of full-suite replacement.
Deployment:
Delivery model selection tracks customer IT staffing maturity and data sovereignty exposure across regulated jurisdictions.
- On-Premise:Perpetual-license installations on customer-managed servers persist where production data must remain within national borders. German metalworking job shops resist cloud migration due to KBA-influenced data localization expectations for automotive supplier certification.
- Cloud-Based:Vendor-hosted infrastructure eliminates capital expenditure and accelerates deployment cycles. Tamil Nadu electronics clusters adopt cloud MES to meet aerospace OEM traceability requirements without dedicated IT departments. Cloud-Based captures the steepest expansion trajectory as subscription pricing reduces upfront barriers for capital-constrained buyers.
- Hybrid:Split architectures retain sensitive production data on-premise while routing analytics workloads to cloud environments. Italian food processors deploy hybrid configurations to satisfy FSSAI audit readiness while accessing AI-driven quality prediction tools.
- SaaS:Software-as-a-service delivery embeds maintenance, updates, and support into recurring subscription fees. US Midwest job shops favor SaaS ERP to preserve owner-operator bandwidth for daily production demands rather than system administration.
SaaS delivery models are displacing perpetual licenses most rapidly among sub-50-employee manufacturers lacking dedicated IT functions.
End User:
Vertical-specific compliance pressures and production complexity drive divergent feature prioritization across buyer segments.
- Electronics:High-mix, low-volume contract manufacturers demand agile routing capabilities to accommodate weekly engineering changes. Bavarian and Tamil Nadu electronics producers compress MES deployment cycles to satisfy OEM carbon disclosure requirements under EU Green Deal and PLI scheme traceability rules. Electronics leads vertical demand concentration.
- Furniture:Batch-oriented producers prioritize inventory optimization and order-to-delivery visibility. Odoo ERP's open-source architecture gains traction among European furniture manufacturers seeking to lower total cost of ownership without sacrificing ISO 9001 audit readiness.
- Textile:Seasonal demand patterns and material variability drive emphasis on demand forecasting and supplier collaboration tools. Indian textile clusters digitize shop-floor operations to meet fast-fashion retailer sustainability disclosure requirements.
- Food & Beverage:Process manufacturers face stringent lot-traceability mandates from FDA 21 CFR Part 11 and FSSAI regulators. Small processors seek affordable compliance tools for digital signature standards and hazard analysis documentation without enterprise-scale budgets.
Food & Beverage exhibits the most acute compliance-driven replacement urgency as audit-readiness functionality determines competitive win rates.
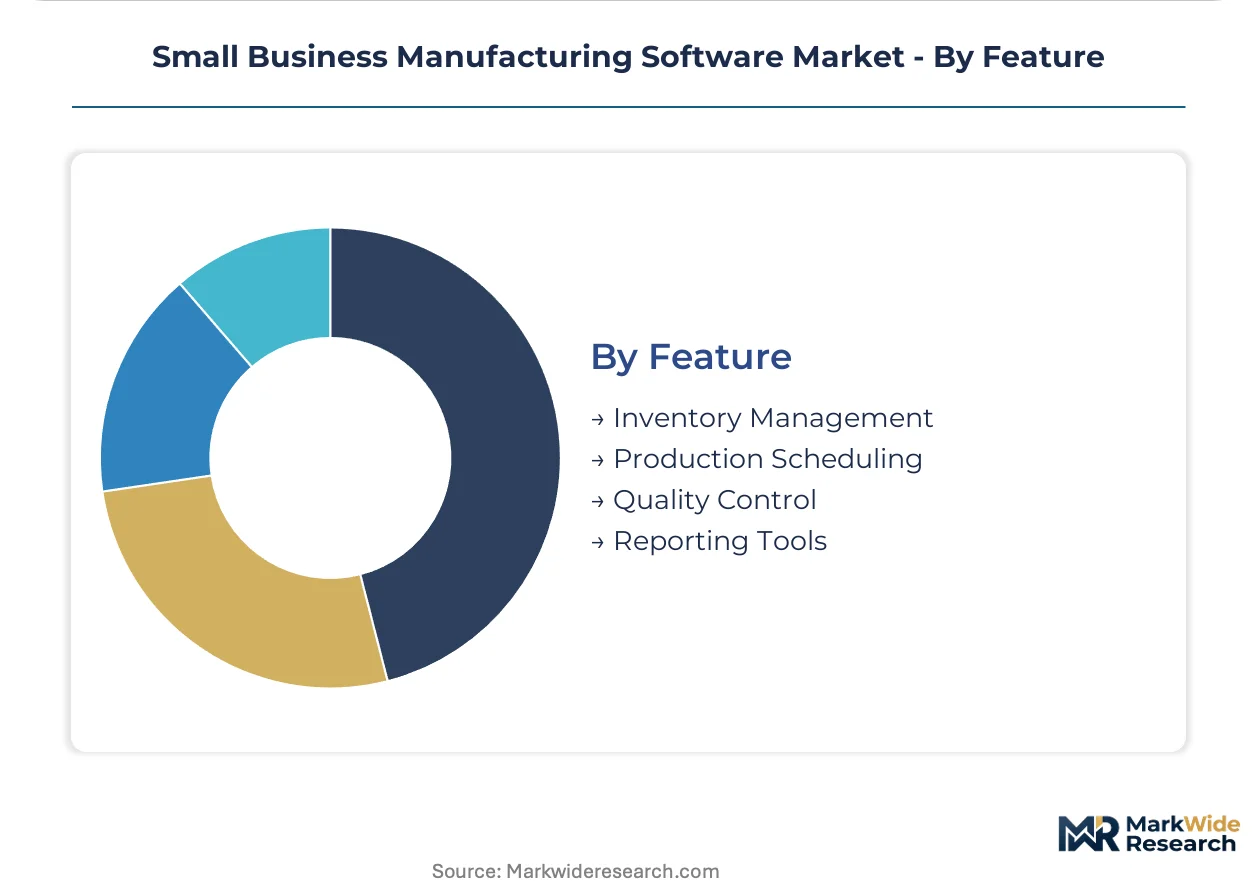
Feature:
Capability prioritization reflects the tension between operational efficiency gains and mandatory compliance documentation.
- Inventory Management:Real-time stock visibility and automated reorder point calculation reduce carrying costs and stockout risk. German automotive suppliers embed emissions tracking into inventory modules to generate Scope 3 disclosures for tier-one customers.
- Production Scheduling:Finite capacity algorithms optimize machine utilization and labor allocation across shifting order priorities. Electronics manufacturers in high-mix environments prioritize scheduling tools that accommodate frequent engineering changes without manual reconfiguration.
- Quality Control:Statistical process control and non-conformance tracking support ISO 9001 and ISO 13485 certification maintenance. Medical device contract manufacturers command premium pricing for quality modules bundled with FDA 21 CFR Part 11 digital signature validation.
- Reporting Tools:Dashboard and analytics capabilities translate operational data into actionable intelligence for owner-operated enterprises. CSRD sustainability reporting mandates pull through demand for emissions calculation engines embedded directly in production planning interfaces.
Quality Control features command the highest pricing premiums in regulated sub-segments, with Reporting Tools expanding most quickly as disclosure mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep pools of industrial software engineering talent concentrate in Germany's automotive belt, India's precision manufacturing corridors, and the US Midwest machine-tool heartland, anchoring regional adoption patterns for small business manufacturing platforms.
Germany
Bavarian electronics contract manufacturers and Baden-Württemberg automotive suppliers drive MES adoption to document component genealogy under EU Green Deal disclosure mandates. KBA-influenced data localization expectations push metalworking job shops toward hybrid cloud configurations rather than full SaaS migration. Stuttgart's precision engineering cluster accelerates ERP refresh cycles to embed CSRD-compliant carbon accounting modules.
India
Tamil Nadu aerospace subcontractors and Karnataka precision component clusters digitize shop-floor operations to satisfy PLI scheme traceability requirements for automotive OEM qualification. FSSAI audit-readiness functionality pulls through demand among Maharashtra food processors retrofitting legacy quality stacks. Telangana's electronics manufacturing zone adopts cloud-native MES to meet export-market disclosure standards without dedicated IT departments.
United States
Midwest job shops and Southeast contract manufacturers favor SaaS ERP to preserve owner-operator bandwidth for production demands rather than system administration. FDA 21 CFR Part 11 digital signature standards shape software validation priorities for pharmaceutical and medical device subcontractors in New England and the Research Triangle. OSHA machine-safety documentation rules condition feature development for metalworking and plastics processors across the Great Lakes region.
France
Île-de-France industrial software vendors and Auvergne-Rhône-Alpes precision manufacturers align platform roadmaps with EFSA-driven supply-chain transparency expectations. Food processors across Provence-Alpes-Côte d'Azur retrofit traceability stacks to satisfy ingredient provenance mapping requirements. Hauts-de-France textile clusters digitize operations to meet fast-fashion retailer sustainability disclosure mandates.
Italy
Lombardy machinery builders and Emilia-Romagna automotive suppliers deploy modular MES architectures to accommodate frequent engineering changes without workflow reconfiguration. Furniture producers in Veneto leverage open-source ERP alternatives to lower total cost of ownership while maintaining ISO 9001 audit readiness. Tuscany food and beverage processors seek affordable compliance tools for FSSAI-aligned hazard analysis documentation.
Small Business Manufacturing Software Market Vendor Landscape
Capital-heavy enterprise software vendors compete with asset-light SaaS specialists for small manufacturing accounts, creating a tiered structure where deployment speed and total cost of ownership determine competitive positioning. The market fragments across three strategic archetypes: legacy ERP incumbents with deep manufacturing specialization, cloud-native challengers with API-first architectures, and open-source platforms with community-driven ecosystems. Dominant competitive moves include modularization of monolithic suites to counter SaaS erosion and vertical partnership networks to reduce implementation friction for capital-constrained buyers.
Within the legacy ERP tier, Epicor Software Corp. and SAP SE exemplify deep manufacturing specialization through discrete industry focus and extensive partner-network deployment models respectively. Odoo ERP occupies a position in the open-source archetype, lowering total cost of ownership for furniture and textile producers through community-driven development. Oracle Corp. and Microsoft Dynamics 365 Business Central sit within the cloud-native convergence zone, representing platform ecosystem strategies that unify previously siloed operational functions.
| Leading Market Players |
|---|
| Epicor Software Corp. |
| Infor Corp. |
| NetSuite |
| Oracle Corp. |
| SAP SE |
| Microsoft Dynamics 365 Business Central |
| Acumatica |
| Odoo ERP |
| MRPeasy |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure pricing indices cascading through vendor cost structures differentiate subscription tiers for small-batch electronics producers in Germany and precision component clusters in India. Tier-one SaaS vendors absorb compute cost volatility into consumption-based metering while on-premise deployers pass through server hardware inflation to capital-constrained buyers.
Pricing Analysis
Bundle-unbundle splits separate core platform licenses from compliance modules and AI-driven predictive maintenance add-ons. Pricing stratifies across premium compliance-integrated tiers, standard SaaS subscriptions, and economy self-service configurations based on ISO 13485 certification level and vertical customization depth. Cost compression in economy tiers intensifies as open-source alternatives erode entry-level subscription value. Capital-constrained owner-operated manufacturers exhibit highest price sensitivity while regulated medical device subcontractors accept premium positioning for audit-ready functionality.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data center concentration in the United States, Ireland, and Singapore with edge computing hardware dependencies on Taiwanese semiconductor foundries and German industrial automation component suppliers. Proprietary machine protocol gateways and API middleware layers feed from specialized European industrial software engineering pools. Single-source vulnerability concentrates in legacy equipment connectivity hardware subject to KBA-influenced localization mandates. Distribution runs through direct vendor sales, regional systems integrators, and self-service onboarding portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal compliance costs in Germany and France exceed PLI scheme subsidized digitization expenses in India, creating divergent vendor margin structures across regulatory jurisdictions.
For Market Incumbents: Anchor European mid-market position through modular ERP architectures that unbundle compliance functionality for tier-two supplier qualification under CSRD mandates. Counter cloud-native SaaS erosion by embedding carbon accounting engines directly into production planning modules. Prioritize certification investment in ISO 13485 audit-readiness tooling to defend medical device subcontractor relationships against API-first challengers. For New Entrants and Emerging Players: Enter via food and beverage lot-traceability white space where small processors lack enterprise-scale budgets for FDA 21 CFR Part 11 compliance tooling. Target Indian precision component clusters under PLI scheme pressure with cloud-native MES deployments requiring minimal IT staffing. Pursue direct-to-manufacturer SaaS distribution with self-service onboarding to bypass traditional systems integrator channel costs. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical-specific compliance software specialists possessing embedded regulatory workflow knowledge rather than horizontal platform generalists. Long-term viability favors vendors with consumption-based revenue models aligned to small manufacturer cash flow constraints. Watch AI-driven predictive maintenance attach rates as inflection indicator for platform stickiness and expansion revenue potential.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies MES, ERP, and quality modules into single-pane visibility for Bavarian electronics contract manufacturers. |
| Geographic Expansion | Establishes region-specific cloud infrastructure in Germany and India to satisfy KBA and data sovereignty requirements. |
| Strategic Partnership | Aligns with automotive OEMs to embed tier-two supplier traceability requirements into standard procurement workflows. |
| Acquisition of Specialist Firm | Consolidates AI-driven predictive maintenance capabilities from industrial data architecture talent pools. |
| Product Launch | Introduces CSRD-compliant carbon accounting modules for Stuttgart precision engineering clusters. |
Methodological Framework
Multiple input streams — primary interviews with manufacturing software CTOs, IT procurement officers at tier-two automotive suppliers, and channel integration specialists, alongside secondary validation through SEC filings, hyperscaler capex disclosures, and EU regulatory mandate documentation — were reconciled through bottom-up deployment tracking and top-down market sizing triangulation.
Historical adoption curves were cross-referenced against panel input from platform vendors and systems integrators across the projection horizon. Segmentation dimensions modeled include deployment model, organization size by employee count, vertical industry, integration complexity tier, and regional regulatory cluster. CAGRs were derived from annualized growth rate interpolation with software-as-a-service subscription renewal rates and compliance-driven replacement cycle compression as key industry-specific forecast inputs.
Inputs from vendor financial disclosures and regulatory filing databases were available through the study window; gaps in privately held SaaS specialist revenue data introduce uncertainty bands around emerging player market share estimates. Forecasts reflect documented assumptions regarding PLI scheme continuation and EU Green Deal enforcement timelines. A small set of triggers — including data sovereignty rule expansion, AI liability framework adoption, and industrial data architecture talent migration patterns — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Media Planning Software Market
Software & Services
Web Framework Software Market
Software & Services
Optical Coatings Design Software Market
Software & Services
Payroll - HR Solutions and Services Market
Software & Services
Systems Administration Management Tools Market
Software & Services
Grant Management Software Market
Software & Services
Automotive Operating Systems Market
Software & Services
North America Restaurant Management Software Market
Software & Services
Test Automation Market
Software & Services
HPC Software Market
Software & Services
Sales Enablement Software Market
Software & Services
Global Workforce Management Software Market
Software & Services
Custom Software Development Market
Software & Services
Global App Design Software Market
Software & Services
Telecom Billing Software Market
Software & Services
Telecom IT Services Market