
 Chemical Manufacturing Software Market | 2026-2036
Chemical Manufacturing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Manufacturing Software Market Outlook
Specialty chemical producers are redrawing procurement priorities as they shift from generic ERP modules toward purpose-built manufacturing execution platforms. SAP S/4HANA leverages deep process-industry functionality to anchor large-enterprise deployments across multi-site operations. BatchMaster ERP specializes in formula-based workflows and competes aggressively for mid-market chemical accounts seeking rapid implementation.
Chemical manufacturing software encompasses enterprise and operational technology platforms engineered to manage formula-driven production, lot traceability, and hazardous-material handling with precision down to parts-per-million tolerances. These systems synchronize recipe management, equipment utilization, and regulatory documentation to prevent batch deviations and ensure product integrity. Process optimization and compliance management command the deepest investment pools as producers face escalating audit scrutiny, while cloud-based deployments outpace on-premises installations among specialty chemical firms seeking scalable infrastructure without capital intensity.
EPA enforcement of Clean Air Act reporting, REACH substance registration through ECHA, and OSHA process safety management standards collectively elevate software from operational convenience to regulatory necessity. Non-compliance penalties now exceed the cost of enterprise system upgrades, accelerating replacement cycles among legacy-dependent producers. Stakeholders must evaluate whether their current platforms can absorb emerging per- and polyfluoroalkyl substances tracking requirements before enforcement windows tighten.
Market Dynamics
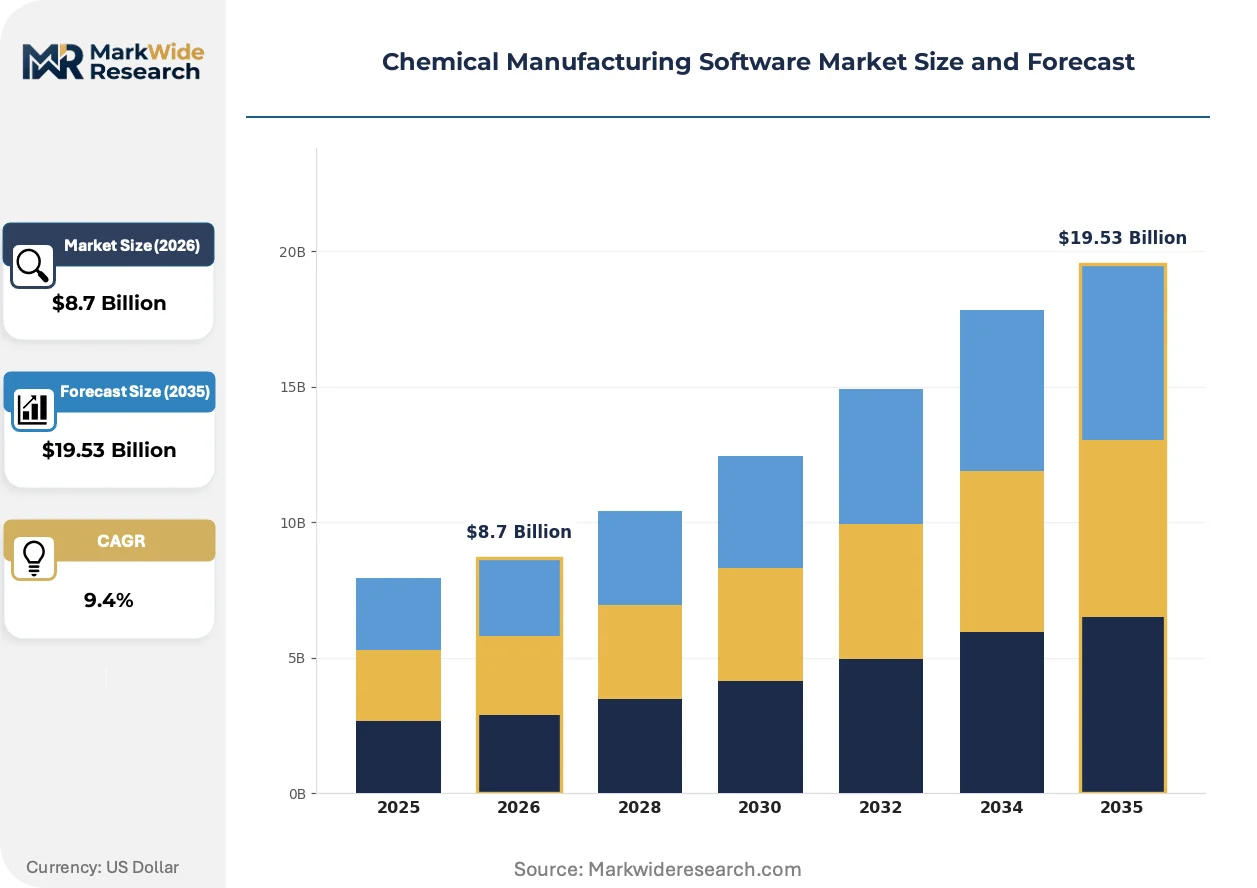
Specialty chemical producers face a structural imperative to replace legacy batch management systems as EPA and REACH enforcement windows compress compliance timelines from years to months. This pressure is redrawing software procurement priorities across formula-driven manufacturing.
Growth Catalysts
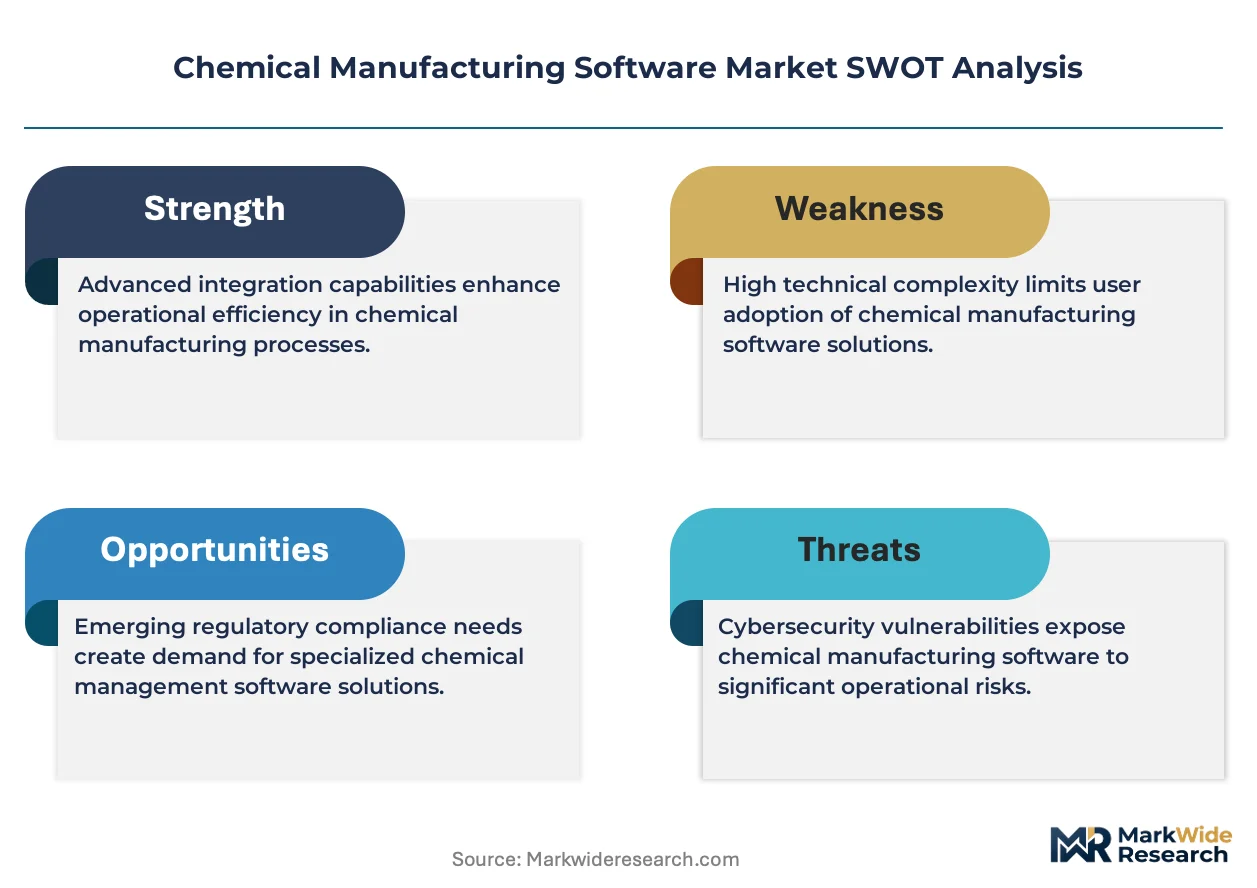
- REACH substance registration deadlines:ECHA mandates force European producers to deploy lot-level tracking systems that legacy platforms cannot support.
- Batch workflow complexity:Multi-step synthesis operations in agrochemical and pharmaceutical intermediates require precision tolerances down to parts-per-million.
- German chemical park density:Integrated production clusters around Ludwigshafen and Leverkusen demand synchronized ERP platforms across supplier networks.
Market Restraints
- Implementation cost structure:Mid-market producers face six-figure deployment costs for validated manufacturing execution systems.
- Legacy system entrenchment:Custom-coded batch recipes in aging platforms create technical debt that blocks cloud migration paths.
- Per- and polyfluoroalkyl substances tracking:Emerging EPA reporting requirements for PFAS extend compliance burdens beyond current software capabilities.
Strategic Opportunities
- Cloud-native MES penetration:Subscription-based deployment models lower capital barriers for specialty chemical firms seeking scalable infrastructure.
- AI-driven process optimization:Machine learning integration with batch analytics enables predictive deviation detection before product integrity compromise.
- OSHA process safety management alignment:Automated hazard documentation creates competitive differentiation for producers serving regulated end-uses.
Industry Challenges
- Validated system migration timelines:FDA and EPA audit trails require parallel operation periods that strain operational bandwidth during cutover.
- Batch recipe IP protection:Cloud deployments raise data sovereignty concerns for proprietary formula management among competitive producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Manufacturing Software Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Process Optimization, Inventory Management, Compliance Management, Quality Assurance Technology: Cloud-Based, On-Premises, Hybrid, SaaS End User: Chemical Producers, Specialty Chemicals, Petrochemicals, Fertilizers Application: Batch Processing, Continuous Processing, Formulation Management, Regulatory Compliance |
| Companies Covered | Aptean ERP, Infor CloudSuite Process Manufacturing, SAP S/4HANA, MRPeasy, Deacom ERP, Microsoft Dynamics 365 Business Central, BatchMaster ERP, MasterControl, Oracle NetSuite ERP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Manufacturing Software Market Strategic Shifts
Digital thread architectures are reconfiguring how chemical producers connect laboratory information management with shop-floor execution. This convergence is compressing development cycles and tightening quality feedback loops.
Edge computing deployments are fragmenting traditional centralized MES architectures. Distributed processing nodes at reactor vessels enable real-time analytics without latency penalties. Specialty batch producers in pharmaceutical intermediates are adopting these architectures fastest. The technology is fragmenting vendor market power by enabling modular, best-of-breed procurement over monolithic suites.
EPA enforcement of Clean Air Act reporting mandates is tightening data granularity requirements. Continuous emissions monitoring systems must now feed directly into batch records. Process manufacturers in Texas and Louisiana petrochemical corridors face the steepest compliance ramps. These producers are prioritizing platforms with pre-built EPA reporting modules over custom integration projects.
Subscription pricing models are displacing perpetual licenses in mid-market procurement. Chemical firms now prioritize operational expenditure treatment over capital depreciation for software assets. This shift favors cloud-native vendors with monthly billing structures. German and US specialty producers are driving this transition fastest as they seek balance-sheet flexibility for capacity expansion.
Chemical Manufacturing Software Market Segmentation
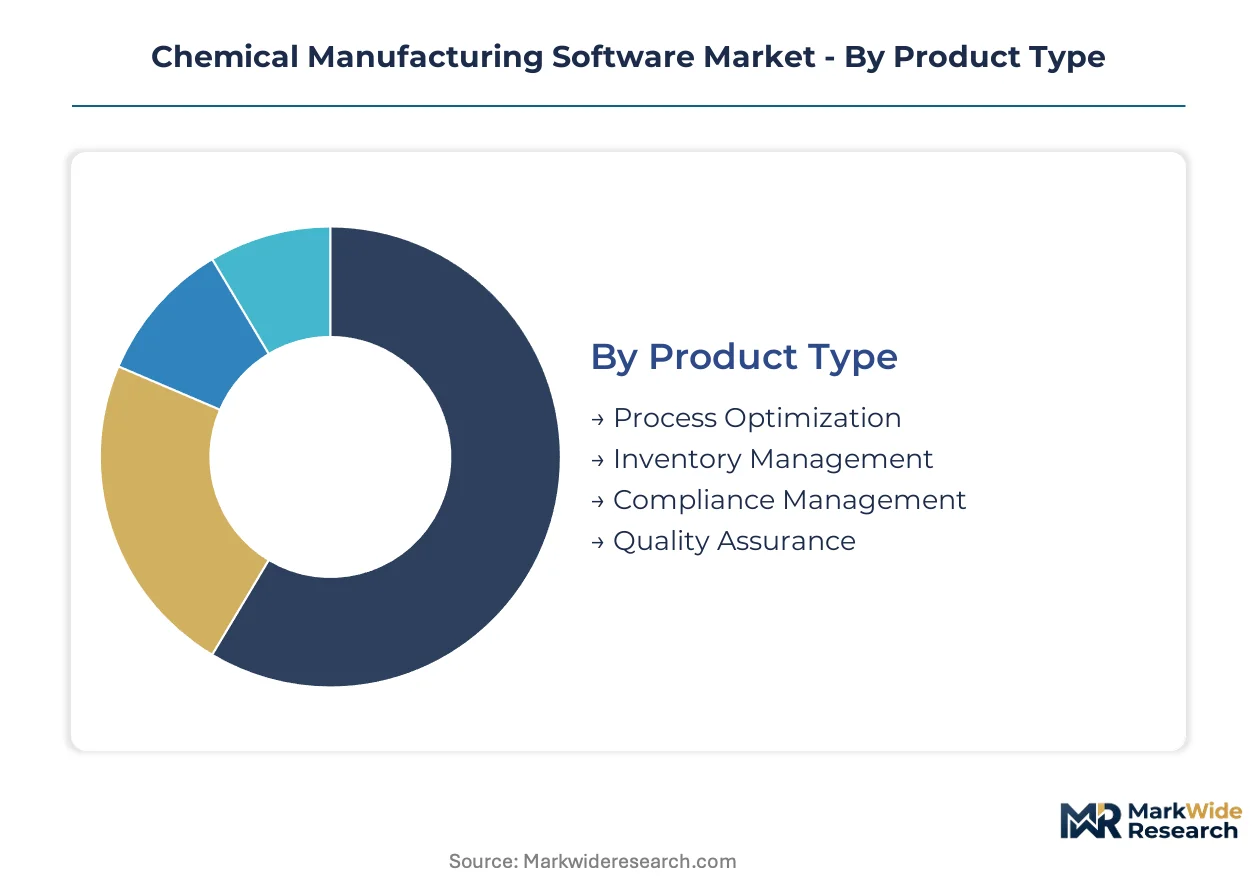
Chemical manufacturing software segments reflect divergent margin structures across operational technology layers. Producers allocate budgets based on regulatory exposure, batch complexity, and infrastructure modernization timelines rather than uniform platform adoption.
Product Type:
Margin pools concentrate in compliance-driven modules where audit failure costs exceed software investment multiples.
- Compliance Management:Platforms automate EPA Clean Air Act reporting, REACH substance registration through ECHA, and OSHA process safety documentation. German specialty chemical producers around Ludwigshafen deploy these systems to compress compliance timelines from years to months as enforcement windows tighten.
- Process Optimization:Systems synchronize recipe management, equipment utilization, and yield analytics with precision down to parts-per-million tolerances. Demand concentrates in Texas and Louisiana petrochemical corridors where continuous emissions monitoring must feed directly into batch records.
- Inventory Management:Modules track lot traceability and hazardous-material handling across multi-site operations.
- Quality Assurance:Platforms prevent batch deviations through laboratory information management integration with shop-floor execution.
The dominant share belongs to Compliance Management, while Process Optimization is closing the gap fastest.
Technology:
Deployment architecture determines capital treatment and implementation velocity across producer tiers.
- Cloud-Based:Subscription models eliminate capital depreciation for software assets. Specialty chemical firms in Germany and the US drive this transition fastest as they seek balance-sheet flexibility for capacity expansion without infrastructure capital intensity.
- SaaS:Purpose-built chemical manufacturing modules deliver rapid implementation for mid-market batch producers. Vendors compete aggressively for formula-driven workflows with monthly billing structures that displace perpetual licenses.
- Hybrid:Architectures split sensitive recipe IP on-premises while pushing analytics to cloud nodes.
- On-Premises:Legacy installations persist where validated system migration timelines require parallel FDA and EPA audit trail operation.
Cloud-Based deployments command the largest current share, though SaaS is expanding most quickly among mid-market accounts.
End User:
Customer type dictates functional requirements from formula complexity to regulatory jurisdiction.
- Specialty Chemicals:Producers of agrochemical and pharmaceutical intermediates require multi-step synthesis operations with precision tolerances. REACH substance registration deadlines through ECHA force European producers to deploy lot-level tracking systems that legacy platforms cannot support.
- Chemical Producers:Broad-base commodity manufacturers prioritize integrated ERP platforms across supplier networks in dense production clusters.
- Petrochemicals:Continuous processing operations in Texas and Louisiana face steep EPA enforcement ramps for Clean Air Act reporting.
- Fertilizers:Seasonal demand patterns and nutrient-specific formulation requirements shape procurement priorities.
Specialty Chemicals holds the deepest margin pool, with Petrochemicals gaining share fastest on regulatory compliance mandates.
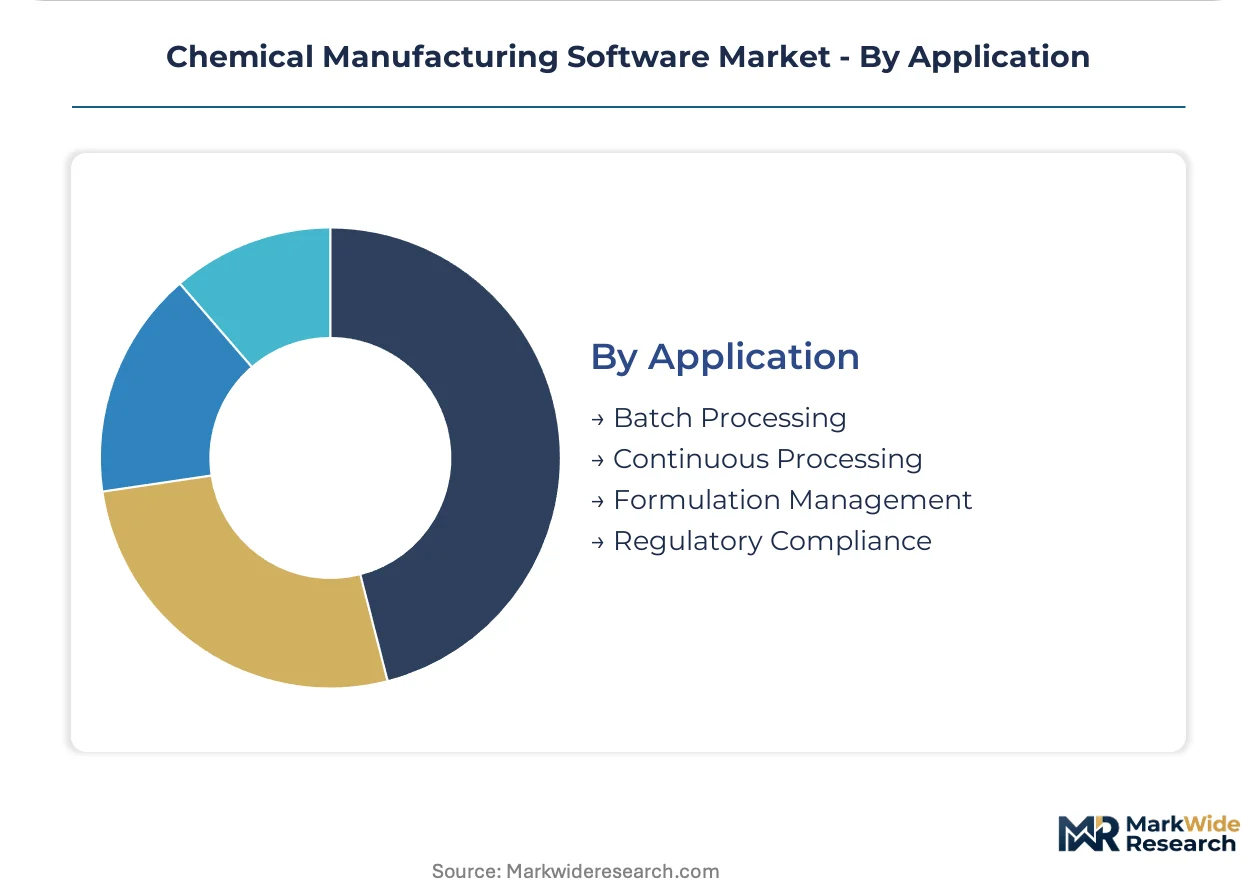
Application:
Use case segmentation tracks production mode and regulatory documentation intensity.
- Regulatory Compliance:Systems automate hazard documentation and emissions reporting. OSHA process safety management alignment creates competitive differentiation for producers serving regulated end-uses in pharmaceutical and agricultural chemical markets.
- Batch Processing:Formula-driven workflows require precision equipment utilization tracking. Edge computing deployments at reactor vessels enable real-time analytics without latency penalties for pharmaceutical intermediate producers.
- Formulation Management:Platforms secure proprietary recipe IP while enabling collaborative development cycles.
- Continuous Processing:Petrochemical operations demand synchronized control systems across integrated production trains.
Regulatory Compliance captures the dominant investment share, while Batch Processing is climbing the fastest on digital thread architecture adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software procurement concentrates where chemical production clusters face the steepest regulatory compliance ramps. Producers in Germany, the United States, China, Japan, and India account for the dominant share of manufacturing execution system deployments as enforcement windows tighten.
United States
Texas and Louisiana petrochemical corridors drive demand for EPA Clean Air Act reporting modules. The Environmental Protection Agency mandates continuous emissions monitoring integration with batch records. Houston-area producers prioritize platforms with pre-built regulatory templates over custom integration projects.
Germany
Ludwigshafen and Leverkusen chemical parks require synchronized ERP platforms across dense supplier networks. ECHA REACH substance registration deadlines force lot-level tracking system deployments. BASF and Bayer suppliers anchor integrated production clusters demanding multi-site coordination.
China
Yangtze River Delta specialty chemical producers upgrade legacy batch management systems under MEE environmental enforcement. The Ministry of Ecology and Environment tightens emissions data granularity requirements. Shanghai and Nanjing chemical parks deploy cloud-native manufacturing execution platforms.
Japan
Osaka and Nagoya pharmaceutical intermediate producers adopt edge computing architectures for real-time batch analytics. METI process safety guidelines elevate software from operational convenience to regulatory necessity. Chubu region chemical manufacturers prioritize predictive deviation detection systems.
India
Gujarat and Maharashtra agrochemical manufacturers deploy formula-based ERP modules for multi-step synthesis operations. CDSCO lot traceability requirements accelerate replacement cycles among legacy-dependent producers. Mumbai and Ahmedabad specialty chemical firms seek rapid implementation timelines.
Chemical Manufacturing Software Market Competitive Environment
Concentration sits with diversified enterprise software conglomerates and purpose-built chemical manufacturing specialists. The vendor landscape splits between horizontal ERP platforms with process-industry functionality and vertical solutions engineered for formula-driven workflows. Two strategic archetypes dominate: full-suite providers anchoring large-enterprise multi-site deployments, and nimble specialists competing for mid-market accounts on implementation velocity. Competitive moves center on cloud migration acceleration and AI-driven process optimization integration.
Within the diversified conglomerate tier, SAP S/4HANA and Oracle NetSuite ERP occupy positions anchoring enterprise-scale deployments across integrated chemical parks. BatchMaster ERP and Deacom ERP exemplify the vertical specialist archetype, representing purpose-built alternatives for formula-driven manufacturers seeking rapid deployment without extensive customization. Microsoft Dynamics 365 Business Central sits within the mid-market convergence zone, bridging horizontal functionality with sector-specific extensions.
| Leading Market Players |
|---|
| Aptean ERP |
| Infor CloudSuite Process Manufacturing |
| SAP S/4HANA |
| MRPeasy |
| Deacom ERP |
| Microsoft Dynamics 365 Business Central |
| BatchMaster ERP |
| MasterControl |
| Oracle NetSuite ERP |
| Others |
Value Chain & Pricing Dynamics
Ninety-day implementation timelines for validated manufacturing execution systems concentrate pricing power with vendors serving mid-market chemical producers in Germany and the United States. This lead-time compression tightens procurement leverage and elevates subscription-based SaaS models over perpetual licenses as buyers seek operational expenditure treatment.
Pricing Analysis
EPA Clean Air Act reporting mandates dictate the pricing tier structure across chemical manufacturing software deployments. Three-tier pricing structure across premium, standard, and economy levels separates validated enterprise suites from rapid-deployment SaaS modules and basic compliance tools. Price differentiation hinges on audit trail granularity and pre-built regulatory template depth. Pricing pressure stems from cloud-native entrants undercutting legacy on-premises maintenance contracts. Mid-market specialty chemical producers exhibit highest price sensitivity, while petrochemical majors prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Just-in-time deployment preferences dominate among German and US specialty chemical firms seeking balance-sheet flexibility, though strategic stockpiling of implementation capacity emerges during ECHA REACH enforcement windows. Software development concentrates in Germany, the United States, and India. Raw material dependencies span cloud infrastructure from hyperscalers, specialized chemical process engineering talent, and regulatory content libraries. Supply chain risk centers on single-source vulnerability for validated system migration expertise. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and cloud marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates formidable defensive moats in chemical manufacturing software as validated system migration costs lock producers into incumbent platforms. Switching costs compound through parallel FDA and EPA audit trail requirements during cutover periods.
For Market Incumbents: Consolidate cloud-native MES capabilities through targeted capability acquisitions rather than organic buildouts. Lock in multi-year subscription renewals before emerging AI-driven process optimization vendors mature. Vertical integration into edge computing hardware partnerships secures reactor-level deployment control against modular best-of-breed challengers.
For New Entrants and Emerging Players: PFAS tracking module gaps expose underserved compliance segments where legacy platforms lack native functionality. Target mid-market agrochemical intermediate producers in India and China with rapid-implementation SaaS offerings. White-label through regional systems integrators to bypass direct sales cost barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native chemical software sub-segments as subscription models displace perpetual license revenue recognition. Prioritize acquisition targets with established ECHA REACH compliance content libraries and validated FDA 21 CFR Part 11 audit trail architectures. Watch for inflection when EPA enforcement windows tighten for per- and polyfluoroalkyl substances reporting.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Converges laboratory information management with shop-floor execution for pharmaceutical intermediate producers. |
| Acquisition of Specialist Firm | Captures PFAS tracking expertise ahead of EPA enforcement window compression. |
| Geographic Expansion | Establishes localized implementation capacity in Yangtze River Delta chemical parks. |
| Strategic Partnership | Aligns edge computing nodes with reactor vessel analytics for real-time deviation detection. |
| Product Launch | Introduces pre-built OSHA process safety management modules for differentiated compliance positioning. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with chemical manufacturing stakeholders and secondary validation across regulatory and trade databases. Interview sources included plant managers at specialty chemical facilities, procurement leads at downstream agrochemical OEMs, distribution channel partners serving Ludwigshafen chemical parks, and technical R&D directors overseeing batch workflow optimization. Secondary sources encompassed ECHA substance registration databases, EPA enforcement action records, SEC 10-K filings from diversified chemical conglomerates, and Cefic industry statistics. Bottom-up deployment sizing triangulated against top-down market aggregation.
Across the projection horizon, the analytical framework modeled value trajectories by deployment architecture, producer tier, regulatory jurisdiction, and application intensity. Segmentation dimensions included cloud versus on-premises treatment, specialty versus commodity chemical orientation, and batch versus continuous processing mode. CAGRs derived from regression analysis against enforcement timeline acceleration and cloud adoption inflection patterns. Forecast inputs incorporated ECHA registration deadline schedules and hyperscaler infrastructure expansion disclosures.
Forecasts assume regulatory continuity in EPA Clean Air Act enforcement and ECHA REACH implementation; material policy shifts would require re-modeling. Specific risks include accelerated PFAS reporting mandates outpacing software capability development and validated system migration timeline extensions straining operational bandwidth. Revision becomes warranted when cloud-native vendor penetration in mid-market accounts crosses threshold dominance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Content Management Systems (CMS) Market
Software & Services
Computer Assisted Translation Software Market
Software & Services
India HR Payroll Software Market
Software & Services
Global User Interface Service Market
Software & Services
Automated Testing Software Market
Software & Services
Fire Software Market
Software & Services
Camera Tracking Software Market
Software & Services
Global Architect Software Market
Software & Services
Global Application Performance Monitoring (APM) Market
Software & Services
Tenant Billing Software Market
Software & Services
Data Center Backup and Recovery Software Market
Software & Services
Multivariate Testing Software Market
Software & Services
Global Job Evaluation Software Market
Software & Services
Mind Mapping Software Market
Software & Services
Middle East HR Payroll Software Market
Software & Services
Global PPC Software Market