
 Global Forestry Software Market | 2026-2036
Global Forestry Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Forestry Software Market Foresight
Multi-source procurement of geospatial analytics is restructuring how forestry enterprises assemble technology stacks. Trimble Inc. leverages its positioning hardware heritage to dominate precision forestry workflows. Environmental Systems Research Institute Inc. sustains platform ubiquity through deep GIS mapping integration across government and commercial accounts. Remsoft Inc. specializes in harvest optimization algorithms that anchor long-term planning contracts with North American timberland investment managers.
Global forestry software encompasses platforms that process satellite imagery, field sensor data, and biometric models to execute inventory monitoring, harvest scheduling, and carbon stock quantification across standing timber assets. These systems integrate GPS telemetry, LiDAR point clouds, and machine learning classifiers to deliver spatial accuracy below one meter for stand boundary delineation. Cloud-based deployment now leads solution type adoption as distributed field crews require real-time synchronization with central biomass calculation engines. GIS mapping commands premium pricing due to regulatory submission requirements in multiple jurisdictions, while risk assessment modules represent the fastest-growing solution category as climate-driven fire and pest exposure intensifies.
The EU Green Deal and associated EUDR deforestation regulations shape product standards by mandating geolocation traceability for imported timber, directly expanding demand for land use planning and inventory monitoring modules. Brazil's national space agency and environmental enforcement bodies enforce satellite-based compliance protocols that mirror EU traceability requirements, creating parallel certification complexity for exporters. Stakeholders must monitor whether emerging biodiversity disclosure frameworks in the European Union and voluntary carbon market standards in voluntary registries will force consolidation of currently separate forest management and carbon credit tracking workflows into unified platforms.
Market Dynamics
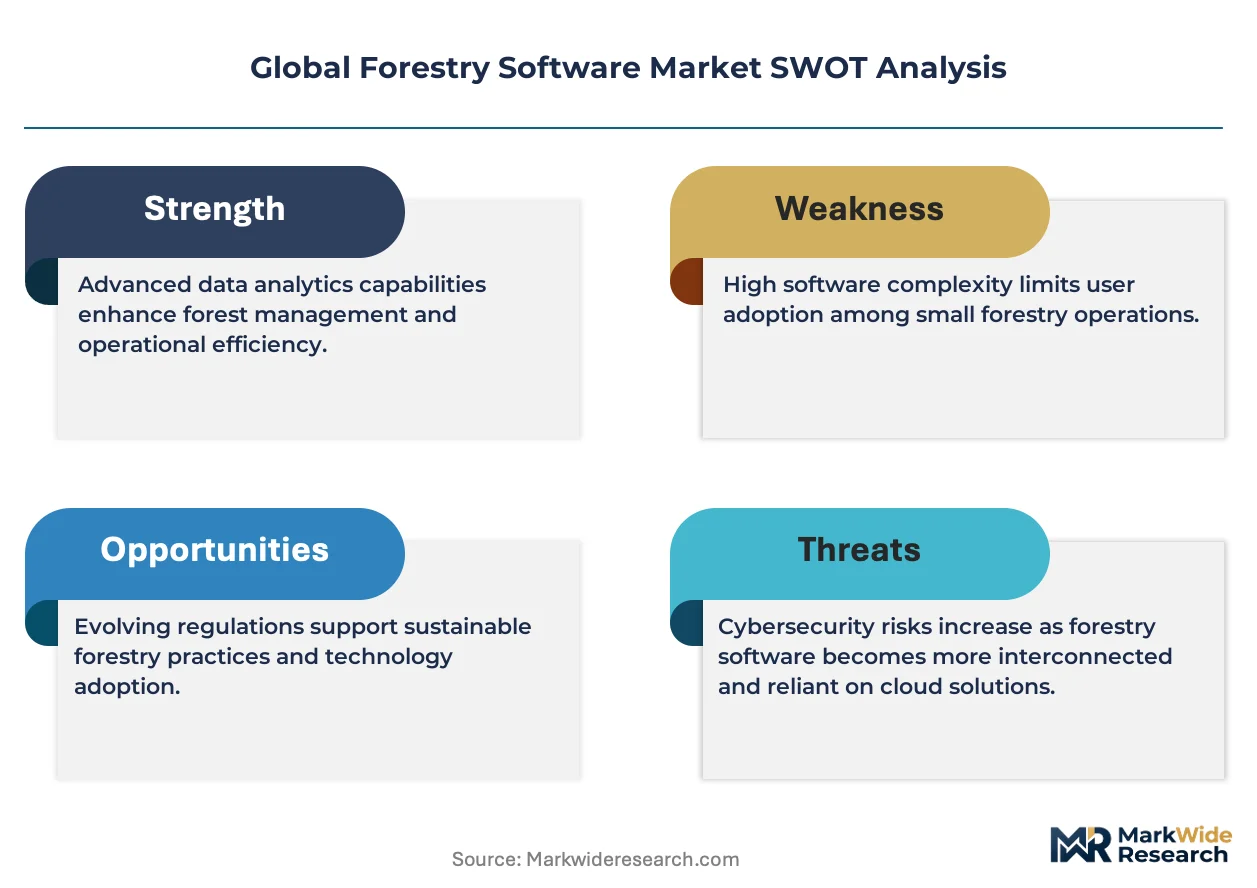
The EU Green Deal's deforestation-free supply chain mandates are compressing procurement timelines for traceability platforms, forcing timber operators to integrate satellite verification with legacy inventory systems before enforcement deadlines.
Growth Catalysts
- EUDR Geolocation Mandates:The EU Deforestation Regulation requires polygon-level traceability for timber imports, expanding demand for GIS-integrated compliance modules across European procurement offices.
- Carbon Credit Verification:Voluntary carbon market standards are requiring biometric quantification of standing biomass, pulling forest investment managers toward unified carbon-stock monitoring platforms.
- Brazil Satellite Integration:Brazil's national forest monitoring system enforces real-time deforestation alerts, compelling exporters to adopt INPE-compatible data feeds for license maintenance.
Market Restraints
- LiDAR Hardware Costs:High-resolution point cloud acquisition requires airborne sensor deployment at $15,000-$40,000 per flight, constraining smallholder adoption regardless of software accessibility.
- Cloud Infrastructure Concentration:Three hyperscale providers dominate forestry SaaS hosting, creating single-point vulnerability for distributed field synchronization across remote concessions.
- Interoperability Friction:Proprietary data formats from legacy harvest scheduling systems resist API integration with modern carbon quantification engines, extending implementation cycles.
Strategic Opportunities
- Indonesia Smallholder Networks:Palm oil and pulp supply chains in Indonesia retain 40% uncaptured plot-level data, creating white space for mobile-first inventory tools with offline functionality.
- CSRD Biodiversity Disclosure:The EU Corporate Sustainability Reporting Directive mandates ecosystem impact metrics, opening module demand for habitat connectivity modeling alongside timber yield optimization.
- Edge-AI Sensor Fusion:Convergence of on-device machine learning with low-earth orbit imagery enables sub-canopy biomass estimation without cloud latency, unlocking real-time harvest decisions in bandwidth-constrained terrain.
Industry Challenges
- Geospatial Talent Scarcity:Forestry enterprises compete with urban planning and defense sectors for remote sensing analysts, inflating compensation for Python-GIS proficiency by 35% annually.
- Dual Certification Burden:Operators supplying both EU and voluntary carbon markets must maintain parallel chain-of-custody documentation, duplicating field data collection without automated reconciliation.
- Legacy ERP Integration:Decades-old enterprise resource planning systems in major timberland investment trusts lack REST API architecture, forcing expensive middleware development for biomass data feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Forestry Software Market |
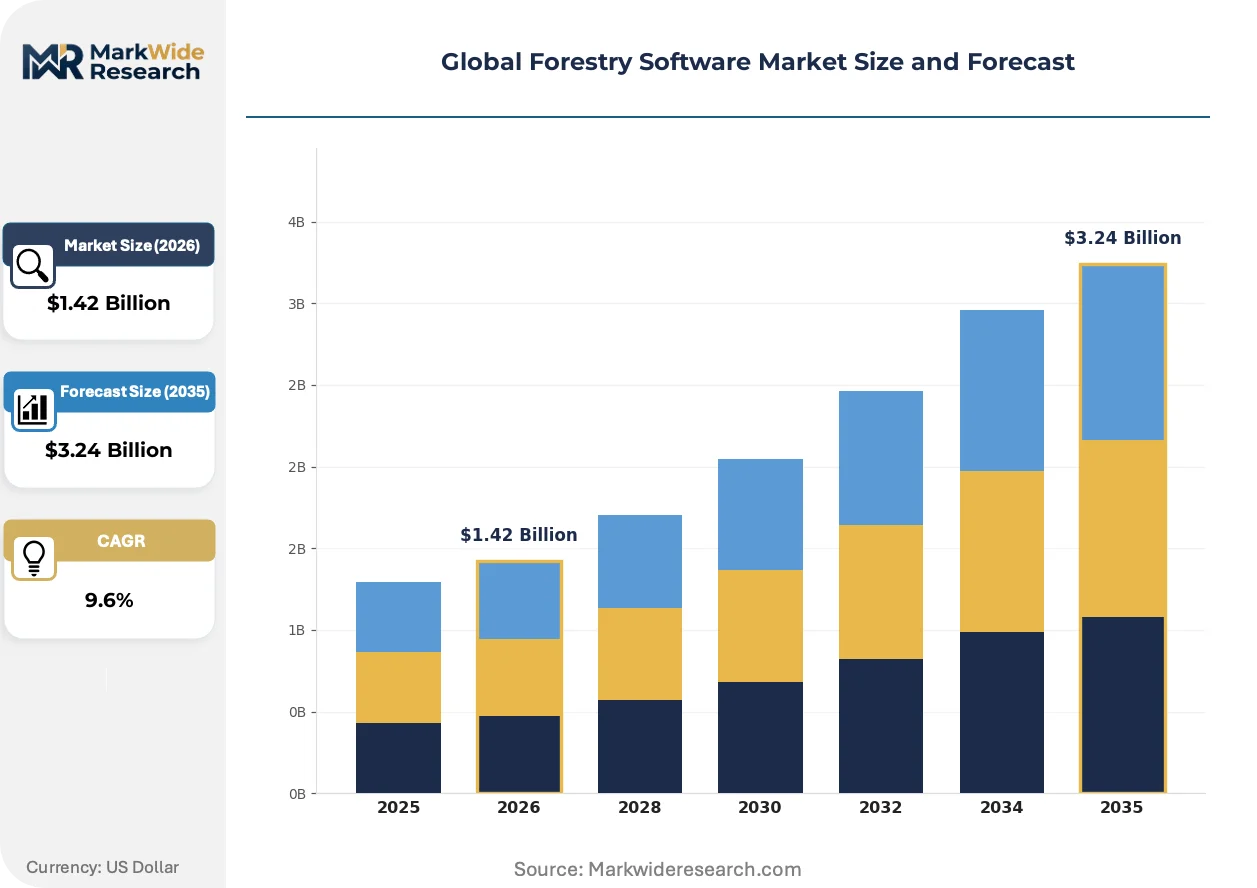
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.24 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based, Mobile Applications Solution Type: Forest Management, Inventory Monitoring, GIS Mapping, Biomass Calculation, Risk Assessment Application: Timberland Management, Wildlife Conservation, Carbon Credit Tracking, Fire Prevention, Land Use Planning End User: Forest Managers, Environmental Consultants, Government Agencies, Research Institutions, Private Landowners |
| Companies Covered | Trimble Inc., Environmental Systems Research Institute Inc., Remsoft Inc., Silvacom Ltd., Assisi Software Corp., Forest Metrix LLC, AFRY AB, Enfor Consultants Ltd., Creative Information Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Forestry Software Market Shifts & Advancements
Machine learning classifiers and low-code platform architectures are compressing the traditional vendor-customer boundary, enabling timber operators to configure domain-specific workflows without dedicated software engineering capacity.
Hyperspectral imaging is consolidating multiple forest health indicators into single-pass data collection. Large-scale concessions in Canada and Sweden are replacing separate pest-detection, moisture-mapping, and species-classification flights with unified sensor payloads. This compression is collapsing the traditional service-provider stack into vertically integrated platform offerings.
REACH chemical traceability extensions are forcing adhesive and treatment suppliers into geolocation data sharing. The European Chemicals Agency's expanded due diligence requirements now cover forest-sourced feedstocks, compelling coating manufacturers to demand polygon coordinates from pulp suppliers. Nordic sawmill clusters are responding by mandating software-enabled chain-of-custody documentation from all inbound chip deliveries.
Subscription-based field crew management is displacing perpetual-license deployment models. Timberland investment managers in the US Southeast and Pacific Northwest are unbundling software access from hardware procurement, paying per-active-user rates that scale with seasonal harvest labor fluctuations. This shift concentrates vendor revenue into Q2-Q3 harvest windows, altering cash flow patterns across the supplier base.
Global Forestry Software Market Segmentation
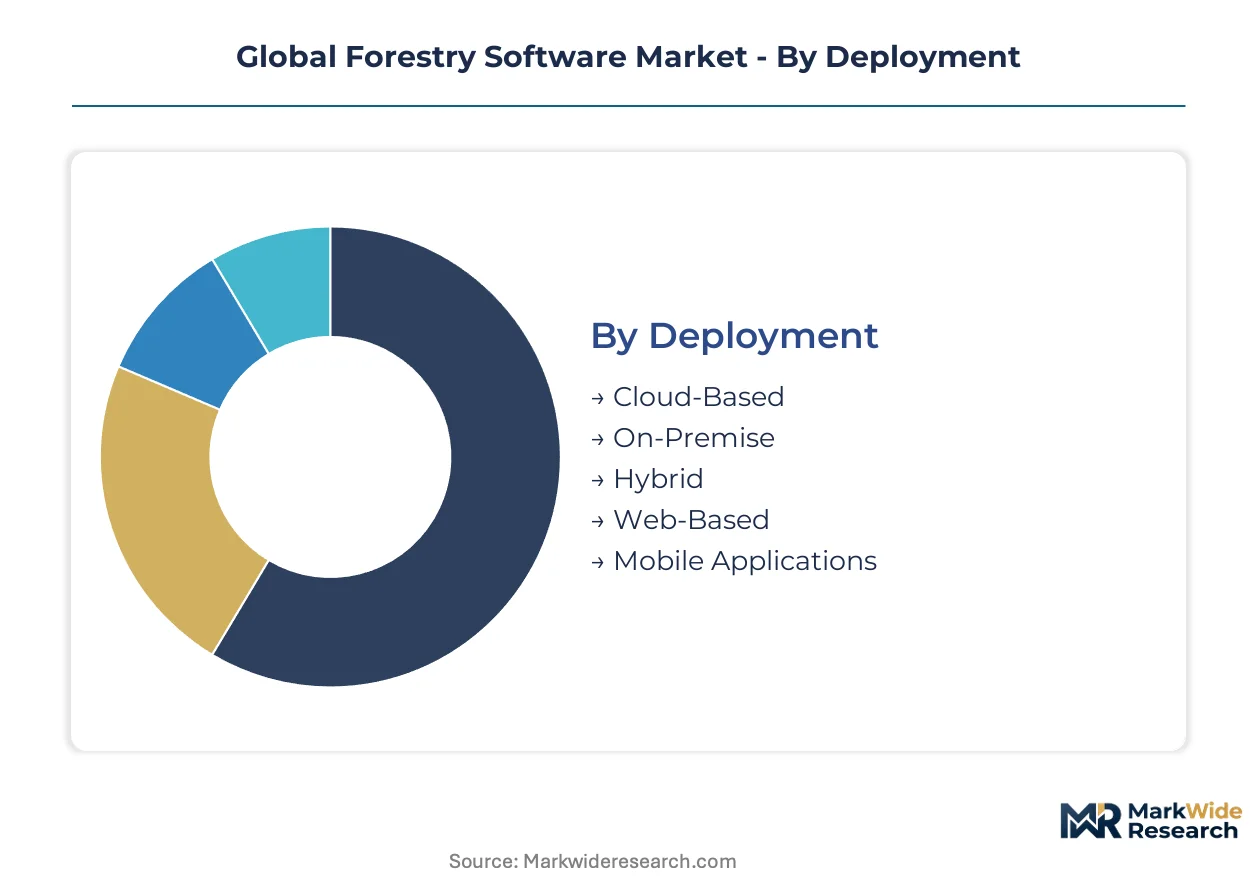
Forestry software procurement patterns diverge sharply between large timberland investment trusts requiring enterprise-grade integration and distributed field operations prioritizing mobile accessibility. Understanding these fault lines reveals where vendor R&D concentrates and which deployment models capture sustained contract value.
Deployment:
Cloud-based platforms dominate transaction volume while hybrid architectures command premium pricing for security-sensitive government accounts.
- Cloud-Based:Real-time synchronization across distributed field crews eliminates version conflicts during multi-concession harvest operations. Demand concentrates in Brazil and Indonesia where cellular coverage expansion enables centralized biomass calculation without local server infrastructure.
- On-Premise:Air-gapped installations serve defense-adjacent timber operations and classified research programs requiring physical data sovereignty. Scandinavian state forest agencies maintain these deployments despite higher total cost of ownership.
- Hybrid:Edge computing nodes process LiDAR point clouds locally before encrypted upload to central repositories. Canadian and Russian operators in bandwidth-constrained boreal zones drive adoption for sub-canopy biomass estimation workflows.
- Web-Based:Browser-accessible dashboards lower procurement friction for smallholder cooperatives with intermittent connectivity. Southeast Asian pulp supply chains deploy these for rapid EUDR compliance documentation.
- Mobile Applications:Offline-capable field data collection tools with GPS telemetry and voice-note transcription. US Pacific Northwest timber cruising crews and Brazilian IBAMA enforcement teams represent core demand pockets.
Mature deployment sits with On-Premise systems in Northern European state forests. Newer deployment is concentrated in Cloud-Based architectures across Latin American export operations.
Solution Type:
Regulatory submission requirements elevate GIS Mapping to premium pricing tiers while carbon market expansion accelerates Biomass Calculation module procurement.
- Forest Management:Integrated platforms combining harvest scheduling, crew dispatch, and equipment maintenance across multi-decade rotation cycles. North American timberland investment managers anchor demand through long-term enterprise contracts with optimization algorithm providers.
- Inventory Monitoring:Satellite-GIS fusion systems tracking stand-level volume changes through synthetic aperture radar and optical imagery classification. Brazilian INPE compliance mandates and EU Deforestation Regulation traceability requirements drive parallel procurement waves.
- GIS Mapping:Polygon-level geolocation documentation satisfying EUDR geolocation mandates and voluntary carbon registry boundary verification. Premium pricing reflects regulatory submission packaging across European procurement offices and California compliance markets.
- Biomass Calculation:Machine learning classifiers converting LiDAR point clouds and field measurements into carbon stock quantifications. Voluntary carbon market standards from Verra and Gold Standard propel adoption among forest investment managers seeking dual revenue streams.
- Risk Assessment:Fire behavior modeling, pest outbreak prediction, and climate exposure scoring for insurance and operational continuity planning. Australian and US Western operators facing intensified wildfire seasons represent the steepest expansion trajectory.
Established procurement patterns favor Forest Management suites with decade-long vendor relationships. Accelerating investment flows into Biomass Calculation and Risk Assessment modules reflect carbon market maturation and climate adaptation imperatives.
Application:
Timberland Management retains the largest installed base while Carbon Credit Tracking exhibits the most rapid contract velocity expansion.
- Timberland Management:Harvest optimization, road network planning, and silvicultural treatment scheduling across institutional timber assets. US Southeast and Pacific Northwest investment trusts sustain the core revenue base for established vendors.
- Wildlife Conservation:Habitat connectivity modeling and biodiversity impact assessment for regulatory compliance and certification maintenance. EU CSRD disclosure requirements and HCVF (High Conservation Value Forest) assessments drive module attachment to core forestry platforms.
- Carbon Credit Tracking:End-to-end quantification, verification, and registry submission workflows for voluntary and compliance carbon markets. Brazil, Indonesia, and US-based forest carbon project developers dominate procurement as market liquidity deepens.
- Fire Prevention:Fuel load mapping, ignition risk scoring, and suppression resource pre-positioning algorithms. Australian state fire agencies and US Forest Service units anchor public-sector demand following catastrophic fire seasons.
- Land Use Planning:Deforestation-free supply chain documentation and concession boundary compliance for export licensing. EU Green Deal implementation and emerging UK and Australian due diligence legislation expand addressable market scope.
Volume concentration remains with Timberland Management applications in mature North American markets. Contract velocity and pricing power are shifting fastest toward Carbon Credit Tracking as financialization of forest carbon accelerates.
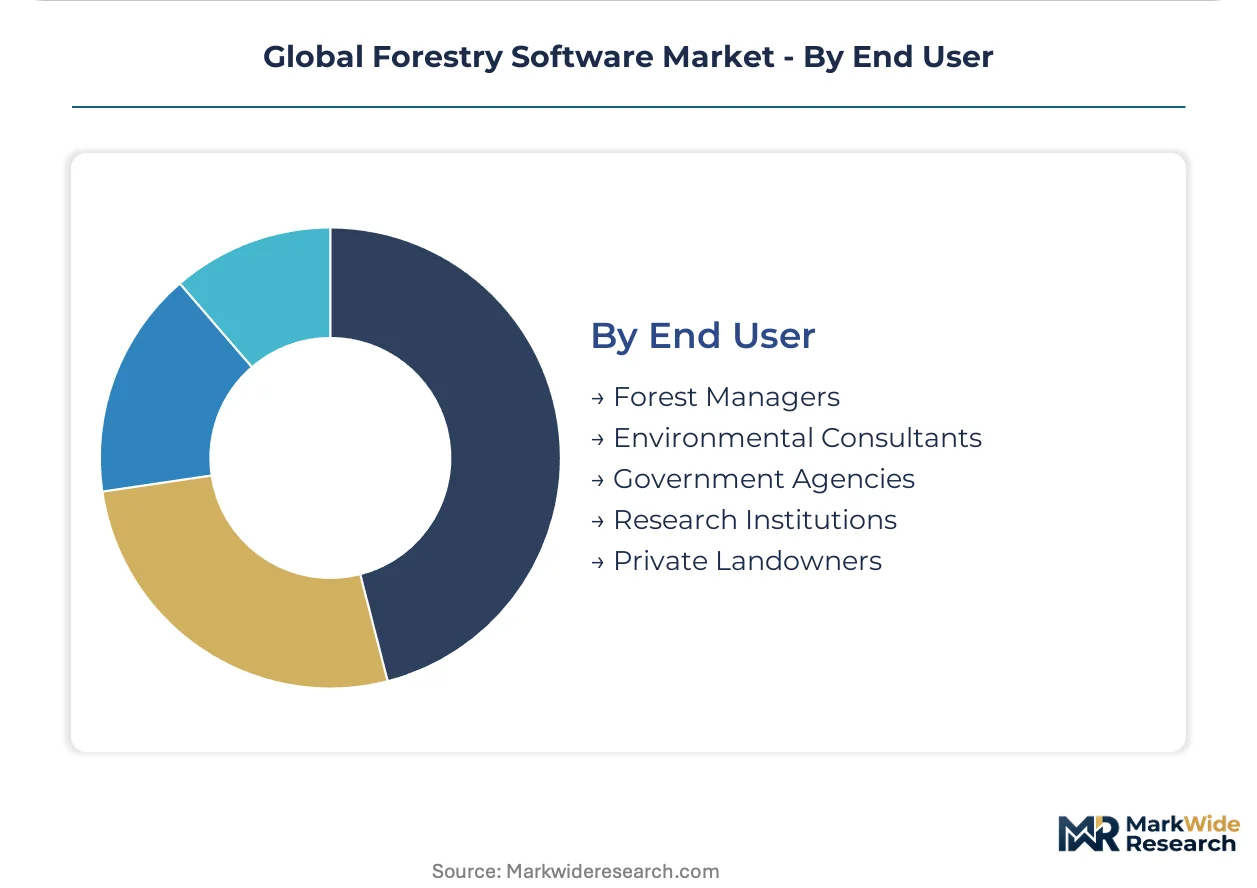
End User:
Forest Managers and Government Agencies represent opposing procurement archetypes: subscription scalability versus bespoke integration requirements.
- Forest Managers:Timberland investment trusts and industrial forestry operators requiring harvest optimization and carbon stock quantification across large holdings. US-based REITs and Canadian pension fund timber assets drive enterprise contract values.
- Environmental Consultants:Third-party verification and certification bodies auditing forest management plans and carbon project methodologies. EU-based sustainability consultancies and Brazilian INPE-licensed analysts represent concentrated demand.
- Government Agencies:National forest services, environmental enforcement bodies, and space agencies operating satellite monitoring infrastructure. Brazil's INPE, US Forest Service, and European Environment Agency procurement cycles shape platform development roadmaps.
- Research Institutions:Universities and national laboratories developing biometric models and machine learning classifiers for canopy analysis. Swedish, Finnish, and Canadian forestry research institutes maintain specialized tool requirements.
- Private Landowners:Non-industrial forest owners and smallholder cooperatives seeking simplified inventory and compliance documentation. Mobile-first, offline-capable tools targeting Indonesian palm oil smallholders and US family forest owners represent emerging vendor priorities.
Long-standing procurement relationships characterize Government Agency accounts with multi-year implementation horizons. Private Landowner segments are attracting venture investment for mobile-native platform development targeting uncaptured plot-level data across tropical supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boreal timber reserves in Sweden anchor European software procurement for precision harvest scheduling, while tropical concessions in Brazil and Indonesia drive satellite-GIS integration for compliance documentation. The analysis traces demand concentration across five national markets where forest asset scale and regulatory stringency intersect.
United States
Timberland investment trusts in the Pacific Northwest and Southeast deploy harvest optimization platforms across multi-decade rotation cycles. The USDA Forest Service procurement shapes public-sector platform requirements for wildfire risk modeling. Seattle and Portland host concentrated vendor development activity for cloud-based biomass calculation engines.
Brazil
Amazon basin exporters integrate INPE-compatible satellite feeds to maintain export licensing under national deforestation monitoring protocols. ANVISA-aligned environmental enforcement drives real-time alert system procurement. São Paulo-based pulp conglomerates anchor demand for polygon-level traceability documentation serving EU import requirements.
Canada
Boreal zone operators in Alberta and British Columbia adopt hybrid edge-computing architectures for bandwidth-constrained biomass estimation. Health Canada forest health monitoring programs influence public-sector software specifications. Vancouver and Calgary clusters concentrate LiDAR processing service providers for precision stand delineation.
Germany
Baden-Württemberg state forest agencies mandate GIS-integrated management platforms for EU Green Deal compliance documentation. ECHA REACH extensions force adhesive suppliers into geolocation data sharing with pulp sources. Munich and Stuttgart host specialized consultancies bridging forestry operations with CSRD biodiversity disclosure requirements.
Indonesia
Sumatra and Kalimantan smallholder networks present uncaptured demand for mobile-first inventory tools with offline functionality. The national environment ministry enforces satellite-based concession monitoring parallel to EU Deforestation Regulation traceability standards. Jakarta-based pulp traders drive procurement of web-based compliance dashboards for rapid EUDR documentation.
Global Forestry Software Market Competitive Landscape
Global majors compete with regional champions across deployment architecture specialization, with cloud-native platforms facing hybrid-edge alternatives in bandwidth-constrained terrain. The vendor base organizes into three tiers: precision hardware-software integrators, pure-play optimization algorithm providers, and GIS-platform incumbents with government account dominance. Consolidation pressure concentrates among harvest scheduling specialists seeking carbon quantification capabilities, while geographic expansion targets tropical supply chain documentation gaps.
Within the precision hardware-software tier, Trimble Inc. and Environmental Systems Research Institute Inc. exemplify divergent heritage strategies—positioning equipment lineage versus mapping platform ubiquity. Remsoft Inc. occupies a specialized position in harvest optimization algorithms for North American timberland investment managers. These three anchors illustrate how vendor archetypes align with distinct procurement archetypes: capital-intensive field hardware, enterprise GIS integration, and quantitative planning tools.
| Leading Market Players |
|---|
| Trimble Inc. |
| Environmental Systems Research Institute Inc. |
| Remsoft Inc. |
| Silvacom Ltd. |
| Assisi Software Corp. |
| Forest Metrix LLC |
| AFRY AB |
| Enfor Consultants Ltd. |
| Creative Information Systems Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up timberland investment trusts concentrate procurement leverage across North American holdings, compressing vendor margins while demanding bundled satellite-GIS compliance modules that fuse legacy harvest scheduling with carbon quantification engines.
Pricing Analysis
Service-bundling architectures separate platform access from implementation support, with subscription tiers scaling by active user count rather than perpetual licensing. Three-tier pricing structure across premium, standard, and economy levels reflects integration depth with ERP systems and carbon registry APIs. Cost compression in the economy tier is intensifying because mobile-first entrants target Indonesian smallholder networks with stripped-down offline tools. Government agencies in Brazil and Germany exhibit lowest price sensitivity due to multi-year procurement cycles and regulatory mandate funding.
Supply Chain Analysis
LiDAR sensor supply rests on Canadian and Swedish airborne survey providers, with hyperspectral payload manufacturing concentrated in US and German precision optics clusters. Cloud infrastructure draws from hyperscale data center networks across Ireland, Singapore, and Virginia. Single-source vulnerability concentrates in satellite imagery feeds from government space agencies. Distribution runs through specialized forestry consultancies bridging software vendors with concession operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning classifiers are displacing rule-based biometric models, forcing vendors to reprice optimization algorithms around predictive accuracy guarantees rather than static feature sets.
For Market Incumbents: Anchor enterprise relationships through backward integration into carbon registry APIs, defending against pure-play biomass calculation entrants. Prioritize hybrid-edge deployment architectures for Canadian and Russian boreal operators facing bandwidth constraints. Certification investment in Verra and Gold Standard methodology alignment secures dual-revenue stream positioning.
For New Entrants and Emerging Players: Edge-AI sensor fusion offers technology-first wedge into fire prevention and pest detection modules where incumbent platforms lack real-time inference capability. Target Indonesian smallholder cooperatives with offline-capable mobile tools addressing the 40% uncaptured plot-level data gap. Go-to-market through pulp trader compliance dashboards accelerates EUDR documentation adoption.
For Investors and Strategic Acquirers: Distressed-cycle entries favor harvest optimization specialists with stranded algorithm IP in North American timberland management. Long-term viability hinges on unified carbon-forestry platform consolidation as voluntary market standards harden. Watch for EU CSRD biodiversity disclosure enforcement as inflection signal forcing habitat connectivity module attachment.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies forest management and carbon credit tracking workflows for EU Green Deal compliance. |
| Acquisition of Specialist Firm | Consolidates harvest optimization algorithms with biomass calculation engines serving timberland REITs. |
| Geographic Expansion | Targets Indonesian smallholder networks with mobile-first tools for EUDR traceability documentation. |
| Strategic Partnership | Links LiDAR service providers with cloud vendors for hybrid-edge deployment in bandwidth-constrained terrain. |
| Product Launch | Introduces edge-AI sensor fusion enabling sub-canopy biomass estimation without cloud latency. |
Research Methodology
Independent corroboration across timberland investment trust CTOs, Brazilian INPE-licensed environmental analysts, EU-based sustainability consultants, and Indonesian pulp supply chain managers underwrites the qualitative findings. Secondary validation draws from USDA Forest Service procurement disclosures, INPE satellite monitoring protocols, EUDR implementation guidance, and Verra carbon registry methodology documents. Bottom-up deployment model penetration estimates triangulate against top-down timberland asset value allocations.
Rate-of-change decomposition separates cloud adoption velocity from carbon market module attachment across the analysis window. Segmentation dimensions include deployment architecture, solution type, application, and end-user procurement archetype. CAGRs derive from biometric model advancement curves and regulatory enforcement timeline phasing. Forecast inputs incorporate cellular coverage expansion trajectories in tropical concessions and LiDAR sensor cost decline patterns.
Several conditions sit outside the modeled scope, including abrupt EUDR enforcement delays, sovereign deforestation monitoring system failures, and hyperscale cloud provider service disruptions. Forecasts reflect documented assumptions about carbon market liquidity and satellite imagery resolution advancement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Franchise Management Software Market
Software & Services
Expense Management Software Market
Software & Services
Sales Performance Management (SPM) Software Market
Software & Services
Global Decision Support Software Market
Software & Services
Application Virtualization Market
Software & Services
Quality Management Software Market
Software & Services
Computer Backup Software Market
Software & Services
Advanced Product Quality Planning (APQP) Software Market
Software & Services
Construction Simulation Software Market
Software & Services
Global Cloud Testing Market
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
App Development Software Market
Software & Services
Global Database Software Market
Software & Services
Enterprise-Grade Saas Market
Software & Services
3D Animation Production Software Market
Software & Services
Contract Abstraction Software Market