
 Global Retail Inventory Management Software Market | 2026-2036
Global Retail Inventory Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Retail Inventory Management Software Market Foresight
GDPR is hardening data residency requirements for inventory platforms processing European consumer information. Oracle Corporation leverages its autonomous database architecture to sustain compliance-heavy deployments across multinational retail chains. Manhattan Associates dominates warehouse-centric inventory optimization through its specialized supply chain execution layer.
Retail inventory management software encompasses systems that track stock levels, automate replenishment, and synchronize supply chain data through barcode scanning, RFID integration, and API-connected ERP modules. Cloud-based deployment leads solution uptake as retailers prioritize elastic infrastructure over fixed on-premise licensing. Demand forecasting within solution offerings is expanding fastest, driven by machine learning pipelines that reduce safety stock carrying costs. E-commerce platforms represent the most margin-rich customer type, requiring sub-second inventory visibility across distributed fulfillment nodes.
The EU AI Act, FDA traceability rules for food retail, and China's GB standards for data security collectively elevate compliance costs for cross-border software vendors. CE marking requirements under the EU Green Deal push vendors toward energy-efficient data center partnerships. Stakeholders must evaluate whether their architecture can absorb emerging algorithmic accountability rules without fragmenting their core codebase.
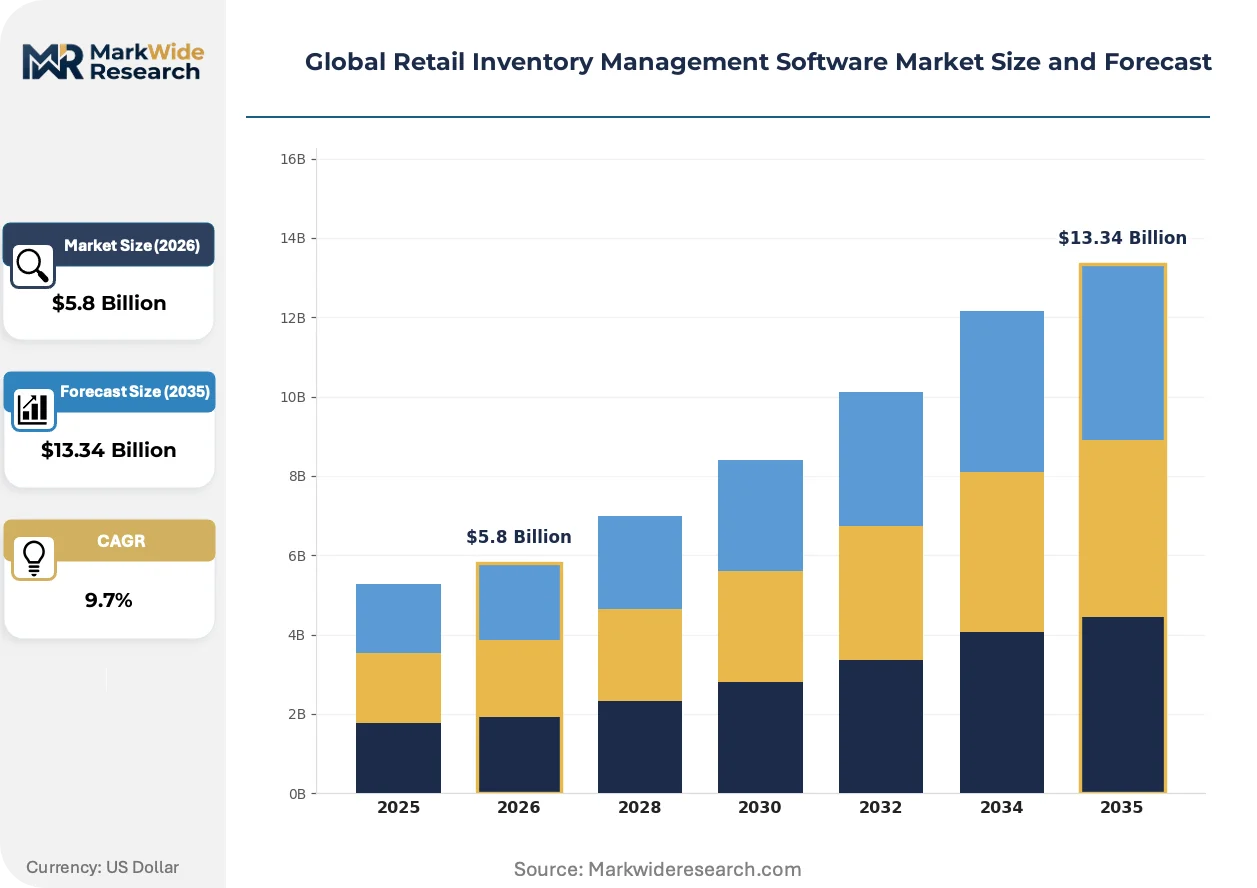
Market Dynamics
Cloud migration is compressing deployment cycles for retail inventory platforms as elastic infrastructure replaces fixed-capacity licensing models. Real-time synchronization demands from omnichannel fulfillment networks are forcing architectural rewrites of legacy stock-tracking systems.
Growth Catalysts
- GDPR data residency mandates:European retailers must process consumer inventory data within jurisdictional boundaries. Cloud vendors with EU sovereign data centers capture replacement demand from non-compliant legacy installations.
- RFID integration at item level:Apparel and electronics retailers deploy radio-frequency tagging to eliminate cycle-count labor. Tag cost curves below five cents per unit unlock mass-market adoption across mid-tier chains.
- Machine learning pipelines:Demand forecasting modules reduce safety stock carrying costs by predicting SKU-level velocity patterns. Retailers with seasonal inventory volatility prioritize these algorithmic replenishment tools.
Market Restraints
- Implementation cost concentration:Mid-market retailers face six-figure minimums for cloud ERP integration with inventory modules. On-premise amortization schedules create switching friction against SaaS migration.
- Technical debt in legacy warehouses:Facilities running twenty-year-old WMS platforms require forklift-level sensor retrofits for real-time visibility. Hardware refresh cycles lag software capability by three to five years.
- EU AI Act algorithmic accountability:Automated demand forecasting systems face audit requirements for decision explainability. Vendors must maintain dual codebases for European versus non-European deployments.
Strategic Opportunities
- India organized retail penetration:Modern trade formats in tier-two cities lack integrated inventory systems. Cloud-native vendors with mobile-first interfaces capture greenfield installations ahead of incumbent arrival.
- FDA food traceability rules:Section 204 of the Food Safety Modernization Act mandates lot-level tracking for high-risk foods. Grocery chains require specialized inventory modules with blockchain-enabled provenance logging.
- Edge-AI convergence:Camera-based shelf monitoring merges computer vision with local inference chips. Distributed fulfillment nodes gain sub-second stock visibility without round-trip cloud latency.
Industry Challenges
- Data engineering talent scarcity:Retailers compete with technology firms for pipeline architects capable of integrating POS, warehouse, and supplier EDI feeds. Compensation inflation reaches twenty percent annually for experienced hires.
- API standardization fragmentation:Each major ERP vendor maintains proprietary inventory event schemas. Middleware development consumes forty percent of implementation timelines for multi-system environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Retail Inventory Management Software Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.34 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Managed Services Solution Offering: Inventory Tracking, Demand Forecasting, Order Management, Supplier Management, Reporting & Analytics Application: Store Management, Warehouse Management, Omnichannel Optimization, Stock Replenishment, Asset Tracking Customer Type: Department Stores, Specialty Retailers, Convenience Stores, E-commerce Platforms, Discount Outlets |
| Companies Covered | Oracle Corporation, SAP SE, Manhattan Associates, IBM Corporation, Microsoft Corporation, Fishbowl, Zoho Corporation, Epicor Software Corporation, Lightspeed Commerce Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Retail Inventory Management Software Market Shifts & Advancements
Artificial intelligence is embedding into operational workflows rather than remaining a layered analytics add-on. Inventory platforms now automate decisions previously requiring human judgment at store and warehouse levels.
Computer vision is absorbing shelf-monitoring responsibilities from manual cycle counts. Grocery and mass-merchandise chains deploy ceiling-mounted camera arrays to detect stockouts and misplaced items in real time. Capital expenditure per store runs below fifty thousand dollars for retrofit installations. The technology is absorbing labor hours previously allocated to overnight inventory teams, compressing operating cost structures for twenty-four-hour operations.
REACH chemical compliance is forcing material traceability into textile and electronics inventory systems. Retailers must map supplier chemical inputs through multi-tier supply chains to satisfy European registration requirements. Apparel brands with Asian manufacturing footprints face the steepest documentation burdens. The regulation is reshaping supplier onboarding workflows, with inventory platforms now required to maintain substance-level bill-of-materials databases.
Subscription replenishment models are decoupling inventory ownership from consumption. Direct-to-consumer brands retain stock on balance sheets while charging customers for access rather than product transfer. Pet supplies and personal care verticals lead this pivot. The shift concentrates demand forecasting risk with vendors while transferring carrying cost visibility to platform operators.
Global Retail Inventory Management Software Market Segmentation
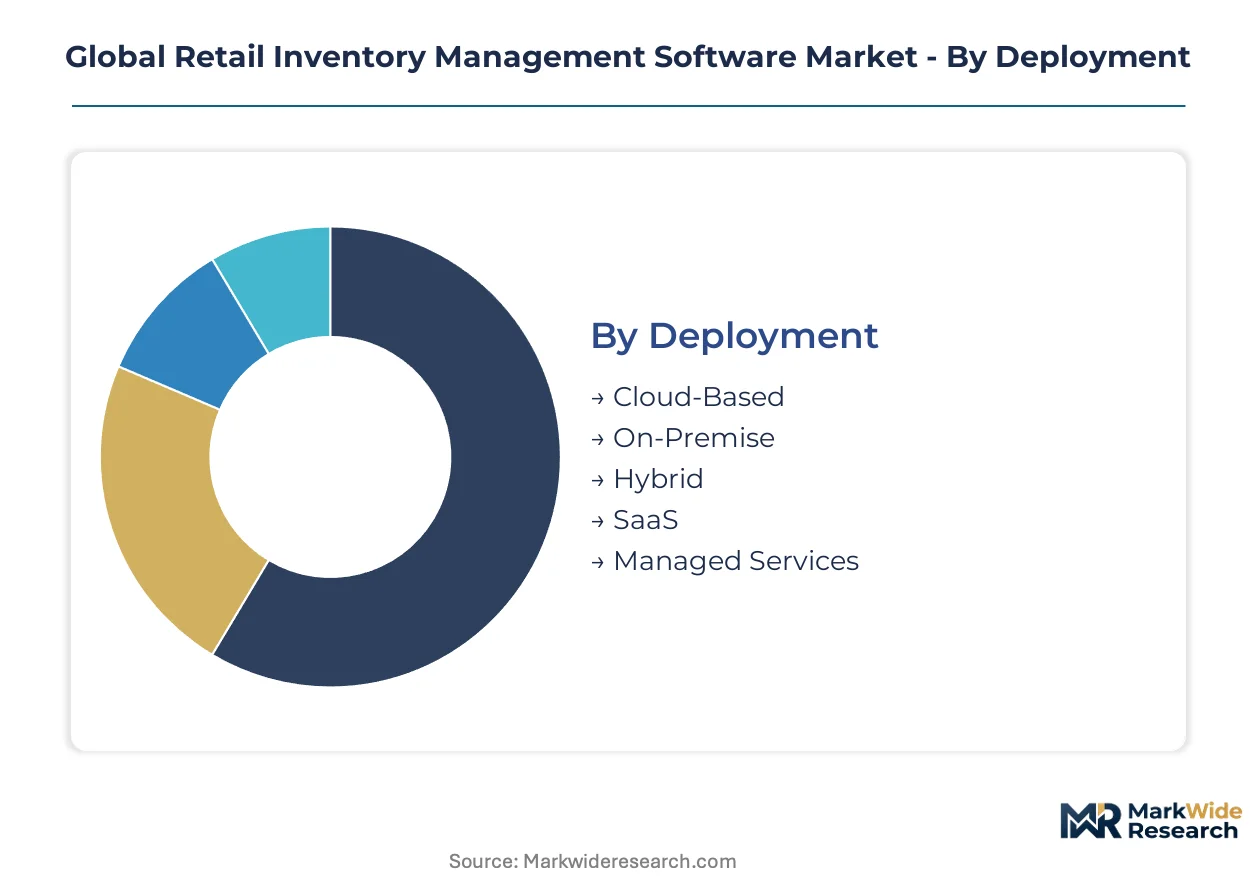
Deployment architecture determines total cost of ownership and compliance posture for retail inventory systems. Solution configurations vary sharply by capital intensity, data residency requirements, and integration complexity with legacy ERP estates.
Deployment:
Capital intensity peaks with on-premise installations requiring server hardware, data center buildout, and dedicated IT staffing. Cloud alternatives shift expenditure to recurring operational budgets while reducing upfront infrastructure commitments.
- Cloud-Based:Elastic compute resources scale with transaction volume spikes during promotional windows. United States retailers with distributed store footprints prioritize multi-region redundancy to maintain sub-second inventory visibility across fulfillment nodes.
- On-Premise:Dedicated infrastructure within corporate data centers satisfies strictest data sovereignty mandates. German retailers processing consumer loyalty data deploy localized instances to satisfy GDPR residency requirements without third-party cloud exposure.
- Hybrid:Sensitive transaction data remains on-premise while analytics workloads burst to public cloud.
- SaaS:Subscription licensing eliminates perpetual software procurement cycles.
- Managed Services:Third-party operators assume infrastructure maintenance burden.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Managed Services as mid-market retailers outsource operational complexity.
Solution Offering:
Functional modules align with specific operational pain points across the retail value chain. Margin capture concentrates in predictive capabilities that reduce working capital tied up in safety stock.
- Demand Forecasting:Machine learning pipelines ingest POS feeds, weather patterns, and promotional calendars to project SKU-level velocity. E-commerce platforms with high SKU turnover deploy these modules to minimize stockouts during demand surges.
- Inventory Tracking:Real-time position monitoring through barcode, RFID, or computer vision feeds. Warehouse operators in China integrate these systems with robotic picking infrastructure to synchronize automated fulfillment.
- Order Management:Orchestrates allocation logic across distributed fulfillment nodes.
- Supplier Management:Vendor scorecarding and automated procurement workflows.
- Reporting & Analytics:Dashboard visualization of inventory health metrics.
Demand Forecasting commands premium pricing per seat. Inventory Tracking maintains the broadest installed base across retail tiers.
Application:
Use case specialization reflects divergent operational rhythms between customer-facing and back-of-house environments. Implementation complexity scales with real-time synchronization requirements.
- Omnichannel Optimization:Unified inventory visibility across digital and physical channels enables buy-online-pickup-in-store and ship-from-store fulfillment. United States department stores invest heavily here to compete with pure-play e-commerce delivery velocity.
- Warehouse Management:Directed put-away, picking optimization, and labor scheduling within distribution centers. German logistics hubs deploy these systems to coordinate cross-border e-commerce fulfillment into EU member states.
- Store Management:Shelf replenishment alerts and intra-store transfer coordination.
- Stock Replenishment:Automated reorder point calculation and purchase order generation.
- Asset Tracking:Fixed asset register maintenance for store equipment and fixtures.
Warehouse Management carries the heaviest per-site implementation cost. Omnichannel Optimization is gaining share fastest as retailers unify previously siloed inventory pools.
Customer Type:
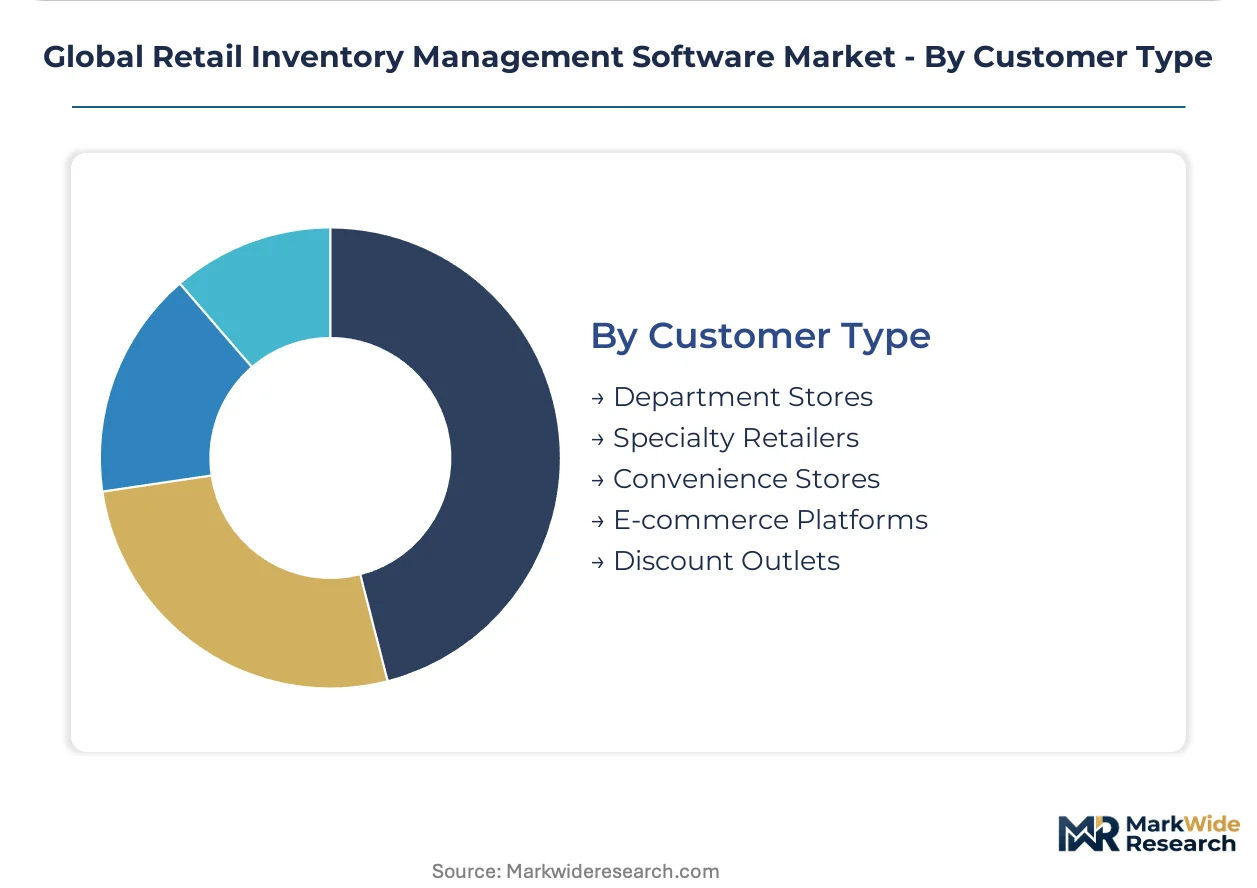
Technology sophistication and integration budget vary dramatically across retail format economics. E-commerce pure-plays start greenfield while legacy formats wrestle with decades of technical debt.
- E-commerce Platforms:Cloud-native architecture from inception with API-first integration patterns. These operators in China and the United States demand millisecond-latency inventory APIs to power dynamic pricing engines.
- Department Stores:Complex multi-banner portfolios with heterogeneous legacy systems. Inventory platforms must reconcile mainframe-era merchandise management with modern digital storefronts.
- Specialty Retailers:Narrow SKU assortments with deep category expertise requirements.
- Convenience Stores:High-velocity replenishment cycles with limited backroom storage.
- Discount Outlets:Price-sensitive procurement with basic functionality requirements.
Department Stores represent the largest aggregate contract value. E-commerce Platforms are climbing the fastest as digital-native retailers expand internationally.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent clusters in the United States, Germany, and India anchor regional deployment capabilities for retail inventory platforms. Cloud infrastructure density and data sovereignty regulations shape vendor prioritization across these markets.
United States
Omnichannel fulfillment networks drive demand for real-time inventory synchronization between digital storefronts and physical locations. FDA Section 204 traceability mandates for food retailers elevate compliance requirements for grocery chain deployments. Seattle and San Francisco Bay Area technology corridors host the densest concentration of cloud-native inventory platform engineering teams.
Germany
Automotive parts distribution and industrial retail formats require precision inventory tracking across complex supplier networks. GDPR data residency rules compel retailers to maintain consumer transaction data within EU sovereign cloud regions. The Rhine-Ruhr logistics corridor concentrates warehouse management system implementations serving cross-border e-commerce fulfillment.
China
Live-streaming commerce and same-day delivery expectations compress inventory visibility requirements to sub-second latency. GB standards for data security and MIIT cloud service regulations govern cross-border data flows for multinational retail chains. Yangtze River Delta manufacturing clusters integrate RFID-enabled inventory tracking directly into export-oriented production workflows.
India
Organized retail penetration in tier-two cities creates greenfield demand for mobile-first inventory systems. BIS certification requirements for point-of-sale hardware influence integration architecture decisions. Bengaluru and Hyderabad technology hubs supply data engineering talent for pipeline development connecting POS, warehouse, and supplier EDI feeds.
United Kingdom
Post-Brexit customs complexity increases inventory tracking granularity requirements for cross-channel retail operations. ECHA REACH compliance for chemical traceability extends into textile and electronics retail supply chains. London's financial technology corridor drives demand forecasting innovation for subscription replenishment business models.
Global Retail Inventory Management Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment architecture and functional module categories. Enterprise software giants leverage existing ERP relationships to bundle inventory capabilities, while supply chain specialists defend warehouse-centric optimization positions. Three archetypes dominate: horizontal platform extenders, vertical supply chain execution specialists, and cloud-native challenger suites. Consolidation activity concentrates in API middleware and computer vision shelf-monitoring acquisitions. Geographic expansion into India and Southeast Asia represents the primary growth vector for scale-driven players.
Among diversified technology conglomerates, Oracle Corporation and SAP SE occupy positions spanning database infrastructure through application layers. Manhattan Associates exemplifies the vertical specialist archetype with concentrated supply chain execution expertise. Zoho Corporation represents the emerging cloud-native tier with mobile-first architectural patterns. These anchors illustrate the competitive tension between breadth and depth in platform selection decisions.
| Leading Market Players |
|---|
| Oracle Corporation |
| SAP SE |
| Manhattan Associates |
| IBM Corporation |
| Microsoft Corporation |
| Fishbowl |
| Zoho Corporation |
| Epicor Software Corporation |
| Lightspeed Commerce Inc. |
| Others |
Supply & Pricing Matrix
E-commerce platforms in China and the United States concentrate procurement authority for inventory management software, anchoring subscription-based SaaS pricing as the dominant commercial model across deployment tiers.
Pricing Analysis
Software vendors split bundled implementation services from unbundled platform licensing to accommodate mid-market budget constraints. Three-tier pricing structure across premium, standard, and economy levels reflects integration complexity and data residency certification requirements. Price differentiation hinges on GDPR compliance architecture and API throughput volume. Cost compression in standard-tier offerings is intensifying because cloud infrastructure commoditization erodes infrastructure margins. Discount outlets exhibit highest price sensitivity, while e-commerce platforms prioritize latency performance over licensing cost.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing and China's MIIT cloud service regulations are reshaping sourcing patterns for hardware-dependent inventory tracking deployments. Software engineering talent concentrates in the United States, Germany, and India. Development pipelines draw from open-source machine learning frameworks, proprietary database kernels, and RFID sensor hardware. Single-source vulnerability in EU sovereign cloud infrastructure creates compliance execution risk for vendors serving German retailers. Distribution runs through direct enterprise sales teams and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as omnichannel fulfillment demands push retailers toward premium real-time synchronization specifications over basic stock-tracking functionality.
For Market Incumbents: Deploy autonomous database architecture as a defensive moat against cloud-native challengers. Deepen upstream control over edge-AI inference chip supply to secure hardware-software integration advantages. Manhattan Associates and Oracle Corporation face substitution threat from API-first platforms; counter by accelerating computer vision shelf-monitoring acquisitions. For New Entrants and Emerging Players: Enter via mobile-first deployment targeting India's tier-two organized retail penetration. White-space concentrates in FDA Section 204 traceability modules for grocery chains and REACH-compliant textile inventory systems. Go-to-market angle: pre-configured compliance templates reducing six-figure implementation minimums for mid-market retailers. For Investors and Strategic Acquirers: ERP conglomerates are the most active acquirer in this space, pursuing API middleware and computer vision specialists to fill architecture gaps. Long-term viability favors vendors with dual-codebase capability for EU AI Act algorithmic accountability without fragmenting core engineering. Acquisition target archetype: warehouse-centric optimization pure-plays with German logistics hub penetration. Signal to watch: BIS certification acceleration in India triggering greenfield installation waves.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Oracle's autonomous database architecture absorbs compliance-heavy multinational retail chain deployments. |
| Acquisition of Specialist Firm | Computer vision shelf-monitoring targets compress operating cost structures for twenty-four-hour grocery operations. |
| Geographic Expansion | India's tier-two city organized retail penetration offers greenfield installations ahead of incumbent arrival. |
| Strategic Partnership | Energy-efficient data center partnerships satisfy CE marking requirements under the EU Green Deal. |
| Product Launch | FDA Section 204 traceability modules with blockchain-enabled provenance logging address grocery chain compliance mandates. |
Research Methodology
Multiple input streams — executive interviews with retail CIOs and supply chain directors, technical consultations with platform engineers and integration specialists, and validation sessions with channel partners — were reconciled against regulatory filings and hyperscaler capex disclosures. Primary fieldwork captured deployment architecture decisions across cloud, on-premise, and hybrid configurations. Secondary sources included SEC filings, EU AI Act implementation guidance, FDA Section 204 draft rules, and customs data on RFID hardware imports. Bottom-up SKU-level demand modeling and top-down retail IT spending analysis were triangulated to anchor volume estimates.
Historical revenue trajectories were cross-referenced against panel input from software procurement officers to project adoption curves across the analysis window. Segmentation dimensions modeled include deployment architecture, solution offering type, application use case, and customer tier by digital maturity. CAGRs were derived from elasticity-adjusted price-volume relationships and technology substitution rates. Industry-specific forecast inputs encompassed GDPR enforcement intensity and live-streaming commerce penetration in China.
Inputs from FDA draft rulemaking and EU AI Act technical standards consultations were available through the study window; gaps in MIIT cloud service regulation implementation timelines introduce uncertainty bands around China deployment forecasts. Forecasts reflect documented assumptions regarding RFID tag cost curves and data engineering talent supply elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market
Software & Services
Landing Page Creation Software Market
Software & Services
Business Productivity Software Market
Software & Services
Blogger Outreach Software Market
Software & Services
Global Recruiting Software Market
Software & Services
Global Survey Software Market
Software & Services
Bridge Analysis Software Market
Software & Services
Self-Storage Software Market
Software & Services
United Kingdom IT Services Market
Software & Services
Storyboarding Software Market
Software & Services
US Software Consulting Market
Software & Services
Global UIUX Software Market
Software & Services
Agile Application Life-Cycle Management Market
Software & Services
Global Application Development Software Market
Software & Services
Simulation Software Market
Software & Services
Compensation Software Market