
 Global Road Marking Materials Market | 2026-2036
Global Road Marking Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Road Marking Materials Market Analysis
European thermoplastic resin suppliers are restructuring production footprints to serve renewed infrastructure budgets across Germany, France, and Poland. SWARCO leverages its vertical manufacturing network from glass beads to finished marking systems across Alpine corridor projects. Ennis-Flint anchors North American supply through captive distribution to state DOT procurement channels. 3M competes on optical performance, sustaining premium positioning in reflective tape technologies for airport runways and critical highway segments.
Road marking materials comprise pigmented binders, reflective glass beads, and performance additives formulated for traffic-bearing surfaces, with thermoplastic compositions requiring heating to application temperatures while cold plastics cure through chemical reaction at ambient conditions. These materials provide delineation, lane guidance, and retroreflectivity for motorized and pedestrian traffic across paved infrastructure. Thermoplastics command the largest volume share among product types due to balance of durability and application speed on high-volume highways, while reflective technology segments capture disproportionate value through glass bead loading specifications and prism-based sheeting. Epoxy systems occupy specialized niches in airport applications where fuel resistance and load-bearing performance justify material cost premiums.
Regulatory frameworks including the US FHWA Manual on Uniform Traffic Control Devices, EU CE marking under construction product regulations, and China's GB/T standards administered by SAMR collectively dictate minimum retroreflectivity thresholds, color stability requirements, and environmental compliance for market access. These standards create product differentiation barriers where certified formulations qualify for public procurement while uncertified alternatives face exclusion. Stakeholders must monitor evolving durability testing protocols and low-VOC formulation mandates as procurement specifications shift toward lifecycle performance metrics rather than first-cost evaluation.
Market Dynamics
Municipal procurement departments are rewriting specifications to prioritize lifecycle cost over first-install pricing, compressing margins for commodity thermoplastic suppliers while rewarding certified high-durability formulations. This specification pivot is consolidating contract awards toward vertically integrated manufacturers with captive glass bead supply and in-house testing laboratories.
Growth Catalysts
- MIIT GB Standards:China's updated reflective marking requirements are accelerating material substitution cycles as provincial highway bureaus replace non-compliant inventory ahead of enforcement deadlines.
- Epoxy airport systems:Fuel-resistant formulations for runways and taxiways are capturing expanded maintenance budgets at hub airports facing heavier cargo aircraft loads.
- India NHAI corridor upgrades:The National Highways Authority's multi-lane expansion program is generating concentrated demand for high-performance thermoplastic systems with extended retroreflectivity warranties.
Market Restraints
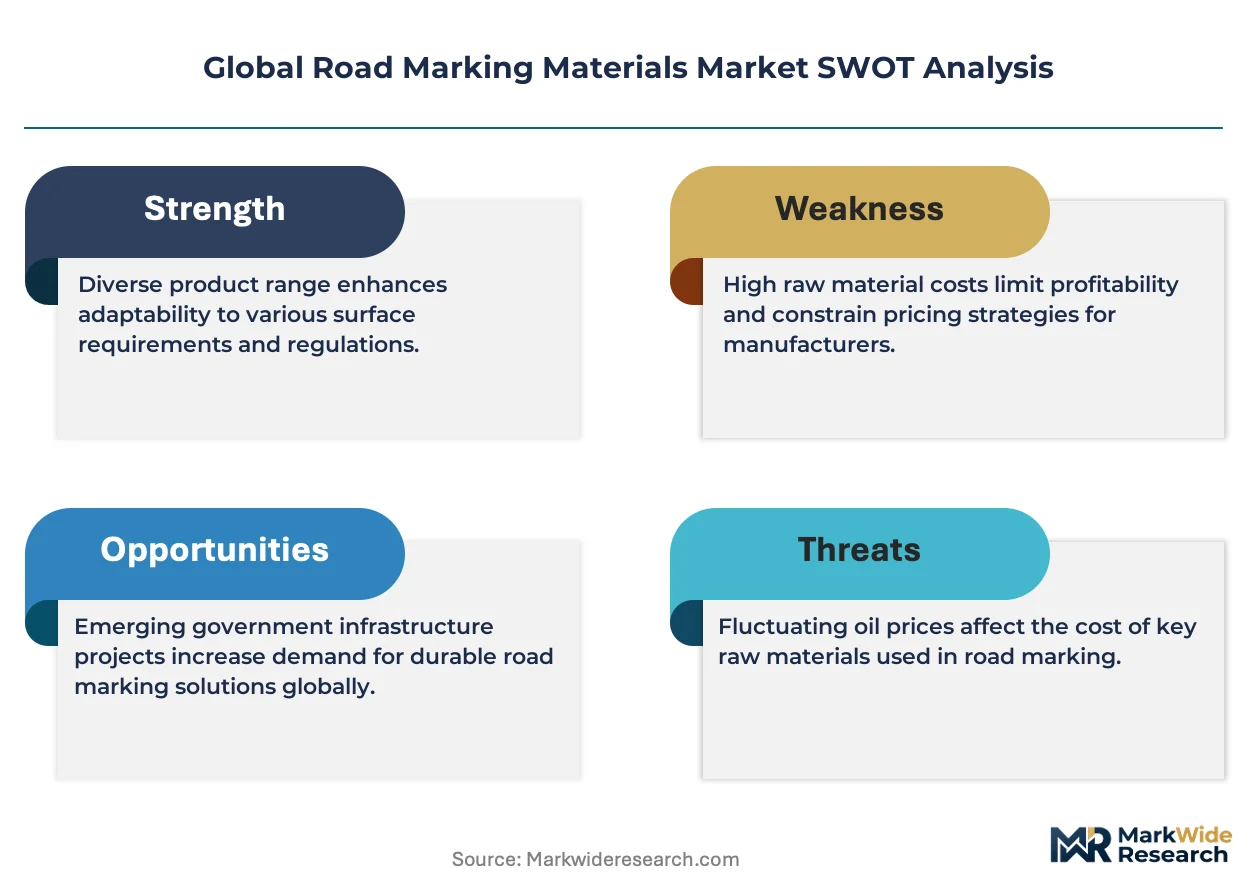
- Petroleum resin volatility:Thermoplastic binder costs fluctuate with naphtha and C5 feedstock pricing, compressing margins for applicators locked into fixed-price municipal contracts.
- Glass bead supply concentration:Reflective media production clusters in select industrial zones, exposing marking contractors to freight cost spikes and import duty uncertainties.
- CE marking friction:EU construction product regulations require third-party durability testing that adds six-to-nine month certification timelines, excluding rapid-turnover importers from public tenders.
Strategic Opportunities
- Poland infrastructure budgets:EU cohesion fund allocations for Trans-European Transport Network corridors are expanding procurement volumes for cold plastic systems in secondary road networks.
- Photoluminescent pedestrian markings:Unpowered glow-in-dark formulations for cycle paths and crosswalks are penetrating urban smart-city pilot programs seeking grid-independent safety infrastructure.
- Waterborne acrylics:Low-VOC formulations are capturing specification share in California and Northeast US markets where state environmental agencies have advanced application bans on solvent-based products.
Industry Challenges
- Retroreflectivity testing capacity:Mobile measurement unit operators face certification backlogs at accredited laboratories, delaying warranty validation and payment release on completed projects.
- Applicator skill gaps:Thermoplastic screed and spray equipment requires calibrated temperature control that experienced crews command premium wages to execute, constraining project throughput during peak season windows.
- Legacy inventory stranding:State DOT warehouses hold pre-2018 formulations that fail updated minimum retroreflectivity thresholds, forcing write-downs as specifications tighten.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Road Marking Materials Market |
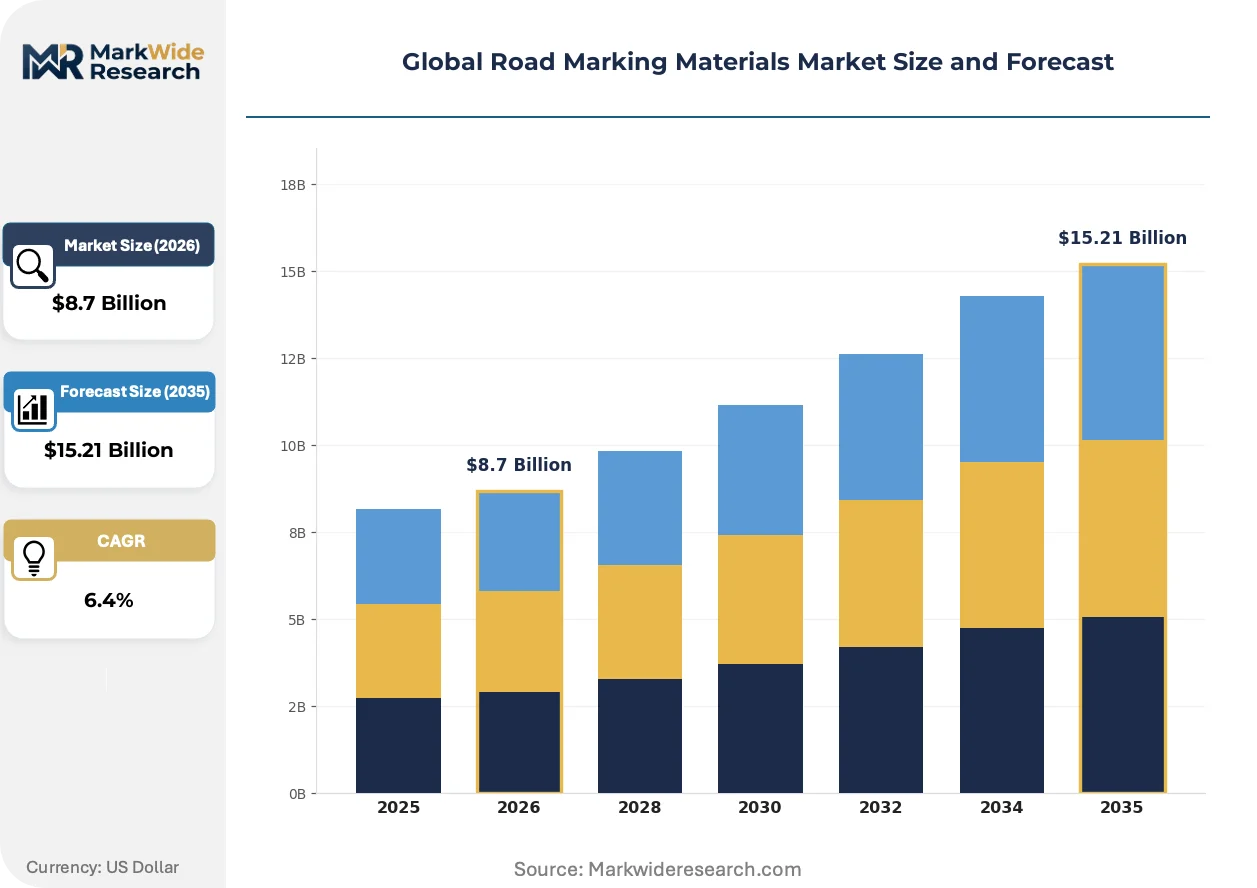
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paints, Thermoplastics, Tapes, Epoxy Application: Highways, Parking Lots, Airports, Streets End User: Government, Construction Companies, Infrastructure Developers, OEMs Technology: Reflective, Non-reflective, Cold Plastic, Warm Plastic |
| Companies Covered | SWARCO, Ennis-Flint, The Sherwin-Williams Company, Asian Paints, Dow Inc., 3M, Geveko Markings, Aximum, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Road Marking Materials Market Emerging Trajectories
Digital specification tools and connected application equipment are compressing the feedback loop between field performance data and formulation adjustments. Material suppliers are embedding sensors and traceability codes to demonstrate compliance across extended warranty periods.
Automated pavement marking vehicles equipped with GPS-guided spray systems and real-time bead dispensing controls are automating lane striping precision on high-volume highway contracts. State DOT maintenance crews in Texas and Florida are deploying these platforms for overnight resurfacing projects where traffic closure windows are measured in hours. The technology is automating quality consistency that previously required decades of operator experience, enabling younger crews to meet specification tolerances.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are pressuring manufacturers to reformulate solvent-based cold plastics around non-fluorinated resin systems. Formulation labs in Germany and the Netherlands are accelerating alkyd and acrylic alternatives through accelerated weathering protocols. Airport operators in France and Benelux markets are piloting the first certified fluorine-free epoxy systems for runway edge markings.
Lifecycle service contracts are displacing transactional material sales as municipal buyers seek guaranteed retroreflectivity performance over five-to-seven year terms. Contractors in the UK and Scandinavia are bundling installation, periodic measurement, and refresh applications into single-source agreements. This procurement evolution is most visible in Sweden and Denmark where transport agencies have eliminated unit-price bidding for marking materials entirely.
Global Road Marking Materials Market Segmentation
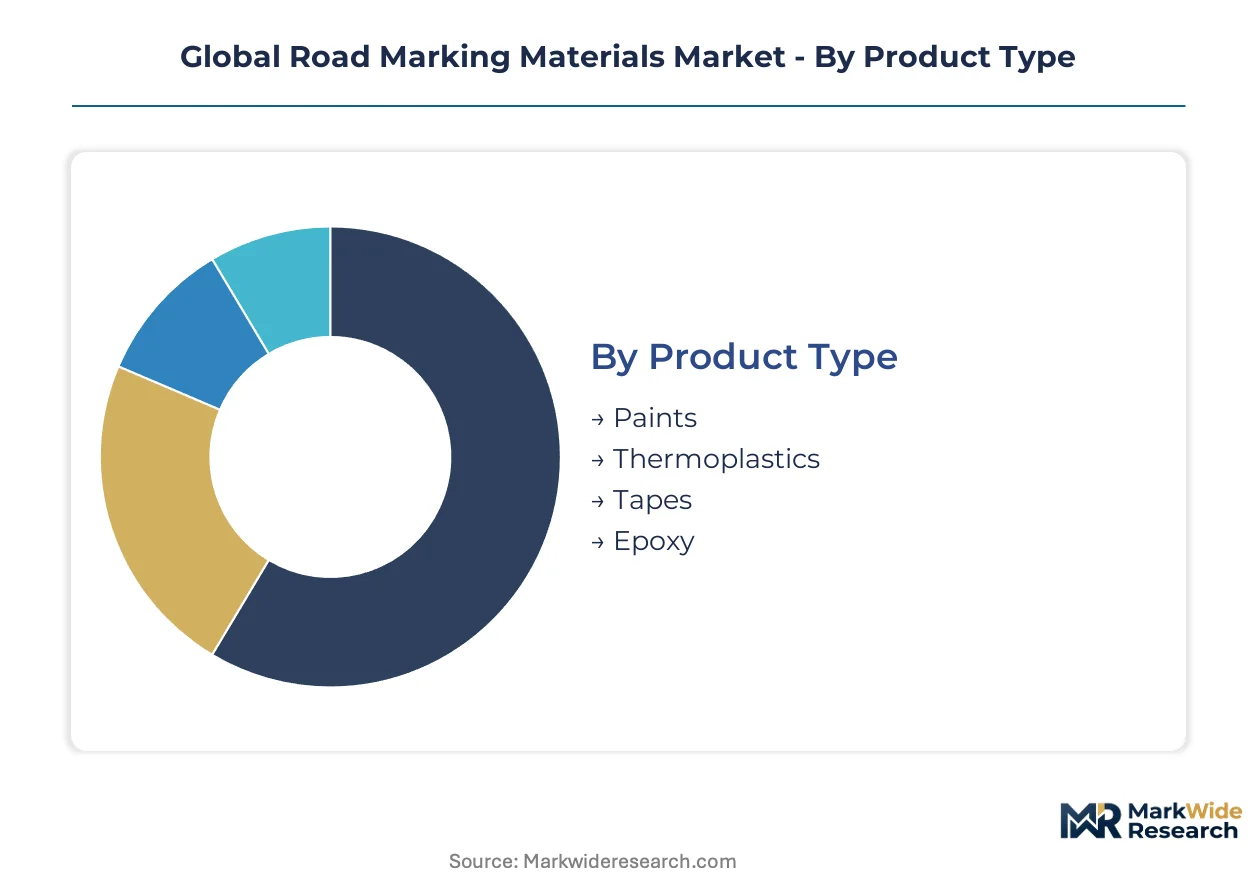
Road marking materials fragment across multiple technical and commercial dimensions, with product chemistry and application environment determining specification requirements. Procurement patterns diverge sharply between high-volume highway contracts and specialized airport installations, creating distinct competitive arenas within the same material categories.
Product Type:
Thermoplastics command volume leadership through highway deployment economics, while premium-priced alternatives capture value in performance-critical niches.
- Thermoplastics:Petroleum-derived binders heated to application temperatures form the dominant highway marking medium across North America and Europe. China's provincial highway bureaus are accelerating substitution toward compliant formulations under MIIT GB standards, compressing demand for legacy inventory.
- Paints:Solvent-borne and waterborne acrylic formulations serve lower-traffic municipal streets and parking infrastructure where durability requirements moderate. California and Northeast US markets are shifting specification share toward low-VOC waterborne systems under state environmental agency mandates.
- Tapes:Preformed reflective sheeting delivers precision application for temporary traffic control and airport runway edge delineation where thermoplastic installation is impractical.
- Epoxy:Fuel-resistant two-part systems occupy runway and taxiway applications at hub airports facing heavier cargo aircraft loads, justifying material cost premiums through extended service intervals.
Mature deployment sits with thermoplastic systems on established highway networks. Newer deployment is concentrated in epoxy formulations for airport infrastructure upgrades.
Application:
Traffic intensity and closure window constraints segment demand between continuous-flow corridors and intermittent-use surfaces.
- Highways:Multi-lane arterial routes require thermoplastic systems with extended retroreflectivity warranties under lifecycle procurement models. India's NHAI corridor upgrades are generating concentrated demand for high-performance marking systems across expanding national highway networks.
- Streets:Urban arterial and collector roads balance visibility requirements against maintenance budget constraints, with European municipalities piloting photoluminescent pedestrian markings in smart-city programs.
- Airports:Runway and taxiway markings demand fuel-resistant epoxy formulations certified to FAA and ICAO friction and retroreflectivity standards.
- Parking Lots:Commercial and municipal parking structures prioritize first-cost economics, accepting shorter service intervals in exchange for lower material and installation expenditure.
Specification complexity peaks in airport applications. Volume concentration centers on highway networks.
End User:
Procurement sophistication varies across public agency, private contractor, and integrated developer channels.
- Government:State DOTs and municipal highway departments are rewriting specifications to prioritize lifecycle cost metrics, consolidating contract awards toward vertically integrated manufacturers with captive testing capabilities.
- Construction Companies:General and specialty contractors bid on installation-only or material-plus-labor contracts, with margin pressure intensifying under fixed-price municipal agreements.
- Infrastructure Developers:Build-operate-transfer concessionaires in India and Southeast Asia bundle marking systems into long-term highway maintenance obligations.
- OEMs:Road marking equipment manufacturers specify compatible material formulations for automated application systems, influencing downstream material selection through equipment-software integration.
Lifecycle service contracting is displacing transactional sales in government channels. OEM specification influence is expanding through connected application equipment deployment.
Technology:
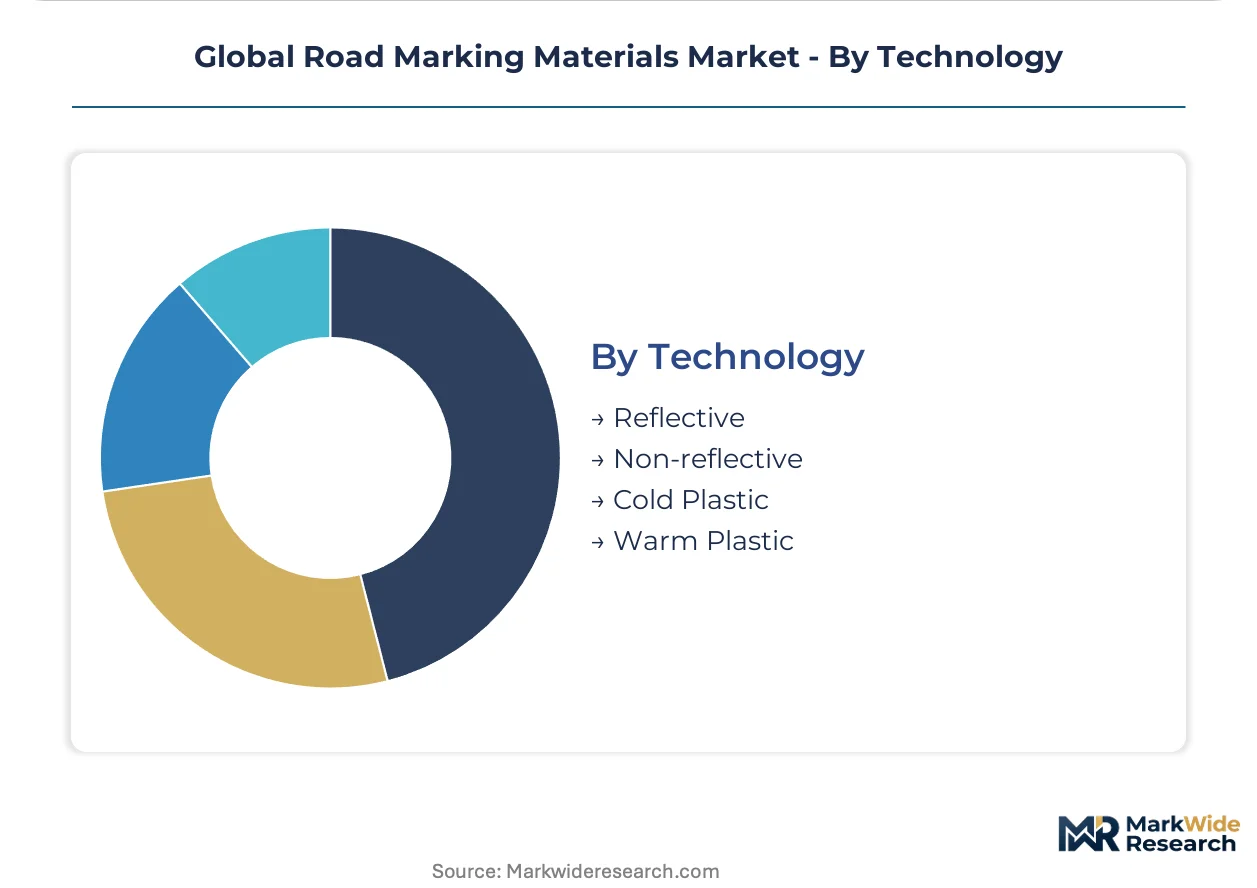
Retroreflectivity mechanism and application temperature define technical differentiation within material categories.
- Reflective:Glass bead and microprism technologies deliver nighttime visibility through retroreflection, with bead loading specifications and embedment depth determining performance durability. EU F-Gas Regulation pressures are accelerating fluorine-free reformulation in cold plastic systems.
- Non-reflective:Unbeaded formulations serve parking lots, warehouse floors, and temporary traffic control where nighttime visibility requirements are minimal.
- Cold Plastic:Two-part chemically curing systems apply at ambient temperatures, penetrating EU secondary road networks through Poland's Trans-European Transport Network corridor upgrades.
- Warm Plastic:Reduced-temperature thermoplastic variants bridge application economics between conventional hot-applied systems and cold plastic alternatives.
Reflective technology captures disproportionate value through specification premiums. Cold plastic systems are climbing the fastest in European cohesion fund procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum resin feedstock clusters in the US Gulf Coast and Rotterdam-Antwerp corridor anchor thermoplastic supply chains serving highway marking demand across three continents.
United States
State DOTs in Texas and Florida deploy automated pavement marking vehicles for overnight resurfacing projects with traffic closure windows measured in hours. FAA regulations governing runway friction and retroreflectivity standards drive epoxy formulation demand at hub airports facing heavier cargo aircraft loads. The Gulf Coast petrochemical corridor supplies C5 hydrocarbon resins to domestic thermoplastic compounders.
China
Provincial highway bureaus are accelerating material substitution cycles under MIIT GB standards for reflective road markings ahead of enforcement deadlines. SAMR-administered GB/T standards dictate minimum retroreflectivity thresholds and color stability requirements for market access. The Yangtze River Delta hosts glass bead production clusters supplying reflective media to domestic marking system manufacturers.
Germany
EU F-Gas Regulation restrictions are pressuring manufacturers to reformulate solvent-based cold plastics around non-fluorinated resin systems. CE marking under construction product regulations requires third-party durability testing that adds six-to-nine month certification timelines. Formulation laboratories in the Rhine-Ruhr industrial region are accelerating alkyd and acrylic alternatives through accelerated weathering protocols.
India
The National Highways Authority's multi-lane expansion program generates concentrated demand for high-performance thermoplastic systems with extended retroreflectivity warranties. BIS standards for road marking materials create product differentiation barriers where certified formulations qualify for public procurement. Build-operate-transfer concessionaires in Maharashtra and Gujarat bundle marking systems into long-term highway maintenance obligations.
Poland
EU cohesion fund allocations for Trans-European Transport Network corridors expand procurement volumes for cold plastic systems in secondary road networks. The country's national infrastructure regulator enforces durability testing protocols aligned with EU construction product regulations. Industrial zones around Katowice and Kraków host applicator fleets serving cross-border corridor upgrades linking to Czech and Slovak networks.
Global Road Marking Materials Market Vendor Landscape
Global majors compete with regional champions across formulation certification and captive raw material access. The vendor base organizes around three tiers: integrated resin-to-bead manufacturers, specialized applicators with testing laboratories, and commodity compounders serving price-sensitive municipal contracts. Two strategic archetypes dominate competitive positioning: vertically integrated players controlling glass bead supply chains, and technology licensors monetizing proprietary binder formulations. Capacity expansion and strategic partnerships represent the dominant competitive moves, with manufacturers securing captive distribution through state DOT procurement channels.
Within the integrated manufacturing tier, SWARCO and Ennis-Flint exemplify contrasting geographic anchoring strategies. SWARCO occupies a position spanning Alpine corridor projects through vertical manufacturing networks from glass beads to finished marking systems. Ennis-Flint anchors North American supply through captive distribution arrangements. Among technology-focused players, 3M represents premium-tier positioning in reflective tape technologies for airport runways and critical highway segments.
| Leading Market Players |
|---|
| SWARCO |
| Ennis-Flint |
| The Sherwin-Williams Company |
| Asian Paints |
| Dow Inc. |
| 3M |
| Geveko Markings |
| Aximum |
| PPG Industries |
| Others |
Supply Flow & Price Mechanics
Captive glass bead production anchors competitive positioning for integrated manufacturers serving municipal procurement channels. SWARCO and Ennis-Flint leverage backward integration into reflective media supply to command premium positioning in lifecycle service contracts, while commodity compounders without upstream control face margin compression under fixed-price state DOT agreements.
Pricing Analysis
Five-to-seven year retroreflectivity warranties bundled with installation and refresh cycles separate lifecycle service contracts from transactional material sales. Three-tier pricing structure across premium certified formulations, standard compliant grades, and economy pre-2018 legacy inventory reflects certification tier and captive testing capability. Cost compression in commodity thermoplastics intensifies as petroleum resin volatility squeezes applicators locked into municipal fixed-price agreements. State DOT procurement departments exhibit lowest price sensitivity when specifying airport epoxy systems, while parking lot developers drive hardest first-cost negotiations.
Supply Chain Analysis
Petroleum-derived binder supply rests on C5 hydrocarbon resin production clusters in the US Gulf Coast and Rotterdam-Antwerp corridor. Glass bead manufacturing concentrates in China's Yangtze River Delta and select European industrial zones, creating freight cost exposure for marking contractors. Raw material dependencies span naphtha feedstocks, specialty titanium dioxide pigments, and soda-lime glass cullet. Single-source vulnerability in reflective media supply chains amplifies margin risk during import duty fluctuations. Distribution runs through state DOT procurement channels and municipal highway department tender systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vertically integrated manufacturers as CE marking friction and lifecycle procurement specifications force commodity compounders toward exit. Regulatory compliance timelines and captive testing requirements create structural barriers that reward scale and punish fragmentation.
For Market Incumbents: Lock in state DOT procurement channel control through captive distribution arrangements and in-house retroreflectivity testing laboratories. Deepen backward integration into glass bead supply chains to insulate margin structures from freight cost volatility. Defend against waterborne acrylic substitution by accelerating fluorine-free cold plastic certification under EU F-Gas Regulation timelines.
For New Entrants and Emerging Players: Capture specification share in Poland's Trans-European Transport Network corridor upgrades where EU cohesion fund procurement favors cold plastic systems for secondary roads. Penetrate India's NHAI corridor expansion through build-operate-transfer concessionaire relationships bundling marking systems into long-term maintenance obligations. Lead with photoluminescent pedestrian marking pilots in European smart-city programs seeking grid-independent safety infrastructure.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated resin-to-bead manufacturers seeking geographic footprint expansion. Long-term viability favors targets with captive glass bead supply and certified formulation libraries spanning thermoplastic, epoxy, and waterborne acrylic chemistries. Watch for inflection in state DOT specification adoption of automated pavement marking vehicle compatibility requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Bead Supply | Captive reflective media production insulates margin structures from import duty volatility and freight cost spikes. |
| CE Marking Certification Investment | Third-party durability testing capabilities unlock six-to-nine month faster access to EU public tender participation. |
| Automated Application Equipment Partnership | GPS-guided spray system compatibility influences downstream material selection through OEM software integration. |
| Fluorine-Free Cold Plastic Reformulation | EU F-Gas Regulation compliance enables continued market access for solvent-based systems in secondary road networks. |
| Lifecycle Service Contract Expansion | Five-to-seven year retroreflectivity warranties displace transactional sales in UK and Scandinavian government procurement channels. |
Methodological Framework
Trade association publications, customs and import-export databases, and SEC regulatory filings formed the secondary backbone of data collection. Primary interviews with state DOT procurement officers, thermoplastic compounder plant managers, glass bead manufacturing technical directors, and municipal highway department maintenance supervisors validated demand assumptions and specification trends. Bottom-up project pipeline analysis across India NHAI corridors and EU cohesion fund allocations triangulated against top-down petrochemical feedstock consumption models.
Historical trendline analysis of thermoplastic resin pricing and retroreflectivity warranty penetration informed projection frameworks across the modeling period. Segmentation dimensions modeled include product chemistry, application environment, retroreflectivity technology, and regional regulatory cluster. CAGRs derived from volume-weighted average of country-level highway construction expenditure forecasts and material substitution cycle assumptions. Industry-specific inputs incorporated MIIT GB standard enforcement timelines and FAA epoxy certification renewal patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petroleum resin price volatility and municipal budget cycle fluctuations. Forecasts reflect documented assumptions regarding specification pivot timing and automated application equipment adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Antiozonant Market
Chemicals & Materials
Hexyl Acetate Market
Chemicals & Materials
Marine Lubricants Market
Chemicals & Materials
Tinplate Market
Chemicals & Materials
Global Imaging Chemicals Market
Chemicals & Materials
Iodoacetonitrile Market
Chemicals & Materials
Emulsion PVC Market
Chemicals & Materials
Polyethylene Terephthalate (PET) Resin Market
Chemicals & Materials
Europe Calcium Chloride Market
Chemicals & Materials
Laminated Steel Market
Chemicals & Materials
India PVC Pipes Market
Chemicals & Materials
Viscosity Reducing Agents Market
Chemicals & Materials
South America Engineering Plastics Market
Chemicals & Materials
Soft Ferrite Core Market
Chemicals & Materials
Food Grade Paraffin Market
Chemicals & Materials
Global High Performance Polymers Market