
 Alkyl Polyglucosides Market | 2026-2036
Alkyl Polyglucosides Market Size, Share, and Industry Trends Forecast 2026-2036
Alkyl Polyglucosides Market Analysis
China is reconfiguring alkyl polyglucoside capacity through state-backed green chemistry investments. BASF SE leverages its Ludwigshafen integrated site to sustain European supply security for cosmetic-grade output. Clariant AG anchors specialty alkyl polyglucoside production through its industrial cleaning focus. Galaxy Surfactants Ltd. competes on cost structure across Asian personal care markets.
Alkyl polyglucosides are non-ionic surfactants synthesized from fatty alcohols and glucose via acid-catalyzed glycosidation, exhibiting low toxicity and rapid biodegradability for detergent and cosmetic applications. The liquid product type dominates formulation flexibility for household cleaners, while powder grades concentrate margin pools in agrochemical dispersants. Cosmetic-grade alkyl polyglucosides command structural premiums as personal care brands reformulate around sulfate-free claims, whereas technical-grade supply matures in industrial degreaser channels.
REACH registration requirements in Europe shape surfactant purity standards and bio-based content thresholds for market access. China's GB standards and NMPA cosmetic ingredient filings impose parallel compliance burdens on imported alkyl polyglucosides. EPA Safer Choice certification in the United States steers institutional procurement toward verified bio-based surfactants. Stakeholders must monitor regulatory divergence between cosmetic-grade and technical-grade specifications as classification rules tighten across jurisdictions.
Market Dynamics
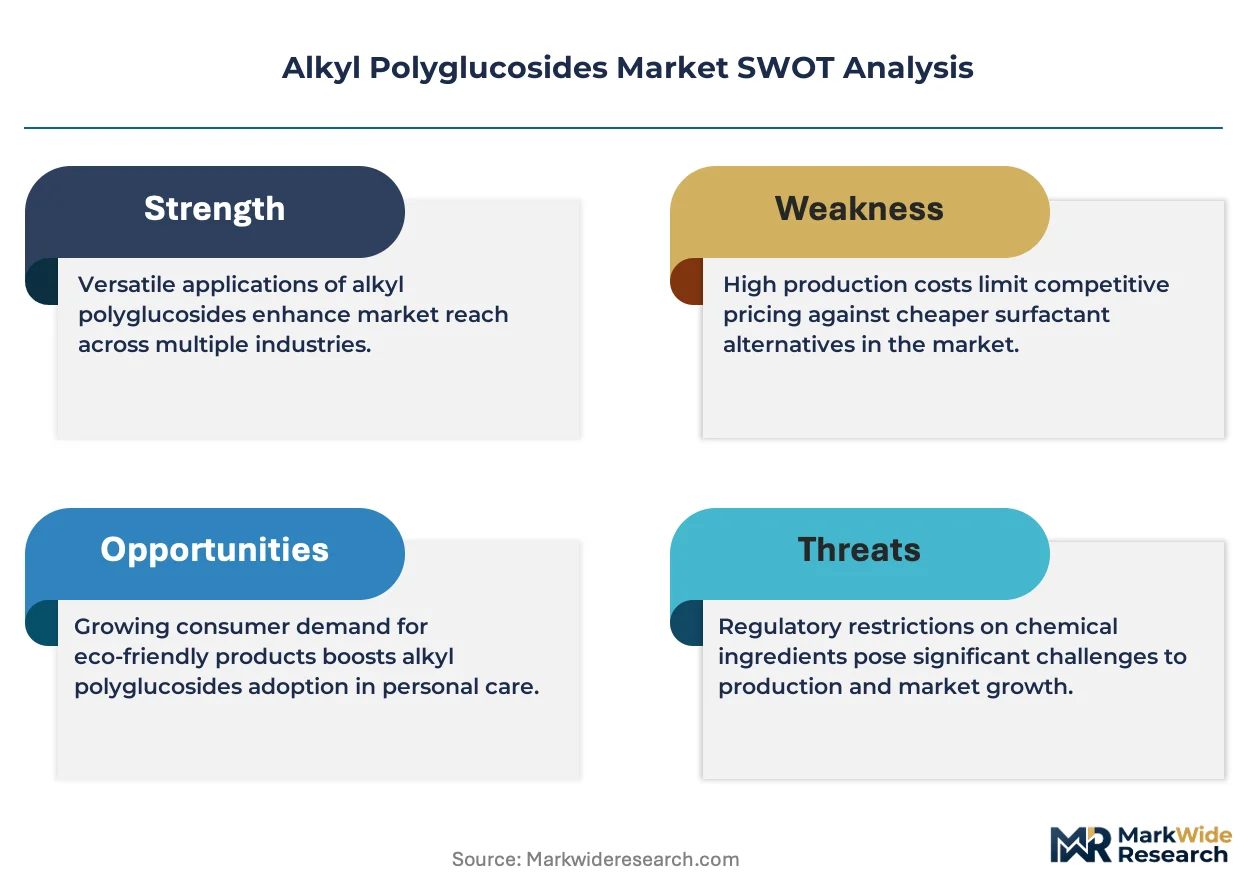
REACH compliance is forcing sulfate-free reformulations across European personal care, redirecting procurement toward bio-based surfactants with verified biodegradability credentials.
Growth Catalysts
- EU Green Deal mandates:Industrial cleaning operators in Germany must replace petrochemical degreasers with bio-based alternatives, accelerating alkyl polyglucoside offtake in metalworking and food processing facilities.
- Sulfate-free cosmetics:Personal care brands are eliminating sodium lauryl sulfate from shampoos and body washes, creating formulation demand for mild, glucose-derived surfactants.
- EPA Safer Choice certification:Institutional procurement in the United States now requires verified bio-based surfactants for federal and municipal cleaning contracts.
Market Restraints
- Fatty alcohol cost volatility:Palm kernel and coconut oil feedstock prices swing with tropical weather patterns and Indonesian export policies, compressing margin stability for producers.
- Technical-grade purity ceilings:Industrial degreaser applications face performance limits against petroleum-derived solvents in heavy-soil environments.
- REACH registration burdens:Small and mid-sized importers struggle with the cost and timeline of full substance dossiers for European market access.
Strategic Opportunities
- Agrochemical dispersants:Powder-grade alkyl polyglucosides penetrate crop protection formulations as glyphosate adjuvant replacements.
- China's dual carbon goals:State-backed green chemistry investments are expanding domestic capacity for export-competitive cosmetic-grade output.
- E-commerce ingredient platforms:Direct procurement channels connect mid-sized personal care brands with certified bio-based surfactant suppliers.
Industry Challenges
- Cosmetic-grade certification timelines:NMPA filings in China and REACH dossier updates in Europe extend product launch cycles by 18-24 months.
- Acid-catalyzed glycosidation expertise:Specialized process engineering talent for high-purity glucose esterification remains concentrated in Ludwigshafen and Mumbai chemical clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkyl Polyglucosides Market |
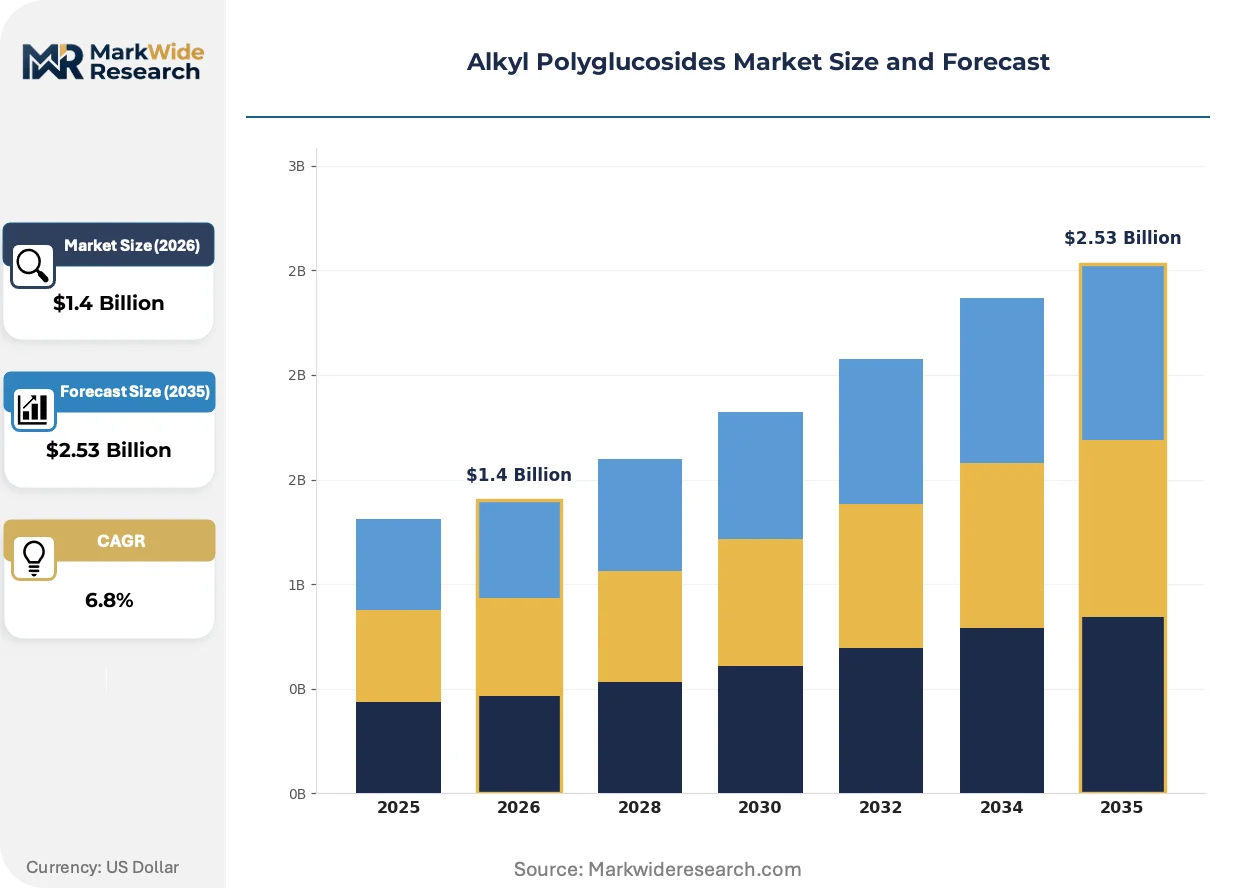
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Paste Application: Household Cleaners, Personal Care, Industrial Cleaning, Agrochemicals Chemical Grade: Food Grade, Cosmetic Grade, Technical Grade, Pharmaceutical Grade End User: Consumer Goods, Food & Beverage, Healthcare, Agriculture |
| Companies Covered | BASF SE, Clariant AG, Croda International PLC, Dow Inc., Kao Corporation, Galaxy Surfactants Ltd., SEPPIC, Fenchem, Shanghai Fine Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkyl Polyglucosides Market Emerging Trajectories
Digital formulation platforms are compressing R&D cycles for surfactant blends, while regulatory data transparency tools reshape how buyers verify bio-based claims across supply chains.
Enzymatic glycosidation is virtualizing traditional acid-catalyzed production routes for cosmetic-grade alkyl polyglucosides. Specialty chemical producers in Germany and India are piloting lipase-mediated synthesis to reduce energy intensity and color formation. This biotechnology convergence is virtualizing the cost structure for premium-grade output, enabling price parity with petroleum-derived alternatives in sulfate-free personal care.
REACH authorization requirements are tightening purity thresholds for surfactants used in leave-on cosmetic products. ECHA's 2024 updated guidance on non-ionic surfactant classifications demands enhanced biodegradability documentation for C8-C14 chain lengths. Cosmetic-grade suppliers are responding with carbon-14 testing investments to verify bio-based content claims for European brand owners.
Brand procurement teams now require blockchain-traceable feedstock documentation from fatty alcohol suppliers. Personal care manufacturers in France and Germany are disintermediating traders to secure direct partnerships with RSPO-certified palm kernel oil processors. This verification-driven purchasing behavior concentrates supplier relationships with integrated producers who control glucose and fatty alcohol inputs.
Alkyl Polyglucosides Market Segmentation
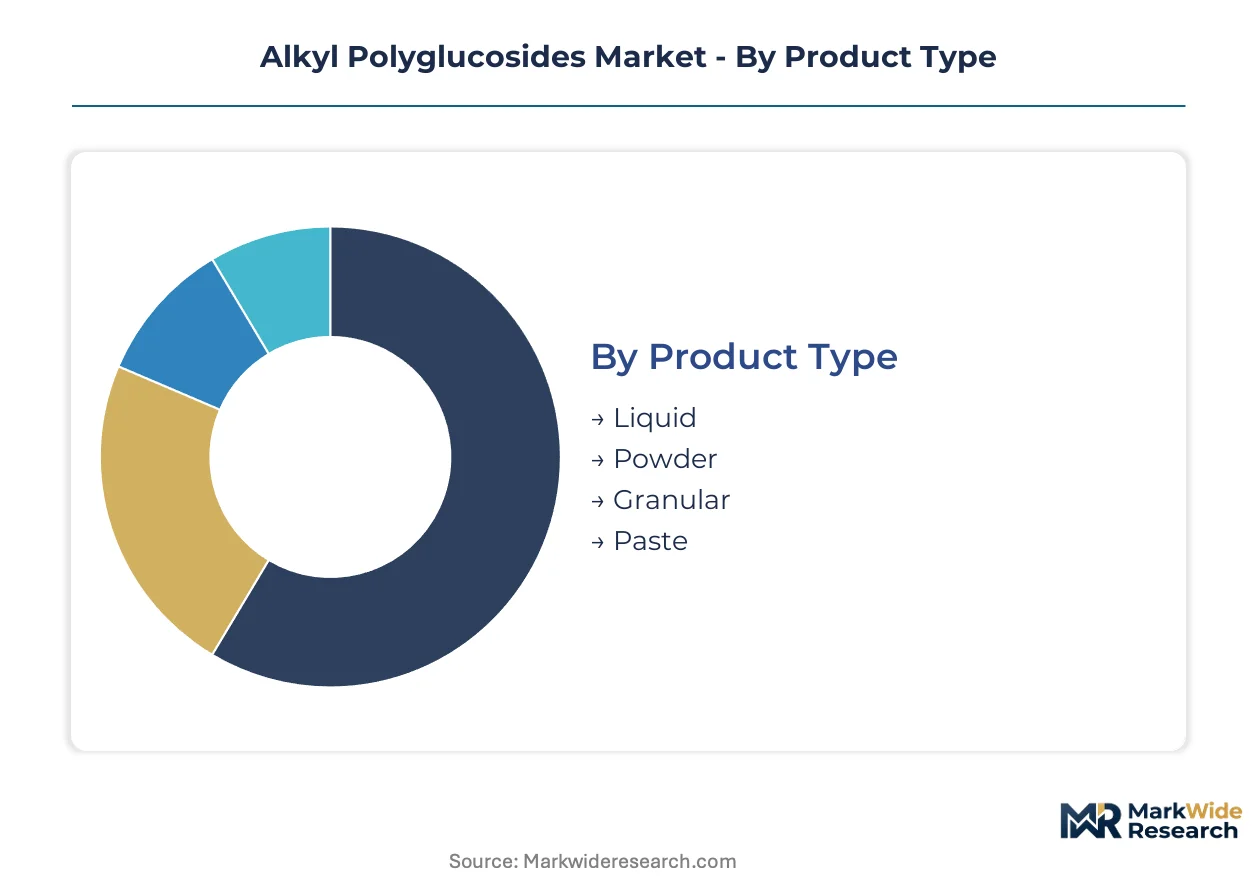
Alkyl polyglucoside manufacturers configure production assets around viscosity requirements and dissolution kinetics that vary sharply across end-use formulations. Segmentation discipline separates commodity liquid volumes from specialty powder margins while navigating divergent purity standards between cosmetic and industrial channels.
Product Type:
After-sales service intensity escalates with formulation complexity, as liquid grades demand technical support for pH stability while powder grades require dispersion troubleshooting in agrochemical applications.
- Liquid:Low-viscosity aqueous solutions with 50-70% active content enable direct incorporation into spray cleaners and shampoos without pre-dissolution. Demand concentrates in German household cleaner manufacturing where EU Green Deal mandates accelerate petrochemical replacement. REACH compliance documentation adds service burden for small-brand procurement teams.
- Powder:Spray-dried granules with 95%+ active content target agrochemical dispersants and concentrated detergent tablets. China's state-backed green chemistry investments are expanding domestic powder capacity for export-competitive output. NMPA cosmetic filings impose parallel compliance burdens on imported powder grades.
- Granular:Free-flowing particles with controlled particle size distribution suit automated dosing systems in institutional cleaning equipment.
- Paste:High-viscosity semi-solids with 60-75% active content serve specialty personal care formulations requiring rheology modification.
Liquid holds the largest share; momentum sits with powder.
Application:
Cost tier separation runs deepest between mass-market household cleaners and premium personal care, where cosmetic-grade certification adds 40-60% to raw material costs.
- Household Cleaners:Multi-surface sprays and laundry detergents exploit rapid biodegradability and low aquatic toxicity for EPA Safer Choice certification. Institutional procurement in the United States now requires verified bio-based surfactants for federal contracts. Formulation flexibility favors liquid alkyl polyglucoside grades with broad pH compatibility.
- Personal Care:Sulfate-free shampoos and body washes leverage mildness profiles and glucose-derived origin claims for clean beauty positioning. European brands reformulate around sodium lauryl sulfate elimination under tightening REACH surfactant restrictions. Carbon-14 testing investments verify bio-based content for ECHA documentation.
- Industrial Cleaning:Metalworking degreasers and food processing equipment sanitizers replace petroleum solvents under EU Green Deal industrial mandates.
- Agrochemicals:Glyphosate adjuvant replacements and crop protection dispersants exploit powder-grade wetting properties.
Household cleaners dominate volume; personal care commands margin expansion.
Chemical Grade:
Customer type stratification separates commodity technical grades from certified cosmetic and food grades where documentation burden determines supplier relationships.
- Cosmetic Grade:Ultra-low residual alcohol and controlled color specifications meet leave-on product safety thresholds. ECHA's updated non-ionic surfactant classifications demand enhanced biodegradability documentation for C8-C14 chain lengths. Blockchain-traceable feedstock documentation now required by French and German brand procurement teams.
- Technical Grade:Standard purity specifications serve industrial degreasers and hard-surface cleaners where performance-cost ratio dominates selection. German metalworking facilities drive offtake under bio-based degreaser mandates. Performance limits against petroleum-derived solvents persist in heavy-soil environments.
- Food Grade:FDA and EFSA compliance for incidental food contact applications in processing equipment cleaning.
- Pharmaceutical Grade:USP and EP monograph compliance for excipient applications in topical drug formulations.
Technical grade anchors volume; cosmetic grade captures value expansion.
End User:
Supply concentration patterns diverge between consolidated consumer goods procurement and fragmented agricultural distribution channels.
- Consumer Goods:Integrated personal care and home care manufacturers leverage scale purchasing for liquid alkyl polyglucoside offtake. E-commerce ingredient platforms now connect mid-sized brands directly with certified bio-based surfactant suppliers. REACH registration costs disadvantage small importers in European sourcing.
- Agriculture:Crop protection formulators specify powder grades for adjuvant and dispersant functions in glyphosate alternatives. Chinese domestic capacity expansion targets export-competitive supply to Asian agrochemical manufacturers. Formulation expertise for alkyl polyglucoside-pesticide compatibility remains concentrated in Mumbai and Ludwigshafen clusters.
- Food & Beverage:Processing equipment cleaning applications under FDA and EFSA hygiene mandates.
- Healthcare:Topical antiseptic and wound cleansing formulations exploiting low-irritancy profiles.
Consumer goods holds the largest share; agriculture climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated chemical complexes in Germany, China, and India anchor alkyl polyglucoside supply chains, while REACH compliance and EPA Safer Choice certification reshape procurement patterns across consumer and industrial channels.
Germany
EU Green Deal mandates accelerate bio-based degreaser adoption in metalworking and food processing facilities. ECHA's updated non-ionic surfactant classifications demand enhanced biodegradability documentation for C8-C14 chain lengths. The Ludwigshafen chemical cluster sustains cosmetic-grade production through captive glucose and fatty alcohol integration.
United States
Institutional procurement for federal and municipal cleaning contracts now requires EPA Safer Choice-certified bio-based surfactants. FDA oversight of incidental food contact applications shapes technical-grade specifications for processing equipment sanitizers. Gulf Coast petrochemical corridors are repurposing assets toward renewable feedstock processing.
China
State-backed green chemistry investments under dual carbon goals expand domestic capacity for export-competitive cosmetic-grade output. NMPA cosmetic ingredient filings impose compliance burdens on imported alkyl polyglucosides. The Yangtze River Delta concentrates spray-dried powder production for agrochemical dispersant applications.
India
Cost-competitive personal care manufacturing drives liquid-grade offtake for sulfate-free shampoo exports to Southeast Asia and Africa. BIS standards for bio-based surfactants create quality benchmarks for domestic procurement. The Mumbai chemical cluster houses specialized acid-catalyzed glycosidation expertise for high-purity glucose esterification.
France
Clean beauty brand procurement teams require blockchain-traceable RSPO-certified palm kernel oil documentation. ANSM oversight of leave-on cosmetic products tightens purity thresholds for surfactant residuals. The Lyon-Paris corridor concentrates formulation R&D for premium personal care applications.
Alkyl Polyglucosides Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The alkyl polyglucosides market structures around three tiers: integrated petrochemical majors with captive feedstock control, mid-cap surfactant specialists with regional formulation expertise, and emerging Asian producers competing on cost structure. Strategic moves concentrate on enzymatic process licensing for cosmetic-grade purity and direct partnerships with RSPO-certified palm kernel oil processors to secure feedstock traceability.
Among European-headquartered integrated producers, BASF SE and Clariant AG exemplify the platform archetype through Ludwigshafen-based captive supply chains. Galaxy Surfactants Ltd. occupies a position within the Asia-Pacific cost-competitive tier, serving personal care export markets from Mumbai-area production assets. These three anchors span the geographic and strategic spectrum without overlapping segment positioning.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Croda International PLC |
| Dow Inc. |
| Kao Corporation |
| Galaxy Surfactants Ltd. |
| SEPPIC |
| Fenchem |
| Shanghai Fine Chemical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Ludwigshafen's captive glucose and fatty alcohol integration anchors European cosmetic-grade supply, concentrating margin capture with producers who control both feedstock streams and certification documentation. REACH registration costs and RSPO traceability requirements push small importers toward trader intermediation, while integrated majors defend premium positioning through direct brand partnerships.
Pricing Analysis
REACH dictates the pricing tier structure across European alkyl polyglucoside procurement, separating cosmetic-grade premiums from technical-grade commoditization. Three-tier pricing stratifies across pharmaceutical-grade, cosmetic-certified, and industrial technical levels, with carbon-14 bio-based verification and ECHA dossier completeness as primary differentiation drivers. Pricing pressure stems from Indonesian palm kernel oil export volatility compressing fatty alcohol margins. Mid-sized personal care brands exhibit highest price sensitivity due to REACH registration cost burdens, while multinational consumer goods manufacturers prioritize supply security over unit economics.
Supply Chain Analysis
Palm kernel oil and coconut fatty alcohol feedstocks draw from Southeast Asian plantation networks, with glucose sourcing anchored in Corn Belt agricultural processing and Yangtze River Delta starch refining. Supply chain risk centers on single-source vulnerability for RSPO-certified sustainable palm derivatives, where traceability documentation gaps disqualify non-compliant batches. Distribution runs through integrated chemical majors with direct brand procurement portals, supplemented by e-commerce ingredient platforms connecting mid-sized formulators with certified suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alkyl polyglucoside supply is consolidating around platform-economics logic where feedstock traceability and regulatory data interoperability determine supplier tier access. Blockchain-verified RSPO documentation and ECHA-compliant carbon-14 testing are becoming minimum viable credentials for cosmetic-grade procurement relationships.
For Market Incumbents: Harden Ludwigshafen and Mumbai production clusters against enzymatic glycosidation disruption by piloting lipase-mediated synthesis routes and locking long-term RSPO-certified palm kernel oil offtake agreements. Prioritize backward integration into glucose refining to insulate margin pools from agricultural commodity swings. Defend cosmetic-grade positioning through NMPA pre-registration investments that extend product launch moats against mid-cap competitors.
For New Entrants and Emerging Players: Agrochemical dispersant applications in China's Yangtze River Delta represent the most penetrable entry point, where powder-grade capacity expansion under state-backed green chemistry investments creates procurement gaps for export-competitive supply. Mid-sized European personal care brands seeking REACH-compliant sulfate-free alternatives offer secondary white-space, accessible through e-commerce ingredient platforms that bypass traditional distributor markups. Lead with carbon-14 bio-based verification bundled with technical formulation support.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across enzymatic glycosidation pilot facilities, reducing barrier thresholds for specialty-grade entrants while concentrating returns with incumbents who license process technology. Target acquisition profiles favor mid-cap surfactant specialists with captive fatty alcohol relationships and existing ECHA dossier infrastructure. Monitor NMPA cosmetic ingredient filing acceleration as inflection indicator for Chinese export competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Licensing | Lipase-mediated synthesis reduces energy intensity for cosmetic-grade purity in German and Indian pilot facilities. |
| RSPO Feedstock Integration | Direct partnerships with certified palm kernel oil processors secure blockchain-traceable documentation for French and German brand procurement. |
| NMPA Pre-Registration Investment | Early filing for cosmetic-grade alkyl polyglucosides extends product launch timelines against Chinese domestic competitors. |
| Powder Capacity Expansion | Spray-dried granule production targets agrochemical dispersant demand under EU glyphosate adjuvant replacement mandates. |
| E-Commerce Platform Partnership | Direct procurement channels connect mid-sized personal care brands with certified bio-based surfactant suppliers. |
Methodological Framework
The analysis maps liquid-grade household cleaner procurement, powder-grade agrochemical dispersant demand, cosmetic-grade personal care formulation, and technical-grade industrial degreaser applications, each validated through surfactant procurement managers, personal care brand formulators, agrochemical R&D directors, and industrial cleaning facility managers. Primary interview intelligence triangulates against customs and trade data, Cefic surfactant industry reports, SEC 10-K chemical segment disclosures, and ECHA registration dossier databases. Bottom-up volume builds from end-use application consumption rates cross-checked against top-down producer capacity assessments.
Forecast assumptions hold EU Green Deal mandate implementation timelines and EPA Safer Choice certification penetration rates as fixed boundary conditions across the projection horizon, while varying palm kernel oil price trajectories and enzymatic glycosidation technology diffusion rates as scenario inputs. Segmentation dimensions span product type viscosity specifications, chemical grade purity thresholds, and end-user industry procurement concentration. CAGRs derive from regression-weighted historical consumption patterns projected through surfactant substitution elasticity models for sulfate-free cosmetic reformulation.
Practitioners should monitor Indonesian palm kernel oil export policy shifts and ECHA non-ionic surfactant classification updates for early signals of margin compression or compliance burden revision. Cross-checking against Cefic bio-based surfactant production statistics and NMPA cosmetic ingredient filing velocity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Tetradecyl Chloride Market
Surfactants
Surfactant Cleansers and Adjuvants Market
Surfactants
Emulsifying Wax Market
Surfactants
Cationic Surfactants Market
Surfactants
Sulfate Free Body Wash Market
Surfactants
Sodium Lauroyl Glycinate Market
Surfactants
Global Demulsifiers Market
Surfactants
Amino Silicone Oil Market
Surfactants
Detergent Grade Zeolite Market
Surfactants
Polymer Surfactants Market
Surfactants
Trisiloxane Market
Surfactants
North America Non-Ionic Surfactants Market
Surfactants
Secondary Alkane Sulfonate Market
Surfactants
Emulsion Stabilizers Market
Surfactants
Global Calcium Sulfonate Market
Surfactants
Dispersant Market