
 Glass Testing Instruments Market | 2026-2036
Glass Testing Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Testing Instruments Market Analytics
Software-defined calibration and remote diagnostics is hardening into a standard service layer that equipment vendors bundle with hardware contracts. Instron leverages its global service network to lock in multi-year maintenance agreements across automotive glass labs. ZwickRoell sustains R&D intensity in optical testing modules that integrate with factory automation systems. Shimadzu Corporation anchors its position in Asia-Pacific through localized technical support centers and application-specific training programs.
Glass testing instruments measure optical, mechanical, and thermal properties of flat, container, and specialty glass using calibrated light sources, load frames, and temperature chambers operating to ISO 1288 and ASTM C1279 specifications. These devices verify compliance with strength, clarity, and thermal-shock thresholds before products enter construction, automotive, or consumer electronics supply chains. Spectrophotometers capture the largest margin pool in quality control workflows where color consistency commands premium pricing. Mechanical testing equipment leads volume in manufacturing applications as tempered and laminated glass specifications tighten. Optical coherence tomography represents the fastest-growing segment for defect detection in thin-film coated architectural panels.
The U.S. FDA regulates optical instruments used in medical glass packaging through device-quality standards, while EPA emissions rules affect thermal testing furnace designs. China's SAMR enforces GB standards for construction glass that mandate certified test reports from accredited laboratories. Japan's METI promotes JIS-compliant testing protocols for automotive glazing exports. Stakeholders must monitor how building-code harmonization between ISO and national standards reshapes instrument certification requirements and cross-border equipment procurement rules.
Market Dynamics
Software-defined calibration is compressing equipment replacement cycles as vendors bundle predictive maintenance with hardware contracts, forcing incumbents to restructure revenue models around recurring service streams rather than discrete instrument sales.
Growth Catalysts
- EU Green Deal emissions rules:Mandatory carbon reporting for construction materials accelerates replacement of thermal testing furnaces in Germany, France, and Italy.
- Automotive laminated glass specifications:Stricter penetration resistance standards in Germany, Japan, and the United States expand mechanical testing equipment procurement.
- Optical coherence tomography:Thin-film coated architectural panel manufacturers adopt this defect detection technology for sub-surface flaw identification.
Market Restraints
- Helium supply concentration:Mass spectrometer leak detection systems depend on helium sourced primarily from Qatar and the United States, creating input cost volatility.
- High-precision optical component fabrication:Spectrophotometer grating production concentrates among German and Japanese specialty suppliers, limiting second-source options.
- Extended ISO 17025 accreditation timelines:Laboratory certification delays in emerging markets stretch 18-24 months, constraining local testing capacity expansion.
Strategic Opportunities
- India's construction glass certification mandate:BIS enforcement of mandatory test reports for facade systems creates demand for localized calibration services.
- Solar photovoltaic glass inspection:Anti-reflective coating uniformity requirements open new application verticals for ellipsometry and reflectance measurement systems.
- Cloud-based instrument management platforms:Remote diagnostics and usage-based billing models penetrate mid-sized automotive glass laboratories seeking operational flexibility.
Industry Challenges
- Metrology technician shortage:Specialized skills in interferometry and spectral analysis remain scarce in Southeast Asian manufacturing hubs.
- Legacy system integration complexity:Factory automation protocols in established automotive glass plants resist seamless connection with modern optical testing modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Testing Instruments Market |
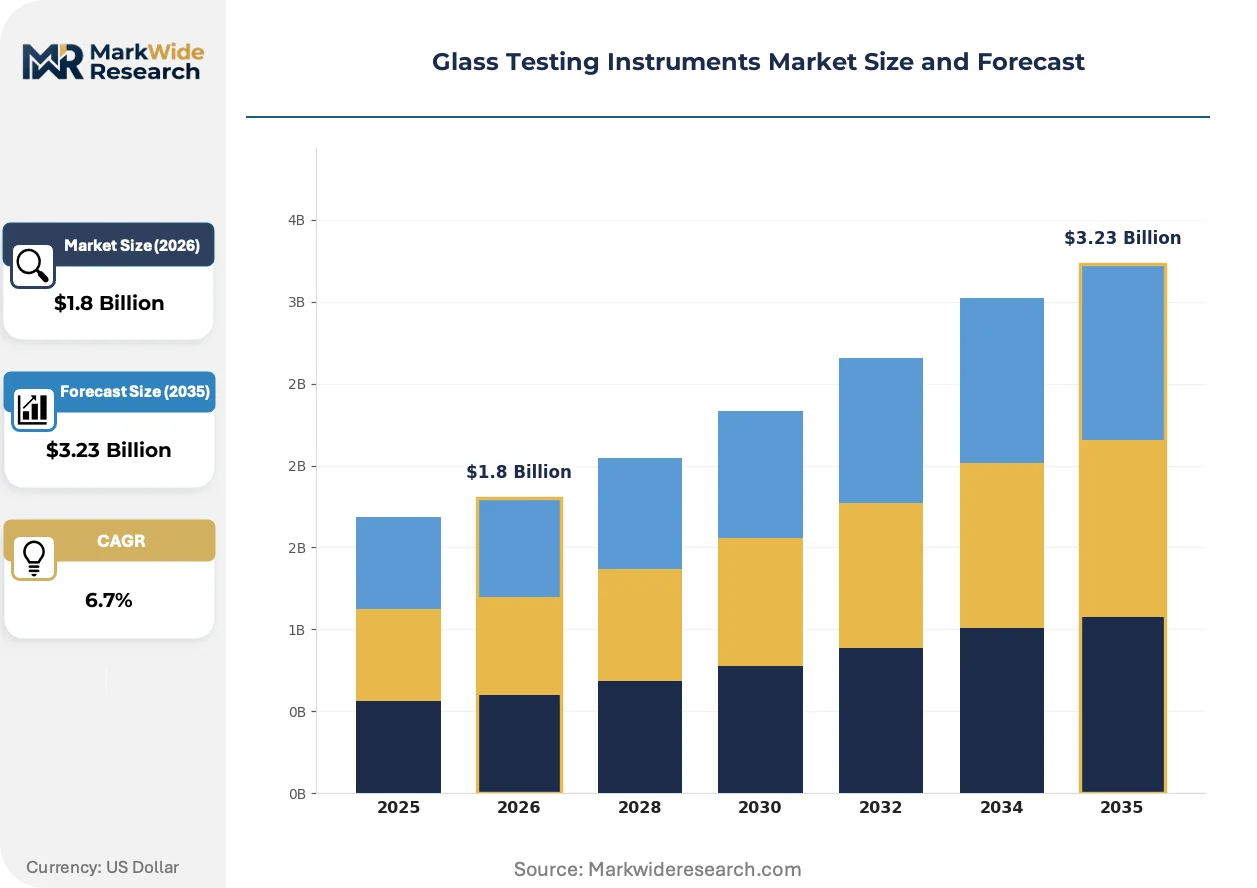
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refractometers, Hardness Testers, Spectrophotometers, Optical Coherence Tomography Technology: Laser Engraving, Thermal Testing, Mechanical Testing, Optical Testing Application: Quality Control, Research & Development, Manufacturing, Repair & Maintenance End User: Glass Manufacturers, Laboratories, Educational Institutions, Construction Industry |
| Companies Covered | Instron, ZwickRoell, Shimadzu Corporation, MTS Systems Corporation, Tinius Olsen Testing Machine Company, AMETEK, ADMET Inc., Qualitest International Inc., Torontech Group International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Testing Instruments Market Evolving Landscape
Digital thread integration between design software and quality control systems is collapsing the feedback loop from glass formulation to final inspection, enabling real-time specification adjustments.
Hyperspectral imaging is electrifying defect classification in container glass manufacturing. European pharmaceutical packaging suppliers deploy these systems at line speeds exceeding 600 bottles per minute. The technology is compressing reliance on manual sampling and offline laboratory verification.
China's GB standards for building materials now mandate third-party accredited test reports for all structural glazing imports. SAMR enforcement has triggered laboratory upgrade cycles across Jiangsu and Guangdong provinces. Domestic instrument vendors are localizing spectrophotometer production to capture compliance-driven procurement.
Subscription-based calibration services are displacing traditional break-fix maintenance contracts in mid-cap automotive glass laboratories. German and Japanese equipment vendors pilot usage-based pricing tied to verified test throughput. This model is most visible in United States manufacturing facilities seeking to convert capital expenditure to operational expenditure.
Glass Testing Instruments Market Segmentation
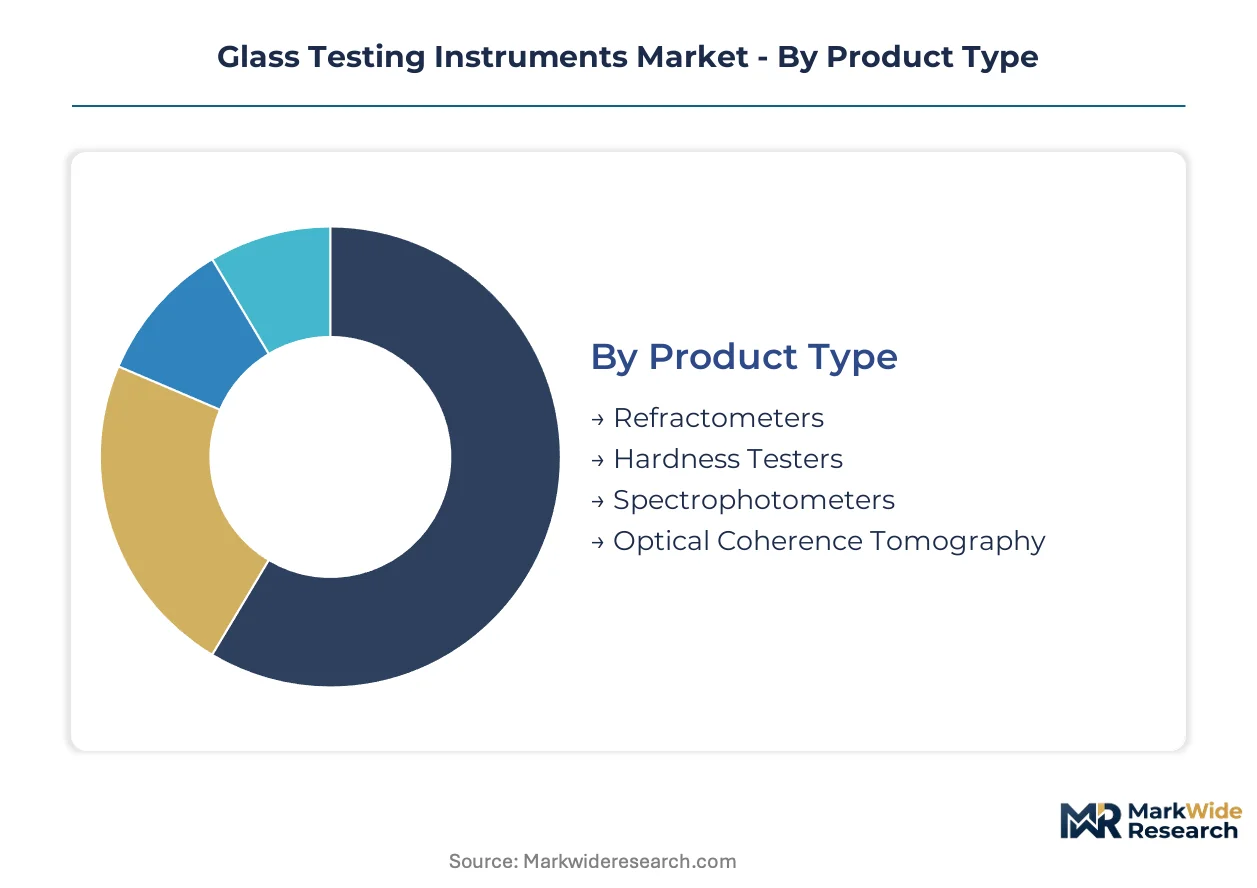
Glass testing instruments serve divergent buyer priorities across product development, compliance verification, and production monitoring. Segment boundaries reflect how capital allocation differs between R&D-intensive laboratories and high-throughput manufacturing floors.
Product Type:
Buyers in this category separate by margin sensitivity versus precision requirements, with premium optical systems commanding multi-year procurement cycles.
- Spectrophotometers:These instruments measure light transmission, absorption, and reflection across defined wavelength ranges using calibrated monochromators and photodetector arrays. Architectural glass manufacturers in Germany and China deploy these for color consistency verification where coating uniformity determines contract acceptance. EU Green Deal emissions rules are accelerating furnace upgrades that require integrated spectral monitoring.
- Optical Coherence Tomography:Non-invasive interferometric imaging captures sub-surface defect structures in thin-film coated panels at micron-scale resolution. Thin-film architectural panel manufacturers in Jiangsu province adopt this technology for flaw detection that manual inspection cannot replicate. China's GB standards for building materials now mandate third-party accredited test reports that OCT systems generate.
- Refractometers:Benchtop and handheld variants measure refractive index to verify glass composition and stress distribution in container glass production.
- Hardness Testers:Vickers and Knoop indentation systems verify surface durability for automotive and architectural glazing specifications.
Spectrophotometers lead volumes today; optical coherence tomography is gaining share fastest.
Technology:
Technology selection tracks the physical property under verification, with thermal and mechanical systems dominating manufacturing floors while optical platforms concentrate in quality laboratories.
- Mechanical Testing:Universal testing machines and specialized fixtures apply controlled loads to verify flexural strength, impact resistance, and penetration thresholds per ISO 1288. Automotive laminated glass specifications in Germany, Japan, and the United States expand procurement of penetration resistance test systems. Stricter penetration standards are forcing upgrades in established automotive glass plants.
- Optical Testing:Interferometers, polarimeters, and wavefront sensors quantify birefringence, flatness, and transmitted wavefront error for precision optics and display glass. Consumer electronics glass manufacturers in Japan and South Korea deploy these for cover lens qualification where cosmetic defects trigger rejection. METI-promoted JIS-compliant protocols standardize export certification workflows.
- Thermal Testing:Gradient furnaces and thermal shock chambers verify resistance to temperature cycling for architectural and cookware applications.
- Laser Engraving:Marking systems embed traceability codes and certification data directly onto glass surfaces for supply chain tracking.
Mechanical testing leads volumes today; optical testing is climbing the fastest.
Application:
Application segmentation reflects where instruments sit in the value chain, from upstream formulation to downstream warranty verification.
- Quality Control:In-line and at-line inspection systems enforce specification compliance before shipment, with spectrophotometers and automated visual inspection dominating. Container glass manufacturers deploy hyperspectral imaging at line speeds exceeding 600 bottles per minute. European pharmaceutical packaging suppliers compress manual sampling reliance through these deployments.
- Manufacturing:Process-integrated sensors monitor forming, tempering, and coating operations to enable real-time parameter adjustment. Automotive glass plants in the United States seek operational flexibility through cloud-based instrument management platforms. Subscription-based calibration services displace break-fix contracts in mid-cap facilities.
- Research & Development:Laboratory-grade systems support formulation iteration and failure analysis with higher precision than production instruments.
- Repair & Maintenance:Portable hardness testers and refractometers verify field-installed glazing compliance with original specifications.
Quality control leads volumes today; manufacturing is expanding most quickly.
End User:
End user categories differ by procurement authority, technical staffing, and integration complexity with existing workflows.
- Glass Manufacturers:Integrated producers and independent fabricators represent the largest equipment purchaser category, with capital budgets tied to capacity expansion and specification upgrades. Tempered and laminated glass specification tightening drives replacement cycles across Germany, China, and the United States. Software-defined calibration compresses equipment replacement cycles as vendors bundle predictive maintenance.
- Laboratories:Independent testing facilities and corporate quality labs require ISO 17025 accreditation that stretches 18-24 months in emerging markets. India's BIS enforcement of mandatory test reports for facade systems creates demand for localized calibration services. Extended accreditation timelines constrain testing capacity expansion.
- Construction Industry:Project-specific testing contractors verify field-installed structural glazing performance against design specifications.
- Educational Institutions:University materials science programs procure entry-level systems for training and foundational research.
Glass manufacturers lead volumes today; laboratories are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China operate divergent procurement rhythms for glass testing equipment, with German automotive glass labs prioritizing predictive maintenance bundles while Chinese architectural panel manufacturers accelerate optical coherence tomography adoption under tightened GB standards.
Germany
Automotive laminated glass specifications from KBA drive penetration resistance testing upgrades across Baden-Württemberg and Bavaria. EU Green Deal emissions rules mandate carbon reporting for construction materials, forcing thermal testing furnace replacements. Stuttgart's automotive glass cluster locks in multi-year maintenance agreements with equipment vendors bundling software-defined calibration.
China
Thin-film coated architectural panel manufacturers in Jiangsu province deploy optical coherence tomography for sub-surface flaw detection. SAMR enforcement of GB standards for building materials mandates third-party accredited test reports for all structural glazing imports. Domestic instrument vendors localize spectrophotometer production in Guangdong to capture compliance-driven procurement from facade system fabricators.
United States
Mid-cap automotive glass laboratories seek operational flexibility through cloud-based instrument management platforms. FDA device-quality standards regulate optical instruments used in medical glass packaging. Michigan and Ohio manufacturing facilities pilot usage-based pricing tied to verified test throughput, converting capital expenditure to operational expenditure.
Japan
Consumer electronics glass manufacturers deploy interferometers and wavefront sensors for cover lens qualification where cosmetic defects trigger rejection. METI promotes JIS-compliant testing protocols for automotive glazing exports. Nagoya's precision optics cluster anchors technical support centers delivering application-specific training programs.
India
BIS enforcement of mandatory test reports for facade systems creates demand for localized calibration services. Extended ISO 17025 accreditation timelines stretch 18-24 months, constraining testing capacity expansion in emerging manufacturing hubs. Maharashtra and Gujarat glass fabricators upgrade quality control workflows as construction glass certification mandates harden.
Glass Testing Instruments Market Competitive Landscape
Top-tier vendors anchor premium optical and mechanical testing systems, while mid-tier specialists occupy calibrated service niches and regional calibration networks. The vendor base organizes around three strategic archetypes: integrated metrology platforms bundling predictive maintenance, precision optical component fabricators controlling grating supply, and localized service providers capturing compliance-driven upgrade cycles. Dominant competitive moves include M&A to secure helium-dependent leak detection capabilities and strategic partnerships to embed instruments within factory automation protocols.
Among precision testing equipment fabricators, Instron, ZwickRoell, and Shimadzu Corporation exemplify divergent geographic anchoring strategies. Instron leverages its global service network position. ZwickRoell occupies a role in optical testing module development. Shimadzu Corporation represents Asia-Pacific localized technical support center deployment. These three entities illustrate how equipment vendors restructure revenue models around recurring service streams rather than discrete instrument sales.
| Leading Market Players |
|---|
| Instron |
| ZwickRoell |
| Shimadzu Corporation |
| MTS Systems Corporation |
| Tinius Olsen Testing Machine Company |
| AMETEK |
| ADMET Inc. |
| Qualitest International Inc. |
| Torontech Group International |
| Others |
Value Network & Pricing Analysis
Helium sourcing from Qatar and the United States feeds mass spectrometer leak detection systems, with price volatility propagating through premium optical testing tiers as equipment vendors bundle predictive maintenance to offset input cost swings.
Pricing Analysis
Capacity additions in China are reshaping price floors for spectrophotometer production as domestic vendors localize manufacturing under GB standards compliance mandates. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-certified laboratory systems from factory-floor quality control units and entry-level educational instruments. Cost compression in economy tiers is intensifying because helium supply concentration and high-precision grating fabrication bottlenecks squeeze component availability. Mid-cap automotive glass laboratories exhibit highest price sensitivity, converting capital expenditure to operational expenditure through subscription-based calibration services.
Supply Chain Analysis
Ocean freight routing from German and Japanese specialty suppliers to Southeast Asian manufacturing hubs elevates landed costs for interferometer gratings and calibrated photodetector arrays. Component fabrication concentrates in Germany, Japan, and China, with spectrophotometer monochromators and OCT interferometric modules drawing from these precision optics clusters. Single-source vulnerability in helium-dependent leak detection systems creates exposure to Qatar supply disruptions. Distribution runs through authorized technical support centers that anchor localized calibration networks in compliance-driven procurement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass testing instruments represent a late-cycle quality story as automotive and architectural specifications tighten penetration resistance and thermal-shock thresholds, forcing replacement cycles that favor vendors bundling software-defined calibration.
For Market Incumbents: Anchor multi-year service contracts through predictive maintenance bundles that lock in automotive glass laboratories across Germany and the United States. Deepen backward integration into high-precision grating fabrication to reduce exposure to German and Japanese specialty supplier bottlenecks. Defend against emerging domestic Chinese vendors by accelerating ISO 17025 accreditation support for laboratory customers facing 18-24 month certification timelines. For New Entrants and Emerging Players: Capture India's BIS-mandated facade certification market by establishing localized calibration services in Maharashtra and Gujarat before extended accreditation timelines constrain testing capacity expansion. Penetrate solar photovoltaic glass inspection verticals through ellipsometry and reflectance measurement systems targeting anti-reflective coating uniformity requirements. Lead with cloud-based instrument management platforms that convert mid-cap automotive glass laboratory procurement from capital expenditure to operational expenditure. For Investors and Strategic Acquirers: Consolidation pressure builds where helium-dependent leak detection capabilities concentrate among limited specialty vendors and predictive maintenance bundling reshapes revenue models toward recurring service streams. Target acquisition profiles include mid-tier calibration service networks with established ISO 17025 credentials in emerging compliance markets. Watch cloud-based platform adoption rates in United States mid-cap facilities as the signal indicating inflection toward usage-based pricing dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Optics | Captive grating production reduces exposure to German and Japanese specialty supplier concentration. |
| Cloud-Based Platform Deployment | Remote diagnostics enable usage-based billing that converts capital expenditure to operational expenditure in mid-cap laboratories. |
| Localized Calibration Network Expansion | ISO 17025-accredited service centers capture BIS-mandated compliance procurement in India's construction glass market. |
| Helium Recovery System Investment | Closed-loop leak detection infrastructure mitigates Qatar supply concentration risk in mass spectrometer operations. |
| OCT Module Factory Integration | Sub-surface defect detection systems embed within Jiangsu province thin-film panel production lines under GB standards mandates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with equipment vendor sales directors, laboratory accreditation managers, automotive glass procurement leads, and metrology technicians with secondary validation against ISO certification databases, SAMR regulatory filings, EU Green Deal implementation reports, and customs trade records. Bottom-up instrument shipment tracking and top-down end-use demand estimation were triangulated against capital expenditure disclosures from major glass manufacturers.
Segment-weighting approaches distributed value across product type, technology, application, and end user dimensions, with additional stratification by regional regulatory cluster and certification tier. CAGRs were derived from fitted growth curves applied to baseline shipment data, incorporating EU Green Deal furnace replacement schedules, automotive laminated glass specification timelines, and China's GB standards enforcement phases as industry-specific forecast inputs across the analysis window.
Helium supply disruptions, extended ISO 17025 accreditation delays, and building-code harmonization between ISO and national standards are the dominant revision risks that could compress or extend replacement cycle assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Liquid Chromatography Market
Testing Equipment
High Performance Liquid Chromatography (HPLC) Market
Testing Equipment
Total Hydrocarbon Analyzers Market
Testing Equipment
Oxidation Stability Analyzer Market
Testing Equipment
Water Penetration Tester Market
Testing Equipment
Microplastics Particle Size and Shape Characterization Systems Market
Testing Equipment
Low-Pressure Liquid Chromatography Market
Testing Equipment
Steel Testing Equipment Market
Testing Equipment
Dynamic Light Scattering (DLS) Measure Instrument Market
Testing Equipment
Cone Calorimeter Market
Testing Equipment
Next-Generation Titrators Market
Testing Equipment
Automated Solid Phase Extraction Systems Market
Testing Equipment
US Eddy-Current Testing Market
Testing Equipment
Paint Tester Market
Testing Equipment
Laboratory Filtration Equipment and Supplies Market
Testing Equipment
Gold Tester Market