
 Global Rheology Modifiers Market | 2026-2036
Global Rheology Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rheology Modifiers Market Foresight
Subscription-based technical service and reformulation support is restructuring how specialty chemical suppliers monetize rheology modifier relationships. BASF SE leverages its global application laboratories to sustain long-term contracts with multinational coatings producers. Evonik Industries AG anchors its position through silicone-polyurethane hybrid expertise in personal care formulations. Arkema competes on acrylate block copolymer technology leadership for high-shear industrial coatings.
Rheology modifiers are substances that alter the flow and deformation behavior of liquid and semi-solid formulations, typically functioning through polymer chain entanglement, particle network formation, or associative thickening mechanisms at concentrations ranging from 0.1% to 5% by weight. Their primary commercial purpose centers on enabling application properties—sprayability, leveling, sag resistance—while maintaining storage stability in packaged products. Cellulose derivatives retain dominant volume share in construction and paper applications where cost-efficient water retention proves critical. Polyurethanes command premium positioning in personal care and high-performance coatings due to their superior optical clarity and pH stability. Acrylates represent the fastest-growing chemistry class as formulators seek associative thickeners compatible with low-VOC water-based systems.
REACH registration requirements and EU Green Deal decarbonization mandates are reshaping product portfolios toward bio-based and low-toxicity thickeners in European manufacturing. EPA TSCA Section 5 premanufacture notifications constrain novel chemical introductions in the United States, favoring incumbent suppliers with established regulatory dossiers. China's GB standards on volatile organic compound emissions in architectural coatings are accelerating domestic reformulation toward compliant rheology systems. Stakeholders must monitor regulatory divergence across jurisdictions to determine whether centralized product platforms or regional specialization delivers superior compliance economics.
Market Dynamics
Water-based formulation mandates across architectural coatings are compressing solvent-thickened legacy systems while concentrating procurement among suppliers with compliant bio-based portfolios. REACH dossier completeness now functions as a competitive moat in European supply negotiations.
Growth Catalysts
- REACH Phase-In Substances:Registration deadlines for existing chemicals are locking out non-compliant thickeners from EU manufacturing supply chains. Formulators face reformulation timelines that favor incumbent rheology modifier suppliers with complete toxicological data packages.
- China GB 18582-2020:Volatile organic compound limits in architectural coatings are forcing domestic producers toward associative polyurethane thickeners. Local coating manufacturers require technical support partnerships to achieve compliance without performance degradation.
- Cellulose nanofibril production scale-up:Scandinavian pulp processors are commercializing mechanically fibrillated cellulose at tonnage volumes suitable for construction applications. This bio-based alternative is penetrating gypsum board joint compounds and cementitious tile adhesives.
Market Restraints
- Ethylene oxide supply concentration:Carbomer production depends on ethoxylated intermediates from Gulf Coast petrochemical complexes. Hurricane-related production outages create 90-day inventory cycles for personal care formulators.
- Acrylic acid feedstock volatility:Propylene derivative pricing swings compress margins for acrylate-based associative thickeners. Water-based coatings producers face unpredictable raw material cost pass-through negotiations.
- Silicone-polyurethane hybrid patent thickets:Evonik's intellectual property portfolio around hydrophobically modified ethoxylated urethanes creates licensing friction for personal care entrants. New market participants must navigate complex freedom-to-operate analyses.
Strategic Opportunities
- India BIS certification gap:Domestic construction chemical producers lack qualified local suppliers of hydroxyethyl cellulose meeting Bureau of Indian Standards specifications. Import substitution partnerships with European cellulose ether producers offer technical credibility advantages.
- 3D printing construction paste rheology:Extrusion-based additive manufacturing of concrete elements requires shear-thinning modifiers with rapid recovery properties. Construction chemical formulators can develop application-specific modifier packages for robotic placement systems.
- EU Green Deal carbon border adjustments:Embodied carbon accounting in imported construction materials creates preference for regionally produced bio-based thickeners. Scandinavian and Baltic producers can leverage renewable electricity credentials in German and Dutch procurement.
Industry Challenges
- Formulation chemist scarcity:Water-based coatings laboratories require expertise in colloidal stability and pigment dispersant interactions that solvent-era technicians lack. Technical service teams struggle to train personnel at the pace of customer reformulation demands.
- Multi-jurisdictional registration synchronization:TSCA Section 5 notifications, REACH updates, and China new chemical substance registrations require parallel regulatory affairs capacity. Smaller specialty chemical suppliers face resource constraints managing divergent filing timelines.
- Legacy coating line retrofit costs:Transitioning automotive OEM electrocoat systems from solvent-based to water-based rheology platforms requires tank cleaning, filtration upgrades, and cure oven modifications. Capital expenditure approvals delay qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rheology Modifiers Market |
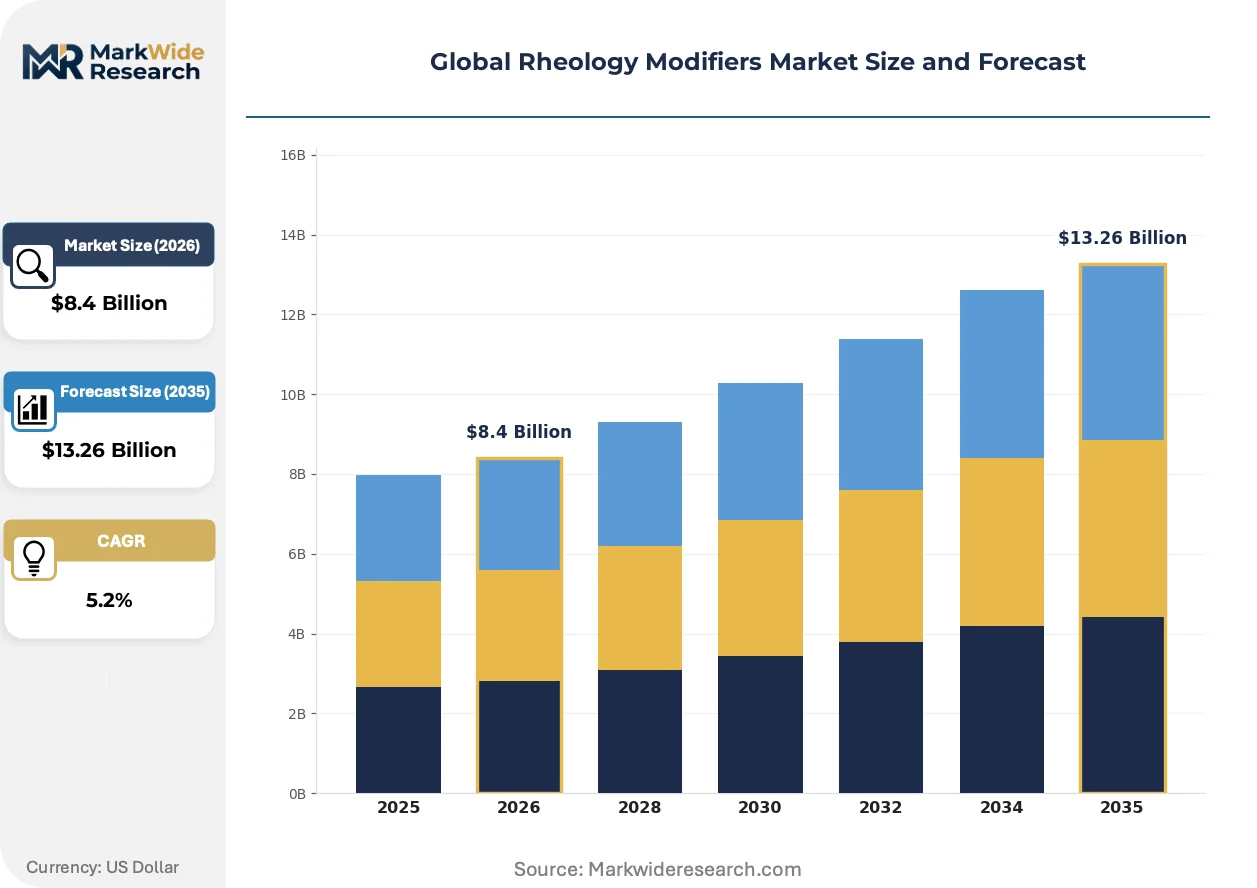
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose Derivatives, Acrylates, Bentonite, Polyurethanes, Silica, Vinyl Polymers Application: Paints & Coatings, Adhesives & Sealants, Personal Care, Oilfield, Construction, Inks End User Industry: Packaging Manufacturers, Cosmetic Producers, Chemical Processors, Textile Plants, Paper Mills, Water Treatment Plants Deployment Type: Water-Based Systems, Solvent-Based Systems, Powder Formulations, Emulsions, Gels |
| Companies Covered | Clariant, Ashland, BASF SE, Elementis Plc, Akzo Nobel N.V., The Dow Chemical Company, Arkema, Evonik Industries AG, Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rheology Modifiers Market Shifts & Advancements
Bio-based feedstock substitution is moving from marketing positioning to procurement specification in European and North American coatings contracts. Technical performance parity with petroleum-derived alternatives now determines commercial viability rather than premium positioning.
Associative thickener technology is electrifying water-based industrial coatings by enabling high-shear stability without optical haze. Automotive refinish formulators in Germany and the United States are qualifying these systems for metallic basecoat applications. The technology is compressing market space for traditional cellulosic thickeners in premium coating segments.
EPA TSCA Section 6(h) persistent, bioaccumulative, and toxic chemical prioritization is accelerating reformulation away from certain fluorinated surfactants used in rheology modifier dispersions. Coating manufacturers serving US federal procurement contracts must certify absence of listed substances. Defense and infrastructure coating suppliers are reformulating ahead of enforcement timelines to maintain qualified supplier status.
Direct technical service engagement is displacing distributor-mediated sales relationships in mid-tier coatings manufacturing. Regional coating producers in Poland, Mexico, and Vietnam now expect on-site formulation support from rheology modifier suppliers. This channel compression concentrates relationship value with suppliers maintaining regional application laboratories.
Global Rheology Modifiers Market Segmentation
Rheology modifier selection determines formulation economics and regulatory compliance across distinct application environments. Segmentation reveals how chemistry choices align with performance requirements, VOC constraints, and processing conditions in target industries.
Product Type:
Cellulose derivatives dominate tonnage shipments while polyurethane and acrylate systems command formulation premiums in performance coatings.
- Cellulose Derivatives:Hydroxyethyl cellulose and methyl cellulose function through water retention and polymer chain entanglement in aqueous systems. Construction applications in China and India absorb the majority of commodity-grade volumes as cementitious tile adhesive production scales.
- Acrylates:Associative thickeners with hydrophobically modified alkali-swellable emulsion chemistry enable low-VOC water-based coatings without optical haze. German and US automotive refinish formulators are qualifying these systems for metallic basecoat segments.
- Bentonite:Organoclay platelet suspensions provide thixotropic flow control in solvent-based industrial primers.
- Polyurethanes:Silicone-urethane hybrids deliver superior pH stability and optical clarity in premium personal care emulsions.
- Silica:Fumed and precipitated grades control sag resistance in high-build protective coatings.
- Vinyl Polymers:Polyvinyl alcohol and related systems serve paper coating and adhesive applications.
Mature deployment sits with Cellulose Derivatives across construction and paper sectors. Newer deployment is concentrated in Acrylates as water-based mandates accelerate.
Application:
Coatings procurement patterns diverge sharply between architectural volume plays and industrial specialty qualifications.
- Paints & Coatings:Architectural, automotive, and industrial sub-segments each demand distinct rheology profiles. China GB 18582-2020 VOC limits are forcing domestic producers toward associative polyurethane thickeners with technical support partnerships.
- Personal Care:Emulsion stability and sensory properties drive hydrophobically modified polymer selection. REACH registration completeness functions as a competitive moat in EU supply negotiations for premium skincare formulators.
- Adhesives & Sealants:Construction adhesives and flexible packaging applications require tailored flow control.
- Oilfield:Drilling fluid viscosity management depends on temperature-stable polymer systems.
- Construction:Cementitious applications prioritize water retention and workability enhancement.
- Inks:Flexographic and gravure printing demands precise shear-thinning characteristics.
Volume concentration centers on Paints & Coatings. Margin expansion is climbing the fastest in Personal Care as formulation complexity increases.
End User Industry:
Customer technical capabilities determine whether sales flow through distributors or direct technical service engagement.
- Packaging Manufacturers:Flexible packaging ink and adhesive formulators require consistent batch-to-batch rheology control. Regional coating producers in Poland, Mexico, and Vietnam now expect on-site formulation support from modifier suppliers.
- Cosmetic Producers:Multinational personal care brands maintain long-term contracts with suppliers maintaining global application laboratories for reformulation support.
- Chemical Processors:Toll manufacturers and specialty chemical blenders serve as intermediate demand channels.
- Textile Plants:Print paste and sizing applications utilize thickener systems for process control.
- Paper Mills:Coating color formulations depend on viscosity stability at high shear rates.
- Water Treatment Plants:Flocculation and sludge conditioning applications represent industrial utility demand.
Established relationships dominate Packaging Manufacturers. Emerging procurement sophistication is most visible in Cosmetic Producers.
Deployment Type:
Formulation platform selection locks in raw material supply chains and capital equipment requirements.
- Water-Based Systems:Associative thickeners and cellulosic polymers serve low-VOC architectural and industrial coatings. EPA TSCA Section 6(h) PBT prioritization is accelerating reformulation away from fluorinated surfactant dispersions in US federal procurement.
- Solvent-Based Systems:Organoclays and fumed silica maintain position in high-performance industrial segments where water compatibility is impractical.
- Powder Formulations:Dry-blend construction additives enable field mixing flexibility.
- Emulsions:Pre-dispersed liquid concentrates simplify handling in high-volume coating operations.
- Gels:Structured delivery systems target personal care and specialized industrial applications.
Regulatory pressure is compressing Solvent-Based Systems. Technical innovation is expanding most quickly in Water-Based Systems as formulators achieve performance parity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor concentrates European rheology modifier demand as coating formulators reformulate for REACH compliance. German chemical clusters drive specification standards across continental supply chains.
United States
Gulf Coast petrochemical complexes supply ethoxylated intermediates for carbomer production used in personal care formulations. EPA TSCA Section 6(h) persistent bioaccumulative toxic chemical prioritization forces coating manufacturers serving federal contracts to eliminate fluorinated surfactant dispersions. Houston-area toll manufacturers maintain inventory buffers against hurricane-related supply disruptions.
Germany
Automotive OEM electrocoat operations in Bavaria and Baden-Württemberg require water-based rheology platforms with high-shear stability. EU Green Deal carbon border adjustment mechanisms favor regionally produced bio-based thickeners from Scandinavian suppliers. Frankfurt-Rhine-Main chemical distributors coordinate technical service partnerships for mid-tier coatings producers.
China
Domestic architectural coating production in the Yangtze River Delta absorbs associative polyurethane thickeners for GB 18582-2020 VOC compliance. Shanghai-based formulators demand on-site technical support from specialty chemical suppliers establishing regional application laboratories. Jiangsu province coating clusters drive procurement consolidation toward qualified domestic and multinational suppliers.
India
Cementitious tile adhesive production in Maharashtra and Gujarat consumes hydroxyethyl cellulose volumes as construction activity expands. Bureau of Indian Standards certification gaps for qualified local suppliers create import substitution opportunities for European cellulose ether producers. Mumbai-Pune industrial corridor distributors struggle to match technical service expectations of reformulating construction chemical manufacturers.
Japan
Precision electronics coatings in the Kanto region require rheology modifiers with optical clarity for display applications. METI industrial standards guide formulation specifications for high-performance industrial segments. Osaka-Kobe chemical processors serve as intermediaries between global suppliers and domestic specialty coatings formulators.
Global Rheology Modifiers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology platforms in the rheology modifier sector. Integrated petrochemical groups maintain captive cellulose ether and acrylate production for construction and coatings verticals. Three strategic archetypes dominate: multinational diversified chemical conglomerates with global application laboratory networks, regional specialists in bio-based or silicone-urethane hybrid chemistries, and toll manufacturers serving private-label demand. Competitive dynamics center on M&A activity consolidating regional distribution capabilities and strategic partnerships securing feedstock supply agreements.
Among diversified chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated archetype with global technical service infrastructure. Arkema occupies a position representing acrylate block copolymer specialization for high-shear industrial coating segments. These three entities anchor the competitive structure through differentiated chemistry platforms and regulatory dossier completeness across REACH, TSCA, and Asian chemical registration frameworks.
| Leading Market Players |
|---|
| Clariant |
| Ashland |
| BASF SE |
| Elementis Plc |
| Akzo Nobel N.V. |
| The Dow Chemical Company |
| Arkema |
| Evonik Industries AG |
| Lubrizol Corporation |
| Others |
Supply & Pricing Matrix
GB 18582-2020 VOC compliance deadlines in China are forcing domestic coating manufacturers toward qualified associative polyurethane thickeners, compelling supply chains to absorb technical service costs and concentrate procurement among REACH-registered suppliers with complete toxicological dossiers.
Pricing Analysis
Margin tightening in commodity cellulose ethers reflects propylene derivative volatility and acrylic acid feedstock swings. Contract-based long-term offtake dominates premium polyurethane grades, while spot purchasing persists for construction-grade cellulosic volumes. Price differentiation hinges on REACH registration completeness and regional production credentials under EU Green Deal carbon border adjustments. Water-based coatings producers exhibit highest price sensitivity due to unpredictable raw material cost pass-through negotiations, whereas personal care formulators prioritize optical clarity and pH stability over unit economics.
Supply Chain Analysis
REACH dossier completeness and BIS certification gaps function as procurement gating mechanisms across European and Indian supply chains. Manufacturing concentrates in Germany, China, and the United States, with ethoxylated intermediates drawing from Gulf Coast petrochemical complexes and cellulose ether production anchored in Scandinavian pulp processing. Carbomer production rests on ethylene oxide availability vulnerable to hurricane-related disruptions. Distribution runs through regional application laboratories that displace traditional distributor relationships in Poland, Mexico, and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around regulatory compliance capabilities, with REACH registration deadlines and multi-jurisdictional filing requirements forcing smaller specialty chemical suppliers toward exit or acquisition.
For Market Incumbents: Deploy captive cellulose ether production to secure construction verticals in India and China against ethylene oxide supply volatility. Deepen technical service infrastructure in Shanghai and Mumbai-Pune corridors to capture reformulation partnerships. Defend against acrylate block copolymer specialists by accelerating bio-based thickener certification under EU Green Deal protocols. For New Entrants and Emerging Players: The price-point gap between premium silicone-urethane hybrids and economy cellulosic grades offers white-space targeting for mid-tier water-based coatings in Vietnam and Poland. Penetrate construction adhesive segments lacking qualified hydroxyethyl cellulose suppliers certified to Bureau of Indian Standards specifications. Pursue toll manufacturing partnerships with European cellulose ether producers to leverage existing regulatory dossiers. For Investors and Strategic Acquirers: The window for entry favors regional application laboratory networks with incomplete REACH portfolios. Long-term viability centers on acquisition targets possessing toxicological data packages across TSCA, REACH, and China new chemical substance registrations. Watch for inflection signals in 3D printing construction paste qualification timelines and robotic placement system adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethoxylated Intermediates | Gulf Coast petrochemical supply disruptions create 90-day inventory vulnerability for carbomer-dependent personal care formulators. |
| Regional Application Laboratory Expansion | Mid-tier coatings producers in Poland, Mexico, and Vietnam now demand on-site formulation support displacing distributor relationships. |
| REACH Dossier Acquisition | Registration completeness functions as competitive moat locking non-compliant thickeners from EU manufacturing supply chains. |
| Bio-based Thickener Certification | EU Green Deal carbon border adjustments favor Scandinavian producers with renewable electricity credentials in German procurement. |
| 3D Printing Construction Paste Development | Extrusion-based additive manufacturing of concrete elements requires shear-thinning modifiers with rapid recovery properties. |
Research Methodology
Independent corroboration across plant managers at construction chemical facilities, procurement leads at downstream coatings OEMs, and technical R&D directors at specialty chemical suppliers underwrites the qualitative findings. Secondary validation draws from customs and trade data, Cefic sector reports, SEC 10-K filings from diversified chemical conglomerates, and GB standards documentation from Chinese regulatory repositories. Bottom-up volume estimates triangulate against top-down market sizing across chemistry classes and application verticals.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions include chemistry type, deployment platform, end-use industry, and regional production hub clustering. CAGRs derive from modeled substitution rates between solvent-based and water-based systems, regulatory compliance timelines, and construction activity indices. Forecast inputs incorporate cellulose nanofibril production scale-up trajectories and automotive OEM electrocoat retrofit capital expenditure patterns.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-time inventory cycle data from Gulf Coast petrochemical complexes introduce uncertainty bands around carbomer supply disruption scenarios. Forecasts reflect assumptions regarding REACH enforcement consistency and China GB standard implementation timelines. A model refresh is warranted upon material change in EU Green Deal carbon border adjustment mechanism scope or EPA TSCA Section 6(h) enforcement prioritization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Rheological Additives Market
Additives
Metallic Stearate Market
Additives
Crystal Growth Modifier Market
Additives
Citrate Ester Market
Additives
Tamarind Gum Derivatives Market
Additives
Global Synthetic Tackifier Market
Additives
Silicone Additives Market
Additives
Automotive Additives Market
Additives
Conditioning Agent Market
Additives
Driveline Additives Market
Additives
Chemical Silage Additives Market
Additives
Global PVC Additives Market
Additives
Impact Modifier Market
Additives
Agrochemicals Additives Market
Additives
Global Rheology Modification Coating Additives Market
Additives
Sodium Caprylate Market