
 Professional Printers Market | 2026-2036
Professional Printers Market Size, Share, and Industry Trends Forecast 2026-2036
Professional Printers Market Analysis
Japanese OEM supply chains is hardening around captive ink and printhead production. HP leverages vertical integration across thermal inkjet architectures to sustain margin control in high-volume commercial segments. Canon anchors its position in photography studios through dye-sublimation specialization, while Epson dominates wide-format signage with precision micro piezo systems that extend color gamut standards.
Professional printers are electromechanical imaging systems engineered to deposit pigmented or dyed materials onto substrates at resolutions typically exceeding 600 dots per inch, employing thermal, piezoelectric, or laser-induced electrophotographic processes to serve commercial reproduction needs. Laser systems occupy the mature core of office and copy center fleets where total cost-per-page economics govern procurement decisions. Inkjet platforms are displacing analog methods in textile and packaging applications where continuous ink supply architectures reduce job-change downtime. LED curing technology competes with traditional UV mercury lamps in signage production, narrowing energy footprints while accelerating substrate throughput.
EPA Energy Star specifications and EU Ecodesign requirements constrain standby power draw and toner cartridge material recovery rates, redirecting R&D budgets toward compliance-first engineering. Japan's METI enacts top-runner efficiency benchmarks that OEMs must meet for domestic market access, tightening the specification gap between regional product variants. Buyers should monitor how F-Gas phase-down schedules and emerging per- and polyfluoroalkyl substance restrictions reshape fuser roller chemistries and long-term service part availability.
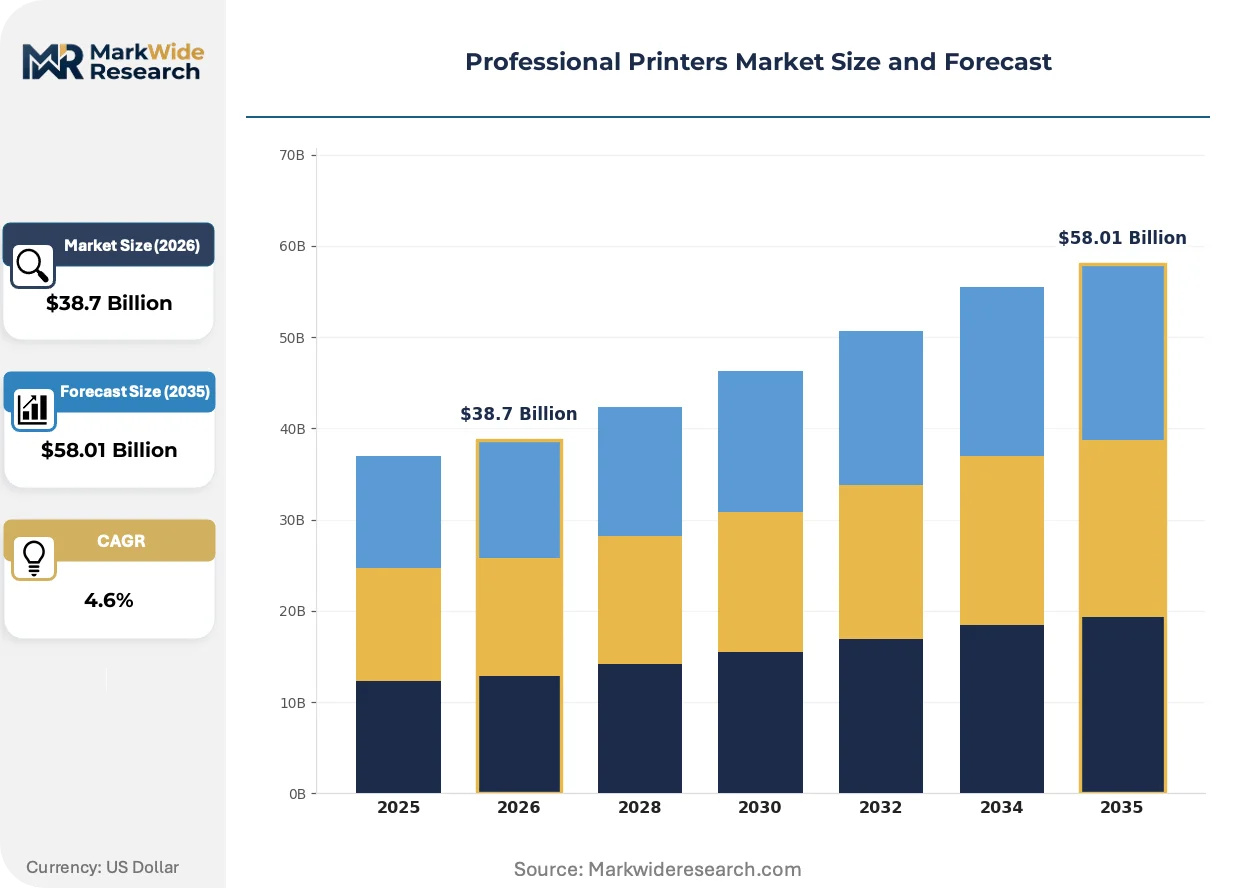
Market Dynamics
Fleet refresh cycles across commercial print operations are compressing as energy-efficiency mandates from Brussels and Beijing force premature retirement of analog and first-generation digital systems.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for hydrofluorocarbons accelerate replacement of mercury-curing UV systems with LED-based alternatives in signage production.
- Packaging converters:Continuous ink supply architectures reduce job-change downtime, pulling demand from flexographic methods toward piezoelectric inkjet platforms.
- China's dual carbon goals:Domestic efficiency benchmarks tighten access for imported equipment, creating captive demand for locally certified LED-curing and toner formulations.
Market Restraints
- Specialized printhead supply:Japanese and Korean captive producers control piezoelectric actuator architectures, exposing non-integrated OEMs to allocation risk during semiconductor cycle tightness.
- PFAS restrictions:Emerging limits on per- and polyfluoroalkyl substances threaten fuser roller chemistries and long-term service part availability across legacy laser fleets.
- Substrate cost volatility:Pulp and petrochemical feedstock swings compress margin predictability for commercial print service providers operating on fixed-price contracts.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing attract component localization investments for inkjet printhead assembly and LED curing module production.
- Textile digitalization:Direct-to-garment and direct-to-fabric systems penetrate apparel hubs in Bangladesh and Vietnam, displacing rotary screen methods for short-run fashion cycles.
- Service-integrated supply contracts:German packaging converters consolidate vendor relationships around managed print services, bundling equipment, consumables, and predictive maintenance.
Industry Challenges
- Color management expertise:ICC profile calibration and expanded gamut workflows require specialized technicians scarce in regional commercial print markets.
- Legacy RIP integration:Raster image processor architectures from pre-2010 installations resist API compatibility with cloud-based job submission and automated preflight systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Professional Printers Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet, Laser, Dye-Sublimation, All-in-One End User: Commercial Printing, Copy Centers, Photography Studios, In-house Printing Technology: Thermal Transfer, LED, Continuous Ink Supply, Solid Ink Application: Textiles, Packaging, Photographic Prints, Signage |
| Companies Covered | Brother Industries, Oce, HP, KIP, Mutoh, Canon, Fujifilm, Pantum, Epson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Professional Printers Market Emerging Trajectories
Hardware differentiation is flattening as software-defined color management and predictive maintenance subscriptions reshape how value is captured across the equipment lifecycle.
Precision micro piezo deposition systems are converging with aqueous pigment chemistry advances to enable uncoated paper direct printing, bypassing primer requirements that add cost and drying time. Magazine and catalog publishers in the US Midwest adopt these configurations to maintain postal qualification while reducing substrate spend. The structural compression of make-ready steps is converging with automated imposition software to collapse job turnaround from days to hours.
EPA Energy Star Version 3.0 specifications tighten standby power draw limits to 1.2 watts, forcing power supply redesigns and sleep-state logic across office multifunction fleets. OEM engineering teams redirect thermal management R&D toward compliance-first architectures rather than throughput acceleration. North American copy center chains face the steepest retrofit burden where 2015-2019 installed bases predominate.
Consolidated procurement through group purchasing organizations is concentrating buyer power among top-ten commercial print groups, unbundling traditional dealer networks. Independent dealers respond with managed print service wraps that capture recurring revenue beyond equipment margin. This channel restructuring is most visible in the Rhine-Ruhr corridor where industrial packaging clusters negotiate enterprise-wide supply agreements.
Professional Printers Market Segmentation
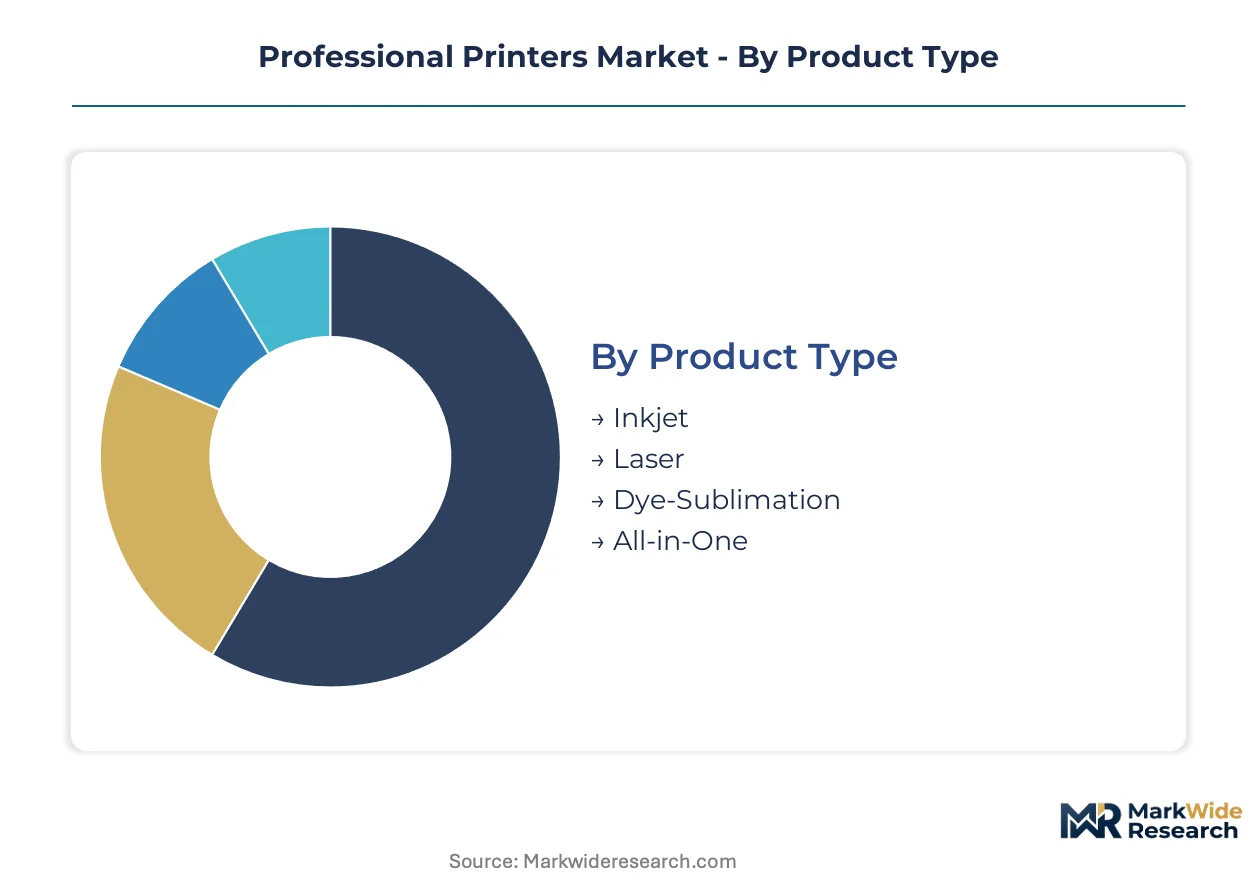
Segmentation in professional printers reveals how technology choices, buyer workflows, and substrate requirements fragment procurement patterns across commercial operations. Equipment specifications diverge sharply between high-volume production environments and specialized creative studios, reshaping vendor engagement models.
Product Type:
Buyer differentiation in this category hinges on total cost-per-page economics versus color fidelity requirements and substrate versatility.
- Inkjet:Piezoelectric and thermal deposition architectures deposit aqueous or solvent-based pigments onto porous and non-porous substrates. Demand concentrates in German packaging converters along the Rhine-Ruhr corridor where continuous ink supply systems collapse job-change downtime for short-run corrugated work.
- Laser:Electrophotographic imaging fuses dry toner onto paper through heat and pressure, delivering sub-cent cost-per-page economics at office volumes. Procurement in North American copy centers prioritizes fleet standardization around monochrome workhorse models that dominate 10,000-plus monthly impressions.
- Dye-Sublimation:Solid dye diffusion onto polyester-coated substrates produces continuous-tone output without halftone screening. Photography studios in Japan and South Korea specify these systems for portrait proofing and event merchandise where color permanence commands premium pricing.
- All-in-One:Consolidated architectures merge printing, scanning, and document management within single footprints. Small commercial print shops in India's emerging tier-two cities adopt these configurations to minimize capital outlay and floor space constraints.
Volume sits with Laser; growth tilts toward Inkjet.
End User:
Procurement authority and service integration expectations separate these buyer types more than equipment specifications alone.
- Commercial Printing:Dedicated reproduction facilities operate production inkjet and offset-hybrid fleets at industrial scale. These buyers in China's Pearl River Delta negotiate consumables contracts tied to per-impression pricing rather than capital purchase.
- Copy Centers:Quick-print and document service bureaus prioritize equipment uptime and same-day service response. Franchise networks across the US Midwest standardize on manufacturer-certified dealer programs to minimize operational risk.
- Photography Studios:Portrait and commercial photographers demand wide color gamut and archival stability. Italian and Spanish studio clusters drive specification requests for 12-color pigment ink systems with museum-grade longevity ratings.
- In-house Printing:Corporate and institutional print departments balance security requirements against outsourcing economics. Financial services firms in London and Frankfurt retain secure monochrome laser fleets for client document production.
Revenue concentrates with Commercial Printing; margin expansion favors In-house Printing.
Technology:
Energy source and ink delivery architecture determine compliance posture and operating cost structure across regulatory jurisdictions.
- Thermal Transfer:Wax or resin ribbon melting onto substrate surfaces produces durable barcode and label output. Logistics hubs in the Netherlands and Belgium specify these systems for shipping compliance where mechanical abrasion resistance is mandatory.
- LED:Solid-state ultraviolet curing replaces mercury arc lamps, narrowing energy footprints and eliminating F-Gas regulatory exposure. Signage producers in France and Germany accelerate adoption as EU Ecodesign deadlines approach.
- Continuous Ink Supply:Bulk ink reservoir architectures decouple cartridge replacement frequency from print volume. Bangladesh and Vietnam textile printers deploy these systems for direct-to-fabric production where dye consumption scales with fashion cycle volatility.
- Solid Ink:Wax-based block formulations melt and jet without liquid ink logistics or drying time. Environmental claims around cartridge-free waste streams attract sustainability-focused buyers in Scandinavian public sector procurement.
Installed base favors Thermal Transfer; regulatory pressure accelerates LED.
Application:
Substrate handling requirements and color precision demands segment this category more than print speed or volume metrics.
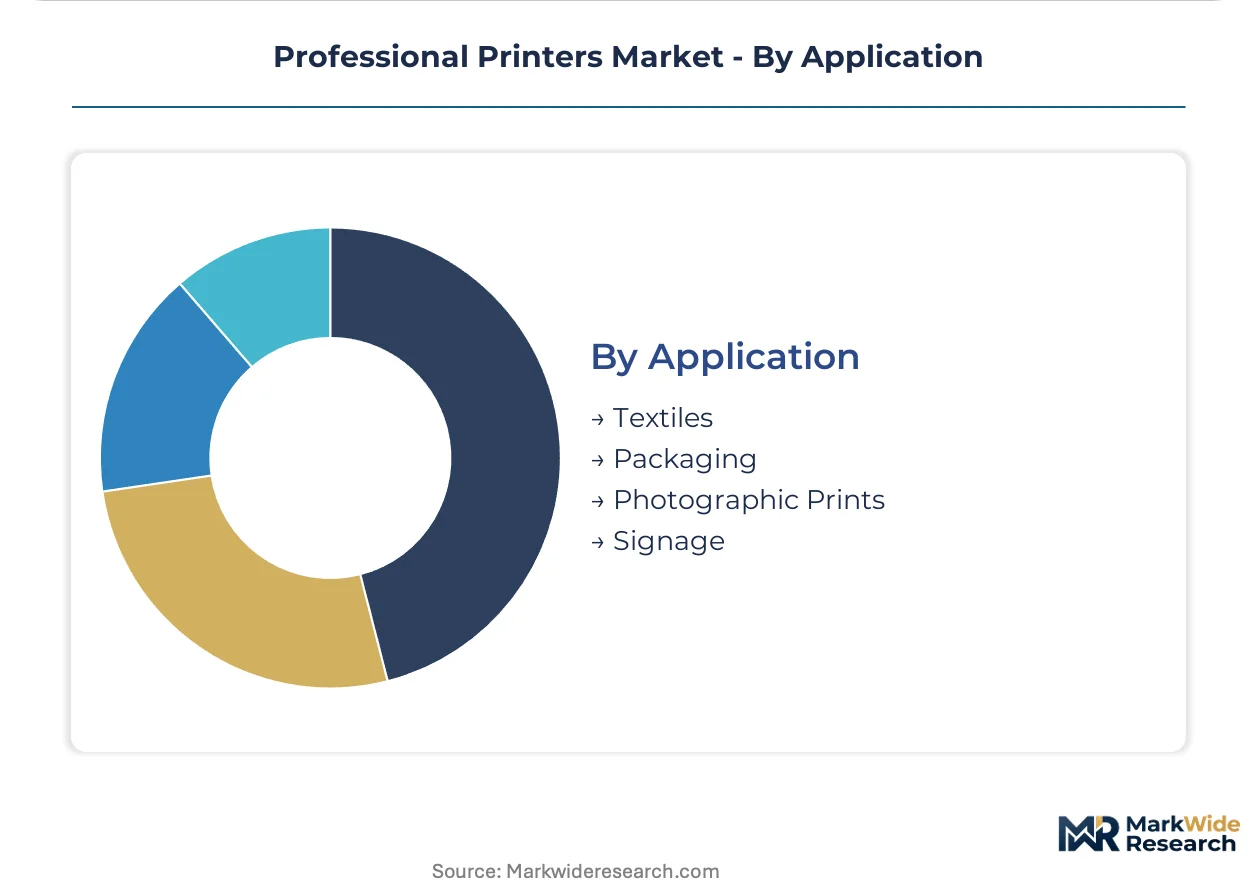
- Textiles:Direct-to-garment and direct-to-fabric systems deposit reactive, acid, or disperse dyes onto cotton, silk, and polyester. Apparel hubs in Vietnam and Bangladesh displace rotary screen methods for runs under 500 units.
- Packaging:Corrugated, folding carton, and flexible film printing demands food-safe ink formulations and substrate adhesion. German converters consolidate vendor relationships around service-integrated supply contracts spanning equipment and consumables.
- Photographic Prints:Archival pigment and silver-halide output serves fine art, wedding, and commercial photography markets. Japanese consumers sustain demand for physical print formats despite digital display proliferation.
- Signage:Wide-format UV and solvent inkjet systems produce durable outdoor graphics on vinyl, mesh, and rigid substrates. US Midwest municipalities refresh transit shelter advertising through local print service providers.
Revenue weight rests with Packaging; steepest expansion trajectory belongs to Textiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toner resin production concentrates in Japan and Germany, anchoring supply-side investment decisions for professional imaging equipment across major demand centers.
United States
Commercial print service providers in the Midwest refresh aging electrophotographic fleets ahead of EPA Energy Star Version 3.0 standby power mandates. The Department of Energy tightens efficiency specifications for imaging equipment sold through federal procurement channels. Chicago-area copy center chains consolidate vendor relationships around predictive maintenance subscriptions to minimize retrofit downtime.
Germany
Packaging converters along the Rhine-Ruhr corridor drive specification requests for LED-curing wide-format systems as EU F-Gas phase-down schedules accelerate. The Federal Environment Agency enforces Ecodesign requirements that constrain toner cartridge material recovery rates. Düsseldorf-based industrial print clusters negotiate enterprise-wide supply agreements bundling equipment, consumables, and service response guarantees.
China
Domestic efficiency benchmarks under dual carbon goals tighten market access for imported imaging equipment lacking local LED-curing certification. The Ministry of Ecology and Environment implements stricter energy-labeling standards for commercial reproduction systems. Pearl River Delta packaging hubs shift procurement toward locally assembled piezoelectric inkjet platforms with captive ink supply architectures.
Japan
Photography studios sustain demand for dye-sublimation and archival pigment systems despite digital display proliferation. METI enforces top-runner efficiency benchmarks that OEMs must meet for domestic market access, narrowing specification gaps between regional product variants. Tokyo-Osaka corridor equipment distributors emphasize color management training programs to address technician scarcity in expanded-gamut workflows.
India
Tier-two commercial print shops adopt consolidated all-in-one architectures to minimize capital outlay and floor space constraints. The PLI scheme for electronics manufacturing attracts component localization investments for inkjet printhead assembly and LED curing module production. Maharashtra and Gujarat industrial zones host emerging direct-to-fabric textile printing operations displacing rotary screen methods for short-run apparel cycles.
Professional Printers Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized deposition niches and regional service integration. Japanese and Korean captive supply chains dominate piezoelectric actuator and precision printhead production, exposing non-integrated competitors to allocation risk. Three archetypes define competitive positioning: vertically integrated imaging conglomerates controlling upstream component supply; regional specialists concentrating on substrate-specific applications; and software-centric vendors capturing recurring revenue through cloud-based color management subscriptions. Consolidation through strategic partnerships and backward integration into consumables formulation represent the dominant competitive moves across the analysis window.
Within the integrated imaging tier, HP exemplifies vertical control across thermal inkjet architectures, while Canon occupies a position anchored in photography studio specialization. Epson represents the precision micro piezo archetype dominating wide-format signage applications. Brother Industries sits within the office-centric electrophotographic segment where total cost-per-page economics govern procurement decisions. Fujifilm exemplifies the chemical formulation specialist pursuing aqueous pigment advances for uncoated paper direct printing.
| Leading Market Players |
|---|
| Brother Industries |
| Oce |
| HP |
| KIP |
| Mutoh |
| Canon |
| Fujifilm |
| Pantum |
| Epson |
| Others |
Supply Flow & Price Mechanics
Petrochemical feedstock volatility cascades through toner resin and ink formulation costs, compressing margin predictability for commercial print service providers while forcing OEMs to stratify equipment pricing across premium certified, standard efficiency, and economy-tier configurations.
Pricing Analysis
Warranty and service-bundling arrangements separate premium-tier procurement from unbundled economy purchases, with German packaging converters negotiating enterprise-wide supply contracts that wrap predictive maintenance and consumables replenishment into per-impression pricing. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by Energy Star certification grade and LED-curing compliance status. Pricing pressure stems from pulp and substrate cost swings that compress fixed-contract margins for commercial print service providers. Copy center franchise networks exhibit highest price sensitivity due to standardized fleet refresh cycles, while photography studios prioritize color gamut performance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German industrial packaging clusters, while authorized dealer networks serve fragmented copy center and small commercial print segments across North American and European markets. Toner resin production concentrates in Japan and Germany, with piezoelectric printhead supply anchored in Japanese and Korean captive manufacturing facilities. Raw material dependencies span petroleum-derived toner polymers, rare-earth elements for LED curing modules, and specialized substrate coatings. Single-source vulnerability in piezoelectric actuator architectures exposes non-integrated OEMs to allocation risk during semiconductor cycle tightness. Distribution runs through manufacturer-certified dealer programs that capture recurring service revenue beyond equipment margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Printhead fabrication capacity constraints in Japanese and Korean captive facilities prop pricing power for vertically integrated OEMs, sustaining margin premiums despite downstream cost compression.
For Market Incumbents: To counter emerging aqueous pigment specialists threatening uncoated paper direct printing applications, incumbents should accelerate backward integration into LED curing module production and secure captive ink formulation capacity in China to satisfy dual carbon certification requirements. Channel control through exclusive dealer certification programs represents a critical defensive lever against independent service-integrated supply contracts. For New Entrants and Emerging Players: The price-point gap between premium-tier production inkjet and economy-tier refurbished electrophotographic equipment creates entry space for mid-market LED-curing specialists targeting India's tier-two commercial print shops. White-space targets include direct-to-fabric textile printing in Bangladesh and Vietnam apparel hubs, plus managed print service wraps for Scandinavian public sector procurement. A cloud-based color management subscription model enables recurring revenue capture without heavy manufacturing capital. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with established service integration capabilities in Germany's Rhine-Ruhr corridor, where packaging converter consolidation demands bundled equipment-consumables-maintenance offerings. Long-term viability hinges on compliance engineering capacity for evolving EU F-Gas and PFAS restriction schedules. The signal to monitor is LED-curing certification adoption rates across Chinese domestic OEMs as a proxy for import displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Printhead Production | Japanese and Korean captive supply chains expose non-integrated competitors to semiconductor cycle allocation risk. |
| LED Curing Module Localization | China's dual carbon certification requirements tighten market access for imported imaging equipment lacking domestic assembly. |
| Service-Integrated Supply Contracts | German packaging converters consolidate vendor relationships around bundled equipment, consumables, and predictive maintenance. |
| Cloud-Based Color Management Subscriptions | Software-defined value capture reshapes competitive positioning beyond hardware differentiation across commercial print segments. |
| PFAS-Compliant Fuser Roller Development | Emerging substance restrictions threaten legacy laser fleet service part availability and long-term maintenance economics. |
Methodological Framework
Independent corroboration across OEM product management interviews, dealer network operational assessments, and packaging converter procurement director consultations underwrites the qualitative findings in this study. Primary fieldwork engaged commercial print service providers, copy center franchise operators, photography studio owners, and in-house corporate print managers across Germany, the United States, China, Japan, and India. Secondary validation drew from EPA Energy Star certification databases, EU Ecodesign regulatory filings, METI efficiency benchmark publications, and customs trade records for imaging equipment imports. Bottom-up equipment shipment analysis and top-down consumables revenue triangulation anchor the market sizing framework.
Rate-of-change decomposition across technology transitions, regulatory compliance deadlines, and substrate cost cycles informs the projection methodology. Segmentation modeling spans product type, end user category, technology architecture, and application vertical, with additional granularity for regional certification requirements and service integration penetration. CAGRs were derived from installed base turnover velocity and replacement demand elasticity rather than extrapolated trend fitting. Industry-specific forecast inputs include LED-curing adoption curves in EU signage markets and piezoelectric inkjet displacement rates in textile digitalization hubs.
Inputs from OEM disclosure filings and national energy regulator certification lists were available through the study window; gaps in proprietary consumables pricing data and regional dealer margin structures introduce uncertainty bands around segment-level value estimates. Forecasts reflect assumptions regarding F-Gas phase-down enforcement consistency, semiconductor fabrication capacity normalization, and pulp feedstock price stabilization. Periodic stress-testing of base assumptions against regulatory acceleration or supply chain disruption scenarios is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Digital Franking Machine Market
Printing Technology
Digital Paper System Market
Printing Technology
Digital Pattern Generator Market
Printing Technology
Global Barcode Printer Market
Printing Technology
Global Wireless Printers Market
Printing Technology
Managed Print Services Market
Printing Technology
Large Character Printers Market
Printing Technology
Variable Data Printing Market
Printing Technology
Digital Presses Market
Printing Technology
US Print on Demand Market
Printing Technology
Photo Printing and Merchandise Market
Printing Technology
GCC Digital Printing Market
Printing Technology
Book Printing Service Market
Printing Technology
Global Point of Sale (Pos) Receipt Printer Market
Printing Technology
Point of Sale (Pos) Printers Market
Printing Technology
Digital Fabric Printer Market