
 Global Barcode Printer Market | 2026-2036
Global Barcode Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Barcode Printer Market Foresight
Asset-light leasing models for industrial print fleets is narrowing the capital barrier for mid-sized logistics firms entering automated labeling. Zebra Technologies Corporation leverages its captive financing arm to bundle hardware with managed print services. SATO Holdings Corporation anchors its competitiveness through deep specialization in RFID-enabled barcode hybrid systems for automotive supply chains. Toshiba Tec Corporation competes on manufacturing scale, operating dedicated thermal printhead foundries that reduce component lead times.
A barcode printer is an electromechanical device that applies variable data—typically linear or two-dimensional symbologies—onto substrates using thermal, impact, or ink-based methods, with print resolutions ranging from 203 to 600 dots per inch depending on application fidelity requirements. Its primary commercial purpose is to encode product identity, lot numbers, and tracking identifiers for automated scanning across supply chain nodes. Thermal transfer technology dominates installed value due to its durability in chemical and abrasion environments, while direct thermal formats occupy high-turnover segments like shipping labels where archival life requirements are shorter. Wi-Fi connectivity is the fastest-growing technology dimension as warehouse management systems shift toward cordless floor layouts.
The US Food and Drug Administration enforces Unique Device Identification mandates that require healthcare facilities to deploy validated barcode labeling systems for medical devices, directly shaping product certification requirements. The European Chemicals Agency's REACH framework restricts certain substances in adhesive-backed label stocks, forcing substrate suppliers to reformulate thermal coatings. China's State Administration for Market Regulation enforces GB standards for electrical safety and electromagnetic compatibility in networked printing equipment. Stakeholders must monitor evolving interoperability standards between barcode hardware and enterprise resource planning platforms as cloud-native warehouse architectures proliferate.
Market Dynamics
E-commerce fulfillment networks are compressing printer replacement cycles as 24-hour delivery mandates force continuous uptime requirements across warehouse floors.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Energy efficiency mandates are accelerating thermal transfer printer refreshes across European distribution centers.
- Automotive supply chain traceability:Tier-one suppliers in Germany and Japan are deploying RFID-enabled hybrid systems for component-level tracking.
- Shenzhen electronics corridor:Export packaging demand from China's manufacturing belt sustains volume procurement of compact desktop units.
Market Restraints
- Thermal printhead supply concentration:Japanese and Korean component foundries create single-source vulnerability for industrial-grade units.
- Silicon wafer input volatility:Semiconductor substrate costs fluctuate with consumer electronics demand cycles.
- Direct thermal substitution ceiling:Short archival life limits penetration in pharmaceutical and chemical labeling.
Strategic Opportunities
- India's pharmaceutical export expansion:Cold-chain serialization mandates under CDSCO guidelines create first-time demand for validated thermal transfer systems.
- Cloud-native warehouse architectures:API-first printer management platforms enable hardware-as-a-service models for mid-market logistics operators.
- Brazil's ANVISA track-and-trace mandate:Serialized medicine packaging drives industrial printer deployment across Latin American distribution hubs.
Industry Challenges
- ISO 15415 print quality certification:Healthcare and aerospace buyers require third-party verification, extending sales cycles by 4-8 months.
- Legacy ERP integration friction:SAP and Oracle warehouse modules demand custom middleware development for cordless printer fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Barcode Printer Market |
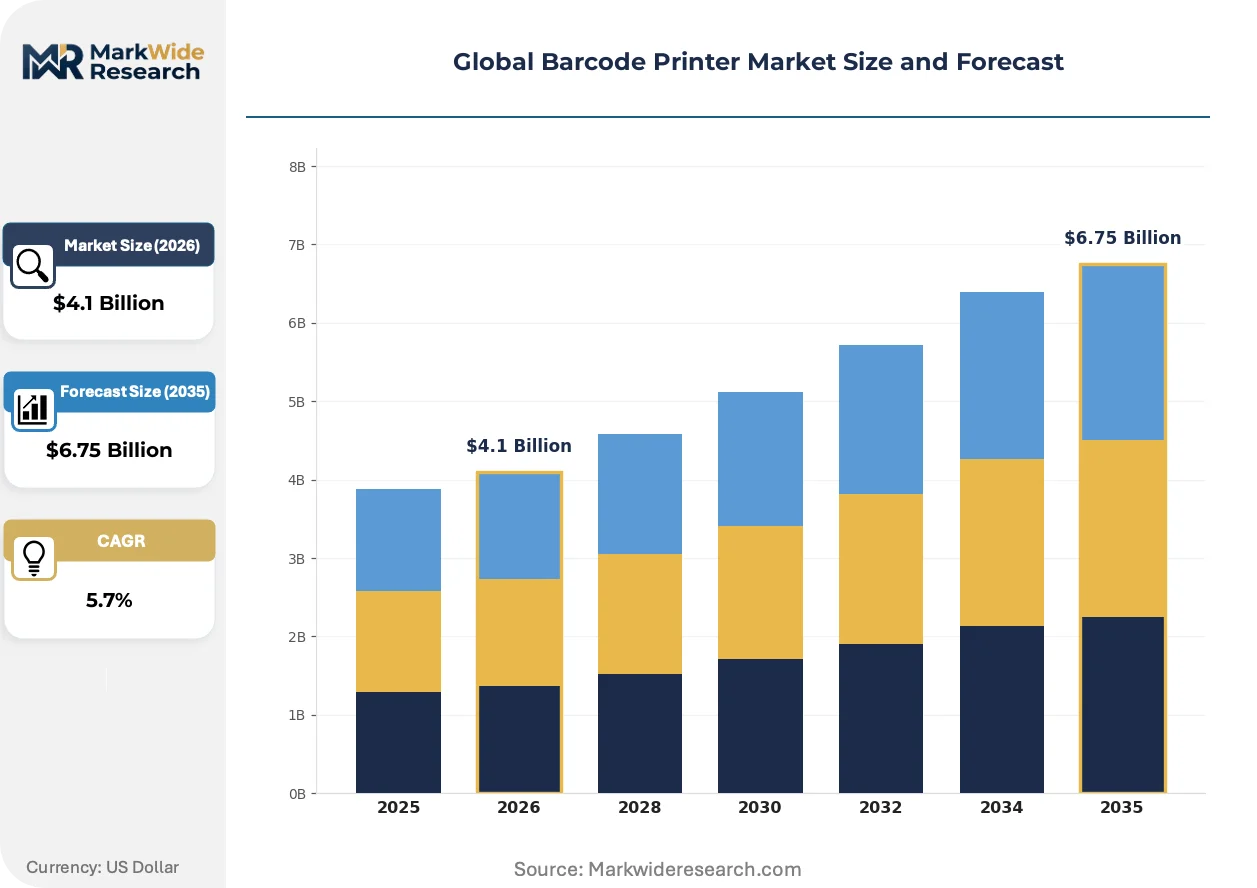
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.75 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Transfer, Direct Thermal, Inkjet, Laser, Dot Matrix Technology: Wi-Fi, Bluetooth, USB, Ethernet, NFC, Serial Application: Supply Chain Management, Asset Tracking, Postal & Courier, Healthcare Facilities, Manufacturing Plants End User: Retail Chains, Warehousing Units, Educational Institutions, Food Service Providers, Logistics Firms |
| Companies Covered | Zebra Technologies Corporation, SATO Holdings Corporation, Toshiba Tec Corporation, Honeywell International Inc., TSC Auto ID Technology Co. Ltd., Avery Dennison Corporation, Canon Inc., Oki Electric Industry Co. Ltd., Dascom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Barcode Printer Market Shifts & Advancements
Barcode printing infrastructure is fragmenting across connectivity standards as warehouse operators decouple hardware from fixed network topologies.
Direct thermal printing is migrating from stationary desktop configurations to mobile cart-mounted units in high-velocity picking zones. Third-party logistics providers in the Netherlands and Singapore are deploying battery-powered units for aisle-side label generation. This shift is compressing the addressable market for traditional fixed-installation equipment.
REACH framework restrictions on adhesive-backed label stocks are forcing substrate suppliers to reformulate thermal coatings across European supply chains. Chemical manufacturers must certify alternative adhesive compositions before Q3 compliance deadlines. Healthcare device labeling faces the steepest reformulation timeline due to FDA-EMA dual filing requirements.
Mid-sized logistics operators are unbundling hardware ownership from consumables procurement, favoring per-label pricing contracts with managed service overlays. This model displaces capital expenditure approval bottlenecks in German and US regional distribution networks. Equipment financiers are capturing margin previously held by distributor channels.
Global Barcode Printer Market Segmentation
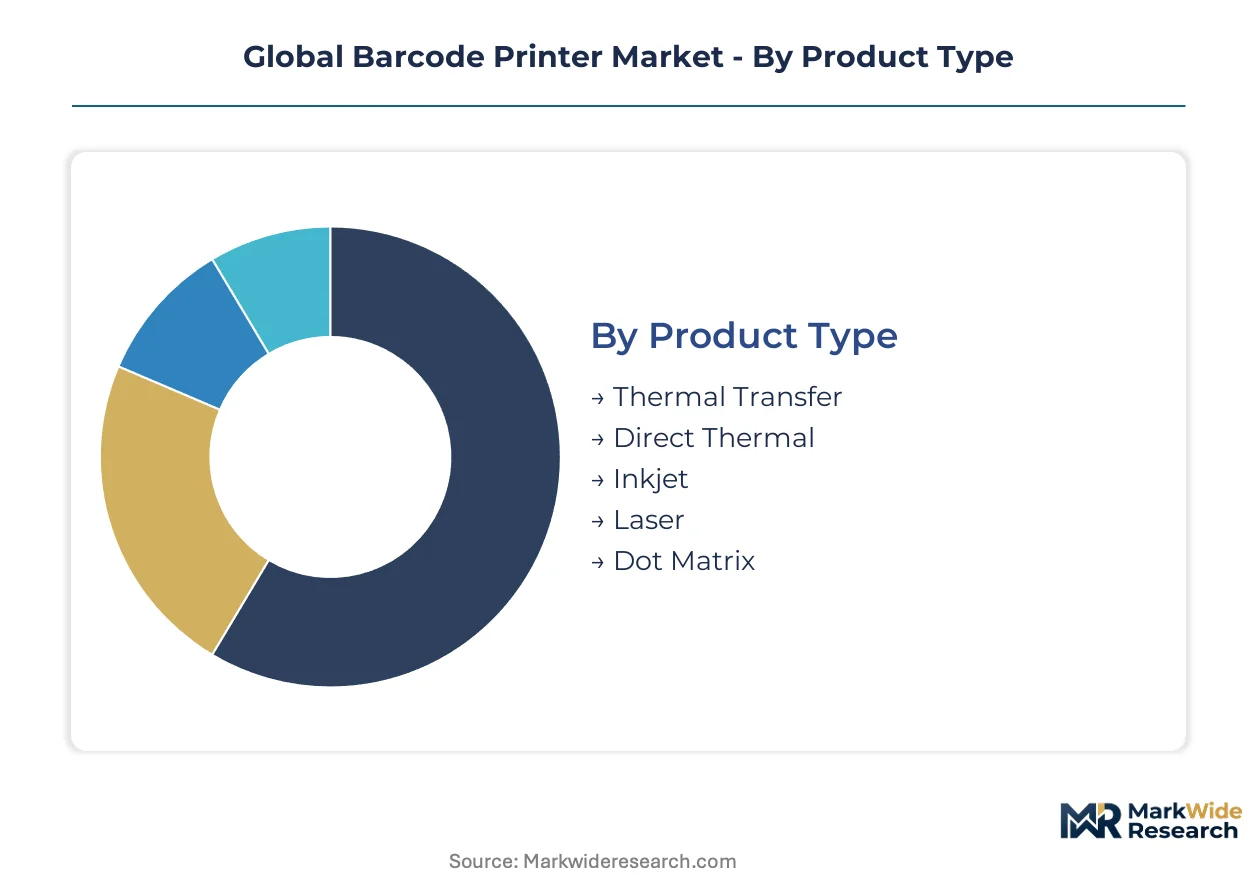
Barcode printer procurement patterns diverge sharply across technology tiers and operational contexts. Thermal transfer systems command premium positioning in chemical-exposed environments. Direct thermal formats dominate high-turnover shipping corridors where label longevity requirements remain minimal.
Product Type:
Cost tier stratification separates archival-grade systems from disposable-label economics across industrial procurement.
- Thermal Transfer:Ribbon-based imaging deposits resin or wax coatings onto synthetic substrates, achieving 5-10 year legibility in solvent and UV exposure. Demand concentrates in German automotive supply chains where component traceability mandates survive harsh manufacturing environments.
- Direct Thermal:Heat-sensitive paper darkens without consumable ribbons, reducing per-label cost by 40-60% versus thermal transfer. E-commerce fulfillment centers in the Netherlands and Singapore deploy these units for 24-hour shipping labels where archival life requirements span days rather than years.
- Inkjet:Piezoelectric drop-on-demand systems apply aqueous or solvent-based inks onto porous and non-porous surfaces. Food service providers leverage this flexibility for direct-case marking in cold-chain distribution.
- Laser:Electrophotographic toner fusion delivers 1200+ dpi resolution for micro-labeling applications. Aerospace component manufacturers specify these systems for Data Matrix codes on space-constrained parts.
- Dot Matrix:Impact pin arrays transfer ink through multi-part forms, persisting in logistics firms requiring carbon-copy documentation for regulatory audit trails.
Thermal Transfer holds installed capacity. Direct Thermal is rotating up the share rankings.
Technology:
Connectivity architecture determines deployment flexibility across cordless warehouse floor plans.
- Wi-Fi:IEEE 802.11ac/ax protocols enable real-time print job queuing from cloud-native warehouse management systems. US-based third-party logistics operators are eliminating Ethernet drops in favor of roaming cart-mounted units.
- Bluetooth:Low-energy pairing suits mobile field service applications where smartphone-triggered label generation replaces dedicated handheld computers. Japanese automotive technicians deploy these configurations for roadside parts identification.
- USB:Wired host connectivity persists in fixed-station retail point-of-sale environments where transaction volume justifies dedicated cabling infrastructure.
- Ethernet:Power-over-Ethernet simplifies installation in warehousing units with existing structured cabling, though demand is plateauing as Wi-Fi coverage densities improve.
- NFC:Tap-to-pair authentication streamlines guest device onboarding in educational institutions where student-owned hardware requires temporary printing access.
- Serial:RS-232 legacy protocols maintain presence in manufacturing plants with 1990s-era programmable logic controllers requiring uninterrupted integration.
Ethernet maintains legacy footprint. Wi-Fi is climbing the fastest.
Application:
Application context dictates print speed, substrate durability, and symbology complexity requirements.
- Supply Chain Management:GS1-128 and SSCC encoding for pallet-level identification drives demand for 6-8 inch print widths in distribution hubs. China's cross-border e-commerce export corridors sustain volume procurement of industrial-grade units.
- Asset Tracking:IT equipment and facility infrastructure labeling requires tamper-evident substrates. Healthcare facilities specify these systems for FDA-mandated Unique Device Identification on capital equipment.
- Postal & Courier:High-velocity sortation demands 10+ inch-per-second print speeds with automatic cutter mechanisms. Last-mile delivery expansion in India and Brazil is accelerating compact desktop deployment.
- Healthcare Facilities:Patient wristband and medication labeling requires antimicrobial coating compatibility. EMA and FDA dual filing requirements constrain substrate selection for European and US export markets.
- Manufacturing Plants:Work-in-process tracking integrates barcode printers with meso-level production execution systems. Automotive tier-one suppliers in Germany and Japan favor RFID-enabled hybrid configurations.
Supply Chain Management anchors volume. Healthcare Facilities is gaining share fastest.
End User:
Customer type determines procurement authority structure and service contract preferences.
- Retail Chains:Shelf-edge and promotional labeling demands color-capable systems for markdown agility. European fast-fashion operators are testing managed print services to unbundle hardware ownership from consumable replenishment.
- Warehousing Units:24-hour operational mandates drive premium service contracts with 4-hour response guarantees. US regional distribution networks are adopting per-label pricing models to bypass capital expenditure approval cycles.
- Educational Institutions:Library asset management and student ID issuance favor desktop units with low total cost of ownership. Budget constraints favor USB-connected configurations over networked alternatives.
- Food Service Providers:Prep-date and allergen labeling requires direct thermal units with food-safe adhesive compliance. REACH framework restrictions on substrate formulations are forcing supplier transitions across European operations.
- Logistics Firms:Multi-client fulfillment demands printer fleets with rapid format changeover capabilities. Asset-light leasing models are narrowing capital barriers for mid-sized operators entering automated labeling.
Warehousing Units dominate installed base. Logistics Firms is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority concentrates with warehousing operators and pharmaceutical serialization mandates across distinct national regulatory environments. Demand patterns diverge sharply between export-manufacturing corridors and import-heavy distribution economies.
United States
FDA Unique Device Identification mandates drive healthcare facility upgrades for validated barcode systems. Third-party logistics operators eliminate fixed Ethernet infrastructure in favor of roaming Wi-Fi cart configurations. Chicago and Dallas distribution corridors sustain premium service contract demand with 4-hour response guarantees.
Germany
Automotive tier-one suppliers deploy RFID-enabled hybrid systems for component-level traceability under EMA quality frameworks. REACH adhesive restrictions force substrate reformulation across thermal coating supply chains. Stuttgart and Wolfsburg manufacturing belts anchor industrial-grade thermal transfer procurement.
China
SAMR enforces GB standards for electrical safety and electromagnetic compatibility in networked printing equipment. Cross-border e-commerce export corridors sustain volume procurement of compact desktop units. Shenzhen's electronics manufacturing belt drives procurement for export packaging applications.
India
CDSCO cold-chain serialization mandates create first-time demand for validated thermal transfer systems in pharmaceutical exports. Last-mile delivery expansion accelerates compact desktop deployment across courier networks. Mumbai and Hyderabad distribution hubs concentrate procurement authority for mid-sized logistics operators.
Brazil
ANVISA track-and-trace mandates for serialized medicine packaging drive industrial printer deployment across Latin American distribution hubs. Regional distribution networks adopt per-label pricing models to bypass capital expenditure approval cycles. São Paulo state anchors volume procurement for pharmaceutical labeling compliance.
Global Barcode Printer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent go-to-market economics. The vendor base separates into consolidated equipment financiers with captive leasing arms and specialized component fabricators with deep thermal printhead expertise. Two strategic archetypes dominate: asset-light service bundlers and vertically integrated manufacturing-scale operators. Competitive moves concentrate on strategic partnerships for cloud-native warehouse integration and geographic expansion into pharmaceutical serialization corridors.
Within the financing-integrated tier, Zebra Technologies Corporation and SATO Holdings Corporation exemplify channel-control strategies that bundle hardware with managed print services. Toshiba Tec Corporation anchors the manufacturing-scale archetype through dedicated thermal printhead foundry operations. Honeywell International Inc. occupies a diversified industrial technology position that spans barcode hardware within broader automation portfolios. These three company structures represent the dominant competitive configurations shaping procurement relationships with mid-sized logistics operators and healthcare facility buyers.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| SATO Holdings Corporation |
| Toshiba Tec Corporation |
| Honeywell International Inc. |
| TSC Auto ID Technology Co. Ltd. |
| Avery Dennison Corporation |
| Canon Inc. |
| Oki Electric Industry Co. Ltd. |
| Dascom |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese thermal printhead foundries is compressing component margins and forcing Japanese suppliers toward premium positioning through extended service bundling. This utilization imbalance feeds downstream pricing fragmentation, where warehousing operators extract per-label concessions while healthcare buyers absorb certification premiums.
Pricing Analysis
Certification level (ISO 15415/FDA-grade/CE-marked) creates the primary spread between industrial-grade thermal transfer systems and desktop shipping-label units. Three-tier pricing structure across validated healthcare systems, standard logistics fleets, and economy desktop configurations dominates procurement. Cost compression in the mid-tier logistics segment is intensifying because per-label managed service contracts displace capital expenditure models. Third-party logistics operators exhibit the highest price sensitivity due to thin fulfillment margins, while pharmaceutical serialization mandates render healthcare buyers relatively inelastic.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for Japanese and Korean thermal printhead suppliers serving European OEMs. Component fabrication concentrates in Japan, South Korea, and coastal China, with final assembly drawing from Shenzhen and Dongguan electronics corridors. Silicon wafer substrates, ceramic heater elements, and precision stepper motors constitute critical input dependencies. Single-source vulnerability for industrial-grade printheads creates structural exposure to regional disruption. Distribution runs through authorized distributor networks with captive financing arms rather than direct manufacturer-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of validated thermal printhead engineering talent constrains rapid capacity scaling, making specialized fabrication expertise the decisive competitive moat. This capability gap favors incumbents with captive foundry operations while raising barriers for assembly-only market entrants.
For Market Incumbents: Harden defensive positioning by deepening backward integration into ceramic heater element production, reducing exposure to Korean component volatility. Anchor channel control through captive financing arms that bundle hardware with consumables replenishment, displacing distributor margin capture. Prioritize ISO 15415 certification investment to extend healthcare sales cycles into sticky long-term service relationships.
For New Entrants and Emerging Players: India's pharmaceutical export corridor offers the most penetrable white-space, where CDSCO serialization mandates outpace local thermal transfer supply capacity. Target cloud-native warehouse management system integrators as channel partners, embedding API-first printer management into platform offerings. Pursue asset-light hardware-as-a-service models to bypass capital expenditure approval bottlenecks in mid-sized logistics operators.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated manufacturing-scale operators with captive thermal printhead foundries and established healthcare certification pathways. Long-term viability hinges on sustained pharmaceutical serialization mandates and automotive traceability expansion. Watch for inflection signals in cloud-native warehouse architecture adoption rates, which accelerate hardware-as-a-service transition and compress traditional distributor relevance.
| Strategic Initiative | Industry Significance |
|---|---|
| RFID-Enabled Hybrid System Development | Automotive tier-one suppliers in Germany and Japan require component-level traceability compliance. |
| Cloud-Native API Integration | Warehouse management system decoupling enables cordless floor layouts and roaming cart deployment. |
| Per-Label Managed Service Transition | Mid-sized logistics operators bypass capital expenditure approval cycles through operational expenditure models. |
| Thermal Printhead Foundry Expansion | Captive component production reduces lead time exposure to Japanese and Korean supply concentration. |
| REACH-Compliant Substrate Reformulation | European adhesive-backed label stocks must meet ECHA chemical restrictions by Q3 compliance deadlines. |
Research Methodology
Cross-validation between primary interviews with warehouse operations directors, biomedical engineering managers at healthcare systems, thermal printhead procurement leads, and logistics fleet managers anchors the qualitative findings. Secondary validation draws from FDA Unique Device Identification guidance documents, ECHA REACH substance restriction updates, SAMR GB standard filings, and customs trade data for thermal printing equipment. Bottom-up demand modeling from end-user procurement patterns triangulates against top-down supply-side capacity assessments across Japanese, Korean, and Chinese manufacturing clusters.
Calibration against historical replacement cycle data and regulatory mandate implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions span product type (thermal transfer, direct thermal, inkjet, laser, dot matrix), connectivity technology (Wi-Fi, Bluetooth, Ethernet, USB, NFC, serial), application context (supply chain, healthcare, manufacturing, postal, asset tracking), and end-user archetype (retail chains, warehousing units, logistics firms, food service, education). CAGR derivation rests on installed base turnover rates, e-commerce fulfillment center expansion trajectories, and pharmaceutical serialization compliance deadlines. Forecast inputs include thermal printhead foundry utilization rates and cloud-native warehouse management system penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese component assemblers or unexpected REACH enforcement acceleration would shift outcomes. Macroeconomic deviation in semiconductor substrate costs, regulatory expansion of serialization mandates beyond pharmaceuticals, or breakthrough displacement by digital watermarking alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
North America Commercial Printing Market
Printing Technology
Digital Paper System Market
Printing Technology
Cloud Print Market
Printing Technology
Industrial Printer Market
Printing Technology
Variable Data Printing Market
Printing Technology
Professional Printers Market
Printing Technology
Print on Demand Market
Printing Technology
Photo Printing and Merchandise Market
Printing Technology
Computer-To-Plate and Computer-To-Press Systems Market
Printing Technology
Card Printers Market
Printing Technology
Book Printing Service Market
Printing Technology
Global Point of Sale (Pos) Receipt Printer Market
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Card Printer Ribbons Market
Printing Technology
Automated Document Inserter (ADI) Market
Printing Technology
Inkjet Printhead Market