
 Web to Print Market | 2026-2036
Web to Print Market Size, Share, and Industry Trends Forecast 2026-2036
Web to Print Market Insights
The gap between premium custom-design platforms and commodity print-brokerage tiers is consolidating around software depth and fulfillment network density. Cimpress plc anchors the premium tier through proprietary manufacturing assets spanning multiple continents. Printful Inc. competes via vertically integrated fulfillment centers that shorten delivery windows for on-demand apparel and home goods. Gelato ASA differentiates through a distributed production model that positions micro-factories close to end consumers in urban European and North American markets.
Web to Print denotes a digital commerce architecture where buyers configure, visualize, and order printed products through browser-based interfaces connected to production management systems. The technology stack typically integrates HTML5 design tools, PDF/X-4 compliant preflight engines, and JDF-enabled workflow automation to bridge front-end customization with back-end digital presses. On-Demand Printing and Digital Printing command the highest margin pools as run lengths shrink and turnaround expectations compress. Variable Data Printing is accelerating fastest among technology segments, driven by hyper-personalized direct mail and packaging campaigns that require unique graphics per impression without stopping the press.
GDPR in Europe and the EU Green Deal's packaging waste directives are tightening data-handling and substrate-recovery requirements for web-to-print platforms serving cross-border e-commerce. The US EPA and state-level extended producer responsibility laws in California and New York are pushing print providers toward certified sustainable papers and vegetable-based inks. Stakeholders must monitor how regulatory fragmentation between EU Ecodesign standards and emerging US state rules reshapes platform compliance costs and supplier qualification criteria.
Market Dynamics
Cloud-native design-to-fulfillment workflows are compressing prepress timelines from days to hours, forcing legacy print management systems into obsolescence as browser-based configurators capture order intake directly from marketing teams.
Growth Catalysts
- GDPR-compliant data handling:European e-commerce platforms now mandate auditable personalization pipelines, driving Variable Data Printing adoption for cross-border direct mail campaigns requiring unique impressions per recipient.
- Apparel-on-demand fulfillment:Fashion retailers in urban North American markets are deploying micro-factory networks to collapse delivery windows for customized merchandise from weeks to 48 hours.
- EU Green Deal packaging mandates:Certified substrate recovery requirements are accelerating platform investments in vegetable-based ink workflows and closed-loop paper sourcing across German commercial print clusters.
Market Restraints
- Pigment and substrate cost volatility:Fluctuations in petroleum-derived ink feedstocks and certified sustainable paper supplies are compressing gross margins for mid-tier print brokerages without captive sourcing.
- Production concentration in Bavaria:Munich and Hamburg host disproportionate platform sophistication, creating geographic single-point-of-failure risk for pan-European fulfillment networks.
- PDF/X-4 preflight complexity:Legacy design files from non-compliant creative tools generate production errors that stall automated JDF workflow handoffs.
Strategic Opportunities
- Underpenetrated Indian e-commerce:Domestic marketplace sellers lack localized web-to-print infrastructure for regional-language marketing collateral, presenting white space for cloud-based configurators.
- Convergence of AI layout engines with HTML5 editors:Automated design assistance is lowering creative skill barriers for small business users who previously outsourced to agencies.
- California extended producer responsibility laws:State-level packaging waste rules are creating compliance-driven demand for certified sustainable print sourcing among US consumer brands.
Industry Challenges
- Preflight automation talent scarcity:Shortage of engineers proficient in JDF workflow orchestration and color management science is delaying platform modernization timelines.
- ISO 12647-2 certification bottlenecks:Extended audit cycles for process standardization are gating supplier qualification for enterprise accounts with stringent quality mandates.
- Legacy ERP integration friction:SAP and Oracle environments in established print houses resist API-based connectivity with cloud-native order management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Web to Print Market |
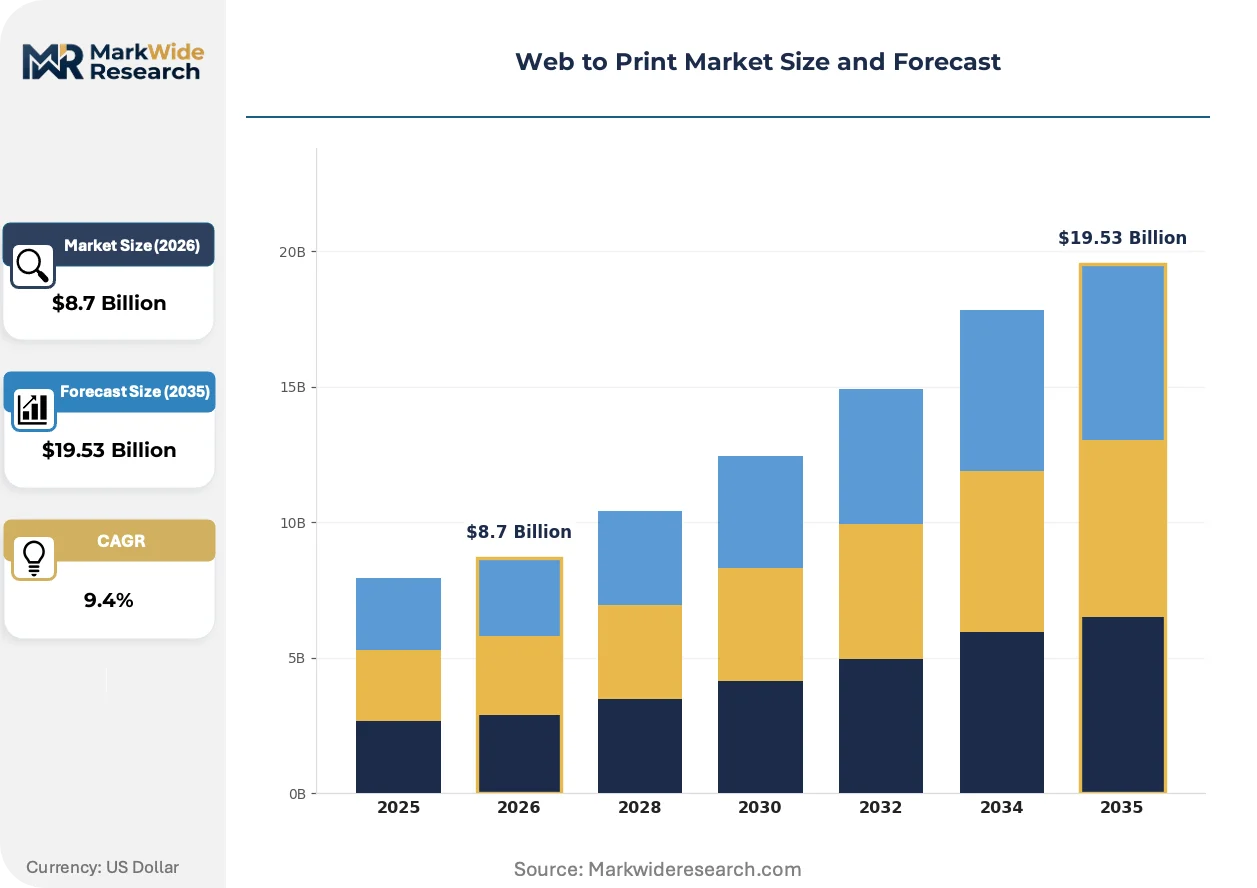
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-Demand Printing, Custom Design Services, Digital Printing, Offset Printing End User: SMEs, Large Enterprises, Advertising Agencies, Retailers Product Type: Brochures, Business Cards, Posters, Promotional Materials Technology: Inkjet, Laser, 3D Printing, Variable Data Printing |
| Companies Covered | Cimpress plc, Printful Inc., Zazzle Inc., Gelato ASA, Shutterfly, LLC, Electronics For Imaging Inc., CustomInk LLC, Design’N’Buy, Printify Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Web to Print Market Trends and Innovations
Artificial intelligence is rewriting the creative-production boundary. Automated layout generation, predictive color optimization, and real-time personalization engines are collapsing the traditional agency-to-press workflow into single-session browser experiences.
AI-driven design assistance is integrating natural language prompts with parametric template systems to generate print-ready artwork without manual file preparation. Mid-market retailers and franchise networks are adopting these tools fastest, replacing agency retainer relationships with self-service configuration. This compression is eliminating prepress bottlenecks that previously delayed campaign launches by days.
REACH substance restrictions and emerging EU Ecodesign standards for printed products are tightening chemical disclosure requirements across substrate and ink supply chains. Print providers must now document SVHC content down to the article level for cross-border shipments. Packaging and children's product categories face the steepest compliance ramps, with German and French markets enforcing earliest deadlines.
Buying patterns among enterprise marketing departments are rotating from annual print procurement contracts toward campaign-based micro-orders with 24-hour fulfillment expectations. Franchise systems and distributed sales organizations are displacing centralized print warehousing with on-demand production at edge locations. This behavioral shift is most visible in US and UK markets where real estate cost pressures make inventory holding uneconomical.
Web to Print Market Segmentation
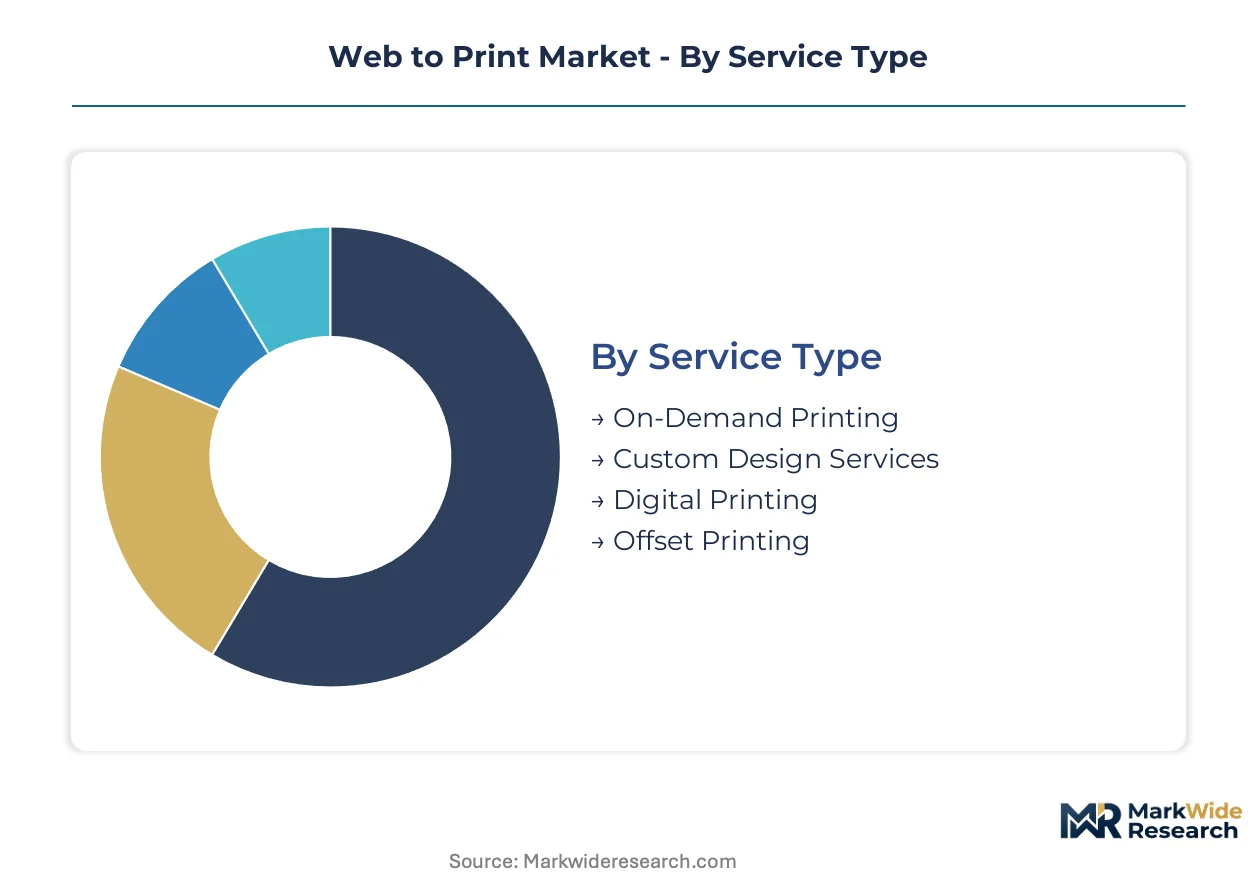
Web-to-print segmentation reveals how production workflows, compliance burdens, and customer scale intersect to determine platform architecture and margin structure. Buyers select service tiers based on run-length economics, while technology choices govern prepress automation depth and substrate flexibility.
Service Type:
Certification requirements vary sharply across service tiers, with GDPR-compliant Variable Data Printing demanding auditable data pipelines and ISO 12647-2 color certification, while commodity offset segments face lighter regulatory loads.
- On-Demand Printing:Short-run production workflows enabled by digital presses with JDF automation, compressing fulfillment windows from days to hours. Demand concentrates among franchise networks and distributed sales organizations in Germany and the United Kingdom, driven by inventory cost pressures and real-time campaign agility requirements.
- Custom Design Services:Template-based configuration tools with HTML5 editors and AI-assisted layout generation, bridging browser-based design with production-ready PDF/X-4 output. Advertising agencies in France and the Netherlands are adopting these platforms fastest, replacing traditional agency retainer models with self-service collateral production.
- Digital Printing:Toner and inkjet production methods for variable data and short-run applications.
- Offset Printing:Conventional lithographic workflows for longer runs with lower per-unit costs.
On-Demand Printing sits at the top of the volume ranking, with Custom Design Services climbing the fastest.
End User:
Customer scale determines order pattern density and platform integration complexity, with large enterprises requiring SAP-connected procurement systems while SMEs prioritize browser-based simplicity.
- SMEs:Fragmented buyer base with campaign-based micro-order patterns and 24-hour fulfillment expectations. These users dominate cloud-native platform adoption in India and Southeast Asia, where localized language support and low-touch onboarding drive platform selection.
- Large Enterprises:Centralized procurement with annual contract frameworks and stringent supplier qualification protocols. German automotive and industrial conglomerates anchor this segment, mandating ISO 12647-2 certification and REACH-compliant substrate documentation across pan-European fulfillment networks.
- Advertising Agencies:Creative intermediaries requiring white-label configurators and API-based workflow integration.
- Retailers:Franchise systems and multi-location merchants with localized marketing collateral needs.
Large Enterprises command the highest contract values, though SMEs are expanding most quickly as self-service tools lower entry barriers.
Product Type:
Physical form factor governs finishing equipment requirements and shipping economics, with dimensional constraints determining whether production localizes or centralizes.
- Business Cards:Standardized format with high personalization density, produced via sheet-fed digital presses or web-to-print aggregators. Demand clusters among professional services firms in London and New York, where real-time proofing and 48-hour delivery have become baseline expectations.
- Promotional Materials:Broad category spanning flyers, postcards, and direct mail with variable data integration. E-commerce marketplace sellers in California and Texas are driving adoption, responding to state-level extended producer responsibility laws that mandate certified sustainable paper sourcing.
- Brochures:Multi-page formats requiring binding and folding capabilities.
- Posters:Large-format output demanding wide-format inkjet or screen production.
Business Cards generate the highest transaction frequency, with Promotional Materials showing the steepest expansion trajectory.
Technology:
Print engine selection determines substrate range, color gamut, and automation compatibility, with regulatory chemical restrictions increasingly filtering equipment choices.
- Variable Data Printing:Database-driven impression customization without press stops, enabling hyper-personalized direct mail and packaging. GDPR-compliant deployments are accelerating across German and French markets, where cross-border campaigns require auditable recipient data handling and SVHC-free ink formulations.
- Inkjet:Piezoelectric and thermal drop-on-demand systems with aqueous, solvent, and UV-curable ink options. Water-based formulations are gaining share in Nordic markets ahead of REACH substance restriction deadlines, displacing solvent platforms in indoor signage applications.
- Laser:Electrophotographic toner systems with precise registration for corporate stationery.
- 3D Printing:Additive manufacturing for prototyping and limited production runs.
Inkjet holds the installed base lead, while Variable Data Printing is gaining share fastest as personalization mandates intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prepress automation engineers concentrate disproportionately in southern Germany and the Netherlands, anchoring European platform sophistication while cloud-native talent clusters in Bengaluru and Singapore drive Asian expansion.
United States
Franchise networks and distributed sales organizations demand 24-hour fulfillment for localized marketing collateral. California's extended producer responsibility laws mandate certified sustainable paper sourcing for e-commerce packaging. Dallas-Fort Worth and Atlanta host expanding micro-factory networks that collapse delivery windows for on-demand apparel.
Germany
Commercial print clusters in Munich and Hamburg drive the highest platform sophistication in European web-to-print. REACH substance restrictions and EU Green Deal packaging waste directives enforce vegetable-based ink workflows and closed-loop substrate recovery. Bavarian automotive conglomerates mandate ISO 12647-2 certification across pan-European fulfillment networks.
United Kingdom
Advertising agencies in London and Manchester replace traditional retainer models with self-service HTML5 configurators. GDPR-compliant Variable Data Printing pipelines require auditable recipient data handling for cross-border direct mail. The Southeast corridor concentrates AI-assisted layout generation adoption among mid-market retailers.
India
Domestic marketplace sellers lack localized web-to-print infrastructure for regional-language marketing collateral. The country's national electronics and IT ministry promotes cloud-based design tool adoption through digital infrastructure schemes. Bengaluru and Hyderabad anchor technical talent pools for JDF workflow automation development.
France
Fashion retailers deploy micro-factory networks to compress customized merchandise delivery from weeks to 48 hours. ANSM and CNIL enforcement of GDPR personalization pipelines accelerates Variable Data Printing for hyper-personalized packaging. The Île-de-France region hosts the steepest compliance ramps for SVHC-free ink formulations in children's product categories.
Web to Print Market Competitive Landscape
Top-tier vendors anchor proprietary manufacturing and distributed production networks, while mid-tier print brokerages compete on cloud-native workflow speed. The vendor base stratifies across three archetypes: vertically integrated fulfillment operators, software-centric platform providers, and hybrid design-to-fulfillment specialists. Consolidation pressure intensifies as JDF automation and ISO certification requirements raise capital barriers. Dominant competitive moves include geographic expansion of micro-factory networks and strategic partnerships with e-commerce marketplaces.
Within the vertically integrated tier, Cimpress plc and Printful Inc. exemplify divergent fulfillment philosophies. Gelato ASA occupies a position emphasizing distributed micro-factory proximity to urban consumers. These three entities represent the primary competitive anchors shaping service tier differentiation across North American and European markets.
| Leading Market Players |
|---|
| Cimpress plc |
| Printful Inc. |
| Zazzle Inc. |
| Gelato ASA |
| Shutterfly, LLC |
| Electronics For Imaging Inc. |
| CustomInk LLC |
| Design'N'Buy |
| Printify Inc. |
| Others |
Pricing and Supply Chain Analysis
Petroleum-derived pigment indices cascade through web-to-print supply chains, compressing margins for mid-tier brokerages without captive ink sourcing while amplifying pricing power for vertically integrated operators with backward integration into vegetable-based formulations.
Pricing Analysis
The bundled-vs-unbundled service split separates platform tiers sharply. Premium vendors package JDF automation, ISO 12647-2 certification, and SAP integration into subscription contracts. Price differentiation hinges on fulfillment network density and compliance documentation depth. Cost compression in commodity offset tiers intensifies as petroleum feedstock volatility passes through to spot pricing. SMEs exhibit highest price sensitivity, while German automotive conglomerates absorb premiums for REACH-compliant substrate traceability.
Supply Chain Analysis
Vegetable-based ink feedstocks rest on German and Dutch specialty chemical producers, with certified sustainable paper supplies drawing from Nordic and Canadian pulp networks. Pigment formulations, prepress automation hardware, and cloud-native design tool licenses constitute critical input dependencies. Single-source vulnerability concentrates in Bavarian prepress engineering talent pools. Distribution runs through direct platform portals for enterprise accounts, with aggregator marketplaces serving fragmented SME demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with procurement patterns shifting toward ISO-certified, REACH-compliant production specifications that favor vendors with documented substrate recovery and auditable personalization pipelines.
For Market Incumbents: Acquire JDF workflow automation engineering teams to close talent scarcity gaps. Consolidate micro-factory networks in underpenetrated Indian and Southeast Asian markets before cloud-native entrants establish localized language platforms. Defend against AI-assisted layout generation commoditization by embedding predictive color optimization into proprietary HTML5 configurators. Prioritize SAP and Oracle ERP certification investments to maintain enterprise procurement access. For New Entrants and Emerging Players: The mid-tier price-point gap between Cimpress-level premium bundling and commodity print brokerage offers white-space entry. Target India's regional-language marketplace sellers with low-touch onboarding and vernacular template libraries. Exploit California extended producer responsibility compliance demand with certified sustainable sourcing as the go-to-market anchor. Avoid direct confrontation with Gelato's distributed micro-factory density in established European urban corridors. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native platform providers possessing JDF orchestration capabilities and ISO 12647-2 certification pathways. Long-term viability favors vendors bridging AI-assisted design tools with production management systems across the 5-10 year technology refresh cycle. Watch for inflection where AI layout engines collapse agency retainer relationships into self-service configuration, accelerating platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| AI Layout Engine Integration | Automated design assistance collapses prepress timelines for mid-market retailers replacing agency relationships. |
| Micro-Factory Network Expansion | Geographic proximity to urban consumers compresses apparel fulfillment windows below 48 hours in North America. |
| REACH Compliance Certification | SVHC documentation down to article level gates supplier qualification for German and French children's product categories. |
| SAP ERP API Connectivity | Legacy system integration unlocks enterprise procurement contracts with Bavarian automotive conglomerates. |
| Regional Language Platform Localization | Vernacular template libraries capture Indian marketplace sellers lacking domestic web-to-print infrastructure. |
Research Methodology
Direct dialogue with prepress automation engineers, cloud platform product managers, print procurement officers at franchise networks, and REACH compliance consultants grounded qualitative findings. Secondary validation drew from SEC filings of publicly traded print technology vendors, EU Ecodesign regulatory databases, German commercial print cluster trade association reports, and customs data on certified sustainable paper imports. Bottom-up order volume estimates and top-down addressable market sizing were triangulated against disclosed platform transaction metrics.
Bottom-up modeling tracked order patterns across service tiers, end-user scale segments, and product categories throughout the forecast period. Segmentation dimensions included deployment model, fulfillment network architecture, compliance certification level, and regional regulatory cluster. CAGRs were derived from trend extrapolation of digital press installation rates and cloud-native platform adoption curves, with cross-checks against e-commerce marketplace seller growth and extended producer responsibility law implementation timelines.
Caveats apply where REACH substance restriction deadlines, EU Green Deal packaging waste directive enforcement intensity, or petroleum feedstock price volatility could materially shift the outlook. Assumptions underlying platform consolidation velocity and AI-assisted design tool penetration rates carry revision risk. A small set of named triggers—regulatory fragmentation between EU and US sustainability standards, JDF automation talent scarcity resolution, and ERP integration friction reduction—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Cloud Print Market
Printing Technology
Global Cloud Printing Services Market
Printing Technology
Global Computer to Plate Printing System Market
Printing Technology
Print on Demand Market
Printing Technology
Dye-Sublimation Printing Machines Market
Printing Technology
Large Format Printer Market
Printing Technology
Large Character Printers Market
Printing Technology
US Print on Demand Market
Printing Technology
Retail Printers Market
Printing Technology
Inkjet Printhead Market
Printing Technology
Barcode Printers and Consumables Market
Printing Technology
Hardcopy Peripherals and Printing Consumables Market
Printing Technology
Global RFID and Barcode Printer Market
Printing Technology
Digital Fabric Printer Market
Printing Technology
Variable Data Printing Market
Printing Technology
Global Point of Sale (Pos) Receipt Printer Market