
 Global Retail Core Banking Systems Market | 2026-2036
Global Retail Core Banking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Retail Core Banking Systems Market Outlook
Direct sales channels between core banking vendors and tier-one institutions is tilting toward subscription and managed-service models. Temenos leverages its cloud-native T24 Transact platform to sustain long-term client relationships across European and African markets. Fiserv competes through its DNA and Premier cores, anchoring community and regional banks with modular upgrade paths. Oracle differentiates via its Banking Cloud Suite, extending database and middleware dominance into financial services infrastructure.
Retail core banking systems constitute the integrated software backbone managing deposit accounts, lending operations, payment processing, and customer data for consumer-facing financial institutions, typically running on relational databases with real-time transaction posting and API-layer extensibility. Their primary commercial purpose is enabling institutions to process high-volume retail transactions while maintaining regulatory compliance and customer-facing digital channels. Cloud-based deployments are capturing the fastest expansion as neobanks and digital-first challengers reject on-premise capital intensity, while managed services generate recurring revenue pools that implementation projects cannot match. Hybrid architectures still occupy the largest installed base among commercial banks navigating phased legacy migration.
The European Banking Authority enforces PSD2 open-banking standards that mandate API accessibility, reshaping procurement toward interoperable platforms. India's RBI operates regulatory sandboxes permitting live testing of cloud core deployments, accelerating vendor qualification for domestic and foreign suppliers. The US OCC and FDIC supervise technology service provider relationships, embedding third-party risk management into core system selection criteria. Stakeholders must weigh sovereign data residency requirements against multi-cloud elasticity when evaluating deployment architecture.
Market Dynamics
Cloud-native architecture migration is collapsing the traditional five-year core banking replacement cycle, compressing vendor-client relationships into continuous upgrade streams and API-first interoperability mandates.
Growth Catalysts
- PSD2 Open Banking Mandates:The European Banking Authority's API accessibility requirements force incumbent institutions to modernize legacy infrastructure, creating procurement urgency for interoperable platforms.
- Neobank Proliferation:Digital-first challengers across Southeast Asia reject on-premise capital intensity, accelerating demand for elastic, containerized core deployments.
- India's Regulatory Sandbox:RBI-permitted live testing environments enable rapid fintech-bank collaboration, qualifying domestic and foreign suppliers for cloud core deployments.
Market Restraints
- Sovereign Data Residency Requirements:Multi-national institutions face architectural constraints when evaluating deployment options against data localization laws in Germany, India, and China.
- Legacy Integration Complexity:Hybrid architectures dominate commercial bank installed bases, creating technical debt that slows full cloud migration timelines.
- Third-Party Risk Management:US OCC and FDIC supervision of technology service provider relationships embeds extended due diligence into core system selection criteria.
Strategic Opportunities
- Brazil's Unbanked Population:Digital public infrastructure initiatives create white space for cloud-native cores targeting financial inclusion at scale.
- Embedded Finance Convergence:Banking-as-a-Service platforms integrating with e-commerce and logistics ecosystems open new revenue pools beyond traditional FI clients.
- Outcome-Based Pricing Models:Subscription and managed-service structures displace perpetual licenses, generating recurring revenue streams that implementation projects cannot match.
Industry Challenges
- Core Banking Talent Scarcity:Specialized engineering skills for real-time transaction posting and API-layer architecture command premium compensation, constraining vendor delivery capacity.
- Certification Timeline Compression:Regulatory sandbox programs accelerate go-live expectations while maintaining rigorous security and resilience standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Retail Core Banking Systems Market |
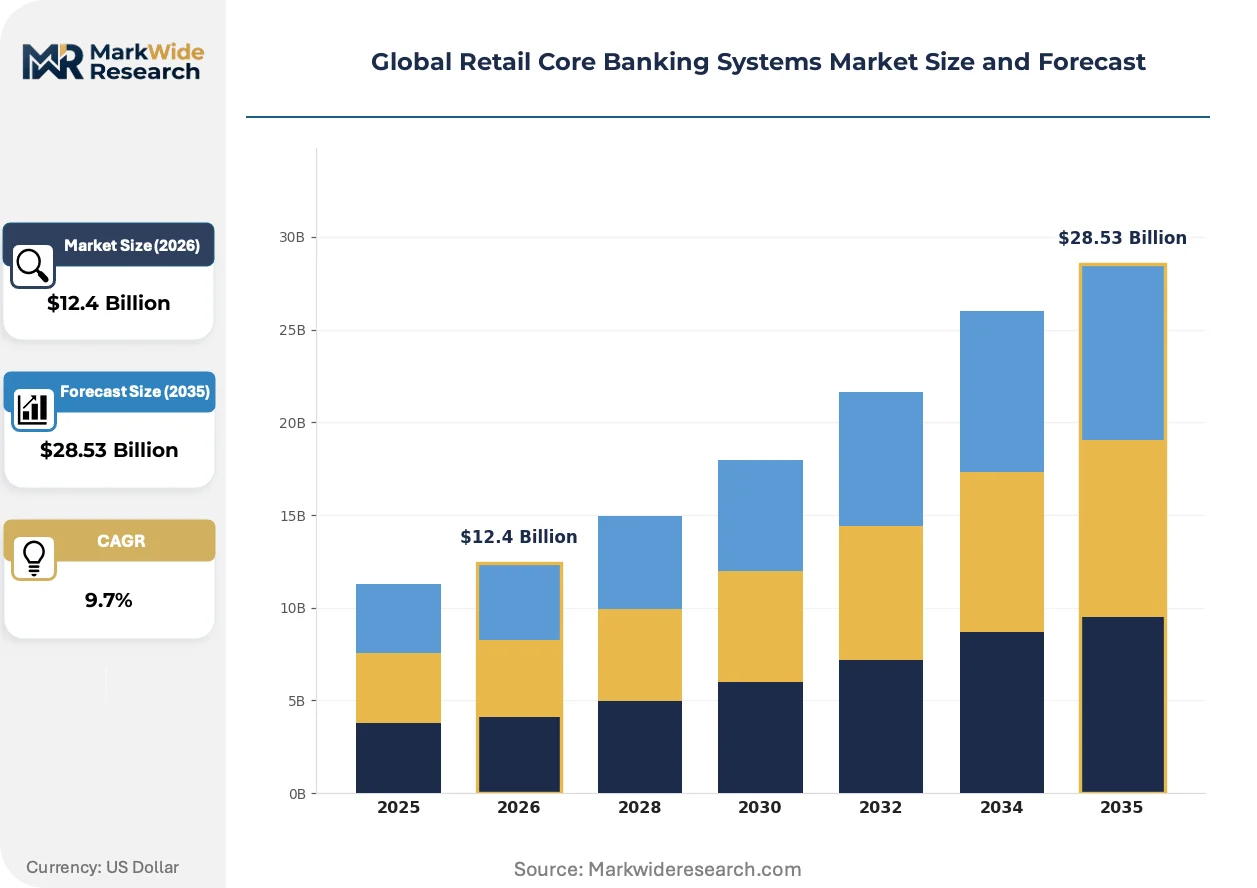
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.53 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: On-Premise, Cloud-Based, Hybrid, SaaS Service Type: Implementation, Maintenance, Managed Services, Consulting End User: Commercial Banks, Credit Unions, Online Banks, Neobanks Deployment: Private Cloud, Public Cloud, Multi-Cloud, Single-Tenant |
| Companies Covered | Temenos, Fiserv, FIS, Oracle, SAP SE, Tata Consultancy Services, Infosys, Finastra, Mambu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Retail Core Banking Systems Market Strategic Shifts
Real-time payment infrastructure and AI-native operations are rewriting the functional requirements for retail core platforms, shifting competitive advantage from batch processing scale to event-driven architecture responsiveness.
Containerized microservices architecture is collapsing the distinction between core banking and middleware layers, enabling neobanks in Indonesia and the Philippines to deploy full-stack platforms in months rather than years. This compression eliminates the traditional systems integration bottleneck, allowing direct vendor-to-bank relationships that bypass consulting intermediaries.
The EU AI Act's risk-based classification system for automated credit decisioning is forcing core vendors to embed algorithmic transparency and audit trails at the database layer. Institutions deploying machine learning for lending operations must now demonstrate explainability by design, reshaping procurement specifications toward platforms with built-in governance tooling.
Buyers are consolidating vendor relationships around integrated cloud suites that combine core processing with payments, risk, and customer engagement modules. Regional banks in the US Midwest and community institutions across Australia's eastern states favor single-stack solutions over best-of-breed integration, prioritizing operational simplicity over functional specialization.
Global Retail Core Banking Systems Market Segmentation
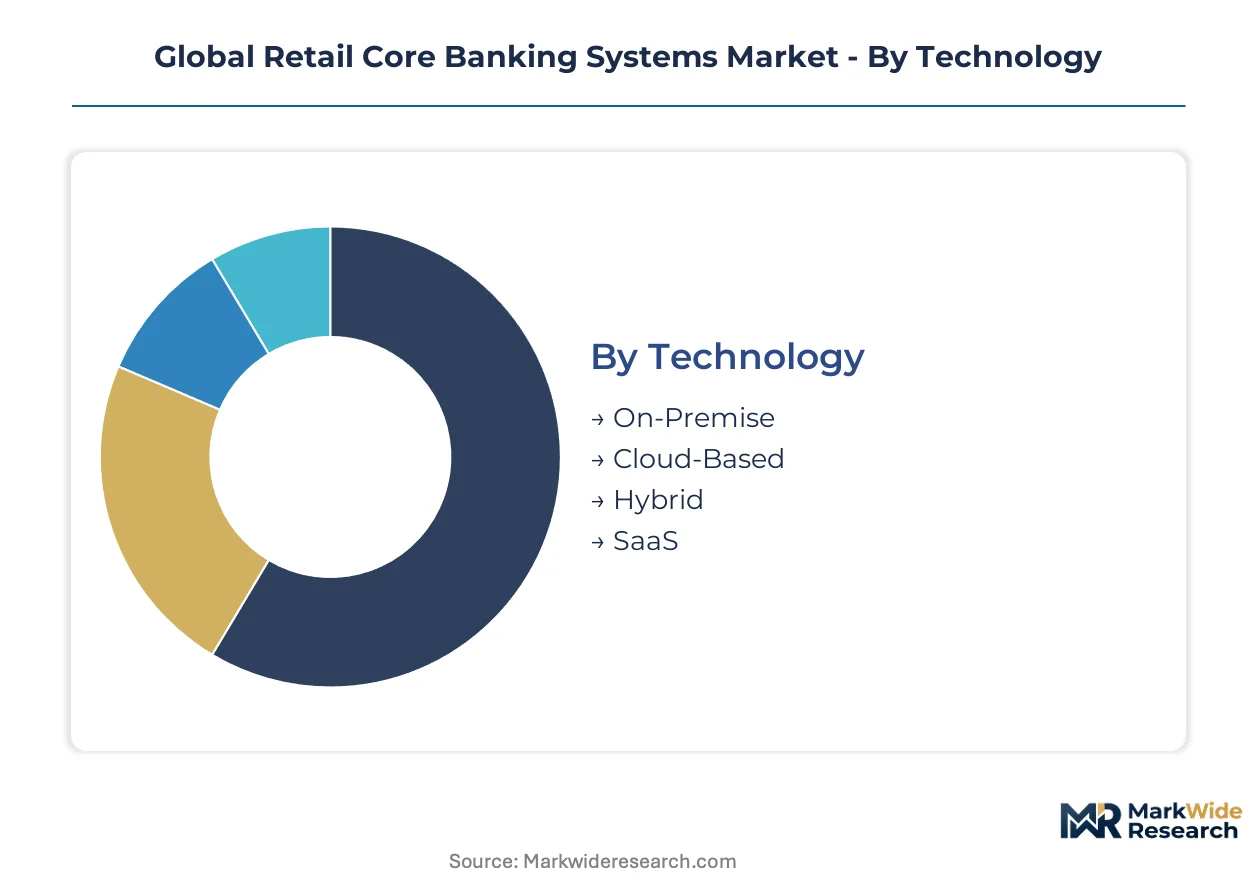
Retail core banking systems fragment across deployment architectures, service models, and institutional types. Each dimension carries distinct procurement patterns, regulatory constraints, and margin structures that reshape vendor positioning.
Technology:
Mature on-premise installations coexist with emerging cloud-native architectures across every geography.
- On-Premise:Legacy mainframe and client-server installations running on proprietary hardware stacks. Demand concentrates among tier-one institutions in Germany and Japan where data sovereignty laws and operational risk committees delay cloud migration timelines.
- Cloud-Based:Fully virtualized infrastructure with API-layer extensibility and elastic compute provisioning. Neobanks in Indonesia and the Philippines reject capital-intensive hardware procurement, compressing deployment cycles from years to months.
- Hybrid:Split workloads between retained on-premise transaction processing and cloud-hosted analytics. Commercial banks navigating phased legacy migration favor this architecture to preserve batch reconciliation systems while modernizing customer channels.
- SaaS:Vendor-operated software with subscription pricing and shared infrastructure multi-tenancy. Community institutions across Australia's eastern states select SaaS to eliminate internal IT overhead.
On-Premise retains volume leadership; Cloud-Based holds the steepest expansion curve.
Service Type:
Cost tier differentiation separates project-based implementation from recurring revenue streams.
- Implementation:System integration, data migration, and parallel-run testing during core replacement. Large-scale transformations at Indian public sector banks consume substantial professional services capacity.
- Maintenance:Patch management, version upgrades, and incident response for production environments. Regulatory-mandated security updates in Europe sustain steady demand regardless of new sales cycles.
- Managed Services:Full operational outsourcing including infrastructure monitoring, backup recovery, and capacity planning. US regional banks facing core banking talent scarcity increasingly contract operational responsibility to vendors.
- Consulting:Advisory on architecture selection, vendor evaluation, and regulatory compliance preparation. RBI sandbox program participants in India engage consultants to navigate cloud qualification requirements.
Implementation captures the largest project values; Managed Services delivers the most predictable recurring revenue.
End User:
Customer type determines functional requirements from batch processing scale to real-time event streaming.
- Commercial Banks:Full-service institutions with diverse product portfolios spanning deposits, lending, and treasury. Hybrid architecture dominance among US and European incumbents reflects complex legacy integration requirements.
- Credit Unions:Member-owned cooperatives with standardized product sets and community-focused operations. US Midwest credit unions favor single-stack solutions prioritizing operational simplicity over functional specialization.
- Online Banks:Digital-only subsidiaries of established banking groups operating without branch networks. Brazilian digital public infrastructure initiatives create white space for cloud-native core deployments targeting financial inclusion.
- Neobanks:Venture-backed challengers built on containerized microservices from inception. Southeast Asian neobanks deploy full-stack platforms in months, eliminating traditional systems integration bottlenecks.
Commercial Banks anchor installed base volume; Neobanks are expanding most quickly.
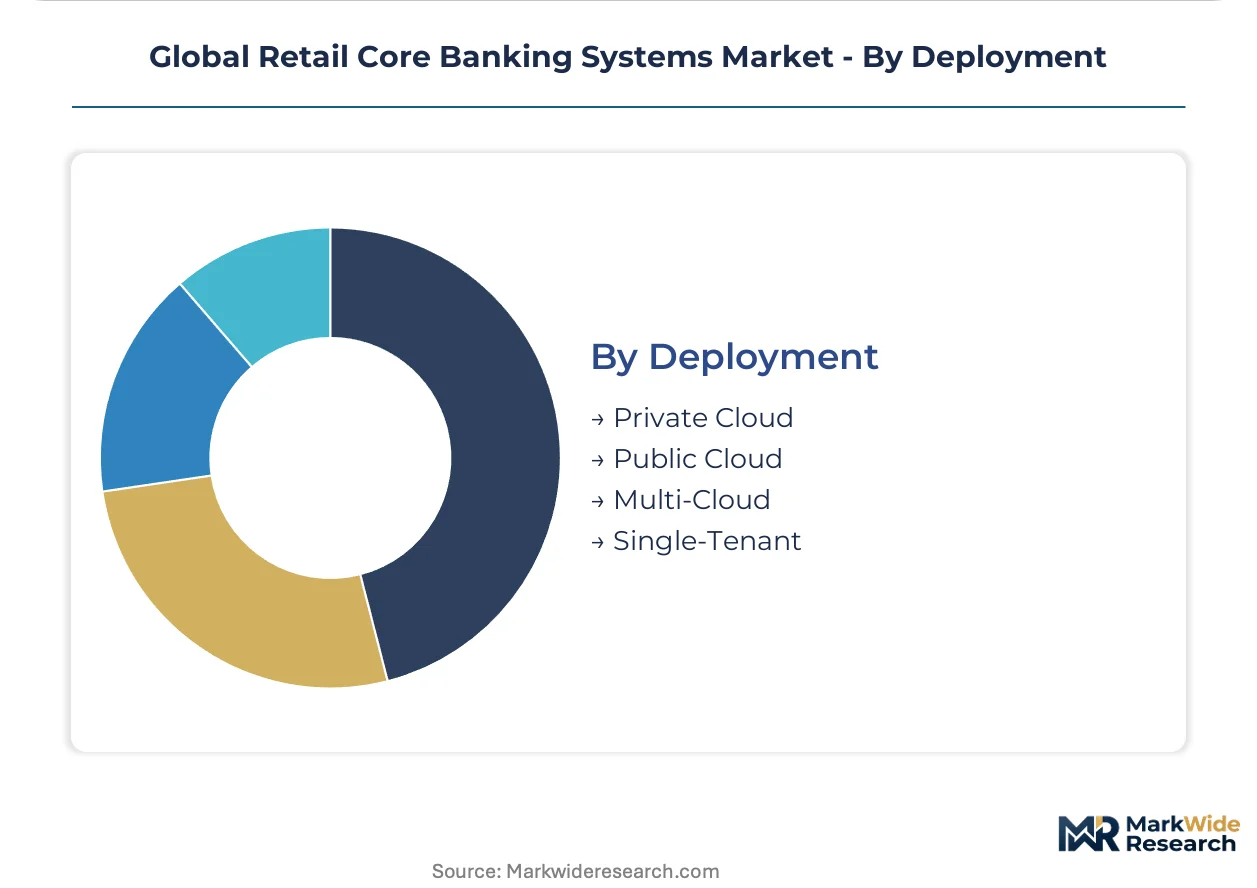
Deployment:
Supply concentration clusters around hyperscaler partnerships and sovereign cloud certifications.
- Private Cloud:Dedicated infrastructure within single-tenant environments, often on bank-owned premises. German institutions facing Bundesbank supervisory requirements retain private cloud for critical payment processing workloads.
- Public Cloud:Shared infrastructure operated by hyperscale providers with consumption-based pricing. Indian fintech-bank collaborations leverage RBI sandbox approvals to deploy on public cloud with regulatory comfort.
- Multi-Cloud:Workload distribution across two or more cloud providers to mitigate vendor lock-in. Multi-national institutions weigh sovereign data residency requirements against elasticity when evaluating multi-cloud architectures.
- Single-Tenant:Physically isolated infrastructure stacks serving one client exclusively. US OCC and FDIC supervision of technology service providers drives conservative institutions toward single-tenant configurations for audit trail control.
Private Cloud maintains regulatory preference; Public Cloud gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The SWIFT messaging network's headquarters in Belgium anchors Europe's dominance in cross-border payment infrastructure, while India's Unified Payments Interface processes billions of monthly transactions through its digital public infrastructure backbone.
United States
Community and regional banks drive modernization demand as legacy mainframe systems age beyond operational viability. The OCC and FDIC embed third-party risk management into vendor selection criteria, extending due diligence timelines. Chicago and Charlotte banking clusters concentrate procurement activity among mid-tier institutions seeking managed-service alternatives.
Germany
Bundesbank supervisory requirements preserve private cloud preference for critical payment workloads among tier-one institutions. Data sovereignty laws delay full cloud migration despite PSD2 API mandates from the European Banking Authority. Frankfurt's financial district hosts concentrated procurement from cooperative banks navigating hybrid architecture transitions.
India
Digital public infrastructure and regulatory sandbox programs enable rapid fintech-bank collaboration at scale. The RBI permits live testing of cloud core deployments, accelerating domestic and foreign supplier qualification. Mumbai and Bangalore technology corridors concentrate neobank formation and incumbent modernization projects.
Indonesia
Neobanks reject capital-intensive hardware procurement, compressing full-stack platform deployment from years to months. The central bank's payment system modernization roadmap drives interoperability requirements. Jakarta's financial district anchors venture-backed challenger formation with direct vendor relationships bypassing traditional systems integrators.
Brazil
Digital public infrastructure initiatives create white space for cloud-native cores targeting financial inclusion among unbanked populations. The central bank's Pix instant payment system mandates real-time processing capabilities. São Paulo's fintech corridor concentrates Banking-as-a-Service platform development integrating with e-commerce ecosystems.
Global Retail Core Banking Systems Market Competitive Environment
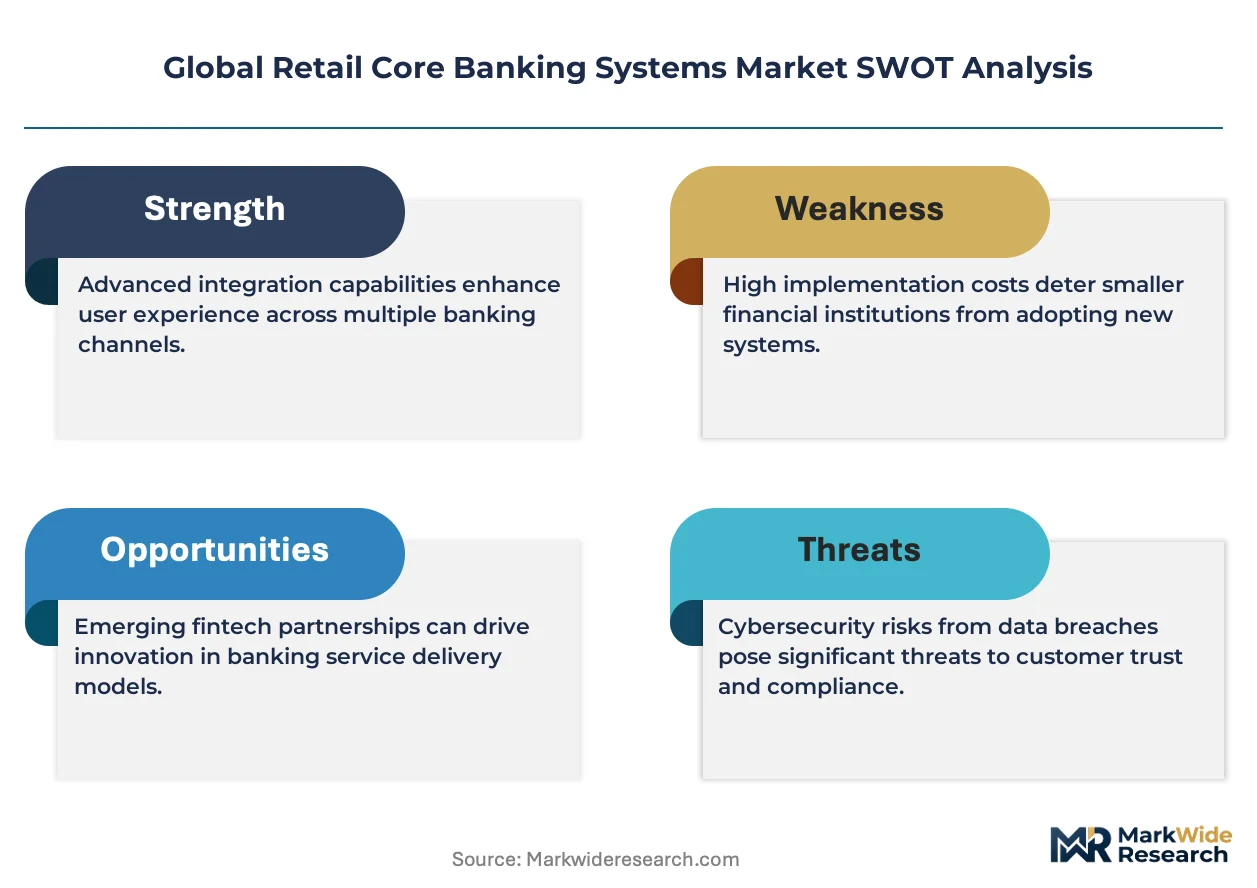
On the supply side, the industry is consolidating around integrated cloud suites that combine core processing with adjacent modules. Tier-one vendors with decades-long client relationships compete against cloud-native challengers built on containerized microservices. Two strategic archetypes dominate: legacy platform modernizers and greenfield digital specialists. Competitive moves center on subscription model migration and hyperscaler partnership formation.
Within the legacy modernizer tier, Temenos leverages its cloud-native T24 Transact platform to sustain relationships across European and African markets. Fiserv anchors community and regional banks with modular upgrade paths through its DNA and Premier cores. Oracle extends database and middleware dominance into financial services infrastructure via its Banking Cloud Suite, occupying a position among hyperscaler-aligned enterprise vendors.
| Leading Market Players |
|---|
| Temenos |
| Fiserv |
| FIS |
| Oracle |
| SAP SE |
| Tata Consultancy Services |
| Infosys |
| Finastra |
| Mambu |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific fiber-optic cable capacity constraints between Singapore and Mumbai amplify cost differentials for cloud-native core banking deployments, concentrating vendor pricing power among hyperscaler-aligned platforms while forcing tier-two institutions toward standardized SaaS tiers with compressed customization budgets.
Pricing Analysis
Volume-discount tiering structures separate enterprise-grade perpetual licenses from consumption-based SaaS subscriptions. Pricing stratifies across premium managed-service bundles, standard self-hosted cloud tiers, and economy multi-tenant configurations. Cost compression in the standard tier is intensifying because Indian and Indonesian neobanks negotiate aggregate procurement pools. Community banks across Australia's eastern states exhibit highest price sensitivity; tier-one German institutions demonstrate lowest elasticity due to regulatory-mandated resilience requirements.
Supply Chain Analysis
Export-control regimes restricting advanced GPU and quantum-resistant cryptography flows from US and Dutch suppliers to Chinese data centers constrain infrastructure scaling for certain deployment architectures. Software engineering talent concentrates in India, Poland, and Vietnam. Container orchestration platforms and API gateway middleware draw from hyperscaler marketplaces. Single-source vulnerability runs through Intel and AMD server chip supply chains. Distribution runs through direct vendor-to-bank relationships that displace traditional systems integrators in Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native core banking sits in early-cycle expansion as regulatory sandbox programs in India and Brazil compress vendor qualification timelines from years to months, accelerating first-mover advantage accumulation.
For Market Incumbents: Harden subscription-model infrastructure to capture recurring revenue streams that implementation projects cannot match. Deepen API-layer governance tooling to meet EU AI Act algorithmic transparency mandates. Defend against Mambu and other containerized challengers by embedding managed-service operational responsibility into long-term client contracts.
For New Entrants and Emerging Players: Establish a beachhead in Brazil's unbanked financial inclusion segment where Pix instant payment mandates create greenfield demand for real-time processing cores. Target Indonesian neobanks with direct vendor relationships that bypass consulting intermediaries. Lead with Banking-as-a-Service platform positioning to capture embedded finance revenue pools beyond traditional FI clients.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hyperscaler-aligned enterprise vendors with database-layer dominance over best-of-breed point solutions. Long-term viability over a decade-long window rests on regulatory certification depth across multiple jurisdictions. The acquisition target archetype combines cloud-native architecture with existing RBI or Bundesbank sandbox approvals. Watch for inflection when tier-one German institutions abandon private cloud preference for multi-cloud elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hyperscaler Partnership Formation | AWS and Azure certifications accelerate RBI sandbox qualification for foreign suppliers. |
| API-First Platform Integration | PSD2 compliance mandates embed Temenos and Fiserv deeper into European incumbent stacks. |
| Managed-Service Revenue Transition | Subscription structures displace perpetual licenses among US Midwest community banks. |
| Regulatory Sandbox Pre-Certification | RBI live-testing approvals compress deployment cycles for Indian fintech collaborations. |
| AI Governance Tooling Embedment | EU AI Act risk classifications force algorithmic transparency at the database layer. |
Study Parameters
A standing panel of core banking CTOs, regulatory compliance officers at RBI and Bundesbank, fintech integration specialists, and managed-service procurement leads provided ongoing calibration. Primary interviews combined with secondary validation from SEC filings of listed vendors, RBI sandbox approval databases, EBA PSD2 implementation reports, and hyperscaler financial services certification disclosures. Bottom-up deployment counts triangulated against top-down vendor revenue segmentation across the analysis window.
Scenario-bracketing anchored projections across technology migration timelines, with segmentation dimensions spanning deployment architecture, service model type, institutional tier, and regional regulatory cluster. CAGRs derived from installed base turnover rates and new entrant formation velocity. Forecast inputs incorporated neobank charter issuance rates and central bank sandbox program expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories and venture capital deployment into fintech would shift the trajectory. Forecasts reflect assumptions on regulatory sandbox program continuity and hyperscaler data center expansion pace. Material shifts in sovereign data residency enforcement or major vendor consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Armenia Banking Market
Banking
Bank Management Software Market
Banking
North America Machine Learning in Banking Market
Banking
US Retail Banking Market
Banking
In Vitro Fertilization Banking Services Market
Banking
China Data Analytics in Banking Market
Banking
Southeast Asia Commercial Banking Market
Banking
UK Banking as a Service Market
Banking
Europe Data Analytics in Banking Market
Banking
Germany Banking As a Service Market
Banking
Smart Banking Solutions Market
Banking
Germany Neobanking Market
Banking
Global Chatbot for Banking Market
Banking
UK Retail Banking Market
Banking
Contactless Smart Cards in Banking Sales Market
Banking
Bank Kiosk Market