
 Southeast Asia Commercial Banking Market | 2026-2036
Southeast Asia Commercial Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Commercial Banking Market Analytics
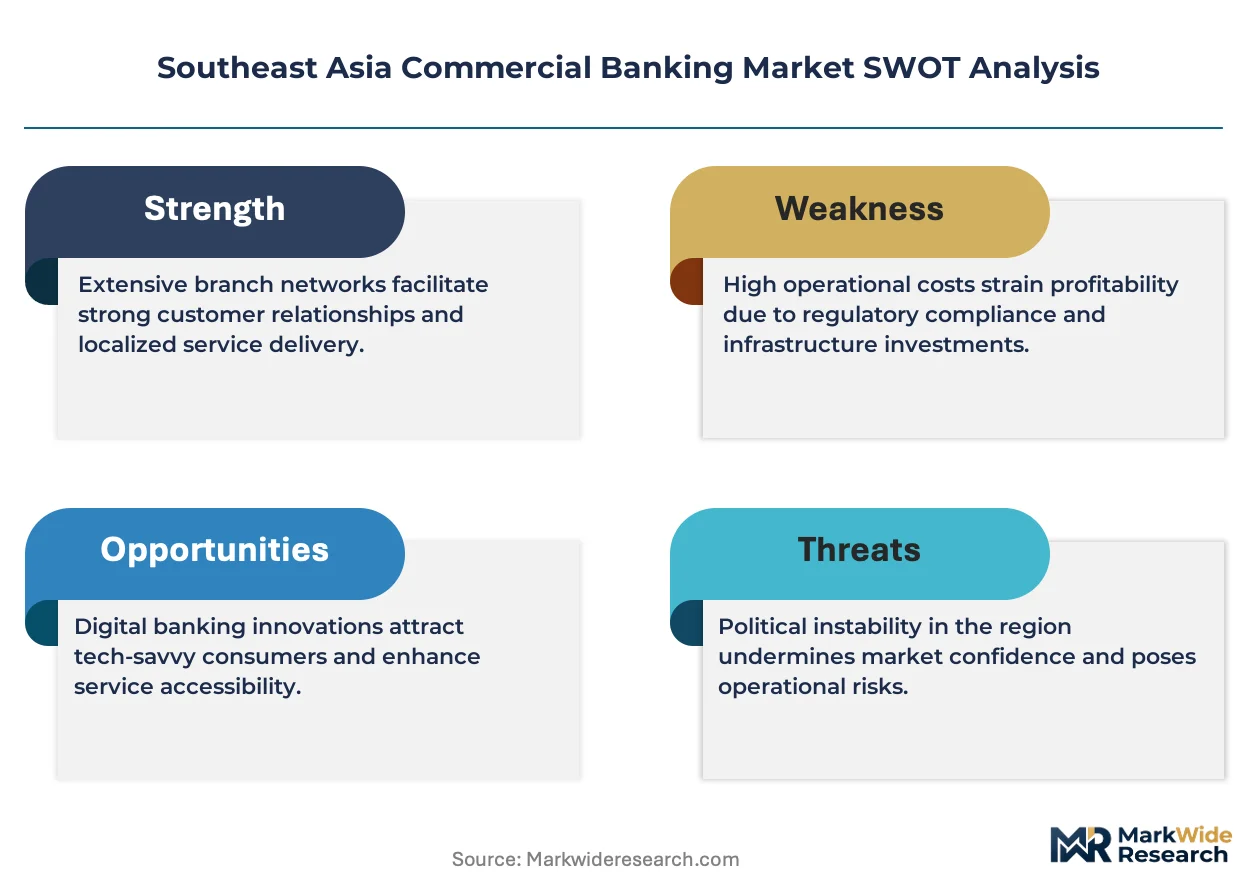
Legacy core banking infrastructure is hardening into a constraint as cloud-native architectures replace on-premise systems across ASEAN financial institutions. DBS Bank leverages its digital platform dominance to capture corporate treasury flows across Singapore and regional hubs. Bangkok Bank anchors its position through extensive branch networks in Thai manufacturing zones and cross-border Mekong trade corridors. United Overseas Bank competes on trade finance specialization, particularly in commodity-linked lending between Southeast Asian ports and Middle Eastern buyers.
Southeast Asia commercial banking encompasses deposit-taking, credit intermediation, trade finance, and treasury services delivered to non-retail entities across ten ASEAN economies, with capital adequacy ratios and liquidity coverage ratios serving as core prudential benchmarks. Corporate banking and SME lending constitute the deepest margin pools, while digital operating models represent the fastest-growing service delivery channel as regulator-supervised open APIs enable real-time payment infrastructure. Wealth management services for family-owned enterprises are expanding fastest in Indonesia and Vietnam, though bricks-and-mortar networks still dominate loan origination in Philippines rural agricultural districts.
Bank Indonesia, the Monetary Authority of Singapore, and Bangko Sentral ng Pilipinas enforce divergent capital reserve and consumer protection standards that fragment product standardization across ASEAN borders. The ASEAN Banking Integration Framework creates partial mutual recognition, yet national deposit insurance schemes and divergent NPL provisioning rules preserve market access barriers for cross-border lenders. Stakeholders must monitor whether ASEAN central banks harmonize digital banking licenses before non-bank fintech platforms capture material shares of working-capital and supply-chain finance volumes.
Market Dynamics
Open banking API mandates across ASEAN central banks are forcing incumbent institutions to dismantle decades-old core infrastructure while defending deposit franchises against cloud-native competitors.
Growth Catalysts
- Bank Indonesia's BI-FAST real-time payment infrastructure:Instant settlement rails enable working-capital products for SME suppliers in Javanese manufacturing corridors.
- Cross-border trade finance digitization:Electronic bills of lading and blockchain-verified letters of credit compress documentary processing from weeks to hours across Mekong Basin trade routes.
- SME credit demand concentration:Indonesian and Vietnamese manufacturing clusters are expanding term-loan uptake as regional supply chains relocate from coastal China.
Market Restraints
- Divergent national deposit insurance schemes:The ASEAN Banking Integration Framework lacks mutual recognition, forcing foreign lenders to maintain redundant capital reserves in each member state.
- Legacy core system replacement costs:Mainframe-dependent institutions in Philippines and Thailand face decade-long migration timelines that delay API-ready product launches.
- Non-performing loan provisioning rule fragmentation:Bangko Sentral ng Pilipinas enforces stricter coverage ratios than Monetary Authority of Singapore, complicating standardized risk pricing.
Strategic Opportunities
- Vietnam's underpenetrated corporate treasury market:State-owned enterprise privatization is creating demand for cash management and hedging products in Ho Chi Minh City and Hanoi.
- Supply-chain finance platform convergence:Integration of IoT inventory tracking with dynamic discounting algorithms enables pre-shipment financing for ASEAN electronics assemblers.
- Wealth management licensing liberalization:Indonesia's Otoritas Jasa Keuangan is expanding private banking permits for family-owned conglomerates in Surabaya and Medan.
Industry Challenges
- Cloud-native engineering talent scarcity:Banks competing with regional technology firms for API architecture and cybersecurity specialists face recruitment bottlenecks in Singapore and Kuala Lumpur.
- Open banking certification timelines:Bangko Sentral ng Pilipinas' phased API standards implementation creates compliance uncertainty for product roadmaps targeting Philippines rural agricultural lending.
- Core banking vendor lock-in:Decades-old contractual dependencies with on-premise software providers complicate migration negotiations and inflate switching costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Commercial Banking Market |
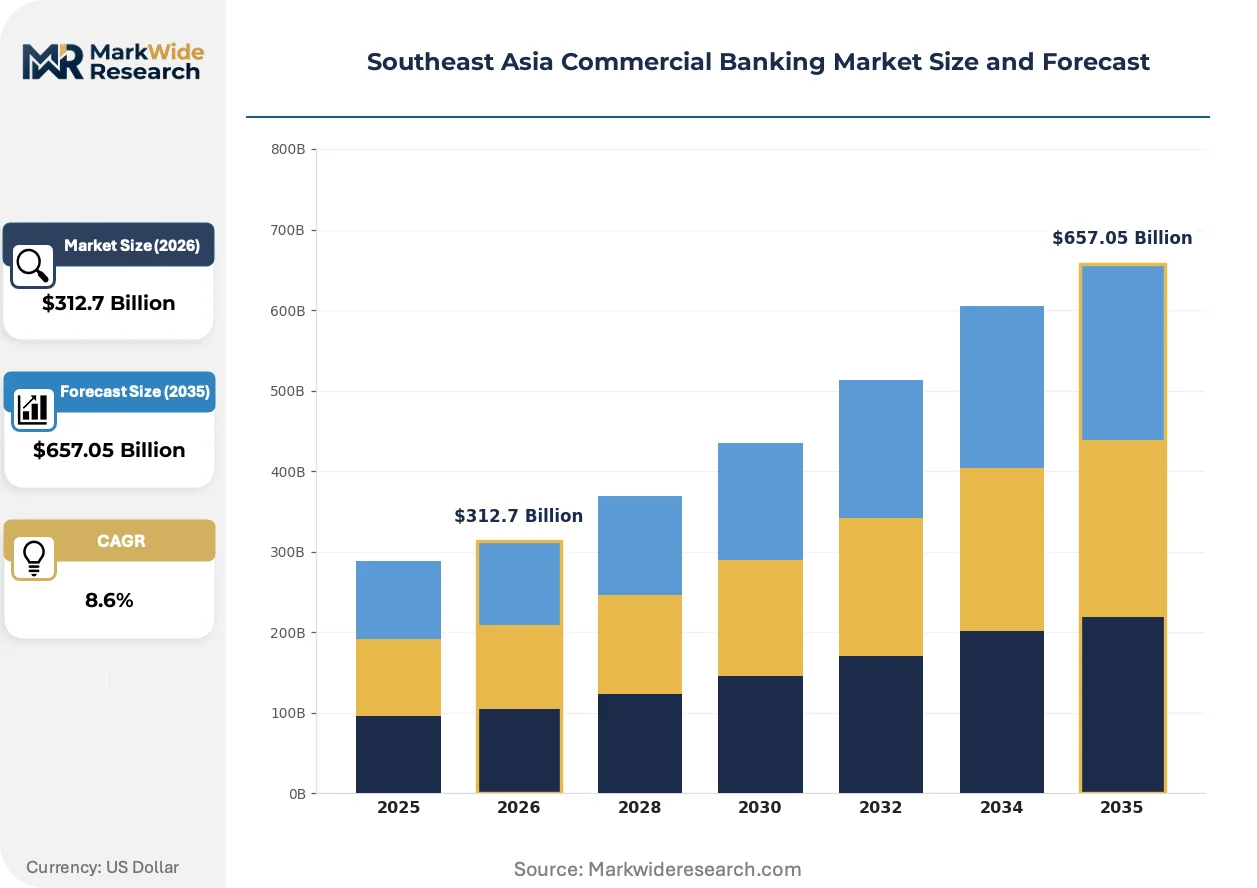
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $657.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Retail Banking, Corporate Banking, Investment Banking, Wealth Management Customer Type: Individual Clients, SMEs, Large Enterprises, Government Entities Operating Model: Bricks-and-Mortar, Digital, Hybrid, Mortgage-Backed Transaction Type: Deposits, Loans, Investments, Fund Transfers |
| Companies Covered | United Overseas Bank, Bangkok Bank, DBS Bank, BDO Unibank, Siam Commercial Bank, Bank Central Asia, Bank Rakyat Indonesia, CIMB, OCBC Bank, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Commercial Banking Market Evolving Landscape
Distributed ledger infrastructure and regulator-supervised API frameworks are compressing settlement cycles and disintermediating correspondent banking relationships across ASEAN trade corridors.
Cloud-native core banking platforms are absorbing transaction processing and customer onboarding functions previously handled by mainframe installations. Indonesian digital banks and Vietnamese joint-stock lenders are adopting these architectures fastest. The technology is absorbing middleware layers and collapsing time-to-market for new credit products from quarters to weeks.
Bank Indonesia's open finance regulatory sandbox creates controlled testing environments for alternative credit scoring models using telco and e-commerce transaction data. The framework permits supervised experimentation outside standard provisioning requirements. Fintech-bank partnerships targeting unbanked SME segments in Sumatra and Sulawesi are the primary beneficiaries.
Corporate treasury teams are consolidating banking relationships around providers offering real-time liquidity visibility across multicurrency ASEAN operations. Static RFP processes are yielding to pilot-based selection criteria emphasizing API reliability and sandbox integration speed. This behavioral shift is most pronounced among Singapore-headquartered multinationals with manufacturing footprints in Vietnam and Indonesia.
Southeast Asia Commercial Banking Market Segmentation
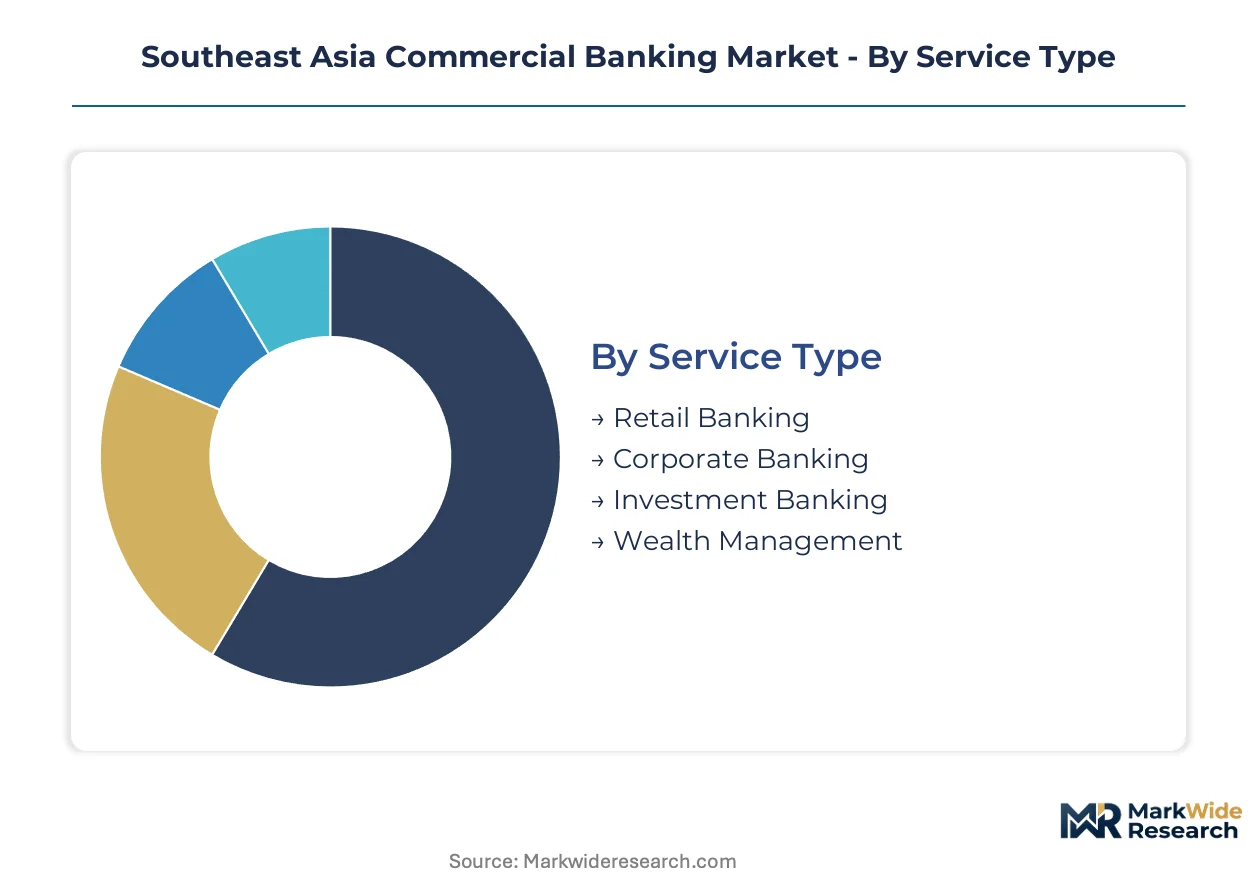
Commercial banking revenue pools across ASEAN fragment along service specialization and customer sophistication axes. Technology deployment and regulatory licensing create divergent margin profiles that reshape competitive positioning across Indonesian, Vietnamese, and Thai markets.
Service Type:
Cloud-native architectures and API-ready infrastructure differentiate margin capture across service lines.
- Corporate Banking:Treasury services, trade finance, and working-capital products dominate revenue concentration in Singapore and Jakarta. Cash management for ASEAN-headquartered multinationals with Vietnam and Indonesia manufacturing footprints drives API reliability requirements.
- Wealth Management:Family-owned conglomerates in Surabaya and Medan expand private banking permits under Otoritas Jasa Keuangan liberalization. Hedging and structured products for commodity-linked enterprises deepen wallet share fastest.
- Retail Banking:Deposit franchises and consumer credit serve mass-market segments through branch networks in Philippines rural districts.
- Investment Banking:Debt underwriting and M&A advisory concentrate in Singapore for regional capital-raising mandates.
Corporate banking leads on scale; wealth management leads on momentum.
Customer Type:
Credit uptake intensity varies by entity size and state ownership status across manufacturing corridors.
- SMEs:Indonesian and Vietnamese manufacturing clusters expand term-loan demand as supply chains relocate from coastal China. BI-FAST real-time settlement enables working-capital products for Javanese supplier networks.
- Large Enterprises:State-owned enterprise privatization in Ho Chi Minh City and Hanoi creates demand for cash management and hedging infrastructure. Corporate treasury consolidation around API-ready providers compresses banking relationship counts.
- Individual Clients:Mass-affluent segments in Kuala Lumpur and Bangkok drive mortgage and installment credit through hybrid channels.
- Government Entities:Sovereign and municipal financing concentrates in Manila and Jakarta through relationship-driven mandate awards.
Large enterprises anchor current revenue; SMEs are expanding most quickly.
Operating Model:
Distribution economics shift as regulator-supervised sandboxes accelerate digital license issuance.
- Digital:Cloud-native platforms absorb transaction processing and onboarding functions previously handled by mainframe installations. Indonesian digital banks and Vietnamese joint-stock lenders adopt these architectures fastest.
- Hybrid:Branches in Thai manufacturing zones anchor Bangkok Bank's position while API layers capture corporate treasury flows. This model preserves rural agricultural lending origination in Philippines provinces.
- Bricks-and-Mortar:Extensive physical networks dominate loan origination in Philippines rural districts and Indonesian outer island territories.
- Mortgage-Backed:Collateralized retail lending concentrates in Singapore and Malaysia urban property markets with standardized valuation frameworks.
Hybrid models lead on scale; digital platforms gain share fastest.
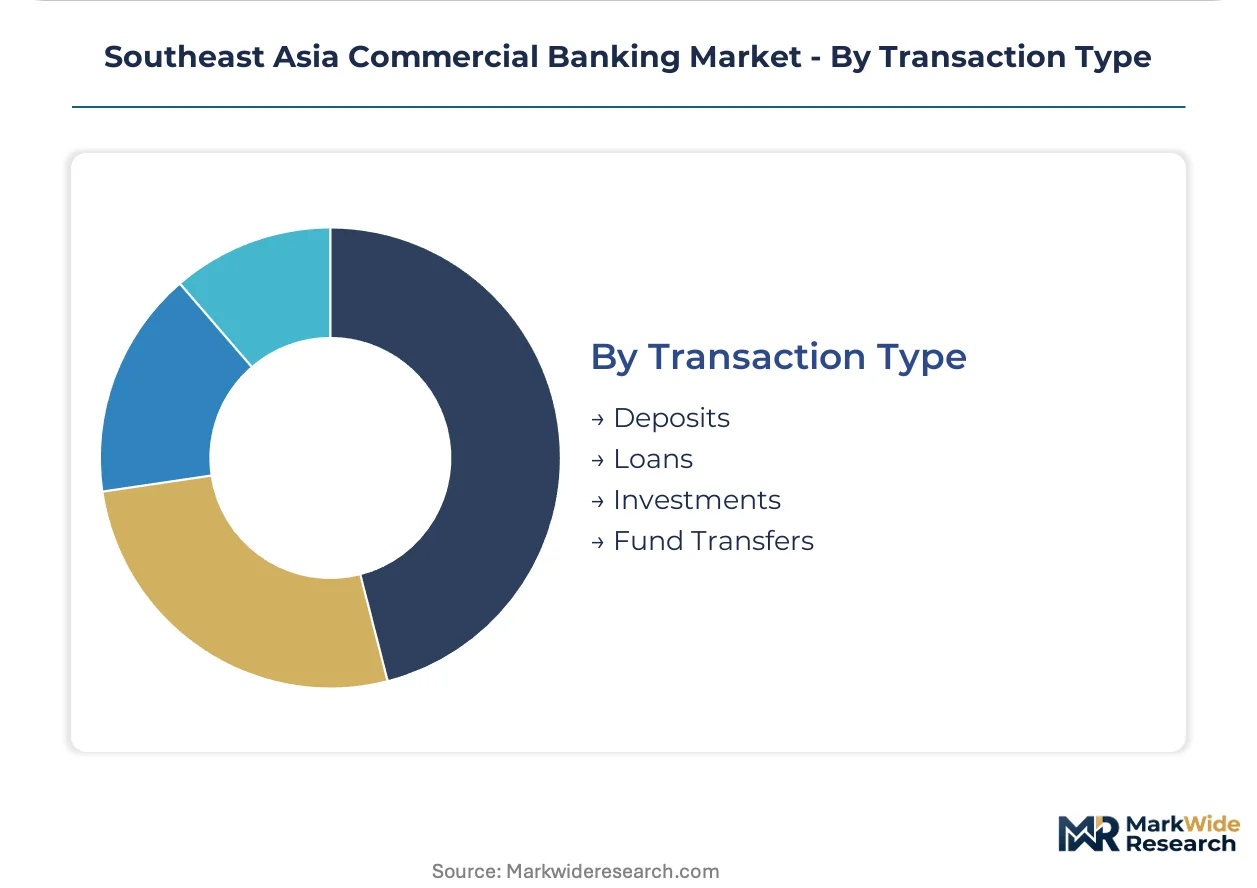
Transaction Type:
Settlement velocity and documentation requirements reshape product profitability across trade corridors.
- Loans:SME term financing and supply-chain credit expand with electronic bills of lading and blockchain-verified letters of credit compressing documentary processing from weeks to hours across Mekong Basin routes.
- Deposits:Current account franchises defend funding costs as BI-FAST and similar real-time rails enable instant balance visibility.
- Fund Transfers:Cross-border remittance and treasury sweep products concentrate demand around Singapore regional hubs.
- Investments:Fixed-income distribution and structured note placement serve institutional mandates through licensed securities subsidiaries.
Loans lead on scale; fund transfers show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Javanese manufacturing corridors concentrate commercial banking activity as Indonesian SME credit demand accelerates through BI-FAST real-time settlement infrastructure. Central bank digital licensing frameworks across ASEAN member states are reshaping competitive access patterns.
Indonesia
SME supplier networks in Surabaya and Medan expand working-capital product uptake as Otoritas Jasa Keuangan liberalizes private banking permits for family-owned conglomerates. Bank Indonesia's BI-FAST rails enable instant settlement products that compress documentary processing timelines. Manufacturing clusters in Java and outer island territories drive hybrid branch-digital distribution models.
Singapore
Corporate treasury consolidation around API-ready providers anchors regional hub status for ASEAN-headquartered multinationals. The Monetary Authority of Singapore enforces capital adequacy standards that exceed ASEAN Banking Integration Framework minima. Marina Bay financial district concentrates cash management and trade finance mandates for Vietnam and Indonesia manufacturing footprints.
Thailand
Cross-border Mekong trade corridors sustain Bangkok Bank's branch network dominance in manufacturing zones. Stricter non-performing loan provisioning timelines than regional peers complicate standardized risk pricing. Industrial estates in Eastern Economic Corridor and border provinces with Laos and Cambodia generate documentary credit demand.
Vietnam
State-owned enterprise privatization in Ho Chi Minh City and Hanoi creates demand for cash management and hedging infrastructure. The State Bank of Vietnam supervises joint-stock lender adoption of cloud-native architectures. Electronics assemblers in Bac Ninh and Hai Phong drive supply-chain finance platform convergence with IoT inventory tracking.
Philippines
Rural agricultural districts maintain bricks-and-mortar loan origination dependence despite Bangko Sentral ng Pilipinas phased API standards implementation. Stricter coverage ratios than Monetary Authority of Singapore preserve compliance complexity for foreign entrants. Metro Manila concentrates government entity financing mandates through relationship-driven awards.
Southeast Asia Commercial Banking Market Competitive Landscape
Platform consolidation dominates the current landscape as incumbent institutions dismantle legacy core infrastructure to defend deposit franchises. The vendor base stratifies across three tiers: Singapore-headquartered regional champions with API-ready treasury platforms, Thai and Indonesian institutions anchored by extensive branch networks in manufacturing corridors, and Philippine lenders navigating prolonged mainframe migration timelines. Strategic archetypes include cloud-native digital attackers, hybrid branch-digital incumbents, and state-affiliated lenders with sovereign mandate access. Competitive intensity concentrates around M&A-driven capability acquisition and regulator-supervised sandbox participation for alternative credit scoring models.
Within the regional champion tier, DBS Bank exemplifies API-first corporate treasury positioning, while United Overseas Bank occupies trade finance specialization between Southeast Asian ports and Middle Eastern buyers. Bangkok Bank anchors hybrid distribution through Mekong Basin branch density. These three institutions represent divergent strategic responses to open banking mandates: cloud-native replacement, trade corridor dominance, and physical network leverage.
| Leading Market Players |
|---|
| United Overseas Bank |
| Bangkok Bank |
| DBS Bank |
| BDO Unibank |
| Siam Commercial Bank |
| Bank Central Asia |
| Bank Rakyat Indonesia |
| CIMB |
| OCBC Bank |
| Others |
Value Network & Pricing Analysis
Family-owned conglomerates with captive treasury operations in Surabaya and Medan anchor pricing discipline across Indonesian commercial banking corridors, while their supplier networks in Javanese manufacturing zones transmit cost pressures into working-capital product margins. Sovereign-backed Thai institutions with Mekong trade corridor dominance leverage branch density to defend deposit pricing against cloud-native competitors.
Pricing Analysis
Input-cost pass-through from real-time payment infrastructure investments shapes pricing architecture across ASEAN commercial banking. Three-tier pricing structure across premium API-enabled, standard digital, and economy branch-delivered levels stratifies by integration complexity and settlement velocity. Price differentiation hinges on Bank Indonesia's BI-FAST certification tier and cross-border corridor access. Pricing pressure stems from cloud-native digital banks compressing SME lending spreads in Jakarta and Ho Chi Minh City. State-owned enterprise treasury teams show lowest price sensitivity; rural agricultural cooperatives in Philippines provinces exhibit highest.
Supply Chain Analysis
Regional distribution centers in Singapore's Marina Bay financial district anchor hub-and-spoke patterns for corporate treasury services across Vietnam and Indonesia manufacturing footprints. Technology sourcing concentrates in India for cloud-native core banking platforms, Singapore for API architecture specialists, and Malaysia for cybersecurity talent pools. Raw material dependencies include proprietary middleware licenses, mainframe migration tooling, and regulator-supervised sandbox certification. Supply chain risk centers on single-source vulnerability for legacy system integration expertise. Distribution runs through hybrid branch-digital networks in Thai manufacturing zones and pure-play API layers for Singapore-headquartered multinationals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN commercial banking operates as a regulatory compounder where Bank Indonesia's BI-FAST real-time payment infrastructure and Otoritas Jasa Keuangan's open finance sandbox create tiered access moats that concentrate margin capture among certified participants.
For Market Incumbents: Deploy API-first treasury platform upgrades to defend corporate relationships against cloud-native attackers. Bangkok Bank should accelerate Mekong corridor branch-digital integration before Vietnamese joint-stock lenders capture cross-border trade finance. DBS Bank must deepen vertical integration into supply-chain finance algorithms to preempt fintech-platform disintermediation.
For New Entrants and Emerging Players: Unbanked SME suppliers in Sumatra and Sulawesi represent the most penetrable white-space target for alternative credit scoring partnerships with Bank Indonesia's regulatory sandbox. Indonesian outer island territories with limited branch penetration offer hybrid digital-agent distribution openings. Go-to-market positioning should emphasize pre-shipment financing convergence with IoT inventory tracking for electronics assemblers in Bac Ninh and Hai Phong.
For Investors and Strategic Acquirers: Regional technology firms with payment infrastructure assets are the most active acquirer in this space, targeting cloud-native engineering capabilities and API-ready licensing. Long-term viability favors institutions with regulator-supervised sandbox participation and BI-FAST certification completion. Acquisition target archetypes include Vietnamese joint-stock lenders with State Bank of Vietnam digital licenses and Indonesian fintech-bank partnerships with telco data access. The signal to watch is ASEAN Banking Integration Framework mutual recognition progress for deposit insurance schemes.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Core Banking Migration | Bank Indonesia's BI-FAST certification enables real-time settlement products for Javanese SME networks. |
| Regulatory Sandbox Participation | Otoritas Jasa Keuangan's open finance framework permits alternative credit scoring outside standard provisioning. |
| Cross-Border Trade Finance Digitization | Blockchain-verified letters of credit compress documentary processing across Mekong Basin corridors. |
| Cloud-Native Talent Acquisition | Singapore and Kuala Lumpur engineering scarcity forces competitive compensation against regional technology firms. |
| Wealth Management Licensing Expansion | Private banking permit liberalization for family-owned conglomerates deepens wallet share in Surabaya and Medan. |
Research Methodology
Multiple input streams — primary interviews with chief risk officers and treasury platform architects, secondary validation through Bank Indonesia regulatory filings and Monetary Authority of Singapore licensing disclosures, and trade data from ASEAN Banking Integration Framework working papers — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included corporate banking heads at Singapore regional hubs, SME lending officers in Javanese manufacturing corridors, fintech partnership leads at Indonesian digital banks, and API compliance specialists at Bangko Sentral ng Pilipinas. Secondary sources encompassed central bank annual reports, open finance regulatory sandbox documentation, and electronic payment infrastructure disclosures.
Historical transaction volume patterns were cross-referenced against panel input from commercial banking executives to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include service type, customer sophistication tier, operating model architecture, and transaction settlement velocity. CAGRs were derived from trend extrapolation adjusted for regulatory milestone impacts. Forecast inputs incorporated BI-FAST adoption curves, cloud-native platform penetration rates, and cross-border trade digitization indices.
Inputs from central bank regulatory filings and sandbox participant disclosures were available through the study window; gaps in real-time API reliability metrics and proprietary credit scoring algorithm performance introduce uncertainty bands around digital lending volume projections. Forecasts reflect documented assumptions regarding ASEAN Banking Integration Framework harmonization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Global AI in Banking Market
Banking
US Retail Banking Market
Banking
Video Banking Service Market
Banking
Cybersecurity in Banking Market
Banking
Latin America Data Analytics in Banking Market
Banking
Banking Smart Cards Market
Banking
Spain Data Analytics in Banking Market
Banking
Middle-East and Africa Banking-As-A-Service Market
Banking
US Banking-As-A-Service Market
Banking
Contactless Smart Cards in Banking Sales Market
Banking
Predictive Analytics in Banking Market
Banking
Machine Learning in Banking Market
Banking
In Vitro Fertilization Banking Services Market
Banking
Global Banking Systems Software Market
Banking
Canada Data Analytics in Banking Market
Banking
Europe Machine Learning in Banking Market