
 Banking Cloud Services Market | 2026-2036
Banking Cloud Services Market Size, Share, and Industry Trends Forecast 2026-2036
Banking Cloud Services Market Analysis
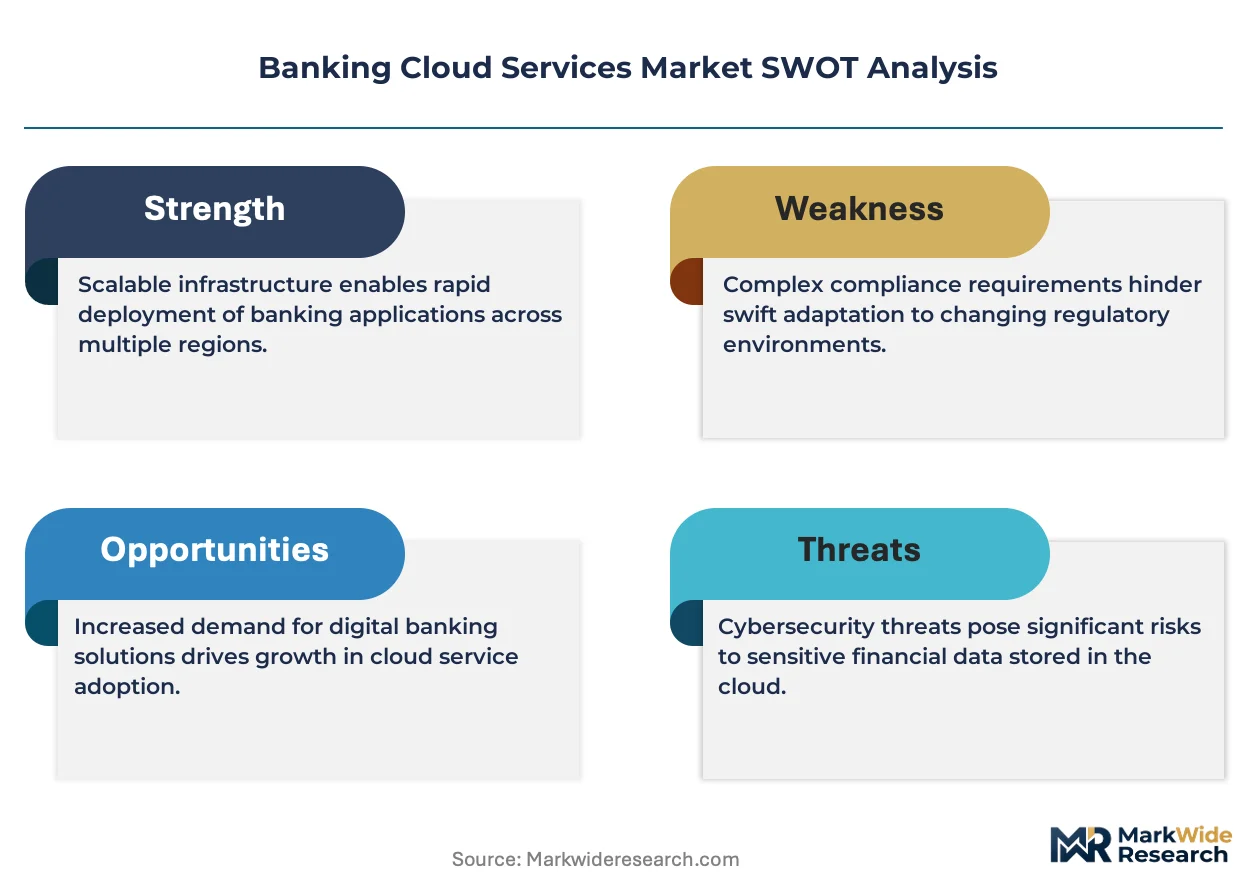
Tier-one resilience certification is collapsing the boundary between legacy core banking and native cloud infrastructure. Amazon Web Services leverages its dedicated financial services regions to anchor sovereign data requirements across multiple jurisdictions. Microsoft Azure sustains hybrid dominance through extensive mainframe integration partnerships with incumbent core banking vendors. Google Cloud differentiates via AI-ready data platforms designed for real-time risk analytics in capital markets.
Banking cloud services encompass the delivery of computing infrastructure, software platforms, and specialized financial applications through remote data centers, with latency thresholds below 10 milliseconds for trading workloads and encryption standards meeting AES-256 for data at rest. The primary purpose is to replace on-premise mainframe capacity with elastic, API-connected resources that support continuous digital banking operations. Software as a Service leads revenue contribution as banks outsource entire core banking stacks rather than managing licensed software internally. Hybrid Cloud deployment captures the fastest expansion trajectory, driven by regulatory mandates requiring customer data residency alongside public cloud scalability for non-sensitive workloads.
Europe's Digital Operational Resilience Act and the EU AI Act impose direct compliance obligations on cloud service providers to banking entities, mandating incident reporting, stress testing, and algorithmic accountability. The US Federal Reserve and OCC scrutiny of third-party risk management compels banks to maintain audit rights and exit strategies within cloud contracts. Stakeholders must weigh the trade-off between multi-cloud redundancy and the operational complexity of harmonizing divergent compliance regimes across jurisdictions.
Market Dynamics
Hybrid cloud architectures are fragmenting procurement patterns across retail banking divisions, forcing institutions to maintain dual-track infrastructure investments while navigating divergent data sovereignty mandates.
Growth Catalysts
- EU AI Act compliance mandates:Banking entities must demonstrate algorithmic accountability for credit-scoring models, accelerating migration to auditable cloud-native platforms with embedded governance tooling.
- Core banking modernization:Sparkassen and Volksbanken in Germany are replacing decades-old mainframe installations with API-connected elastic infrastructure, creating concentrated demand for regulated cloud environments.
- Real-time payment rails:Instant settlement systems require sub-10-millisecond latency thresholds that only distributed cloud edge nodes can reliably deliver.
Market Restraints
- Cross-border data friction:The Digital Operational Resilience Act imposes strict incident reporting and stress-testing obligations on cloud service providers, limiting vendor flexibility across EU member states.
- Encryption key custody complexity:AES-256 standards for data at rest require banks to retain cryptographic control, complicating multi-tenant architectures and inflating operational overhead.
- Mainframe integration debt:Extensive COBOL codebases in incumbent core banking systems resist containerization, extending migration timelines and preserving hybrid complexity.
Strategic Opportunities
- AI-ready data platforms:Convergence of streaming analytics engines with sovereign cloud regions enables real-time risk modeling for capital markets desks previously constrained by on-premise capacity.
- SaaS core banking stacks:Entire licensed software replacements eliminate internal infrastructure management, capturing institutions seeking to outsource operational resilience liability.
- Regulatory technology integration:Embedded compliance automation addresses EU AI Act algorithmic accountability requirements, differentiating providers in vendor selection processes.
Industry Challenges
- Multi-cloud harmonization:Banks must orchestrate divergent compliance regimes across jurisdictions while maintaining unified security postures, straining governance frameworks.
- Exit strategy engineering:US Federal Reserve and OCC scrutiny of third-party risk management compels contractual audit rights and data portability guarantees that few providers can satisfy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banking Cloud Services Market |
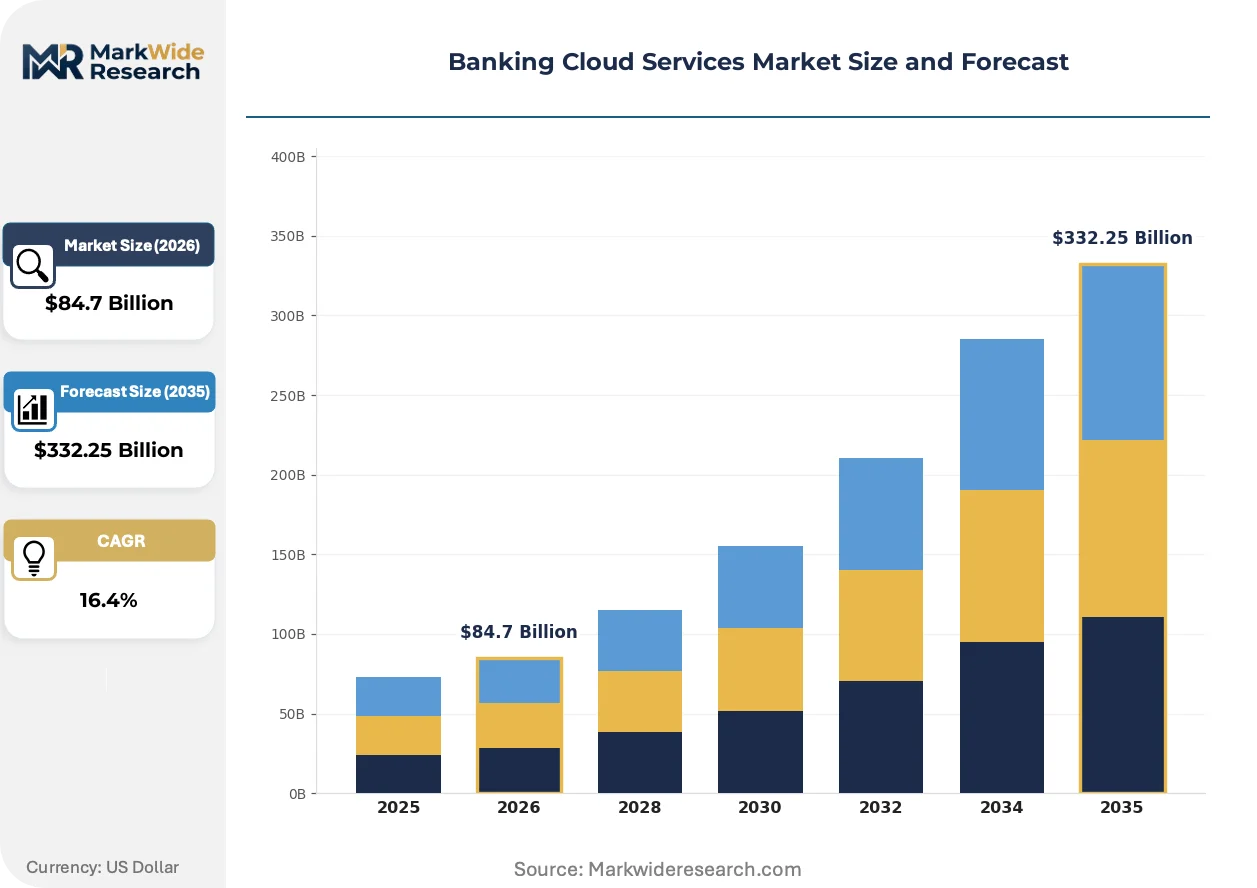
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $332.25 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Infrastructure as a Service, Software as a Service, Platform as a Service, Backup as a Service Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Customer Type: Commercial Banks, Investment Banks, Credit Unions, Fintech Companies Compliance Standards: GDPR, PCI DSS, ISO 27001, SOC 2 |
| Companies Covered | Amazon Web Services (AWS), Microsoft Azure, Google Cloud, IBM Cloud, Oracle Corporation, Temenos AG, Finastra, FIS (Fidelity National Information Services), Tata Consultancy Services (TCS), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banking Cloud Services Market Emerging Trajectories
Native cloud infrastructure is eroding the boundary between legacy core systems and modern elastic platforms, with certification requirements now dictating architectural decisions across retail and investment banking divisions.
Containerized microservices architectures are supplanting monolithic mainframe batch processing in transaction banking operations. Tier-one institutions are adopting Kubernetes-orchestrated workloads at accelerated pace. This shift is compressing vendor consolidation timelines as banks demand unified control planes across hybrid estates.
The Digital Operational Resilience Act is reshaping vendor qualification protocols across European banking entities. Direct compliance obligations now fall on cloud service providers rather than solely on regulated banks. German Sparkassen are prioritizing providers with pre-certified Tier-one resilience status, filtering procurement shortlists before technical evaluation begins.
Consumption-based pricing models are displacing fixed-term enterprise licensing in core banking procurement. Regional banks and mutuals favor operational expenditure structures that align costs with transaction volumes. This pattern is most visible among Germany's cooperative banking sector, where Volksbanken are negotiating usage-tiered contracts with sovereign cloud operators.
Banking Cloud Services Market Segmentation
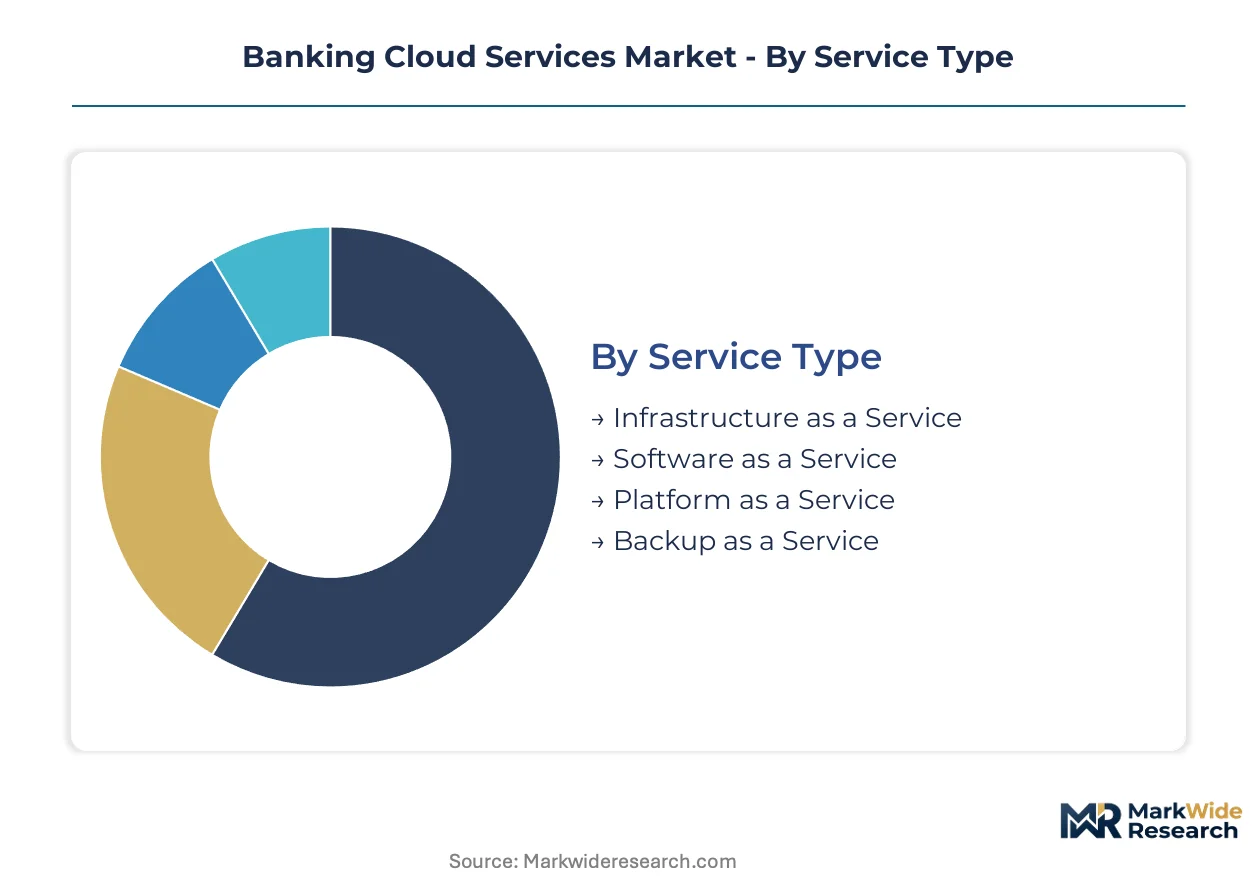
Banking cloud services fragment across four critical dimensions that determine procurement priorities. Regulatory mandates reshape how institutions weight service characteristics against deployment flexibility. Each segmentation axis carries distinct compliance implications that filter vendor shortlists before technical evaluation begins.
Service Type:
GDPR and PCI DSS obligations force divergence between infrastructure procurement and software licensing strategies across EU and US jurisdictions.
- Infrastructure as a Service:Raw compute, storage, and networking resources delivered through virtualized environments with tenant-isolated encryption key management. German Sparkassen concentrate procurement here for core system migration, driven by DORA-mandated stress-testing requirements that IaaS providers must satisfy directly.
- Software as a Service:Complete application stacks including core banking, CRM, and risk management platforms accessed via subscription models. Volksbanken in Germany favor SaaS for operational expenditure alignment, constrained by EU AI Act algorithmic accountability demands that require embedded governance tooling.
- Platform as a Service:Managed development environments with pre-integrated middleware and database services.
- Backup as a Service:Automated disaster recovery and archival solutions with geographically distributed replication.
SaaS handles the majority of throughput; Hybrid Cloud deployment is the fastest mover on share.
Deployment Model:
Cost tier differentiation separates institutions maintaining legacy mainframe integration from those pursuing greenfield cloud-native architectures.
- Hybrid Cloud:Orchestrated workloads spanning private data centers and public cloud regions with unified policy enforcement. Tier-one banks in Frankfurt and London prioritize this model, balancing DORA data residency mandates against scalability needs for non-sensitive analytics workloads.
- Public Cloud:Shared infrastructure resources with consumption-based pricing and global edge node distribution. Fintech companies in Berlin and Paris concentrate demand here, attracted by sub-10-millisecond latency for real-time payment rails despite cross-border data friction risks.
- Private Cloud:Dedicated single-tenant environments with full infrastructure control.
- Multi-Cloud:Deliberate distribution across competing provider platforms for redundancy.
Hybrid Cloud handles the majority of throughput; Public Cloud is expanding most quickly among new entrants.
Customer Type:
Application complexity determines whether institutions prioritize sovereign cloud certification or API flexibility in vendor selection.
- Commercial Banks:Full-service retail and corporate banking institutions with diverse workload portfolios. Germany's cooperative banking sector drives concentrated demand for regulated cloud environments, compelled by DORA incident reporting obligations that fall directly on cloud service providers.
- Fintech Companies:Technology-native financial services providers with cloud-first operational models. Berlin-based neobanks and payment processors favor elastic infrastructure, constrained by PCI DSS audit requirements that complicate multi-tenant architectures.
- Investment Banks:Capital markets and securities trading operations with extreme latency sensitivity.
- Credit Unions:Member-owned cooperative institutions with limited internal IT capacity.
Commercial Banks handles the majority of throughput; Fintech Companies is climbing the fastest on customer acquisition.
Compliance Standards:
Margin pressure intensifies for providers lacking pre-certified status as German procurement teams filter shortlists before technical evaluation.
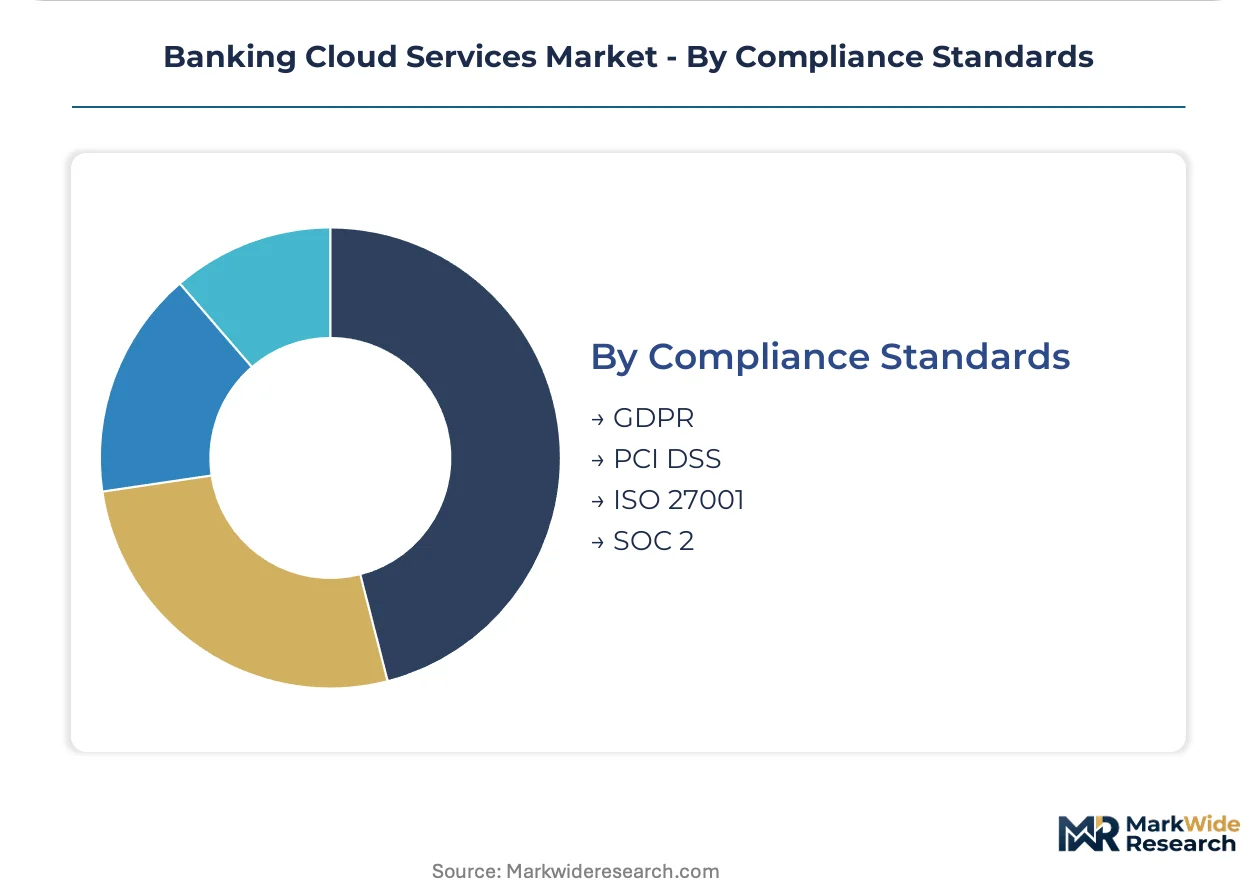
- GDPR:EU data protection framework mandating breach notification within 72 hours and data portability guarantees. Cloud contracts with German banks now embed these obligations explicitly, with penalties for provider non-compliance.
- PCI DSS:Payment card industry security standard requiring encrypted cardholder data environments. Frankfurt-based transaction processors demand this certification for any infrastructure touching payment rails.
- ISO 27001:International information security management system certification.
- SOC 2:US-focused service organization control framework for security and availability.
GDPR handles the majority of throughput; EU AI Act alignment is gaining share fastest as algorithmic accountability requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply by jurisdiction. German cooperative banks absorb premium sovereign cloud costs under DORA mandates. US money-center banks prioritize scale economics over data residency. Emerging market institutions face acute trade-offs between compliance and affordability.
United States
New York-based global systemically important banks drive demand for multi-tenant public cloud capacity. The Federal Reserve's SR 11-7 guidance on model risk management compels algorithmic audit trails. Chicago derivatives exchanges cluster latency-sensitive workloads at edge nodes.
Germany
Sparkassen and Volksbanken concentrate procurement of regulated cloud infrastructure for core banking migration. The Digital Operational Resilience Act imposes direct stress-testing obligations on providers. Frankfurt's financial district anchors sovereign cloud region development.
United Kingdom
London investment banks prioritize sub-10-millisecond latency for real-time risk analytics. The Prudential Regulation Authority's outsourcing guidelines mandate contractual exit provisions. The Square Mile hosts concentrated demand for AI-ready data platforms.
India
Domestic private banks and fintech startups expand public cloud consumption for digital payment rails. The Reserve Bank of India's data localization directive constrains cross-border data flows. Mumbai's Bandra-Kurla Complex clusters regulated financial technology development.
Singapore
Wealth management institutions and ASEAN-facing banks adopt hybrid architectures for regional treasury operations. The Monetary Authority of Singapore's Technology Risk Management Guidelines enforce cyber resilience standards. Marina Bay financial district concentrates demand for multi-currency cloud core systems.
Banking Cloud Services Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes. Hyperscale cloud providers anchor infrastructure innovation while legacy core banking vendors retain customer relationship depth. Three archetypes dominate: sovereign-certified infrastructure operators, AI-native analytics platforms, and mainframe-integration specialists. Competitive moves concentrate on strategic partnerships with regulated financial institutions and geographic expansion of certified cloud regions.
Within the hyperscale tier, Amazon Web Services, Microsoft Azure, and Google Cloud occupy distinct positioning vectors. AWS anchors sovereign data requirements through dedicated financial services regions. Microsoft exemplifies hybrid dominance via mainframe integration partnerships. Google represents AI-ready infrastructure specialization for capital markets workloads.
| Leading Market Players |
|---|
| Amazon Web Services (AWS) |
| Microsoft Azure |
| Google Cloud |
| IBM Cloud |
| Oracle Corporation |
| Temenos AG |
| Finastra |
| FIS (Fidelity National Information Services) |
| Tata Consultancy Services (TCS) |
| Others |
Supply Flow & Price Mechanics
Ninety-day provisioning cycles for sovereign cloud regions concentrate pricing power with hyperscale providers holding pre-certified infrastructure, while procurement teams at German cooperative banks absorb premium costs to satisfy Digital Operational Resilience Act mandates. Tier-one resilience certification functions as a gatekeeping mechanism that filters vendor shortlists before technical evaluation, compressing competitive tension among qualified suppliers.
Pricing Analysis
Managed services and extended compliance-support contracts drive lifetime value beyond initial infrastructure provisioning. The dominant pricing structure operates through tiered subscription models aligned to transaction volume bands and certification grade, with premium tiers commanding substantial markups for sovereign data residency. Price differentiation rests on Tier-one operational resilience status and geographic proximity to financial district edge nodes. Cost compression in mid-market SaaS tiers is intensifying because containerized microservices architectures reduce marginal delivery costs. Fintech startups exhibit acute price sensitivity, while systemically important banks prioritize compliance-grade infrastructure over unit economics.
Supply Chain Analysis
Just-in-time capacity scaling dominates hyperscale operations, though strategic stockpiling of specialized encryption hardware occurs among sovereign cloud operators serving regulated financial hubs. Supply concentration centers on the United States, Ireland, and Singapore for primary data center infrastructure, with Germany and the United Kingdom anchoring European financial services regions. Raw material and component dependencies span specialized semiconductors for low-latency networking, liquid cooling systems for high-density compute, and quantum-resistant cryptographic modules. Single-source vulnerability in encryption chip fabrication presents structural risk. Distribution runs through direct enterprise sales teams and certified systems integrators with financial services specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Banking cloud services constitute a high-growth disruption propelled by regulatory mandates collapsing the boundary between legacy core systems and native cloud infrastructure. The Digital Operational Resilience Act and EU AI Act function as simultaneous accelerants and gatekeepers, concentrating procurement among pre-certified providers.
For Market Incumbents: Secure Tier-one operational resilience certification across multiple jurisdictions to defend against emerging sovereign cloud specialists capturing German cooperative banking procurement. Anchor hybrid cloud dominance through deeper mainframe integration partnerships that extend COBOL containerization timelines and preserve switching costs. Prioritize embedded regulatory technology tooling to address EU AI Act algorithmic accountability requirements as a defensive moat. For New Entrants and Emerging Players: API-native core banking migration services for mid-tier regional banks represent a service-layer gap where incumbent hyperscalers under-serve customization demands. Concentrate penetration efforts on India's domestic private banks and fintech clusters constrained by Reserve Bank of India data localization but underserved by global provider edge density. Pursue go-to-market positioning through certified systems integrators with existing relationships at target institutions. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because compliance obligations concentrate procurement among shrinking qualified vendor pools, embedding durable revenue visibility. Target acquisition candidates with pre-certified sovereign cloud regions and established mainframe integration capabilities. Monitor Digital Operational Resilience Act enforcement patterns across EU member states as the critical inflection signal for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Expansion of Certified Cloud Regions | Frankfurt and Singapore financial districts anchor sovereign data requirements for DORA and MAS compliance. |
| Strategic Partnership with Core Banking Vendors | Temenos and Finastra partnerships enable Microsoft Azure to extend hybrid dominance through mainframe integration. |
| Acquisition of Specialist RegTech Firms | Embedded compliance automation addresses EU AI Act algorithmic accountability in vendor selection processes. |
| Platform Integration with Real-Time Payment Rails | Sub-10-millisecond latency nodes capture instant settlement workloads from Berlin and Paris fintech clusters. |
| Product Launch of AI-Ready Data Platforms | Google Cloud's streaming analytics engines target London capital markets desks constrained by on-premise capacity. |
Methodological Framework
Initial hypotheses were tested against primary input from cloud infrastructure procurement officers, core banking modernization program directors, regulatory compliance leads, and systems integration specialists, then refined through secondary validation against SEC filings from hyperscale providers, European Banking Authority guidance documents, Digital Operational Resilience Act implementation texts, and Bundesbank supervisory reports. Bottom-up triangulation across service-type deployment volumes and top-down cross-checks against aggregate banking IT expenditure flows ensured analytical coherence.
Variance decomposition across service type, deployment model, customer segment, and compliance standard dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from segmented growth rate assumptions calibrated to regulatory implementation timelines and core banking replacement cycles. Forecast inputs incorporated sovereign cloud region buildout announcements, Tier-one resilience certification award patterns, and mainframe modernization contract disclosures.
Forecasts assume regulatory continuity in EU Digital Operational Resilience Act enforcement, US Federal Reserve third-party risk guidance, and Reserve Bank of India data localization directives; material policy shifts would require re-modeling of vendor qualification protocols and procurement timing assumptions. Revision becomes warranted when sovereign cloud certification backlogs exceed eighteen months or when mainframe containerization breakthroughs accelerate hybrid-to-native migration timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Financial Services Operational Risk Management Solution Market
Financial Services
Commodity Services Market
Financial Services
ATM Software Market
Financial Services
Debt Settlement Solution Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
Cash Flow Market
Financial Services
Global Trust and Corporate Service Market
Financial Services
Hyperinflation System Market
Financial Services
Broker Affiliate Programs Market
Financial Services
Check Cashing Services Market
Financial Services
Power Bank Sharing Services Market
Financial Services
Capital Restructuring Services Market
Financial Services
BFSI A2P SMS Market
Financial Services
Saas Escrow Services Market
Financial Services
Europe E-Invoicing Market
Financial Services
Direct Selling Market