
 Europe Data Analytics in Banking Market | 2026-2036
Europe Data Analytics in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Analytics in Banking Market Analytics
Market Context
The cloud delivery channel is reshaping how European banks procure analytics capabilities, shifting procurement from perpetual licenses toward subscription architectures. Temenos leverages its Swiss heritage to sustain dominance in core banking integrations that feed downstream analytics engines. SAP anchors its position through deep ERP connectivity, while Oracle competes by extending database-layer analytics directly into institutional workflows.
Technical Definition and Segment Structure
Data analytics in banking encompasses the systematic extraction, processing, and interpretation of structured and unstructured financial data to optimize decision-making, employing distributed computing frameworks, SQL and NoSQL query engines, and real-time stream processing with sub-second latency requirements. Risk Management applications dominate current deployment value, while Fraud Detection segments capture accelerating growth as real-time transaction monitoring becomes mandatory across SEPA corridors. Machine Learning technology leads R&D allocation, though Predictive Analytics retains the widest installed base among mid-tier European banks.
Regulatory Environment
EMA data governance standards, GDPR data protection mandates, and the EU AI Act's risk-based classification system collectively determine which analytics models European banks can deploy in production environments. The ECB's supervisory expectations on model risk management further constrain vendor selection, privilecing providers with demonstrable algorithmic audit trails. Stakeholders must weigh compliance automation investments against the operational drag of fragmented national interpretations of EU-level directives.
Market Dynamics
The EU AI Act's risk-based classification system is forcing European banks to restructure algorithmic governance frameworks before deploying automated decision systems, creating a structural pivot toward explainable analytics architectures.
Growth Catalysts
- Real-time transaction monitoring mandates:SEPA corridor regulations now require sub-second fraud detection capabilities, driving replacement of batch-processed risk engines with stream analytics infrastructure.
- Germany's banking cluster concentration:Frankfurt's density of systemically important institutions generates concentrated demand for enterprise-grade data platforms and specialized implementation talent.
- GDPR-compliant analytics tooling:Privacy-preserving computation methods including federated learning and differential privacy are unlocking previously restricted customer datasets for modeling.
Market Restraints
- Algorithmic audit infrastructure costs:ECB supervisory expectations on model risk management require specialized documentation systems that mid-tier institutions struggle to fund internally.
- Cloud vendor concentration risk:European banks remain dependent on hyperscale providers for elastic compute, creating systemic vulnerability if cross-border data flows face renewed restrictions.
- Legacy core banking entanglement:Decades-old COBOL-based transaction engines resist API-based extraction, limiting data quality for downstream analytics pipelines.
Strategic Opportunities
- Poland's underpenetrated mid-tier segment:Polish cooperative banks operate with minimal analytics sophistication, presenting white-space demand for standardized cloud-native platforms.
- CSRD sustainability reporting convergence:The Corporate Sustainability Reporting Directive mandates granular emissions tracking that banks must embed into lending decision workflows.
- Explainable AI and quantum encryption fusion:Emerging cryptographic methods are hybridizing with interpretable machine learning to address both regulatory transparency and future-proof security requirements.
Industry Challenges
- Quantitative risk modeler scarcity:European institutions compete for PhD-level talent capable of building production-grade credit scoring algorithms that satisfy ECB validation standards.
- Cross-border data residency fragmentation:National interpretations of GDPR Article 44 create operational friction for banks operating multi-country analytics platforms from centralized cloud regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Analytics in Banking Market |
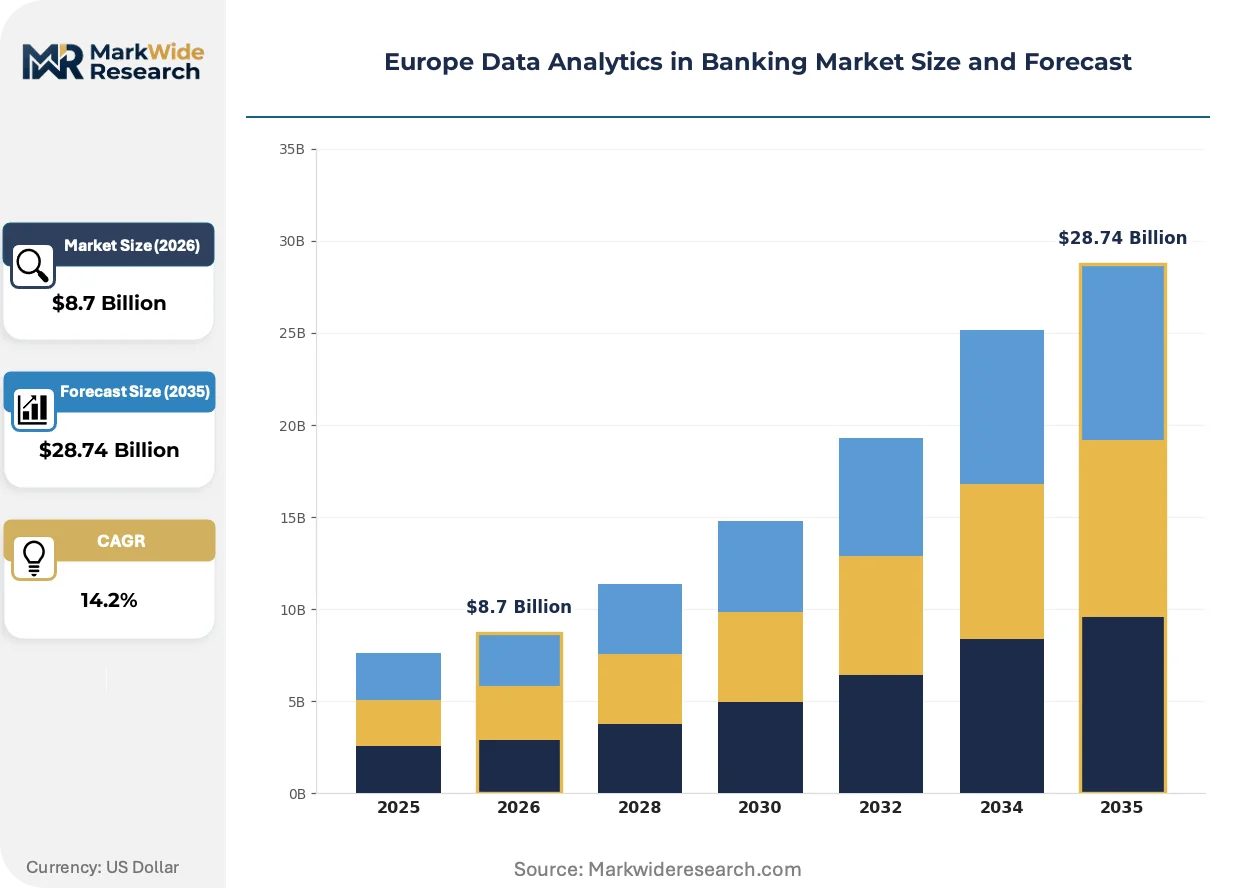
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Risk Management, Customer Insights, Fraud Detection, Regulatory Compliance Technology: Machine Learning, Predictive Analytics, Data Warehousing, Business Intelligence End User: Commercial Banks, Investment Banks, Credit Unions, Fintech Companies Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Temenos, FIS, Finastra, SAP, Oracle, Infosys, Fiserv, NICE, Avaloq, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Analytics in Banking Market Evolving Landscape
European banking analytics is pivoting from descriptive reporting toward predictive and prescriptive capabilities, with regulatory pressure and cloud economics jointly reshaping vendor selection criteria and internal capability development priorities.
Stream processing architectures are hybridizing batch and real-time analytical workloads into unified platforms. Tier-one institutions in Germany and France are consolidating previously separate fraud detection and customer personalization engines. This convergence is compressing vendor margins by eliminating redundant infrastructure spend while demanding higher-performance SLA guarantees from platform providers.
The EU AI Act's high-risk system designation is redrawing procurement checklists for automated credit decisions. Banks must now demonstrate human oversight mechanisms and algorithmic impact assessments before production deployment. Retail lending divisions face the steepest compliance burden, with several institutions establishing dedicated AI ethics committees to pre-validate model architectures.
Subscription-based platform access is displacing perpetual license ownership across European procurement departments. Mid-tier banks in Spain and Italy are leading this transition, trading capital expenditure flexibility for operational agility. Vendor response has stratified into consumption-tiered pricing that aligns compute costs directly with transaction volume fluctuations rather than fixed user counts.
Europe Data Analytics in Banking Market Segmentation
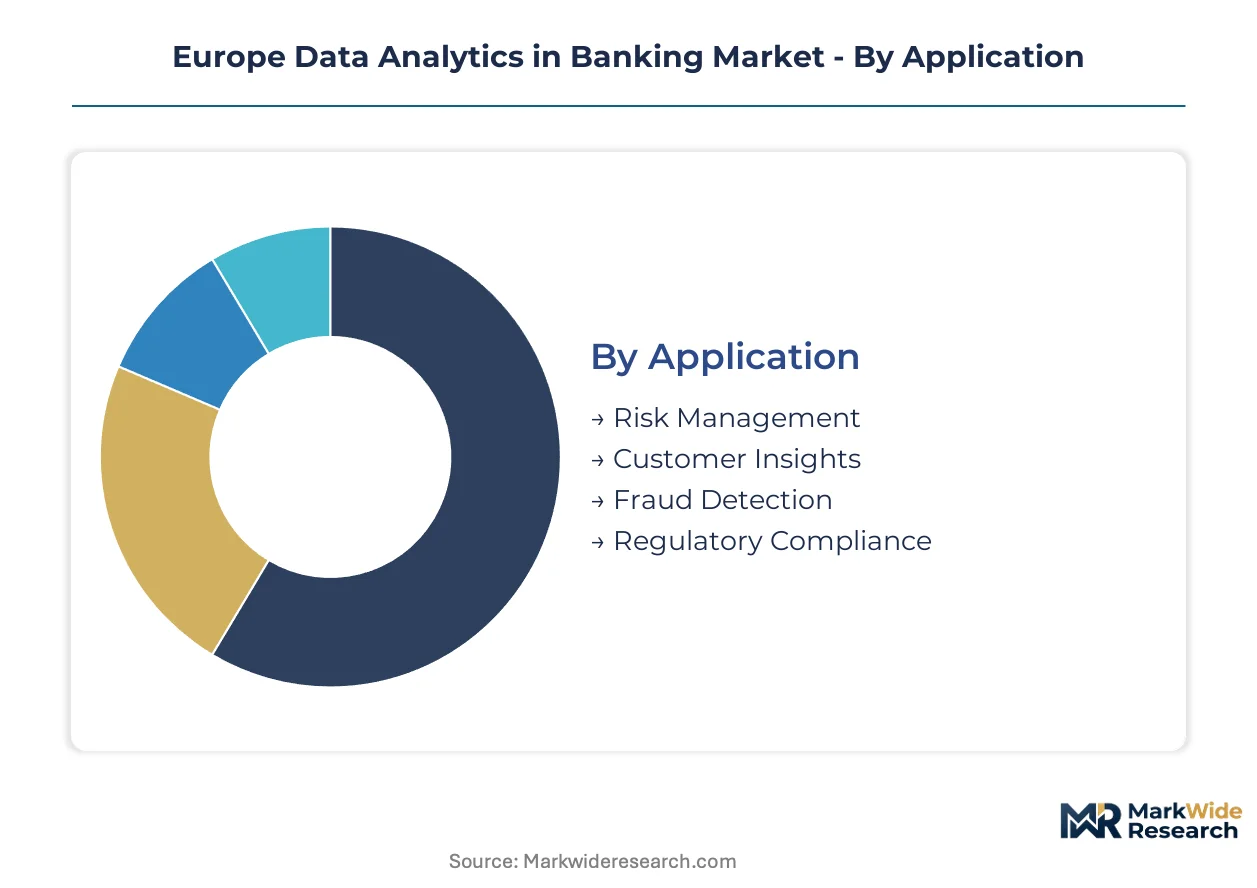
European banks structure analytics procurement around four intersecting dimensions: regulatory use case, processing technology, institutional user type, and infrastructure delivery model. Each dimension carries distinct vendor selection criteria and compliance obligations under EU AI Act and ECB supervisory frameworks.
Application:
After-sales service intensity varies sharply across banking analytics applications, with real-time fraud detection demanding 24/7 vendor support while regulatory compliance tools require periodic model revalidation services.
- Risk Management:Credit scoring, market risk quantification, and liquidity stress testing models dominate current enterprise deployment value. German systemically important institutions in Frankfurt drive concentrated demand for Basel IV-compliant capital calculation engines that satisfy ECB validation standards.
- Fraud Detection:Real-time transaction monitoring systems process SEPA corridor payments with sub-second latency requirements. French and Dutch retail banks are replacing batch-processed engines with stream analytics infrastructure to meet mandatory monitoring regulations.
- Customer Insights:Behavioral segmentation and lifetime value prediction tools enable personalized product recommendations. GDPR-compliant deployment constraints limit dataset scope for mid-tier institutions lacking privacy-preserving computation capabilities.
- Regulatory Compliance:Automated reporting engines for EBA stress tests and CSRD sustainability disclosures. Polish cooperative banks represent underpenetrated demand for standardized compliance automation.
Risk Management holds the largest share; momentum sits with Fraud Detection.
Technology:
Technology selection in European banking analytics follows a cost-tier logic, with tier-one institutions investing in advanced machine learning infrastructure while mid-tier banks prioritize proven predictive analytics with lower total cost of ownership.
- Machine Learning:Deep learning and ensemble methods for credit default prediction and anomaly detection. Tier-one institutions in Germany and France allocate the largest R&D budgets to production-grade algorithm development.
- Predictive Analytics:Statistical modeling and regression-based forecasting retains the widest installed base among Spanish and Italian mid-tier banks seeking proven, auditable methodologies.
- Data Warehousing:Centralized repositories integrating structured transaction data with unstructured customer communications. Cloud-native architectures are displacing on-premises appliances.
- Business Intelligence:Dashboard and visualization tools for executive reporting and regulatory submissions. Standardized implementations dominate procurement in Benelux retail banking.
Predictive Analytics maintains broadest adoption; Machine Learning claims the steepest expansion trajectory.
End User:
End user segmentation reflects maturity gradients across European banking archetypes, with commercial banks possessing the most sophisticated data infrastructure and fintech companies exhibiting the leanest, cloud-native analytics stacks.
- Commercial Banks:Full-service retail and corporate banking institutions with legacy core systems requiring API-based data extraction for downstream analytics. Frankfurt and Paris house the densest concentrations of enterprise platform demand.
- Investment Banks:Trading desk analytics and counterparty risk modeling drive specialized requirements for ultra-low latency data feeds. London's trading infrastructure remains significant despite post-Brexit regulatory fragmentation.
- Credit Unions:Cooperative banking structures with limited IT budgets and standardized product portfolios. Polish credit unions present white-space opportunity for templated cloud-native deployments.
- Fintech Companies:Neobanks and payment processors built on cloud-native architectures without legacy entanglement. Berlin and Amsterdam host the fastest-scaling fintech analytics operations.
Commercial Banks command the largest procurement volumes; Fintech Companies are expanding most quickly.
Deployment:
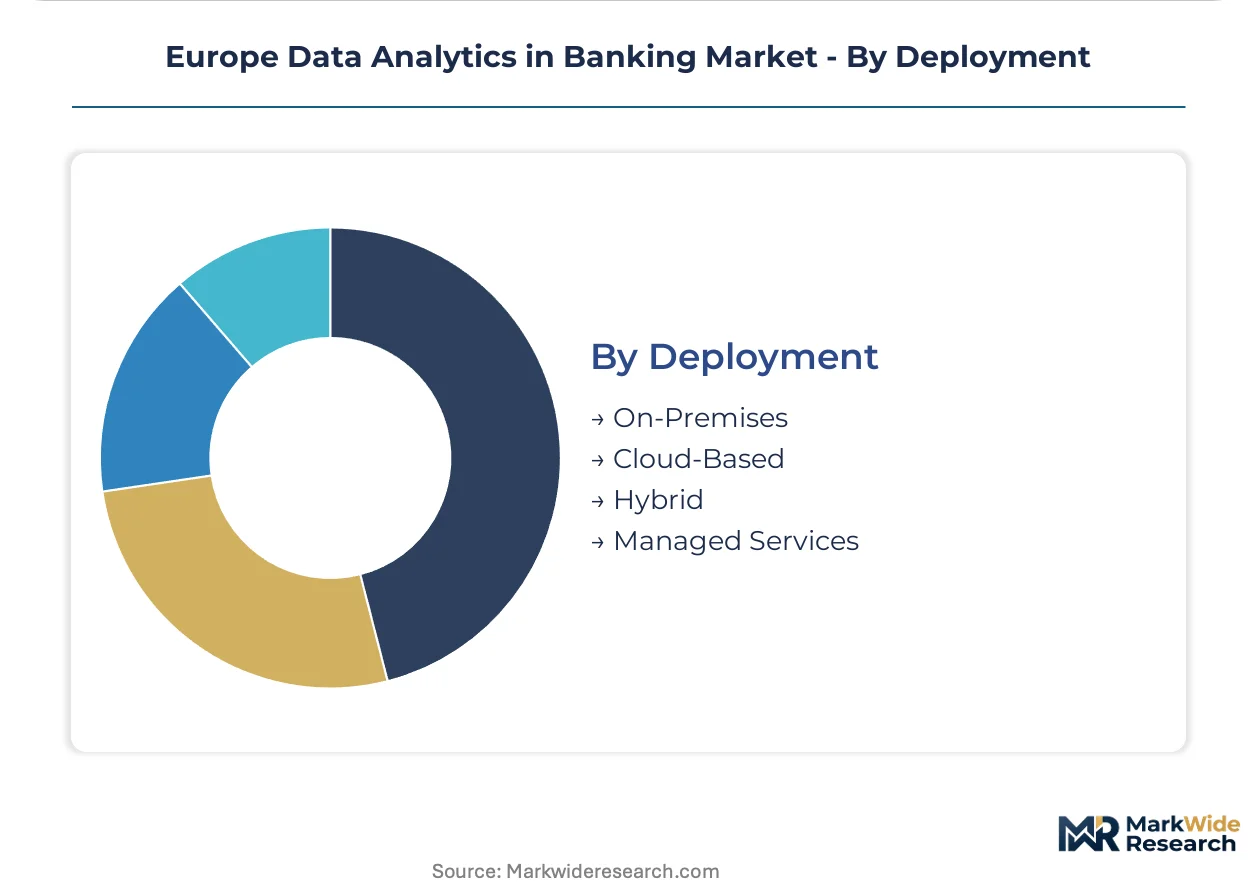
Deployment mode selection tracks directly to data residency requirements and ECB supervisory expectations, with hybrid architectures gaining traction as banks navigate cross-border GDPR Article 44 compliance.
- On-Premises:Dedicated hardware installations for core banking analytics subject to strictest data localization mandates. Austrian and Swiss private banks maintain preference for physical infrastructure control.
- Cloud-Based:Elastic compute and storage via hyperscale providers with consumption-tiered pricing. Spanish and Italian mid-tier banks lead subscription-based procurement transitions.
- Hybrid:Sensitive data remains on-premises while compute-intensive modeling leverages cloud burst capacity. German institutions favor this architecture for AI Act high-risk system deployment.
- Managed Services:Outsourced platform operation with vendor-assumed compliance responsibility. Growing traction among Benelux institutions seeking to externalize ECB model risk management obligations.
On-Premises retains largest legacy footprint; Cloud-Based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ECB anchors European banking analytics demand through Frankfurt's supervisory density and model validation standards. German institutions drive the largest share of enterprise platform investments. National regulators in France, Netherlands, Spain, and Poland enforce divergent data localization interpretations that shape procurement patterns.
Germany
Frankfurt's banking cluster concentrates demand for real-time risk engines and Basel IV-compliant capital calculation systems. The BaFin enforces ECB-aligned model risk management expectations that privilege vendors with algorithmic audit trails. Munich and Stuttgart house mid-tier institutions accelerating cloud-native platform transitions.
France
Parisian retail banks replace batch-processed fraud detection with stream analytics infrastructure for SEPA corridor compliance. The CNIL interprets GDPR Article 44 strictly, forcing hybrid deployment architectures for cross-border data flows. Lyon and Bordeaux host cooperative banks adopting standardized compliance automation tools.
Netherlands
Amsterdam's fintech ecosystem drives lean, cloud-native analytics stack adoption without legacy core entanglement. The Dutch Central Bank applies ECB supervisory frameworks with emphasis on outsourcing governance for managed services. Rotterdam institutions lead subscription-based procurement transitions among mid-tier banks.
Spain
Barcelona and Madrid mid-tier banks prioritize proven predictive analytics with lower total cost of ownership over experimental machine learning. The Spanish Data Protection Agency enforces GDPR transparency requirements that constrain customer insights dataset scope. Valencia hosts emerging demand for CSRD sustainability reporting automation.
Poland
Warsaw cooperative banks operate with minimal analytics sophistication, presenting white-space demand for templated cloud-native deployments. The Polish Financial Supervision Authority applies EU AI Act risk classifications with transitional flexibility for smaller institutions. Krakow's IT services cluster supplies implementation talent for regional platform rollouts.
Europe Data Analytics in Banking Market Competitive Landscape
Core banking incumbents and cloud-native challengers split the market along legacy integration versus greenfield deployment vectors. The vendor base concentrates around three strategic archetypes: Swiss-German core banking specialists with deep ERP connectivity, American hyperscale platforms extending database-layer analytics, and Indian IT services firms offering managed implementation capacity. Competitive moves center on subscription pricing realignment and partnership structures that externalize compliance responsibility.
Within the core banking integration tier, Temenos leverages its Swiss heritage to sustain dominance in downstream analytics feed architectures. SAP anchors the ERP connectivity vector through deep institutional workflow embedding. Oracle competes by extending database-layer analytics directly into banking operations, exemplifying the hyperscale platform archetype. These three represent distinct strategic positions rather than interchangeable substitutes.
| Leading Market Players |
|---|
| Temenos |
| FIS |
| Finastra |
| SAP |
| Oracle |
| Infosys |
| Fiserv |
| NICE |
| Avaloq |
| Others |
Value Network & Pricing Analysis
Overcapacity in cloud compute regions serving Frankfurt and Amsterdam is compressing infrastructure margins while forcing analytics vendors toward consumption-based pricing models that align costs with transaction volatility.
Pricing Analysis
Geographic price spreads between German systemically important institutions and Polish cooperative banks exceed three-to-one for equivalent platform capabilities. The dominant model is subscription-tiered SaaS pricing with consumption scaling, where price differentiation rests on data residency certification levels and after-sales service bundling. Cost compression in the mid-tier segment is intensifying because Spanish and Italian institutions trade capital expenditure flexibility for operational agility. Polish cooperative banks exhibit the highest price sensitivity, while Frankfurt's banking cluster demonstrates lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Export-control regimes restricting advanced GPU and quantum-encryption technology flows into European financial infrastructure are fragmenting vendor access to specialized hardware. Supply concentrates in the United States, Taiwan, and Ireland for cloud-native platform development, with raw material dependencies spanning semiconductor lithography equipment, high-bandwidth memory modules, and cryptographic processing units. Single-source vulnerability sits with NVIDIA's dominance in AI training accelerators. Distribution runs through hyperscale provider marketplaces and specialized systems integrators with ECB model risk management credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Data Analytics in Banking Market is entering a cyclical recovery phase as the EU AI Act implementation timeline forces replacement demand for non-compliant legacy systems.
For Market Incumbents: Harden algorithmic audit trail capabilities to defend against cloud-native challengers exploiting ECB model validation bottlenecks. Invest in backward integration into privacy-preserving computation infrastructure to capture GDPR-compliant analytics premiums. Vertical control over federated learning development reduces dependency on external cryptography specialists. For New Entrants and Emerging Players: Pursue white-space penetration in Poland's cooperative banking segment where templated cloud-native deployments face minimal incumbent saturation. Target managed services positioning that externalizes AI Act compliance responsibility for mid-tier Benelux institutions. A direct sales model through Krakow's IT services cluster minimizes customer acquisition costs relative to Frankfurt-centric approaches. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native analytics sub-segments as subscription pricing displaces perpetual license revenue recognition. Long-term viability favors acquisition targets with demonstrable EU AI Act high-risk system pre-certification and established ECB supervisory relationships. The signal to monitor is BaFin enforcement discretion on transitional compliance timelines for smaller institutions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidating fraud detection and customer personalization engines compresses vendor margins while demanding higher SLA guarantees. |
| Regulatory Pre-Certification | EU AI Act high-risk system designation requires human oversight mechanisms and algorithmic impact assessments before deployment. |
| Geographic Expansion | Poland's underpenetrated mid-tier segment presents white-space demand for standardized cloud-native platform rollouts. |
| Strategic Partnership | Partnership structures that externalize ECB model risk management obligations are gaining traction among Benelux institutions. |
| Acquisition of Specialist Firm | Privacy-preserving computation specialists with federated learning capabilities unlock previously restricted customer datasets for modeling. |
Research Methodology
A standing panel of chief data officers, model risk management leads, ECB supervisory specialists, and cloud procurement officers provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against EBA stress test disclosures, BaFin enforcement notices, EU AI Act implementation guidance, and hyperscaler capex allocation reports. Bottom-up deployment estimates triangulated against top-down banking IT spend forecasts.
Scenario-bracketing framed projections across the analysis window, modeling four intersecting segmentation dimensions: regulatory use case, processing technology, institutional user type, and infrastructure delivery model. CAGRs derived from elasticity-adjusted adoption curves incorporating SEPA corridor compliance deadlines and CSRD sustainability reporting convergence timelines. Forecast inputs included real-time transaction volume growth and cloud-native platform migration velocity.
Macroeconomic conditions sit as an overlay; deviation in ECB interest rate trajectories or cross-border data flow restrictions would shift the trajectory. Forecasts reflect documented assumptions on AI Act enforcement consistency and GDPR Article 44 interpretation stability. Material shifts in EU AI Act high-risk system designation scope or ECB model validation standard stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Banking Maintenance Support and Services Market
Banking
Smart Banking Solutions Market
Banking
US Investment Banking Market
Banking
Banking Wearable Devices Market
Banking
Bank Guarantee Market
Banking
Asia-Pacific Challenger Banks Market
Banking
Latin America Data Analytics in Banking Market
Banking
Banking Wearable Market
Banking
Asia-Pacific Islamic Finance Market
Banking
Australia Data Analytics in Banking Market
Banking
Global Banking BPS Market
Banking
China Retail Banking System Market
Banking
North America Challenger Banks Market
Banking
Digital Banking Market
Banking
Cloud Computing Banking Market
Banking
Payment Bank Solutions Market