
 Contactless Smart Cards in Banking Sales Market | 2026-2036
Contactless Smart Cards in Banking Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Contactless Smart Cards in Banking Sales Market Insights
Consolidation among tier-one retail banks is repositioning procurement power toward institutions with multi-million-card annual volumes. IDEMIA leverages its manufacturing scale across European and Asian production facilities to serve these concentrated buyers. Giesecke+Devrient anchors its position through deep relationships with central banks and national payment schemes. Thales competes by integrating secure element design with end-to-end personalization services.
Contactless smart cards in banking embed radio-frequency communication interfaces, typically operating at 13.56 MHz with ISO/IEC 14443 compliance, enabling tap-to-pay authentication without physical insertion. These devices serve primarily to reduce transaction friction while maintaining cryptographic security for card-present payments. The technology dimension shows NFC-enabled EMV chip configurations commanding the dominant share of new issuance, while biometric authentication represents the fastest-growing tier as issuers seek differentiation against mobile wallets. Within application segments, point-of-sale deployment remains the volume anchor, though transit-access convergence is opening incremental card slots in urban mobility programs.
The European Banking Authority's PSD2 strong customer authentication requirements, alongside PCI SSC contactless payment standards and national central bank issuance guidelines in India and Brazil, collectively shape product certification pathways and interoperability mandates. EMVCo compliance now functions as a baseline market-access filter rather than a competitive differentiator. Stakeholders must monitor how biometric template storage standards evolve, as this will determine whether authentication logic stays card-bound or migrates to host-device architectures.
Market Dynamics
EMVCo compliance mandates from payment networks are compressing hardware refresh cycles while consolidating procurement power toward retail banks with multi-million-card annual volumes, fundamentally restructuring supplier-buyer relationships across the value chain.
Growth Catalysts
- India's RBI Digital Payment Push:The Reserve Bank of India's guidelines for contactless transaction limits and tokenization infrastructure are accelerating card issuance in urban banking corridors.
- Transit-Access Convergence:Municipal mobility programs in São Paulo and London are opening incremental card slots as banking credentials merge with urban transport authentication systems.
- Biometric Template Integration:Fingerprint-on-card modules are gaining traction as issuers seek differentiation against smartphone-based payment wallets.
Market Restraints
- Secure Element Supply Concentration:Foundry capacity for certified smart card microcontrollers concentrates among three European and East Asian semiconductor suppliers, creating input bottlenecks during demand surges.
- PCI SSC Certification Friction:Contactless payment security standard updates require 12-18 month recertification cycles that freeze product roadmaps and delay revenue recognition.
- Mobile Wallet Substitution:Device-bound NFC credentials from Apple Pay and Google Pay are capturing transaction volume in premium urban demographics, compressing plastic card utility in developed markets.
Strategic Opportunities
- Brazil's Unbanked Corridor:The national instant payment scheme Pix is creating infrastructure for contactless card issuance to previously cash-dependent populations in Northeast urban centers.
- Biometric-EMV Convergence:Match-on-card architectures that fuse fingerprint sensors with traditional chip modules offer premium positioning against commoditized dual-interface plastic.
- Central Bank Digital Currency Interfaces:Pilot programs in Nigeria and the Eastern Caribbean are testing hybrid cards that bridge CBDC wallets with legacy payment rails.
Industry Challenges
- Personalization Equipment Capex:Laser engraving and secure data injection machinery requires seven-figure capital commitments that strain mid-tier card bureau balance sheets.
- Legacy Core Banking Integration:Mainframe-dependent institutions in Southeast Asia face 18-24 month timelines to enable real-time contactless transaction authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contactless Smart Cards in Banking Sales Market |
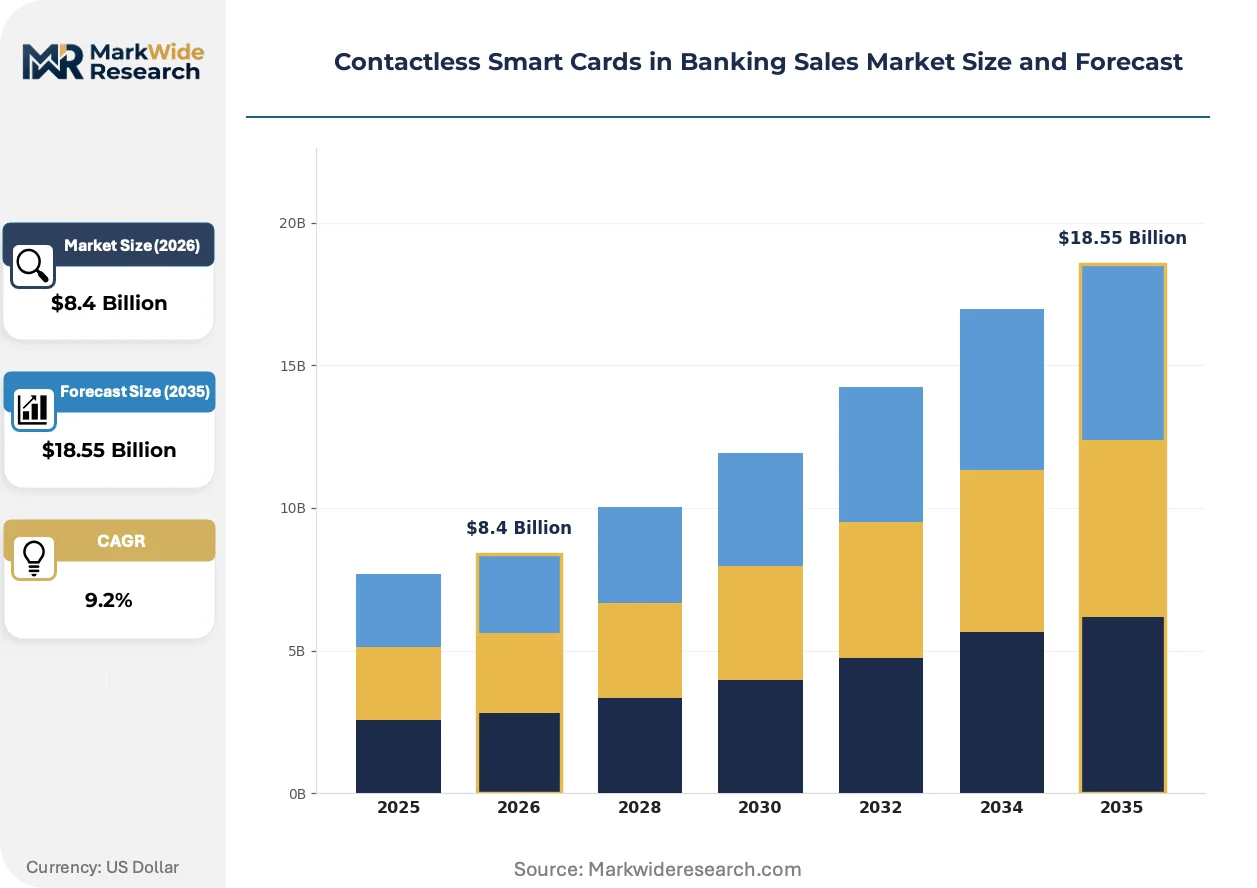
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Credit Cards, Debit Cards, Prepaid Cards, Gift Cards, Loyalty Cards Technology: NFC, RFID, Secure Element, EMV Chip, Biometric Authentication Application: Point of Sale, ATM Transactions, Metro Transit, Access Control, Online Payments End User Segment: Retail Banks, Credit Unions, Payment Processors, FinTech Companies |
| Companies Covered | IDEMIA, Giesecke+Devrient, Thales, NXP Semiconductors, Infineon Technologies, CPI Card Group, STMicroelectronics, Entrust Corporation, CardLogix Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contactless Smart Cards in Banking Sales Market Trends and Innovations
Authentication logic is migrating from host-device architectures toward card-bound biometric templates, while regulatory mandates on strong customer authentication are forcing hardware refresh decisions that favor integrated secure element suppliers.
Biometric-on-card modules combining capacitive fingerprint sensors with EMV-compliant secure elements are rewriting competitive positioning in premium issuance tiers. Tier-one retail banks in France and South Korea are piloting these devices for high-net-worth segments. The technology is compressing differentiation timelines as mobile wallet feature parity forces plastic credentials toward physical security superiority.
The European Banking Authority's PSD2 strong customer authentication requirements are mandating dynamic linking of transaction amount and payee identity to authentication credentials. Hardware manufacturers must embed cryptographic counters that satisfy both EMVCo and EBA technical standards. Dual-interface card shipments to EU member states now carry certification documentation spanning three regulatory frameworks rather than one.
Consolidation among tier-one issuers is concentrating annual procurement volumes into fewer hands with greater negotiating leverage. Regional card bureaus in Poland and Malaysia are losing share to global personalization houses that can guarantee million-unit quarterly throughput. This concentration is most visible in India's urban banking corridors where State Bank of India and HDFC Bank together account for the majority of contactless migration volume.
Contactless Smart Cards in Banking Sales Market Segmentation
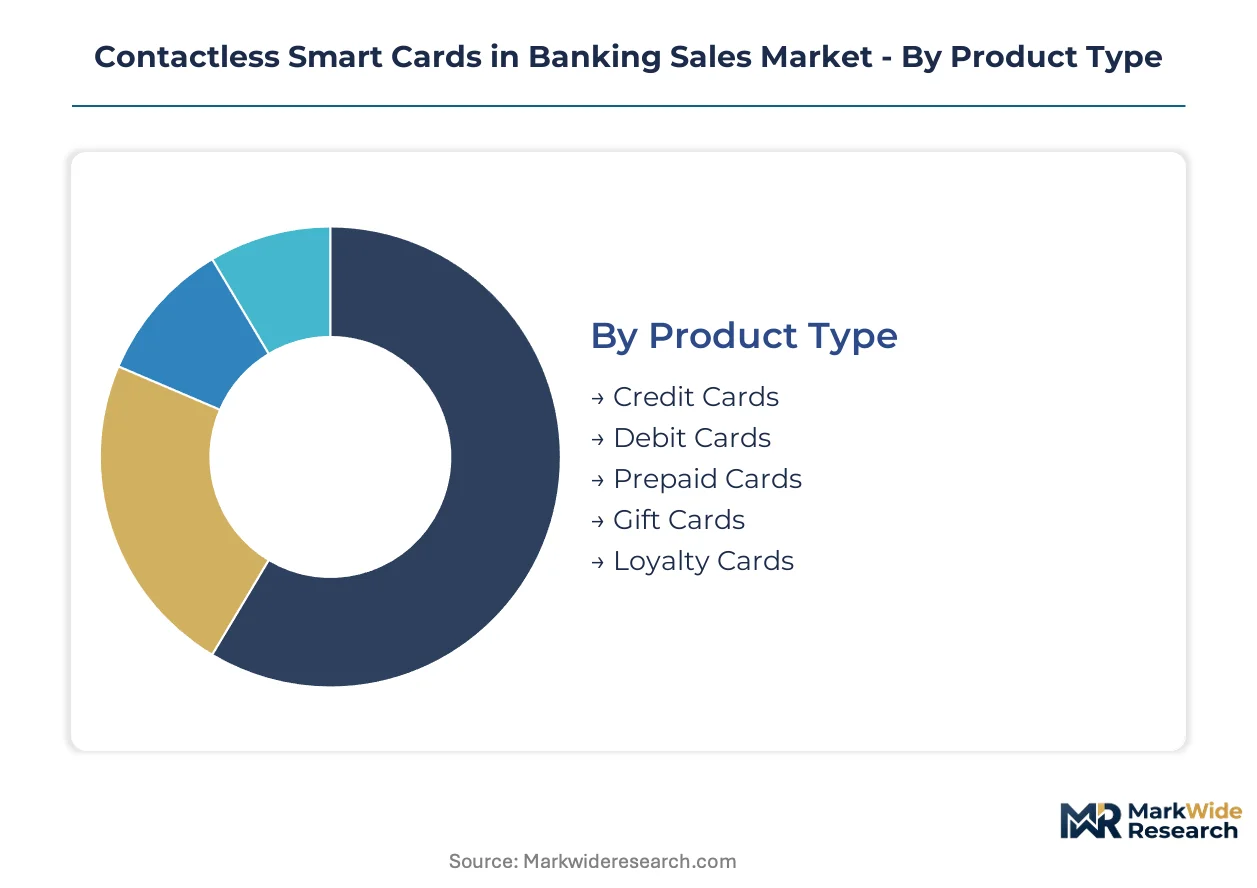
Segmentation in contactless smart cards reveals how hardware specifications, authentication protocols, and deployment contexts fragment procurement requirements across banking and adjacent payment ecosystems. Understanding these divisions exposes where volume concentrates versus where technology premiums command pricing power.
Product Type:
Standalone plastic credentials dominate issuance volumes, while embedded-form-factor cards serve transit-converged and co-branded programs where physical durability requirements exceed standard PVC constructions.
- Credit Cards:Dual-interface EMV configurations with NFC antennas laminated between PVC layers serve revolving-credit portfolios at tier-one retail banks. Demand clusters in India's urban banking corridors where HDFC Bank and State Bank of India are migrating magnetic-stripe portfolios to contactless rails under RBI guidelines.
- Debit Cards:PIN-prioritized chip modules with lower cryptographic throughput than credit-tier products anchor mass-market checking account programs. Issuance concentrates among payment processors serving credit unions and regional banks in Brazil's Northeast urban centers where Pix infrastructure enables first-time cardholding populations.
- Prepaid Cards:Single-load or reloadable stored-value credentials with simplified KYC onboarding serve underbanked demographics and corporate disbursement programs.
- Gift Cards:Closed-loop or open-loop prepaid instruments with limited authentication requirements target seasonal retail distribution and incentive marketing channels.
- Loyalty Cards:Co-branded payment credentials integrating merchant reward programs with banking rails require custom antenna tuning for dual-brand acceptance.
Volume placements concentrate in Debit Cards; the faster expansion belongs to Credit Cards.
Technology:
Cost tiering separates certified secure-element modules from commodity radio-frequency interfaces, with biometric layers commanding 3-4x hardware premiums over baseline NFC configurations.
- NFC:Near-field communication interfaces operating at 13.56 MHz with ISO/IEC 14443 Type A/B compliance form the baseline radio layer for tap-to-pay acceptance. Deployment concentrates at point-of-sale terminals across Southeast Asian retail banks expanding contactless issuance to capture unbanked populations.
- EMV Chip:Europay-Mastercard-Visa certified secure microcontrollers with cryptographic coprocessors handle transaction authorization and offline PIN verification. EMVCo compliance mandates from payment networks are accelerating hardware refresh cycles among issuers with multi-million-card annual volumes.
- RFID:Ultra-high-frequency or low-frequency radio interfaces serve niche access-control and asset-tracking applications outside standard payment acceptance networks.
- Secure Element:Tamper-resistant hardware enclaves with Common Criteria EAL4+ certification protect cryptographic keys against physical and side-channel attacks.
- Biometric Authentication:Fingerprint-on-card modules combining capacitive sensors with match-on-card architectures are gaining traction as issuers seek differentiation against smartphone-based payment wallets.
EMV Chip configurations anchor current procurement volumes; Biometric Authentication is climbing the fastest as premium issuers in France and South Korea pilot fingerprint-enabled devices for high-net-worth segments.
Application:
Application context determines antenna specification, transaction velocity requirements, and backend integration complexity—factors that reshape supplier selection beyond unit cost considerations.
- Point of Sale:Retail payment acceptance with sub-500ms transaction completion times requires optimized RF field coupling and minimal power draw from terminal proximity. Deployment concentrates in India's urban banking corridors where digital payment infrastructure is scaling fastest.
- ATM Transactions:Contactless cash withdrawal and balance inquiry functions demand backward compatibility with legacy motorized card readers while enabling tap-and-go authentication at modernized terminals.
- Metro Transit:Open-loop fare payment convergence with banking credentials requires cards to survive flexing, abrasion, and electromagnetic interference in high-throughput turnstile environments. Municipal mobility programs in São Paulo and London are opening incremental card slots as banking credentials merge with urban transport authentication systems.
- Access Control:Physical security applications leveraging banking-grade authentication for building entry and logical access serve enterprise campus and government facility deployments.
- Online Payments:Card-not-present authentication through dynamic CVV generation or tokenized credential presentation requires secure element integration with issuer mobile applications.
Point of Sale maintains the dominant placement share; Metro Transit is gaining share fastest as transit-access convergence opens hybrid use cases.
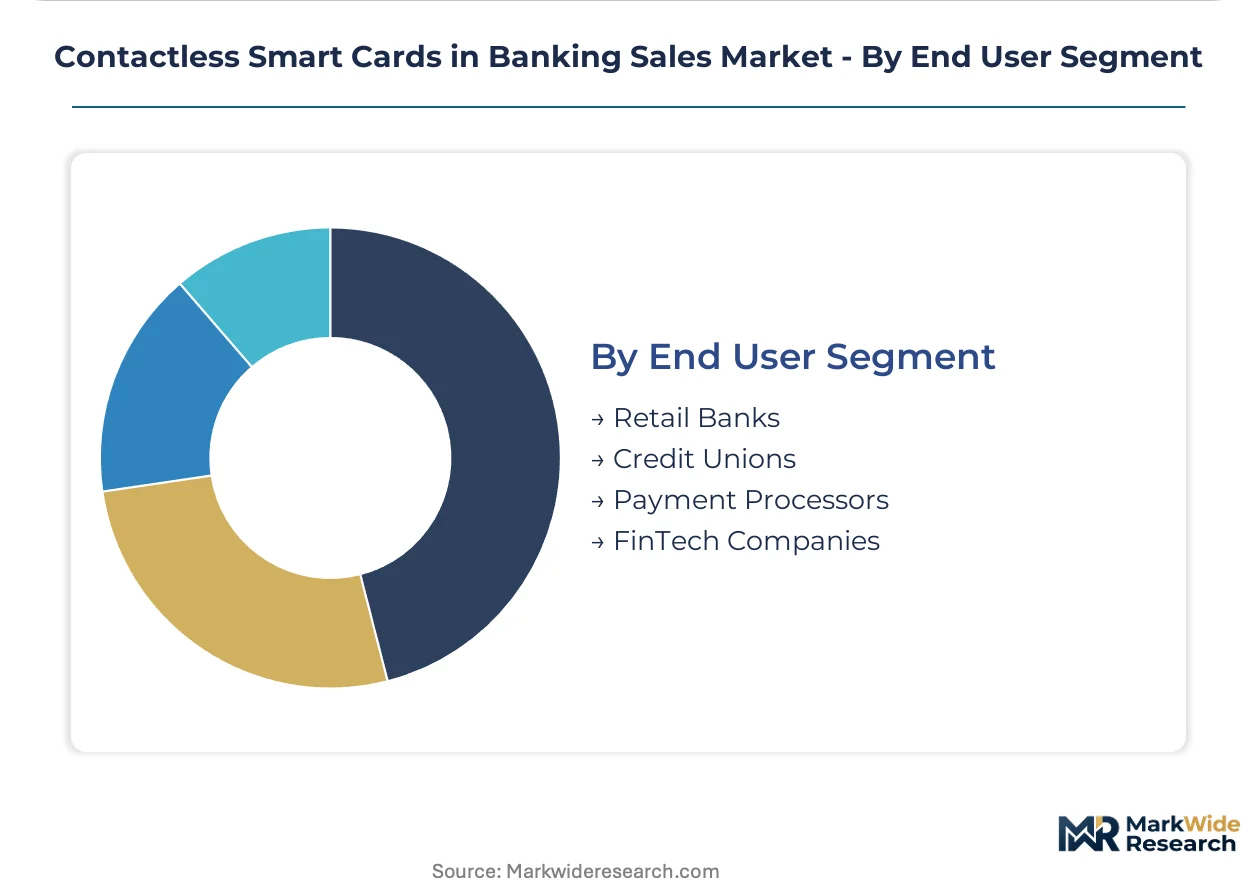
End User Segment:
Customer type segmentation exposes procurement scale disparities: retail banks with centralized treasury functions negotiate million-unit annual contracts, while credit unions and FinTechs favor flexible personalization services over volume discounts.
- Retail Banks:Full-service deposit and lending institutions with proprietary card issuance programs and in-house personalization capabilities. Consolidation among tier-one institutions is repositioning procurement power toward entities with multi-million-card annual volumes.
- Payment Processors:Third-party card program managers serving smaller financial institutions through bureau personalization and BIN sponsorship arrangements. Regional card bureaus in Poland and Malaysia are losing share to global personalization houses that can guarantee million-unit quarterly throughput.
- Credit Unions:Member-owned cooperative banks with limited IT infrastructure dependence on processor-managed card programs with standardized EMV templates.
- FinTech Companies:Digital-native challengers with API-first core banking platforms favor cloud-integrated personalization APIs and just-in-time card fulfillment over traditional batch issuance cycles.
Retail Banks command the dominant procurement volume; FinTech Companies are expanding most quickly as neobank challengers scale contactless-first product architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Taiwan and South Korea supplies the secure microcontrollers that anchor contactless card manufacturing across banking corridors worldwide.
India
Urban banking corridors in Mumbai, Delhi-NCR, and Bangalore are scaling contactless issuance fastest. RBI guidelines on contactless transaction limits and tokenization infrastructure are compressing hardware refresh timelines. State Bank of India and HDFC Bank together drive the majority of migration volume from magnetic-stripe portfolios.
Brazil
Northeast urban centers including Recife and Salvador are opening first-time cardholding populations through Pix-enabled infrastructure. The national instant payment scheme creates rails for contactless issuance to previously cash-dependent demographics. Central bank issuance guidelines favor dual-interface EMV configurations for unbanked corridor expansion.
United Kingdom
London's transit-access convergence programs are merging banking credentials with urban mobility authentication systems. Municipal mobility frameworks require cards to survive abrasion and electromagnetic interference in high-throughput turnstile environments. Tier-one retail banks are piloting biometric-on-card modules for high-net-worth segments.
Germany
Bavaria and North Rhine-Westphalia host personalization bureaus serving EU-wide EMVCo compliance mandates. The European Banking Authority's PSD2 strong customer authentication requirements are forcing hardware refresh decisions toward integrated secure element suppliers. Dual-interface card shipments now carry certification documentation spanning three regulatory frameworks.
South Korea
Seoul Capital Area financial institutions are piloting fingerprint-on-card devices for premium customer tiers. Biometric template integration is gaining traction as issuers seek differentiation against smartphone-based payment wallets. Match-on-card architectures command hardware premiums over baseline NFC configurations.
Contactless Smart Cards in Banking Sales Market Competitive Landscape
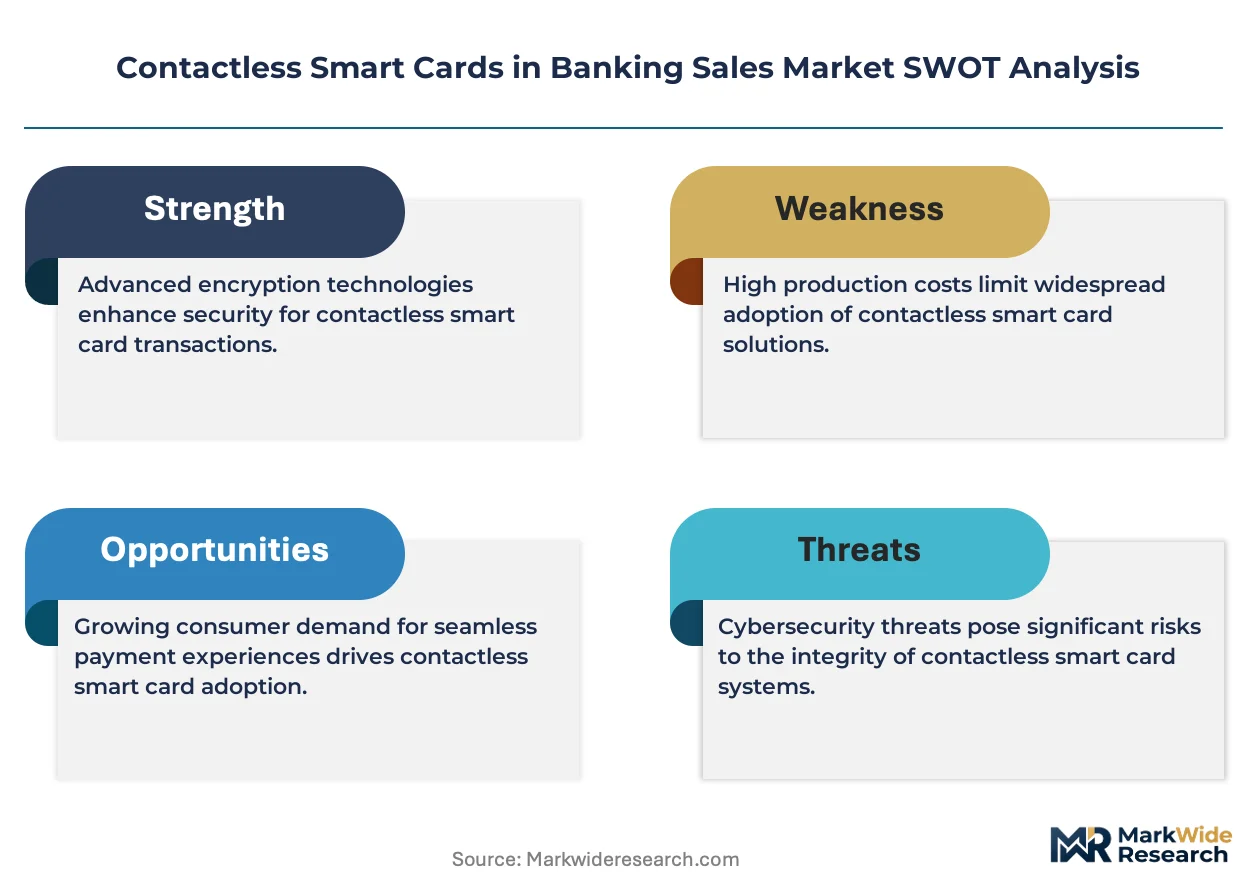
Established producers occupy the standard tier; emerging entrants pursue biometric authentication and CBDC interface adjacencies. The supplier base concentrates around secure element design, end-to-end personalization services, and manufacturing scale across multi-continental production footprints. Three archetypes dominate: integrated secure element suppliers, global personalization houses with million-unit quarterly throughput, and regional card bureaus serving mid-tier issuers. Competitive moves center on manufacturing scale expansion and strategic partnerships with central banks and national payment schemes.
Among European-anchored secure element specialists, IDEMIA, Giesecke+Devrient, and Thales exemplify the integrated-supplier archetype. IDEMIA represents manufacturing-scale positioning across European and Asian production facilities. Giesecke+Devrient occupies a position anchored through relationships with central banks and national payment schemes. Thales sits within the tier combining secure element design with end-to-end personalization services. These three entities collectively illustrate how procurement power consolidation toward multi-million-card annual volumes is restructuring supplier-buyer dynamics across the value chain.
| Leading Market Players |
|---|
| IDEMIA |
| Giesecke+Devrient |
| Thales |
| NXP Semiconductors |
| Infineon Technologies |
| CPI Card Group |
| STMicroelectronics |
| Entrust Corporation |
| CardLogix Corporation |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up personalization specialists have consolidated regional card bureaus across Poland and Malaysia, tightening supply discipline while anchoring pricing power in million-unit quarterly throughput commitments from tier-one retail banks. This ownership concentration feeds back into procurement dynamics as concentrated buyers extract volume discounts that strain mid-tier bureau margins.
Pricing Analysis
The volume-versus-margin split separates million-unit annual contracts at 40-60% discounts from spot orders at list pricing. Three-tier pricing structure across biometric-enabled premium, dual-interface standard, and single-interface economy levels tracks certification grade and EMVCo compliance tier. Cost compression in the standard tier is intensifying because NXP Semiconductors and Infineon Technologies exercise foundry pricing power over secure microcontroller supply. Regional credit unions exhibit highest price sensitivity; tier-one retail banks with centralized treasury functions leverage lowest sensitivity through committed offtake agreements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from State Bank of India and HDFC Bank, while distributor-mediated flows serve credit unions and FinTech challengers. Silicon foundry capacity concentrates in Taiwan and South Korea, with final card assembly feeding from Germany and Malaysia. Supply draws from PVC substrate, NFC antenna copper coil, and Common Criteria EAL4+ certified secure microcontrollers as core inputs. Single-source vulnerability in certified smart card microcontroller foundries creates bottleneck exposure during demand surges. Distribution runs through central bank-certified personalization bureaus with EMVCo audit compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EMVCo certification mandates erect barrier-to-entry moats favoring incumbents with twelve-to-eighteen-month recertification capabilities and frozen product roadmap discipline.
For Market Incumbents: Cement manufacturing scale advantages through captive secure element supply agreements with Taiwan and South Korea foundries. Deepen personalization bureau automation to absorb PCI SSC recertification cycle costs that freeze mid-tier competitor roadmaps. Biometric-on-card module R&D investment defends against mobile wallet substitution in premium urban demographics. For New Entrants and Emerging Players: Launch via cloud-integrated personalization APIs serving FinTech challengers with just-in-time fulfillment models that bypass batch issuance infrastructure. Brazil's Northeast urban centers and India's tier-two banking corridors present most penetrable geographies where Pix-enabled and RBI-guided infrastructure reduces incumbent relationship stickiness. Biometric-EMV convergence for high-net-worth segments offers premium positioning against commoditized dual-interface plastic. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier personalization bureaus in Southeast Asia with central bank relationships and underutilized laser engraving capacity. Long-term viability hinges on biometric template storage standard evolution determining whether authentication logic stays card-bound or migrates host-ward. Watch EMVCo specification updates as inflection signal for hardware refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secure Element Supply | Captive foundry agreements with Taiwan semiconductor houses insulate against input bottlenecks during demand surges. |
| Biometric-on-Card Module Certification | Match-on-card architectures with capacitive fingerprint sensors command premium positioning in France and South Korea. |
| Central Bank Digital Currency Interface Development | Hybrid card pilots in Nigeria and the Eastern Caribbean bridge CBDC wallets with legacy payment rails. |
| Transit-Access Convergence Partnership | Municipal mobility programs in São Paulo and London merge banking credentials with urban transport authentication systems. |
| Cloud-Integrated Personalization API Launch | API-first fulfillment models serve neobank challengers scaling contactless-first product architectures. |
Research Methodology
Independent corroboration across card bureau operations executives, EMVCo certification auditors, central bank payment system directors, and retail bank procurement leads underwrites the qualitative findings. Secondary validation draws from RBI circulars on contactless transaction limits, PCI SSC security standard documentation, EMVCo compliance bulletins, and payment processor annual disclosures. Bottom-up shipment estimates from personalization bureaus triangulate against top-down payment network issuance data across the analysis window.
Comparable-period anchoring to magnetic-stripe-to-contactless migration curves in India and Brazil shapes the projection framework. Segmentation modeling spans product type, technology tier, application context, and end-user archetype dimensions throughout the forecast period. CAGRs derive from hardware refresh cycle velocity under EMVCo mandates and biometric authentication adoption curves. Forecast inputs incorporate foundry capacity utilization rates and central bank digital payment infrastructure deployment timelines.
Regulatory specification changes, secure element supply disruptions, and mobile wallet penetration acceleration are the dominant revision risks. Forecasts reflect assumptions on EMVCo compliance timeline stability and biometric template standard convergence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Germany Data Analytics in Banking Market
Banking
Banking Software Market
Banking
Global Neobanking Market
Banking
Investment Banking Market
Banking
Banking As a Service (BAAS) Market
Banking
US Banking-As-A-Service Market
Banking
Global Retail Core Banking Systems Market
Banking
Payment Bank Solutions Market
Banking
Cloud Billing in Banking Market
Banking
South America Challenger Banks Market
Banking
France Data Analytics in Banking Market
Banking
Australia Data Analytics in Banking Market
Banking
Credit Intermediation Market
Banking
Singapore Data Analytics in Banking Market
Banking
Middle East Data Analytics in Banking Market
Banking
India Data Analytics in Banking Market