
 US Retail Banking Market | 2026-2036
US Retail Banking Market Size, Share, and Industry Trends Forecast 2026-2036
US Retail Banking Market Analytics
Small business owners is reorganizing demand within US retail banking, pulling share from mass-market individual consumers as entrepreneurs seek integrated treasury and lending solutions. JPMorgan Chase anchors this shift through its commercial banking arm's branch density in high-growth metros. Capital One Financial differentiates via technology leadership in digital-first small business credit products. Wells Fargo sustains relevance through its legacy agricultural and commercial real estate lending networks.
US retail banking encompasses deposit-taking, consumer credit extension, payment facilitation, and wealth management services delivered to individuals and small enterprises through regulated financial intermediaries. Core products include demand deposit accounts bearing near-zero interest, term loans underwritten through FICO-based risk scoring, and payment networks operating on ACH and real-time rail infrastructure. Checking accounts and credit cards dominate transaction volume, while mobile banking channels are displacing branch-based service delivery fastest among individuals under forty. Loans command the widest interest spreads, though savings accounts with high-yield features are capturing deposits from rate-sensitive customers in competitive markets like Atlanta and Dallas.
The Federal Reserve shapes market access through reserve requirements and stress testing protocols under CCAR, while the Consumer Financial Protection Bureau enforces disclosure standards and fair lending rules that constrain product pricing flexibility. The Office of the Comptroller of the Currency supervises national bank charters, creating compliance thresholds that favor scaled players with dedicated regulatory technology investments. Stakeholders must monitor how the SEC's climate disclosure rules and evolving state-level data privacy statutes in California and New York reshape data architecture requirements and customer consent frameworks.
Market Dynamics
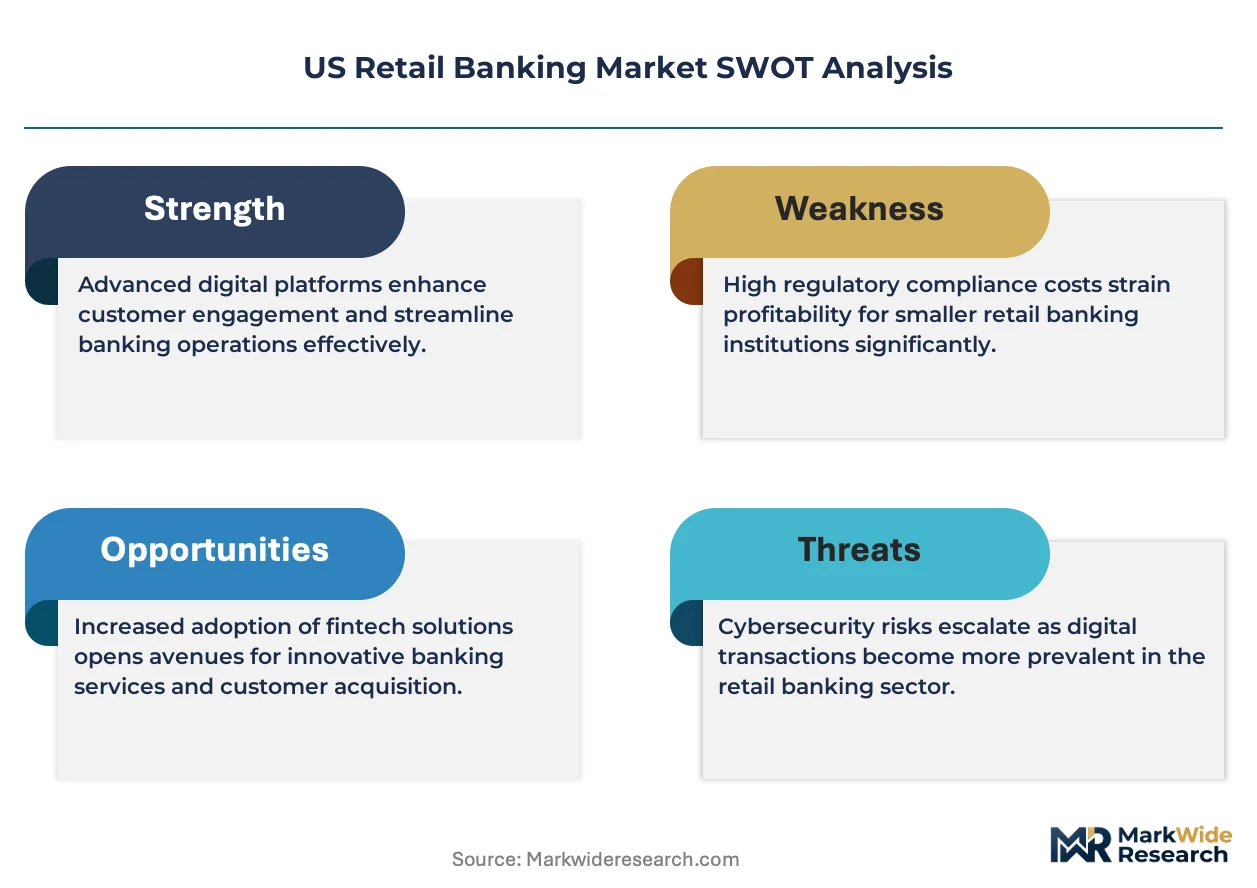
Deposit migration toward high-yield digital accounts is compressing net interest margins across branch-dependent institutions while accelerating technology investments in automated underwriting infrastructure.
Growth Catalysts
- Open Banking Frameworks:The Consumer Financial Protection Bureau's data portability mandates enable third-party fintech integration, expanding addressable customer bases for API-enabled institutions.
- Texas and Florida Demographics:Population inflows into Dallas-Fort Worth and Miami metro corridors sustain organic deposit growth without proportional branch expansion costs.
- Real-Time Payment Rails:FedNow infrastructure deployment reduces settlement friction for small business treasury operations, unlocking integrated cash management adoption.
Market Restraints
- Interest Rate Sensitivity:Certificate of deposit repricing velocity compresses duration-matched asset yields faster than liability costs adjust.
- Regulatory Capital Requirements:Federal Reserve stress testing protocols under CCAR constrain balance sheet expansion for sub-regional institutions below $250 billion assets.
- Deposit Beta Asymmetry:Rate-sensitive customers migrate to direct banks and credit unions, fragmenting core funding stability.
Strategic Opportunities
- Embedded Finance Integration:Banking-as-a-Service APIs enable non-financial platforms to originate deposits and payments without charter acquisition.
- Small Business Credit Automation:Cash-flow-based underwriting algorithms expand addressable lending pools beyond FICO-constrained traditional scoring.
- State-Level Privacy Tailwinds:California Consumer Privacy Act and New York SHIELD Act create compliance complexity that favors scaled institutions with dedicated data architecture investments.
Industry Challenges
- Core System Modernization:Legacy mainframe dependencies constrain real-time product deployment and increase integration costs with cloud-native fintech partners.
- Talent Acquisition:Competition for machine learning engineers and data infrastructure specialists elevates compensation costs above traditional banking salary bands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Retail Banking Market |
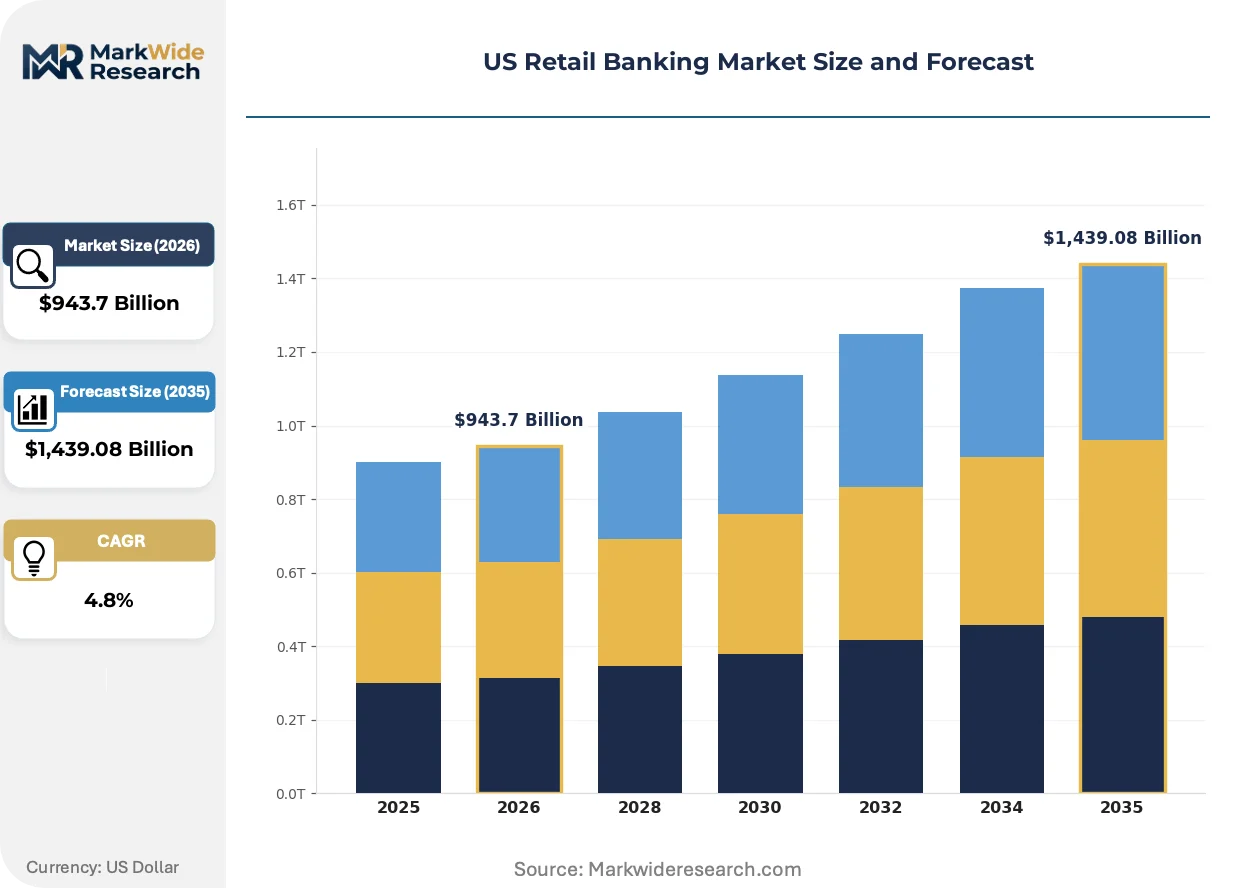
| Market Size in 2026 | $943.7 Billion |
| Market Size in 2035 | $1,439.08 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Savings Accounts, Checking Accounts, Credit Cards, Loans Customer Type: Individuals, Small Businesses, Corporates, Non-Profits Channel: Online Banking, Mobile Banking, Branch Banking, ATMs Account Features: No Fees, High Interest Rates, Cashback Rewards, Easy Transfers |
| Companies Covered | Citigroup, Capital One Financial, JPMorgan Chase, Truist Financial, PNC Financial Services, Bank of America, U.S. Bancorp, Goldman Sachs, Wells Fargo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Retail Banking Market Evolving Landscape
Artificial intelligence applications are restructuring customer acquisition economics and risk assessment velocity across deposit and lending products.
Generative AI is bifurcating customer service operations across the sector. Large language models handle routine transaction inquiries and account servicing through conversational interfaces. Institutions with advanced deployments reduce call center headcount while compressing average handle times. This technology is bifurcating the market between AI-native digital banks and branch-dependent incumbents facing stranded cost structures.
The Consumer Financial Protection Bureau's open banking rulemaking imposes standardized data sharing protocols and consent management requirements. Institutions must restructure data architecture to enable third-party access while maintaining cybersecurity posture. National banks with existing API infrastructure adapt faster than regional institutions dependent on legacy core processors.
Small business owners now demand integrated treasury platforms combining deposit accounts, receivables financing, and expense management within single interfaces. Traditional branch-based relationship models lose share to vertical software platforms embedding financial services. This pattern concentrates in high-growth metro corridors where entrepreneur density sustains platform economics.
US Retail Banking Market Segmentation
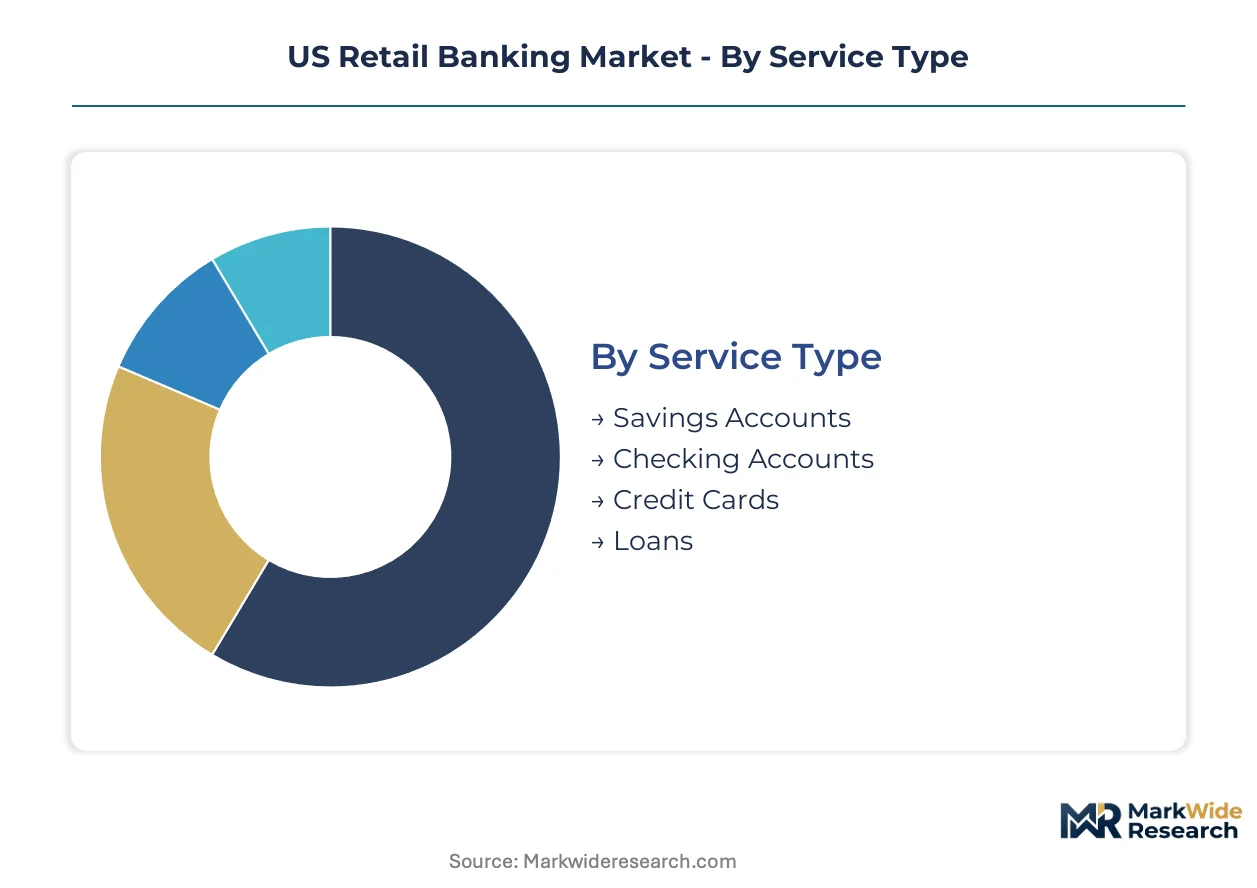
Segmentation in US retail banking reveals how regulatory frameworks and technology investments create divergent profitability profiles across service lines and customer cohorts. Institutions optimize capital allocation by matching product architecture to specific compliance burdens and acquisition economics.
Service Type:
The Federal Reserve's reserve requirements and the CFPB's disclosure mandates impose distinct compliance costs across deposit and credit products, shaping competitive positioning.
- Savings Accounts:Interest-bearing deposit vehicles with tiered rate structures. Demand concentrates in Dallas-Fort Worth and Miami corridors where population inflows from high-tax states sustain organic deposit growth without proportional branch expansion.
- Checking Accounts:Demand deposit accounts with near-zero interest and payment facilitation features. Small business owners in Texas and Florida drive integrated treasury adoption, pulling share from mass-market individual consumers as entrepreneurs seek unified cash management solutions.
- Credit Cards:Revolving credit lines underwritten through FICO-based risk scoring with interchange revenue models.
- Loans:Term credit products commanding the widest interest spreads across consumer and commercial segments.
Established volume favors checking accounts; emerging adoption favors integrated small business lending suites.
Customer Type:
Acquisition economics vary sharply across cohorts, with digital onboarding reducing branch dependency for entrepreneurs while corporates sustain relationship-based pricing.
- Individuals:Mass-market consumers under forty displace branch-based service delivery fastest through mobile banking channels, though rate-sensitive customers migrate to direct banks and credit unions fragmenting core funding stability.
- Small Businesses:Entrepreneur segments expanding share of lending products as cash-flow-based underwriting algorithms expand addressable pools beyond traditional FICO constraints.
- Corporates:Large enterprises with complex treasury operations requiring dedicated relationship management and customized credit facilities.
- Non-Profits:Mission-driven organizations with specialized compliance needs and restricted deposit utilization requirements.
Margin concentration sits with corporates; addressable base expansion favors small businesses.
Channel:
Technology investments in automated underwriting infrastructure accelerate as deposit migration toward high-yield digital accounts compresses net interest margins across branch-dependent institutions.
- Online Banking:Web-based platforms enabling account management and transaction execution. JPMorgan Chase anchors digital demand through commercial banking arm density in high-growth metros.
- Mobile Banking:Smartphone-native interfaces displacing physical channels fastest among younger demographics. Capital One Financial differentiates via technology leadership in digital-first credit products.
- Branch Banking:Physical locations sustaining relevance through agricultural and commercial real estate lending networks in legacy markets.
- ATMs:Self-service cash dispensing infrastructure with declining transaction share as real-time payment rails reduce settlement friction.
Cost efficiency favors mobile; relationship depth favors branch networks in specialized lending.
Account Features:
Product differentiation increasingly centers on data architecture investments that enable compliance with state-level privacy statutes in California and New York.
- No Fees:Zero-monthly-charge structures attracting price-sensitive depositors. Rate-sensitive customers in competitive markets like Atlanta and Dallas capture high-yield alternatives.
- High Interest Rates:Yield-focused accounts capturing deposits from rate-sensitive customers as certificate of deposit repricing velocity compresses duration-matched asset yields.
- Cashback Rewards:Transaction-based incentive programs driving credit card engagement and interchange revenue.
- Easy Transfers:Frictionless payment facilitation through ACH and FedNow real-time rail infrastructure.
Deposit stability favors high interest features; transaction volume favors cashback rewards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deposit flows from California and New York sustain lending capacity in Texas and Florida corridors. Population migration patterns reshape branch economics across state lines.
Texas
Dallas-Fort Worth and Houston metro corridors absorb deposit inflows from high-tax states, sustaining organic growth without proportional branch expansion. The Texas Department of Banking supervises state-chartered institutions under localized compliance frameworks. Entrepreneur density in Austin's technology corridor drives demand for integrated treasury platforms combining deposit accounts and receivables financing.
Florida
Miami and Tampa Bay metro areas attract retiree and small business capital seeking tax-advantaged deployment. Florida's Office of Financial Regulation enforces consumer protection standards that shape disclosure requirements for digital onboarding. The Southeast Florida banking cluster concentrates wealth management services for cross-border Latin American clientele.
California
Silicon Valley and Los Angeles basin institutions face deposit outmigration as rate-sensitive customers seek yield in direct banks. The California Department of Financial Protection and Innovation implements state-level privacy statutes that exceed federal baselines. San Francisco-based fintech partnerships reshape API infrastructure requirements for legacy core processors.
New York
New York City anchors commercial banking relationships requiring complex treasury operations and customized credit facilities. The New York State Department of Financial Services enforces cybersecurity regulations that elevate compliance costs for sub-regional institutions. The Manhattan financial district concentrates correspondent banking and payment clearing infrastructure.
Illinois
Chicago metro institutions serve agricultural and manufacturing supply chains across the Midwest corridor. The Illinois Department of Financial and Professional Regulation supervises mortgage lending practices that influence underwriting automation investments. The Chicago banking cluster sustains relevance through legacy commercial real estate lending networks.
US Retail Banking Market Competitive Landscape
Listed leaders compete with private specialists across deposit gathering and lending origination. The market structures around three tiers: money-center banks with national charters, regional institutions with state-level concentration, and digital-native platforms without branch infrastructure. Strategic archetypes include scale-driven deposit gatherers, technology-forward credit originators, and relationship-based commercial lenders. M&A activity consolidates regional footprints while API partnerships embed banking services into non-financial platforms.
Among national-scale institutions, JPMorgan Chase, Bank of America, and Wells Fargo occupy positions across the archetype spectrum. JPMorgan Chase exemplifies the integrated commercial banking model with metro corridor density. Bank of America represents technology-forward deployment across mobile and digital channels. Wells Fargo anchors relationship-based positioning through legacy agricultural and commercial real estate networks.
| Leading Market Players |
|---|
| Citigroup |
| Capital One Financial |
| JPMorgan Chase |
| Truist Financial |
| PNC Financial Services |
| Bank of America |
| U.S. Bancorp |
| Goldman Sachs |
| Wells Fargo |
| Others |
Value Network & Pricing Analysis
Long-term deposit beta contracts lock in funding cost visibility for institutions while constraining pricing flexibility when rate environments shift. These structures tether liability costs to Fed policy trajectories, forcing asset repricing strategies that compress net interest margins during inversion cycles.
Pricing Analysis
Digital-native versus branch-legacy pricing gaps widen as technology-forward institutions deploy automated underwriting to reduce acquisition costs. Three-tier pricing structure across premium relationship, standard retail, and economy digital tiers segments customers by service intensity and cross-sell potential. Pricing pressure stems from certificate of deposit repricing velocity outpacing asset yield adjustments. Rate-sensitive retail depositors exhibit highest price elasticity, while small business treasury clients accept premium pricing for integrated cash management functionality.
Supply Chain Analysis
The United States anchors core banking infrastructure production, with India and Ireland concentrating technology service delivery and back-office operations. Cloud computing capacity, specialized data infrastructure, and regulatory technology software constitute critical input dependencies. Single-source vulnerability concentrates in legacy core processor relationships that constrain real-time product deployment. Distribution runs through correspondent banking networks and API-enabled fintech partnerships rather than traditional branch expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deposit migration toward high-yield digital platforms shifts bargaining power toward rate-sensitive retail customers, fragmenting core funding stability for branch-dependent institutions.
For Market Incumbents: Compound defensive positioning through accelerated core system modernization and captive development of machine learning underwriting capabilities. Vertical integration into cloud-native data architecture reduces dependency on legacy processor relationships. Prioritize Texas and Florida metro corridor density to capture organic deposit inflows without proportional branch expansion costs. For New Entrants and Emerging Players: OCC fintech charter fast-tracks enable market entry without legacy compliance overhead burden. Embedded finance partnerships with vertical software platforms targeting Austin and Miami entrepreneur clusters offer lowest customer acquisition costs. White-space concentration sits with cash-flow-based small business lending algorithms that bypass traditional FICO constraints. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among institutions with integrated small business treasury platform adoption. Long-term viability favors scaled players with dedicated regulatory technology investments and API infrastructure. Monitor CFPB open banking implementation velocity as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Core System Modernization | Cloud-native migration reduces legacy processor dependency and enables real-time FedNow integration. |
| Small Business Credit Automation | Cash-flow-based underwriting algorithms expand addressable lending pools beyond FICO constraints. |
| Embedded Finance Partnership | Banking-as-a-Service APIs embed deposit and payment origination into non-financial platforms. |
| Metro Corridor Density Expansion | Texas and Florida branch positioning captures organic deposit inflows from high-tax state migration. |
| Regulatory Technology Investment | Dedicated compliance architecture addresses CFPB data portability and state-level privacy mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Federal Reserve statistical releases, FDIC call report data, and CFPB regulatory filings. Primary interviews engaged retail banking executives, digital product officers, regulatory compliance leads, and small business treasury managers. Secondary validation drew from SEC 10-K disclosures, NCUA financial reports, and fintech partnership announcements. Bottom-up deposit and lending volume estimates triangulate against top-down macroeconomic scenario modeling.
Segmentation dimensions modeled span service type, customer cohort, distribution channel, and account feature configuration across the projection horizon. CAGRs derive from historical growth rate analysis adjusted for demographic migration patterns, regulatory implementation timelines, and technology adoption curves. Forecast inputs incorporate Fed policy trajectory assumptions and open banking penetration scenarios.
Underlying assumptions cover interest rate normalization paths and deposit beta stability, with deviation risk concentrated in regulatory capital requirement changes and core system modernization execution. Recalibration cycles align with material shifts in CFPB rulemaking and FedNow infrastructure deployment velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Biometric Banking Wristband Market
Banking
Cardless ATM Market
Banking
Blockchain in Banking Market
Banking
Global Certificate of Deposit Market
Banking
E-Banking Market
Banking
Smart Banking Solutions Market
Banking
Smart ATM Market
Banking
Digital Banking Market
Banking
Germany Neobanking Market
Banking
ATM Market
Banking
Banking CRM Software Market
Banking
Asia-Pacific Data Analytics in Banking Market
Banking
Latin America Banking As a Service Market
Banking
Biometrics for Banking and Financial Services Market
Banking
UK Banking as a Service Market
Banking
Banking Wearable Devices Market