
 Smart Banking Solutions Market | 2026-2036
Smart Banking Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Banking Solutions Market Insights
Branch networks and direct-to-consumer digital channels is tilting decisively toward mobile-first engagement models. Temenos leverages its cloud-native core banking platform to serve tier-one institutions across multiple continents. Finastra sustains competitive pressure through open API marketplaces that connect banks with third-party fintech providers. Backbase specializes in engagement banking layers that sit atop legacy cores without requiring full replacement.
Smart banking solutions encompass software platforms, middleware, and analytics engines that automate credit decisions, detect anomalous transactions, and orchestrate customer journeys across touchpoints. These systems typically process sub-second API calls, maintain uptime above 99.9%, and integrate with core banking ledgers through ISO 20022 messaging standards. Payment processing and fraud detection solutions currently occupy the largest revenue pools, while compliance automation is expanding fastest as regulators tighten AML and KYC requirements. Cloud-based deployment dominates new implementations, though hybrid architectures persist among institutions with sovereign data constraints.
The EU's PSD2 and GDPR frameworks shape product roadmaps for any vendor serving European retail banks, while the US OCC and CFPB scrutinize fair lending algorithms and digital redlining risks. India's RBI mandates data localization for payment systems, forcing architecture decisions for global platform providers. Stakeholders must monitor how divergent regulatory timelines for AI governance create compliance complexity across jurisdictions.
Market Dynamics
Cloud-native core banking platforms are compressing replacement cycles from decade-long transformations to incremental layer-by-layer upgrades, forcing incumbent vendors to rearchitect delivery models around API-first engagement layers rather than monolithic system sales.
Growth Catalysts
- PSD2 Open Banking Mandates:European Union regulations compel legacy institutions to expose payment APIs, creating immediate demand for middleware vendors capable of ISO 20022 integration and consent management frameworks.
- Real-Time Payment Rails:India's UPI and Brazil's Pix instant payment systems demonstrate how government-backed infrastructure investments accelerate fraud detection and transaction orchestration software procurement.
- AI-Powered Credit Decisioning:Machine learning models trained on alternative data sources expand lending access to thin-file borrowers, driving adoption among retail banks seeking portfolio diversification.
Market Restraints
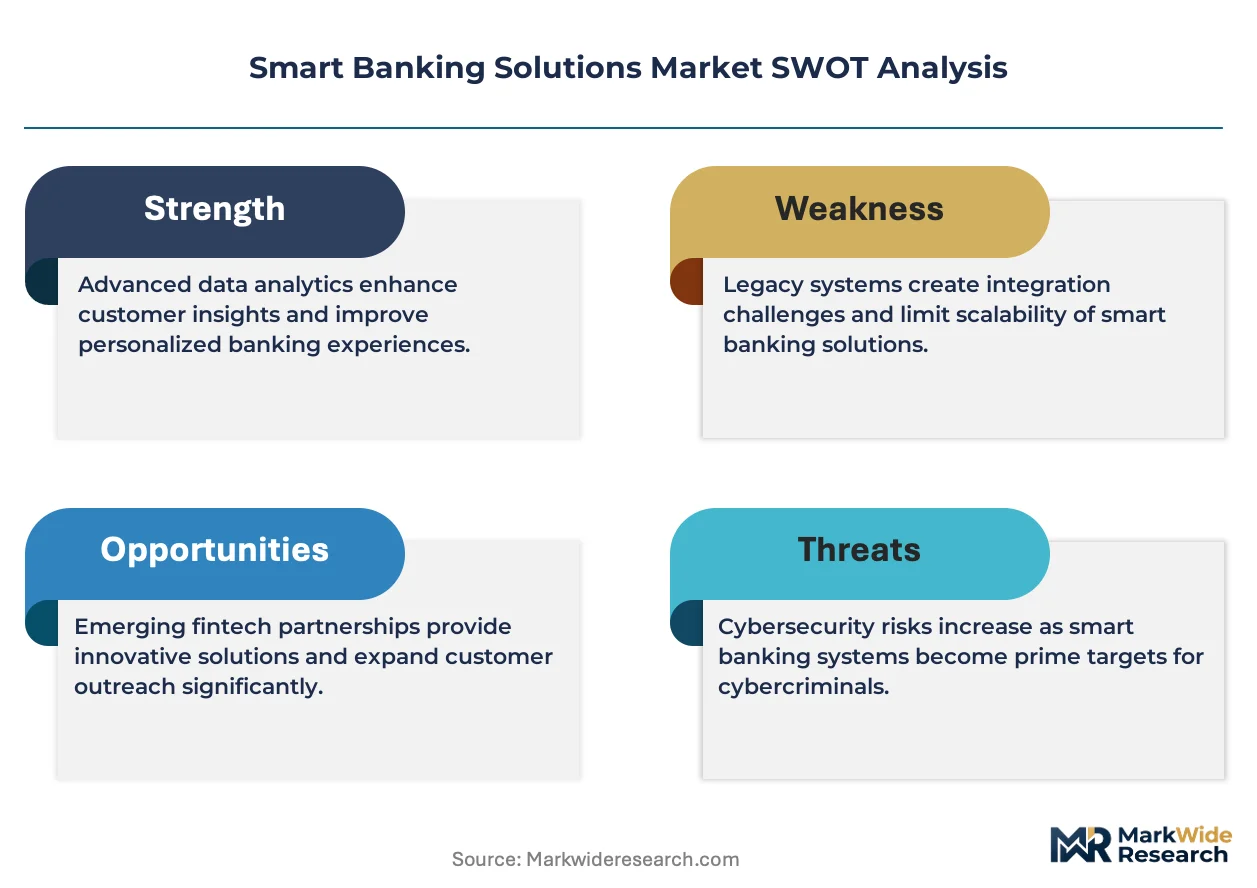
- Sovereign Data Localization:India's RBI and Saudi Arabia's SAMR mandate in-country server presence for payment data, fragmenting cloud architecture strategies and inflating compliance costs for multinational platform providers.
- Core System Entrenchment:COBOL-based legacy ledgers at major money-center banks resist full replacement, constraining smart banking solution penetration to overlay deployments with limited functional depth.
- Talent Scarcity in RegTech:Shortages of compliance engineers fluent in both AML/KYC rule engines and cloud-native development extend implementation timelines and inflate project costs.
Strategic Opportunities
- Embedded Finance Convergence:Non-bank retailers and logistics platforms seek white-labeled banking infrastructure, creating distribution partnerships for core banking-as-a-service providers.
- EU AI Act Compliance Tools:Mandatory algorithmic transparency requirements for credit scoring systems generate new revenue pools in explainable AI auditing and bias detection modules.
- SME Banking Digitization:Underpenetrated segments in Germany and Italy still rely on branch-heavy relationship models, presenting greenfield deployment opportunities for cash flow analytics and automated working capital products.
Industry Challenges
- Multi-Jurisdiction Regulatory Divergence:Simultaneous compliance with EU GDPR, US fair lending algorithms scrutiny by the CFPB, and divergent AI governance timelines fragments product roadmaps and delays feature releases.
- ISO 20022 Migration Complexity:Cross-border payment message format transitions require simultaneous core ledger, middleware, and correspondent banking system upgrades, straining IT integration capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Banking Solutions Market |
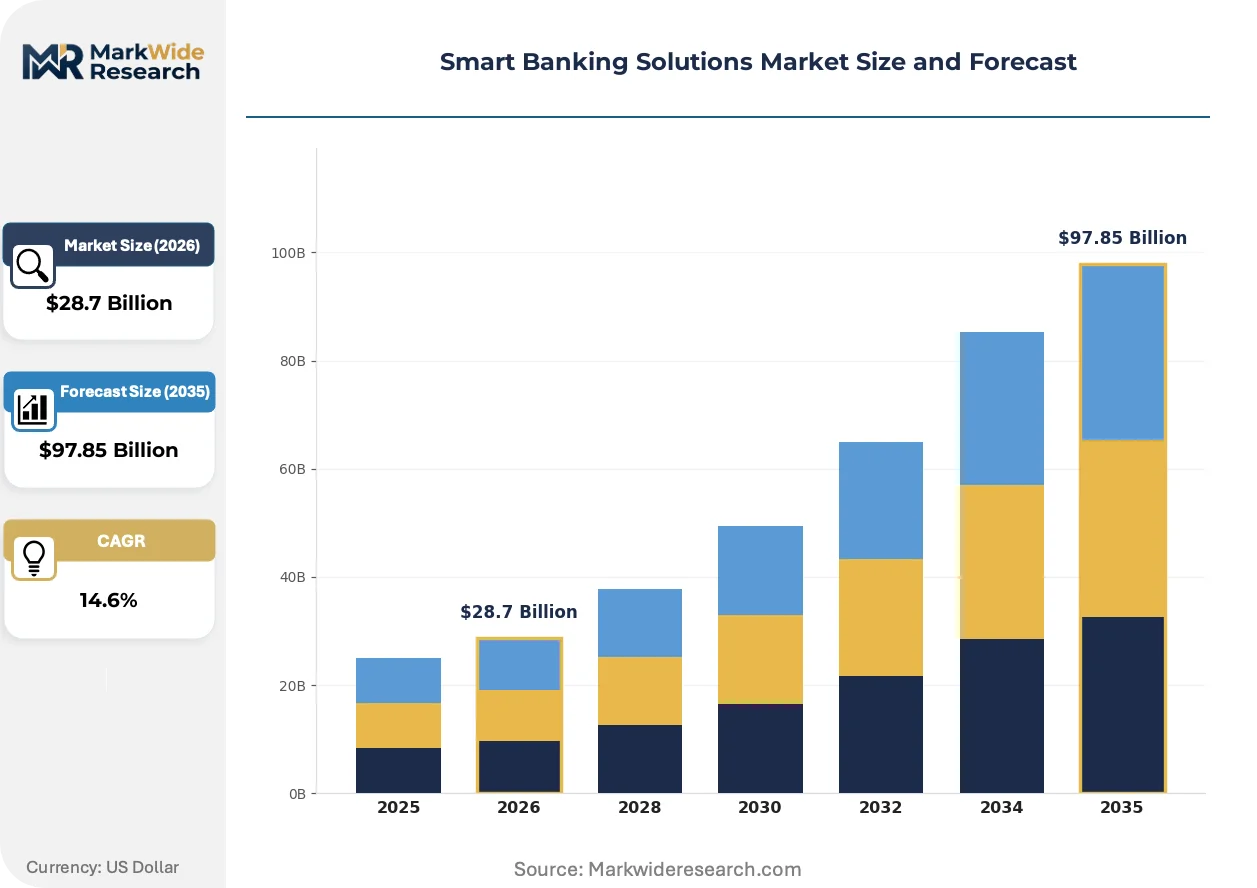
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $97.85 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Payment Processing, Fraud Detection, Risk Management, Customer Analytics, Loan Origination, Compliance Automation Deployment Mode: Cloud-Based, On-Premise, Hybrid, Edge Computing, Multi-Cloud End User: Retail Banks, Credit Unions, Mortgage Lenders, Microfinance Institutions, Private Wealth Firms Technology: Artificial Intelligence, Blockchain, Big Data Analytics, Robotic Process Automation, Biometric Authentication |
| Companies Covered | Temenos, Finastra, Fiserv, FIS, Backbase, nCino, Oracle, Infosys Finacle, Sopra Banking Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Banking Solutions Market Trends and Innovations
Generative AI is compressing customer service cost structures while simultaneously raising regulatory scrutiny, creating a tension between automation gains and explainability requirements that vendors must engineer around.
Embedded finance infrastructure is hybridizing banking services into non-financial customer journeys. Logistics platforms in Germany now integrate invoice financing at point-of-delivery confirmation. E-commerce marketplaces in Brazil embed split-payment options without redirecting to bank applications. This convergence collapses the traditional boundary between financial and commercial software stacks.
The EU AI Act's risk-based classification system imposes documentation burdens on automated credit decisioning tools. High-risk algorithmic systems must maintain audit trails and human oversight protocols. Retail banks serving European markets are reengineering model governance frameworks to satisfy conformity assessment requirements before enforcement deadlines.
Corporate treasury departments are consolidating banking relationships around API connectivity depth rather than branch proximity. Large multinational manufacturers now evaluate financial institutions primarily on real-time cash visibility and automated hedging execution capabilities. This procurement recalibration favors technology-forward banks in the Netherlands and Singapore over traditional relationship-driven competitors.
Smart Banking Solutions Market Segmentation
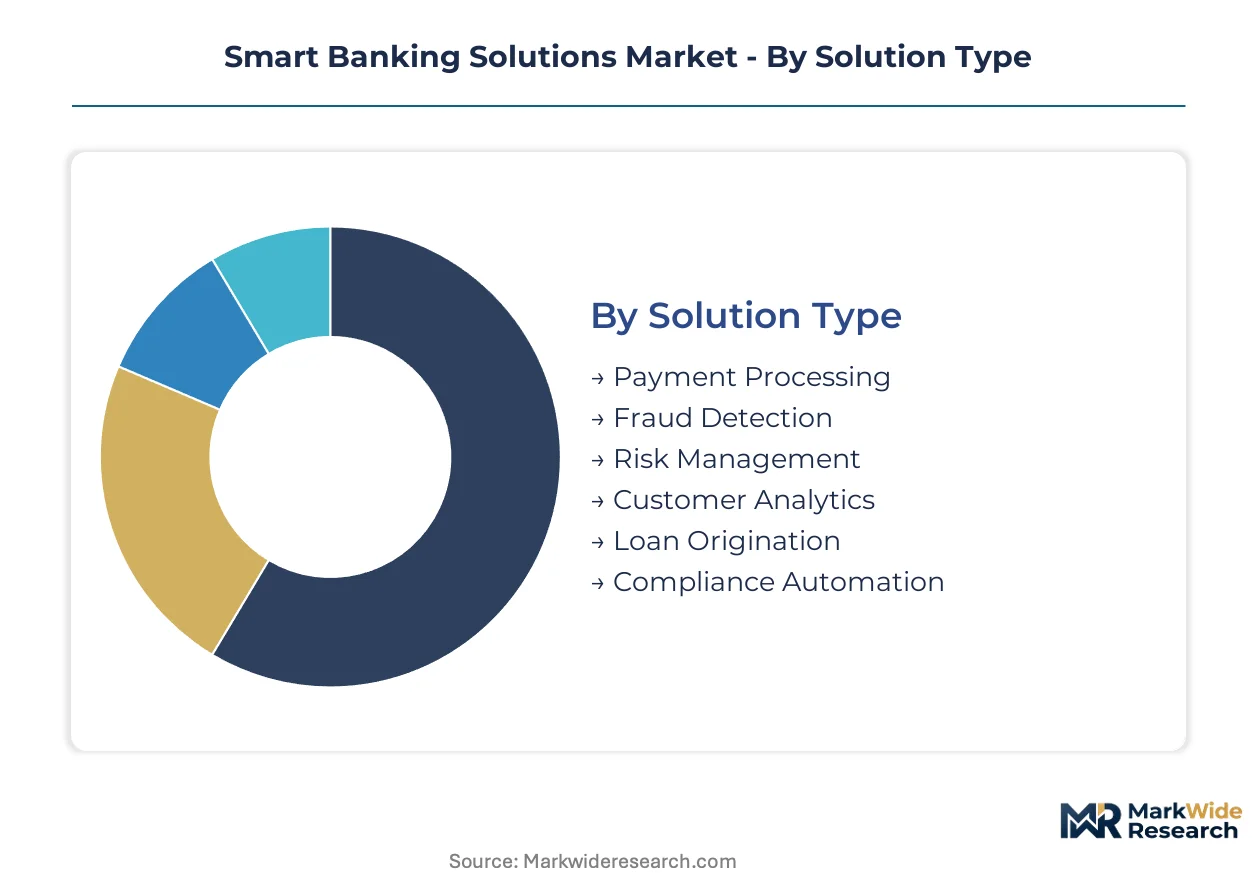
Smart banking solutions fragment across four orthogonal dimensions that determine procurement patterns and vendor positioning. Solution type governs contract value and replacement cadence. Deployment mode shapes infrastructure partnerships and compliance architecture. End user concentration determines feature prioritization. Technology foundation dictates talent requirements and integration complexity.
Solution Type:
Payment processing platforms turn over fastest as real-time rails force continuous upgrades, while compliance automation contracts stretch longest due to regulatory certification timelines.
- Payment Processing:Real-time transaction orchestration engines handle sub-second API calls across instant payment networks. Demand concentrates among tier-one retail banks in the United States competing on settlement speed. India's UPI and Brazil's Pix deployments accelerate procurement cycles for fraud-resistant message handling.
- Fraud Detection:Machine learning models flag anomalous patterns across digital channels and card-not-present transactions. Large money-center banks in the United States dominate deployment as synthetic identity attacks escalate. Behavioral biometrics integration drives upgrade frequency.
- Risk Management:Portfolio-level credit and market risk engines aggregate exposure across asset classes.
- Customer Analytics:AI-powered segmentation platforms personalize product recommendations and predict churn propensity.
- Loan Origination:Digital underwriting workflows automate document verification and decision logic for consumer and commercial credit.
- Compliance Automation:AML screening and KYC orchestration modules maintain audit trails for regulatory examinations.
Payment processing dominates installed base. Compliance automation is where expansion concentrates.
Deployment Mode:
Cost tier separation runs sharpest here — cloud-native implementations command premium pricing against legacy on-premise estates with heavy customization debt.
- Cloud-Based:Fully managed SaaS platforms deliver elastic compute for transaction spikes without capital expenditure. European retail banks under PSD2 mandates favor this model for rapid API deployment. GDPR data residency requirements force regional instance selection.
- Hybrid:Sensitive ledger data remains on-premise while customer-facing layers migrate to cloud infrastructure. Large United States banks with sovereign data constraints prefer this architecture for payment systems. RBI-mandated localization in India reinforces hybrid persistence.
- On-Premise:Dedicated hardware installations serve institutions with strict air-gapped security requirements.
- Edge Computing:Distributed processing nodes reduce latency for branch-based biometric authentication.
- Multi-Cloud:Workload portability across AWS, Azure, and GCP mitigates vendor concentration risk.
Cloud-based deployments capture new implementation volume. Hybrid architectures retain the largest committed contract value.
End User:
Customer type stratification reveals divergent feature requirements — retail banks demand omnichannel integration while private wealth firms prioritize relationship analytics over transaction scale.
- Retail Banks:Full-service institutions serving mass-market and affluent segments through digital and branch channels. United States money-center banks drive largest contract sizes as they consolidate vendor relationships. Open banking mandates in the European Union force API infrastructure investment.
- Credit Unions:Member-owned cooperatives with limited IT staff require pre-integrated solution stacks. North American deployments concentrate among institutions seeking cloud-native core alternatives. Regulatory examination schedules shape procurement timing.
- Mortgage Lenders:Specialized originators and servicers with document-heavy workflows.
- Microfinance Institutions:High-volume, small-ticket lenders operating in emerging markets.
- Private Wealth Firms:Family offices and registered investment advisors managing concentrated portfolios.
Retail banks dominate installed base. Credit unions represent the steepest expansion trajectory.
Technology:
Maturity gradients separate established analytics stacks from emerging infrastructure requiring specialized implementation partners.
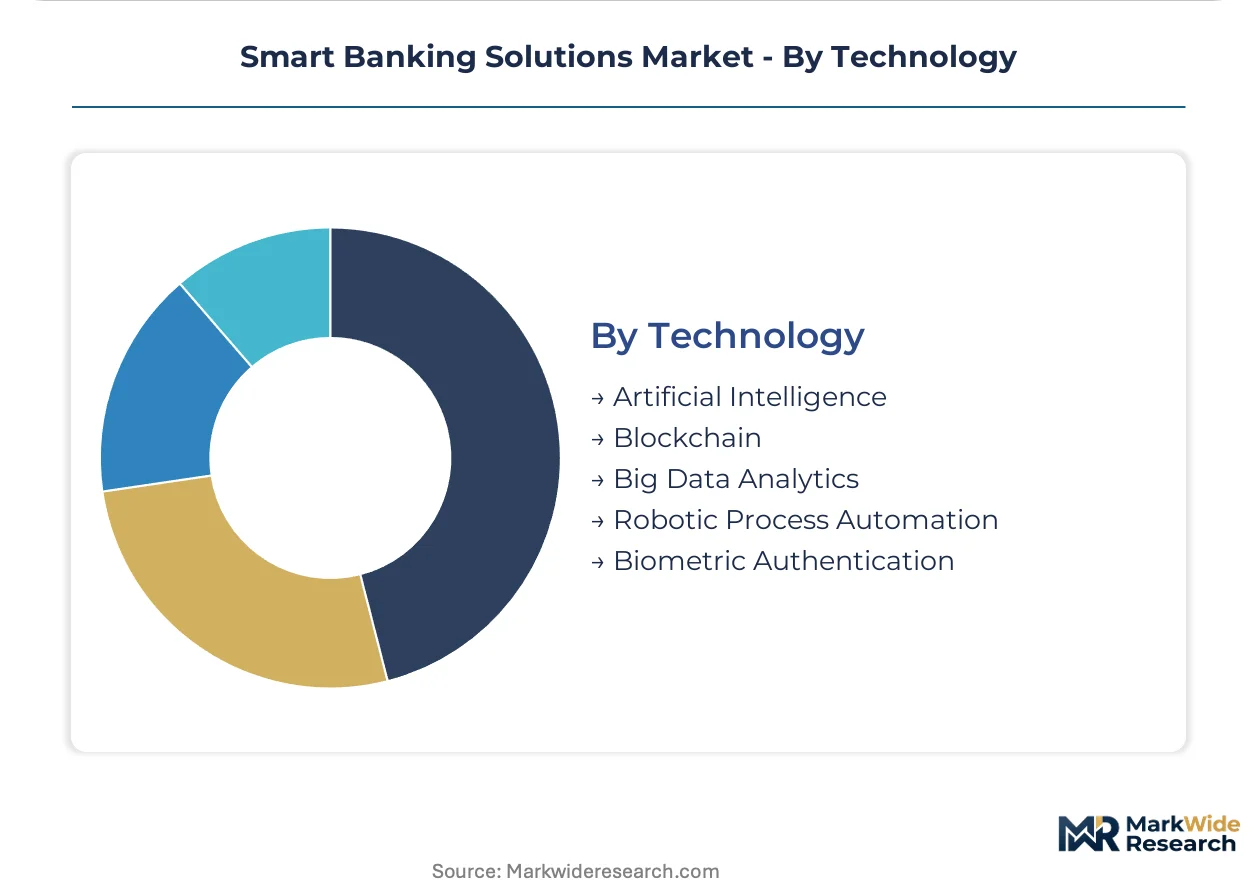
- Artificial Intelligence:Neural networks and ensemble methods power credit scoring, fraud detection, and conversational interfaces. European retail banks under EU AI Act timelines reengineer model governance for high-risk system documentation. Explainability requirements inflate auditing costs.
- Big Data Analytics:Distributed processing frameworks aggregate structured and unstructured data for customer intelligence. United States banks leverage alternative data sources for thin-file lending decisions. Real-time stream processing capabilities differentiate vendor offerings.
- Blockchain:Distributed ledger infrastructure for trade finance and cross-border settlement.
- Robotic Process Automation:Software bots automate repetitive back-office tasks in reconciliation and reporting.
- Biometric Authentication:Fingerprint, facial, and voice recognition for identity verification.
Big data analytics dominates installed base. Artificial intelligence is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where tier-one banks negotiate enterprise-wide platform contracts, while European institutions fragment procurement across national regulatory silos and compress vendor margins.
United States
Money-center banks drive the largest contract values as they consolidate vendor relationships around cloud-native core replacements. The OCC and CFPB scrutinize fair lending algorithms and digital redlining risks, forcing explainable AI investments. New York and San Francisco anchor fintech challenger activity that pressures incumbent institutions to accelerate modernization timelines.
Germany
SME banking digitization lags behind retail segments, creating greenfield demand for cash flow analytics and automated working capital products. BaFin implements EU AI Act conformity assessment requirements ahead of enforcement deadlines. Frankfurt's financial cluster hosts major institutions reengineering model governance frameworks for high-risk algorithmic systems.
United Kingdom
Open banking API adoption exceeds continental European penetration, sustaining middleware procurement for consent management and ISO 20022 integration. The Financial Conduct Authority coordinates with the Bank of England on stablecoin and digital pound frameworks. London's fintech density generates partnership opportunities for engagement banking layer providers.
India
UPI real-time payment rails accelerate fraud detection and transaction orchestration software procurement across public and private sector banks. RBI mandates data localization for payment systems, fragmenting cloud architecture strategies for multinational platform providers. Mumbai and Bengaluru concentrate domestic IT services firms delivering core banking modernization.
Brazil
Pix instant payment infrastructure demonstrates how government-backed investments drive fraud-resistant message handling demand. The central bank's open finance regulations expand API exposure requirements beyond payment data to credit and investment products. São Paulo anchors both traditional institution headquarters and emerging fintech challengers embedding split-payment options into e-commerce journeys.
Smart Banking Solutions Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower functional scope. The vendor base stratifies between cloud-native core providers, engagement banking overlay specialists, and infrastructure-agnostic middleware vendors. Three archetypes dominate: full-stack modernizers, legacy bridge builders, and API-first engagement layers. Consolidation pressure manifests through strategic partnerships between core vendors and fintech challengers, alongside geographic expansion into underpenetrated SME banking segments.
Within the full-stack modernizer tier, Temenos and Finastra occupy positions representing cloud-native delivery models and open API marketplace strategies respectively. Backbase exemplifies the engagement banking archetype with overlay deployments that circumvent core replacement cycles. These three anchors illustrate how competitive positioning diverges between institutions pursuing rip-and-replace transformations versus incremental layer-by-layer upgrades.
| Leading Market Players |
|---|
| Temenos |
| Finastra |
| Fiserv |
| FIS |
| Backbase |
| nCino |
| Oracle |
| Infosys Finacle |
| Sopra Banking Software |
| Others |
Pricing and Supply Chain Analysis
Trans-Atlantic fiber cable routes connecting Frankfurt to New York carry API traffic and cloud synchronization loads that concentrate vendor delivery costs in Western corridors. Tier-one institutions negotiate enterprise-wide SaaS contracts that compress margins for standardized deployment tiers while configured-to-order implementations retain substantial premium capture.
Pricing Analysis
The customization-premium spread separates standardized cloud-native subscriptions from configured legacy-core integrations requiring specialized engineering. Pricing stratifies across premium, standard, and economy tiers with differentiation anchored in ISO 20022 certification depth and real-time processing SLAs. Cost compression in the standard tier intensifies because hyperscaler infrastructure commoditizes baseline compute resources. Credit unions and regional banks exhibit highest price sensitivity; money-center institutions prioritize functional depth over unit economics.
Supply Chain Analysis
Supplier-financing facilities extend payment terms to 90-120 days for middleware vendors serving tier-one banks, preserving cash flow across implementation cycles. Software development concentrates in India, Ireland, and Poland with cloud infrastructure sourcing from hyperscaler regions in the United States, Germany, and Singapore. The supply chain draws from specialized AML rule-engine libraries, biometric SDKs, and ISO 20022 messaging stacks. Single-source vulnerability persists in core ledger integration protocols. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of engineers fluent in both COBOL legacy systems and Kubernetes-native architectures constrains deployment velocity and inflates implementation timelines across the vendor landscape.
For Market Incumbents: Pre-empt fintech challenger encroachment by acquiring specialist consent-management vendors before open banking mandates expand beyond payment data. Fortify API marketplace positions through backward integration into core ledger modernization services. Vertical control over ISO 20022 migration tooling defends against margin erosion in middleware layers. For New Entrants and Emerging Players: Build out embedded finance infrastructure for logistics and e-commerce platforms in Brazil and India where regulatory frameworks favor non-bank distribution. SME banking digitization in Germany and Italy offers the most penetrable greenfield segment. White-label banking-as-a-service partnerships provide the strongest go-to-market angle against entrenched core vendors. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate technology parents seeking to divest non-core financial services software units. Long-term viability hinges on cloud-native architecture completion and regulatory certification breadth across multiple jurisdictions. Watch for EU AI Act enforcement deadlines as inflection indicators accelerating explainable AI vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Core Banking Modernization | Cloud-native replacements unlock API-first architectures for open banking compliance. |
| Regulatory Technology Acquisition | AML and KYC specialist purchases address talent scarcity in compliance engineering. |
| Embedded Finance Partnership | Non-bank platform integrations expand distribution without branch infrastructure investment. |
| Explainable AI Development | EU AI Act conformity requirements create differentiated model governance offerings. |
| Geographic Expansion | SME banking digitization in underpenetrated European markets drives greenfield revenue. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with CTOs, core banking platform engineers, regulatory compliance officers, and fintech partnership leads; and secondary validation against SEC 10-K filings, RBI circulars, EU regulatory databases, and hyperscaler financial services vertical disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from vendor revenue disclosures and systems integrator contract announcements.
Forecast inputs span deployment mode, solution type, end-user institution category, and regional regulatory cluster across the projection horizon. CAGRs derive from segment-level growth rate reconciliation with macroeconomic banking technology spend indicators. Real-time payment rail adoption curves and AI governance timeline divergence shape scenario-weighted outcomes.
The forecast holds incumbent behavior within observed patterns; aggressive consolidation moves by private equity-backed platform aggregators would shift outcomes. Macroeconomic credit contraction, abrupt AI liability rulings, or sovereign data localization expansion would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Latin America Neo Banking Services Market
Banking
China Retail Banking System Market
Banking
Biometric Banking Wristband Market
Banking
Embedded Banking Market
Banking
Canada Data Analytics in Banking Market
Banking
Investment Banking and Trading Services Market
Banking
Performance Bank Guarantee Market
Banking
France Data Analytics in Banking Market
Banking
Bank Management Software Market
Banking
Italy Data Analytics in Banking Market
Banking
Australia Data Analytics in Banking Market
Banking
Germany Neobanking Market
Banking
Middle East Data Analytics in Banking Market
Banking
United Kingdom Data Analytics in Banking Market
Banking
Commercial Banking Market
Banking
US Banking-As-A-Service Market