
 Bank Management Software Market | 2026-2036
Bank Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Bank Management Software Market Insights
Buyer concentration among large retail banks is hardening as regional institutions merge and consolidate technology procurement budgets. Oracle Corporation leverages its database heritage to anchor core banking infrastructure for tier-one institutions. Temenos competes through modular architecture that allows phased cloud migration without full rip-and-replace.
Bank management software encompasses integrated platforms that automate ledger management, transaction processing, and regulatory reporting through API-connected microservices and real-time data pipelines. These systems serve commercial purpose by reducing operational risk and enabling instant payment clearing across correspondent networks. Cloud-based deployment leads solution type growth as banks exit fixed-capital data center commitments, while risk management commands premium pricing due to Basel-aligned calculation engines. Core banking retains the largest installed base though growth rates lag behind fraud detection applications.
Federal banking agencies including the OCC and FDIC shape vendor selection through cybersecurity examination criteria and third-party risk management guidance. The EU's DORA framework and GDPR impose cross-border data residency requirements that constrain cloud provider geography. Stakeholders must monitor how AI governance standards from the EU AI Act and pending US agency guidance reshape algorithmic credit scoring modules.
Market Dynamics
Cloud migration mandates from banking regulators are forcing wholesale replacement of legacy core systems, compressing procurement cycles from decade-long horizons to five-year modernization sprints as institutions race to meet real-time payment interoperability deadlines.
Growth Catalysts
- Open banking compliance deadlines:Regulatory mandates in the United States and European Union require API-enabled data sharing, compelling institutions to upgrade core platforms with standardized interoperability layers.
- Real-time payment infrastructure:The Federal Reserve's FedNow service and comparable instant clearing systems in multiple jurisdictions demand ledger modernization to handle 24/7 transaction processing.
- Consolidation among regional banks:Merged institutions are pooling technology budgets to fund enterprise-grade core replacements previously accessible only to tier-one players.
Market Restraints
- Data residency requirements:The EU's GDPR and DORA frameworks restrict cloud provider geography, forcing redundant infrastructure investments that inflate total cost of ownership.
- Specialized talent scarcity:Core banking modernization requires expertise in both legacy COBOL systems and cloud-native microservices, a skill combination concentrated among aging workforces.
- Protracted procurement cycles:Vendor selection processes stretch 18-24 months due to stringent due diligence requirements from the OCC and FDIC third-party risk management guidance.
Strategic Opportunities
- Embedded finance integration:Non-bank platforms in retail and logistics seek white-labeled banking infrastructure, opening new distribution channels beyond traditional financial institutions.
- AI governance preparation:Anticipated algorithmic credit scoring rules from US federal agencies create first-mover advantage for vendors with explainable AI modules.
- Community bank cloud leapfrogging:Smaller institutions in secondary US markets are skipping on-premise upgrades entirely, moving directly to SaaS core platforms without legacy migration burden.
Industry Challenges
- Interoperability debt:Decades of custom-coded integrations between core systems and peripheral applications create brittle connection points that fail during cloud migration.
- Parallel run complexity:Regulatory requirements mandate extended periods where legacy and modern platforms operate simultaneously, doubling operational overhead and error risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bank Management Software Market |
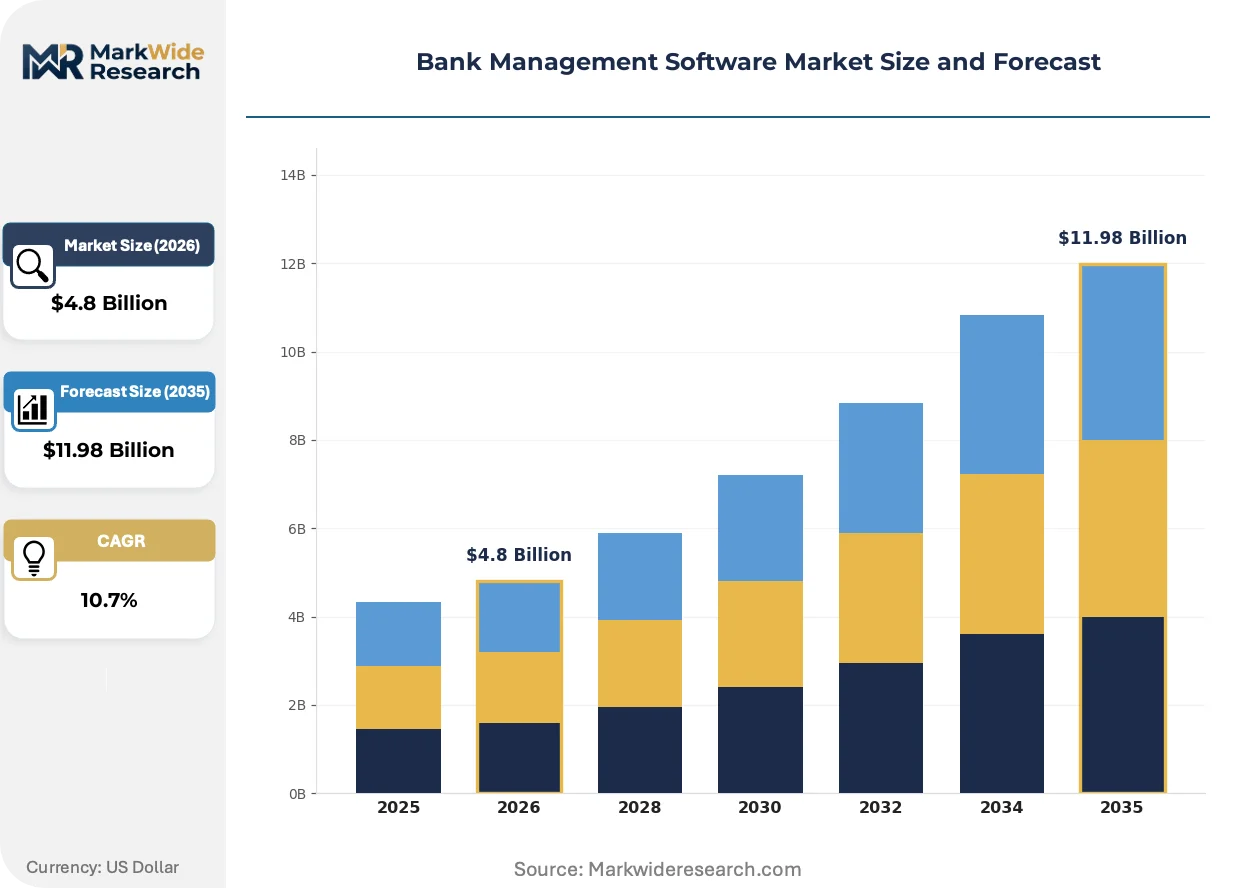
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.98 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted, Private Cloud Solution Type: Core Banking, Risk Management, Customer Relationship Management, Compliance Monitoring, Treasury Management Application: Loan Origination, Fraud Detection, Asset Management, Payment Processing, Credit Scoring End User: Retail Banks, Credit Unions, Investment Firms, Mortgage Lenders, Microfinance Institutions |
| Companies Covered | Oracle Corporation, SAP SE, Fiserv Inc, Finastra, FIS Global, Temenos, Jack Henry & Associates, IBM Corporation, Infosys Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bank Management Software Market Trends and Innovations
API-first architecture is dismantling monolithic banking platforms, enabling modular replacement of specific functions without full system overhauls. This shift is accelerating vendor competition around microservices specialization.
Containerized core banking infrastructure is consolidating previously fragmented technology stacks into unified deployment environments. Mid-tier institutions are adopting Kubernetes-orchestrated platforms to escape vendor lock-in. The technology is compressing implementation timelines from years to months.
The EU's Digital Operational Resilience Act is mandating stringent third-party risk management protocols for critical banking software. Financial institutions must now audit vendor supply chains and maintain operational continuity plans. European banks are prioritizing EU-domiciled cloud providers to satisfy data sovereignty requirements.
Subscription-based licensing is displacing perpetual ownership models across procurement departments. Chief information officers are negotiating usage-based contracts that align costs with transaction volumes. This pattern is most visible among US regional banks seeking to preserve capital for strategic initiatives.
Bank Management Software Market Segmentation
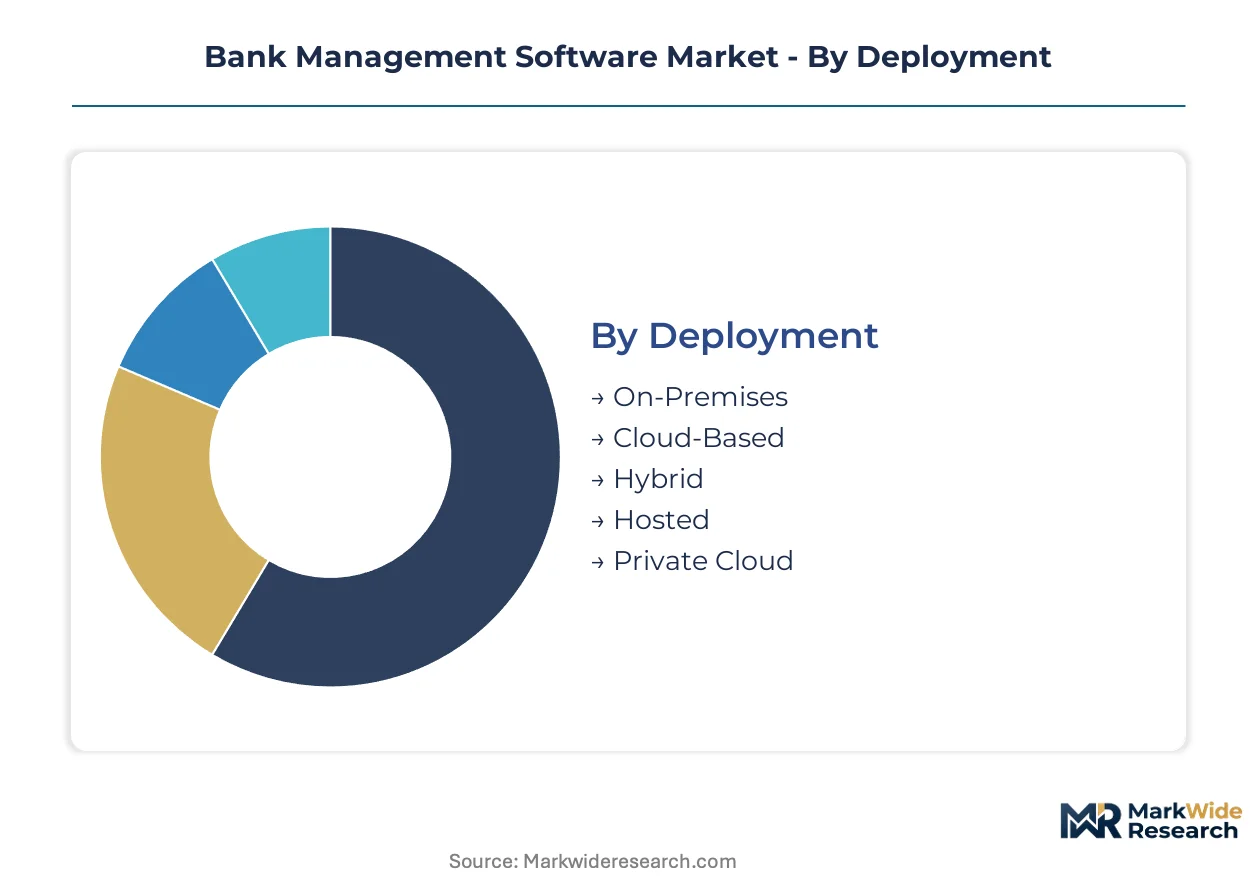
Bank management software segmentation reveals how procurement priorities diverge across institutional size, regulatory exposure, and technical maturity. Deployment choices and solution architectures cluster distinctly between tier-one institutions optimizing for control and regional players prioritizing speed-to-market.
Deployment:
Customization intensity varies sharply across this spectrum, with fully managed environments at one pole and self-operated infrastructure at the other dictating staffing models and capital commitments.
- On-Premises:Institutions retain physical hardware within owned or leased data centers, maintaining direct control over security perimeter and patch cycles. Tier-one banks in the United States favor this model for FedNow integration timelines where milliseconds of latency matter.
- Cloud-Based:Multi-tenant SaaS platforms eliminate fixed-capital data center commitments while embedding automatic compliance updates. Regional banks across Texas, Florida, and Ohio are consolidating onto these platforms to escape COBOL maintenance burdens.
- Hybrid:Sensitive core ledger functions remain on-premise while customer-facing channels migrate to cloud elasticity. This architecture dominates among institutions navigating parallel run requirements during modernization sprints.
- Hosted:Single-tenant deployments in vendor-managed facilities preserve isolation without operational overhead. Mid-tier institutions seeking SOC 2 Type II attestation without building internal capabilities gravitate here.
- Private Cloud:Dedicated cloud infrastructure satisfies data residency mandates from EU banking regulators while capturing cloud-native agility. Institutions with correspondent banking networks spanning Frankfurt, Paris, and Amsterdam prioritize this model.
Most installed capacity flows through On-Premises legacy estates. Expansion is steepest in Cloud-Based deployments.
Solution Type:
Margin profiles stratify across this category based on regulatory complexity and calculation engine sophistication, with risk functions commanding premium pricing relative to operational modules.
- Core Banking:Central ledger systems processing deposits, loans, and general ledger entries through real-time transaction engines. The largest installed base resides here, though replacement cycles stretch longer than peripheral applications.
- Risk Management:Basel-aligned calculation engines for credit, market, and operational risk exposure with stress testing automation. Demand concentrates among institutions facing enhanced supervisory scrutiny from the OCC and FDIC.
- Customer Relationship Management:Unified customer data platforms enabling personalized product recommendations and lifecycle marketing. Community banks in secondary US markets deploy these to compete against national branch networks.
- Compliance Monitoring:Automated surveillance of transaction patterns against AML and sanctions screening lists. Regulatory examination findings are driving urgent procurement among institutions with recent consent orders.
- Treasury Management:Liquidity forecasting, cash positioning, and investment portfolio optimization for institutional clients. Corporate banking divisions use these platforms to defend against fintech treasury offerings.
Core Banking retains the dominant share of installed systems. Compliance Monitoring is climbing fastest as examination intensity rises.
Application:
Volume concentration tracks payment modernization timelines, with instant clearing infrastructure creating urgent demand for specific functional modules.
- Loan Origination:Digital application intake, automated underwriting, and document management compressing approval cycles from weeks to hours. Mortgage lenders across California and New York are prioritizing these platforms to defend market share against non-bank originators.
- Fraud Detection:Real-time behavioral analytics and anomaly detection interrupting suspicious transactions before settlement. The FedNow 24/7 operating window is accelerating procurement of sub-second detection capabilities.
- Asset Management:Portfolio accounting, performance attribution, and regulatory reporting for wealth management divisions. Registered investment advisers seeking to white-label banking services drive niche demand.
- Payment Processing:ACH, wire, and instant payment routing with ISO 20022 message formatting. Institutions racing to meet FedNow interoperability deadlines are replacing legacy payment engines.
- Credit Scoring:Alternative data ingestion and machine learning models expanding approval rates while controlling loss rates. Anticipated algorithmic fairness rules from US federal agencies are reshaping vendor selection criteria.
Payment Processing carries the heaviest transaction volume. Fraud Detection is gaining share fastest as real-time exposure windows expand.
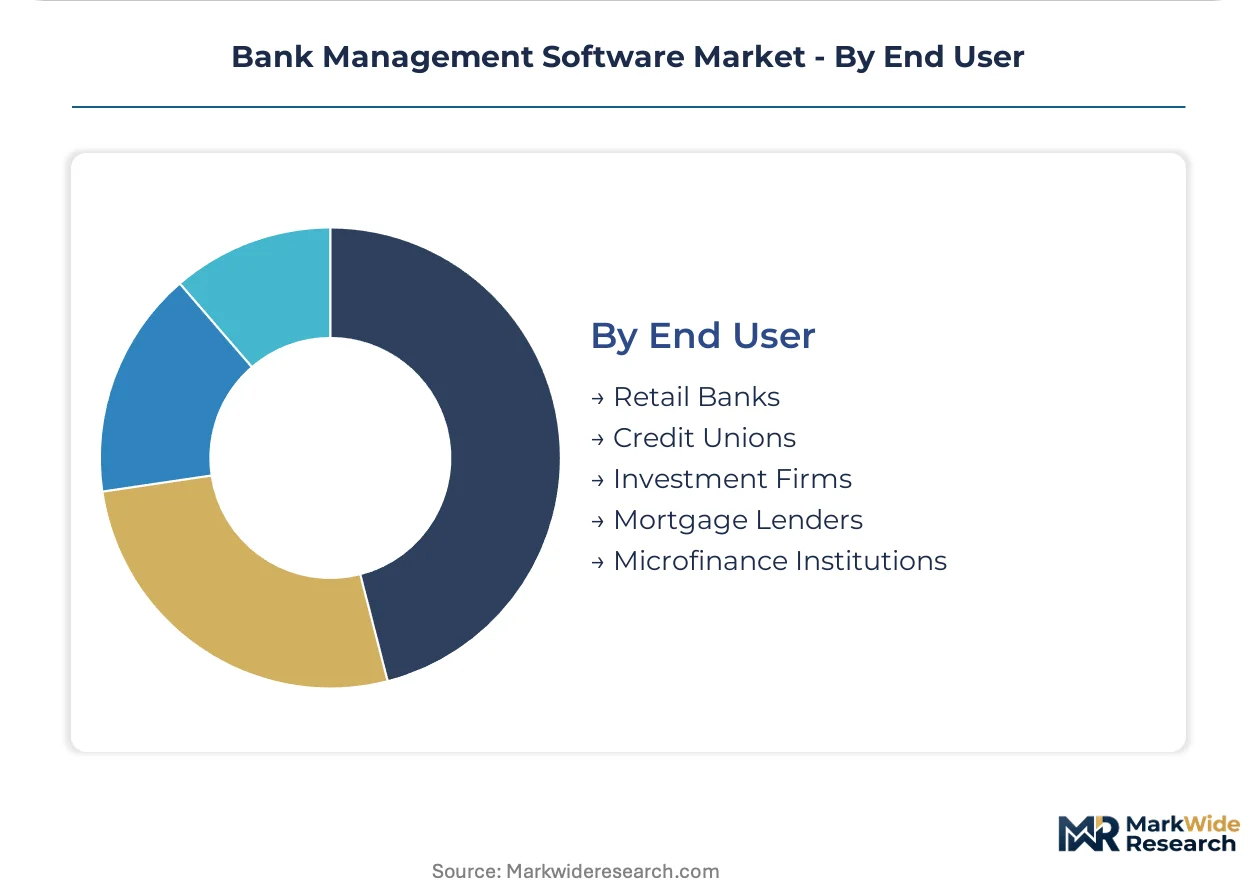
End User:
Customer type determines procurement authority sophistication and implementation risk tolerance, with regulated depositories facing distinct vendor diligence requirements.
- Retail Banks:Full-service institutions offering consumer and commercial banking with extensive branch networks. Consolidation among regional players is pooling technology budgets for enterprise-grade core replacements.
- Credit Unions:Member-owned cooperatives with tax-advantaged status and community-focused lending mandates. The National Credit Union Administration's cybersecurity examination criteria shape vendor selection.
- Investment Firms:Broker-dealers and asset managers requiring custody and cash management capabilities alongside trading infrastructure. SEC custody rule compliance drives specialized procurement.
- Mortgage Lenders:Non-depository originators and servicers dependent on warehouse lending and secondary market execution. Consumer Financial Protection Bureau examination risk concentrates procurement on compliance-embedded platforms.
- Microfinance Institutions:Small-balance lenders serving underbanked populations with mobile-first distribution. Institutions in emerging markets leapfrog directly to cloud-native cores without legacy migration.
Retail Banks account for the largest procurement expenditure. Credit Unions are expanding fastest as field-of-membership rules loosen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud architects and core banking engineers concentrate in financial centers where regulatory pressure and modernization budgets intersect. Talent clusters in these jurisdictions shape vendor deployment patterns and platform selection criteria.
United States
FedNow interoperability deadlines and open banking compliance are accelerating procurement of real-time payment engines among regional banks. The OCC and FDIC third-party risk management guidance extends vendor diligence timelines to 18-24 months. Dallas, Charlotte, and New York host the densest concentrations of core banking modernization projects.
Germany
EU data residency mandates under GDPR and DORA are driving private cloud infrastructure investments among Frankfurt-based institutions. BaFin operational resilience requirements compress migration windows for legacy core systems. The Rhine-Main financial cluster anchors correspondent banking platform deployments serving cross-border payment networks.
United Kingdom
Open Banking Standard compliance and PSD2 API requirements sustain demand for interoperability layers among London clearing banks. The Financial Conduct Authority's operational resilience rules mandate cloud exit strategies and vendor concentration limits. The Square Mile and Canary Wharf host specialized engineering teams bridging legacy COBOL estates to containerized architectures.
India
RBI cloud guidelines and digital public infrastructure expansion are propelling SaaS core adoption among urban cooperative banks and regional rural banks. The central bank's regulatory sandbox permits live testing of instant payment integrations. Mumbai, Bangalore, and Hyderabad concentrate fintech engineering talent supporting white-labeled banking infrastructure for non-bank platforms.
Singapore
MAS technology risk management guidelines and Project Orchid CBDC pilots are stimulating ledger modernization among ASEAN-focused institutions. Cross-border payment corridor initiatives with Thailand and Malaysia demand ISO 20022 message compatibility. The Marina Bay financial district anchors vendor development centers serving Southeast Asian expansion strategies.
Bank Management Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated vendor landscape where scale advantages clash with modular agility. Tier-one institutions favor integrated suites from technology conglomerates with database heritage, while mid-market players prioritize phased migration paths that avoid rip-and-replacement trauma. Two strategic archetypes dominate: full-stack platform vendors anchoring enterprise transformation programs, and component specialists supplying fraud detection or compliance modules for hybrid architectures. Competitive intensity centers on M&A consolidation to fill capability gaps and strategic partnerships embedding banking infrastructure into non-financial platforms.
Within the full-stack tier, Oracle Corporation and SAP SE exemplify diversified technology conglomerates leveraging enterprise software heritage to anchor core banking procurement. Temenos occupies a position among modular specialists enabling cloud migration without wholesale system replacement. These three entities represent contrasting philosophical approaches to institutional modernization—vertical integration versus architectural openness—shaping competitive dynamics across procurement segments.
| Leading Market Players |
|---|
| Oracle Corporation |
| SAP SE |
| Fiserv Inc |
| Finastra |
| FIS Global |
| Temenos |
| Jack Henry & Associates |
| IBM Corporation |
| Infosys Limited |
| Others |
Pricing and Supply Chain Analysis
FedNow interoperability deadlines are compressing procurement cycles from decade-long horizons to five-year sprints, forcing vendors to restructure delivery models and compress implementation margins to capture accelerated replacement demand.
Pricing Analysis
Capacity additions in India and Singapore are reshaping price floors for cloud-native core banking platforms. Subscription-based SaaS licensing dominates procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating by customization depth and regulatory jurisdiction coverage. Cost compression in the mid-tier segment is intensifying because regional bank consolidations are pooling technology budgets for enterprise-grade negotiations. Community banks exhibit highest price sensitivity due to capital constraints, while tier-one institutions prioritize control over cost.
Supply Chain Analysis
Single-source vulnerability sits with legacy COBOL expertise concentrated among aging workforces in the United States and Western Europe. Engineering talent clusters draw from India, Poland, and Singapore, while cloud infrastructure rests on hyperscaler facilities in Frankfurt, Dublin, and Singapore. Regulatory restriction risk runs through EU data residency mandates under GDPR and DORA. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU data residency requirements inflate total cost of ownership by 40-60% relative to US deployments, creating margin expansion opportunities for vendors with multi-jurisdictional infrastructure.
For Market Incumbents: Deploy modular architecture investments to anchor phased cloud migration contracts against rip-and-replace specialists. Consolidate COBOL modernization expertise through targeted capability acquisitions in Central European talent markets. Defensive positioning requires preemptive FedNow certification to lock out emerging cloud-native competitors from real-time payment procurement cycles. For New Entrants and Emerging Players: API-first distribution channels offer the lowest friction entry path for white-labeled banking infrastructure targeting non-bank retail and logistics platforms. Community banks in secondary US markets represent the most penetrable segment, with SaaS core platforms enabling direct cloud leapfrogging without legacy migration burden. Target embedded finance integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with modular compliance specialists possessing explainable AI modules for anticipated algorithmic credit scoring rules. Long-term viability centers on vendors bridging legacy COBOL estates to containerized architectures without operational disruption. Monitor OCC and FDIC third-party risk management guidance revisions as the critical inflection signal for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Modular API layers enable phased FedNow compliance without core replacement trauma. |
| Strategic Partnership | Systems integrator alliances compress implementation timelines from years to months. |
| Acquisition of Specialist Firm | COBOL modernization expertise fills capability gaps in legacy-to-cloud migration. |
| Geographic Expansion | EU-domiciled cloud infrastructure satisfies BaFin and DORA data sovereignty mandates. |
| Product Launch | Explainable AI credit scoring modules capture first-mover advantage under pending US agency guidance. |
Research Methodology
Coverage spans the United States, Germany, United Kingdom, India, and Singapore, with primary inputs from each jurisdiction combining structured interviews with CTOs, IT procurement officers, platform engineers, and integration specialists alongside secondary validation from SEC filings, hyperscaler capex disclosures, regulatory examination reports, and vendor implementation case studies. Bottom-up sizing of installed base and replacement cycles triangulates against top-down market aggregation.
Granularity-level modeling deploys deployment mode, institution size tier, solution architecture type, and regional regulatory cluster as core segmentation dimensions across the projection horizon. CAGRs derive from regression analysis of historical replacement cycles adjusted for regulatory mandate acceleration. Forecast inputs incorporate FedNow adoption timelines, DORA implementation deadlines, and cloud migration completion rates by institutional category.
The model assumes a particular technology adoption path; alternative pathways for containerized core infrastructure would alter the outlook. Forecasts reflect assumptions about regulatory examination intensity and talent availability that external shocks could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Australia Neobanking Market
Banking
Biometric Banking Wristband Market
Banking
Middle-East and Africa Banking-As-A-Service Market
Banking
US Commercial Banking Market
Banking
Commercial Banking Market
Banking
Bank Guarantee Market
Banking
AI and Automation in Banking Market
Banking
Third-Party Banking Software Market
Banking
India Data Analytics in Banking Market
Banking
Global AI in Banking Market
Banking
UK Banking as a Service Market
Banking
Germany Data Analytics in Banking Market
Banking
Automated Teller Machine (ATM) Market
Banking
Open Banking Market
Banking
Canada Data Analytics in Banking Market
Banking
South America Challenger Banks Market