
 Global Chatbot for Banking Market | 2026-2036
Global Chatbot for Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chatbot for Banking Market Foresight
Market Context
Conversational AI distribution through core banking platforms is reconfiguring how financial institutions procure customer-facing automation. Kore.ai leverages deep vertical integration into banking-specific intent libraries to sustain enterprise-grade deployment pipelines. Kasisto anchors its position through specialized finance-domain natural language understanding that differentiates from generalist competitors.
Technical Definition and Segment Structure
Chatbot for Banking denotes software systems that simulate human conversation through text or voice interfaces to execute banking functions, typically incorporating natural language processing engines, dialog management frameworks, and API integrations to core banking systems for real-time balance inquiry, fund transfers, and fraud alerts. AI-driven Assistants command the premium solution tier as institutions prioritize contextual personalization over rigid rule-based pathways, while Cloud-based deployment dominates infrastructure decisions by eliminating on-premise hardware refresh cycles. Retail Banks represent the most penetrated end-user category, though Wealth Management is emerging as a high-margin segment where personalized recommendation engines justify elevated per-seat licensing.
Regulatory Environment
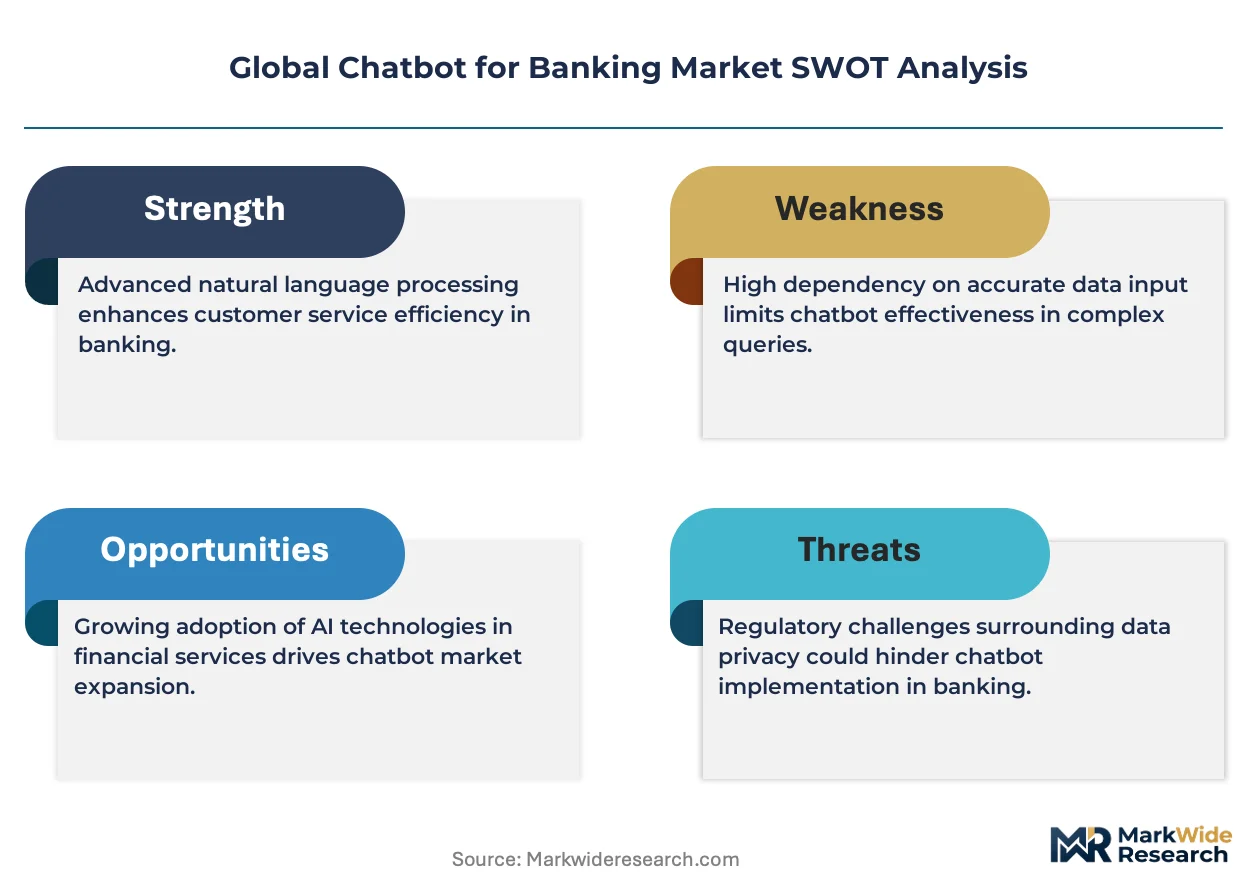
The EU AI Act imposes stringent conformity obligations on credit-scoring and risk-assessment chatbot applications, compelling vendors to redesign audit trails and explainability modules for European bank clients. The SEC and OCC in the United States enforce fiduciary duty standards that extend to robo-advisory conversations, while GDPR and analogous privacy frameworks mandate granular consent management within conversational data retention policies. Stakeholders must monitor evolving cross-border data localization requirements that threaten cloud-based deployment economics in jurisdictions with restrictive financial data sovereignty laws.
Market Dynamics
Conversational AI deployment in banking is restructuring around cloud-native architectures that compress implementation timelines from months to weeks. The EU AI Act's risk-classification mandates are forcing vendors to reengineer audit trails and explainability modules for European financial clients.
Growth Catalysts
- EU AI Act Conformity Pressure:The regulation's high-risk system obligations are compelling banks to upgrade legacy chatbot infrastructure, creating replacement demand for explainable AI platforms.
- Call-Center Volume Deflection:Retail banking operations are automating routine balance inquiries and fund transfers through voice-enabled interfaces to reduce human agent headcount.
- Cloud Migration Acceleration:Financial institutions are eliminating on-premise hardware refresh cycles by adopting API-first conversational platforms that integrate directly with core banking systems.
Market Restraints
- GPU Supply Concentration:Training large language models for banking applications depends on NVIDIA-dominated semiconductor supply chains subject to export control volatility.
- Data Sovereignty Fragmentation:Restrictive financial data localization laws in multiple jurisdictions threaten the unit economics of centralized cloud deployments.
- Legacy Core Integration Friction:Decades-old banking IT architectures impose middleware complexity that extends implementation timelines and inflates professional services costs.
Strategic Opportunities
- Wealth Management Personalization:High-net-worth advisory segments are adopting recommendation engines that justify elevated per-seat licensing through portfolio optimization conversations.
- India's Digital Public Infrastructure:The country's account aggregator framework and open banking APIs are creating standardized data pipes for conversational financial services.
- Voice Biometric Convergence:Multimodal authentication combining natural language understanding with speaker recognition is opening fraud-resistant transaction channels.
Industry Challenges
- Prompt Engineering Talent Scarcity:Financial institutions compete for specialists capable of tuning large language models for regulated domain accuracy without hallucination risks.
- Cross-Border Compliance Orchestration:Vendors must maintain parallel audit trails satisfying GDPR consent management, SEC fiduciary duty standards, and emerging AI Act documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chatbot for Banking Market |
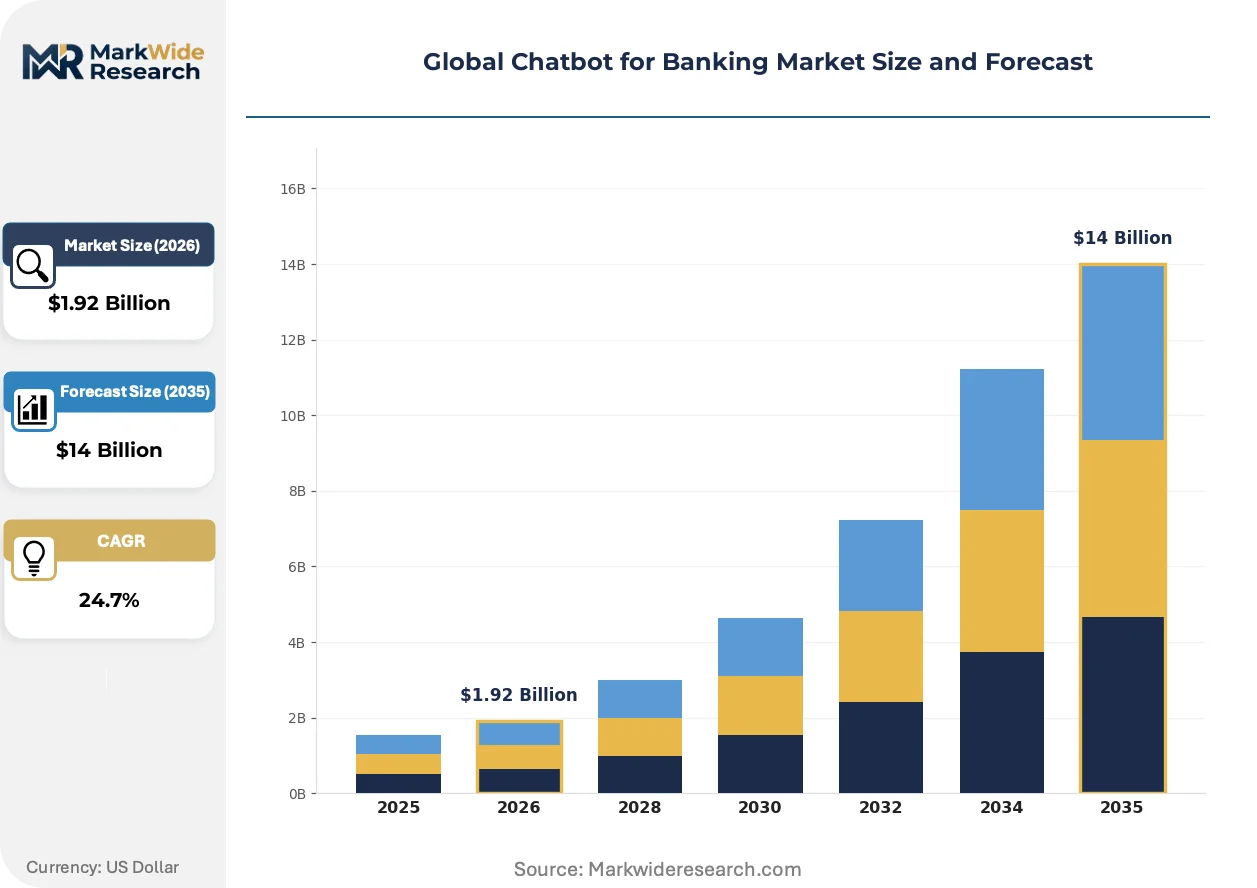
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $14 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: AI-driven Assistants, Rule-based Chatbots, Transactional Bots, Customer Support Bots Deployment: On-premise, Cloud-based, Hybrid, Mobile End User: Retail Banks, Investment Banks, Credit Unions, Wealth Management Functionality: 24/7 Support, Transaction Processing, Account Management, Personalized Recommendations |
| Companies Covered | Kore.ai, Kasisto, Inbenta Technologies, Nuance Communications, CreativeVirtual, Pypestream, Haptik, VeriPark, Neurons Lab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chatbot for Banking Market Shifts & Advancements
Generative AI is compressing the gap between scripted chatbot responses and truly contextual banking conversations. Three forces are reshaping how financial institutions procure, deploy, and monetize conversational interfaces.
Large language models with retrieval-augmented generation capabilities are digitizing the knowledge management layer that previously required dedicated call-center training programs. Tier-one banks in the United States are piloting these systems for complex mortgage origination conversations. The technology is digitizing compliance documentation workflows by automatically surfacing regulatory citations during customer interactions.
The EU AI Act's high-risk system classification for credit-scoring algorithms is mandating human-in-the-loop architectures for automated lending conversations. Vendors must now engineer real-time explainability dashboards that satisfy conformity assessment body scrutiny. European retail banks are responding by segmenting chatbot deployments into lower-risk informational queries versus restricted advisory functions.
Corporate treasury departments are consolidating vendor relationships around platforms offering unified conversational interfaces across payments, FX hedging, and liquidity management. This procurement consolidation is displacing point solutions that handled single functions. The pattern is most visible among multinational banks operating across London, Singapore, and New York where centralized technology procurement mandates are reducing supplier fragmentation.
Global Chatbot for Banking Market Segmentation
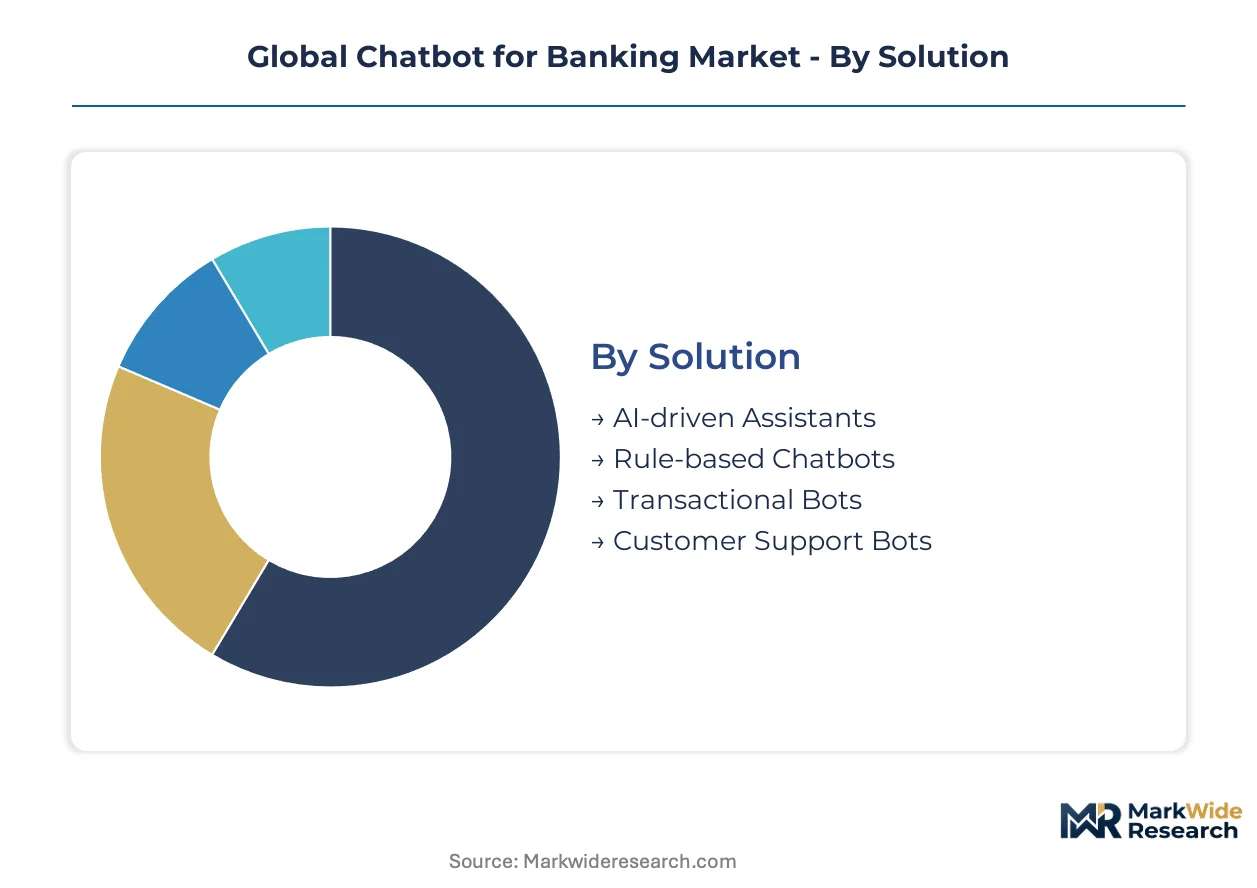
Banking chatbot procurement patterns diverge sharply by deployment maturity and regulatory exposure. Solution architecture choices determine whether institutions capture call-center deflection savings or remain trapped in legacy integration cycles.
Solution:
Replacement cycles vary from eighteen months for lightweight rule-based deployments to five-year enterprise AI assistant contracts.
- AI-driven Assistants:Large language models with retrieval-augmented generation handle complex mortgage origination and wealth advisory conversations. United States retail banks concentrate demand here as they pursue contextual personalization beyond scripted pathways.
- Rule-based Chatbots:Decision-tree architectures execute predictable balance inquiries and password resets with minimal hallucination risk. Credit unions and smaller institutions favor these for compliance simplicity and lower total cost of ownership.
- Transactional Bots:API-integrated systems execute fund transfers and bill payments within conversational interfaces. India's account aggregator framework accelerates deployment through standardized open banking pipes.
- Customer Support Bots:Deflection-focused tools triage Tier-1 inquiries before human escalation. European banks segment these into lower-risk informational functions under EU AI Act risk-classification protocols.
Rule-based Chatbots dominate installed base. AI-driven Assistants is where expansion concentrates.
Deployment:
Cost tier structures separate capital-intensive on-premise builds from variable-cost cloud consumption models.
- Cloud-based:API-first platforms eliminate hardware refresh cycles and compress implementation timelines from months to weeks. United States national banks with centralized procurement mandates drive volume here.
- Hybrid:Sensitive authentication logic remains on-premise while natural language processing leverages cloud elasticity. German and French institutions favor this architecture under GDPR data sovereignty constraints.
- On-premise:Fully captive infrastructure serves jurisdictions with restrictive financial data localization laws. Middle Eastern and select Southeast Asian markets require this deployment mode.
- Mobile:Smartphone-native conversational interfaces with embedded voice biometric authentication. India's UPI ecosystem and Brazil's PIX infrastructure accelerate mobile-first adoption.
Cloud-based deployments capture new contract flow. Hybrid architectures is where vendor engineering investment concentrates.
End User:
Margin profiles separate high-volume retail automation from premium wealth management advisory licensing.
- Retail Banks:Mass-market institutions automate routine inquiries across voice and digital channels to reduce human agent headcount. Call-center volume deflection drives procurement decisions here.
- Wealth Management:High-net-worth segments justify elevated per-seat licensing through portfolio optimization and tax-loss harvesting conversations. Singapore and Switzerland private banking clusters concentrate demand.
- Investment Banks:Corporate treasury and capital markets functions deploy conversational interfaces for FX hedging and liquidity management. Multinational banks operating across London, New York, and Singapore lead adoption.
- Credit Unions:Member-owned institutions prioritize cost containment and community-specific service models over enterprise-scale AI investment. North American cooperative banking networks represent the primary geography.
Retail Banks dominate installed base. Wealth Management is climbing the fastest.
Functionality:
Application criticality separates always-on infrastructure from episodic advisory interactions.
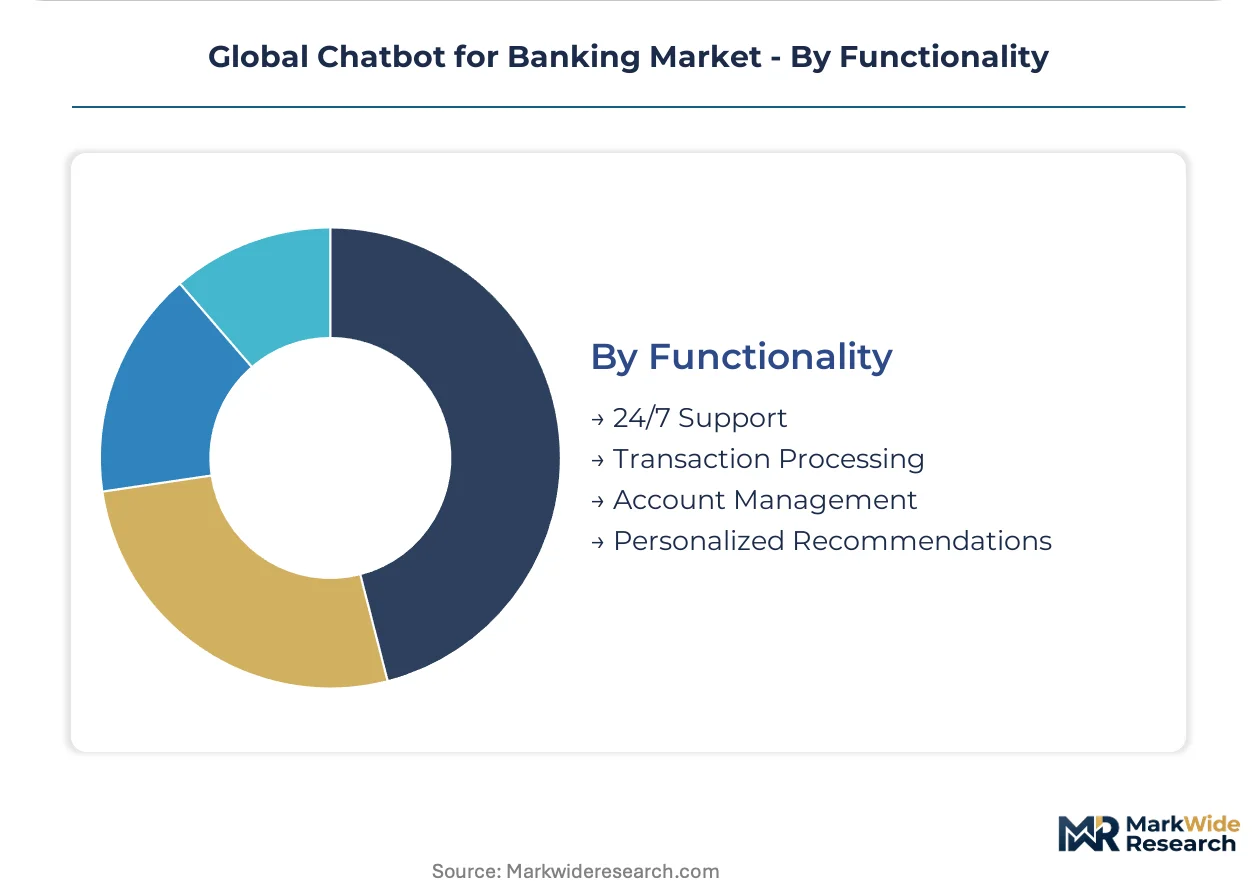
- 24/7 Support:Round-the-clock availability for balance inquiries, fraud alerts, and service outages. Australian and Canadian retail banking markets treat this as table stakes for customer retention.
- Transaction Processing:Conversational execution of payments, transfers, and bill settlements with real-time core banking integration. India's digital public infrastructure enables standardized deployment here.
- Account Management:Self-service address updates, card ordering, and limit modifications through natural language. United Kingdom open banking regulations mandate API availability that supports this functionality.
- Personalized Recommendations:AI-generated product suggestions and financial wellness coaching based on transaction history. SEC fiduciary duty standards in the United States constrain how these conversations execute.
24/7 Support dominates installed base. Personalized Recommendations is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Swiss private banking clusters where wealth management licensing commands per-seat premiums exceeding United States retail deployments by multiples. German institutions absorb compliance premiums under GDPR and EU AI Act mandates. India's digital public infrastructure compresses implementation costs through standardized open banking APIs.
United States
National banks deploy enterprise-grade natural language processing infrastructure for mortgage origination and complex advisory conversations. SEC fiduciary duty standards constrain robo-advisory chatbot architectures through strict documentation requirements. New York and San Francisco financial technology clusters drive procurement of retrieval-augmented generation systems for Tier-1 institutions.
Germany
Retail banks segment chatbot deployments into lower-risk informational queries versus restricted advisory functions under EU AI Act protocols. Bafin supervision mandates granular audit trails for credit-scoring algorithm conversations. Frankfurt and Munich banking centers favor hybrid cloud architectures that retain sensitive authentication logic on-premise while leveraging cloud elasticity for natural language processing.
India
Account aggregator frameworks and UPI infrastructure enable standardized data pipes for conversational financial services across mass-market segments. RBI guidelines on digital lending transparency shape chatbot disclosure requirements for automated credit decisions. Mumbai and Bangalore fintech clusters concentrate mobile-first deployments with embedded voice biometric authentication.
Switzerland
Private banking institutions justify elevated per-seat licensing through portfolio optimization and tax-loss harvesting conversation engines. FINMA guidelines on digital client interaction mandate human-in-the-loop oversight for algorithmic advisory recommendations. Geneva and Zurich wealth management centers concentrate demand for multimodal authentication combining natural language understanding with speaker recognition.
Singapore
Multinational banks operating across London, New York, and Singapore procurement mandates consolidate vendor relationships around unified conversational interfaces for corporate treasury functions. MAS technology risk management guidelines impose resilience standards on cloud-based chatbot deployments. The Marina Bay financial district anchors regional headquarters procurement decisions for FX hedging and liquidity management automation.
Global Chatbot for Banking Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with modular natural language understanding engines. The vendor base separates into three concentration levels: enterprise AI assistant providers with banking-specific intent libraries, cloud-native conversational platforms with API-first architectures, and legacy rule-based chatbot maintainers serving credit union segments. Two competitive moves dominate: strategic partnerships between core banking platform vendors and conversational AI specialists, and geographic expansion through regulatory sandbox approvals in jurisdictions with emerging open banking frameworks.
Within the vertical specialist tier, Kore.ai and Kasisto occupy positions defined by finance-domain natural language understanding differentiation. Haptik represents the mobile-first archetype emerging from India's digital public infrastructure environment. These three companies exemplify how geographic origin and deployment architecture specialization shape competitive positioning without requiring horizontal expansion across all banking functions.
| Leading Market Players |
|---|
| Kore.ai |
| Kasisto |
| Inbenta Technologies |
| Nuance Communications |
| CreativeVirtual |
| Pypestream |
| Haptik |
| VeriPark |
| Neurons Lab |
| Others |
Supply & Pricing Matrix
Trans-Pacific submarine cable latency costs differentially compress margins for cloud-native conversational AI vendors serving European banks against on-premise competitors. This freight-logistics corridor's pricing volatility amplifies the customization-premium spread between configured enterprise deployments and standardized SaaS tiers, while GPU supply concentration in Taiwan and South Korea feeds downstream price differentiation across deployment architectures.
Pricing Analysis
The customization-premium spread separates configured-to-order enterprise AI assistant deployments from standardized rule-based chatbot SaaS tiers. Pricing stratifies across premium AI-driven assistants with retrieval-augmented generation capabilities, standard cloud-based transactional bots, and economy rule-based deflection tools for credit unions. Cost compression in the standard tier intensifies because hyperscaler API commoditization erodes middleware value capture. Credit unions exhibit highest price sensitivity; Swiss private banking clusters demonstrate least.
Supply Chain Analysis
Supplier-financing facilities from NVIDIA-dominated semiconductor vendors extend 90-120 day payment terms to cloud infrastructure providers training banking-domain large language models. GPU silicon fabrication concentrates in Taiwan and South Korea, with advanced packaging in Malaysia and Vietnam. The supply chain rests on HBM3 memory modules, TSMC CoWoS advanced packaging capacity, and NVIDIA CUDA software licensing. Single-source vulnerability around TSMC's leading-edge nodes threatens deployment timelines. Distribution runs through hyperscaler marketplaces and direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as EU AI Act compliance replacement cycles create upgrade demand following post-pandemic procurement freezes. The cyclical driver centers on regulatory-mandated infrastructure refresh rather than organic technology obsolescence.
For Market Incumbents: Insulate enterprise relationships by embedding explainability modules that preempt EU AI Act conformity assessments. Acquire specialized prompt engineering talent pools before scarcity intensifies. Threat substitution from generative AI-native entrants demands banking-specific intent library deepening as the defensive lever. For New Entrants and Emerging Players: Establish a beachhead in India's account aggregator-enabled mobile-first deployments where standardized open banking APIs reduce integration friction. Target credit union segments underserved by enterprise sales complexity. Go-to-market angle: voice biometric authentication bundles for UPI ecosystem integration. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy core banking platform vendors seeking conversational AI capability gaps. Long-term viability favors vertical specialists with finance-domain natural language understanding differentiation over horizontal generalists. Signal to watch: regulatory sandbox approvals in jurisdictions with emerging open banking frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Engineering | Human-in-the-loop architectures satisfy Bafin and ECB scrutiny for credit-scoring chatbot deployments. |
| Voice Biometric Authentication Integration | Multimodal speaker recognition opens fraud-resistant transaction channels for UPI and PIX ecosystems. |
| Retrieval-Augmented Generation Deployment | Contextual mortgage origination conversations differentiate Tier-1 US retail banks from rule-based competitors. |
| Core Banking Platform Partnership | API-first integration with FIS and Temenos compresses implementation timelines from months to weeks. |
| Wealth Management Per-Seat Licensing | Portfolio optimization engines justify premiums exceeding retail deployments in Singapore and Switzerland. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EU regulatory conformity assessment documentation, and hyperscaler capex disclosures. Conversations with chief information officers at retail banks, digital channel heads at wealth management institutions, compliance officers navigating EU AI Act implementation, and procurement leads at credit union networks informed demand-side validation. Vendor-side perspectives came from conversational AI platform executives, core banking integration specialists, and cloud infrastructure account managers. Bottom-up deployment counts triangulate against top-down banking IT spend allocation models.
Forecast inputs span solution architecture tiers, deployment modality choices, end-user institution types, and geographic regulatory clusters across the analysis window. Segmentation dimensions modeled include AI capability maturity, infrastructure sovereignty requirements, and wealth management licensing intensity. CAGRs derive from deployment velocity curves adjusted for replacement cycle compression under EU AI Act mandates. Industry-specific inputs incorporate call-center deflection ROI thresholds and GPU supply availability constraints.
Stress conditions across NVIDIA export control volatility, EU AI Act enforcement intensity, and Indian digital public infrastructure adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation timelines and cloud migration acceleration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Cybersecurity in Banking Market
Banking
Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
Singapore Data Analytics in Banking Market
Banking
Saudi Arabia Retail Banking Market
Banking
Virtual Teller Machine (VTM) Market
Banking
Core Banking Solutions Market
Banking
Global Certificate of Deposit Market
Banking
India Data Analytics in Banking Market
Banking
Automated Teller Machine (ATM) Market
Banking
Retail Banking IT Spending Market
Banking
China Retail Banking System Market
Banking
Europe Machine Learning in Banking Market
Banking
Letter of Credit Confirmation Market
Banking
Digital LED Retail Banking Market
Banking
Global AI in Banking Market
Banking
US Retail Banking Market