
 Germany Neobanking Market | 2026-2036
Germany Neobanking Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Neobanking Market Foresight
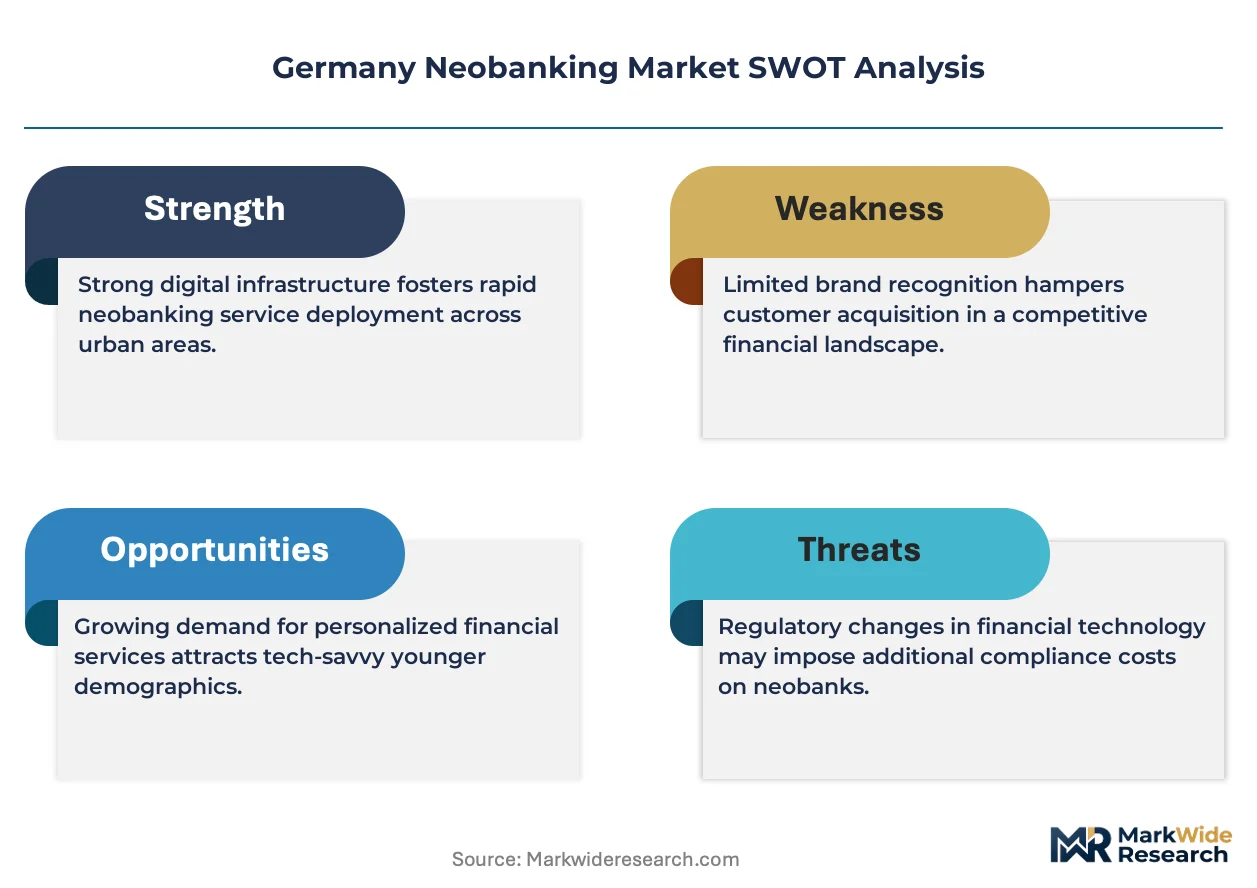
EU banking passport authorization under CRD IV and the associated BaFin fintech licensing pathway is redrawing competitive boundaries for new entrants. N26 GmbH leverages its full European banking license to sustain cross-border expansion without establishing local subsidiaries in each jurisdiction. Trade Republic Bank GmbH anchors its position through commission-free securities trading integrated with deposit accounts, differentiating from pure payment-focused challengers. Fidor Bank AG, an earlier entrant now under institutional ownership, navigates the transition from pioneer to infrastructure provider for other digital brands.
Germany neobanking denotes the provision of retail and SME financial services through mobile-first platforms operating without physical branch networks, typically underpinned by real-time payment rails and cloud-native core banking systems. These platforms execute account opening, transaction processing, and lending decisions through automated workflows that reduce marginal cost per customer to fractions of traditional banking economics. Personal loans and digital wallets capture the deepest margin pools among service types, while small business owners and freelancers represent the fastest-expanding customer categories as platform features expand into invoicing, tax automation, and multi-currency operations. API banking and AI-based risk assessment constitute the most strategically contested technology layers, determining underwriting precision and third-party ecosystem reach.
BaFin supervises licensing under the German Banking Act, while the ECB directly oversees significant institutions that breach threshold criteria for total assets. The EU AI Act introduces forthcoming compliance obligations for automated credit scoring systems, reshaping product development priorities for neobanks deploying machine learning models. Stakeholders must monitor how PSD3 implementation alters account access rules and interchange economics, as these provisions determine whether incumbent banks can restrict data sharing or impose surcharges that erode challenger unit economics.
Market Dynamics
BaFin's tightened licensing framework for e-money institutions is filtering market participants and compressing the operational runway for capital-light entrants, forcing a strategic pivot toward full banking license acquisition or infrastructure partnerships.
Growth Catalysts
- PSD2 Open Banking Mandates:Regulatory-driven account data access is dismantling incumbent information monopolies and enabling third-party payment initiation services to capture transaction flows previously locked inside legacy institutions.
- Real-Time Payment Rails:SEPA Instant Credit Transfer infrastructure deployment is eliminating settlement latency, allowing neobanks to match incumbent payment speeds without maintaining proprietary clearing networks.
- SME Digital Migration:Small business owners in Berlin and Hamburg are abandoning branch-based relationships for platforms offering integrated invoicing, tax automation, and multi-currency treasury management.
Market Restraints
- Capital Buffer Requirements:BaFin's escalating minimum capital thresholds for payment institutions are extending breakeven timelines and constraining organic expansion capacity for sub-scale operators.
- Cloud Concentration Risk:Core banking system dependency on AWS, Google Cloud, and Microsoft Azure creates single-point-of-failure exposure that regulators are scrutinizing under outsourcing guidelines.
- Interchange Compression:European Commission caps on card transaction fees are squeezing the primary revenue stream for payment-focused challengers lacking diversified lending income.
Strategic Opportunities
- BaFin Sandbox Pathway:The regulator's structured testing environment for innovative business models is lowering entry barriers for specialized providers targeting niche verticals like freelance tax optimization.
- Embedded Finance Convergence:API banking integration with e-commerce platforms and accounting software is creating distribution channels that bypass traditional customer acquisition economics.
- Eastern State Expansion:Underpenetrated SME populations in Saxony and Brandenburg present first-mover advantages for platforms willing to localize beyond Berlin-Hamburg corridor saturation.
Industry Challenges
- Machine Learning Risk Modeling:The EU AI Act's forthcoming compliance obligations for automated credit scoring systems are forcing product development pivots and explainability investments that delay underwriting automation roadmaps.
- Legacy Core Migration:Established fintech infrastructure providers impose integration complexity and data portability friction that extends time-to-market for new feature deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Neobanking Market |
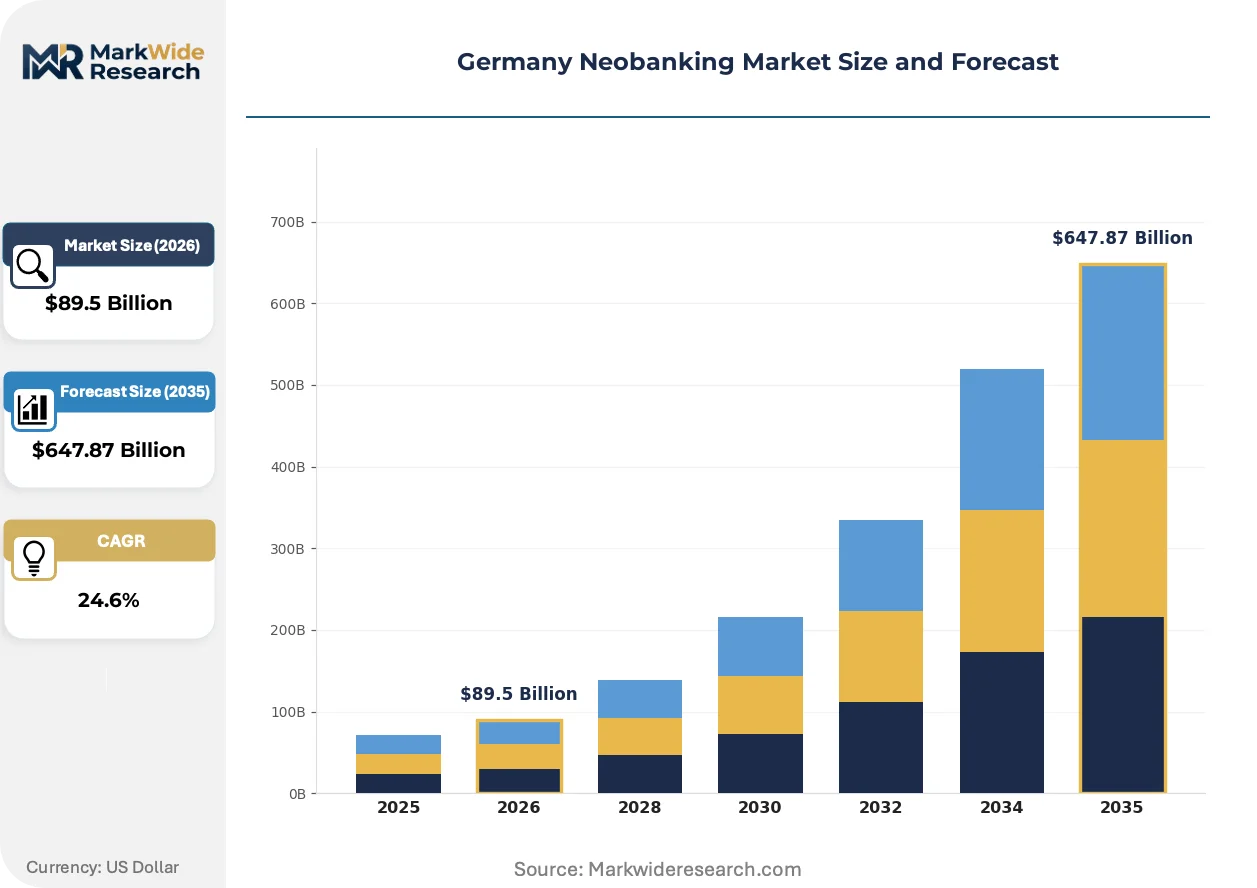
| Market Size in 2026 | $89.5 Billion |
| Market Size in 2035 | $647.87 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Digital Wallets, Peer-to-Peer Transfers, Savings Accounts, Personal Loans, Forex Services Customer Type: Millennials, Small Business Owners, Freelancers, Students, Retirees Technology: AI-based Risk Assessment, Blockchain, API Banking, Cloud Computing, Biometric Authentication Distribution Channel: Mobile Applications, Web Portals, Social Media, Affiliate Networks, Direct Marketing |
| Companies Covered | Fidor Bank AG, Trade Republic Bank GmbH, N26 GmbH, Penta Fintech GmbH, Tomorrow GmbH, Deutsche Kreditbank AG (DKB), solaris SE, Kontist GmbH, Vivid Money GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Neobanking Market Shifts & Advancements
Cloud-native core banking architectures are decomposing traditional technology stacks, enabling modular service assembly that accelerates product iteration cycles and compresses vendor lock-in durations across the competitive landscape.
Containerized microservices architecture is decomposing monolithic legacy systems into discrete functional components. Mid-tier neobanks are adopting this approach fastest, rebuilding their technology estates module-by-module rather than executing wholesale replacements. The structural consequence is decomposing the traditional core banking vendor oligopoly, as specialized providers capture individual service layers.
BaFin's implementation of the EU AI Act is imposing algorithmic transparency requirements on automated lending decisions. Credit scoring product teams must now document model logic and audit trails that satisfy supervisory review. Retail unsecured lending segments face the steepest compliance burden, with several operators freezing machine learning deployments pending regulatory clarification.
Freelancers and gig-economy workers are consolidating financial relationships onto single platforms that bundle payment acceptance, expense categorization, and tax reserve calculation. Traditional banks with siloed product structures are losing these customers to integrated challengers. This behavioral shift concentrates most visibly among creative professionals in Berlin's media and technology clusters.
Germany Neobanking Market Segmentation
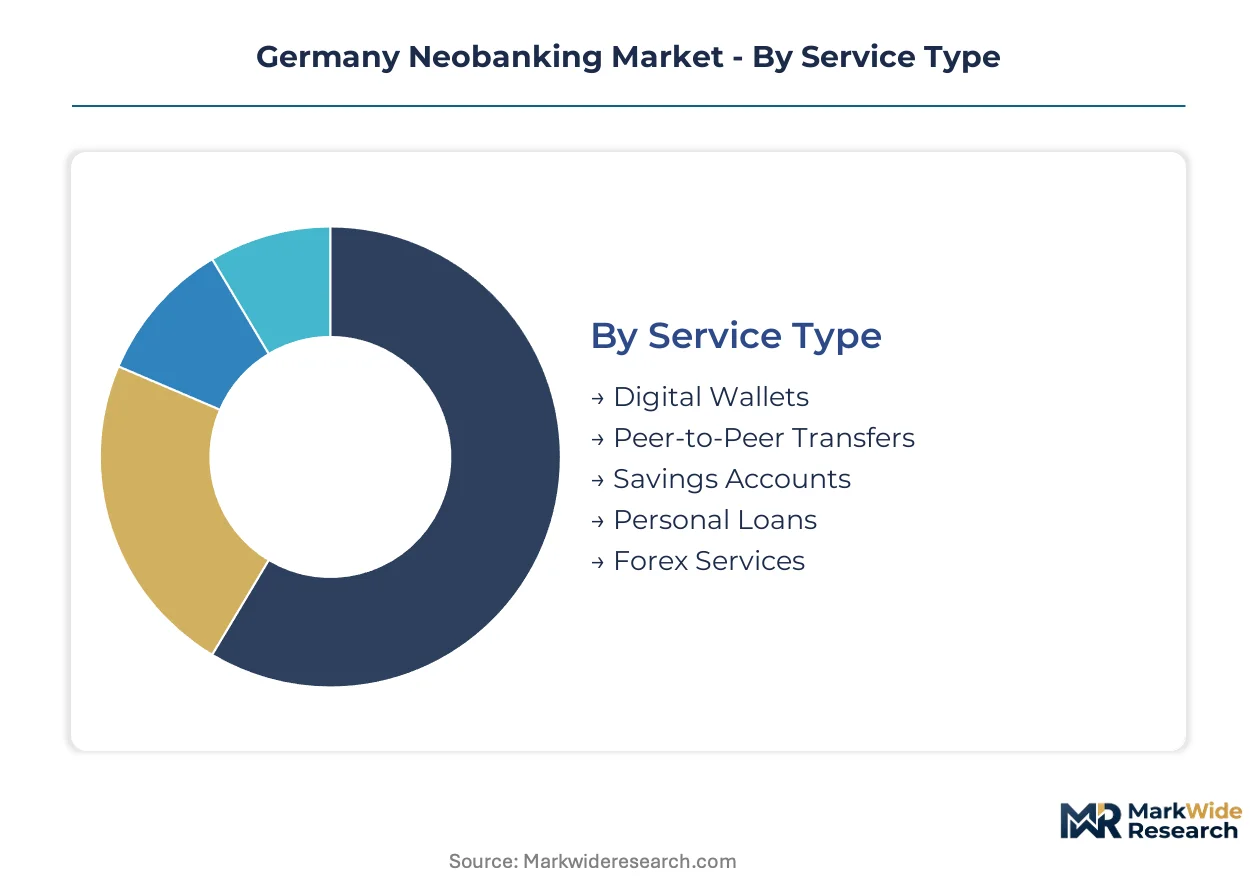
Neobank profitability hinges on matching service architecture to distinct behavioral clusters. German market dynamics reward precise targeting across service mix, customer life stage, and technology deployment choices.
Service Type:
Domestic demand concentrates on payment and deposit services, while cross-border lending and forex operations extend revenue reach into neighboring eurozone markets.
- Digital Wallets:Mobile-first payment aggregation platforms combining SEPA Instant rails with merchant QR acceptance. Berlin and Hamburg freelancers drive adoption for gig-economy payment splitting and expense tracking.
- Personal Loans:Unsecured credit products underwritten through alternative data streams and automated decision engines. Small business owners in Saxony and Brandenburg access working capital without traditional collateral requirements.
- Peer-to-Peer Transfers:Domestic and cross-border remittance services leveraging SEPA infrastructure.
- Savings Accounts:High-yield deposit products with automated round-up features.
- Forex Services:Multi-currency accounts with real-time conversion for cross-border commerce.
Digital wallets hold the largest share; momentum sits with personal loans as BaFin clarifies automated underwriting rules.
Customer Type:
Cost-to-serve varies dramatically across segments, with business customers generating 3-4x revenue per user but requiring complex feature integration.
- Small Business Owners:SME operators demanding integrated invoicing, tax automation, and multi-currency treasury. Eastern German states present underpenetrated expansion terrain beyond saturated Berlin-Hamburg corridors.
- Freelancers:Self-employed professionals consolidating payment acceptance, expense categorization, and tax reserve calculation onto single platforms. Creative clusters in Berlin's media districts show highest platform stickiness.
- Millennials:Digital-native retail customers prioritizing mobile experience over branch access.
- Students:Price-sensitive segment attracted by zero-fee structures and educational budgeting tools.
- Retirees:Emerging segment requiring simplified interfaces and voice-assisted navigation.
Small business owners contribute dominant revenue per user; freelancers are expanding most quickly as platform feature depth increases.
Technology:
Technology deployment maturity separates scaled operators from capital-constrained challengers, with cloud infrastructure now table stakes rather than differentiator.
- API Banking:Open banking infrastructure enabling third-party service integration and embedded finance distribution. E-commerce platforms and accounting software partnerships bypass traditional customer acquisition economics.
- AI-based Risk Assessment:Machine learning models for credit scoring facing EU AI Act compliance deadlines. Retail unsecured lending segments confront steepest documentation and audit trail requirements.
- Cloud Computing:Core banking system virtualization on AWS, Google Cloud, and Microsoft Azure.
- Blockchain:Distributed ledger applications for settlement and identity verification.
- Biometric Authentication:Facial and voice recognition replacing password-based security layers.
API banking anchors current infrastructure investment; AI-based risk assessment faces steepest expansion trajectory once regulatory clarity emerges.
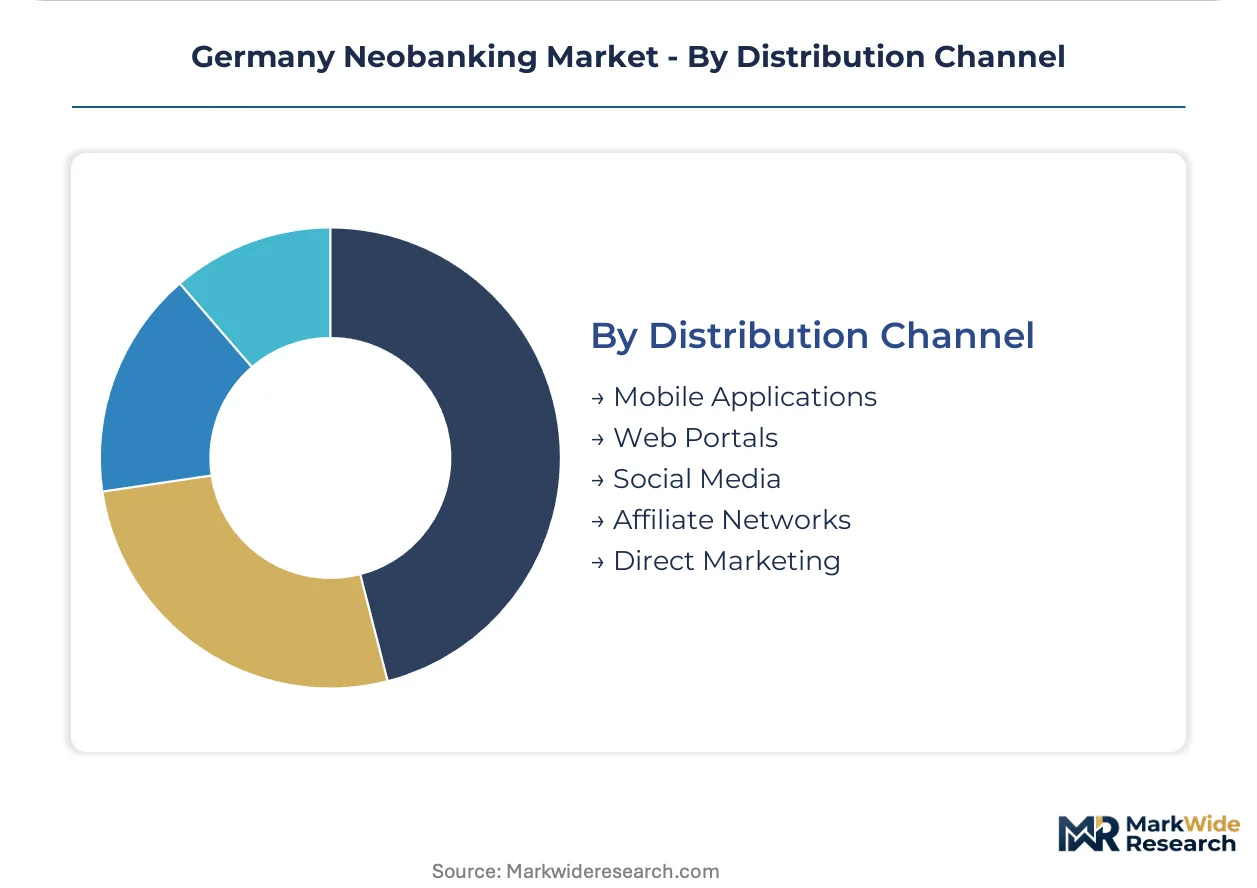
Distribution Channel:
Channel economics determine unit profitability, with organic mobile acquisition outperforming paid affiliate networks by substantial margins.
- Mobile Applications:Native iOS and Android platforms serving as primary customer interface. Real-time push notifications and biometric login drive daily engagement metrics.
- Web Portals:Browser-based access for complex account management and document upload workflows.
- Social Media:Instagram and TikTok campaigns targeting demographic cohorts with influencer partnerships.
- Affiliate Networks:Comparison site and fintech aggregator referral arrangements.
- Direct Marketing:Email and push notification campaigns for cross-sell and retention.
Mobile applications command dominant usage share; social media channels are climbing the fastest as Gen Z acquisition intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEPA Instant Credit Transfer infrastructure and dense fiber-optic networks across German metropolitan corridors anchor the neobanking ecosystem's geographic distribution. Berlin and Hamburg concentrate venture capital deployment and fintech startup density. Eastern federal states present underpenetrated expansion terrain beyond saturated western demand centers.
Berlin-Brandenburg
Creative professionals and gig-economy workers drive platform adoption for integrated payment acceptance and tax automation. BaFin's fintech licensing pathway streamlines authorization for e-money institutions testing innovative business models. Media and technology clusters in Berlin's Kreuzberg and Mitte districts exhibit highest customer stickiness for challenger banking platforms.
Hamburg
SME operators demand multi-currency treasury management and automated invoicing features. The city's port logistics ecosystem generates cross-border payment flows that favor real-time settlement rails. Fintech venture capital concentrates in HafenCity and St. Pauli districts, supporting neobank product development cycles.
Bavaria
Munich's affluent retail customer base prioritizes mobile-first investment products and high-yield deposit structures. The state's manufacturing Mittelstand generates working capital demand for unsecured lending products. Industrial clusters around Ingolstadt and Nuremberg show rising adoption of embedded finance solutions through accounting software integrations.
North Rhine-Westphalia
Düsseldorf and Cologne host established corporate banking relationships that digital challengers target for displacement. The region's dense SME population seeks alternatives to branch-based business account servicing. Ruhr Valley industrial restructuring is producing freelance-heavy service economies receptive to consolidated financial platforms.
Saxony and Brandenburg
Underpenetrated SME populations outside Berlin's immediate orbit present first-mover advantages for localized platform offerings. Dresden and Leipzig technology clusters are emerging as secondary fintech talent pools. Eastern state regulatory familiarity with BaFin sandbox procedures accelerates market entry timelines for specialized providers.
Germany Neobanking Market Competitive Landscape
Listed leaders compete with private specialists across licensing status and capital access. Full European banking license holders command structural advantages in cross-border expansion without local subsidiary requirements. Three archetypes dominate: deposit-and-lending integrated platforms, payment-focused challengers, and infrastructure-as-a-service providers. Competitive moves concentrate on M&A for license acquisition and strategic partnerships for embedded finance distribution.
Among Berlin-based challengers, N26 GmbH exemplifies the full-license archetype enabling passported European operations. Trade Republic Bank GmbH anchors the commission-free securities trading vector, differentiating from pure payment specialists. Fidor Bank AG, now under institutional ownership, occupies a position as infrastructure provider for other digital brands rather than direct consumer challenger.
| Leading Market Players |
|---|
| Fidor Bank AG |
| Trade Republic Bank GmbH |
| N26 GmbH |
| Penta Fintech GmbH |
| Tomorrow GmbH |
| Deutsche Kreditbank AG (DKB) |
| solaris SE |
| Kontist GmbH |
| Vivid Money GmbH |
| Others |
Supply & Pricing Matrix
BaFin's licensing framework for e-money institutions and payment services gates both vendor qualification and pricing tier eligibility simultaneously, compressing margins for sub-scale operators while rewarding full-license holders with structural pricing power over transaction-based revenue streams.
Pricing Analysis
Volume-discount tiering structures dominate SaaS-based business banking packages, with platform providers segmenting freelancers from SME operators through feature depth rather than pure transaction volume. Price differentiation rests on API integration complexity and real-time payment rail access, with embedded finance partnerships commanding premium positioning. Pricing pressure stems from European Commission interchange caps squeezing card-based revenue models. Freelancers in Berlin's creative clusters exhibit highest price sensitivity, while Hamburg's port-logistics SMEs absorb premium tiers for multi-currency treasury functionality.
Supply Chain Analysis
Inventory and lead-time compression in core banking infrastructure has shifted vendor relationships toward modular microservices procurement rather than monolithic system replacement. Cloud computing supply concentrates in Ireland, the Netherlands, and Germany itself, with AWS, Google Cloud, and Microsoft Azure anchoring data center capacity. Core banking system components draw from specialized German fintech infrastructure providers and Nordic API specialists. Single-source vulnerability in cloud concentration risk looms as BaFin scrutinizes outsourcing guidelines. Distribution runs through direct vendor relationships and systems integrator partnerships serving mid-tier neobanks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent digital banks must defend against embedded finance substitution, where non-bank platforms absorb payment flows and customer relationships through accounting software and e-commerce integrations.
For Market Incumbents: Compound defensive positioning through API banking infrastructure control and strategic embedded finance partnerships with accounting software providers. Acquire specialized tax-automation capabilities to block freelance platform migration. Vertical integration into cloud-native core systems reduces vendor lock-in and accelerates feature deployment cycles against challengers.
For New Entrants and Emerging Players: Differentiate on regulatory specialization, targeting BaFin sandbox authorization for niche verticals like cross-border freelancer tax optimization. Eastern German SME populations in Saxony and Brandenburg present the most penetrable expansion terrain beyond saturated Berlin-Hamburg corridors. Pursue white-label infrastructure partnerships rather than full-license acquisition to compress capital requirements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across full European banking license acquisition pathways, extending breakeven timelines and favoring scaled operators. Target acquisition profiles center on infrastructure-as-a-service providers with existing BaFin authorization and modular technology stacks. Monitor EU AI Act implementation clarity as the critical signal for automated underwriting product viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Full Banking License Acquisition | Passported European operations under CRD IV eliminate subsidiary requirements in each jurisdiction. |
| Embedded Finance Partnership | API integration with accounting software bypasses traditional customer acquisition economics. |
| Cloud-Native Core Migration | Microservices architecture decomposes vendor lock-in and accelerates product iteration cycles. |
| AI Explainability Investment | EU AI Act compliance for automated credit scoring preserves underwriting automation roadmaps. |
| Eastern State Geographic Expansion | Underpenetrated SME populations in Saxony and Brandenburg offer first-mover positioning. |
Research Methodology
A spread of perspectives from neobank product executives, BaFin regulatory specialists, fintech infrastructure vendors, and SME banking relationship managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through ECB statistical releases, BaFin licensing registers, SEPA infrastructure deployment data, and European Commission payment system reports. Bottom-up customer segmentation analysis triangulated against top-down market sizing from venture capital deployment tracking and fintech startup density metrics.
Segmentation dimensions modeled encompass service type, customer archetype, technology deployment maturity, and distribution channel economics across the analysis window. CAGRs derive from regression analysis against SEPA Instant adoption curves, SME digital migration velocity, and regulatory implementation timelines. Forecast inputs incorporate BaFin licensing pipeline data and cloud infrastructure capacity expansion disclosures from hyperscale providers.
The analysis sits within stated boundaries; outcomes outside current regulatory implementation schedules or macroeconomic stability conditions would require recalibration. Forecasts reflect documented assumptions around PSD3 implementation, EU AI Act enforcement clarity, and interchange fee regime continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
US Data Analytics in Banking Market
Banking
Europe Neobanking Market
Banking
Spain Data Analytics in Banking Market
Banking
Europe Banking-As-A-Service Market
Banking
GCC Mobile Banking Market
Banking
Investment Banking and Trading Services Market
Banking
Commercial Banking Market
Banking
US Investment Banking Market
Banking
Global AI in Banking Market
Banking
Germany Banking As a Service Market
Banking
Armenia Banking Market
Banking
Global Banking Systems Software Market
Banking
Bank Management Software Market
Banking
Payment Bank Solutions Market
Banking
Retail Banking IT Spending Market
Banking
Corporate Banking Market