
 Armenia Banking Market | 2026-2036
Armenia Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Armenia Banking Market Insights
Market Context
Armenia's pool of certified risk management professionals is rotating toward fintech-integrated lenders, tightening talent availability for traditional branch-heavy institutions. Ameriabank leverages its corporate banking franchise to dominate syndicated lending for mining and energy clients. Ardshinbank sustains the widest ATM and branch footprint outside Yerevan, anchoring rural deposit capture. Evocabank competes through a mobile-first architecture that minimizes physical infrastructure costs.
Technical Definition and Segment Structure
Armenia banking encompasses licensed financial intermediation governed by the Central Bank of Armenia, involving deposit mobilization, credit extension, payment settlement, and treasury operations denominated in Armenian dram and foreign currency. The system operates through fractional reserve mechanics with mandatory reserve requirements and deposit insurance caps set by the regulator. Retail banking generates the deepest margin pools through net interest spread on dram-denominated consumer loans, while mobile banking as a delivery channel captures the fastest user growth as smartphone penetration crosses threshold levels in secondary cities. Corporate banking occupies the most relationship-intensive segment, with loan officers maintaining direct ties to large exporters and government contractors.
Regulatory Framework and Outlook
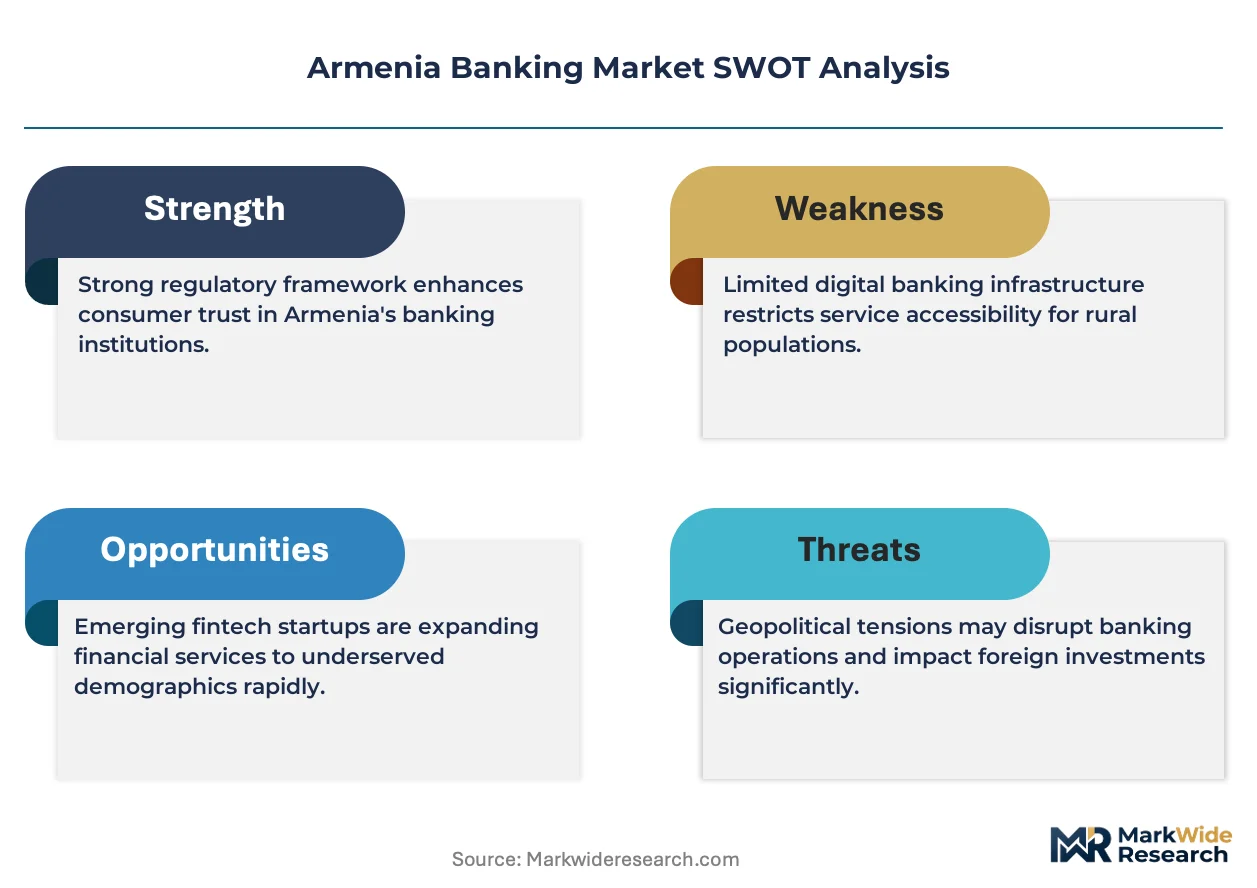
The Central Bank of Armenia enforces prudential standards aligned with Basel III capital buffers, while the country's deposit guarantee fund shapes retail liability pricing through insured threshold levels. FATF compliance reviews and EU correspondent banking access conditions jointly determine foreign currency clearing capabilities for Armenian lenders. Stakeholders must monitor how digital banking license categories and open banking API mandates reshape competitive entry barriers.
Market Dynamics
Basel III-aligned capital adequacy rules from the Central Bank of Armenia are compressing smaller lenders into consolidation, while digital onboarding platforms slash origination costs for agile competitors. This regulatory-technology tension is redistributing market power toward capital-rich institutions and mobile-native entrants.
Growth Catalysts
- Digital Onboarding Platforms:Automated KYC and remote identity verification slash customer acquisition costs for retail lenders. Secondary cities outside Yerevan see the fastest adoption as smartphone penetration crosses critical thresholds.
- SME Lending Acceleration:Streamlined credit scoring for small enterprises unlocks previously uneconomical borrower segments. The Central Bank of Armenia's simplified collateral registry reduces documentation friction for working capital loans.
- Mobile Penetration Threshold Effects:Smartphone density in Gyumri and Vanadzor enables branch-light distribution models. Deposit mobilization costs fall as USSD and app-based channels displace physical infrastructure.
Market Restraints
- Dollarization Fragility:Foreign currency deposit dominance exposes balance sheets to dram depreciation shocks. Lenders cannot fully hedge mismatch risk given shallow local forex derivatives markets.
- Talent Rotation Toward Fintech:Certified risk management professionals migrate to technology-integrated lenders. Traditional branch-heavy institutions face hollowed-out credit committees and compliance functions.
- Correspondent Banking Access Conditions:FATF compliance reviews determine foreign currency clearing capabilities. Armenian dram liquidity management depends on EU-based correspondent relationships subject to de-risking pressures.
Strategic Opportunities
- Rural Deposit Capture:ATM and agent network expansion outside Yerevan's metropolitan corridor taps underbanked agricultural communities. Ardshinbank's branch footprint demonstrates viable unit economics in secondary towns.
- Open Banking API Mandates:Regulatory frameworks enabling third-party payment initiation and account aggregation create new revenue pools. Fintech partnerships through standardized interfaces reduce internal development burdens.
- Syndicated Mining Finance:Copper and molybdenum export revenues anchor large-ticket corporate lending. Relationship-intensive structures favor lenders with established government contractor ties and project finance expertise.
Industry Challenges
- Core Banking System Modernization:Legacy mainframe architectures constrain real-time payment processing and API integration. Replacement timelines stretch 18-36 months, freezing product innovation cycles during competitive pressure.
- Deposit Insurance Threshold Management:The country's deposit guarantee fund shapes retail liability pricing through insured cap levels. Rate competition intensifies as uninsured depositors demand yield premiums for perceived institutional risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armenia Banking Market |
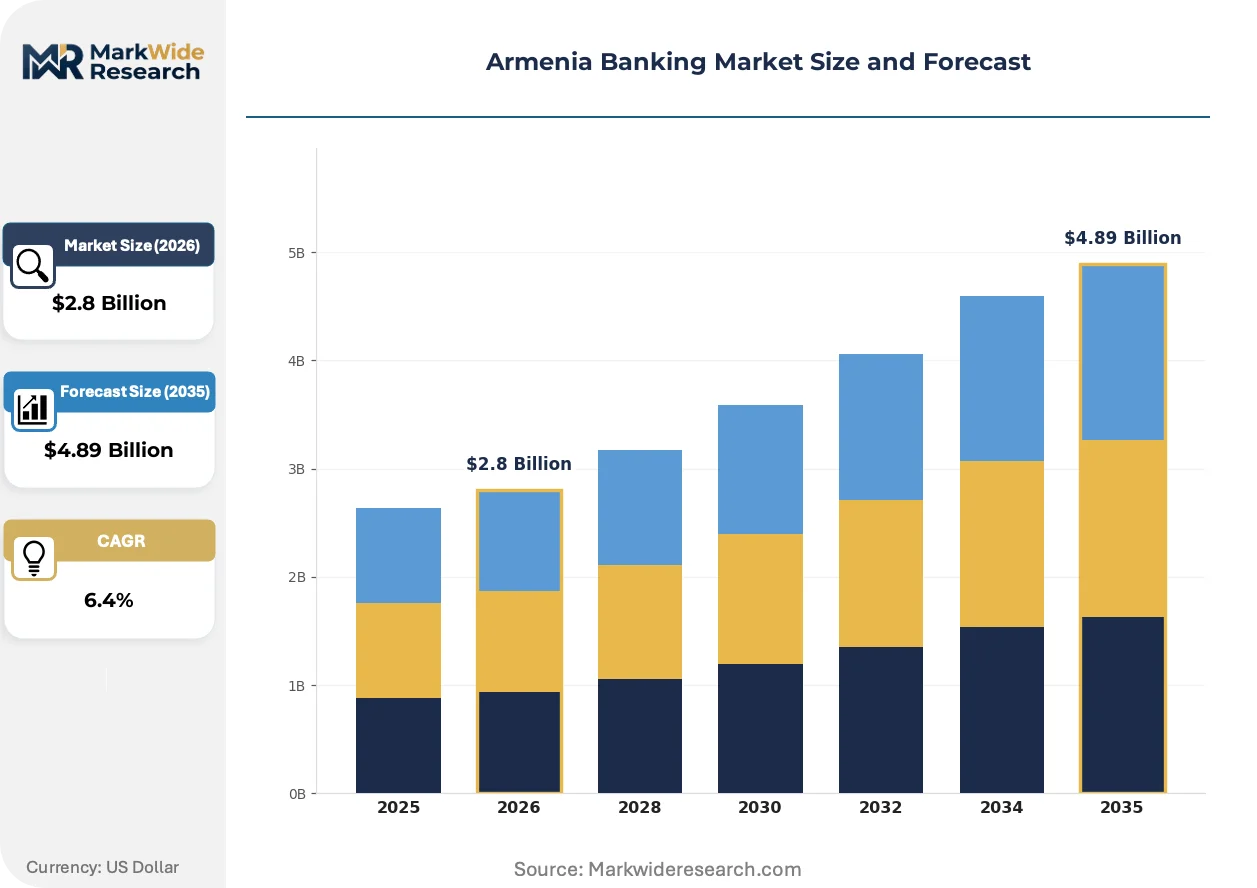
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Retail Banking, Corporate Banking, Investment Banking, Treasury Services, Private Banking, Trade Finance Customer Type: Individual Clients, Small & Medium Enterprises, Large Corporations, Government Entities, Non-Profit Organizations, Financial Institutions Delivery Channel: Branch Network, Internet Banking, Mobile Banking, Call Center, ATM Services, Agent Banking Product Offering: Loans, Deposits, Payment Services, Wealth Management, Foreign Exchange, Cards |
| Companies Covered | Inecobank, Converse Bank, Ardshinbank, ARARATBANK, ArmSwissBank, Ameriabank, Evocabank, ID Bank, ACBA Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armenia Banking Market Trends and Innovations
Cloud-native core banking architectures are supplanting on-premise legacy systems, enabling Armenian lenders to compress product development cycles and deploy microservices-based customer interfaces without capital-intensive hardware refresh programs.
Biometric authentication protocols are supplanting signature-based verification for high-value transactions. Retail borrowers in Yerevan's metropolitan corridor adopt facial recognition and fingerprint authorization fastest, with rural branches following within 18-24 months. Fraud losses compress while transaction abandonment rates fall, though implementation costs concentrate among smaller lenders lacking dedicated IT security functions.
The Central Bank of Armenia's digital banking license categories reshape competitive entry barriers for non-bank payment providers. Specialized permits for e-money issuance and payment initiation separate prudential requirements from full commercial banking charters. Fintech entrants target remittance corridors and merchant acquiring without deposit-taking obligations, forcing traditional lenders to defend payment rails through fee compression.
Subscription-based financial service bundling disrupts traditional fee-for-transaction models. Younger dram depositors in urban centers prefer flat monthly charges covering unlimited transfers, currency conversion, and investment access. Revenue volatility rises as predictable interchange income yields to customer lifetime value calculations and churn management investments.
Armenia Banking Market Segmentation
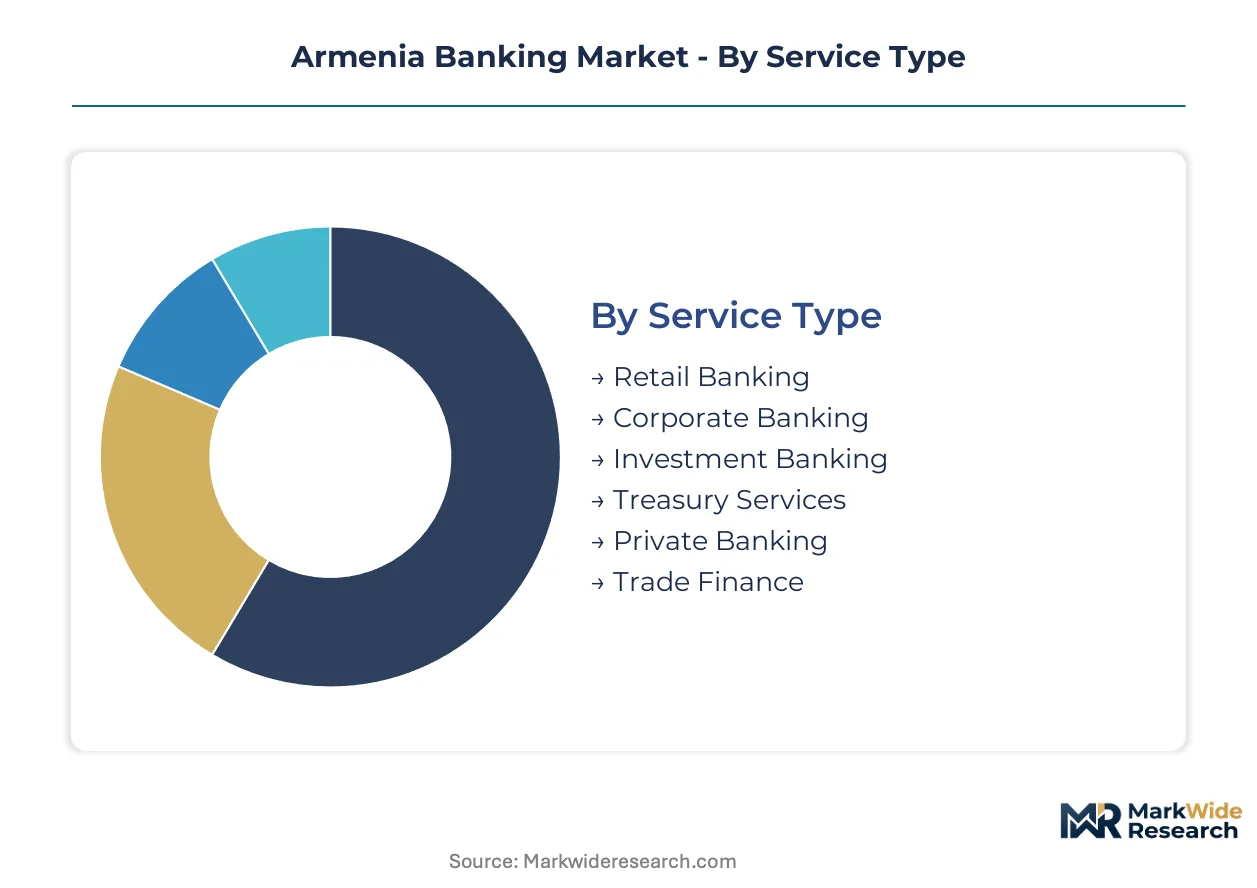
Segmentation in Armenia's banking market reveals how digital delivery channels and customer type specialization redistribute profitability across service lines. Lenders must align capital allocation with segment-specific margin profiles and regulatory capital requirements.
Service Type:
Retail banking and corporate banking face divergent substitution pressures from fintech entrants and capital market disintermediation respectively.
- Retail Banking:Consumer deposit mobilization and dram-denominated lending generate the deepest margin pools through net interest spread. Demand concentrates in Yerevan's metropolitan corridor where mobile penetration enables branch-light distribution models.
- Corporate Banking:Relationship-intensive credit extension to large exporters and government contractors requires dedicated loan officer coverage. Mining and energy sector clients anchor syndicated lending volumes for established franchise players.
- Investment Banking:Advisory and underwriting services for privatization transactions and debt issuance.
- Treasury Services:Liquidity management and interbank operations denominated in Armenian dram and foreign currency.
- Private Banking:High-net-worth client advisory with wealth preservation mandates.
- Trade Finance:Documentary credit and guarantee instruments for import-export operations.
Retail banking anchors the volume base while corporate banking gains share at the steepest rate through mining sector expansion.
Customer Type:
Cost-to-serve differentials widen dramatically between individual clients and large corporations, reshaping frontline staffing models.
- Individual Clients:Mass-market depositors and retail borrowers accessed through digital onboarding platforms. Smartphone penetration in Gyumri and Vanadzor accelerates mobile-first acquisition outside Yerevan.
- Small & Medium Enterprises:Working capital borrowers benefiting from the Central Bank of Armenia's simplified collateral registry. Streamlined credit scoring unlocks previously uneconomical segments.
- Large Corporations:Relationship-managed clients with complex treasury and trade finance requirements.
- Government Entities:Public sector deposit accounts and project finance mandates.
- Non-Profit Organizations:Mission-driven depositors with restricted investment policies.
- Financial Institutions:Interbank placements and correspondent banking relationships.
Individual clients deliver the widest revenue base while SME lending expands most quickly through digitized origination.
Delivery Channel:
Physical infrastructure intensity determines competitive viability across Armenia's geographic dispersion.
- Branch Network:Full-service locations maintaining direct ties to rural agricultural communities. Ardshinbank's footprint outside Yerevan demonstrates viable unit economics in secondary towns.
- Mobile Banking:App-based interfaces capturing the fastest user growth as smartphone density crosses threshold levels. Evocabank's architecture minimizes physical infrastructure costs.
- Internet Banking:Browser-based platforms for complex transaction workflows.
- Call Center:Voice-channel support for demographic segments with lower digital literacy.
- ATM Services:Cash withdrawal and deposit infrastructure in high-traffic locations.
- Agent Banking:Third-party retail outlets extending reach to underbanked areas.
Branch networks retain deposit stability while mobile banking climbs the fastest on user acquisition metrics.
Product Offering:
Net interest margin compression on traditional products pushes diversification into fee-generating lines.
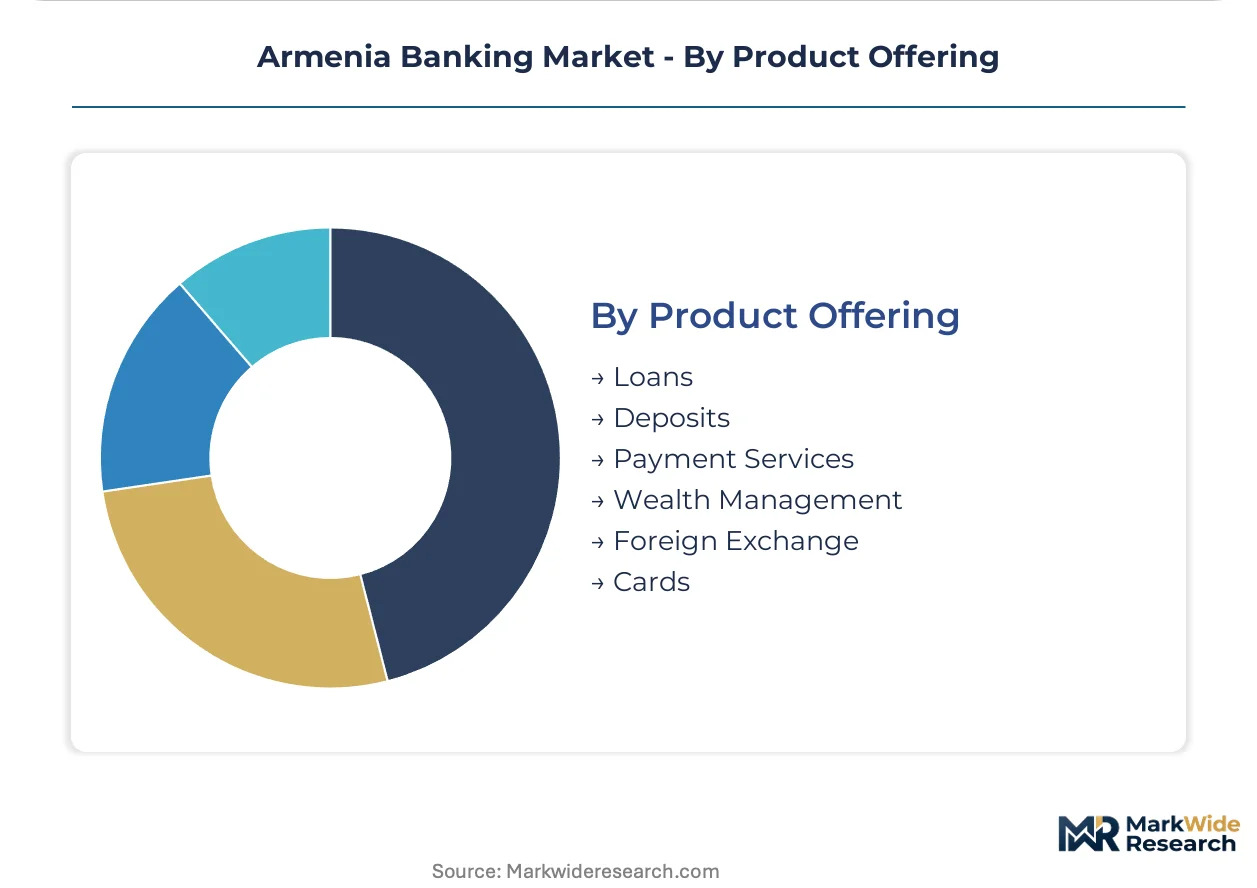
- Loans:Consumer and commercial credit extension with dram and foreign currency denomination. Dollarization fragility exposes balance sheets to depreciation shocks given shallow local hedging markets.
- Deposits:Retail liability mobilization shaped by deposit insurance threshold levels. Rate competition intensifies as uninsured depositors demand yield premiums.
- Payment Services:Transaction processing and merchant acquiring facing fintech fee compression.
- Wealth Management:Investment advisory and portfolio construction for affluent segments.
- Foreign Exchange:Currency conversion and hedging dependent on EU correspondent banking access.
- Cards:Debit and credit payment instruments with biometric authentication integration.
Loans generate the widest revenue contribution while payment services face the steepest margin pressure from non-bank entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yerevan commands deposit pricing premiums that rural branches cannot replicate, widening the metropolitan-provincial spread on dram-denominated liabilities. This asymmetry shapes capital allocation across Armenia's banking network.
Yerevan Metropolitan Corridor
Smartphone penetration and merchant density drive mobile-first adoption at scale. The Central Bank of Armenia's open banking API mandates accelerate fintech partnerships in the capital. Ameriabank and Evocabank concentrate digital product development teams in central Yerevan.
Gyumri and Shirak Province
Remittance inflows from Russia sustain foreign currency deposit bases in Armenia's second city. Simplified collateral registry rules from the central bank unlock SME working capital demand. Ardshinbank maintains the widest ATM footprint to capture agricultural community liquidity.
Vanadzor and Lori Province
Mining sector payrolls generate stable corporate deposit flows from copper and molybdenum operations. Basel III capital buffers constrain smaller lenders from syndicated project finance participation. Branch networks here serve as collection points for mining contractor receivables.
Southern Agricultural Belt
Ararat and Syunik provinces present underbanked borrower segments with limited credit bureau coverage. Agent banking regulations enable third-party retail outlets to extend deposit and payment reach. ACBA Bank leverages rural cooperative ties to penetrate agricultural lending markets.
Armenia Banking Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Armenia's banking system. The market exhibits tiered consolidation where capital-rich institutions absorb regulatory pressure while mobile-native entrants capture growth corridors. Three archetypes dominate: corporate banking franchise holders with mining sector relationships, branch-intensive deposit gatherers with rural coverage, and digital-first challengers with minimal physical infrastructure. Competitive moves center on core banking system modernization timelines and open banking partnership structures.
Among established franchise players, Ameriabank anchors the corporate banking tier through mining and energy sector relationships, while Ardshinbank exemplifies the branch-network archetype with coverage extending beyond Yerevan's metropolitan corridor. Evocabank occupies the mobile-native position with infrastructure-light distribution. These three represent the strategic poles around which smaller institutions must position.
| Leading Market Players |
|---|
| Inecobank |
| Converse Bank |
| Ardshinbank |
| ARARATBANK |
| ArmSwissBank |
| Ameriabank |
| Evocabank |
| ID Bank |
| ACBA Bank |
| Others |
Pricing and Supply Chain Analysis
Core banking system replacement timelines stretching 18-36 months concentrate vendor negotiation leverage among three dominant technology providers serving Armenian lenders, amplifying pricing power for those with established implementation track records in the South Caucasus.
Pricing Analysis
Yerevan's metropolitan corridor commands dram-denominated deposit pricing premiums that rural branches in Shirak and Lori provinces cannot replicate. Three-tier pricing structure across premium relationship-managed, standard digital-access, and economy branch-basic tiers differentiates net interest margins based on customer lifetime value calculations and cross-sell penetration. Cost compression in the standard tier is intensifying because mobile-native entrants force fee compression on payment services. SME borrowers demonstrate highest price sensitivity due to working capital constraints, while mining sector corporate clients exhibit lowest sensitivity given relationship bundling with trade finance and treasury services.
Supply Chain Analysis
Container availability on the Poti-Tbilisi-Yerevan trade lane constrains hardware refresh schedules for ATM and branch infrastructure deployments outside the capital. Technology sourcing draws from Germany, the United Arab Emirates, and Russia for core banking software licensing, server hardware, and network security appliances respectively. Single-source vulnerability concentrates in SWIFT connectivity and international card scheme processor relationships subject to EU correspondent banking de-risking pressures. Distribution runs through Tbilisi-based logistics hubs with final-mile completion by domestic IT integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Central Bank of Armenia's open banking API mandates constitute a regulatory inflection that will redistribute payment revenues toward fintech-integrated lenders within the analysis window.
For Market Incumbents: Fortify core banking modernization roadmaps to compress 18-36 month replacement cycles threatening product innovation during competitive pressure. Prioritize backward integration into cloud-native architecture development through partnerships with regional technology vendors to reduce vendor lock-in from dominant providers.
For New Entrants and Emerging Players: Anchor in rural deposit capture across Ararat and Syunik provinces where ACBA Bank's cooperative ties have not fully penetrated agricultural lending markets. Target agent banking regulations enabling third-party retail outlet partnerships as the primary go-to-market angle to bypass branch infrastructure capital requirements.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because Basel III capital adequacy rules are compressing smaller lenders toward absorption by capital-rich institutions. Acquisition targets should display viable mobile-first unit economics in secondary cities alongside unresolved legacy mainframe technical debt that acquirers can retire. The signal to watch is dram deposit mobilization cost divergence between branch-heavy and digital-native institutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Core Banking System Modernization | Cloud-native architecture deployment enables real-time payment processing and API integration for open banking compliance. |
| Rural Agent Network Expansion | Third-party retail outlet partnerships extend deposit and payment reach to underbanked agricultural communities in southern provinces. |
| Biometric Authentication Integration | Facial recognition and fingerprint authorization reduce fraud losses while accelerating high-value transaction completion rates. |
| Syndicated Mining Finance Structuring | Copper and molybdenum export revenue anchoring builds relationship moats with government contractors and large exporters. |
| Digital Banking License Acquisition | Specialized permits for e-money issuance enable fintech entrants to target remittance corridors without full commercial banking charters. |
Research Methodology
The analysis maps retail banking, corporate banking, and digital delivery channel segments, each validated through primary interviews with central bank regulatory affairs officers, commercial bank chief risk officers, fintech product development leads, and rural branch network managers. Secondary sources include Central Bank of Armenia prudential reporting, FATF mutual evaluation documentation, and deposit guarantee fund disclosure filings. Bottom-up loan book segmentation and top-down macroeconomic scenario modeling were triangulated to ensure consistency.
Model outputs were validated against external benchmarks including correspondent banking access condition assessments and regional banking sector consolidation patterns. Segmentation dimensions modeled encompass service type, customer type, delivery channel, and product offering across the projection horizon. CAGRs were derived from loan origination volume trajectories, deposit mobilization cost curves, and mobile banking user adoption saturation curves calibrated to smartphone penetration thresholds in secondary cities.
Material uncertainties — dram depreciation shocks, EU correspondent banking de-risking decisions, and core banking vendor consolidation — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory implementation timelines and technology adoption S-curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
UK Retail Banking Market
Banking
Germany Banking As a Service Market
Banking
Global Banking BPS Market
Banking
Smart Banking Solutions Market
Banking
US Investment Banking Market
Banking
Singapore Neobanking Market
Banking
Digital Banking Market
Banking
Smart ATM Market
Banking
Banking Tax Management Software Market
Banking
Onsite and Offsite Atms Market
Banking
Bank Kiosk Market
Banking
Europe Machine Learning in Banking Market
Banking
Asia-Pacific Data Analytics in Banking Market
Banking
ATM Market
Banking
Middle East and Africa Neobanking Market