
 Germany Banking As a Service Market | 2026-2036
Germany Banking As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Banking As a Service Market Foresight
Mid-sized online retailers and challenger banks are redrawing demand patterns across Germany's Banking As a Service landscape. Solaris leverages its full banking license to dominate API-first infrastructure provision. Mambu sustains technology leadership through cloud-native core banking architecture. Deutsche Bank anchors institutional credibility by extending compliance-heavy services to embedded finance partners.
Banking As a Service denotes the delivery of licensed banking products through third-party APIs, enabling non-bank entities to embed accounts, payments, and lending into their own customer interfaces. The model operates on RESTful API protocols with OAuth authentication, permitting real-time balance queries and transaction initiation. Payment Processing services lead current revenue pools as merchants seek instant settlement rails. Embedded Banking integration levels are capturing the fastest expansion as automotive and retail platforms embed lending at point-of-sale. API-First deployment remains the mature baseline, though Platform-Based solutions are consolidating margin through bundled compliance and fraud modules.
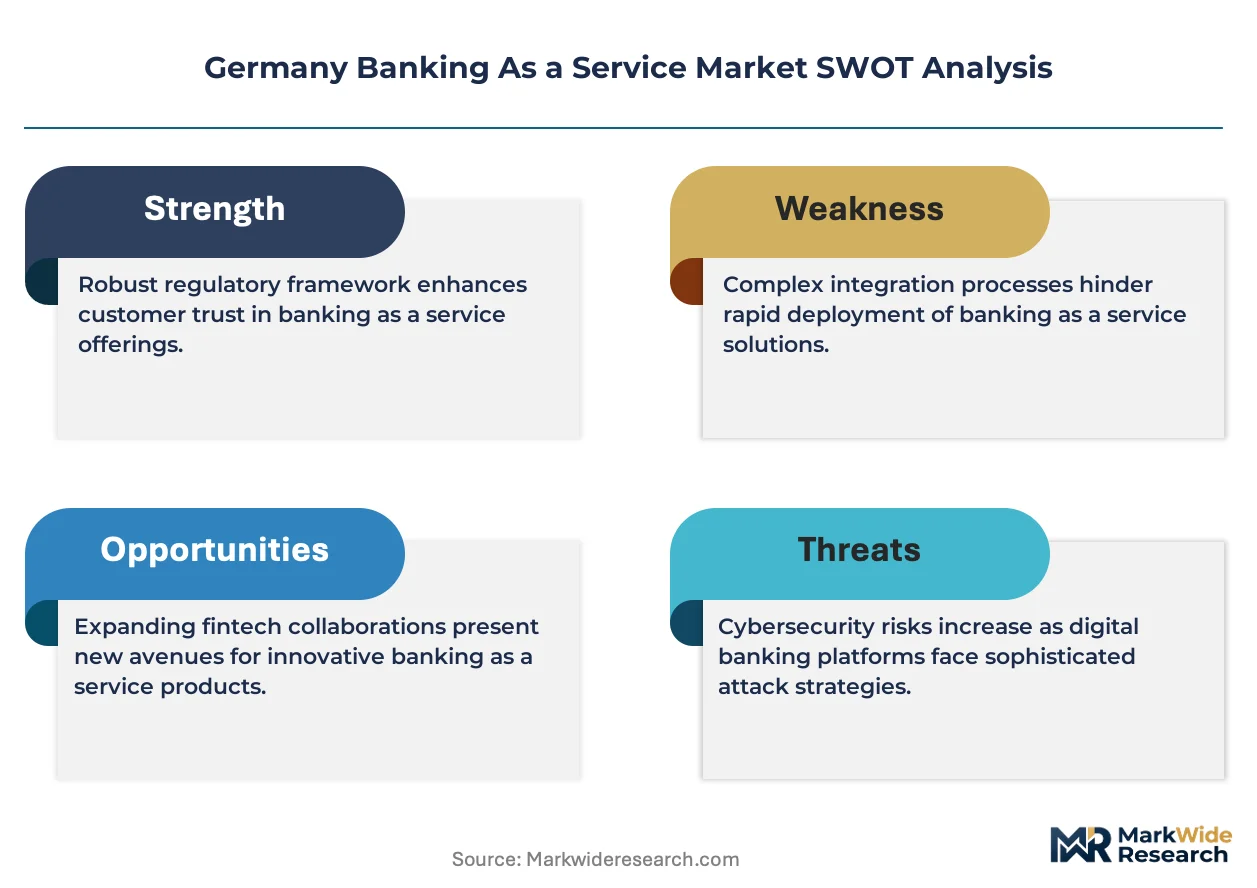
BaFin supervises licensing and outsourcing arrangements under the German Banking Act, while PSD2 and the forthcoming PSD3 framework mandate open API standards and strong customer authentication. The German Federal Financial Supervisory Authority's scrutiny of cloud concentration risk is forcing providers to diversify infrastructure across domestic data centers. Stakeholders must monitor how BaFin's pending guidance on embedded deposit-taking reshapes liability allocation between platform operators and licensed banks.
Market Dynamics
Embedded finance integration by German automotive and retail platforms is compressing traditional banking distribution channels, forcing licensed institutions to reposition as invisible infrastructure providers rather than customer-facing brands.
Growth Catalysts
- PSD2 Strong Customer Authentication:Regulatory mandates for open API standards have normalized third-party access to account data, reducing friction for non-bank platforms seeking banking partnerships.
- Cloud-native core banking migration:German fintechs and incumbent IT divisions are rebuilding on microservices architecture, cutting deployment cycles from months to days for new financial products.
- Point-of-sale lending demand:Automotive OEMs and electronics retailers in Stuttgart and Munich are embedding installment credit at checkout, pulling banking services deeper into commerce workflows.
Market Restraints
- Cloud concentration risk:BaFin scrutiny of hyperscaler dependency is forcing providers to maintain redundant infrastructure across domestic data centers, raising operational overhead.
- Qualified personnel scarcity:Competition for API security engineers and regulatory compliance specialists in Berlin and Frankfurt corridors has compressed salary structures and extended hiring timelines.
- Deposit insurance liability ambiguity:Pending BaFin guidance on embedded deposit-taking has frozen product roadmaps for platforms uncertain where regulatory liability terminates.
Strategic Opportunities
- Baden-Württemberg manufacturing corridor:Industrial equipment leasing platforms serving Mittelstand exporters remain underserved by current BaaS providers focused on consumer retail.
- PSD3 readiness services:Compliance automation tools addressing forthcoming open finance scope expansion represent a preemptive service layer for platforms preparing 2025 implementation.
- Real-time payment infrastructure:TARGET Instant Payment Settlement integration enables new use cases in gig economy payroll and B2B supply chain finance previously blocked by settlement latency.
Industry Challenges
- Core banking system interoperability:Incumbent institutions running COBOL-based legacy stacks face multi-year transformation timelines to achieve API parity with cloud-native competitors.
- Fraud model calibration:Embedded finance transactions lack historical behavioral data, forcing providers to build risk scoring from sparse signals with elevated false-positive rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Banking As a Service Market |
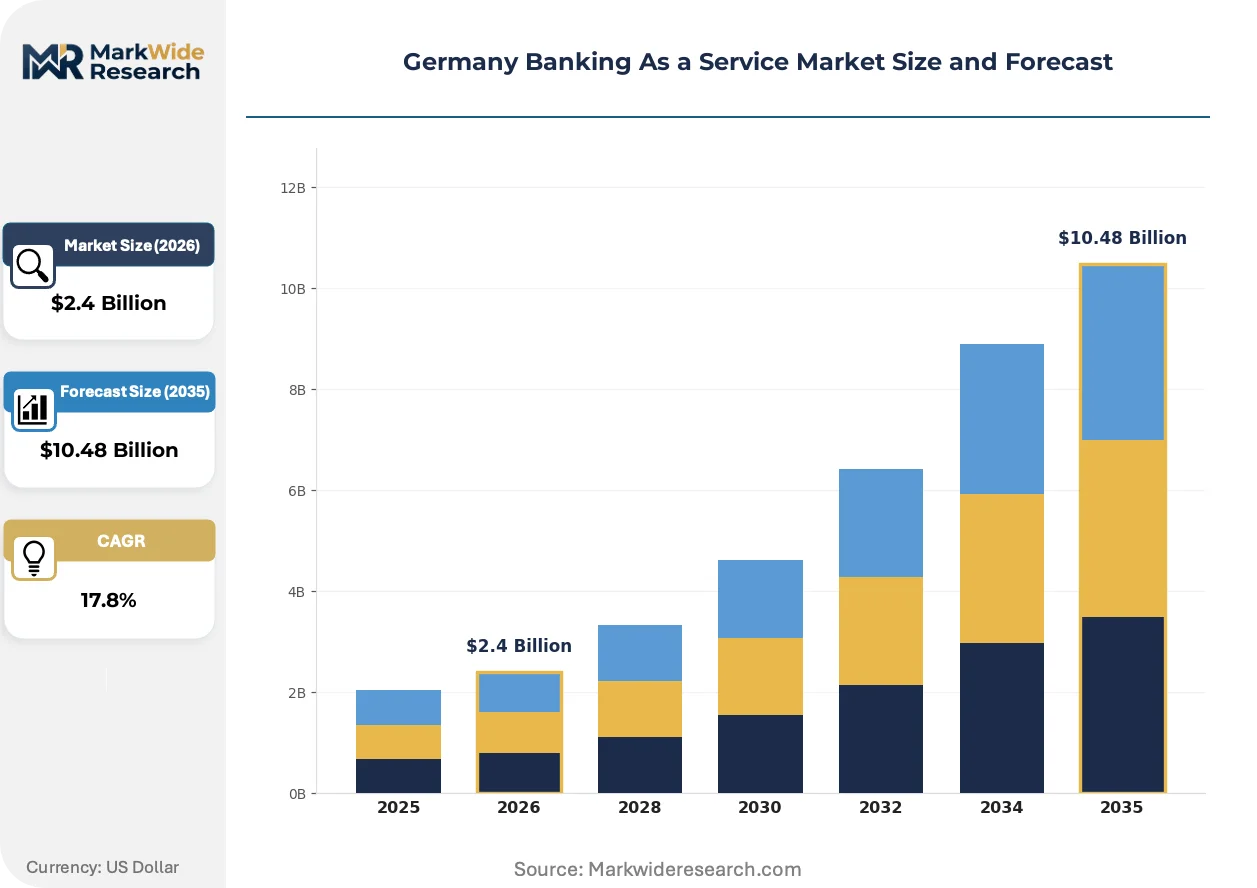
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $10.48 Billion |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Account Management, Payment Processing, Compliance Management, Fraud Detection, Loan Origination, Card Issuance Customer Type: FinTech Startups, Digital Wallet Providers, Online Retailers, Payment Gateways, Challenger Banks, Credit Unions Deployment Model: Private Cloud, Public Cloud, Hybrid Cloud, On-Premises Integration Level: API-First, Platform-Based, Embedded Banking, Modular Solutions |
| Companies Covered | Deutsche Bank, Commerz Bank, KFW Bankgruppe, DZ Bank, HypoVereinsbank, Solaris, Figo, Mambu, Bankable, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Banking As a Service Market Shifts & Advancements
Modular financial infrastructure is dismantling the traditional bank-customer relationship, replacing it with invisible banking woven into software platforms users already inhabit.
Composable banking architecture is fragmenting monolithic core systems into interoperable microservices. Tier-2 German banks and automotive captive finance units are adopting API-first stacks to launch white-label products without full license applications. This modularity is compressing vendor lock-in and enabling rapid feature swapping based on regulatory or competitive pressure.
BaFin's pending guidance on embedded deposit-taking is tightening liability frameworks. The regulator's scrutiny of platform-bank arrangements is forcing contractual restructuring that clarifies where consumer protection obligations reside. Fintech partnerships in Frankfurt's financial district are front-loading legal review to preempt enforcement action once rules finalize.
Merchant acquisition patterns are rotating toward vertical-specific BaaS providers. Agricultural equipment dealers in Lower Saxony and medical device distributors in Bavaria are selecting platforms with pre-built compliance for their regulatory environments rather than generic banking APIs. This specialization is fragmenting what had been a consolidated middleware market into sector-specific solution stacks.
Germany Banking As a Service Market Segmentation
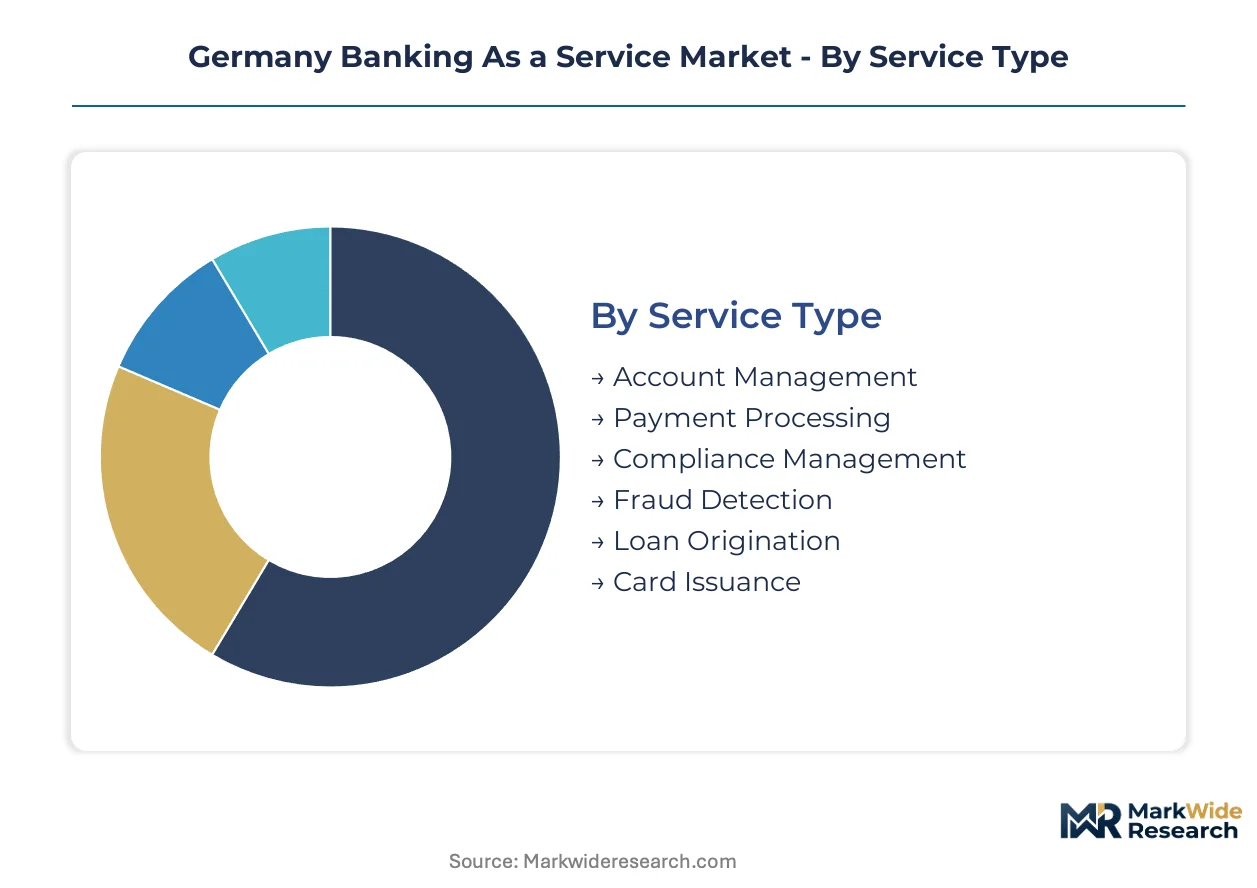
Segmentation reveals how BaFin's regulatory perimeter reshapes competitive boundaries across service tiers. Providers must calibrate offerings against distinct compliance burdens and infrastructure requirements that vary sharply by customer sophistication and deployment architecture.
Service Type:
Substitution pressure from embedded finance platforms is fragmenting traditional service bundles, with standalone offerings facing displacement from integrated stacks.
- Payment Processing:Real-time settlement rails leveraging TARGET Instant Payment Settlement infrastructure. Stuttgart automotive OEMs and Munich electronics retailers embed installment credit at checkout, compressing legacy acquiring margins.
- Account Management:White-label current accounts and savings products delivered through RESTful APIs with OAuth authentication. Berlin fintech corridors and Frankfurt's financial district concentrate demand as neobanks seek rapid license bypass.
- Compliance Management:Automated KYC/AML workflows addressing BaFin's evolving outsourcing scrutiny.
- Fraud Detection:Machine learning models calibrated for sparse behavioral signals in embedded transactions.
- Loan Origination:Point-of-sale credit APIs serving Baden-Württemberg manufacturing equipment distributors.
- Card Issuance:Virtual and physical card provisioning with SEPA-compliant BIN sponsorship.
Payment Processing anchors the volume base while Embedded Banking integration gains share at the steepest rate.
Customer Type:
Cost tier stratification separates lean API consumers from compliance-heavy institutional partnerships requiring dedicated infrastructure.
- Online Retailers:Mid-sized e-commerce platforms embedding accounts and lending at checkout. Lower Saxony agricultural equipment dealers and Bavarian medical device distributors drive vertical-specific customization demands.
- Challenger Banks:Neobanks leveraging full banking licenses from Solaris and others to bypass multi-year authorization timelines. Berlin and Frankfurt corridors face acute talent scarcity for API security engineering.
- FinTech Startups:Early-stage ventures prioritizing speed-to-market over regulatory depth.
- Digital Wallet Providers:Payment aggregators seeking SEPA instant credit transfer integration.
- Payment Gateways:Merchant acquirers adding banking services to core processing stacks.
- Credit Unions:Cooperative banks modernizing legacy cores through cloud-native partnerships.
Challenger Banks dominate current revenue concentration while Online Retailers expand most quickly as embedded finance penetrates commerce workflows.
Deployment Model:
Application criticality determines cloud posture, with BaFin's scrutiny of hyperscaler dependency forcing domestic redundancy investments.
- Public Cloud:Microservices architectures on AWS, Azure, and GCP enabling sub-day product deployment cycles. Frankfurt financial district providers front-load legal review to address BaFin's pending guidance on liability allocation.
- Hybrid Cloud:Sensitive transaction data retained on-premises with burst capacity to public infrastructure. Tier-2 German banks adopt this model to balance agility against regulatory conservatism.
- Private Cloud:Dedicated infrastructure for institutions with elevated data sovereignty requirements.
- On-Premises:COBOL legacy stacks facing multi-year transformation timelines to achieve API parity.
Public Cloud carries the steepest expansion trajectory while Hybrid Cloud captures growing share among mid-tier institutions navigating compliance complexity.
Integration Level:
Maturity gradients separate established API protocols from emerging platform consolidations bundling compliance and fraud modules.
- Embedded Banking:Full financial services woven into non-bank customer interfaces. Automotive OEMs in Stuttgart and retail platforms across Germany compress traditional distribution channels by embedding lending at point-of-sale.
- Platform-Based:Bundled infrastructure combining core banking, compliance automation, and fraud prevention. Vertical specialization fragments the middleware market into sector-specific stacks for agricultural and medical equipment finance.
- API-First:Modular RESTful endpoints enabling selective capability adoption.
- Modular Solutions:Componentized microservices permitting rapid feature swapping under regulatory pressure.
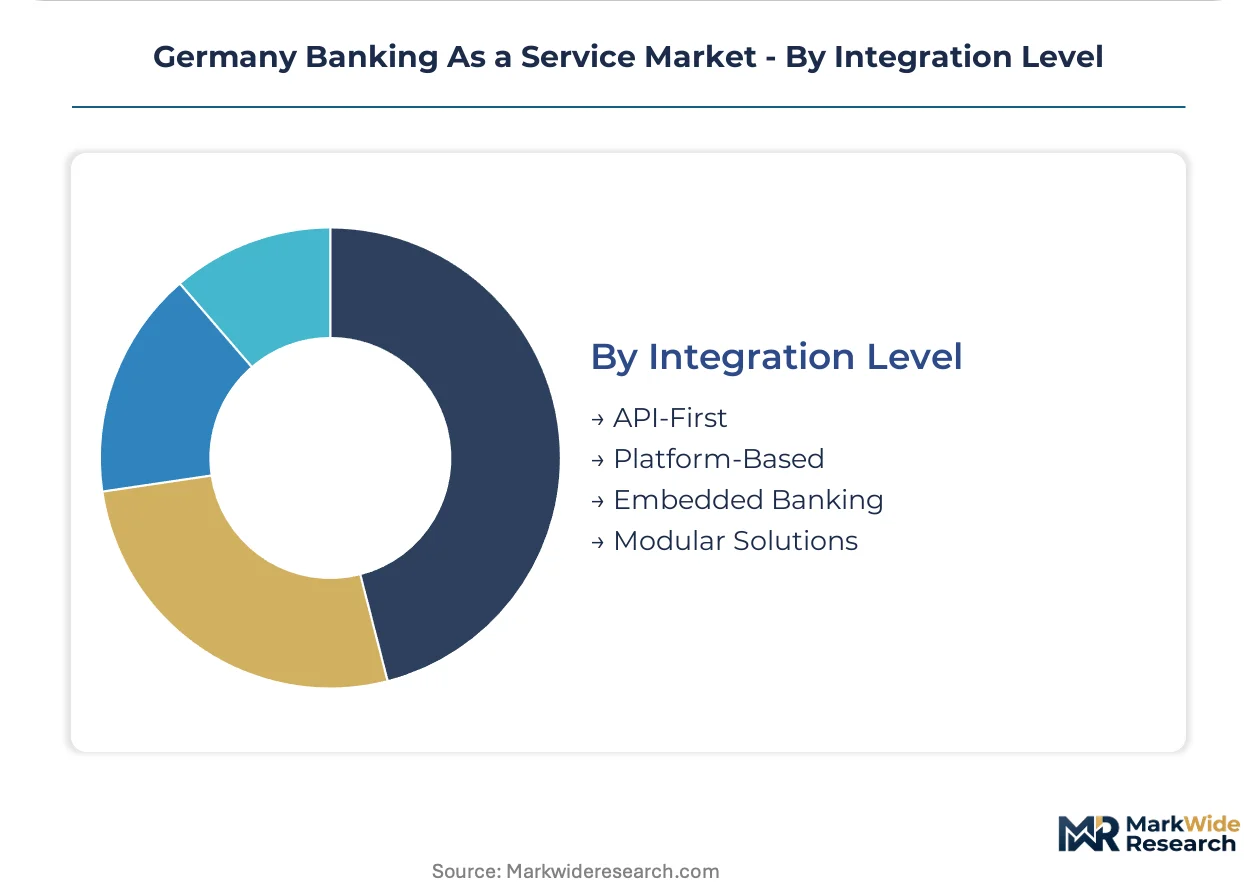
API-First integration retains the largest installed base while Embedded Banking climbs the fastest as invisible infrastructure displaces branded banking relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Rhine-Main metropolitan region anchors Germany's Banking As a Service infrastructure through TARGET2 real-time settlement connectivity and proximity to BaFin headquarters, concentrating API development and regulatory interpretation capacity in a single corridor.
Berlin-Brandenburg
Challenger banks and fintech startups cluster around Berlin's Kreuzberg and Mitte districts, drawn by venture capital density and co-working infrastructure. BaFin's Berlin office maintains secondary supervisory presence here, streamlining licensing consultations for neobank applicants. Embedded finance developers in Potsdam's software parks build white-label lending modules for e-commerce platforms.
Bavaria
Munich's automotive OEMs and electronics retailers drive point-of-sale lending demand, embedding installment credit at checkout through BaaS partnerships. The Bavarian Ministry of Economic Affairs funds fintech incubators through Bayern Innovativ programs. Nuremberg's payment processors specialize in SEPA instant credit transfer integration for merchant acquirers.
Baden-Württemberg
Stuttgart's Mittelstand equipment manufacturers seek BaaS platforms for industrial leasing workflows, a segment underserved by consumer-focused providers. The state's Ministry of Finance coordinates with BaFin on sandbox approvals for manufacturing finance pilots. Karlsruhe's IT security firms supply fraud detection algorithms to embedded banking platforms.
North Rhine-Westphalia
Cologne and Düsseldorf host legacy bank IT divisions modernizing through cloud-native partnerships, balancing agility against regulatory conservatism. The NRW.BANK development agency channels state guarantees into fintech lending ventures. Dortmund's logistics platforms embed freight payment APIs through BaaS integrations.
Hesse
Frankfurt's financial district concentrates full banking license holders extending compliance-heavy services to embedded finance partners. The Deutsche Bundesbank headquarters provides liquidity infrastructure and regulatory signaling. Wiesbaden's insurance groups experiment with embedded banking for policy premium financing.
Germany Banking As a Service Market Competitive Landscape
Listed leaders compete with private specialists across licensing depth and API granularity, creating a tiered structure where full banking license holders anchor institutional credibility while cloud-native platforms capture speed-to-market advantages. Tier-1 incumbents leverage balance sheet scale for deposit-taking partnerships. Tier-2 fintechs specialize in vertical-specific compliance modules. Tier-3 infrastructure vendors supply microservices architecture. Dominant competitive moves include strategic partnerships between license holders and technology platforms, plus geographic expansion into underserved manufacturing corridors.
Within the full-license archetype, Deutsche Bank and Commerz Bank occupy positions as institutional anchors extending regulatory infrastructure to embedded finance partners. Among cloud-native specialists, Solaris and Mambu exemplify the API-first model that compresses product deployment cycles. These named entities represent distinct strategic postures—incumbent credibility versus technical agility—without implying specific market share or performance metrics.
| Leading Market Players |
|---|
| Deutsche Bank |
| Commerz Bank |
| KFW Bankgruppe |
| DZ Bank |
| HypoVereinsbank |
| Solaris |
| Figo |
| Mambu |
| Bankable |
| Others |
Supply & Pricing Matrix
Forty-five-day API provisioning cycles for white-label banking infrastructure concentrate pricing power with full-license holders in Frankfurt, while BaFin's pending deposit-taking guidance extends procurement timelines and compresses margin flexibility across embedded finance tiers.
Pricing Analysis
Volume-discount tiering structures separate enterprise API consumers committing to multi-year contracts from pay-per-transaction startups. Pricing stratifies across premium compliance-bundled, standard modular, and economy self-service tiers based on regulatory depth and integration complexity. Cost compression in the economy tier intensifies as cloud-native challengers undercut legacy license holders on deployment speed. Challenger banks exhibit lowest price sensitivity given regulatory bypass value, while mid-sized online retailers drive hardest bargain on per-transaction rates.
Supply Chain Analysis
Inventory lead-times for banking-grade API infrastructure stretch across German domestic data centers, Irish AWS regions, and Dutch Azure availability zones under BaFin's cloud concentration scrutiny. Core banking microservices draw from container orchestration platforms, identity verification APIs, and SEPA-compliant payment rails. Single-source vulnerability concentrates in hyperscaler identity management layers. Distribution runs through direct enterprise sales teams for institutional clients and self-service developer portals for fintech adopters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's Banking As a Service market functions as a service-attach opportunity where recurring compliance automation revenue expands faster than standalone API licensing as platforms bundle fraud and KYC modules.
For Market Incumbents: Compound defensive positioning through exclusive deposit-taking partnerships with automotive OEMs embedding lending at Stuttgart and Munich point-of-sale, while accelerating COBOL-to-microservices migration to neutralize cloud-native speed advantages. Lock in multi-year infrastructure contracts before PSD3 implementation raises compliance automation switching costs. For New Entrants and Emerging Players: Differentiate on vertical-specific compliance pre-configuration for Baden-Württemberg manufacturing equipment leasing, a segment underserved by consumer-focused incumbents. Target agricultural equipment dealers in Lower Saxony and medical device distributors in Bavaria with pre-built regulatory modules. Pursue partnership-first go-to-market through Bayern Innovativ incubator networks rather than direct enterprise sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid cloud deployments as BaFin's domestic redundancy requirements force redundant infrastructure investment. Long-term viability favors platforms with existing full banking licenses and established BaFin relationships over pure-technology plays. Monitor Solaris and Mambu partnership expansion velocity as inflection signal for license-holder consolidation appetite.| Strategic Initiative | Industry Significance |
|---|---|
| PSD3 Compliance Automation Buildout | Bundled KYC/AML modules preempt regulatory expansion and capture switching costs across embedded finance platforms. |
| Vertical Manufacturing Finance Partnership | Stuttgart Mittelstand equipment leasing partnerships unlock white-space in industrial BaaS underserved by retail-focused providers. |
| Hybrid Cloud Infrastructure Diversification | Domestic data center redundancy addresses BaFin scrutiny while preserving burst capacity for transaction spikes. |
| Real-Time Payment Rail Integration | TARGET Instant Payment Settlement connectivity enables gig economy payroll and supply chain finance use cases. |
| API Security Engineering Talent Acquisition | Berlin and Frankfurt corridor recruitment compresses competitor deployment timelines and builds regulatory interpretation depth. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with API product managers, BaFin regulatory affairs specialists, neobank CTOs, and embedded finance platform engineers; and secondary validation through ECB payment statistics, BaFin outsourcing circulars, PSD2/PSD3 regulatory texts, and Bundesbank infrastructure disclosures. Bottom-up triangulation across service-type deployment volumes and top-down reconciliation against TARGET2 settlement flow aggregates anchored value estimates.
Across the projection horizon, the analytical framework modeled service type segmentation, customer tier stratification, deployment architecture migration patterns, and integration level maturity gradients. CAGRs derived from historical API adoption velocity, regulatory implementation timelines, and embedded finance penetration rates across automotive and retail verticals. Cloud migration curves and real-time payment infrastructure buildout served as industry-specific demand drivers.
Material uncertainties — BaFin's pending embedded deposit-taking guidance, PSD3 scope finalization, and hyperscaler concentration enforcement intensity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory timeline stability and challenger bank license application approval rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Banking Wearable Devices Market
Banking
Internet of Things (IoT) in Banking Market
Banking
Bank Kiosk Market
Banking
AI and Automation in Banking Market
Banking
Onsite and Offsite Atms Market
Banking
Smart Banking Solutions Market
Banking
Global Banking Systems Software Market
Banking
Cloud-Based Core Banking Market
Banking
Russia Data Analytics in Banking Market
Banking
Credit Intermediation Market
Banking
Singapore Neobanking Market
Banking
North America Bank Kiosk Market
Banking
Singapore Data Analytics in Banking Market
Banking
Mobile Banking Market
Banking
Africa Data Analytics in Banking Market
Banking
Middle-East and Africa Banking-As-A-Service Market