
 China Data Analytics in Banking Market | 2026-2036
China Data Analytics in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
China Data Analytics in Banking Market Insights
China's state-owned banking technology infrastructure is repositioning around real-time data processing at scale. Industrial and Commercial Bank of China Ltd. leverages its domestic branch network to anchor proprietary analytics platforms across provincial operations. China Construction Bank Corp. competes through deep integration of machine learning into credit scoring workflows for small-enterprise lending. Shenzhen Sunline Tech Co. Ltd. specializes in core banking system overlays that connect legacy infrastructure to modern data pipelines.
Data analytics in banking encompasses the computational extraction, processing, and predictive modeling of structured and unstructured financial data to optimize decision velocity across credit, operations, and compliance functions. Systems typically operate on sub-second latency thresholds for transactional scoring and integrate streaming data architectures with historical warehouse layers. Fraud Detection applications dominate current deployment value as banks absorb rising synthetic-identity losses, while Cloud Computing infrastructure expands fastest among technology segments as MIIT cloud security certifications ease institutional adoption barriers. Commercial Banks command the largest end-user share given their balance-sheet scale, though Online Lenders represent the most dynamic demand segment through algorithmic underwriting models.
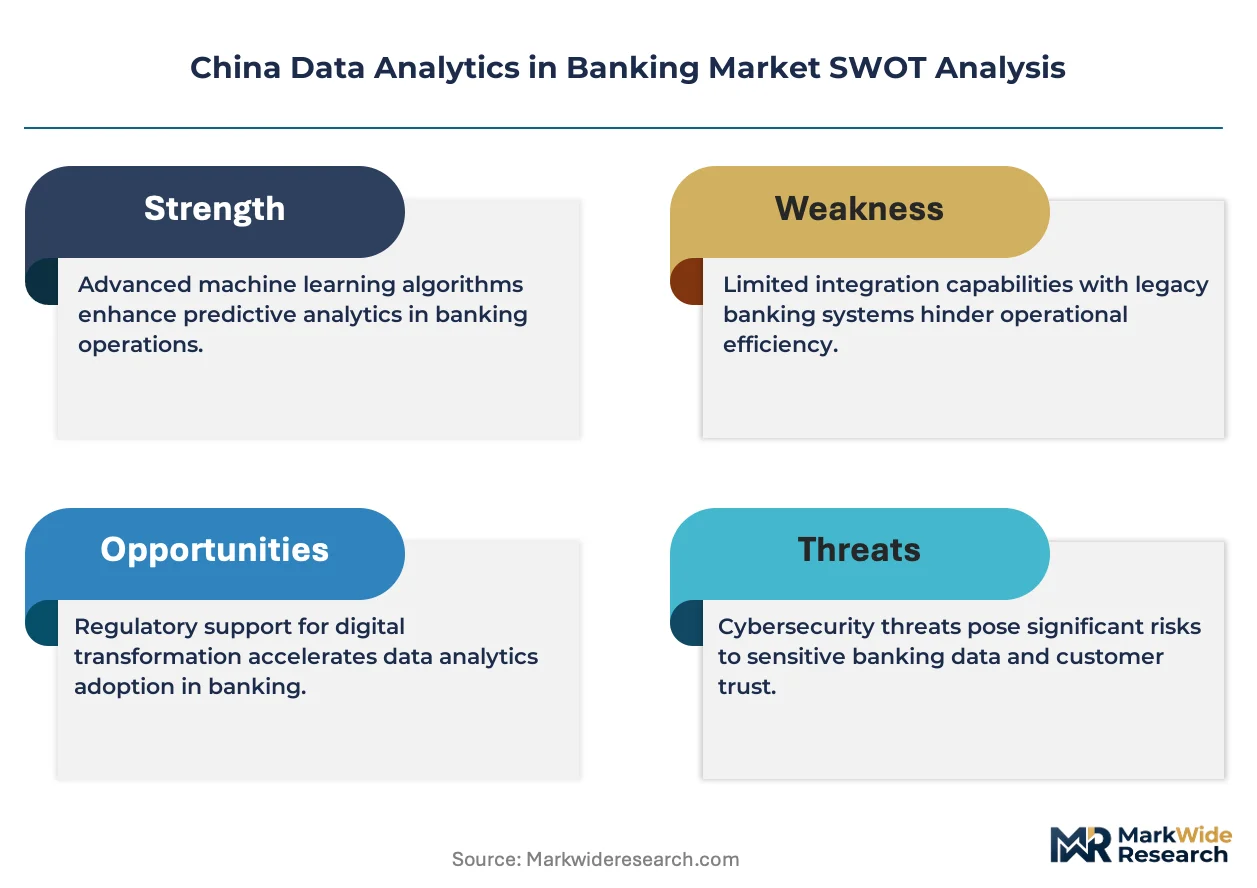
SAMR enforces algorithmic recommendation transparency rules that directly shape how banks deploy customer-facing predictive models. GB standards for financial data security, supplemented by NMPA-aligned privacy protocols for cross-sector data fusion, constrain vendor system architectures and elevate compliance-module procurement. Stakeholders must weigh the pace of MIIT cloud certification expansion against the capital requirements of on-premise hybrid deployments as regulatory clarity evolves.
Market Dynamics
MIIT cloud security certifications are compressing migration timelines for state-owned commercial banks, forcing infrastructure decisions before full regulatory clarity emerges on cross-border data flows. This certification pressure is restructuring vendor procurement patterns and accelerating domestic cloud provider consolidation.
Growth Catalysts
- Dual carbon goals:Energy efficiency mandates are driving banks to replace on-premise data centers with certified cloud infrastructure, creating procurement urgency for MIIT-compliant platforms.
- Real-time risk analytics:Commercial banks in Shanghai and Beijing are deploying streaming data architectures to compress fraud detection latency from minutes to sub-second thresholds.
- Synthetic-identity fraud:Rising losses in digital lending channels are forcing algorithmic underwriting investments among online lenders seeking predictive model upgrades.
Market Restraints
- GB standards compliance costs:Financial data security certifications require multi-year capital commitments that constrain mid-tier joint-stock banks.
- Cross-border data restrictions:NMPA-aligned privacy protocols fragment data lake architectures when banks fuse healthcare or insurance datasets.
- Legacy core system debt:Provincial branch networks operate on decades-old infrastructure that resists API-based analytics integration without complete replacement.
Strategic Opportunities
- Western province expansion:Sichuan and Shaanxi banking markets show underpenetrated demand for cloud-native analytics platforms among city commercial banks.
- Small-enterprise credit scoring:Machine learning integration into agricultural and manufacturing lending workflows remains nascent outside tier-one banks.
- SAMR algorithmic transparency:Recommendation engine disclosure rules create compliance-module procurement opportunities for explainable AI vendors.
Industry Challenges
- Streaming architecture talent scarcity:Banks compete with technology firms for engineers capable of sub-second latency system design.
- Hybrid deployment complexity:On-premise historical warehouses must synchronize with cloud streaming layers without disrupting core banking operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Data Analytics in Banking Market |
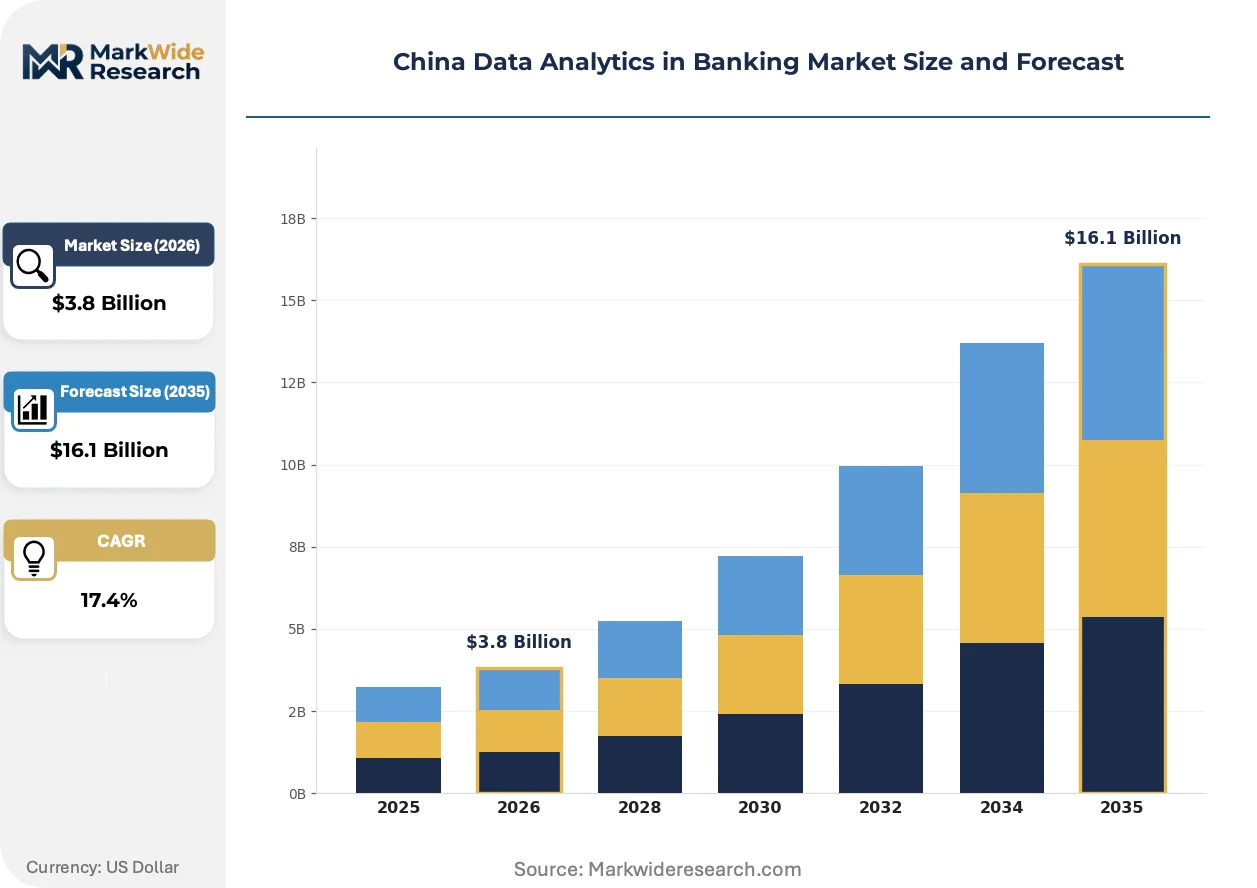
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.1 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Risk Management, Customer Insights, Regulatory Compliance Technology: Machine Learning, Big Data, Cloud Computing, Data Visualization End User: Commercial Banks, Investment Banks, Credit Unions, Online Lenders Deployment: On-Premise, Cloud-Based, Hybrid, API Integration |
| Companies Covered | Industrial and Commercial Bank of China Ltd., China Construction Bank Corp., Agricultural Bank of China Ltd., Bank of China Ltd., Shenzhen Sunline Tech Co. Ltd., Temenos AG, Oracle Corporation, SAP SE, Tata Consultancy Services Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Data Analytics in Banking Market Trends and Innovations
Banking technology infrastructure is bifurcating between real-time streaming architectures and static batch systems, with regulatory pressure forcing convergence timelines that outpace organizational readiness. This tension is compressing vendor consolidation and reshaping procurement evaluation criteria.
Stream processing engines built on Apache Flink and Kafka-native architectures are overtaking traditional ETL pipelines for transactional scoring workflows. State-owned commercial banks in Beijing are deploying these systems across provincial branch networks to enable continuous credit risk recalculation. The shift is overtaking legacy overnight batch processing windows and collapsing decision latency from hours to milliseconds.
SAMR algorithmic recommendation transparency rules are mandating interpretability layers for customer-facing predictive models. Banks must now document feature importance and decision boundaries for credit and product recommendation engines. Online lenders with algorithmic underwriting models face the steepest compliance retrofit costs as they rebuild black-box systems into auditable architectures.
Consumption patterns among commercial banks are fragmenting between centralized procurement of enterprise analytics suites and departmental acquisition of specialized fraud detection modules. Shanghai-based banks are piloting unbundled procurement that separates infrastructure from application licensing. This pattern is most visible among joint-stock banks seeking to bypass vendor lock-in from core banking system overlays.
China Data Analytics in Banking Market Segmentation
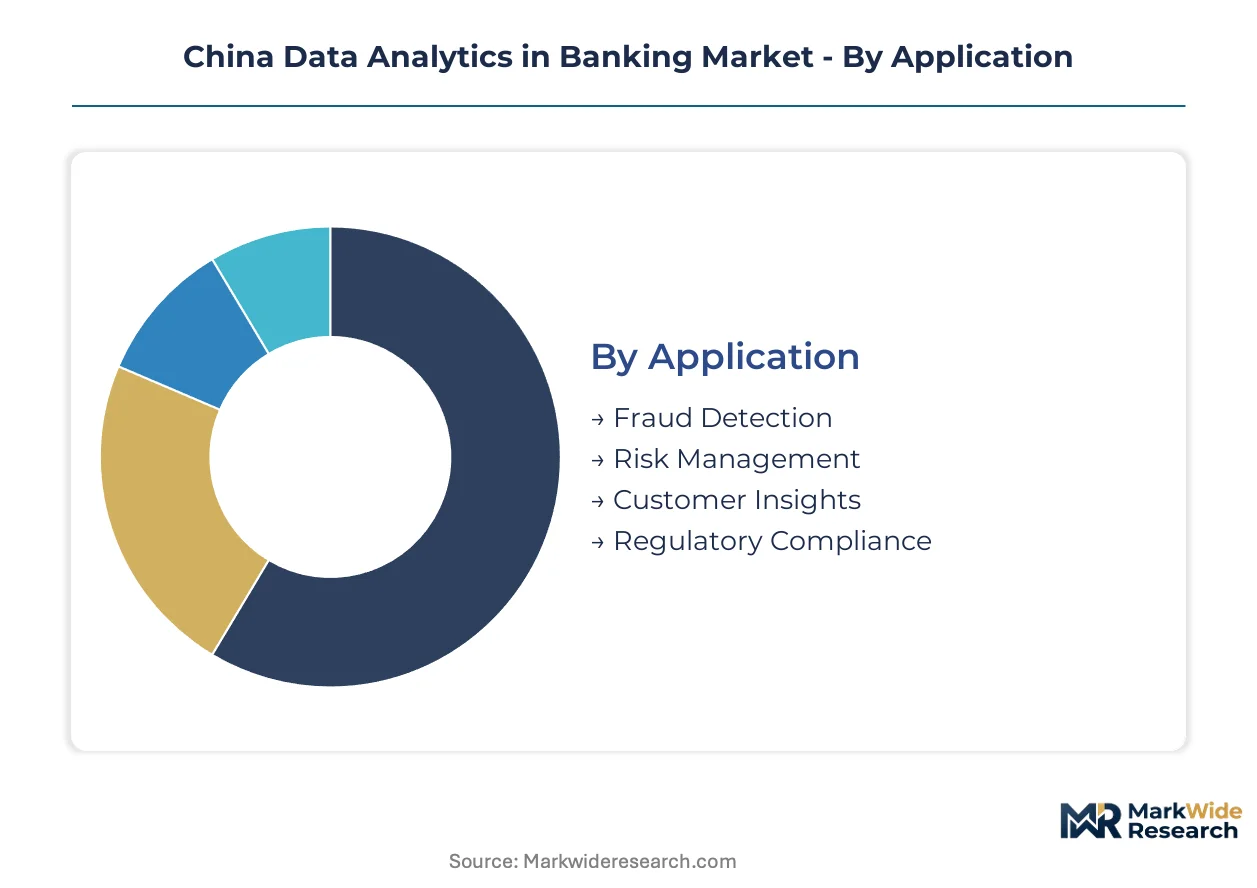
China's banking data analytics market fragments across four critical dimensions that shape procurement priorities and vendor positioning. Application use cases, underlying technology stacks, end-user institutional types, and deployment architectures each concentrate value differently across state-owned commercial banks and emerging digital lenders.
Application:
Supply concentration in fraud detection modules is restructuring vendor competition as synthetic-identity losses force algorithmic underwriting upgrades across Shanghai and Beijing banking networks.
- Fraud Detection:Systems operate on sub-second latency thresholds for transactional scoring, integrating streaming data architectures with real-time pattern recognition. State-owned commercial banks in tier-one cities absorb the majority of deployment value as synthetic-identity fraud in digital lending channels accelerates procurement urgency for predictive model upgrades.
- Risk Management:Continuous credit risk recalculation engines built on Apache Flink architectures compress decision latency from overnight batch windows to milliseconds. Demand concentrates among joint-stock banks modernizing provincial branch networks to enable real-time exposure monitoring across agricultural and manufacturing lending portfolios.
- Customer Insights:SAMR-mandated algorithmic transparency rules require interpretability layers for recommendation engines, elevating explainable AI procurement for product cross-selling workflows.
- Regulatory Compliance:GB standards for financial data security and MIIT cloud certification requirements drive modular procurement of audit-trail and data-governance functionalities.
Fraud Detection absorbs the bulk of installed capacity; Cloud Computing infrastructure is expanding most quickly among technology investments.
Technology:
Cost tier differentiation separates enterprise-grade streaming platforms from departmental visualization tools, with MIIT certification requirements elevating procurement budgets for cloud-native architectures.
- Cloud Computing:MIIT cloud security certifications are compressing migration timelines for state-owned commercial banks, forcing infrastructure decisions before full regulatory clarity emerges on cross-border data flows. Dual carbon goals drive replacement of on-premise data centers with certified platforms, creating procurement urgency among Beijing and Shanghai banking networks.
- Machine Learning:Credit scoring workflows for small-enterprise lending integrate deep neural networks with interpretability overlays to satisfy SAMR algorithmic transparency mandates. Online lenders face steepest compliance retrofit costs as they rebuild black-box underwriting systems into auditable architectures.
- Big Data:Historical warehouse layers must synchronize with streaming architectures without disrupting core banking operations, creating hybrid deployment complexity for provincial branch networks.
- Data Visualization:Departmental acquisition of specialized modules fragments procurement patterns among joint-stock banks seeking to bypass vendor lock-in from core banking system overlays.
Cloud Computing commands the steepest investment trajectory; Data Visualization represents the most fragmented procurement pattern.
End User:
Volume concentration among commercial banks with trillion-yuan balance sheets is displacing mid-tier procurement patterns as state-owned institutions consolidate vendor relationships around proprietary analytics platforms.
- Commercial Banks:ICBC leverages its domestic branch network to anchor proprietary analytics platforms across provincial operations, while China Construction Bank competes through deep machine learning integration into credit scoring workflows. Balance-sheet scale enables centralized procurement of enterprise analytics suites with multi-year capital commitments.
- Online Lenders:Algorithmic underwriting models represent the most dynamic demand segment, with synthetic-identity fraud losses forcing continuous predictive model upgrades. Shenzhen-based digital lenders pilot unbundled procurement separating infrastructure from application licensing.
- Investment Banks:Cross-border data restrictions fragment data lake architectures when fusing healthcare or insurance datasets for structured product development.
- Credit Unions:Legacy core system debt constrains API-based analytics integration without complete replacement of decades-old provincial infrastructure.
Commercial Banks absorb the bulk of installed capacity; Online Lenders are gaining share fastest among end-user categories.
Deployment:
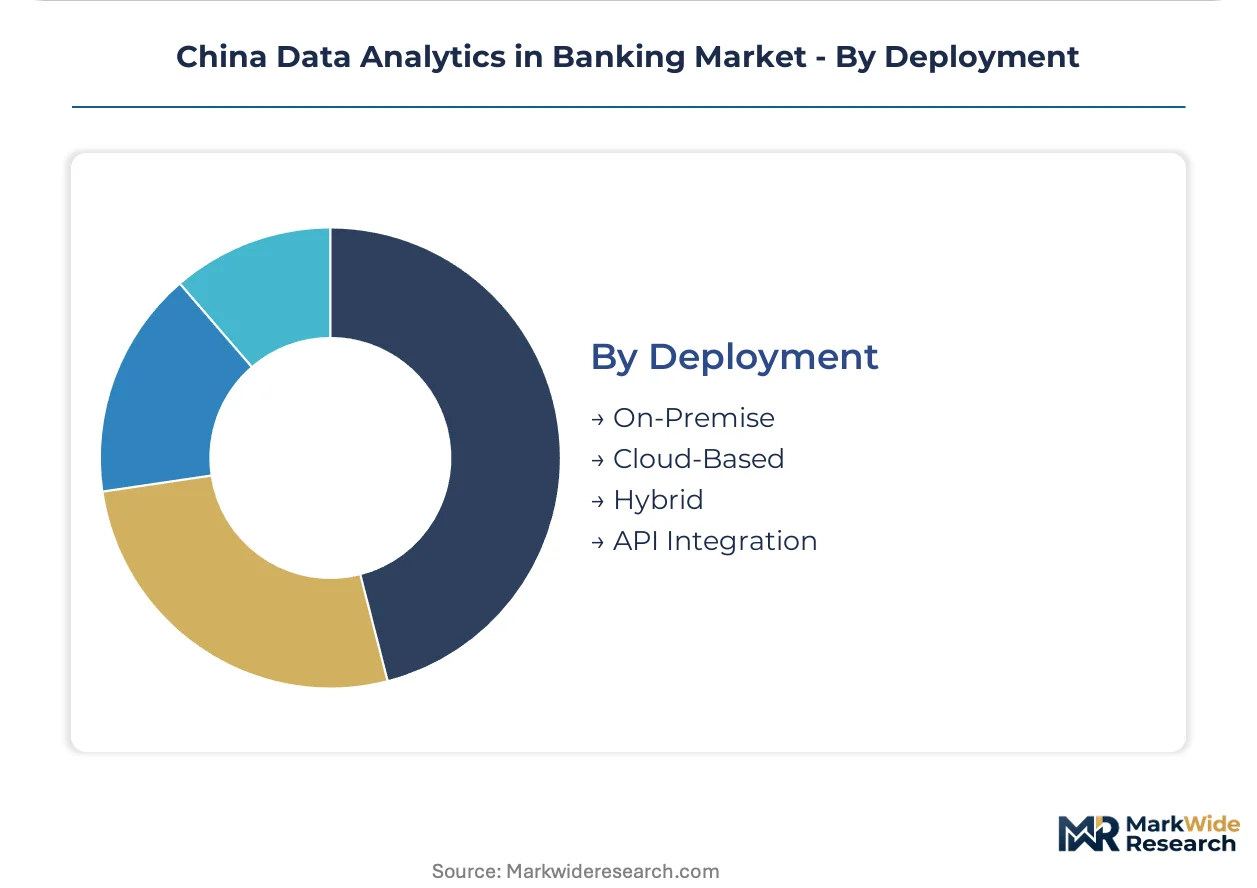
Customer type segmentation separates centralized state-owned bank procurement from distributed online lender architectures, with hybrid deployments dominating transitional migration strategies.
- Hybrid:On-premise historical warehouses synchronize with cloud streaming layers to maintain core banking continuity during MIIT certification timelines. State-owned commercial banks in Beijing deploy these architectures across provincial networks to bridge legacy infrastructure with modern data pipelines.
- Cloud-Based:MIIT-compliant platforms enable real-time risk analytics deployment without capital-intensive data center construction, appealing to joint-stock banks with constrained technology budgets.
- On-Premise:GB standards compliance costs and multi-year capital commitments favor institutions with established data center footprints in tier-one cities.
- API Integration:Core banking system overlays connect legacy infrastructure to modern data pipelines, with Shenzhen Sunline Tech specializing in middleware procurement for provincial branch networks.
Hybrid deployments absorb the bulk of installed capacity; Cloud-Based architectures are climbing the fastest as certification barriers ease.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beijing's concentration of state-owned bank headquarters and Shanghai's fintech infrastructure anchor domestic demand for real-time analytics platforms. Provincial branch networks in western provinces operate on legacy systems that resist rapid cloud migration despite MIIT certification pressure.
Beijing-Tianjin-Hebei
State-owned commercial banks headquartered in Beijing deploy streaming data architectures across provincial branch networks to enable continuous credit risk recalculation. MIIT cloud security certifications compress migration timelines for Industrial and Commercial Bank of China Ltd. and China Construction Bank Corp. The Beijing cluster absorbs the bulk of enterprise analytics suite procurement as dual carbon goals drive replacement of on-premise data centers.
Yangtze River Delta
Shanghai-based joint-stock banks pilot unbundled procurement patterns that separate infrastructure from application licensing to bypass vendor lock-in. SAMR algorithmic transparency mandates elevate explainable AI procurement for customer-facing predictive models in this region. The Shanghai fintech corridor hosts concentrated demand for fraud detection modules as synthetic-identity losses accelerate in digital lending channels.
Pearl River Delta
Shenzhen's online lenders represent the most dynamic demand segment for algorithmic underwriting model upgrades. GB standards for financial data security constrain mid-tier joint-stock banks with multi-year capital commitments that favor established data center footprints. Shenzhen Sunline Tech Co. Ltd. anchors middleware procurement for core banking system overlays connecting legacy infrastructure to modern data pipelines.
Sichuan-Chongqing
Western province banking markets show underpenetrated demand for cloud-native analytics platforms among city commercial banks. Provincial branch networks in Sichuan operate on decades-old infrastructure that resists API-based analytics integration without complete replacement. Chongqing's emerging fintech cluster attracts specialized vendors seeking expansion beyond saturated tier-one markets.
Shandong Peninsula
Agricultural and manufacturing lending workflows in Shandong remain nascent for machine learning integration outside tier-one bank networks. Local city commercial banks face GB standards compliance costs that constrain technology procurement relative to state-owned institutions. Qingdao's port finance infrastructure generates specialized demand for supply chain analytics modules.
China Data Analytics in Banking Market Competitive Landscape
Global majors compete with regional champions across cloud infrastructure and core banking integration layers. State-owned commercial banks consolidate vendor relationships around proprietary analytics platforms with multi-year capital commitments. Three archetypes dominate: domestic technology conglomerates with MIIT-certified cloud platforms, specialized core banking overlay vendors, and international enterprise software providers with localized compliance modules. Competitive dynamics center on strategic partnerships for hybrid deployment architectures and technology licensing for streaming data engines.
Within the state-owned banking tier, Industrial and Commercial Bank of China Ltd. and China Construction Bank Corp. exemplify institutions that anchor proprietary analytics platforms across provincial operations. Shenzhen Sunline Tech Co. Ltd. occupies a position among specialized vendors bridging legacy infrastructure to modern data pipelines. These three entities represent distinct competitive archetypes: balance-sheet-scale centralized procurement, machine learning-integrated credit scoring workflows, and middleware specialization for provincial branch networks.
| Leading Market Players |
|---|
| Industrial and Commercial Bank of China Ltd. |
| China Construction Bank Corp. |
| Agricultural Bank of China Ltd. |
| Bank of China Ltd. |
| Shenzhen Sunline Tech Co. Ltd. |
| Temenos AG |
| Oracle Corporation |
| SAP SE |
| Tata Consultancy Services Limited |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure spot pricing indices in Beijing and Shanghai cascade through banking technology procurement, compressing margins for vendors without MIIT certification while elevating premium tiers for compliant domestic platforms serving state-owned institutions.
Pricing Analysis
Warranty and service bundling separates enterprise analytics suites from unbundled procurement patterns gaining traction among joint-stock banks. Three-tier pricing structure across premium, standard, and economy levels reflects MIIT certification grade and deployment complexity, with premium tiers capturing multi-year capital commitments from ICBC and China Construction Bank. Cost compression in mid-tier offerings intensifies because domestic cloud providers compete aggressively for provincial branch network contracts. City commercial banks in western provinces exhibit highest price sensitivity, while Beijing-headquartered state-owned banks prioritize compliance over cost.
Supply Chain Analysis
Domestic-content mandates under MIIT cloud security certifications reshape sourcing toward certified domestic providers, displacing uncertified international infrastructure vendors from state-owned bank procurement. Hardware supply concentrates in China, Taiwan, and South Korea for server components and networking equipment. Apache Flink and Kafka-native streaming engines draw from open-source distributions and commercial support licenses. Single-source vulnerability around MIIT certification timelines creates procurement bottlenecks when banks cannot source compliant alternatives. Distribution runs through direct enterprise sales teams for large institutions and channel partners for mid-tier joint-stock banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around MIIT-certified domestic platforms as certification barriers force weaker international vendors without localized compliance modules to exit state-owned bank procurement channels.
For Market Incumbents: Extend proprietary analytics platform capabilities into western province branch networks before domestic challengers establish footholds. Deepen machine learning integration into agricultural lending workflows to defend against specialized fintech entrants. Acquire streaming architecture talent pools in Shenzhen and Beijing to counter technology firm competition for sub-second latency engineers. For New Entrants and Emerging Players: SAMR algorithmic transparency rules in China open a window for explainable AI specialists to capture compliance-module procurement from online lenders rebuilding black-box underwriting systems. Target Sichuan and Shaanxi city commercial banks with cloud-native analytics platforms priced below enterprise suite tiers. Pursue API-based core banking overlay partnerships with provincial institutions seeking modernization without complete infrastructure replacement. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized core banking middleware vendors with established MIIT certification pathways in the Pearl River Delta. Five-to-ten-year viability hinges on hybrid deployment expertise bridging legacy infrastructure to modern pipelines. Watch MIIT cloud certification expansion velocity as the inflection signal for domestic provider valuation multiples versus international software incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Cloud Certification Acquisition | Eliminates procurement barriers for state-owned commercial banks in Beijing and Shanghai. |
| Streaming Architecture Talent Acquisition | Secures engineering capacity for sub-second latency fraud detection systems. |
| Western Province Distribution Partnership | Unlocks underpenetrated demand among Sichuan and Shaanxi city commercial banks. |
| Explainable AI Module Development | Captures SAMR-mandated compliance procurement from algorithmic online lenders. |
| Legacy Core System Overlay Integration | Enables provincial branch modernization without complete infrastructure replacement. |
Research Methodology
Document review covered MIIT regulatory filings, SAMR algorithmic transparency guidelines, and GB standards documentation, complemented by interviews with chief technology officers at state-owned commercial banks, procurement directors at joint-stock banks, platform engineers at domestic cloud providers, and integration specialists at core banking overlay vendors. Secondary validation drew from MIIT certification databases, banking technology expenditure disclosures, and provincial branch network modernization announcements. Bottom-up vendor revenue estimates and top-down banking IT spending analysis were triangulated to establish market sizing.
Cross-referencing historical deployment patterns against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include application use case, underlying technology stack, end-user institutional type, and deployment architecture complexity. CAGRs were derived from regression analysis of certified cloud infrastructure adoption curves and real-time analytics deployment timelines. Forecast inputs incorporated dual carbon goal compliance deadlines and synthetic-identity fraud loss trajectories.
Caveats apply where MIIT cross-border data flow clarifications or GB standards enforcement intensity could materially shift the outlook for hybrid deployment architectures. Forecasts reflect assumptions around certification timeline adherence and provincial branch modernization funding continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Europe Machine Learning in Banking Market
Banking
North America Challenger Banks Market
Banking
Investment Banking and Trading Services Market
Banking
Latin America Banking As a Service Market
Banking
Asia-Pacific Data Analytics in Banking Market
Banking
Canada Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
Bank Guarantee Market
Banking
Global Big Data Analytics in Banking Market
Banking
Singapore Neobanking Market
Banking
Automated Teller Machine (ATM) Market
Banking
Armenia Banking Market
Banking
Smart ATM Market
Banking
US Investment Banking Market
Banking
Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
Asia-Pacific Machine Learning in Banking Market
Banking
Embedded Banking Market