
 In Vitro Fertilization Banking Services Market | 2026-2036
In Vitro Fertilization Banking Services Market Size, Share, and Industry Trends Forecast 2026-2036
In Vitro Fertilization Banking Services Market Outlook
Vitrification technology is reshaping how reproductive tissues are preserved and distributed across fertility networks. Fairfax Cryobank leverages extensive donor screening protocols to sustain quality leadership in sperm banking. Cryos International anchors European distribution through centralized cryogenic logistics. MyEggBank competes on scale by operating one of the largest frozen egg donor pools in North America.
In vitro fertilization banking services encompass the cryogenic preservation, inventory management, and distribution of gametes and embryos for assisted reproduction. Vitrification protocols using ultra-rapid cooling with cryoprotectants achieve survival rates exceeding 90% for oocytes, replacing slower controlled-rate freezing methods in premium service tiers. Egg donor services command the highest margins within service type segmentation due to donor recruitment costs and matching complexity. Fertility clinics dominate end-user demand as integrated sites that both produce and consume banked reproductive material. Subscription payment models are expanding fastest among individuals planning deferred parenthood, spreading upfront costs across annual cycles.
FDA donor screening regulations, EU Tissue and Cell Directives, and HIPAA privacy requirements collectively shape operational compliance costs and market access thresholds for banking operators. These frameworks mandate infectious disease testing, genetic screening documentation, and chain-of-custody tracking that directly influence laboratory infrastructure investment decisions. Stakeholders must monitor evolving state-level insurance mandates for fertility preservation coverage, as reimbursement expansion would fundamentally alter patient payment model preferences and clinic revenue mix.
Market Dynamics
Vitrification technology has compressed cryopreservation protocols from hours to minutes, forcing fertility clinics to retool laboratory infrastructure or lose competitive standing in donor gamete sourcing.
Growth Catalysts
- Delayed parenthood planning:Professional women in urban United States centers are banking oocytes at accelerating rates, creating recurring revenue streams through subscription storage models.
- FDA donor screening harmonization:Standardized infectious disease testing protocols reduce cross-jurisdictional compliance friction, enabling multi-state clinic networks to scale donor pools efficiently.
- Vitrification survival rates:Ultra-rapid cooling with cryoprotectants now achieves oocyte viability exceeding 90%, eliminating historical quality gaps that restricted market expansion.
Market Restraints
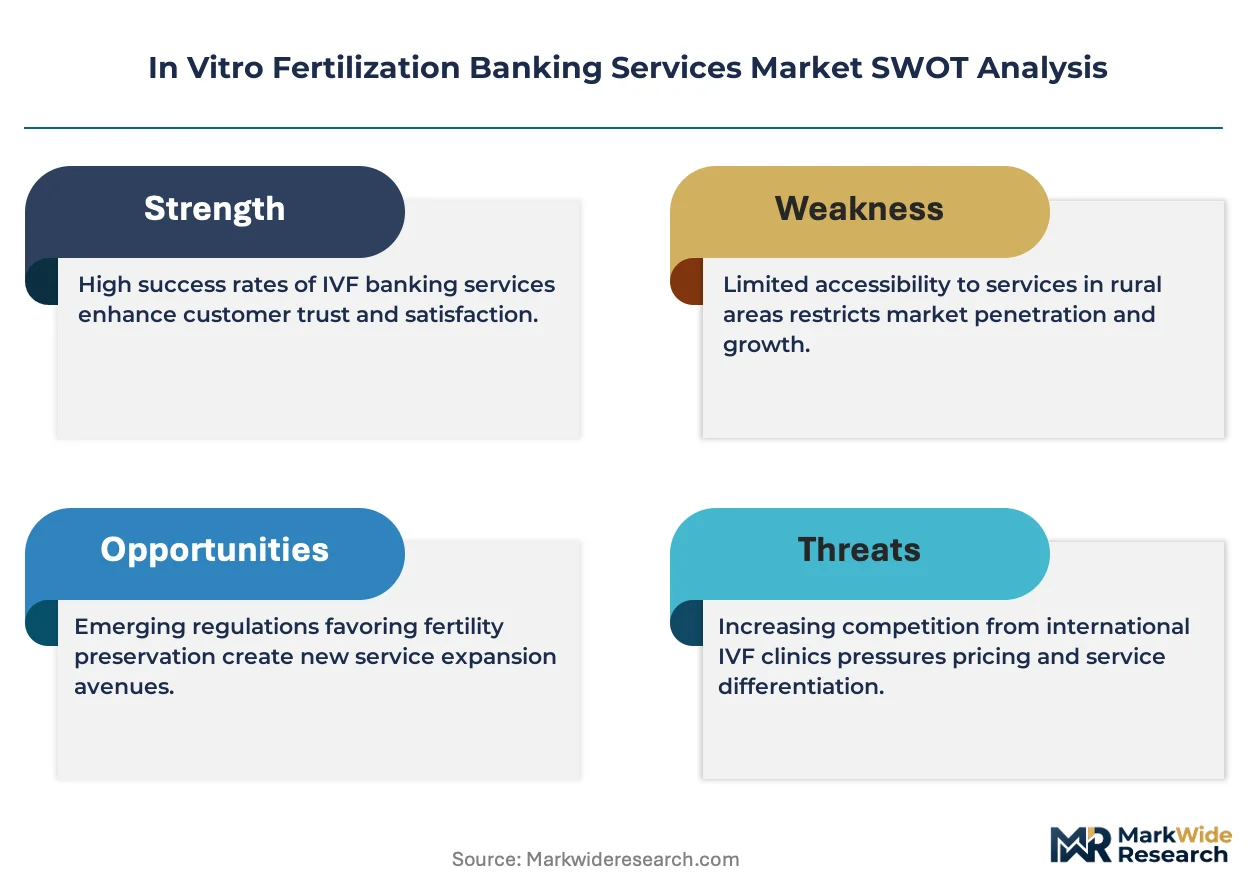
- Liquid nitrogen supply concentration:Cryogenic logistics depend on regional industrial gas suppliers, exposing banking operators to price volatility and delivery disruptions.
- EU Tissue Directive compliance costs:Member state traceability requirements mandate expensive chain-of-custody documentation systems that deter smaller clinic entrants.
- Embryo disposition legal uncertainty:Jurisdictional variation in storage duration limits and ownership rights creates liability exposure for long-term banking contracts.
Strategic Opportunities
- Oncofertility preservation mandates:State-level insurance coverage expansion for cancer patients creates guaranteed payment pools independent of elective fertility tourism.
- Same-sex family formation:Male couples in Canada and Spain are driving demand for gestational carrier-egg donor combinations that require coordinated multi-bank sourcing.
- AI-assisted donor matching:Phenotypic prediction algorithms are converging with genomic screening databases to reduce matching cycle failures and improve client retention.
Industry Challenges
- Embryologist training pipeline:Vitrification proficiency requires 12-18 month certification timelines that lag clinic expansion plans, constraining service scaling.
- HIPAA-compliant data architecture:Genetic screening databases must integrate with cryogenic inventory systems without creating breach vulnerabilities, complicating IT procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Vitro Fertilization Banking Services Market |
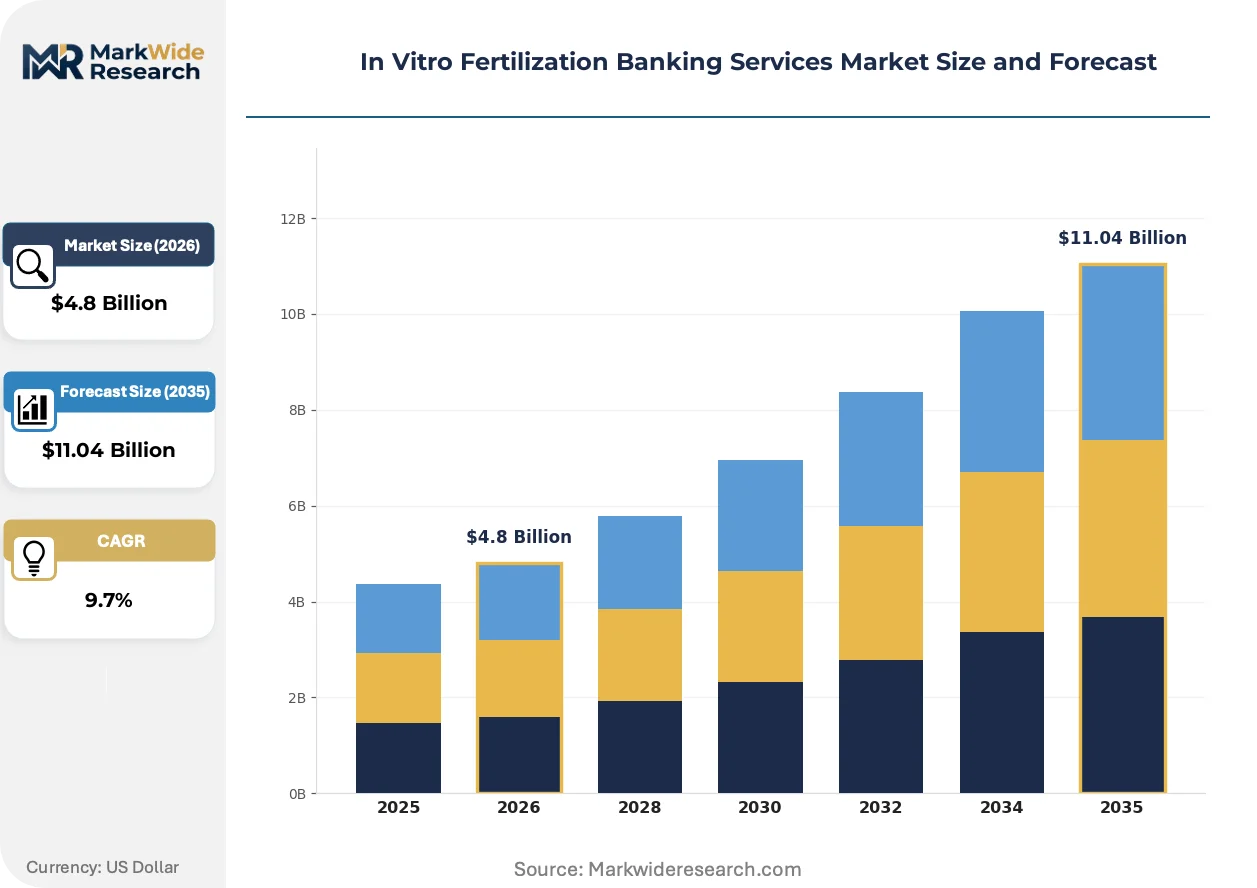
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Egg Freezing, Sperm Banking, Embryo Cryopreservation, Egg Donor Services End User: Fertility Clinics, Research Institutions, Hospitals, Individuals Technology: Vitrification, Controlled-Rate Freezing, Automatic Cryopreservation, Thawing Systems Payment Model: Subscription Plan, Pay-Per-Use, Package Deal, Insurance Covered |
| Companies Covered | The World Egg Bank, Fairfax Cryobank, MyEggBank, Cryos International, Seattle Sperm Bank, European Sperm Bank, California Cryobank, CCRM Fertility, Boston IVF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Vitro Fertilization Banking Services Market Strategic Shifts
Reproductive tissue banking is experiencing simultaneous pressure from automation, regulatory harmonization, and changing family formation patterns that collectively reshape competitive requirements for laboratory operators.
Artificial intelligence is digitizing donor phenotype prediction by analyzing facial morphology databases against client preference profiles. Fertility networks in California and New York are deploying these matching engines to reduce donor selection cycles from weeks to days. The compression is digitizing client acquisition economics by lowering consultation overhead and improving conversion rates for premium egg donor services.
EU Tissue and Cell Directives are mandating interoperable traceability standards across member state borders. Banking operators must now implement unified barcoding systems that satisfy both French ANSM documentation requirements and German federal tissue authority audits. Cryos International and centralized European distributors are consolidating logistics networks to amortize compliance infrastructure across higher volumes.
Subscription payment structures are displacing lump-sum storage fees among elective fertility preservation clients. Young professionals in Boston and San Francisco prefer annual billing cycles that spread cryogenic storage costs across income growth trajectories. This behavioral pivot is forcing clinic business development teams to redesign pricing architectures around lifetime value metrics rather than upfront margin capture.
In Vitro Fertilization Banking Services Market Segmentation
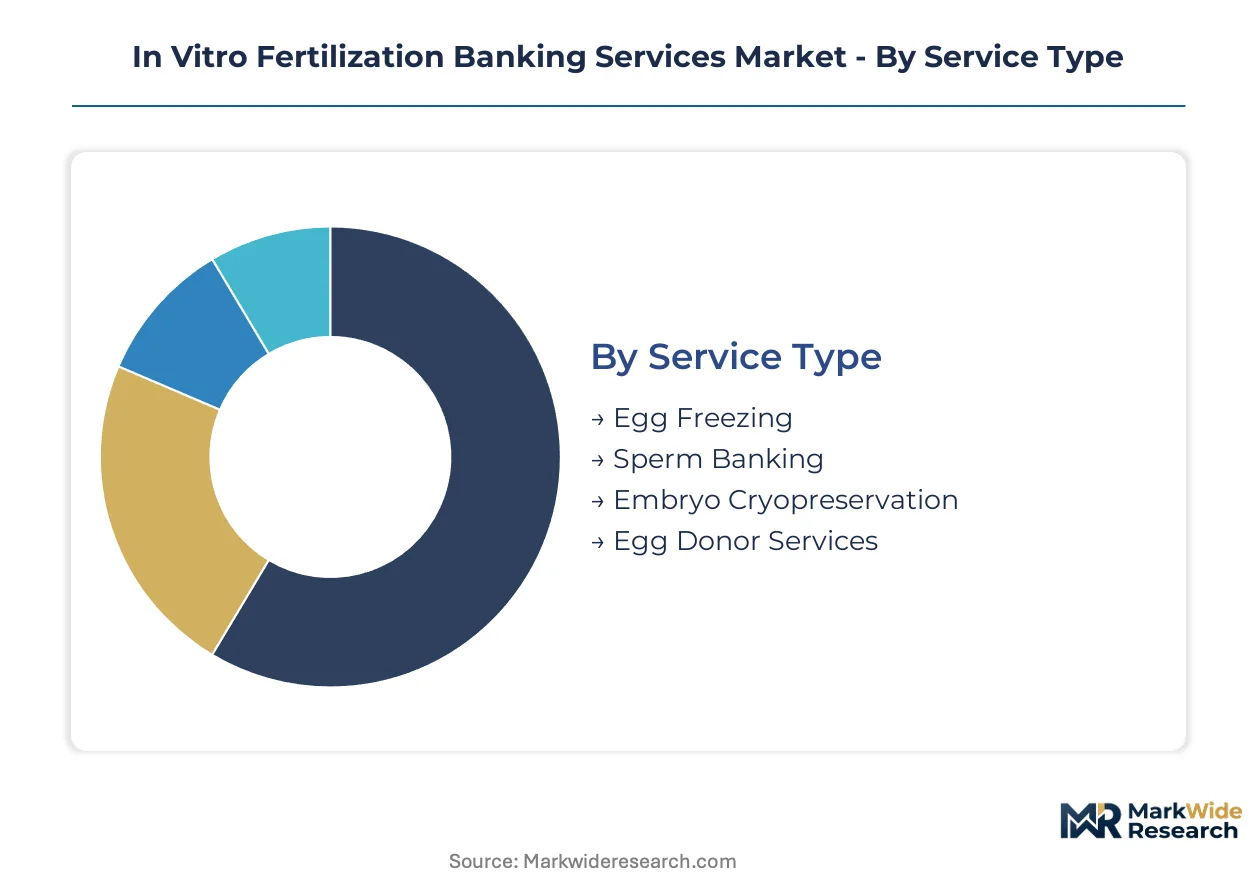
IVF banking services fragment across four distinct axes that determine operational intensity and revenue predictability. Service type and payment model together shape cash flow velocity, while end-user concentration and technology adoption dictate capital deployment priorities for laboratory operators.
Service Type:
Egg donor services turn inventory fastest with recurring matching cycles, while embryo cryopreservation locks capital into multi-year storage contracts with minimal turnover.
- Egg Donor Services:Recruitment, screening, and matching of third-party oocyte donors for intended parents. Demand concentrates in large networked fertility centers across the United States where commercial egg banks maintain extensive phenotypic databases. Donor compensation and genetic screening costs sustain premium pricing tiers that absorb compliance overhead.
- Egg Freezing:Elective oocyte cryopreservation for deferred parenthood planning, typically among professional women in urban United States centers. Boston and San Francisco fertility networks report accelerating subscription uptake as annual billing models displace lump-sum storage fees.
- Sperm Banking:Cryogenic preservation of donor and client-donated semen specimens with FDA-mandated infectious disease quarantine protocols. Fairfax Cryobank and Cryos International dominate distribution through centralized cryogenic logistics networks.
- Embryo Cryopreservation:Long-term storage of fertilized embryos with jurisdictional variation in storage duration limits creating legal exposure. Fertility clinics in Spain and Canada report extended holding periods for same-sex family formation cases requiring gestational carrier coordination.
Embryo cryopreservation dominates installed base. Egg donor services is where expansion concentrates.
End User:
Cost tier stratification separates integrated production-consumption sites from referral-dependent channels that pay premium markups for banked gametes.
- Fertility Clinics:Integrated sites that both produce and consume banked reproductive material through in-house laboratories. These operators capture margin across the full service chain from retrieval to transfer, justifying vitrification infrastructure investment.
- Individuals:Elective fertility preservation clients and intended parents sourcing donor gametes through direct-to-consumer channels. Subscription payment structures are displacing lump-sum fees among young professionals planning delayed parenthood.
- Hospitals:Academic medical centers with oncology-fertility preservation programs serving cancer patients prior to gonadotoxic therapy. State-level insurance mandates in the United States are expanding guaranteed payment pools for this segment.
- Research Institutions:Universities and biobanks utilizing cryopreserved gametes and embryos for reproductive biology studies. Demand tracks federal research funding cycles with lower price sensitivity than clinical applications.
Fertility clinics command the highest per-site revenue. Individuals is climbing the fastest as direct-to-consumer channels proliferate.
Technology:
Application-criticality separates survival-rate-dependent clinical services from auxiliary laboratory functions that support but do not determine treatment outcomes.
- Vitrification:Ultra-rapid cooling with cryoprotectants achieving oocyte survival rates exceeding 90%. This protocol has compressed processing from hours to minutes, forcing laboratory retooling across fertility networks in California and New York.
- Controlled-Rate Freezing:Slower temperature reduction protocols using programmable freezers with established but lower survival rates. Legacy installations persist in smaller clinics deferring capital replacement.
- Thawing Systems:Standardized warming protocols to minimize ice crystal formation during specimen retrieval. Equipment standardization is easing training pipeline constraints for embryologist certification.
- Automatic Cryopreservation:Robotic handling systems reducing human error in cryoprotectant exposure timing. Early adoption concentrates in high-volume banking operators amortizing automation investment across larger specimen inventories.
Controlled-rate freezing retains legacy installed base. Vitrification is gaining share fastest as survival rate advantages compound.
Payment Model:
Customer type and volume predictability distinguish recurring revenue streams from episodic transactions with higher acquisition costs.
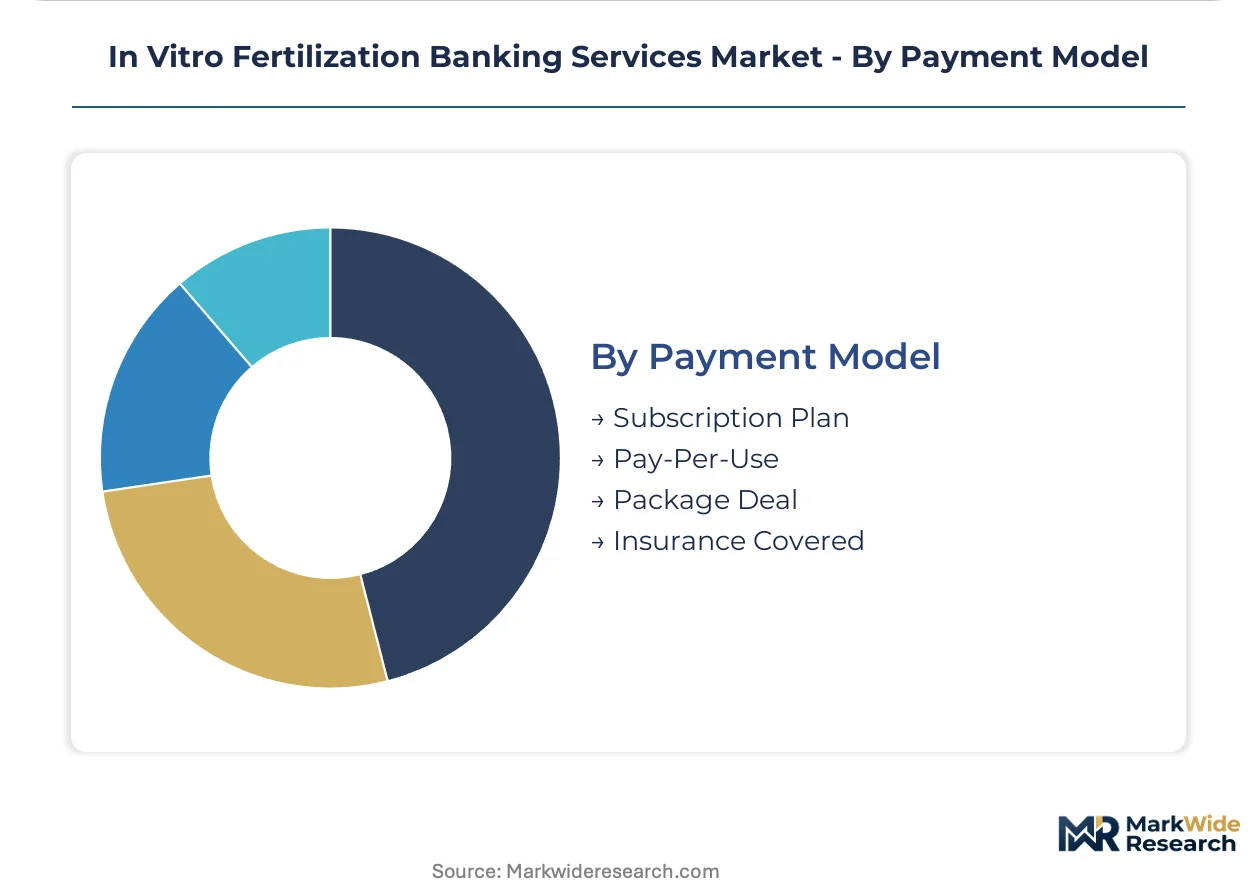
- Subscription Plan:Annual billing cycles spreading cryogenic storage costs across income growth trajectories. Fertility clinics in Boston and San Francisco redesigned pricing architectures around lifetime value metrics to capture this behavioral pivot.
- Insurance Covered:State-mandated fertility preservation benefits for cancer patients and certain elective indications. United States regulatory expansion into oncofertility coverage is creating guaranteed payment pools independent of discretionary spending.
- Pay-Per-Use:Transactional pricing for single-cycle services including donor matching and one-time retrievals. Higher per-procedure margins offset customer acquisition overhead in competitive urban markets.
- Package Deal:Bundled pricing combining retrieval, cryopreservation, and multiple storage years. These structures improve upfront cash flow for clinic operators while locking in client commitment.
Pay-per-use retains transactional volume concentration. Subscription plan is where expansion concentrates as deferred parenthood planning normalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States fertility networks export cryopreserved gametes to Canada and Mexico, establishing a North American trade corridor that concentrates banking service volumes in metropolitan fertility clusters.
United States
Large networked fertility centers in Boston and San Francisco drive elective egg freezing subscriptions among professional women delaying parenthood. FDA donor screening rules mandate infectious disease testing protocols that shape laboratory infrastructure investment across multi-state clinic networks. California Cryobank and Fairfax Cryobank anchor distribution capacity in Los Angeles and Washington D.C. corridors.
Germany
Federal tissue authority audits enforce chain-of-custody documentation that consolidates banking operations among high-volume operators capable of absorbing compliance overhead. The EU Tissue and Cell Directives mandate interoperable traceability standards that reshape cryogenic logistics networks. Berlin and Munich fertility clusters concentrate automated cryopreservation adoption among academic medical centers.
Spain
Same-sex family formation from France and Italy drives cross-border demand for gestational carrier-egg donor combinations requiring coordinated multi-bank sourcing. The country's national pharmaceutical regulator enforces storage duration limits that create legal exposure for long-term embryo banking contracts. Barcelona and Madrid fertility networks specialize in international patient recruitment.
Canada
Male couples in Toronto and Vancouver drive demand for donor sperm-egg donor combinations that require integrated sourcing across provincial banking networks. Health Canada mandates donor screening protocols that align with FDA standards, reducing cross-border compliance friction for US-sourced specimens. Pacific Northwest fertility corridors concentrate oncofertility preservation programs serving cancer patients prior to gonadotoxic therapy.
United Kingdom
London fertility networks attract deferred parenthood clients from Gulf states and Southeast Asia seeking premium egg donor matching services. The Human Fertilisation and Embryology Authority enforces storage limit regulations that influence embryo disposition contract structures. Greater Manchester and Birmingham academic medical centers expand cryopreservation capacity for NHS-funded fertility preservation pathways.
In Vitro Fertilization Banking Services Market Competitive Environment
On the supply side, the industry is consolidating around fertility networks with integrated laboratory infrastructure and centralized cryogenic logistics capabilities. Tiered competitive positioning separates high-volume banking operators from regional clinic laboratories serving local retrieval-to-transfer cycles. Three archetypes dominate: commercial donor banks with extensive phenotypic databases, fertility network laboratories with captive patient flows, and academic medical centers with research-funded preservation programs. Capacity expansion and strategic partnerships represent the dominant competitive moves as operators seek to amortize compliance infrastructure across larger specimen inventories.
Within the commercial donor bank archetype, Fairfax Cryobank and Cryos International exemplify operators leveraging centralized cryogenic logistics to serve distributed fertility networks. MyEggBank occupies a position among North American scale-driven operators maintaining extensive frozen egg donor pools. These three entities represent the competitive template for quality leadership through donor screening protocol standardization and multi-jurisdictional regulatory compliance.
| Leading Market Players |
|---|
| The World Egg Bank |
| Fairfax Cryobank |
| MyEggBank |
| Cryos International |
| Seattle Sperm Bank |
| European Sperm Bank |
| California Cryobank |
| CCRM Fertility |
| Boston IVF |
| Others |
Value Chain & Pricing Dynamics
Liquid nitrogen supply concentration in regional industrial gas markets determines both tiered pricing spreads across fertility networks and cryogenic logistics infrastructure deployment. This single-source dependency for cryoprotectant cooling forces banking operators to absorb volatile input costs or pass them through to subscription storage clients.
Pricing Analysis
Vitrification versus controlled-rate freezing versus legacy programmable freezer installations stratify service pricing across three distinct technology tiers. Premium-mid-economy pricing differentiation reflects survival rate guarantees, with vitrification protocols commanding margins that absorb donor screening compliance overhead. Cost compression in standard-tier controlled-rate freezing is intensifying because embryologist training pipeline constraints limit service scaling. Individual elective fertility preservation clients show highest price sensitivity, while integrated fertility clinics with captive patient flows absorb markups with least friction.
Supply Chain Analysis
Export-control regimes on cryoprotectant formulations and automated vitrification equipment limit technology transfer to banking operators in certain jurisdictions. Manufacturing concentrates in the United States, Germany, and Japan for programmable freezing systems and robotic handling platforms. Raw material dependencies span liquid nitrogen from industrial gas suppliers, medical-grade cryoprotectants from specialty chemical producers, and donor screening reagents from diagnostic manufacturers. Single-source vulnerability in regional liquid nitrogen distribution creates supply interruption exposure. Distribution runs through centralized cryogenic logistics networks serving multi-state clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vitrification survival rates exceeding 90% constitute a technological inflection that disrupts legacy freezing infrastructure investments and reshapes competitive viability timelines for laboratory operators.
For Market Incumbents: Insulate donor pool quality leadership through backward integration into genetic screening laboratory networks and embryologist certification academies. Fairfax Cryobank and Cryos International demonstrate how multi-jurisdictional regulatory compliance infrastructure amortizes across higher specimen volumes. Threat substitution from AI-assisted donor matching platforms demands preemptive database investments in phenotypic prediction capabilities. For New Entrants and Emerging Players: Mid-market fertility clinics in Canada and Spain lacking integrated cryopreservation capacity represent the most penetrable entry point for contract vitrification services. Same-sex family formation segments requiring coordinated multi-bank sourcing offer white-space demand with lower incumbent saturation. Go-to-market positioning around subscription payment architectures captures deferred parenthood planning behavior shifts among urban professional demographics. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors high-volume banking operators with centralized cryogenic logistics and interoperable traceability systems. Long-term viability across the next decade hinges on regulatory harmonization exposure and automation amortization capacity. Acquisition targets should demonstrate FDA donor screening protocol standardization and EU Tissue Directive compliance infrastructure. The signal to watch is state-level insurance mandate expansion for oncofertility preservation, which would fundamentally alter payment model preferences and clinic revenue mix stability.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Cryopreservation Deployment | Robotic handling systems from manufacturers in Germany reduce human error in cryoprotectant exposure timing. |
| Multi-Jurisdictional Compliance Certification | FDA donor screening harmonization with EU Tissue Directive standards enables cross-border specimen distribution. |
| AI-Assisted Donor Matching Platform | Phenotypic prediction algorithms analyzing facial morphology databases compress donor selection cycles from weeks to days. |
| Subscription Payment Architecture Redesign | Annual billing models spreading cryogenic storage costs capture lifetime value from deferred parenthood planners in Boston and San Francisco. |
| Oncofertility Preservation Program Expansion | State-mandated insurance coverage for cancer patients creates guaranteed payment pools independent of elective fertility tourism. |
Study Parameters
Cross-validation between primary interviews with laboratory directors and embryologists and secondary validation through FDA donor screening guidance documents anchors the qualitative findings. Stakeholder consultations spanned fertility clinic operators, cryogenic logistics specialists, donor screening laboratory managers, and reproductive endocrinologists across the United States, Germany, and Spain. Secondary sources included FDA tissue establishment registration databases, EU Tissue and Cell Directive implementation reports, and hospital procurement records for cryopreservation equipment. Bottom-up specimen volume estimates triangulated against top-down fertility clinic capacity assessments.
Calibration against historical vitrification adoption curves and controlled-rate freezing replacement cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass service type, end-user concentration, technology generation, and payment model architecture. CAGRs derived from specimen volume growth trajectories and pricing evolution patterns across subscription versus pay-per-use structures. Forecast inputs incorporated embryologist training pipeline capacity constraints and liquid nitrogen supply volatility indices.
Practitioners should monitor regulatory harmonization progress and state-level insurance mandate expansion for early signals of payment model disruption. Forecasts reflect assumptions regarding vitrification survival rate stability and cryoprotectant supply chain continuity. Material shifts in FDA donor screening protocols or EU traceability requirement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Global Banking Systems Software Market
Banking
Automated Teller Machine (ATM) Market
Banking
Smart ATM Market
Banking
Banking Software Market
Banking
Global Big Data Analytics in Banking Market
Banking
Investment Banking Market
Banking
Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
Europe Neobanking Market
Banking
Global Neo and Challenger Bank Market
Banking
GCC Mobile Banking Market
Banking
South America Challenger Banks Market
Banking
Global IoT in Banking and Financial Services Market
Banking
China Retail Banking System Market
Banking
Credit Intermediation Market
Banking
Banking Wearable Devices Market
Banking
APAC Banking-As-A-Service Market