
 Global Remote Work Software Market | 2026-2036
Global Remote Work Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Remote Work Software Market Foresight
Subscription-based financing and asset-light deployment models is reconfiguring competitive entry barriers, allowing mid-size vendors to challenge incumbents without heavy infrastructure commitments. Microsoft leverages its cloud ecosystem to anchor enterprise accounts across productivity suites. Zoom Video Communications sustains brand recognition in video-first communication segments. Atlassian specializes in developer-centric project management tools that dominate technical team workflows.
Remote work software encompasses cloud-native and on-premise applications enabling distributed collaboration, virtual desktop access, and asynchronous project coordination through APIs, encryption protocols, and multi-tenant architecture. Its primary commercial purpose is sustaining operational continuity across geographically dispersed employees while reducing real estate overhead. Cloud-based deployment leads in revenue contribution due to lower upfront capital requirements and faster scaling for SMEs. Collaboration tools represent the most contested margin pool as vendors bundle messaging, file sharing, and video into unified platforms. Virtual desktop infrastructure occupies a specialized niche serving regulated industries with strict endpoint control requirements.
The EU AI Act and GDPR shape product development timelines for vendors serving European enterprises, mandating algorithmic transparency and data localization features. The US lacks federal privacy uniformity, yet state frameworks like California's CCPA compel compliance investments that ripple through global product roadmaps. ISO 27001 certification has become a baseline procurement filter for enterprise buyers evaluating vendor security posture. Stakeholders must monitor how fragmented regulatory requirements across jurisdictions influence platform architecture decisions and customer acquisition costs.
Market Dynamics
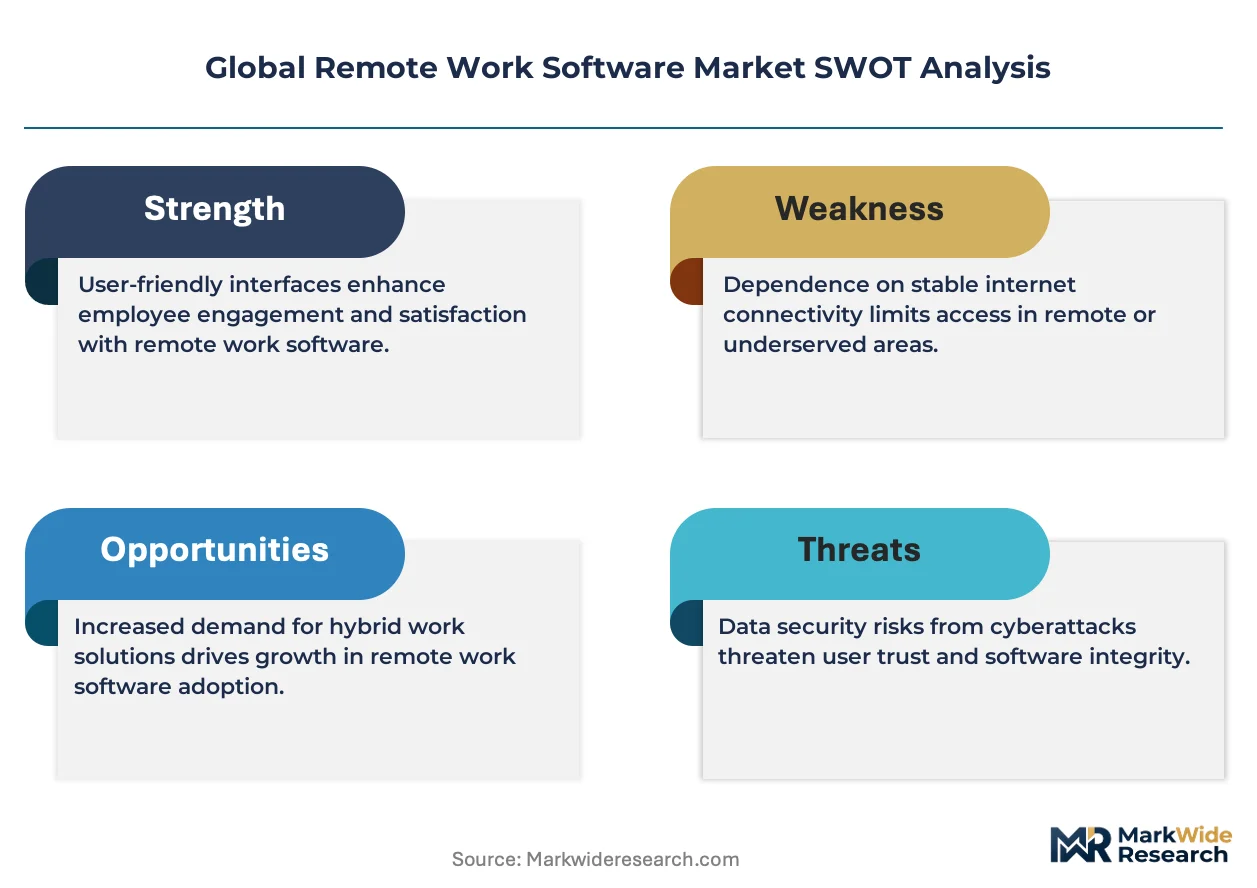
Enterprise migration toward zero-trust security architectures is compressing procurement cycles for remote work platforms, forcing vendors to embed identity verification and endpoint compliance directly into core product stacks rather than offering bolt-on modules.
Growth Catalysts
- GDPR data localization mandates:European enterprises now require sovereign cloud deployments, compelling vendors to establish regional data centers and residency controls that accelerate platform standardization across multinational accounts.
- API-first architecture adoption:IT services firms in India demand modular integration between communication, project management, and HR systems, driving procurement of unified platforms over point solutions.
- Distributed engineering team expansion:Large enterprises in Germany and the United States are consolidating vendor relationships around collaboration suites that support real-time code review and technical documentation workflows.
Market Restraints
- State-level privacy fragmentation:The absence of federal US privacy law forces vendors to maintain parallel compliance tracks for California CCPA, Virginia VCDPA, and Colorado CPA, inflating legal overhead and delaying product releases.
- Specialized endpoint control requirements:Virtual desktop infrastructure for financial services and healthcare remains tethered to on-premise deployment, constraining cloud revenue conversion in high-margin regulated segments.
- Encryption protocol divergence:Incompatible national cryptographic standards between the United States, China, and Russia fragment product development and limit cross-border feature parity.
Strategic Opportunities
- EU AI Act compliance tooling:Algorithmic transparency requirements for automated productivity scoring create demand for audit-ready workforce analytics modules among French and German enterprise buyers.
- Indonesia and Vietnam IT services growth:Underpenetrated SaaS adoption in Southeast Asian outsourcing hubs offers first-mover positioning for localized pricing and Bahasa/ Vietnamese language support.
- Convergence of asynchronous video and project management:Loom-style recorded updates integrated with Jira or Asana workflows address time-zone friction in globally distributed technical teams.
Industry Challenges
- Zero-trust architecture skill scarcity:Enterprise IT departments lack sufficient security engineers to configure micro-segmentation and continuous verification for remote access platforms, extending implementation timelines.
- ISO 27001 certification bottlenecks:Audit backlogs at accredited bodies delay vendor eligibility for RFPs at Fortune 500 accounts, compressing sales cycles for uncertified competitors.
- Legacy on-premise integration complexity:Hybrid deployments requiring seamless handoffs between cloud-native tools and decades-old ERP systems demand costly professional services engagements that erode SaaS margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Remote Work Software Market |
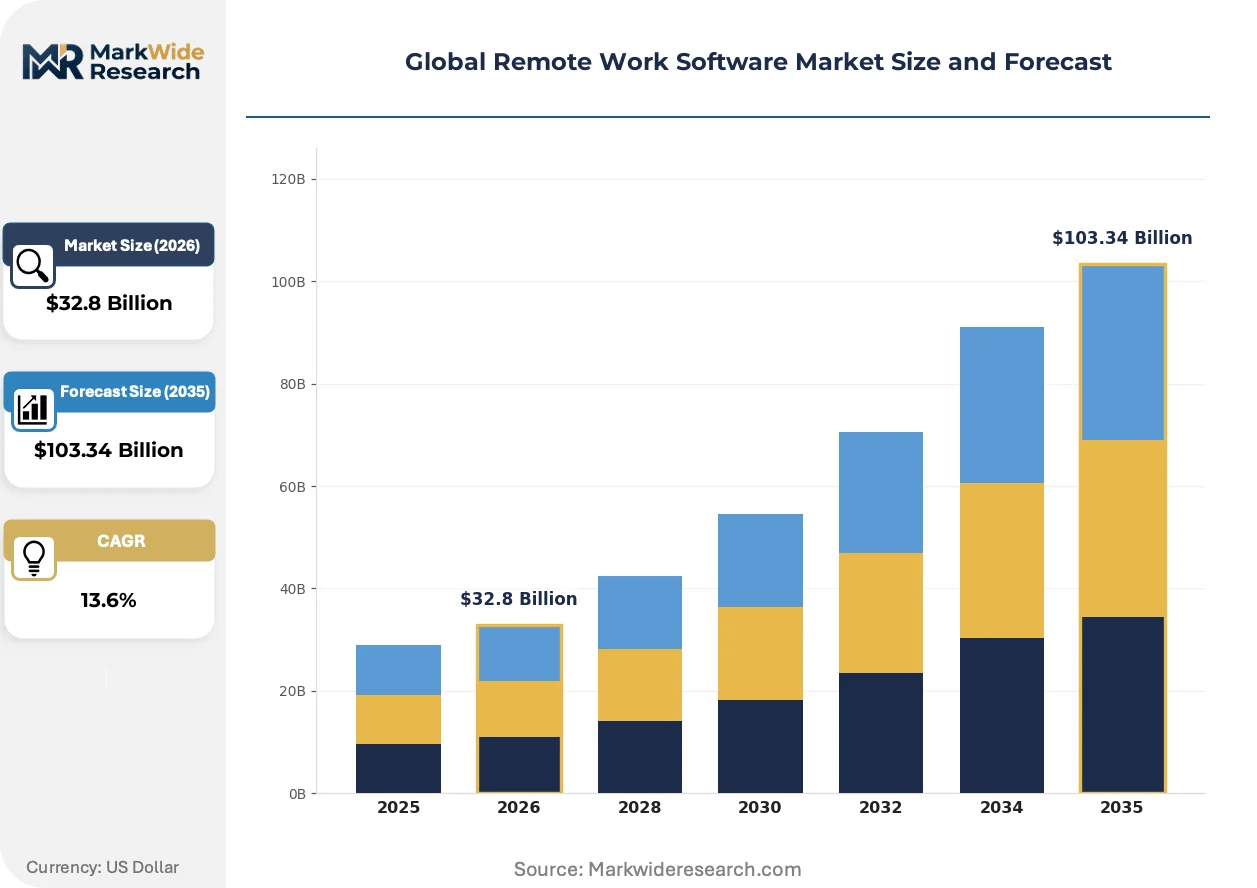
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $103.34 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Type: Collaboration Tools, Virtual Desktop Infrastructure, Project Management, Communication Platforms, Time Tracking End User: SMEs, Large Enterprises, Government Agencies, Freelancers, Educational Institutions Pricing Model: Subscription-Based, Perpetual License, Freemium, Pay-As-You-Go |
| Companies Covered | Automattic, Microsoft, GitLab, Asana, Zoom Video Communications, Atlassian, Slack Technologies, Deel, Zapier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Remote Work Software Market Shifts & Advancements
Artificial intelligence is embedding predictive capabilities throughout remote work stacks, automating meeting transcription, sentiment analysis, and workload balancing while raising new governance questions about algorithmic management.
Browser-based virtual desktop infrastructure is virtualizing endpoint computing by delivering full Windows environments through WebAssembly and streaming protocols. Pharmaceutical and legal services firms in Switzerland and the United Kingdom are piloting these solutions to eliminate physical device provisioning for contractors. This architecture is virtualizing the traditional VDI market by collapsing client software requirements and enabling instant provisioning from any hardware.
The EU AI Act's risk classification system for workplace monitoring tools is forcing vendors to redesign productivity analytics dashboards. Algorithmic scoring of employee engagement now requires human oversight interfaces and explainability documentation. German works councils and French labor inspectors are demanding these features before approving enterprise rollouts, compressing development timelines for vendors serving continental European accounts.
Consumption-based licensing for collaboration seats is displacing annual contracts in mid-market segments. Channel partners in Australia and Canada now offer month-to-month tiers tied to active user counts rather than total employee headcount. This flexibility appeals to seasonal professional services firms and venture-backed startups with volatile hiring plans, shifting revenue recognition patterns across the vendor base.
Global Remote Work Software Market Segmentation
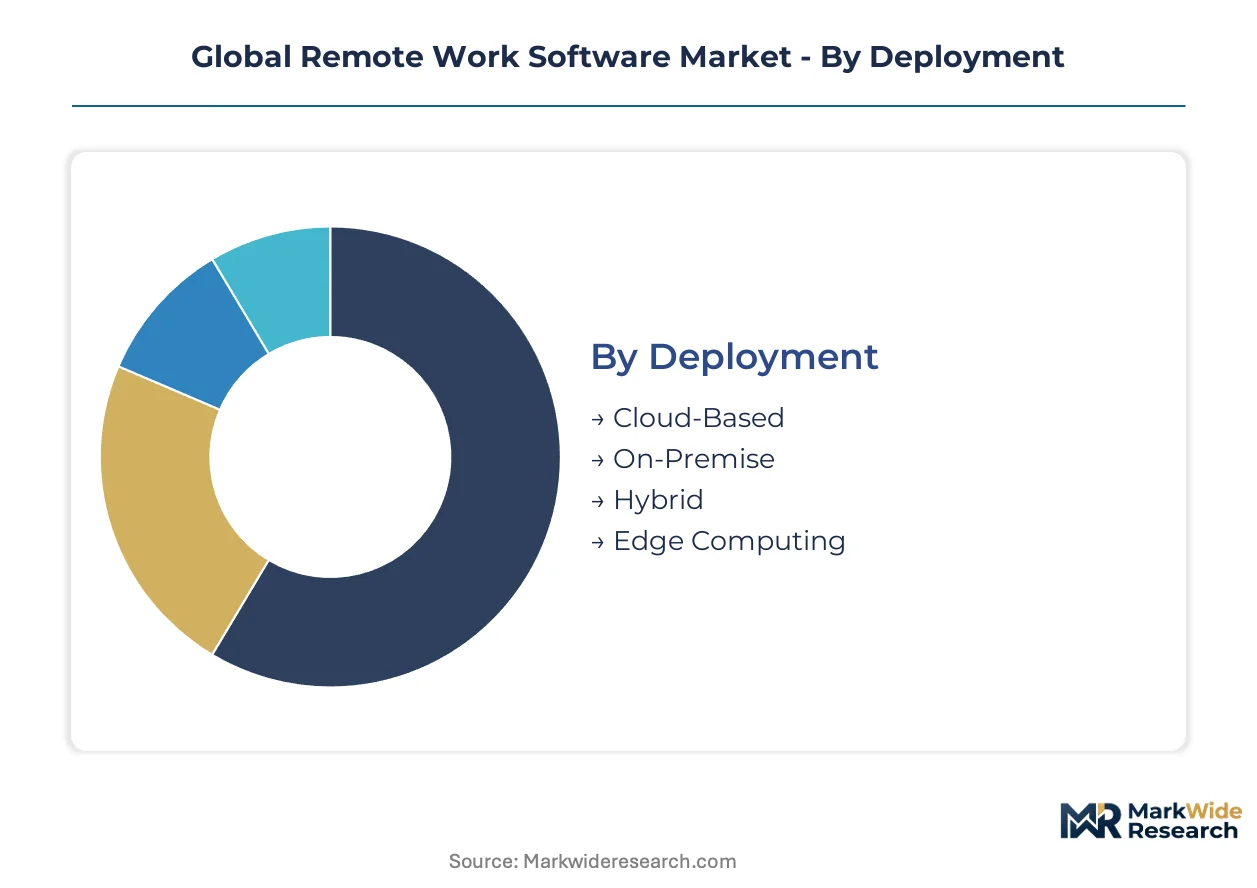
Remote work software vendors architect product portfolios around four intersecting dimensions: how infrastructure deploys, what functional problems get solved, who pays, and how revenue gets captured. These segmentation boundaries determine R&D allocation, sales motion design, and partnership strategy.
Deployment:
Use-case spectrum spans from asset-light SaaS consumption to sovereign infrastructure mandates.
- Cloud-Based:Multi-tenant architectures with regional data residency controls dominate procurement from Indian IT services firms and German automotive suppliers seeking GDPR-compliant scaling. SME adoption concentrates here due to zero CapEx requirements and instant provisioning.
- On-Premise:Air-gapped installations serve Swiss pharmaceutical manufacturers and US defense contractors with classified workload requirements. Hardware refresh cycles and perpetual licensing create predictable but declining revenue pools.
- Hybrid:Split architectures route sensitive data to private infrastructure while pushing collaboration traffic to public clouds. French banking consortiums and Japanese automotive engineering centers favor this model for intellectual property segmentation.
- Edge Computing:Localized processing nodes reduce latency for real-time video collaboration in resource extraction sites across Australia and remote Canadian mining operations.
The dominant share belongs to Cloud-Based, while Edge Computing is gaining share fastest.
Solution Type:
Customer budgets fragment across productivity workflows, with integration depth determining switching costs.
- Collaboration Tools:Unified messaging, video, and document platforms anchor enterprise software spend. US technology firms and Indian SaaS startups drive consolidation around single-vendor suites rather than point solutions.
- Virtual Desktop Infrastructure:Streaming Windows environments through browsers eliminates endpoint provisioning for UK legal services and Swiss contract research organizations. Browser-based WebAssembly implementations are displacing traditional client-heavy deployments.
- Project Management:Developer-centric tools with API extensibility dominate technical team procurement in Israel and Singapore.
- Communication Platforms:Voice-first and video-first architectures compete for frontline worker adoption in Brazilian logistics and Mexican manufacturing.
- Time Tracking:Automated productivity analytics face regulatory headwinds under EU AI Act algorithmic scoring restrictions, compressing feature roadmaps for French and German deployments.
Collaboration Tools command the largest revenue pool, though Virtual Desktop Infrastructure shows the steepest expansion trajectory.
End User:
Procurement sophistication varies sharply by organizational scale and compliance exposure.
- SMEs:Month-to-month subscription flexibility and self-service onboarding define vendor selection criteria for Australian professional services firms and Canadian seasonal employers.
- Large Enterprises:Zero-trust security mandates and ISO 27001 certification requirements filter vendor eligibility at Fortune 500 accounts in the United States and Germany.
- Government Agencies:FedRAMP and equivalent national security frameworks constrain supplier pools for US federal and UK public sector procurement.
- Freelancers:Freemium tier conversion and mobile-first design drive adoption among independent contractors in Spain and Italy.
- Educational Institutions:Volume licensing and accessibility compliance shape procurement for K-12 districts in Texas and university systems in Ontario.
Large Enterprises contribute the dominant revenue share, while Government Agencies are expanding procurement fastest.
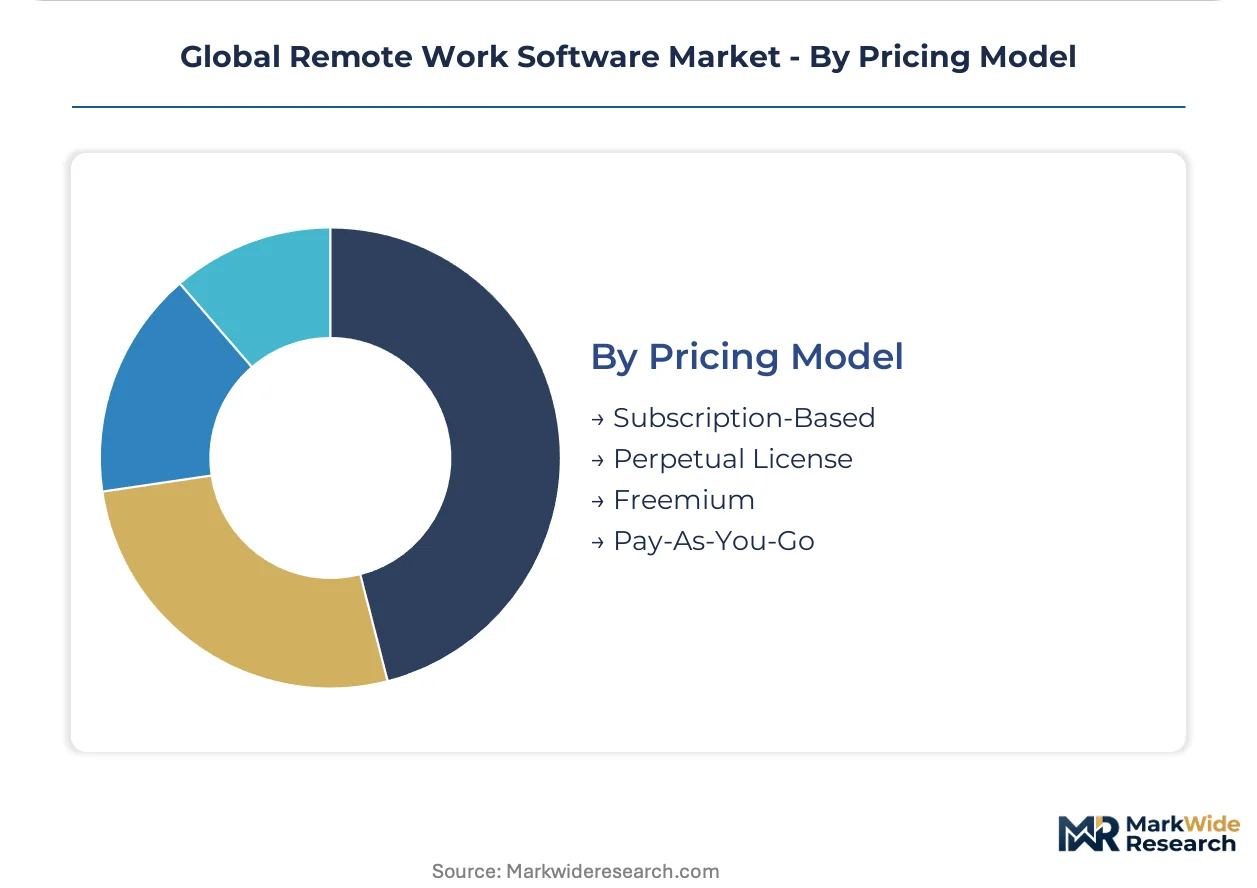
Pricing Model:
Revenue recognition patterns diverge between predictable recurring streams and volatile consumption-based mechanics.
- Subscription-Based:Annual or multi-year contracts with seat-based billing anchor enterprise relationships. German automotive suppliers and US healthcare systems favor this predictability for budget planning.
- Perpetual License:Upfront CapEx with maintenance renewals persists in regulated on-premise deployments for Russian energy firms and Chinese state-owned enterprises with restricted cloud access.
- Freemium:Tiered conversion funnels from individual to team licenses capture viral growth in Indonesian and Vietnamese startup ecosystems.
- Pay-As-You-Go:Metered consumption tied to active usage minutes or storage volumes appeals to Australian seasonal firms and venture-backed startups with volatile hiring.
Subscription-Based retains the dominant share, while Pay-As-You-Go is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in the United States drive the largest procurement volumes for integrated collaboration platforms, while Indian IT services firms and German automotive suppliers anchor demand growth across cloud-native deployment models.
United States
Fortune 500 technology firms and venture-backed startups consolidate vendor relationships around unified productivity suites. CCPA compliance investments ripple through product roadmaps for California-based buyers. Seattle and San Francisco Bay Area engineering clusters demand real-time code collaboration and API-first architecture integrations.
Germany
Automotive suppliers and industrial conglomerates mandate sovereign cloud deployments for distributed engineering teams. GDPR data localization requirements accelerate regional data center establishment. Stuttgart and Munich manufacturing hubs prioritize zero-trust security architectures for supplier network access.
India
IT services firms and SaaS startups drive procurement of modular communication platforms with HR system integrations. TRAI data governance guidelines shape vendor selection criteria for domestic enterprises. Bangalore and Hyderabad technology corridors concentrate demand for scalable collaboration infrastructure.
United Kingdom
Legal services firms and contract research organizations pilot browser-based virtual desktop infrastructure for contractor provisioning. UK GDPR alignment maintains compliance continuity post-Brexit. London financial services and Cambridge life sciences clusters adopt streaming endpoint solutions for intellectual property protection.
Japan
Automotive engineering centers and electronics manufacturers favor hybrid deployment models for intellectual property segmentation. METI cybersecurity frameworks influence vendor certification requirements. Tokyo-Osaka industrial corridors integrate asynchronous project coordination tools for timezone-distributed technical teams.
Global Remote Work Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where ecosystem breadth determines enterprise account retention. Microsoft anchors the upper tier through cloud ecosystem integration, while mid-size vendors challenge through modular API-first architectures. Strategic archetypes include platform consolidators bundling messaging-video-documentation, vertical specialists serving regulated industries, and workflow-native tools embedded in developer environments. Dominant competitive moves center on M&A for feature gap closure and strategic partnerships expanding distribution reach into IT services channels.
Among ecosystem-anchored platform providers, Microsoft and Zoom Video Communications occupy positions representing scale-driven consolidation, while Atlassian exemplifies the developer-centric workflow specialization archetype. These three companies collectively illustrate how competitive positioning diverges between horizontal suite breadth and deep technical team integration.
| Leading Market Players |
|---|
| Automattic |
| Microsoft |
| GitLab |
| Asana |
| Zoom Video Communications |
| Atlassian |
| Slack Technologies |
| Deel |
| Zapier |
| Others |
Supply & Pricing Matrix
GDPR data localization mandates function as a regulatory chokepoint that compresses pricing tier spreads between sovereign cloud deployments and standard multi-tenant offerings while forcing vendors to absorb regional data center buildout costs into supply chain architecture decisions.
Pricing Analysis
Cost-plus contracts with annual CPI indexation anchor enterprise subscription renewals for German automotive suppliers and US healthcare systems. Pricing stratifies across premium, standard, and economy tiers based on ISO 27001 certification grade and dedicated support SLAs. Cost compression in the mid-market tier is intensifying because Indian IT services firms demand modular API access without bundled professional services. Freelancers and seasonal professional services firms in Australia exhibit highest price sensitivity, while Fortune 500 accounts in the United States show lowest elasticity due to zero-trust security mandates.
Supply Chain Analysis
Supply-chain finance facilities with 90-day extended terms have become standard for hyperscaler infrastructure procurement, easing cash flow for vendors establishing EU data residency nodes. Cloud infrastructure concentrates in the United States, Ireland, and Singapore, with compute capacity expansion accelerating in India and Germany. Software development draws from distributed engineering talent pools across Poland, Ukraine, and Vietnam. Single-source vulnerability in encryption protocol licensing from US-origin suppliers creates compliance friction for vendors serving Chinese and Russian enterprise accounts. Distribution runs through direct enterprise sales teams with channel partner overlays in mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Remote Work Software Market operates as a defensive-moat story where switching costs embedded in API-integrated workflow stacks protect incumbent positions against modular challengers.
For Market Incumbents: Pre-empt API-first challengers by deepening native integrations with HRIS and ERP systems that increase customer switching costs. Acquire browser-based VDI specialists to close feature gaps against emerging zero-trust security entrants. Expand sovereign cloud capacity in Germany and India ahead of GDPR and TRAI enforcement waves to lock out regional competitors. For New Entrants and Emerging Players: Build out localized language support and consumption-based pricing for Indonesian and Vietnamese IT services markets where incumbent penetration remains shallow. Target mid-market professional services firms in Australia and Canada with month-to-month active-user licensing that incumbents resist due to revenue recognition complexity. Lead with asynchronous video-project management convergence to capture distributed engineering teams in Israel and Singapore. For Investors and Strategic Acquirers: EU AI Act algorithmic transparency mandates reshape the acquisition landscape by elevating vendors with pre-built audit-ready workforce analytics modules above compliance-lagged competitors. Viability over the medium-term horizon hinges on data residency infrastructure depth rather than feature velocity alone. Monitor ISO 27001 certification backlog resolution at accredited bodies as a signal for vendor RFP eligibility inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified messaging-video-documentation bundles reduce vendor consolidation risk for German automotive suppliers. |
| Strategic Partnership | IT services channel alliances in Bangalore and Hyderabad accelerate enterprise procurement cycles for cloud-native suites. |
| Acquisition of Specialist Firm | Browser-based VDI capabilities address Swiss pharmaceutical and UK legal services contractor provisioning requirements. |
| Geographic Expansion | Sovereign cloud nodes in Jakarta and Hanoi capture first-mover positioning in underpenetrated Southeast Asian outsourcing hubs. |
| Product Launch | EU AI Act-compliant workforce analytics modules unlock French and German enterprise rollouts blocked by works council objections. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and EU regulatory filings to establish vendor revenue allocation and infrastructure investment patterns. Interviews with CTOs, IT procurement officers, platform engineers, and channel partners across the United States, Germany, and India inform adoption driver assessment. Bottom-up sizing of deployment models and solution types triangulates against top-down macroeconomic indicators across the analysis window.
Forecast inputs span deployment architecture, organization size tier, vertical industry, integration complexity, and regional regulatory cluster to model adoption elasticity. CAGRs derive from segmented growth rate application calibrated to primary interview indicators. Cloud infrastructure capacity expansion timelines and GDPR enforcement phase-ins feed directly into sovereign deployment projections throughout the forecast period.
The forecast holds incumbent behavior within observed patterns; aggressive capacity moves by hyperscaler challengers or accelerated EU AI Act enforcement would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Staffing Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Global Catalog Management Software Market
Software & Services
Asia-Pacific Communication Platform-As-A-Service Market
Software & Services
Asia-Pacific Database Management Software Market
Software & Services
Customer Self-Service Software Market
Software & Services
Mindfulness Meditation Application Market
Software & Services
Artwork Management Software Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
Visitor Identification Software Market
Software & Services
App Creation Software Market
Software & Services
School Timetable Software Market
Software & Services
Global Virtual Desktop Market
Software & Services
North America Equity Management Software Market
Software & Services
Global Cinema Software Market
Software & Services
Construction Suites Software Market